
 Chromatography Food Testing Market | 2026-2036
Chromatography Food Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Chromatography Food Testing Market Analysis
The EU Green Deal is decoupling food safety compliance from legacy testing protocols across European supply chains. Agilent Technologies Inc. leverages its liquid chromatography portfolio to anchor laboratory workflows for pesticide residue quantification. Eurofins Scientific sustains competitive density through its geographic reach across food testing laboratories in multiple countries. Thermo Fisher Scientific Inc. dominates mass spectrometry-chromatography integration for contaminant detection at trace levels.
Chromatography food testing employs separation science to isolate and quantify chemical constituents in food matrices, typically achieving detection thresholds at parts-per-billion concentrations through column-based partitioning mechanisms. Its primary commercial purpose is to verify regulatory compliance for contaminants, nutritional content, and authenticity markers before market release. Liquid chromatography leads instrument revenue due to versatility in analyzing non-volatile compounds such as mycotoxins and veterinary drug residues. Gas chromatography occupies the fastest-expanding margin pool for fatty acid profiling and volatile flavor compound analysis in premium food categories. HPLC technology anchors routine quality control workflows, while UHPLC gains share where throughput acceleration justifies capital intensity.
The European Food Safety Authority (EFSA) and the U.S. Food and Drug Administration (FDA) enforce maximum residue limits that directly determine chromatography sensitivity requirements for market access. REACH and FDA Food Safety Modernization Act compliance obligations force continuous instrument upgrades as detection thresholds tighten. Stakeholders must monitor evolving multi-residue methods and harmonization between Codex Alimentarius standards and national enforcement regimes to anticipate procurement cycles.
Market Dynamics
The EU Green Deal's Farm to Fork Strategy is forcing residue limit reductions that obsolete legacy detection thresholds and trigger instrument replacement cycles across European food laboratories. This regulatory compression cascades through supply chains, reconfiguring procurement priorities for chromatography systems capable of parts-per-trillion sensitivity.
Growth Catalysts
- REACH and MRL tightening:The European Chemicals Agency's evolving substance restrictions compel food exporters to upgrade liquid chromatography-mass spectrometry platforms for compliant contaminant screening.
- Dairy sector allergen verification:European dairy manufacturers are deploying high-performance liquid chromatography for protein fractionation to meet EFSA labeling mandates.
- Volatile compound profiling:Premium beverage producers in France and Italy are adopting gas chromatography-olfactometry for flavor authenticity certification.
Market Restraints
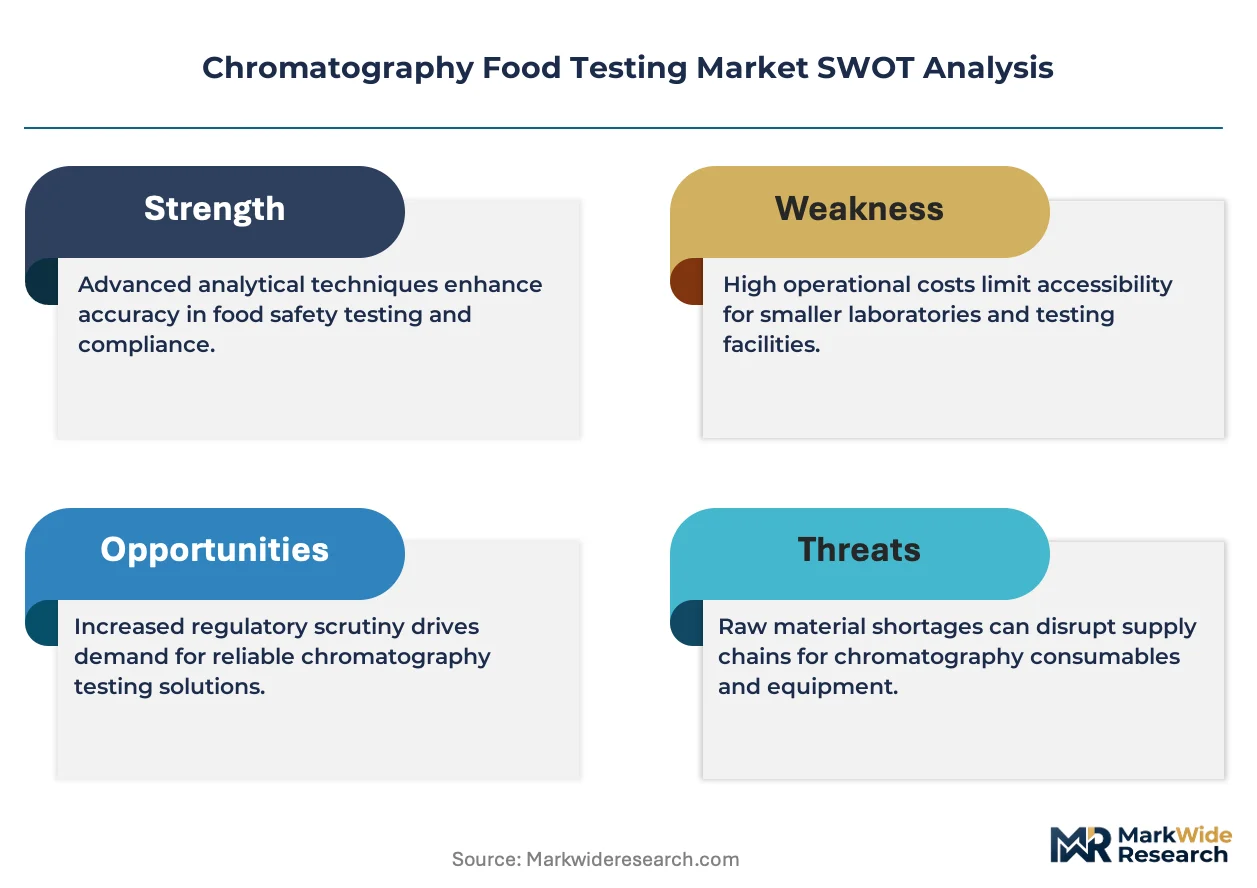
- Helium supply volatility:Gas chromatography operations face input cost instability due to concentrated helium sourcing from US federal reserves and Algerian production.
- Capital intensity barriers:Ultra-high-performance liquid chromatography systems require substantial upfront investment that constrains mid-tier laboratory adoption.
- Technical substitution pressure:Biosensor-based rapid testing is capturing low-sensitivity screening applications previously served by chromatography.
Strategic Opportunities
- Plant-based protein authentication:Chromatography vendors can penetrate the alternative protein sector for amino acid profiling and adulteration detection.
- Service contract unbundling:Independent service providers are capturing maintenance revenue from original equipment manufacturers through remote diagnostics and predictive parts replacement.
- EU AI Act compliance infrastructure:Automated chromatography data analysis tools qualify for regulatory technology procurement budgets under emerging algorithmic accountability frameworks.
Industry Challenges
- Mass spectrometry operator scarcity:Laboratories face recruitment friction for technicians capable of troubleshooting ion source contamination and method development.
- Multi-residue method validation timelines:EFSA approval processes for novel analyte combinations extend commercialization cycles for new column chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chromatography Food Testing Market |
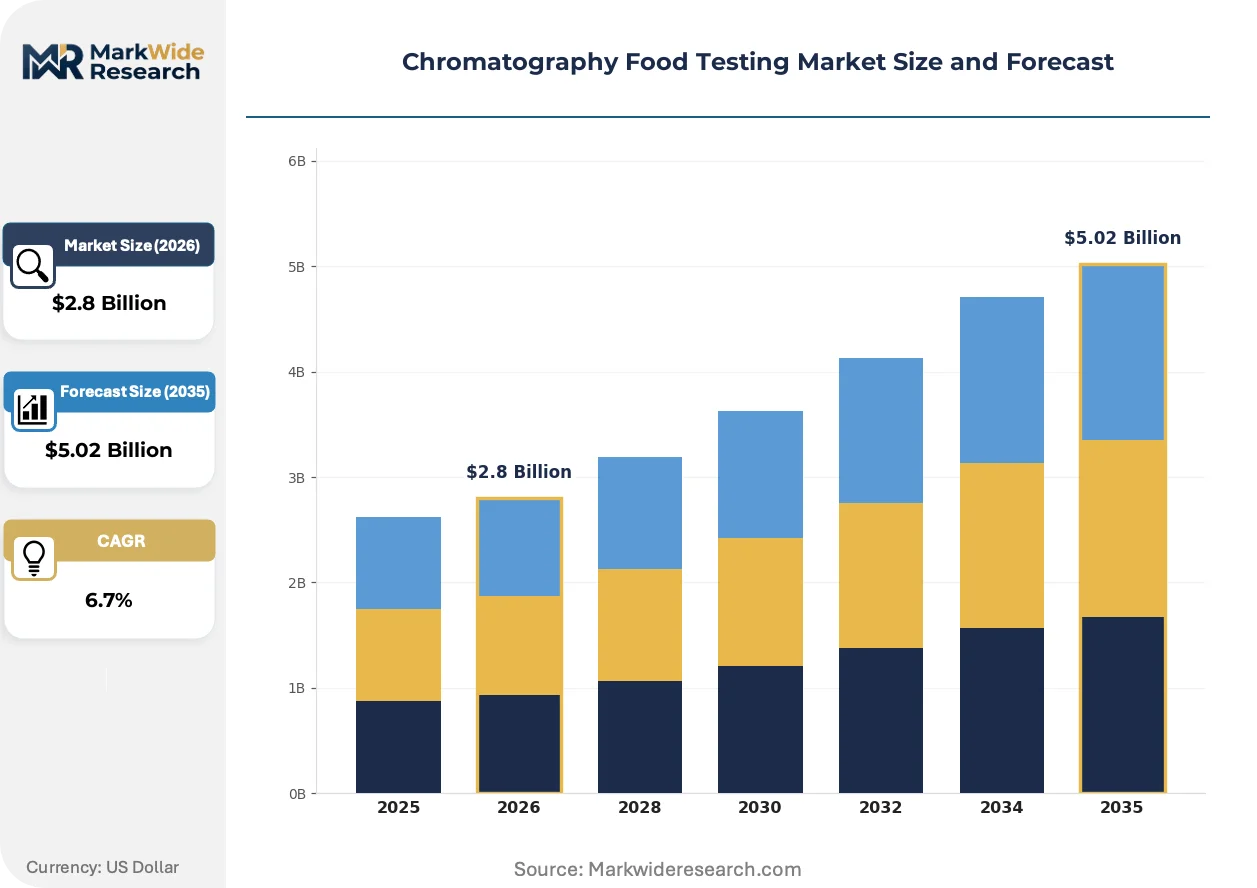
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Chromatography, Gas Chromatography, Supercritical Fluid Chromatography, Ion Chromatography Application: Food Quality Testing, Contaminant Detection, Nutritional Analysis, Pesticide Residue Testing End User: Food Manufacturers, Research Laboratories, Government Agencies, Quality Control Laboratories Technology: HPLC, GC, UHPLC, SFC |
| Companies Covered | Agilent Technologies Inc., Eurofins Scientific, Thermo Fisher Scientific Inc., PerkinElmer Inc., SGS SA, Shimadzu Corporation, Merck KGaA, Bruker Corporation, Waters Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chromatography Food Testing Market Emerging Trajectories
Chromatography food testing is converging with artificial intelligence and miniaturization, compressing detection timelines while expanding deployable environments beyond centralized laboratories. These shifts are fragmenting the traditional capital-equipment model toward modular, service-integrated platforms.
Ultra-high-performance liquid chromatography is rewriting routine contaminant screening workflows by compressing run times from thirty minutes to under five minutes per sample. Mid-sized contract laboratories in Germany and the Netherlands are adopting these systems to triple daily throughput without facility expansion. This acceleration is compressing per-test economics and forcing competitive differentiation toward method exclusivity rather than capacity scale.
The EU Green Deal's pesticide reduction targets are mandating multi-residue panels that exceed legacy instrument capabilities. Food testing laboratories must now quantify hundreds of analytes simultaneously, driving demand for quadrupole time-of-flight mass spectrometry configurations. Dairy and infant formula manufacturers face the steepest compliance ramps, accelerating their procurement of high-resolution accurate mass systems.
Buyers are unbundling instrument purchases from captive service contracts, forcing vendors to compete on maintenance pricing transparency. Third-party service providers in France and Spain are capturing calibration and preventive maintenance revenue through subscription models. This disintermediation is most pronounced among beverage conglomerates with multi-site laboratory networks seeking standardized service levels across facilities.
Chromatography Food Testing Market Segmentation
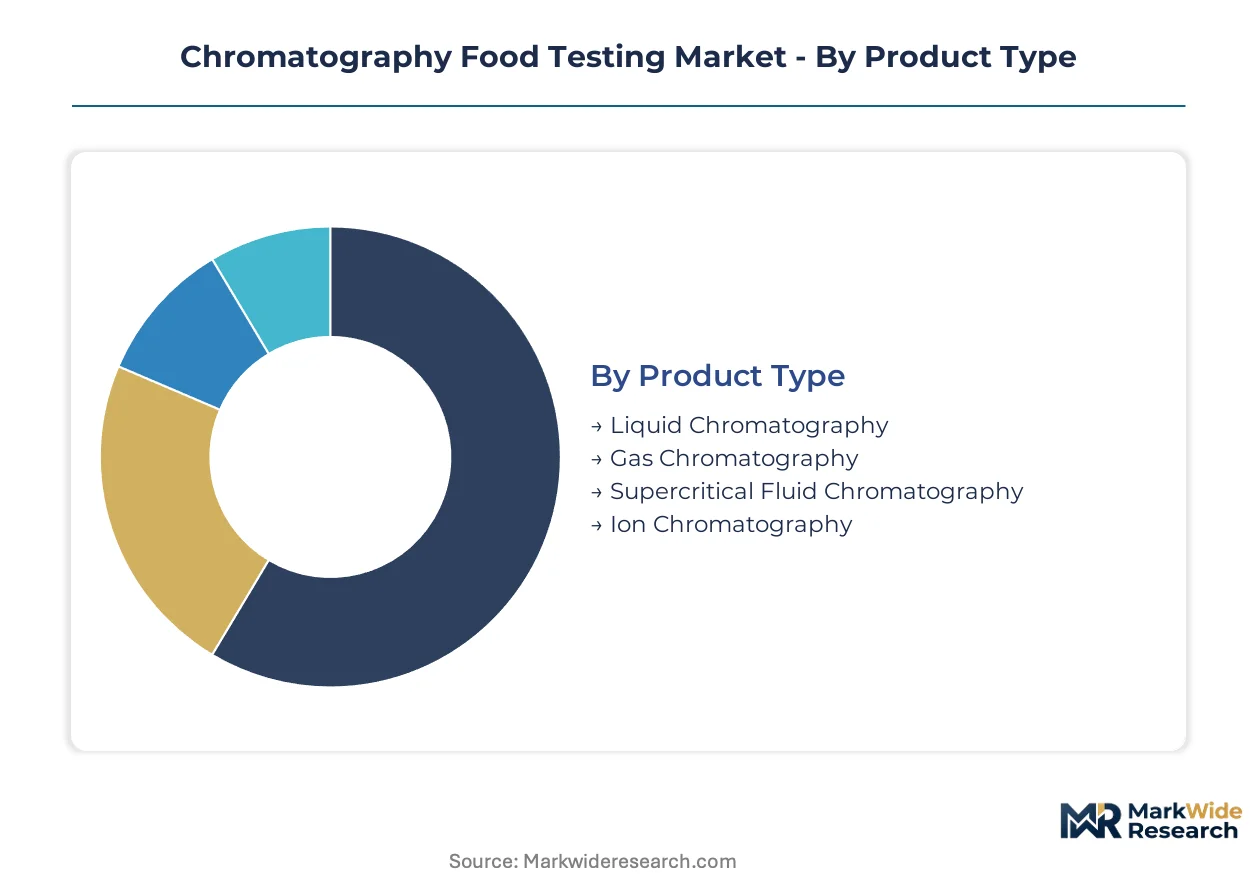
Chromatography food testing segments fragment along technical capability lines, with instrument selection directly constraining which contaminants laboratories can quantify at regulatory thresholds. Procurement decisions cascade through application requirements, end-user scale, and detection sensitivity mandates.
Product Type:
Supply concentration in key component manufacturing shapes competitive dynamics across instrument categories, with column chemistry and detector sourcing determining vendor lock-in intensity.
- Liquid Chromatography:HPLC and UHPLC platforms separate non-volatile compounds including mycotoxins, veterinary drug residues, and nutritional markers through pressurized solvent systems. German dairy manufacturers and Dutch contract laboratories drive premium instrument procurement to meet EFSA residue limit compressions under the EU Green Deal.
- Gas Chromatography:Volatile and semi-volatile compound separation occurs through heated carrier gas systems, with electron capture and flame ionization detectors enabling parts-per-billion sensitivity for pesticide and flavor profiling. French and Italian beverage producers deploy GC-olfactometry configurations for authenticity certification in premium wine and spirits categories.
- Supercritical Fluid Chromatography:CO2-based mobile phase systems enable rapid chiral separations for food additive enantiomer analysis.
- Ion Chromatography:Suppressed conductivity detection quantifies inorganic anions and cations in mineral content and adulteration screening workflows.
Liquid Chromatography absorbs the bulk of installed capacity; Gas Chromatography is expanding most quickly.
Application:
Regulatory enforcement intensity varies sharply across testing purposes, with contaminant detection commanding capital allocation priority due to non-compliance penalties.
- Food Quality Testing:Macro-nutrient quantification, moisture content verification, and shelf-life stability monitoring employ standardized HPLC methods with UV-Vis detection. Routine quality control at large-scale food manufacturers in Spain and Poland sustains mid-tier instrument demand.
- Contaminant Detection:Trace-level quantification of heavy metals, mycotoxins, and process contaminants requires mass spectrometry-coupled systems achieving parts-per-trillion sensitivity. REACH substance restrictions and FDA Food Safety Modernization Act compliance obligations force continuous platform upgrades.
- Nutritional Analysis:Vitamin, amino acid, and fatty acid profiling supports label claim verification and reformulation initiatives.
- Pesticide Residue Testing:Multi-residue panel expansion under EU Green Deal pesticide reduction targets drives quadrupole time-of-flight mass spectrometry adoption.
Contaminant Detection captures the dominant share of capital expenditure; Pesticide Residue Testing is climbing the fastest.
End User:
Customer scale and regulatory exposure determine instrument sophistication requirements, with multi-site manufacturers pursuing standardization across laboratory networks.
- Food Manufacturers:In-house quality control and regulatory pre-release testing at dairy, beverage, and processed food facilities deploy HPLC for routine screening and UHPLC for high-throughput environments. Mid-sized European manufacturers face capital intensity barriers that constrain ultra-high-performance system adoption.
- Research Laboratories:Academic and government research institutes develop novel multi-residue methods and validate column chemistries for emerging contaminants. EFSA approval timelines for novel analyte combinations extend commercialization cycles.
- Government Agencies:National reference laboratories enforce maximum residue limits and harmonize methods with Codex Alimentarius standards.
- Quality Control Laboratories:Independent testing providers serve food exporters requiring third-party certification for market access.
Food Manufacturers deploy the largest installed base; Quality Control Laboratories are gaining share fastest.
Technology:
Performance tier differentiation separates routine workflows from premium applications, with throughput acceleration justifying capital intensity at scale.
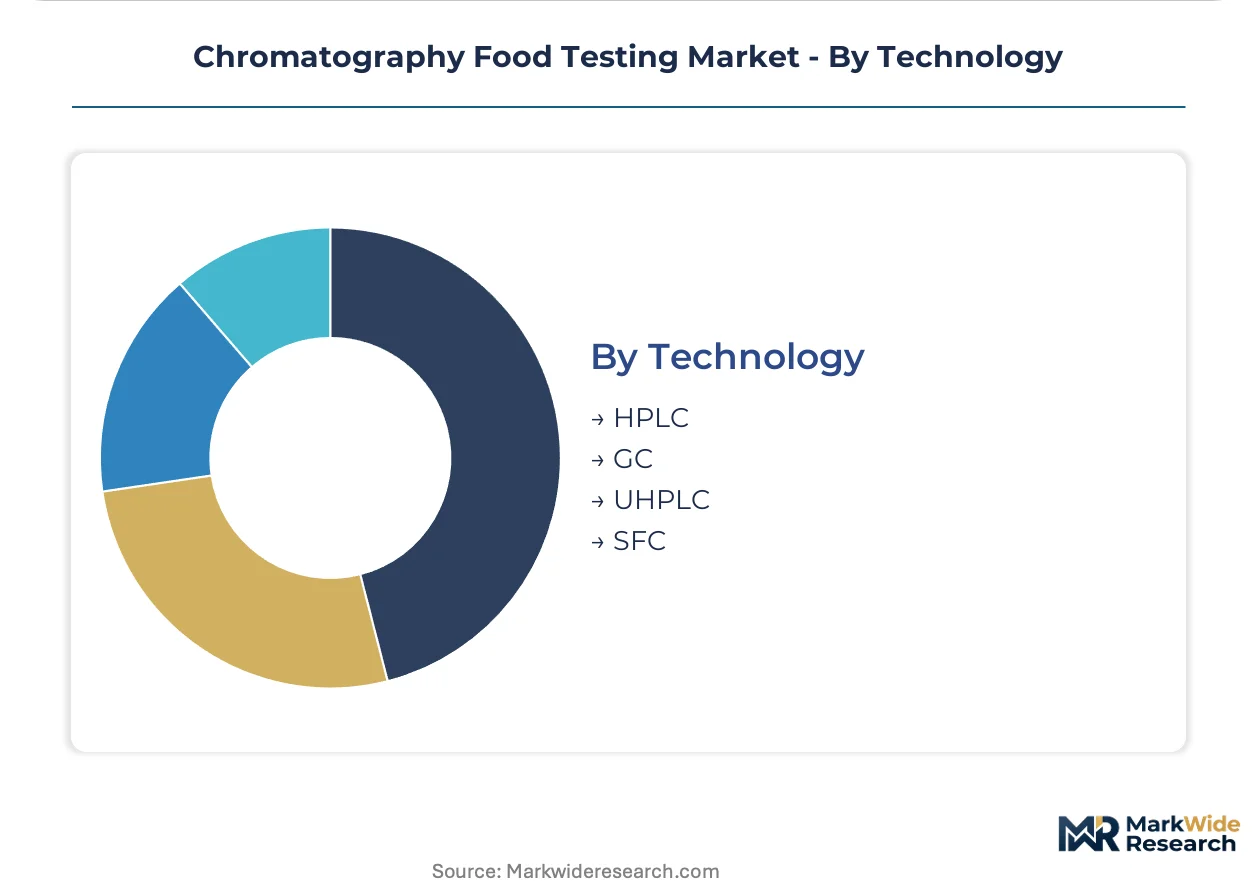
- HPLC:High-performance liquid chromatography anchors routine quality control with 30-minute run times and established method libraries. Mid-tier laboratories across Europe rely on HPLC for cost-effective compliance with legacy residue limits.
- GC:Gas chromatography systems with mass spectrometry detection dominate volatile compound analysis and fatty acid profiling in premium food authentication.
- UHPLC:Ultra-high-performance liquid chromatography compresses run times below five minutes through sub-2-micron particle columns and elevated pressure limits. German and Dutch contract laboratories adopt these systems to triple throughput without facility expansion.
- SFC:Supercritical fluid chromatography offers orthogonal selectivity for lipid and chiral compound analysis in specialized applications.
HPLC retains the largest installed base; UHPLC is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich anchors European chromatography procurement as Bavarian dairy conglomerates upgrade liquid chromatography-mass spectrometry platforms for EFSA residue compliance. German food exporters drive premium instrument adoption across the Rhine-Ruhr corridor and Hamburg port laboratories.
Germany
Dairy manufacturers in Bavaria and North Rhine-Westphalia deploy UHPLC systems for allergen verification under tightened EFSA labeling mandates. The EU Green Deal's Farm to Fork Strategy forces parts-per-trillion detection thresholds that obsolete legacy HPLC installations. Stuttgart-based precision engineering clusters supply sub-2-micron column chemistries to contract laboratories tripling throughput without facility expansion.
France
Bordeaux and Champagne wine producers adopt gas chromatography-olfactometry for volatile flavor authentication in premium export categories. ANSM enforcement of REACH substance restrictions compels pesticide residue screening upgrades at Loire Valley cooperative laboratories. Lyon food testing hubs integrate quadrupole time-of-flight configurations for multi-residue panels exceeding 500 analytes.
Netherlands
Rotterdam port laboratories handle third-party certification for re-export foodstuffs bound for Asian and Middle Eastern markets. Dutch contract testing firms in Eindhoven adopt UHPLC platforms to compress per-test economics under competitive pressure from German rivals. ECHA substance restriction updates trigger preventive instrument replacement cycles ahead of enforcement deadlines.
Italy
Parmesan and Parma ham consortia in Emilia-Romagna deploy HPLC for nutritional marker verification protecting geographic indication status. Italian beverage exporters in Piedmont face EFSA mycotoxin limit compressions requiring high-resolution accurate mass systems. Milan analytical service providers unbundle maintenance contracts from original equipment manufacturers through subscription-based remote diagnostics.
United Kingdom
London quality control laboratories serve Commonwealth food exporters navigating divergent post-Brexit residue limits. UK Food Standards Agency enforcement of retained EU law maintains chromatography sensitivity requirements at parity with continental competitors. Cambridge research institutes develop novel column chemistries for emerging contaminant detection awaiting EFSA validation timelines.
Chromatography Food Testing Market Vendor Landscape
Premium-margin players sit above commodity-margin players across detection sensitivity tiers, with mass spectrometry-coupled systems commanding pricing power at parts-per-trillion thresholds. The vendor base organizes around three strategic archetypes: diversified life science conglomerates with chromatography divisions, specialized analytical instrument pure-plays, and testing service providers with captive equipment procurement leverage. Consolidation pressure concentrates in the mid-tier HPLC segment where Chinese manufacturers displace legacy European suppliers. Dominant competitive moves include vertical integration into consumables manufacturing and geographic expansion through distribution partnerships in food-exporting economies.
Among diversified technology conglomerates, Agilent Technologies Inc. and Thermo Fisher Scientific Inc. occupy positions anchoring high-end laboratory workflows, while Eurofins Scientific exemplifies the service-provider archetype leveraging multi-site procurement scale. These three entities represent distinct competitive vectors: instrumentation manufacturing, integrated workflow solutions, and third-party testing capacity. Their positioning reflects divergent margin structures across hardware sales, recurring consumables revenue, and fee-for-service analytical contracts.
| Leading Market Players |
|---|
| Agilent Technologies Inc. |
| Eurofins Scientific |
| Thermo Fisher Scientific Inc. |
| PerkinElmer Inc. |
| SGS SA |
| Shimadzu Corporation |
| Merck KGaA |
| Bruker Corporation |
| Waters Corporation |
| Others |
Supply Flow & Price Mechanics
Multi-site food manufacturers in Germany and France concentrate procurement leverage, anchoring contract-based pricing for chromatography platforms where detection sensitivity tiers determine capital allocation thresholds.
Pricing Analysis
Value-based pricing anchors chromatography platform transactions, with buyers paying premiums tied to parts-per-trillion detection thresholds and validated uptime guarantees rather than hardware specifications alone. Three-tier pricing structure across premium, standard, and economy levels separates quadrupole time-of-flight configurations from routine HPLC systems and refurbished legacy installations. Cost compression in mid-tier HPLC segments is intensifying because Chinese manufacturers displace European suppliers with equivalent column chemistries. Small contract laboratories in Spain and Poland exhibit highest price sensitivity, while Bavarian dairy conglomerates prioritize detection capability over capital expenditure.
Supply Chain Analysis
Freight costs for sub-2-micron particle columns and mass spectrometer ion sources concentrate vulnerability in trans-Atlantic and intra-European lanes, with Stuttgart precision engineering clusters and Massachusetts detector fabrication facilities anchoring upstream supply. Manufacturing draws from Germany, Japan, and the United States for high-pressure pump assemblies, fused silica capillaries, and electron multiplier detectors. Single-source vulnerability sits with helium sourcing from US federal reserves and Algerian production for gas chromatography carrier gas. Distribution runs through authorized dealer networks serving national reference laboratories and multi-site food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mass spectrometry operator scarcity props pricing for integrated LC-MS platforms, constraining laboratory throughput expansion and sustaining premium tier margins despite hardware commoditization pressure.
For Market Incumbents: Cement column chemistry exclusivity through EFSA validation partnerships for emerging multi-residue panels, blocking Chinese manufacturers from premium tier access. Deepen backward integration into sub-2-micron particle manufacturing to capture consumables revenue from German contract laboratories tripling throughput. Biosensor-based rapid testing threatens low-sensitivity screening applications; defend position through service contract bundling with predictive maintenance analytics. For New Entrants and Emerging Players: The gap between premium quadrupole time-of-flight systems and economy-grade refurbished HPLC creates entry space for mid-performance UHPLC platforms with compressed run times. Target Italian quality control laboratories unbundling maintenance contracts from original equipment manufacturers through subscription-based remote diagnostics. Penetrate plant-based protein authentication for amino acid profiling, where method development timelines lag instrument procurement cycles. For Investors and Strategic Acquirers: The window for entry favors specialized analytical instrument pure-plays with validated column chemistries awaiting EFSA approval for novel analyte combinations. Long-term viability centers on consumables recurring revenue models rather than capital equipment sales cycles. Watch EFSA multi-residue method validation timelines as inflection indicator for column chemistry commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Column Chemistry Validation Partnership | EFSA approval for novel analyte combinations extends vendor lock-in duration at German dairy laboratories. |
| Remote Diagnostics Platform Launch | Subscription-based predictive maintenance captures revenue from Italian laboratories unbundling OEM service contracts. |
| Alternative Protein Method Development | Amino acid profiling for plant-based authentication opens white-space segment ahead of regulatory standardization. |
| Helium Recovery System Integration | Closed-loop carrier gas recycling mitigates supply volatility for French beverage GC-olfactometry installations. |
| UHPLC Throughput Acceleration Program | Dutch contract laboratories triple daily sample capacity without facility expansion capex. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with laboratory directors at German dairy manufacturers, procurement leads at French beverage conglomerates, service contract managers at Dutch contract testing firms, and EFSA regulatory affairs specialists. ECHA substance restriction updates, FDA Food Safety Modernization Act guidance documents, and EU Green Deal Farm to Fork Strategy implementation timelines provided regulatory trajectory inputs. Bottom-up instrument shipment analysis triangulated against top-down food testing laboratory capital expenditure surveys.
Segmentation granularity modeled instrument category at product-type level, application purpose at contaminant detection versus quality control distinction, end-user scale at manufacturer versus third-party laboratory split, and technology tier at HPLC versus UHPLC performance threshold. CAGRs derived from elasticity-adjusted demand curves across the projection horizon, with EFSA residue limit compression schedules and REACH substance restriction timelines as primary forecast drivers.
Inputs from EFSA method validation databases and ECHA regulatory restriction notices were available through the study window; gaps in real-time laboratory capital expenditure tracking introduce uncertainty bands around mid-tier HPLC replacement cycle timing. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and helium supply stabilization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Food Testing Services Market
Food Safety Testing
Ireland Food Testing Market
Food Safety Testing
Salmonella Testing Market
Food Safety Testing
Rapid Microbiology Testing Market
Food Safety Testing
Beverage Tester Market
Food Safety Testing
North America Consumer Product Safety Testing Market
Food Safety Testing
Water Quality Testing Market
Food Safety Testing
Food Authentication Testing Market
Food Safety Testing
Testing, Inspection, and Certification in Consumer Goods and Retail Market
Food Safety Testing
Food Pathogen Testing Market
Food Safety Testing
Global Bacteriological Testing Market
Food Safety Testing
Food Allergens and Intolerance Testing Market
Food Safety Testing
Fresh Food Residue Testing Market
Food Safety Testing
Carbohydrates Testing Services Market
Food Safety Testing
Global Food Diagnostics Market
Food Safety Testing
UK Food Testing Market