
 Rapid Microbiology Testing Market | 2026-2036
Rapid Microbiology Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Rapid Microbiology Testing Market Intelligence
Asset-light leasing models for automated microbial identification platforms is narrowing the capital barrier for mid-sized diagnostic laboratories seeking enterprise-grade throughput. Danaher Corporation leverages its Beckman Coulter Life Sciences division to sustain integrated workflow automation across clinical and pharmaceutical segments. bioMérieux SA anchors its competitive position through chromogenic media specialization and real-time pathogen detection algorithms. Thermo Fisher Scientific Inc. dominates laboratory-based deployment channels with centralized testing infrastructure that spans contract research organizations and government agencies.
Rapid microbiology testing encompasses accelerated analytical methods for detecting, enumerating, and identifying microorganisms within hours rather than days, employing technologies such as polymerase chain reaction amplification, matrix-assisted laser desorption ionization time-of-flight mass spectrometry, and ATP bioluminescence with sensitivity thresholds reaching single-colony-forming-unit detection. These systems serve critical industrial functions including pharmaceutical sterility assurance, foodborne pathogen surveillance, and clinical sepsis diagnostics where delayed results elevate mortality risk or trigger regulatory non-compliance. Polymerase chain reaction systems command premium positioning due to their nucleic acid specificity and expanding multiplex panel capabilities for antimicrobial resistance gene profiling. Immunoassay kits retain volume leadership in food safety applications where lateral flow simplicity supports high-throughput screening at processing facility loading docks. Mass spectrometry platforms represent the fastest-expanding margin pool as pharmaceutical manufacturers adopt MALDI-TOF for rapid microbial identification in quality control release testing.
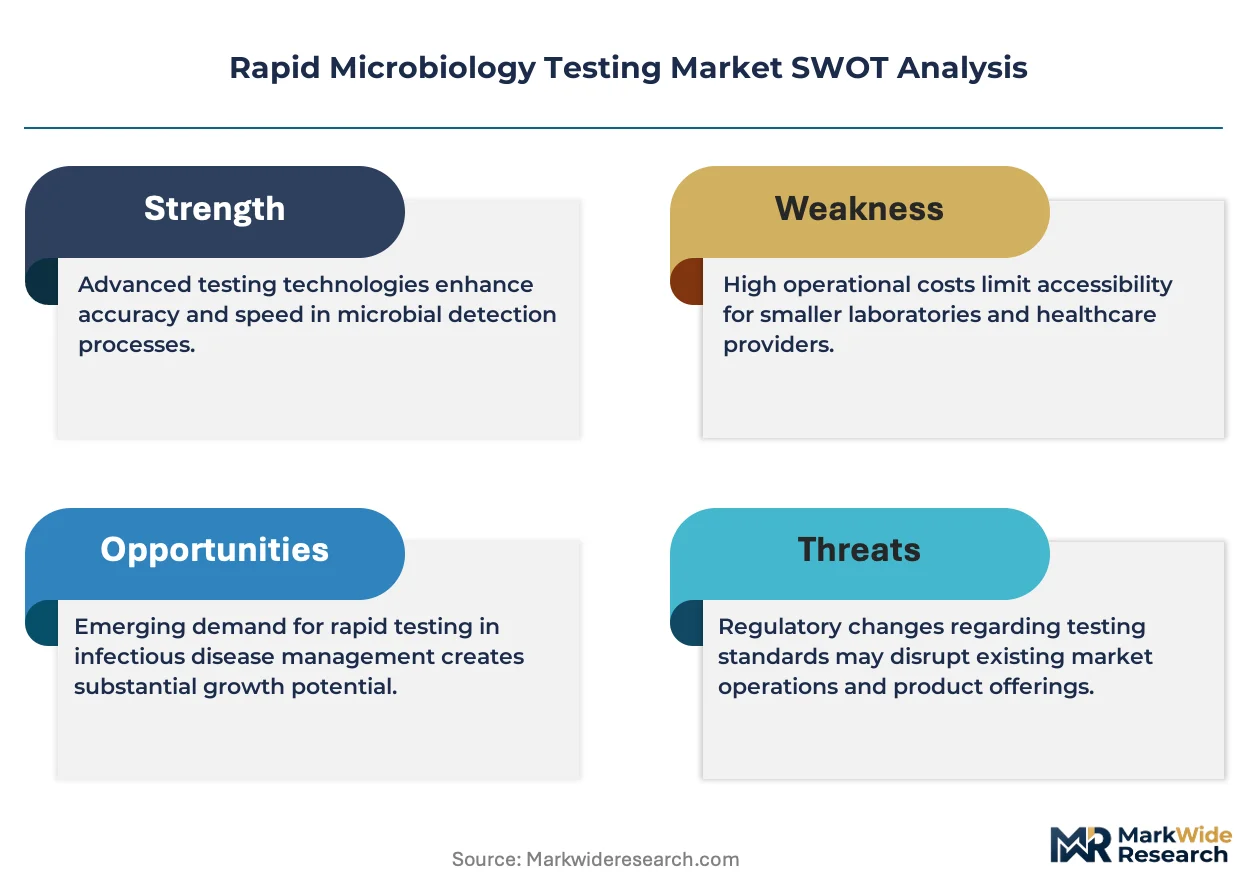
The FDA enforces rapid sterility test validation under USP 71 and USP 1223 guidelines, compelling manufacturers to demonstrate equivalence to compendial methods before product release. EPA protocols for drinking water microbial monitoring and EMA's Annex 1 revision on sterile manufacturing create overlapping compliance obligations that expand instrument qualification service revenues. ISO 17025 accreditation requirements for diagnostic laboratories further standardize performance benchmarks across regional markets. Stakeholders must monitor how harmonization between FDA breakthrough device pathways and EMA's qualification opinion process for novel rapid methods reshapes competitive access timelines and R&D prioritization.
Market Dynamics
Pharmaceutical sterility assurance requirements are compressing microbial detection timelines from days to hours, forcing quality control departments to abandon traditional culture-based methods in favor of nucleic acid and mass spectrometry platforms that satisfy FDA and EMA release testing mandates.
Growth Catalysts
- Annex 1 Revision:EMA's sterile manufacturing guidelines now mandate rapid microbial methods for environmental monitoring, compelling European biopharmaceutical facilities to accelerate validation of alternative sterility tests.
- Sepsis Mortality Pressure:Clinical diagnostic laboratories are adopting MALDI-TOF and PCR systems to reduce bloodstream pathogen identification from 48 hours to under 90 minutes, directly addressing ICU mortality reduction targets.
- ATP Bioluminescence:Food processing facilities at loading docks now deploy portable luminometers for real-time surface hygiene verification, replacing delayed plate count methods that allowed contaminated batches to enter distribution.
Market Restraints
- Validation Cost Burden:USP 1223 compendial equivalence studies require 12-18 month timelines and specialized regulatory consulting, creating capital barriers for mid-sized diagnostic laboratories.
- Reagent Supply Concentration:Polymerase chain reaction master mixes and MALDI-TOF calibration standards concentrate among three specialty chemical suppliers, exposing buyers to input volatility and qualification delays.
- Culture Method Lock-In:Pharmacopeial monographs still reference colony-forming unit enumeration as the legal standard, forcing parallel method operation during rapid technology transition periods.
Strategic Opportunities
- Point-of-Care Expansion:Lateral flow immunoassays for respiratory pathogen panels remain underpenetrated in rural urgent care settings, creating channel whitespace for decentralized testing infrastructure.
- Antimicrobial Resistance Surveillance:Multiplex PCR panels detecting carbapenemase and ESBL genes are converging with hospital infection control databases, enabling real-time resistance mapping for pharmacy stewardship programs.
- ISO 17025 Accreditation Services:Diagnostic laboratory certification mandates in Germany and France are generating recurring revenue streams for instrument qualification and proficiency testing providers.
Industry Challenges
- Bioinformatics Talent Scarcity:Mass spectrometry platforms require skilled operators capable of spectral library curation and algorithm validation, creating hiring bottlenecks for clinical microbiology departments.
- Legacy LIMS Integration:Automated microbial identification systems face interoperability friction with decade-old laboratory information management systems, forcing costly middleware development or full-stack replacement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rapid Microbiology Testing Market |
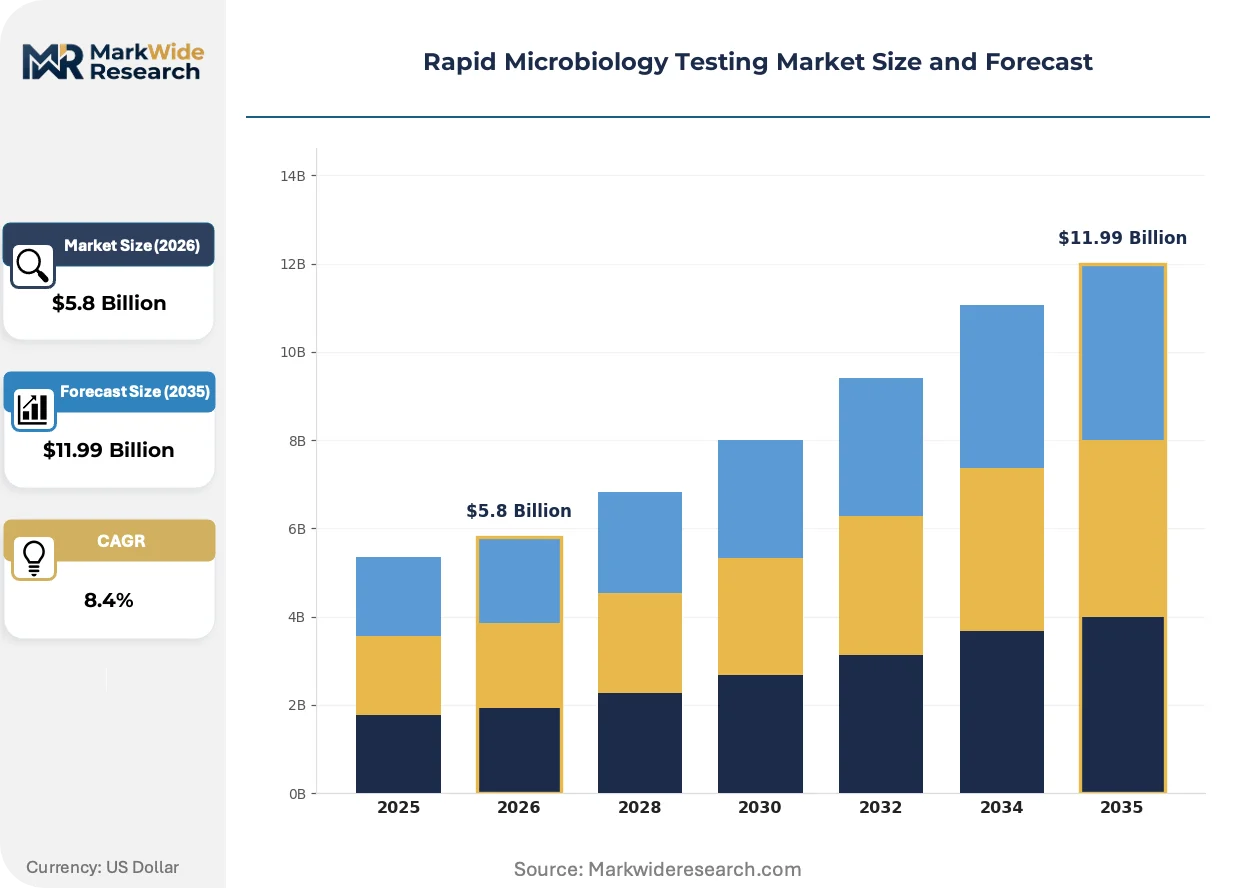
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.99 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Microbial Identification, Rapid Culture Methods, Polymerase Chain Reaction, Immunoassay Kits, Mass Spectrometry, Chromogenic Media Application: Pharmaceutical Quality Control, Food Safety, Water Testing, Clinical Diagnostics, Environmental Monitoring, Biotechnological Research End User: Contract Research Organizations, Diagnostic Laboratories, Food Processing Facilities, Academic Research Institutes, Biopharmaceutical Manufacturers, Government Agencies Deployment: Laboratory-Based, Portable Devices, Point-of-Care Testing, On-Site Testing, Remote Monitoring, Centralized Testing |
| Companies Covered | bioMérieux SA, Becton Dickinson and Company, Danaher Corporation, Abbott Laboratories, Thermo Fisher Scientific Inc., Merck KGaA, Sartorius AG, Bruker Corporation, QuidelOrtho Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rapid Microbiology Testing Market Strategic Shifts & Innovations
Next-generation sequencing and artificial intelligence-powered spectral analysis are collapsing the cost and time boundaries between research-grade microbial characterization and routine industrial quality control, reshaping competitive positioning across pharmaceutical, clinical, and food safety verticals.
Matrix-assisted laser desorption ionization time-of-flight mass spectrometry is collapsing the turnaround time for microbial identification in pharmaceutical release testing. Quality control laboratories at biologics manufacturing sites now deploy these platforms for same-day batch clearance decisions. The technology is collapsing the economic viability of extended incubation protocols that previously tied up inventory for 14-day sterility holds.
REACH chemical registration requirements and EMA's quality by design framework are tightening specifications for chromogenic media components used in rapid detection assays. Manufacturers must now document supply chain provenance for enzyme substrates and selective agents. Pharmaceutical contract manufacturers in Germany and Switzerland are responding by qualifying dual-source media suppliers and implementing incoming raw material identity testing.
Diagnostic procurement committees now unbundle instrument placement from reagent supply agreements, reversing decade-old bundled leasing structures. Hospital laboratory administrators negotiate separate capital acquisition and consumable sourcing contracts to optimize total cost of ownership. This pattern is most visible in French and Italian public health systems where centralized purchasing authorities mandate competitive tendering for each cost layer.
Rapid Microbiology Testing Market Segmentation
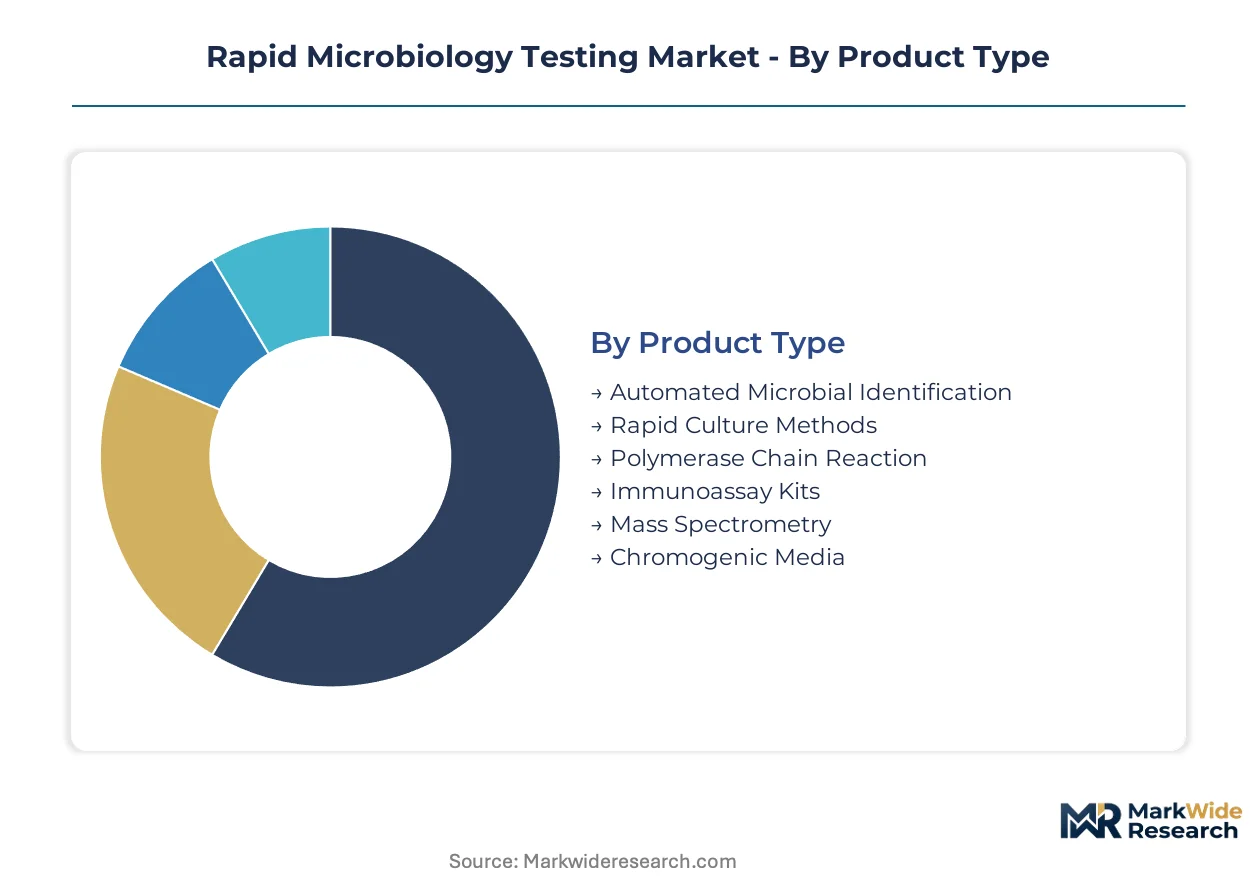
Technology maturity and regulatory acceptance create divergent commercial trajectories across product categories. Application-specific validation requirements fragment demand patterns, while end-user consolidation in biopharmaceutical manufacturing reshapes procurement concentration.
Product Type:
Mature automated platforms anchor routine throughput, while emerging molecular methods capture the fastest expansion in pharmaceutical release testing.
- Automated Microbial Identification:Integrated colony imaging systems with AI-powered morphometric analysis now dominate high-volume pharmaceutical QC labs. Demand concentrates at biologics manufacturing sites in Germany and Switzerland where FDA-aligned validation protocols compress batch release timelines.
- Mass Spectrometry:MALDI-TOF platforms deliver species-level identification within minutes through protein fingerprint matching. Biopharmaceutical manufacturers in Basel and Boston clusters are displacing biochemical panels for rapid sterility confirmation, though spectral library maintenance creates operational complexity.
- Polymerase Chain Reaction:Multiplex nucleic acid amplification systems target antimicrobial resistance gene profiling in clinical sepsis workflows.
- Immunoassay Kits:Lateral flow and ELISA formats retain food safety screening dominance at processing facility loading docks.
- Rapid Culture Methods:Accelerated growth media with fluorescent indicators shorten time-to-result for environmental monitoring applications.
- Chromogenic Media:Enzyme-substrate formulations enable visual pathogen detection without secondary confirmation steps.
Automated microbial identification handles the majority of throughput; mass spectrometry is gaining share fastest in pharmaceutical QC release testing.
Application:
Regulatory stringency varies sharply across use cases, with sterile manufacturing mandates driving premium technology adoption.
- Pharmaceutical Quality Control:Sterility testing, environmental monitoring, and raw material release programs now require rapid methods under EMA Annex 1 revisions. Facilities in Ireland and Germany are validating ATP bioluminescence and PCR alternatives to 14-day compendial incubation.
- Clinical Diagnostics:Bloodstream pathogen identification demands sub-90-minute turnaround to meet ICU mortality reduction targets. MALDI-TOF and multiplex PCR systems are displacing conventional blood culture workflows in tertiary hospitals across France and the United Kingdom.
- Food Safety:Pathogen screening at slaughterhouses and dairy processing plants relies on immunoassay and molecular methods for same-day clearance decisions.
- Water Testing:Drinking water microbial monitoring employs ATP bioluminescence for real-time distribution system surveillance.
- Environmental Monitoring:Cleanroom and controlled environment testing tracks viable particle counts using rapid air sampling technologies.
- Biotechnological Research:Cell culture contamination detection supports bioprocess development timelines in academic and commercial labs.
Pharmaceutical quality control commands the highest instrument margins; clinical diagnostics is expanding most quickly as sepsis mortality protocols tighten.
End User:
Capital deployment capacity and validation expertise separate enterprise adopters from price-sensitive volume buyers.
- Biopharmaceutical Manufacturers:In-house QC departments at monoclonal antibody and vaccine producers drive enterprise instrument placements. Sites in Massachusetts and Bavaria are consolidating onto integrated MALDI-TOF and automated identification platforms to satisfy FDA pre-approval inspection readiness.
- Contract Research Organizations:Multi-client testing labs require flexible method portfolios spanning pharmaceutical, food, and environmental matrices. Charles River and Eurofins facilities are standardizing on vendor-agnostic data formats to streamline client reporting.
- Diagnostic Laboratories:Hospital-affiliated and independent clinical labs balance throughput demands against reimbursement constraints for rapid pathogen identification.
- Food Processing Facilities:In-house microbiology labs at meat and dairy processors prioritize portable ATP systems for hygiene verification.
- Government Agencies:Public health laboratories and reference centers maintain compendial method capability alongside rapid method validation.
- Academic Research Institutes:University core facilities support grant-funded method development with lower utilization requirements.
Biopharmaceutical manufacturers absorb the largest capital equipment share; contract research organizations are climbing fastest on test volume expansion.
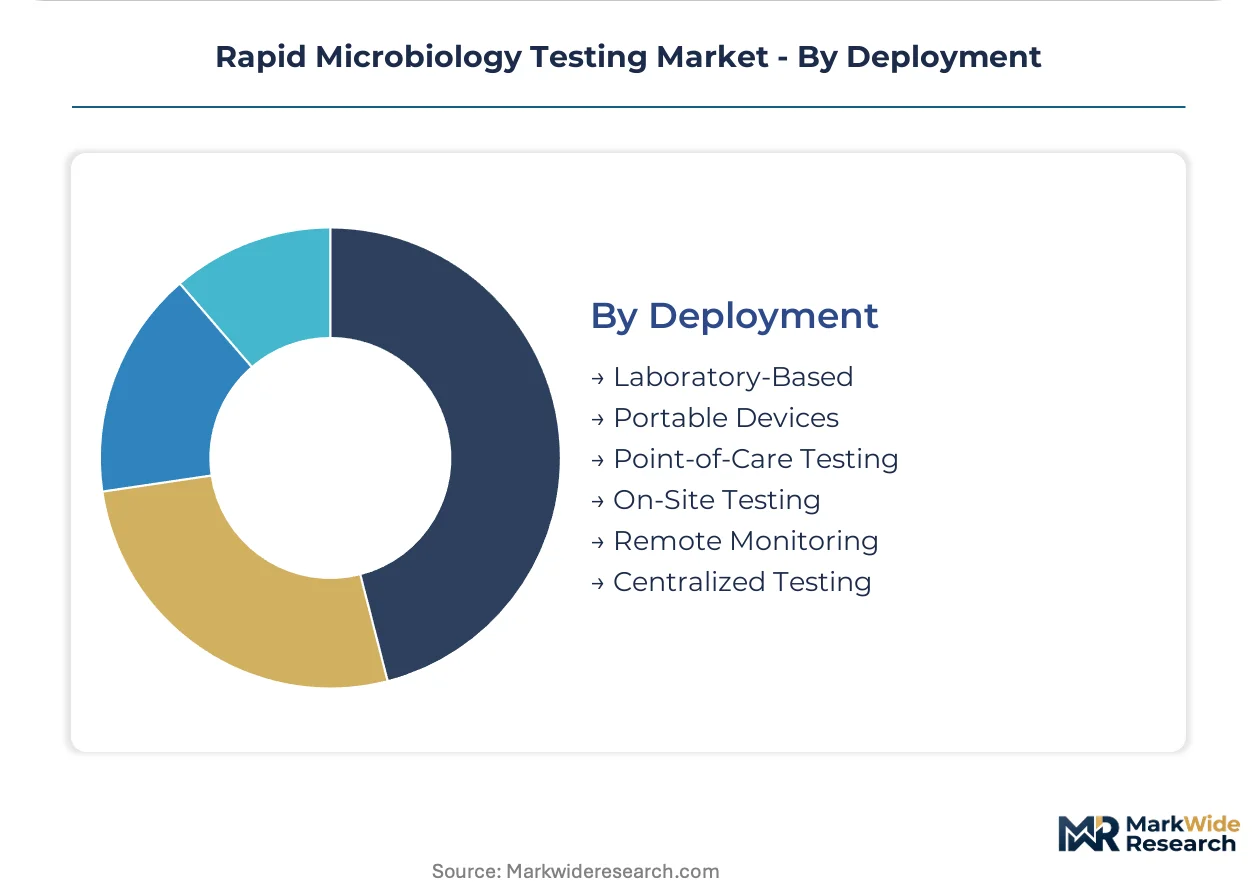
Deployment:
Physical infrastructure requirements and regulatory oversight intensity shape site-level technology selection.
- Laboratory-Based:Centralized facilities with controlled environmental conditions host high-complexity mass spectrometry and automated identification systems. These deployments dominate pharmaceutical release testing where ISO 17025 accreditation and FDA inspection readiness are mandatory.
- Point-of-Care Testing:Decentralized respiratory and sepsis pathogen detection in emergency departments and urgent care clinics is accelerating lateral flow and cartridge-based molecular adoption. Rural healthcare networks in Spain and Italy are piloting these systems to reduce centralized lab referral delays.
- Portable Devices:Handheld luminometers and field PCR units support environmental and food safety screening outside fixed laboratory infrastructure.
- On-Site Testing:Processing facility loading docks deploy rapid methods for incoming raw material and finished product verification.
- Remote Monitoring:Networked sensors enable continuous environmental surveillance in pharmaceutical manufacturing suites.
- Centralized Testing:High-volume reference laboratories aggregate specimens from distributed collection points for economies of scale.
Laboratory-based deployment retains the dominant installed base; point-of-care testing shows the steepest expansion trajectory as decentralized diagnostic infrastructure spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in rapid microbiology testing equipment tilt toward net-importing jurisdictions with dense pharmaceutical manufacturing footprints. Germany and the United States absorb the largest absolute import volumes of automated microbial identification platforms. Switzerland and Ireland run substantial per-capita equipment trade deficits as biopharmaceutical contract manufacturing concentrates in these territories.
United States
FDA pre-approval inspection readiness drives enterprise instrument placements at monoclonal antibody manufacturing sites. The agency's updated guidance on rapid sterility testing methods compresses validation timelines for domestic manufacturers. Massachusetts and North Carolina biotech clusters are consolidating onto integrated MALDI-TOF platforms to satisfy batch release mandates.
Germany
EMA-aligned regulatory consulting clusters in Frankfurt and Munich support biopharmaceutical validation workflows for Annex 1 compliance. The country's national pharmaceutical regulator enforces sterile manufacturing guidelines that mandate rapid microbial methods for environmental monitoring. Bavarian biologics facilities are validating ATP bioluminescence alternatives to 14-day compendial incubation.
Switzerland
Swissmedic oversight of sterile manufacturing creates premium demand for mass spectrometry platforms in quality control release testing. Basel's pharmaceutical manufacturing corridor anchors European demand for rapid microbial identification systems. Contract manufacturers here are qualifying dual-source chromogenic media suppliers under REACH chemical registration requirements.
United Kingdom
NHS sepsis mortality reduction targets accelerate MALDI-TOF adoption in tertiary hospital laboratories. The Medicines and Healthcare products Regulatory Agency aligns with FDA breakthrough device pathways for novel rapid methods. London and Cambridge diagnostic networks are deploying multiplex PCR systems to reduce bloodstream pathogen identification timelines.
France
ANSM oversight of in vitro diagnostics shapes procurement patterns for hospital-affiliated clinical laboratories. Centralized purchasing authorities mandate competitive tendering for instrument and consumable contracts separately. Paris and Lyon public health systems are piloting point-of-care respiratory pathogen panels in rural urgent care settings.
Rapid Microbiology Testing Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in reagents and calibration standards. The vendor base separates into three strata: diversified life science conglomerates with full workflow automation portfolios, precision instrument manufacturers with spectral analysis specialization, and niche consumable suppliers with chromogenic media expertise. Consolidation pressure runs highest at the mid-tier where scale disadvantages compound against integrated competitors. Dominant competitive moves include backward integration into captive reagent production and technology licensing partnerships to secure distribution in EMA-aligned regulatory environments.
Among diversified life science conglomerates, Danaher Corporation and Thermo Fisher Scientific Inc. exemplify the platform-integrator archetype with cross-segment workflow automation capabilities. bioMérieux SA occupies a distinct position as a European specialist anchoring competitive position through chromogenic media depth and real-time detection algorithms. These three entities represent the structural poles around which mid-sized competitors must differentiate or accept sub-scale procurement exposure.
| Leading Market Players |
|---|
| bioMérieux SA |
| Becton Dickinson and Company |
| Danaher Corporation |
| Abbott Laboratories |
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Sartorius AG |
| Bruker Corporation |
| QuidelOrtho Corporation |
| Others |
Cost & Logistics Intelligence
The Rhine-Alpine freight corridor's cost dynamics compress margins for chromogenic media shipments moving from Basel to Bavarian biologics facilities, amplifying price differentiation between enterprise-grade MALDI-TOF platforms and mid-tier automated identification systems while concentrating procurement leverage among consolidated biopharmaceutical manufacturers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in this market. Premium tiers command certification-grade positioning for FDA pre-approval inspection readiness, while economy tiers serve food processing facilities with portable ATP systems. Cost compression in the standard tier intensifies because diagnostic procurement committees now unbundle instrument placement from reagent supply agreements. Hospital laboratory administrators in French public health systems demonstrate highest price sensitivity through competitive tendering mandates, whereas Swiss contract manufacturers absorb premium pricing for Swissmedic-aligned validation protocols.
Supply Chain Analysis
Export control restrictions on spectrometer laser components and nucleic acid amplification thermal cyclers limit flows from United States and German precision instrument manufacturers to certain jurisdictions. Manufacturing concentrates in Germany, Switzerland, and the United States for automated identification platforms and MALDI-TOF systems. Polymerase chain reaction master mixes and chromogenic enzyme substrates draw from specialty chemical suppliers in France and the Netherlands. Single-source vulnerability in MALDI-TOF calibration standards exposes buyers to qualification delays. Distribution runs through authorized distributor networks serving biopharmaceutical clusters in Basel, Boston, and Bavaria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as biopharmaceutical manufacturers consolidate quality control departments onto integrated platform vendors, fragmenting procurement access for mid-tier instrument suppliers.
For Market Incumbents: Pre-empt displacement by multiplex PCR panels through backward integration into captive chromogenic media production and spectral library curation services. Anchor platform stickiness via ISO 17025 accreditation support for German diagnostic laboratories facing EMA Annex 1 compliance deadlines. Counter bioinformatics talent scarcity with automated algorithm validation tools that reduce operator skill requirements.
For New Entrants and Emerging Players: Build out point-of-care respiratory pathogen testing infrastructure in rural Spanish and Italian urgent care networks where centralized lab referral delays create channel whitespace. Target lateral flow immunoassay manufacturing partnerships with food processing facilities seeking loading dock hygiene verification. Pursue antimicrobial resistance surveillance database integration as the primary go-to-market angle for hospital infection control departments.
For Investors and Strategic Acquirers: Niche consumable specialists with REACH-compliant chromogenic media formulations and dual-source qualification capabilities present the most defensible acquisition profile. Long-term viability hinges on recurring revenue streams from reagent supply rather than one-time instrument placements. Monitor harmonization progress between FDA breakthrough device pathways and EMA qualification opinion processes as the critical inflection signal for competitive access timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough device designation compresses validation timelines for alternative sterility methods. |
| Backward Integration | In-house chromogenic media production secures supply chain provenance documentation under REACH requirements. |
| Platform Integration | AI-powered morphometric analysis modules bridge legacy LIMS systems with automated identification workflows. |
| Strategic Partnership | Hospital system partnerships in France and Italy unlock point-of-care testing deployment at rural urgent care clinics. |
| Acquisition of Specialist Firm | Spectral library curation services address bioinformatics talent scarcity in clinical microbiology departments. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with regulatory affairs leads at biopharmaceutical manufacturers, quality control directors at contract research organizations, hospital laboratory administrators, and chromogenic media procurement specialists; and secondary validation against FDA 510(k) filings, EMA qualification opinion documents, ISO 17025 accreditation registries, and Swissmedic sterile manufacturing inspection reports. Bottom-up instrument placement tallies and top-down reagent consumption estimates were triangulated to derive market sizing.
Forecast inputs span technology maturity curves, regulatory acceptance timelines, and end-user consolidation patterns across the projection horizon. Segmentation dimensions modeled include product type, application vertical, end-user category, and deployment mode. CAGRs were derived from fitted growth curves calibrated to historical adoption rates of nucleic acid amplification and mass spectrometry platforms. Industry-specific inputs incorporate EMA Annex 1 compliance deadlines and NHS sepsis mortality reduction targets.
Stress conditions across reagent supply concentration, validation timeline compression, and reimbursement rate volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory harmonization progress and technology substitution elasticities. Material shifts in FDA-EMA rapid method approval alignment or REACH chemical registration enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Chromatography Food Testing Market
Food Safety Testing
US Legionella Testing Market
Food Safety Testing
Global Meat Speciation Testing Market
Food Safety Testing
Screening Equipment Market
Food Safety Testing
Food Allergens and Intolerance Testing Market
Food Safety Testing
Food Authentication Testing Market
Food Safety Testing
Middle East and Africa Food Safety Testing Market
Food Safety Testing
Global Inline Metal Detector Market
Food Safety Testing
Food Testing Kits Market
Food Safety Testing
Food Allergen Testing Market
Food Safety Testing
Dairy Testing Services Market
Food Safety Testing
Mycotoxin Testing Market
Food Safety Testing
Meat Species Identification Kits Market
Food Safety Testing
High-Throughput Food Allergen Screening Test Instruments Market
Food Safety Testing
Inline Beverage Gas and Microbial Load Monitoring Test Systems Market
Food Safety Testing
Europe Food Safety Testing Market