
 Meat Testing Market | 2026-2036
Meat Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Meat Testing Market Intelligence
The ISO/IEC 17025 accreditation requirement for laboratory competence is unwinding the historical reliance on less-formal internal quality checks. Eurofins leverages its extensive network of accredited labs to offer a broad testing portfolio across multiple geographies. Mérieux NutriSciences specializes in microbiological and chemical analysis, while Neogen Corporation competes with rapid diagnostic kits for on-site use in processing plants.
Meat testing is the analytical process of verifying the safety, quality, and authenticity of meat products. It employs methods like Polymerase Chain Reaction (PCR) to identify specific pathogen DNA, ensuring products are free from contaminants like E. coli and Salmonella. The pathogen detection segment commands the largest share of testing parameters due to stringent food safety regulations. Meat authenticity testing, however, is a high-growth area, driven by concerns over species adulteration and religious certification requirements.
Regulatory frameworks established by the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) define mandatory testing protocols for pathogens. China's State Administration for Market Regulation (SAMR) enforces strict import testing, shaping market access for international suppliers. Consequently, a key strategic decision for processors and labs is whether to centralize advanced testing capabilities or to decentralize screening with rapid, on-site technologies.
Market Dynamics
The professionalization of food safety assurance, driven by stringent regulatory frameworks, is the central force shaping the meat testing market. A structural transition is underway from informal internal checks to mandatory, third-party-verified testing performed by ISO/IEC 17025 accredited laboratories.
Growth Catalysts
- Chinese Regulations:China's SAMR enforces strict testing on meat imports, requiring international suppliers to validate products against local standards. This mandate directly stimulates demand for accredited testing services.
- Rapid Diagnostic Adoption:Food processing plants are increasingly using technologies like PCR for faster pathogen detection. This allows for quicker quarantine and release of products, improving operational efficiency.
- Demand for Authenticity:Consumer and regulatory pressure for meat authenticity, driven by concerns over species adulteration and religious certifications like halal, is expanding the market beyond just safety testing.
Market Restraints
- High Capital Costs:Establishing laboratories compliant with the ISO/IEC 17025 standard requires significant investment in advanced analytical equipment and infrastructure.
- Technical Limitations:The turnaround time for complex analyses, such as speciation or veterinary drug residue testing, can create bottlenecks in high-volume meat processing operations.
- Skilled Labor Scarcity:A limited global pool of trained microbiologists and technicians capable of operating sophisticated analytical instruments constrains laboratory capacity expansion.
Strategic Opportunities
- On-Site Testing in Emerging Markets:Expanding rapid, on-site testing solutions in Southeast Asian and Latin American markets, where meat production is industrializing, presents a significant growth avenue.
- Multiplex Assay Development:Creating advanced multiplex PCR kits that can simultaneously screen for multiple pathogens and common species adulterants offers a clear value proposition for efficiency.
- Integrated Service Platforms:Developing digital platforms that link on-site screening data with centralized lab confirmations provides processors a unified quality dashboard, creating a high-value service model.
Industry Challenges
- Protocol Harmonization:A lack of globally harmonized testing methods for new contaminants and allergens creates compliance ambiguity for companies exporting to multiple regions with different standards.
- Technician Skill Gaps:The industry faces a shortage of personnel trained in both molecular biology techniques and the specifics of food safety regulations, particularly in developing nations.
- Data System Integration:Integrating disparate data from on-site rapid tests and central lab information management systems into a single, auditable record poses a considerable IT challenge for processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meat Testing Market |
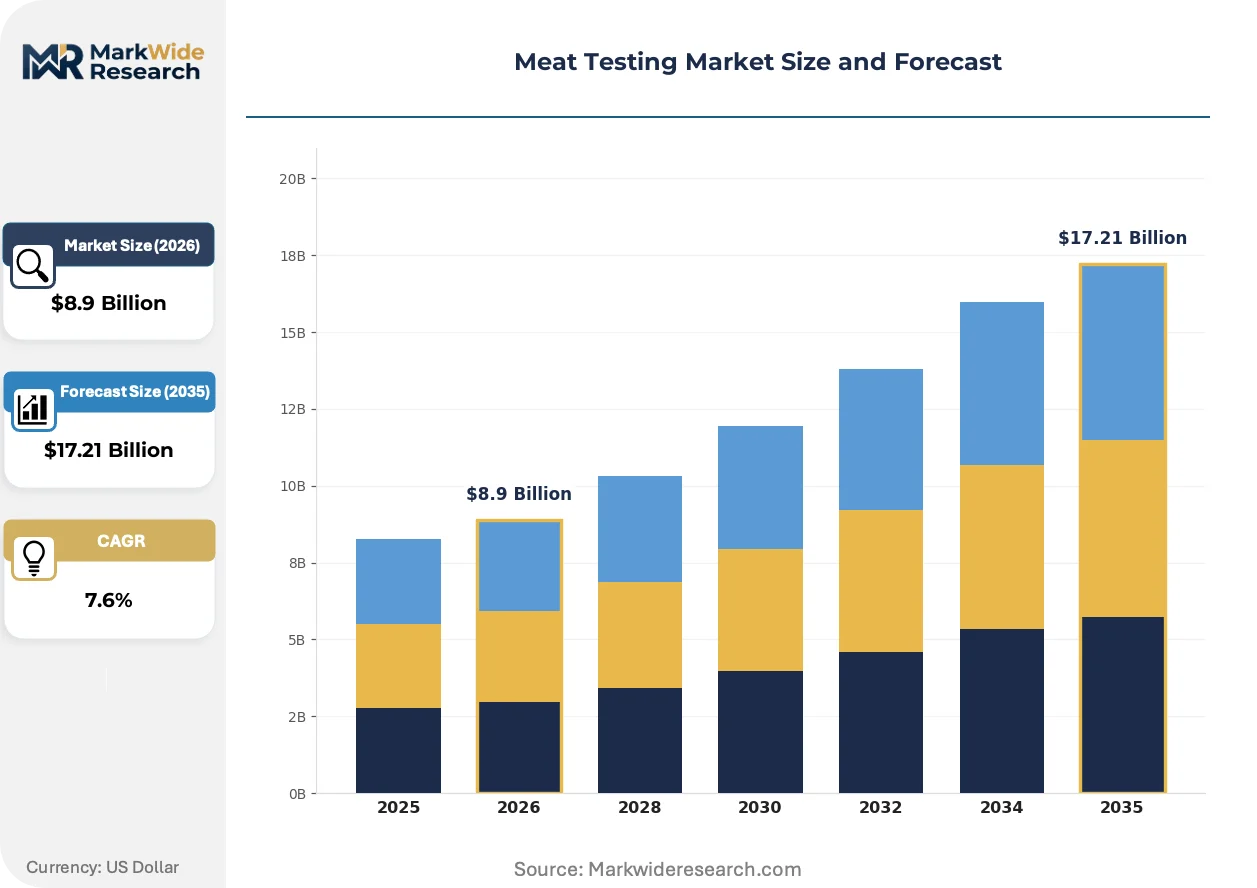
| Market Size in 2026 | $8.9 Billion |
| Market Size in 2035 | $17.21 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spectrometers, Chromatographs, PCR Systems, Immunoassay Kits, Biosensors Testing Parameter: Pathogen Detection, Hormone Residues, Antibiotic Residues, Meat Authenticity, Nutritional Analysis End User: Food Processing Plants, Quality Control Laboratories, Regulatory Authorities, Meat Packers Distribution Channel: Direct Sales, Online Platforms, Distributors, OEMs |
| Companies Covered | SGS, Eurofins, Bureau Veritas, Intertek, ALS Limited, Mérieux NutriSciences, TUV SUD, Neogen Corporation, AsureQuality, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meat Testing Market Strategic Shifts & Innovations
The market's evolution is defined by a technological push toward decentralization, moving analytical capabilities from remote laboratories closer to the point of production. This enables a more proactive and responsive approach to quality and safety management within the meat supply chain.
Rapid diagnostic technologies, including lateral flow assays and portable PCR systems, offer on-site screening capabilities. Meat processors adopt these tools for preliminary checks on incoming raw materials and in-process samples. This adoption is bifurcating the market into rapid on-site screening and centralized lab analysis for regulatory confirmation.
Europe's General Food Law establishes a framework emphasizing traceability and operator responsibility for safety. This regulation compels processors to implement testing protocols from farm to final product. The pathogen detection segment is most affected, requiring more frequent analysis and documentation throughout the supply chain.
A definitive shift is occurring from ad-hoc sample testing toward managed service contracts for quality control. In this model, third-party labs manage the entire testing regimen, including sampling and data analytics, displacing transactional services. The trend is most prominent in North America and Europe, where processors seek to standardize quality and reduce overhead.
Meat Testing Market Segmentation
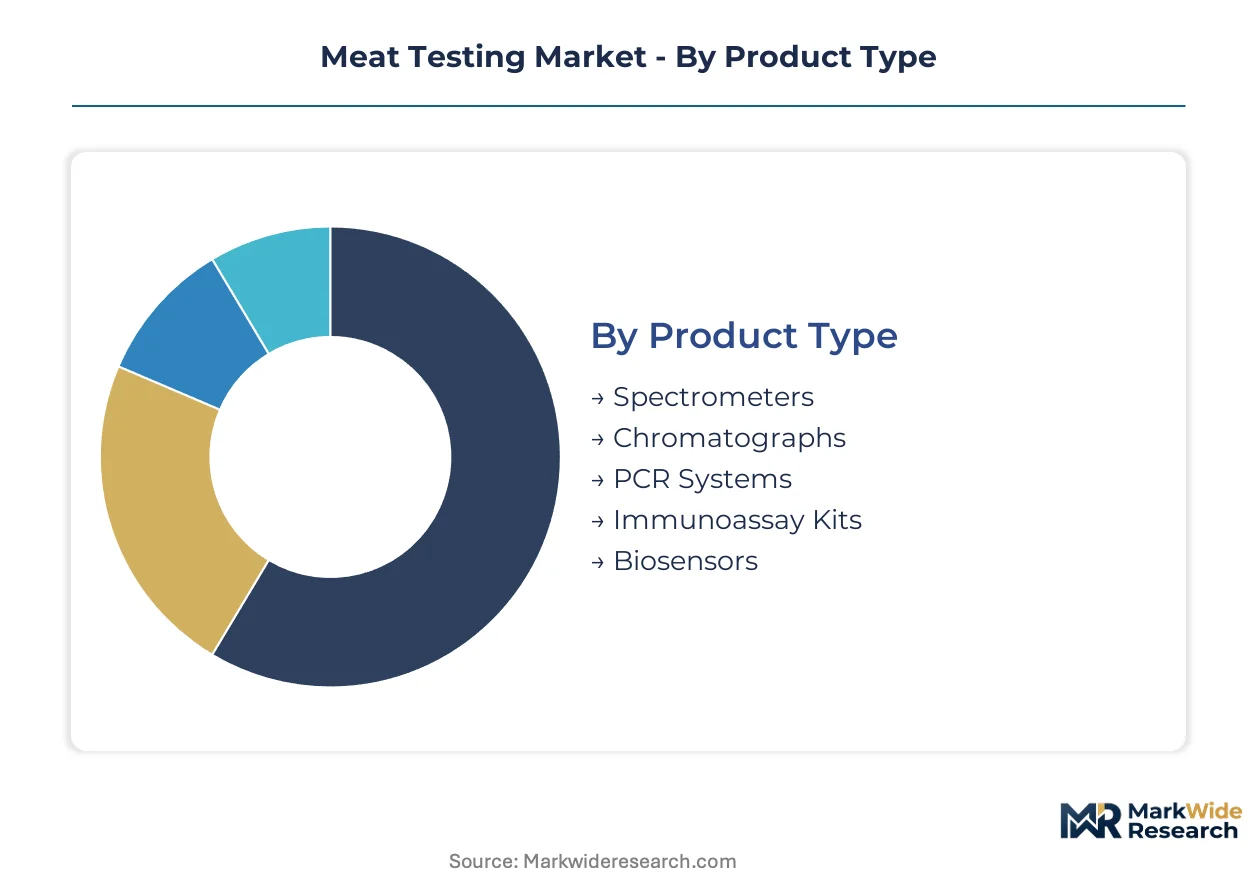
The meat testing market dissects into distinct segments based on the analytical tools employed, the specific parameters examined, the operational end-users, and the distribution routes for testing services. This segmentation clarifies where value creation occurs and how different market participants engage with evolving regulatory demands.
Product Type:
Margin pools within product types are often found in sophisticated analytical instruments requiring specialized reagents and technical expertise for operation and maintenance.
- Spectrometers:These instruments analyze light absorption or emission to identify and quantify chemical components in meat samples, often used for nutritional profiling or residue detection.
- Chromatographs:Employing techniques like GC-MS and LC-MS, these systems separate and identify complex mixtures, providing precise quantification of veterinary drug residues or contaminants. Demand concentrates across European and North American quality control labs due to stringent residue limits.
- PCR Systems:Polymerase Chain Reaction technology amplifies specific DNA sequences for rapid and highly sensitive detection of pathogens like Salmonella or E. coli. Food processing plants in China and the United States drive demand for faster, on-site pathogen screening capabilities.
- Immunoassay Kits:These kits utilize antibody-antigen reactions for quick, qualitative or semi-quantitative detection of allergens, hormones, or antibiotics.
- Biosensors:Devices integrating biological recognition elements with transducers, offering real-time or near real-time detection of specific analytes directly in meat matrices.
The dominant share belongs to PCR Systems, while Immunoassay Kits are closing the gap fastest.
Testing Parameter:
The application of various testing parameters directly addresses specific safety, quality, and regulatory compliance requirements within the meat supply chain.
- Pathogen Detection:This segment focuses on identifying harmful microorganisms such as E. coli, Salmonella, and Listeria through methods like PCR. Stringent regulations from the US FDA and European EFSA mandate comprehensive pathogen analysis, especially in raw meat products.
- Hormone Residues:Testing for hormone residues ensures compliance with regulations prohibiting or limiting growth-promoting hormones in livestock, particularly relevant in European markets.
- Antibiotic Residues:This analysis detects residual antibiotics in meat, preventing their presence in human food and addressing concerns about antimicrobial resistance.
- Meat Authenticity:This parameter verifies the species origin of meat products and detects adulteration, driven by consumer concerns and religious certifications like halal. Regulatory bodies like China's SAMR increasingly demand such verification for imported products.
- Nutritional Analysis:This involves determining the fat, protein, moisture, and calorie content of meat products, supporting accurate labeling and consumer information.
Pathogen Detection commands the largest volume of tests, while Meat Authenticity is climbing the fastest.
End User:
Different customer types engage with meat testing services based on their operational needs, regulatory obligations, and internal quality assurance protocols.
- Food Processing Plants:These facilities conduct extensive testing on raw materials, in-process samples, and finished products to ensure safety, quality, and compliance with national standards. Their demand for rapid, on-site solutions is particularly high.
- Quality Control Laboratories:Independent or in-house laboratories perform specialized and confirmatory testing, often requiring ISO/IEC 17025 accreditation for regulatory validation. These labs serve multiple clients across various meat product categories.
- Regulatory Authorities:Government bodies like the US FDA and China's SAMR utilize testing services for surveillance, import checks, and enforcement of food safety laws.
- Meat Packers:These entities typically perform initial screening and basic quality checks on carcasses and primary cuts before further processing or distribution.
Food Processing Plants represent the largest segment by volume, with Quality Control Laboratories experiencing the most significant expansion.
Distribution Channel:
Supply concentration for meat testing products and services varies across channels, reflecting the complexity of instrumentation and the need for technical support.
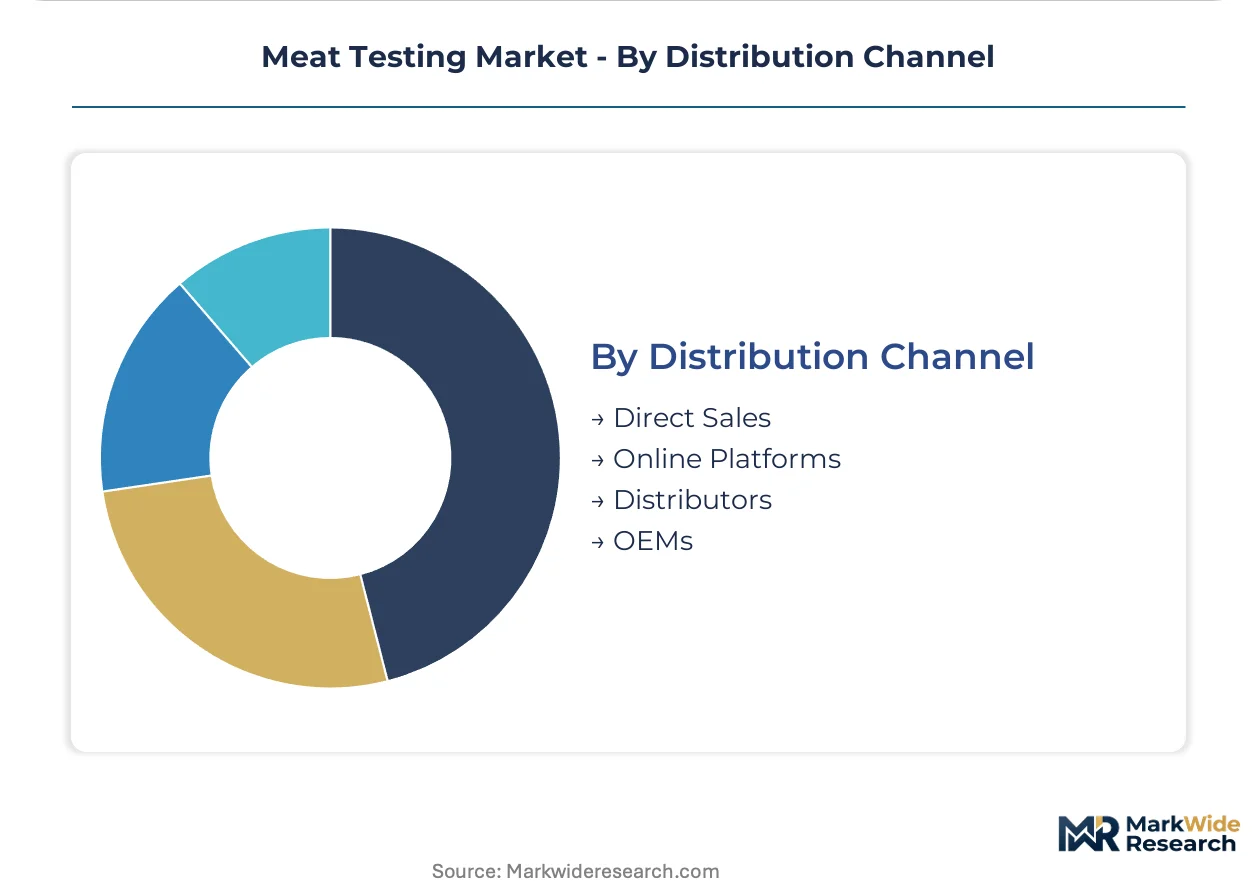
- Direct Sales:Manufacturers sell directly to large food processors or government labs, offering customized solutions, technical support, and training. This channel often facilitates high-value equipment sales and long-term service contracts.
- Online Platforms:These platforms offer convenient access to standardized testing kits, reagents, and basic analytical services, particularly appealing to smaller labs or for routine tests.
- Distributors:Third-party companies manage sales, logistics, and technical support for a range of testing products from multiple manufacturers. They serve a broad customer base across regions like Southeast Asia, providing localized reach and support.
- OEMs:Original Equipment Manufacturers integrate testing components or systems into larger processing lines or laboratory setups, providing embedded solutions.
Direct Sales remains critical for complex systems, while Online Platforms demonstrate the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food processing plants across key geographies concentrate demand for meat testing services, driven by evolving safety standards and consumer expectations. These facilities require robust analytical support for both raw materials and finished products, influencing regional market dynamics. Regulatory bodies like the US FDA and China's SAMR establish critical testing mandates, shaping market access and operational protocols for processors.
United States
Demand for advanced meat testing services in the United States stems from stringent food safety regulations and a large domestic meat processing industry. The US FDA's Food Safety Modernization Act (FSMA) compels processors to implement comprehensive preventative controls, increasing the frequency of pathogen detection. Major meat-producing states like Iowa and Nebraska are seeing significant investment in rapid, on-site testing technologies at processing facilities.
China
China's meat testing market is rapidly expanding, fueled by increased meat imports and rising domestic production standards. The State Administration for Market Regulation (SAMR) enforces strict import testing protocols, requiring international suppliers to meet local safety and authenticity benchmarks. Cities like Shanghai and Guangzhou, major import hubs, are developing advanced laboratory infrastructure to handle the growing volume of analytical requirements.
Germany
Germany's meat testing sector is characterized by its adherence to the European General Food Law, which emphasizes traceability and operator responsibility throughout the supply chain. This regulatory framework drives demand for sophisticated chemical and microbiological analysis, particularly for hormone and antibiotic residues. Quality control laboratories in regions such as Bavaria and North Rhine-Westphalia are at the forefront of adopting high-precision chromatographic techniques.
Brazil
Brazil, a major global meat exporter, exhibits significant growth in its meat testing market due to industrializing production and international trade requirements. Health authorities like ANVISA enforce rigorous testing for export compliance, particularly for pathogens and residues. The state of Mato Grosso, a leading beef producer, is witnessing increased adoption of rapid diagnostic kits for preliminary screening at large processing facilities.
India
India's meat testing market is gaining momentum as domestic consumption rises and food safety awareness improves. The Food Safety and Standards Authority of India (FSSAI) is progressively tightening regulations on meat quality and hygiene, mandating more frequent pathogen and authenticity checks. Major urban centers like Delhi and Mumbai are developing specialized laboratories to cater to the growing demand from both organized and unorganized meat sectors.
Meat Testing Market Key Industry Players
Player mix skews toward large, diversified testing networks and specialized analytical service providers, alongside niche rapid diagnostic solution manufacturers. The market exhibits a tiered structure, with global leaders offering comprehensive portfolios and regional specialists focusing on specific analytical needs. Strategic partnerships to integrate on-site screening with confirmatory lab analysis represent a key competitive move.
Eurofins and SGS exemplify large, global laboratory networks, offering a broad spectrum of testing services across multiple geographies. Mérieux NutriSciences occupies a position as a specialized analytical service provider, focusing on microbiological and chemical analysis for the food industry. Neogen Corporation, a US-based entity, anchors the rapid diagnostic kit segment, providing on-site solutions for preliminary screening in processing plants.
| Leading Market Players |
|---|
| SGS |
| Eurofins |
| Bureau Veritas |
| Intertek |
| ALS Limited |
| Mérieux NutriSciences |
| TUV SUD |
| Neogen Corporation |
| AsureQuality |
| Others |
Cost & Logistics Intelligence
Long-term service contracts for accredited laboratory testing lock in both supply access for processors and predictable revenue streams for service providers, ensuring consistent quality assurance within the meat supply chain.
Pricing Analysis
Cost-plus contract models, often indexed to reagent costs and labor rates, define pricing for specialized meat testing services. Price differentiation drivers include the accreditation level of the testing laboratory (e.g., ISO/IEC 17025 certification) and the complexity of the analytical method employed. Pricing pressure stems from the increasing availability of rapid, on-site testing kits, which offer a lower-cost alternative for preliminary screening. Food processing plants often exhibit high price sensitivity for routine pathogen detection, while regulatory authorities prioritize analytical accuracy over cost for compliance validation.
Supply Chain Analysis
China and the United States anchor the supply of advanced PCR systems and immunoassay kits for meat testing. Raw material dependencies include specialized enzymes for PCR amplification and antibodies for immunoassay reagents. Supply chain risk emerges from the single-source vulnerability for certain proprietary diagnostic components. Distribution runs through a dual model, with direct sales channels for high-value analytical instruments and online platforms for standardized kits and reagents globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment creates a defensive moat in the meat testing market, providing a stable foundation for long-term growth and specialized service providers.
For Market Incumbents:Secure long-term managed service contracts with large food processing plants to counter margin pressure from rapid diagnostic kit providers. Invest in advanced multiplex assay development to offer comprehensive screening solutions that consolidate multiple tests into one. Expand ISO/IEC 17025 accredited laboratory networks in emerging markets like Southeast Asia, leveraging the lever of regulatory compliance as a competitive advantage. This strategy defends against new entrants offering single-parameter, low-cost solutions.
For New Entrants and Emerging Players:Differentiate on speed and ease-of-use for on-site rapid diagnostic kits targeting preliminary screening within food processing plants. Focus on underpenetrated regions, such as industrializing meat production facilities in Latin America, where demand for immediate results is high. A go-to-market angle emphasizing integration with existing quality control workflows and minimal technical expertise for operation can accelerate adoption. The most penetrable segment remains small to medium-sized meat processors seeking efficient internal quality checks.
For Investors and Strategic Acquirers:Specialized analytical service providers with strong regional accreditations represent attractive acquisition targets for their established client bases and technical expertise. The long-term viability of this market, driven by persistent food safety concerns and evolving regulatory landscapes, remains strong over a five-to-ten-year window. A key signal to watch is the increasing mandate for digital integration of testing data, indicating a shift towards platform-based quality management systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquire regional ISO/IEC 17025 accredited labs | This consolidates market share and expands geographic testing capabilities for diversified service providers. |
| Invest in multiplex PCR kit R&D | This offers efficiency gains for food processors by simultaneously detecting multiple pathogens and adulterants. |
| Develop integrated digital quality platforms | This provides a unified dashboard for processors, linking on-site screening with central lab confirmations. |
| Expand rapid diagnostic kit distribution in Southeast Asia | This addresses the growing demand for quick, preliminary testing in industrializing meat production hubs. |
| Form strategic partnerships with food tech startups | This integrates novel biosensor technologies for real-time meat quality monitoring into existing services. |
Research Approach
A spread of perspectives from food safety officers, laboratory directors, regulatory compliance specialists, and procurement managers converged on the working assumptions for the meat testing market. This involved extensive primary interviews, complemented by secondary validation through government food safety reports, industry association publications, and academic research. Bottom-up and top-down triangulation ensured data consistency across various market segments.
The market was modeled across product type, testing parameter, end-user, and distribution channel, with an additional industry-specific dimension of regulatory compliance level. The analytical framework projects market growth over the projection horizon, with Compound Annual Growth Rates (CAGRs) derived from historical trends and anticipated shifts in regulatory enforcement. Key forecast inputs included projected meat production volumes and evolving food safety legislation from US FDA and China's SAMR.
Material uncertainties — including unforeseen pandemics impacting global meat trade or rapid technological breakthroughs in home testing — sit outside the modeled envelope. Forecasts reflect assumptions regarding stable regulatory environments and consistent consumer demand for verified meat products. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Testing, Inspection, and Certification in Consumer Goods and Retail Market
Food Safety Testing
Food Allergens and Intolerance Testing Market
Food Safety Testing
Allergen Testing Market
Food Safety Testing
Residual Lactose Analyzer Market
Food Safety Testing
Adulteration Tester Market
Food Safety Testing
Inline Beverage Gas and Microbial Load Monitoring Test Systems Market
Food Safety Testing
Rapid Microbiology Testing Market
Food Safety Testing
Global Inline Metal Detector Market
Food Safety Testing
Shelf-Life Testing Market
Food Safety Testing
North America Food Safety Testing Market
Food Safety Testing
Food Allergen Testing Market
Food Safety Testing
Global Dairy Testing Market
Food Safety Testing
Food Pathogen Testing Market
Food Safety Testing
Gum Content Tester Market
Food Safety Testing
UK Food Testing Market
Food Safety Testing
Food Traceability Solutions Market