
 Fruit & Vegetable Wash Market | 2026-2036
Fruit & Vegetable Wash Market Size, Share, and Industry Trends Forecast 2026-2036
Fruit & Vegetable Wash Market Analytics
The gap between premium botanical formulations and commodity chemical-based washes is consolidating into two distinct supply chains with separate raw material sourcing and retail placement strategies. Procter & Gamble leverages its grocery channel dominance to occupy shelf space in mass-market retail, while Ecolab anchors its position in foodservice and institutional contracts through specialized bulk delivery systems. Marico Limited differentiates via regional formulation expertise tailored to tropical produce cleaning requirements.
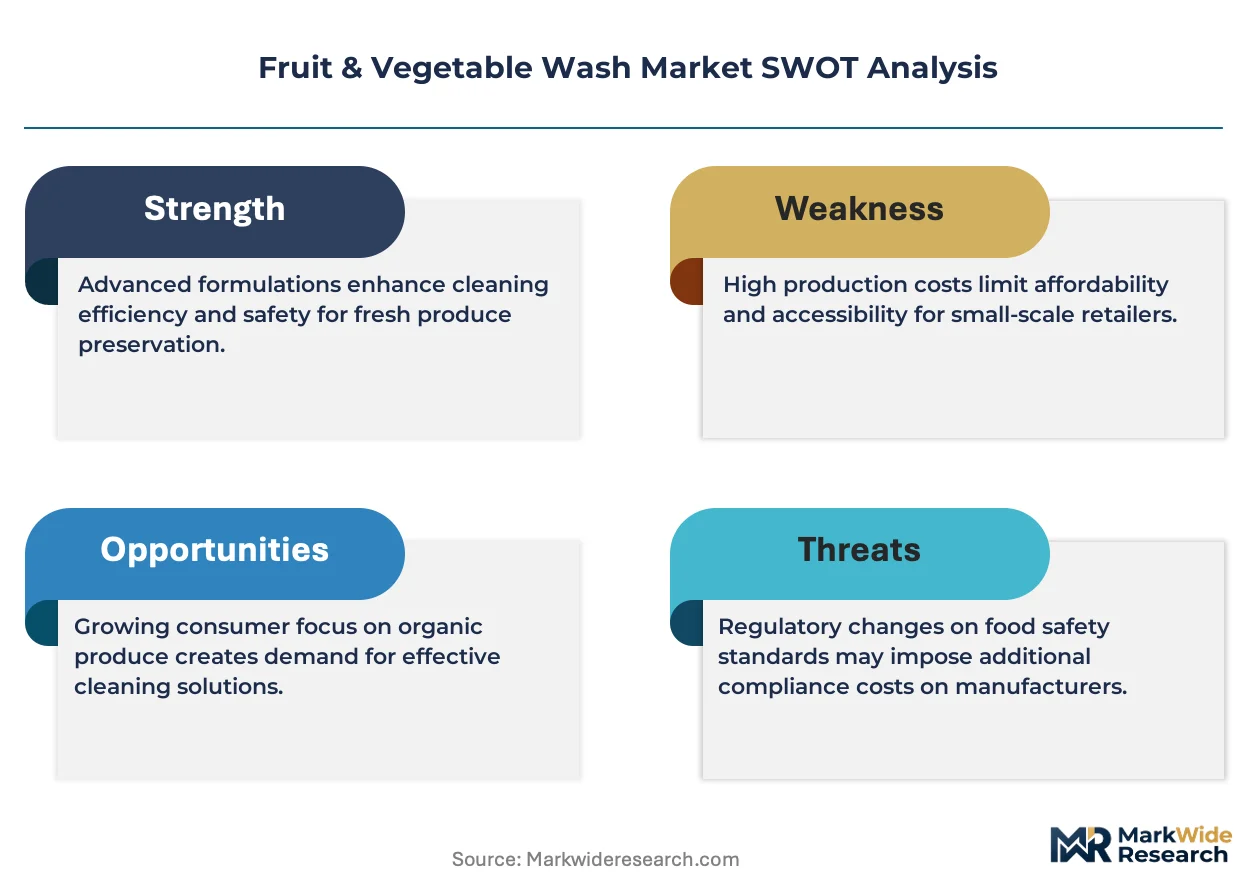
Fruit and vegetable wash denotes a formulated cleaning agent designed to reduce pesticide residues, microbial load, and surface contaminants from fresh produce through surfactant action and mild chelation, typically delivered as aqueous solutions with pH buffers between 5.5 and 7.0 to prevent tissue damage. Liquid wash formats sustain the largest volume share due to consumer familiarity and dosing flexibility, though concentrate formulations represent the fastest-growing segment as refill economics and plastic reduction targets reshape household purchasing patterns. Natural and organic formulations command premium positioning and higher margin pools, particularly in European and North American retail channels where clean-label claims influence shelf velocity.
The EPA regulates antimicrobial wash claims under FIFRA, requiring registration for products targeting specific pathogen reduction, while the FDA governs food contact substance safety under 21 CFR regulations for processing applications. EU REACH compliance and the F-Gas Regulation indirectly shape formulation choices by restricting certain solvent chemistries and propellant systems used in spray packaging. Stakeholders must monitor evolving maximum residue limits from EFSA and corresponding state-level enforcement variations, as regulatory divergence between jurisdictions increasingly determines which formulation platforms achieve multi-region commercial viability.
Market Dynamics
Post-pandemic hygiene persistence has hardened into durable consumer habit, locking in elevated baseline demand for produce cleaning protocols while regulatory tightening on chemical residues forces continuous reformulation cycles across the supply base.
Growth Catalysts
- EPA Safer Choice penetration:Federal procurement preferences and retailer certification requirements pull formulators toward plant-derived surfactant systems, expanding addressable shelf space in mass-market channels.
- Concentrate economics:Refill-format adoption among household buyers compresses per-use cost while satisfying corporate plastic-reduction commitments, driving volume migration from ready-to-use liquids.
- India mass-market activation:Pouch-format distribution through kirana networks and e-commerce quick commerce platforms penetrates price-sensitive segments previously excluded from category participation.
Market Restraints
- Coconut-derived surfactant supply concentration:Southeast Asian plantation output volatility and weather-driven harvest disruptions transmit directly to input cost instability for natural-formulation producers.
- FIFRA registration timelines:EPA antimicrobial claim validation requires 18-24 month review cycles, freezing product pipeline velocity for pathogen-targeting innovations.
- Tap-water substitution:Consumer perception that municipal water rinsing suffices for produce cleaning caps category penetration in lower-awareness demographics.
Strategic Opportunities
- Brazil formal retail expansion:ANVISA cosmetic-to-food-contact regulatory harmonization opens modern trade placement for imported wash formulations in São Paulo and Rio de Janeiro metropolitan corridors.
- Quick-commerce bundling:Integration with grocery delivery platforms as default checkout add-ons captures impulse purchase behavior in urban Indian and Southeast Asian markets.
- EU F-Gas Regulation tailwind:Aerosol propellant phase-out mandates accelerate pump-spray and trigger-spray format conversion, favoring suppliers with liquid-dispensing manufacturing assets.
Industry Challenges
- Green chemistry talent scarcity:Formulation chemists with dual competence in surfactant science and biodegradability testing command premium compensation, constraining R&D team scaling.
- Multi-jurisdiction label compliance:Divergent EPA, ECHA, and FSSAI residue claim thresholds force SKU proliferation and inventory fragmentation for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fruit & Vegetable Wash Market |
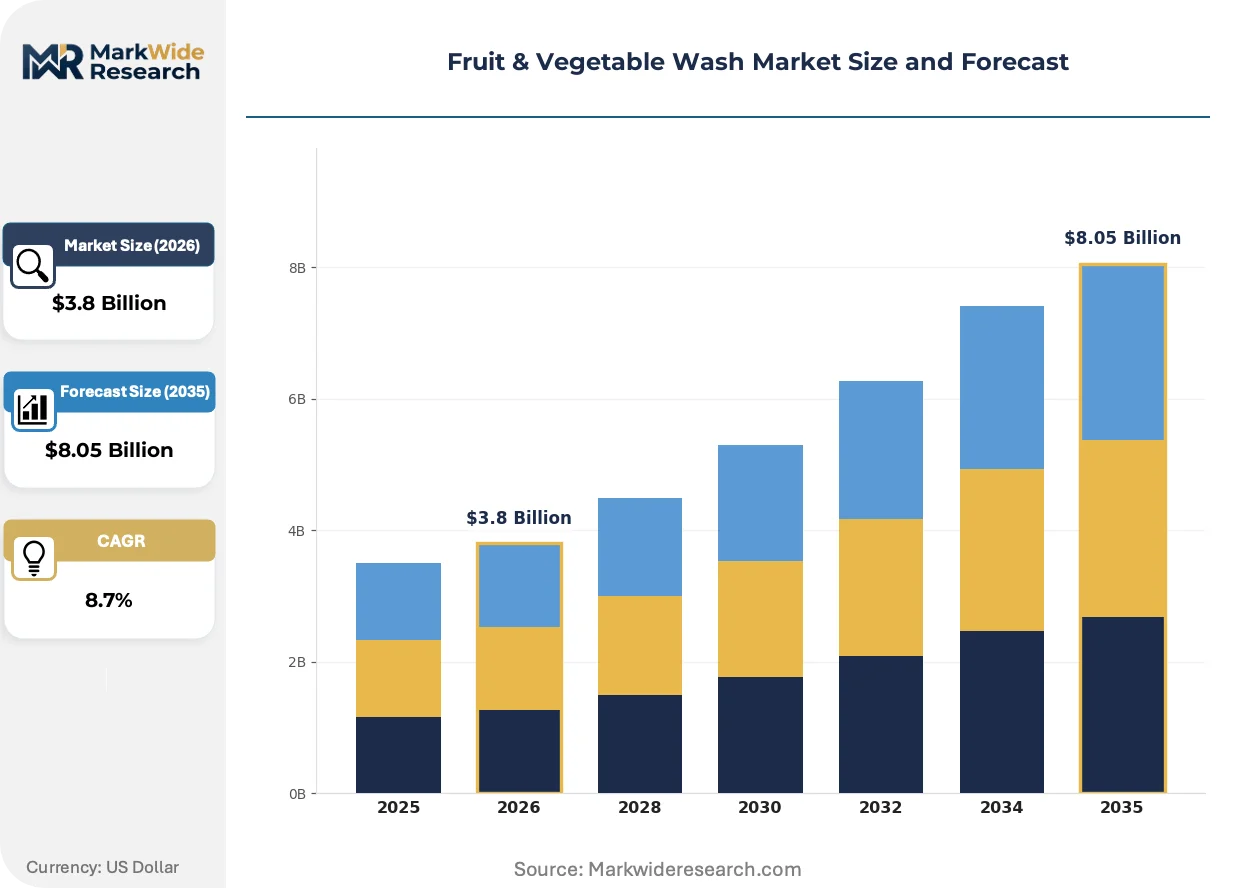
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Wash, Spray, Concentrate, Wipe Formulation: Natural, Chemical-Based, Organic, Synthetic End User: Household, Restaurants, Food Processing, Retailers Packaging Type: Bottles, Pouches, Spray Pumps, Bulk Containers |
| Companies Covered | ITC, Diversey, Procter & Gamble, Marico Limited, The Clorox Company, Ecolab, Wipro, Grow Green Industries, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fruit & Vegetable Wash Market Evolving Landscape
Formulation chemistry and packaging delivery systems are converging around sustainability imperatives, with regulatory pressure and consumer preference operating as twin forcing functions compressing legacy petrochemical-based supply positions.
Enzyme-based cleaning systems incorporating pectinase and cellulase blends are modularizing formulation architectures, allowing manufacturers to swap active modules based on regional produce-type prevalence. Foodservice operators in North American institutional channels pilot these systems for bulk processing of leafy greens and soft-skinned fruits. The technology is modularizing supplier-customer relationships, enabling co-development agreements where end-users specify enzyme cocktails matched to their procurement baskets.
EU REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating residual fluorosurfactant chemistries from premium wash formulations. German and French formulators accelerate plant-protein-derived alternatives through ECHA pre-registration pathways. Concentrate products bearing Ecolabel certification achieve shelf placement premiums in Carrefour and REWE systems, compressing uncertified competitor margins.
Subscription-based replenishment models displace supermarket impulse purchasing among urban professional households in London, New York, and Singapore. Direct-to-consumer platforms bundle seasonal produce boxes with matched wash formulations, capturing full cleaning-protocol spend. This pattern concentrates most visibly in millennial-age cohorts with established meal-kit purchasing histories, where vendor stickiness exceeds conventional retail loyalty metrics.
Fruit & Vegetable Wash Market Segmentation
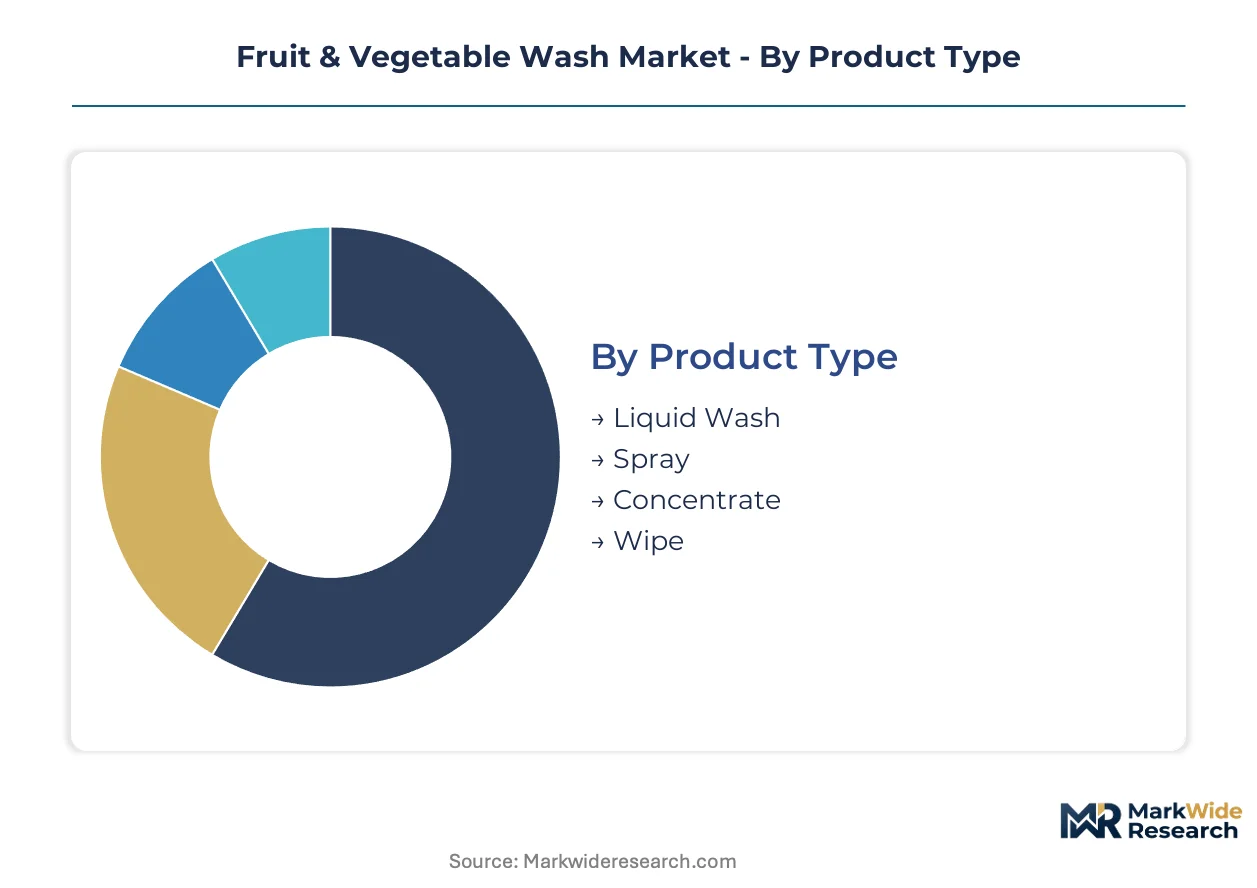
Produce cleaning protocols diverge sharply across consumer sophistication levels and operational scale, forcing suppliers to maintain parallel formulation architectures. Segmentation discipline determines whether a supplier captures mass-market volume or premium margin pools.
Product Type:
Standardization dominates at the high-volume end while customization concentrates in specialized dispensing formats requiring dedicated manufacturing assets.
- Liquid Wash:Aqueous solutions with pH buffers between 5.5 and 7.0 delivered in conventional bottles or refill pouches. Demand concentrates in North American and European household channels where dosing flexibility and consumer familiarity sustain repeat purchase rates despite higher per-use plastic footprint.
- Concentrate:Dilution-required formulations delivering 3-5x use cycles per container unit. Expansion is steepest in urban Indian and Southeast Asian quick-commerce channels where refill economics and corporate plastic-reduction commitments reshape purchasing patterns.
- Spray:Ready-to-dispense aerosol or pump-trigger systems for surface coverage of irregular produce geometries. Foodservice operators in Brazil and Mexico favor this format for line-speed efficiency.
- Wipe:Pre-moistened towelette formats impregnated with surfactant solution. Convenience-oriented retail placement in Japanese and South Korean convenience store networks.
Most installed capacity flows through Liquid Wash. Expansion is steepest in Concentrate.
Formulation:
Margin stratification follows certification intensity, with premium tiers commanding shelf placement premiums in regulated European retail environments.
- Natural:Plant-derived surfactant systems utilizing coconut, citrus, or corn-based cleaning agents. Ecolabel-certified variants achieve placement premiums in Carrefour and REWE systems across Germany and France where EU REACH Annex XVII restrictions eliminate fluorosurfactant alternatives.
- Organic:USDA Organic or EU Organic certified formulations with full supply chain traceability. Premium positioning in Whole Foods Market and specialist retail channels in California and New York metropolitan areas where clean-label claims influence velocity.
- Chemical-Based:Petrochemical surfactant systems with established cost structures. Price-sensitive penetration in Indian kirana networks and Southeast Asian traditional trade.
- Synthetic:Laboratory-engineered cleaning agents with controlled molecular architecture. Institutional food processing applications requiring documented pathogen log reduction.
Volume concentration sits with Chemical-Based formulations. Organic climbs fastest.
End User:
Procurement authority separates fragmented household decision-making from centralized institutional contracting with divergent specification requirements.
- Household:Individual consumers purchasing through retail or e-commerce channels. Post-pandemic hygiene persistence in US, UK, and Australian metropolitan areas has locked in elevated baseline demand for home produce cleaning protocols.
- Restaurants:Commercial kitchen operators requiring food-safe formulations with rapid rinsing characteristics. Full-service and fast-casual chains in Dubai and Riyadh specify halal-certified variants through centralized procurement.
- Food Processing:Industrial-scale operators cleaning bulk produce prior to packaging or further processing. North American leafy greens processors pilot enzyme-based pectinase and cellulase systems for soft-skinned fruit applications.
- Retailers:Supermarket chains operating in-house produce preparation facilities. European discount chains Lidl and Aldi specify private-label formulations with Ecolabel certification.
Contract value aggregates in Food Processing. Restaurants gain share fastest.
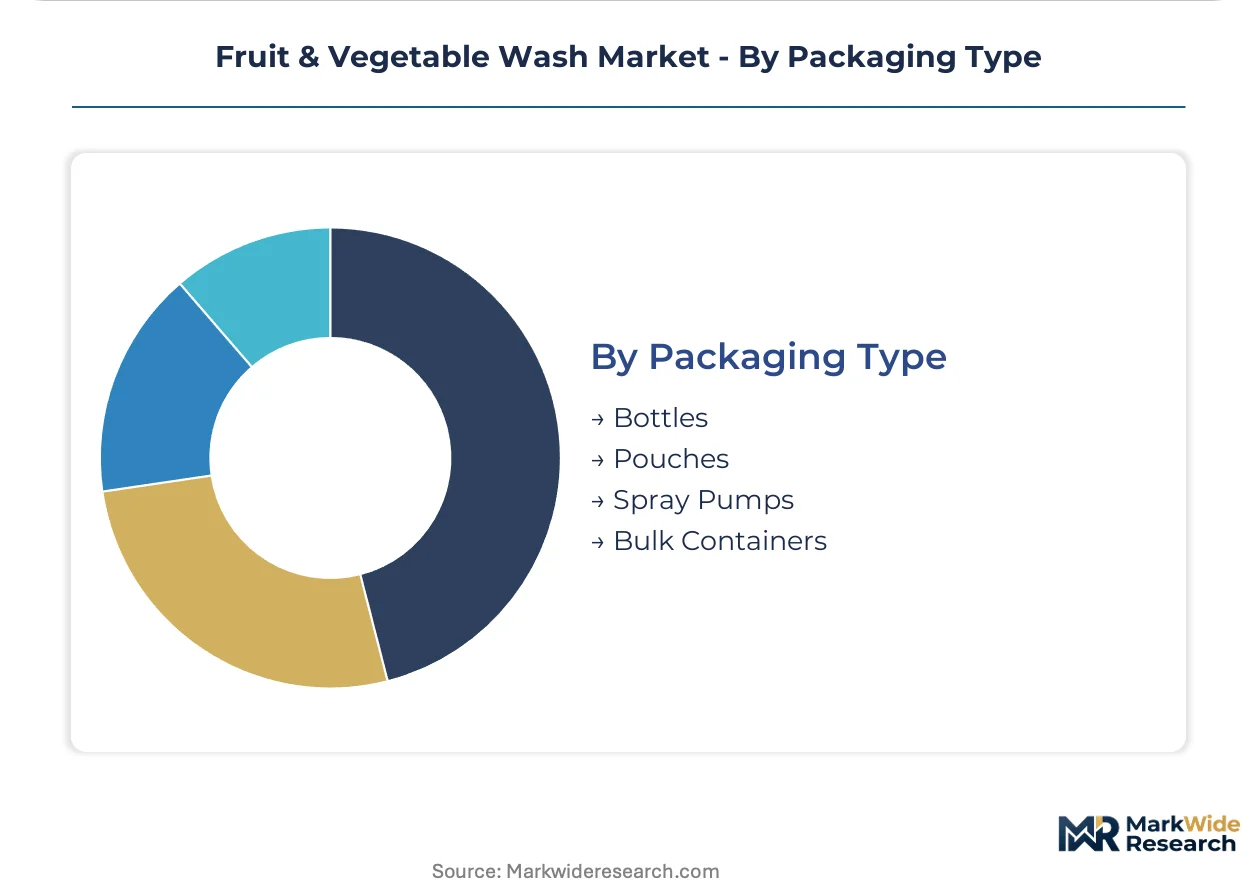
Packaging Type:
Format selection reflects channel economics and logistics infrastructure maturity across target geographies.
- Bottles:Conventional rigid PET or HDPE containers with screw-cap closure. Dominant format in established retail channels across the US, Canada, and Western Europe.
- Pouches:Flexible film formats with spout or tear-open dispensing. ITC and Marico Limited deploy this format for mass-market penetration through Indian kirana networks and quick-commerce platforms.
- Spray Pumps:Trigger or finger-pump dispensing mechanisms replacing aerosol propellant systems. EU F-Gas Regulation compliance favors this format conversion in German and French manufacturing.
- Bulk Containers:Industrial-scale totes or drums for institutional replenishment. Ecolab anchors foodservice contracts through specialized bulk delivery systems in North American institutional channels.
Unit volume concentrates in Bottles. Pouch expansion is accelerating.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemists with dual competence in surfactant science and biodegradability testing concentrate in Germany and the United States, anchoring the technical workforce that enables regulatory-compliant product development.
United States
Post-pandemic hygiene persistence has locked in elevated baseline demand for home produce cleaning protocols in metropolitan areas. The EPA's Safer Choice program pulls formulators toward plant-derived surfactant systems through federal procurement preferences. Ecolab anchors its foodservice position through specialized bulk delivery systems in North American institutional channels.
Germany
EU REACH Annex XVII restrictions on per- and polyfluoroalkyl substances eliminate residual fluorosurfactant chemistries from premium wash formulations. German formulators accelerate plant-protein-derived alternatives through ECHA pre-registration pathways. Concentrate products bearing Ecolabel certification achieve shelf placement premiums in REWE systems.
India
Pouch-format distribution through kirana networks and e-commerce quick commerce platforms penetrates price-sensitive segments previously excluded from category participation. FSSAI residue claim thresholds shape local formulation requirements distinct from Western markets. ITC and Marico Limited drive mass-market activation through affordable pouch formats in Mumbai and Delhi corridors.
France
Ecolabel-certified variants achieve placement premiums in Carrefour systems where clean-label claims influence shelf velocity. The EU F-Gas Regulation indirectly shapes formulation choices by restricting certain propellant systems used in spray packaging. Paris-based formulators specialize in botanical extraction for premium positioning.
Brazil
ANVISA cosmetic-to-food-contact regulatory harmonization opens modern trade placement for imported wash formulations. Foodservice operators in São Paulo and Rio de Janeiro metropolitan corridors favor spray formats for line-speed efficiency. Quick-commerce bundling captures impulse purchase behavior in urban Brazilian markets.
Fruit & Vegetable Wash Market Competitive Landscape
Top-tier vendors anchor mass-market grocery channels, while mid-tier specialists occupy foodservice and institutional contracts. The vendor base spans multinational conglomerates with grocery channel dominance, regional formulators with tropical produce expertise, and industrial-scale suppliers with bulk delivery capabilities. Two strategic archetypes predominate: mass-market shelf-space occupiers leveraging brand recognition, and institutional contract specialists delivering customized formulation services. Competitive moves concentrate on geographic expansion into quick-commerce channels and portfolio diversification toward concentrate formats.
Among India-based consumer goods specialists, ITC and Marico Limited exemplify the regional-formulation archetype tailored to tropical produce cleaning requirements and price-sensitive distribution networks. Procter & Gamble occupies a position within the mass-market tier, representing grocery channel dominance through established retail placement strategies. Ecolab anchors the institutional-contract vector, sitting within the foodservice and industrial processing segment with specialized bulk delivery infrastructure.
| Leading Market Players |
|---|
| ITC |
| Diversey |
| Procter & Gamble |
| Marico Limited |
| The Clorox Company |
| Ecolab |
| Wipro |
| Grow Green Industries |
| Unilever |
| Others |
Value Network & Pricing Analysis
Coconut fatty acid methyl ester price volatility cascades through surfactant procurement tiers, compressing margins for natural-formulation producers while amplifying cost advantages for petrochemical-based commodity suppliers serving Indian kirana networks.
Pricing Analysis
Bundled subscription services separate from unbundled transactional retail purchases. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification intensity, with Ecolabel-certified variants commanding shelf placement premiums in German REWE and French Carrefour systems. Pricing pressure stems from concentrate-format adoption compressing per-use revenue while plastic-reduction commitments lock in refill economics. Household buyers in Indian quick-commerce channels exhibit highest price sensitivity, whereas North American foodservice operators demonstrate lowest sensitivity due to pathogen-liability risk transfer.
Supply Chain Analysis
Single-source vulnerability sits with Southeast Asian coconut plantation output, where Philippine and Indonesian harvest disruptions transmit directly to plant-derived surfactant availability. Raw material procurement draws from palm kernel derivatives, citrus terpenes, and corn-based ethanolamines as formulation backbones. Supply chain risk centers on weather-driven commodity price volatility intersecting with EU REACH pre-registration timelines for novel plant-protein alternatives. Distribution runs through dual-channel structures: mass-market retail placement for household formats and specialized bulk delivery systems for institutional foodservice contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates in concentrate-format migration, where refill economics and corporate plastic-reduction commitments simultaneously lower unit production costs and unlock premium positioning.
For Market Incumbents: Anticipate pouch-format disruption from regional specialists by securing flexible-film manufacturing partnerships in Indian quick-commerce corridors. Defensive consolidation requires backward integration into coconut-derived surfactant supply and accelerated EPA Safer Choice certification to preempt federal procurement preference shifts. For New Entrants and Emerging Players: Begin with enzyme-based modular formulations targeting North American leafy greens processors seeking co-development partnerships for customized pectinase cocktails. White-space concentration sits in Brazilian formal retail expansion following ANVISA regulatory harmonization, with spray-format line-speed efficiency as the anchor value proposition for São Paulo foodservice operators. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-jurisdiction label compliance forces SKU proliferation and inventory fragmentation for cross-border suppliers. Acquisition targets with dual competence in surfactant science and biodegradability testing command premium positioning. Signal to monitor: FIFRA registration timeline compression for pathogen-targeting innovations, indicating regulatory arbitrage opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| Concentrate Format Migration | Refill economics in Indian quick-commerce channels capture price-sensitive household segments previously excluded. |
| Enzyme-Based Formulation Partnerships | Co-development agreements with North American leafy greens processors enable customized pectinase module swapping. |
| EU Ecolabel Certification Investment | REACH Annex XVII fluorosurfactant elimination creates shelf placement premiums in German REWE and French Carrefour systems. |
| Pouch Distribution Network Expansion | Flexible-film formats penetrate Mumbai and Delhi kirana networks at unit economics below rigid PET bottles. |
| Green Chemistry Talent Acquisition | Formulation chemists with dual surfactant-biodegradability competence command scarcity premiums constraining R&D scaling. |
Research Methodology
Multiple input streams — formulation chemist interviews, retail channel audits, regulatory filing analysis — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged plant managers at Southeast Asian surfactant facilities, category buyers at European discount chains, procurement leads at North American foodservice operators, and technical R&D directors at regional formulators. Secondary validation drew from EPA Safer Choice certified product listings, ECHA pre-registration databases, FSSAI residue limit notifications, and customs trade data on coconut fatty acid derivative flows.
Cross-referencing historical volume patterns against expert panel input anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, formulation certification tier, end-user procurement scale, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves incorporating concentrate-format substitution rates and quick-commerce penetration trajectories as industry-specific forecast inputs.
Caveats apply where FIFRA registration timeline delays, coconut harvest disruptions, or divergent maximum residue limit enforcement could materially shift the outlook. Forecasts reflect documented assumptions about post-pandemic hygiene persistence durability and refill-format adoption velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
North America Food Safety Testing Market
Food Safety Testing
High-Throughput Food Allergen Screening Test Instruments Market
Food Safety Testing
Central & South America Food Safety Testing Market
Food Safety Testing
Food Safety Testing Services Market
Food Safety Testing
Ireland Food Testing Market
Food Safety Testing
Carbohydrates Testing Services Market
Food Safety Testing
Meat Speciation Testing Service Market
Food Safety Testing
Food Pathogen Testing Market
Food Safety Testing
Global Food Diagnostics Market
Food Safety Testing
Food Tester Market
Food Safety Testing
US Legionella Testing Market
Food Safety Testing
Food Allergen Testing Market
Food Safety Testing
Genetically Modified Food Safety Testing Market
Food Safety Testing
Global Dairy Testing Market
Food Safety Testing
Xylose Absorption Tests Market
Food Safety Testing
Chromatography Food Testing Market