
 Generative Design Market | 2026-2036
Generative Design Market Size, Share, and Industry Trends Forecast 2026-2036
Generative Design Market Intelligence
The bundling of generative design tools within broader CAD and PLM software suites is realigning buyer preferences toward integrated platforms. This shift favors established ecosystem providers offering seamless workflows. Autodesk Inc. leverages its dominance in CAD software to embed these advanced capabilities, while Dassault Systèmes SE differentiates through its 3DEXPERIENCE platform. Siemens competes by integrating generative design into its comprehensive digital twin and industrial automation portfolio.
Generative design is an iterative design exploration process using AI to generate optimized outputs based on predefined constraints. The technology often employs topology optimization algorithms to create complex, high-performance geometries for specific manufacturing methods. Cloud-based software deployments are becoming the standard, offering the necessary computational power for these intensive tasks. While adoption is strong in aerospace engineering for lightweighting, the industrial machinery application segment represents the fastest-growing area due to its potential for part consolidation and performance improvement.
Regulatory frameworks create both challenges and opportunities for adoption. In the United States, designs for aerospace must meet stringent FAA certification for materials and structural integrity. Similarly, components for industrial equipment in Europe must adhere to safety standards implicit in CE marking. ISO standards provide a baseline for quality management in the design process. The critical decision for engineering teams is balancing algorithmic novelty with the rigorous validation required for mission-critical applications.
Market Dynamics
The central force shaping the generative design market is the imperative for material efficiency and performance optimization. This is driven by sustainability mandates and lightweighting requirements in capital-intensive industries like aerospace, automotive, and industrial machinery across developed economies.
Growth Catalysts
- Cloud Computing Accessibility:The proliferation of scalable, high-performance cloud infrastructure provides the necessary computational power for complex topology optimization algorithms, lowering the barrier to entry for smaller engineering firms.
- Aerospace and Automotive Demand:The aerospace sector's relentless pursuit of lightweighting for fuel efficiency, alongside the automotive industry's push for part consolidation in electric vehicles, creates sustained demand, especially in Germany and the United States.
- Sustainability Mandates:Regulatory frameworks like the EU Green Deal and corporate ESG commitments are pushing manufacturers to minimize material waste and energy consumption, positioning generative design as a key enabling technology for sustainable product development.
Market Restraints
- High Computational Costs:Despite cloud accessibility, the processing-intensive nature of generative design simulations incurs significant operational costs, which can be prohibitive for extensive exploration or smaller projects.
- Stringent Certification Hurdles:Novel designs generated by algorithms face long and rigorous validation processes to meet safety and structural integrity standards, such as FAA certification in aerospace or CE marking for industrial equipment in Europe.
- Specialized Talent Scarcity:A persistent shortage of engineers and designers possessing the dual expertise in traditional mechanical engineering principles and advanced computational design tools limits the technology's effective implementation.
Strategic Opportunities
- Industrial Machinery Applications:The industrial machinery segment represents the fastest-growing area, offering significant opportunities for part consolidation, performance enhancement, and reduced material usage in complex assemblies.
- Expansion in Asian Manufacturing Hubs:There is significant potential for adoption in the advanced manufacturing sectors of Japan and South Korea, particularly in robotics, electronics, and automotive components where precision and optimization are critical.
- Convergence with Additive Manufacturing:The pairing of generative design with 3D printing technologies unlocks the ability to physically produce the complex, organic geometries that algorithms create, enabling a direct digital-to-physical workflow.
Industry Challenges
- Legacy System Integration:Engineering teams face significant friction when integrating generative design software into established, and often rigid, legacy CAD and Product Lifecycle Management (PLM) ecosystems, creating workflow disruptions.
- Validation of Non-Intuitive Designs:Verifying the performance and reliability of algorithmically-generated, non-intuitive geometries is a major operational hurdle, requiring extensive physical testing and advanced simulation to build trust and ensure safety.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Generative Design Market |
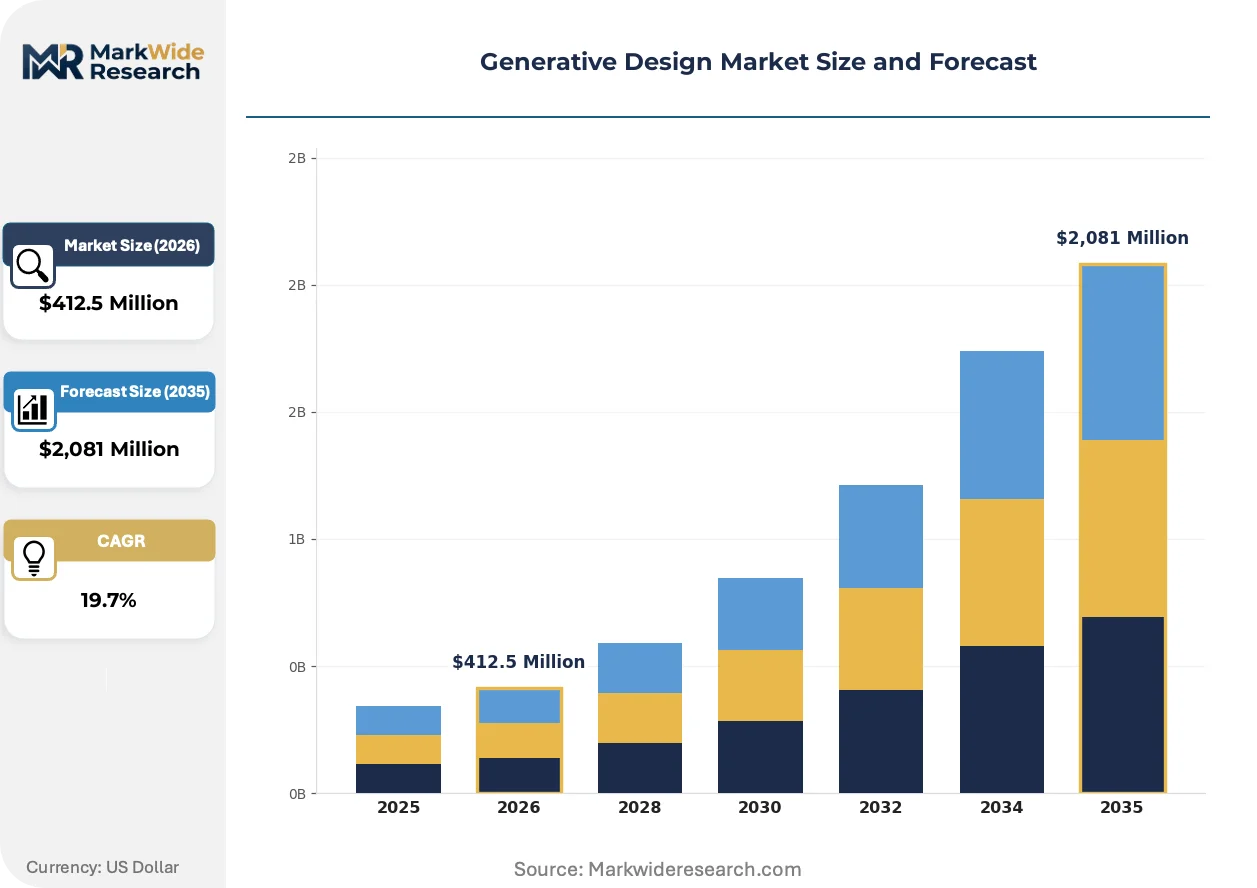
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $2,081 Million |
| CAGR (2026 – 2036) | 19.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Software Type: Cloud-Based, On-Premise, Hybrid, SaaS, Enterprise Software Technology: AI-Driven Optimization, Topology Optimization, Machine Learning, Evolutionary Algorithms, Constraint-Based Modeling Application: Product Development, Aerospace Engineering, Consumer Electronics, Architecture Design, Industrial Machinery End User Industry: OEMs, Construction Firms, Electronics Manufacturers, Defense Contractors, Toolmakers |
| Companies Covered | NVIDIA Corporation, Bentley Systems, Inc., Autodesk Inc., Adobe Inc., Microsoft Corporation, Dassault Systèmes SE, PTC Inc., Synopsys, Inc., Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Generative Design Market Strategic Shifts & Innovations
The market's evolution is defined by the integration of generative capabilities into mainstream engineering workflows, moving the technology from a specialized tool to a core component of the product development cycle. This transition is powered by advancements in AI and simulation.
Multi-physics simulation is being embedded directly within generative design software, allowing for simultaneous analysis of structural, thermal, and fluid dynamics properties. Aerospace and defense engineering teams are the primary adopters, seeking to accelerate development timelines. This integration is unifying the traditionally siloed stages of conceptual design and performance validation into a cohesive, automated process.
European regulations, specifically the EU AI Act, are introducing new risk management obligations for AI systems. This framework classifies generative design tools used in critical applications like medical devices or transportation as high-risk, mandating greater transparency and human oversight. Software vendors targeting the European market are responding by building in enhanced audit trails and explainability features.
A definitive shift is occurring from perpetual software licenses to cloud-based, consumption-driven subscription models. This change lowers the upfront investment, making advanced design tools more accessible to small and medium-sized enterprises that favor operational expenditures. This trend is most advanced in North America, where mature cloud infrastructure supports project-based work in architecture and industrial design.
Generative Design Market Segmentation

The segmentation of the generative design market illuminates distinct pathways for technology adoption and solution development. Understanding these segments is crucial for providers to align their offerings with specific industry needs, whether addressing computational demands or specialized application requirements. Each segment reflects unique operational priorities and integration challenges across diverse engineering environments.
Software Type:
The upgrade cycles for engineering software are increasingly driving preferences toward flexible, accessible deployment models. This shift impacts how enterprises procure and integrate advanced generative design capabilities into their existing digital ecosystems.
- Cloud-Based:This deployment model provides scalable computational resources and remote access, lowering the barrier to entry for smaller engineering firms. Demand concentrates among project-based design studios in North America, driven by the need for on-demand processing power.
- SaaS:Software as a Service offers a subscription-based model, reducing upfront capital expenditure and providing continuous updates and support. This model is gaining traction with small and medium-sized enterprises across Europe, favoring operational expenditure for design tools.
- On-Premise:This traditional deployment involves software installed and run on local servers, offering maximum data control and security for sensitive intellectual property. Large aerospace and defense contractors in the United States often prefer this model for mission-critical projects.
- Hybrid:Combining elements of both cloud and on-premise solutions, hybrid models offer flexibility, allowing businesses to manage sensitive data locally while leveraging cloud scalability.
- Enterprise Software:Comprehensive software suites integrate generative design tools with broader CAD and PLM functionalities, catering to large organizations seeking unified engineering platforms.
Volume placements concentrate in Cloud-Based solutions; the faster expansion belongs to SaaS offerings.
Technology:
The maturity curve of various generative design technologies dictates their widespread applicability and the complexity of problems they can solve. Newer, more sophisticated algorithms are steadily gaining ground, pushing the boundaries of design exploration.
- AI-Driven Optimization:This core technology leverages artificial intelligence to explore vast design spaces and generate optimized solutions based on predefined performance criteria. It underpins much of the iterative design exploration in advanced manufacturing sectors.
- Topology Optimization:A specific algorithmic approach that removes material from a design space, creating lightweight and structurally efficient components while adhering to specific load cases and constraints. This is critical for lightweighting initiatives in aerospace engineering.
- Machine Learning:Utilized within generative design workflows to recognize patterns, predict material behaviors, and refine design iterations, accelerating the overall design process.
- Evolutionary Algorithms:These algorithms mimic natural selection processes to iteratively evolve and improve design candidates, particularly effective for complex, multi-objective optimization problems.
- Constraint-Based Modeling:This approach defines design rules and parameters that the generative algorithm must adhere to, ensuring manufacturability and compliance with engineering specifications.
The market's technological advancement is driven by AI-Driven Optimization, with Topology Optimization showing consistent adoption for performance-critical applications.
Application:
The diverse customer types engaging with generative design highlight its versatility, from accelerating new product introductions to optimizing existing industrial processes. Each application area presents unique challenges and opportunities for specialized solution providers.
- Aerospace Engineering:Generative design is extensively used for lightweighting aircraft components, optimizing structural integrity, and improving fuel efficiency. This application segment is vital for major manufacturers in the United States and Europe.
- Industrial Machinery:This segment represents a significant growth area, leveraging generative design for part consolidation, performance enhancement, and material reduction in complex industrial equipment. German machinery manufacturers are prominent adopters.
- Product Development:Broadly applied across industries, generative design accelerates the conceptualization and iteration phases of new product development, fostering innovation and reducing time-to-market.
- Consumer Electronics:In this sector, generative design helps optimize internal component layouts, manage thermal performance, and create aesthetically complex enclosures for electronic devices.
- Architecture Design:Used for structural optimization, form generation, and material efficiency in buildings and infrastructure projects, pushing the boundaries of sustainable construction.
While Aerospace Engineering currently holds substantial market share, Industrial Machinery is poised for accelerated expansion.
End User Industry:
The supply concentration within specific end-user industries dictates the scale and type of generative design solutions required. Industries with high-value, complex products drive demand for sophisticated and highly integrated tools.
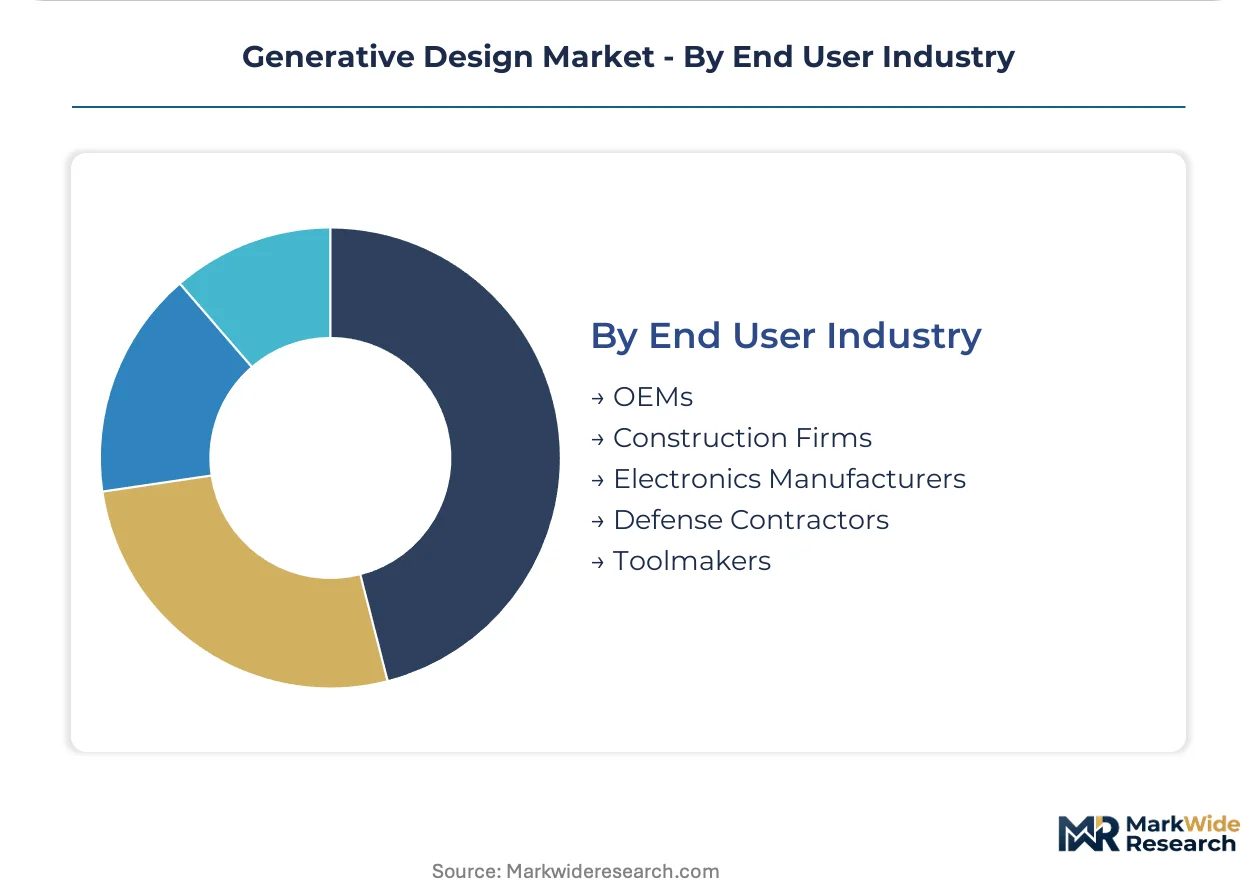
- OEMs:Original Equipment Manufacturers across automotive, aerospace, and heavy industry sectors utilize generative design to optimize component performance and reduce material costs. Major automotive OEMs in Germany are significant users.
- Defense Contractors:These firms employ generative design for mission-critical applications, focusing on enhanced performance, reduced weight, and structural integrity for military hardware. Strict FAA certification requirements influence design processes.
- Construction Firms:Generative design aids in optimizing structural elements, reducing material usage, and enhancing the efficiency of building designs.
- Electronics Manufacturers:Applied for miniaturization, thermal management, and robust enclosure design in consumer and industrial electronics.
- Toolmakers:Generative design optimizes the creation of molds, jigs, and fixtures, particularly benefiting additive manufacturing processes for complex tooling.
The demand landscape is shaped by diverse needs, with OEMs representing a stable base and Defense Contractors an emerging frontier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The generative design market exhibits a notable divide between regions driving technological innovation and those rapidly adopting these tools. Production of advanced generative design software often concentrates in tech-forward economies. Consumption patterns reflect industrial maturity and regulatory environments, influencing regional demand for optimized design solutions.
United States
Aerospace lightweighting and defense applications drive significant demand for generative design tools in the United States. FAA certification for new materials and structural integrity influences design processes for mission-critical components. Silicon Valley and Seattle areas drive cloud infrastructure and software development for engineering firms.
Germany
The automotive industry's push for part consolidation and industrial machinery optimization are key demand drivers in Germany. Components for industrial equipment must adhere to safety standards implicit in CE marking, influencing design validation. Bavaria and North Rhine-Westphalia house major automotive OEMs and machinery manufacturers.
Japan
Precision manufacturing in robotics, automotive components, and electronics requires advanced optimization from generative design in Japan. METI initiatives support advanced manufacturing technologies and digital transformation across various sectors. The Kanto region, including Tokyo, serves as a hub for advanced R&D and industrial automation.
France
Aerospace and defense engineering teams accelerate development timelines and structural optimization using generative design in France. The EU AI Act introduces risk management obligations for AI systems, including critical design tools. Toulouse, a major aerospace hub, integrates generative design into aircraft component development.
South Korea
Advanced manufacturing sectors like automotive, electronics, and robotics require precision and optimization in South Korea. MOTIE initiatives support digital manufacturing and smart factory implementation across industrial clusters. The Seoul Capital Area drives innovation in consumer electronics and automotive R&D.
Generative Design Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists within the generative design market. This market exhibits a tiered competitive structure, where major software vendors offer comprehensive engineering platforms. Smaller, specialized firms deliver niche solutions tailored for specific design challenges. Ecosystem providers focus on integrating generative capabilities into broader CAD and PLM suites, emphasizing seamless workflows for engineering teams. Portfolio diversification and strategic partnerships are prevalent competitive moves, alongside continuous R&D investment in AI and simulation.
Within the integrated platform segment, Autodesk Inc. exemplifies a software giant leveraging its CAD dominance to embed advanced generative capabilities for its broad customer base. Dassault Systèmes SE, a French multinational, represents another major player differentiating through its 3DEXPERIENCE platform, offering extensive design and simulation tools for complex product development. Siemens, a German industrial conglomerate, occupies a position by integrating generative design into its comprehensive digital twin and industrial automation portfolio, catering to large-scale manufacturing ecosystems. These entities collectively anchor the market's enterprise solution offerings.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Bentley Systems, Inc. |
| Autodesk Inc. |
| Adobe Inc. |
| Microsoft Corporation |
| Dassault Systèmes SE |
| PTC Inc. |
| Synopsys, Inc. |
| Siemens |
Cost & Logistics Intelligence
Computational resource costs, particularly for cloud-based processing, flow from hyperscale providers through software vendors to end-users, influencing subscription tiers. This upstream cost structure directly impacts the accessibility and pricing models for advanced generative design tools across different enterprise sizes.
Pricing Analysis
Operational expenditure pressure on small and medium-sized enterprises drives demand for subscription-based models in generative design software. SaaS offerings, with their reduced upfront capital expenditure and continuous updates, are gaining traction across Europe. Price differentiation stems from the level of computational power, feature set, and integration with broader PLM suites. Buyer price sensitivity is highest among smaller engineering firms seeking project-based access, while large aerospace and defense contractors prioritize performance and security, showing lower price sensitivity.
Supply Chain Analysis
Dual-sourcing requirements for critical software components and cloud infrastructure are becoming standard practice for major generative design vendors. The supply of high-performance computing resources concentrates in technology hubs like Silicon Valley and Seattle, with major cloud providers acting as key dependencies. Raw material dependencies include specialized chip manufacturing from Taiwan and South Korea for high-performance computing hardware. A structural risk is single-source vulnerability for specific AI acceleration hardware. Distribution runs through direct sales channels for enterprise solutions and online marketplaces for SaaS subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The generative design market is consolidating, driven by the intense computational demands and the need for integrated solutions that push smaller, standalone providers towards acquisition by larger platform companies.
For Market Incumbents: Acquire specialized AI optimization startups to integrate novel algorithms and expand application-specific capabilities. This move counters the threat from niche pure-play specialists offering advanced, focused solutions. Bolster existing platforms by investing in multi-physics simulation integration for aerospace and defense engineering teams. Deepen vertical integration into cloud infrastructure partnerships to secure scalable computational power and reduce operational costs.
For New Entrants and Emerging Players: A price-point gap exists for accessible, project-based generative design tools targeting small and medium-sized enterprises in North America. Develop specialized solutions for the industrial machinery segment, focusing on part consolidation and performance enhancement. A go-to-market angle involves offering a freemium model for basic design exploration, converting users to subscription tiers as their needs grow. Target underpenetrated sectors like architecture design with simplified, intuitive interfaces.
For Investors and Strategic Acquirers: The integration of multi-physics simulation into generative design software is the leading indicator that comprehensive platform providers will dominate the market long-term. Focus on acquisition targets with strong intellectual property in AI-driven optimization and a proven track record in integrating with existing CAD/PLM ecosystems. Long-term viability hinges on the ability to demonstrate quantifiable performance improvements and cost savings for mission-critical applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate Multi-Physics Simulation | Unifies design and validation, accelerating development timelines for aerospace and defense engineering teams. |
| Expand Cloud-Based SaaS Offerings | Lowers entry barriers for small and medium-sized enterprises, driving broader market adoption across Europe. |
| Target Industrial Machinery Segment | Captures growth opportunities in part consolidation and performance enhancement for German manufacturers. |
| Invest in Explainable AI Features | Addresses regulatory requirements like the EU AI Act, building trust in critical applications. |
| Form Strategic Partnerships with Additive Manufacturers | Enables a direct digital-to-physical workflow, unlocking complex geometries for physical production. |
Research Approach
Independent corroboration across industry reports, academic publications, and regulatory filings underwrites the qualitative findings and quantitative forecasts. Primary interviews with CTOs, engineering leads, and procurement officers from OEMs and defense contractors provided direct market insights. Secondary validation drew from technical journals, patent databases, and government economic reports, ensuring robust data integrity. Bottom-up and top-down triangulation reconciled disparate data points.
The market's rate-of-change decomposition framework analyzed historical growth drivers and projected future trends across the analysis window. Segmentation dimensions modeled included software type, technology, application, and end-user industry, alongside the regional adoption patterns. CAGRs were derived from a weighted average of segment-specific growth rates, considering technological maturity and regulatory impacts. Industry-specific forecast inputs included R&D spending in aerospace and automotive production volumes.
Inputs from financial disclosures, industry association reports, and technical specifications were available through the study window; gaps in emerging technology adoption rates introduce uncertainty bands. Forecasts reflect assumptions regarding technological advancements and regulatory stability. Deviation in global economic growth or unexpected shifts in sustainability mandates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Technology
3D Scanning Market
3D Technology
Digital Holography Market
3D Technology
Spatial Computing Market
3D Technology
LAMEA Smartphone 3D Camera Market
3D Technology
North America 3D 4D Technology Market
3D Technology
3D Printing CAD Software Market
3D Technology
APAC 3D 4D Technology Market
3D Technology
UK 3D Rendering Services Market
3D Technology
3D Geospatial Technologies Market
3D Technology
Mobile 3D Market
3D Technology
Global Mobile 3D Sensing Market
3D Technology
Global 3D Rendering Service Market
3D Technology
Contactless 3D Laser Scanner Market
3D Technology
3D Scanner Market
3D Technology
3D Point Cloud Processing Software Market
3D Technology
Global 3D Mapping and 3D Modeling Market