
 UK 3D Rendering Services Market | 2026-2036
UK 3D Rendering Services Market Size, Share, and Industry Trends Forecast 2026-2036
UK 3D Rendering Services Market Insights
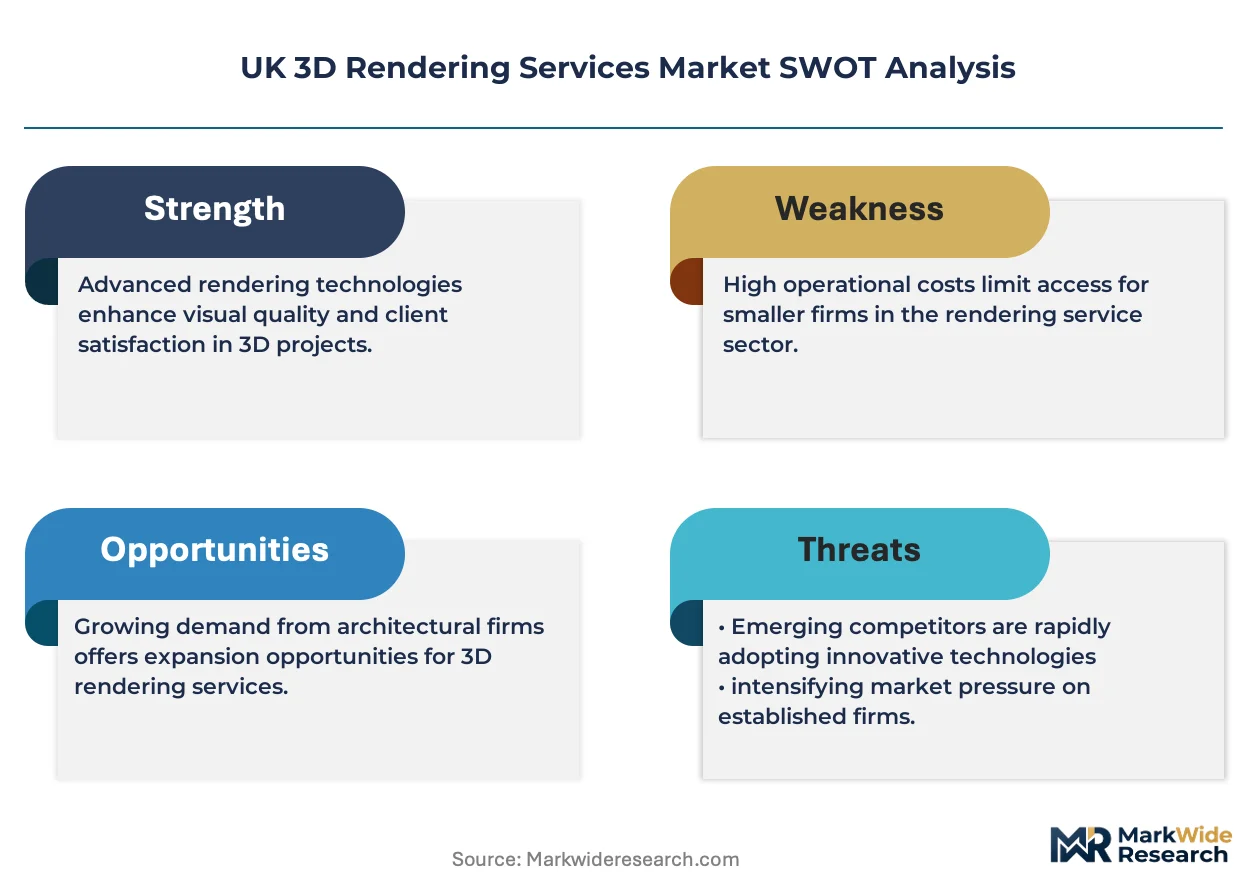
Photorealistic quality tiers is reorganizing the UK 3D rendering services landscape as clients reject basic wireframe outputs for immersive pre-visualization. Curved Axis leverages its London studio network to dominate high-end architectural commissions. Hayes Davidson sustains premium positioning through specialized heritage and cultural project expertise. RealRender3D anchors its growth in Manchester's expanding commercial development corridor.
3D rendering services encompass the computational generation of two-dimensional images from three-dimensional digital models, typically employing ray-tracing algorithms, global illumination calculations, and physically based material shaders to achieve visual accuracy. These services enable stakeholders to evaluate spatial relationships, lighting behavior, and surface finishes before physical construction or manufacturing commitment. Architectural visualization leads service type demand as UK planning authorities intensify visual impact requirements. Product rendering within the advertising vertical captures expanding margin pools as FMCG brands shift budget toward digital-first campaign assets. Subscription delivery models are gaining traction among design firms seeking predictable operational expenditure over lumpy project-based billing.
The UK's Building Regulations, enforced by local authority building control bodies, mandate energy performance visualization that rendering services increasingly supply. BSI standards for digital construction workflows, alongside emerging MHCLG guidance on building safety case visual documentation, shape compliance-driven procurement criteria. Stakeholders must monitor whether forthcoming UK-specific digital twin standards will merge rendering outputs with live sensor data, fundamentally altering service scope and technical capability requirements.
Market Dynamics
Real-time rendering pipelines are compressing project timelines across UK architectural visualization studios, forcing traditional offline ray-tracing workflows into obsolescence as clients demand same-day iteration cycles for planning submissions.
Growth Catalysts
- Building Regulations Part L:Energy performance visualization mandates are expanding the addressable market for photorealistic thermal and daylighting simulations within commercial development proposals.
- Ray-tracing hardware acceleration:NVIDIA RTX workstation adoption across Manchester and London studios is collapsing render times from hours to minutes, enabling competitive same-day delivery guarantees.
- Commercial property developers:Pre-leasing requirements in Greater London's speculative office sector are standardizing immersive virtual walkthroughs as a contractual precondition.
Market Restraints
- GPU supply concentration:NVIDIA's dominance in professional visualization silicon creates input cost volatility and procurement bottlenecks for mid-tier studios scaling render farm capacity.
- Skill scarcity:Unreal Engine technical artists command premium compensation that compresses margins for project-based service providers outside London's talent pool.
- Software licensing inflation:Autodesk and Chaos Group subscription escalations are structurally elevating operational expenditure faster than client billing rate acceptance.
Strategic Opportunities
- Heritage England documentation:Listed building consent applications are creating a compliance-driven niche for photogrammetric reconstruction and historically accurate material rendering.
- Digital twin convergence:Integration of real-time sensor data with pre-construction visualization outputs is opening recurring revenue streams beyond one-off project delivery.
- Subscription service models:Design firms in the South East are piloting retained visualization partnerships that convert lumpy project income into predictable monthly recurring revenue.
Industry Challenges
- Unreal Engine pipeline integration:Legacy 3ds Max and V-Ray workflows require substantial retraining investment and temporary productivity degradation during capability transition.
- BSI digital construction certification:Emerging standards for visual documentation in building safety cases are creating compliance timeline uncertainty and scope ambiguity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK 3D Rendering Services Market |
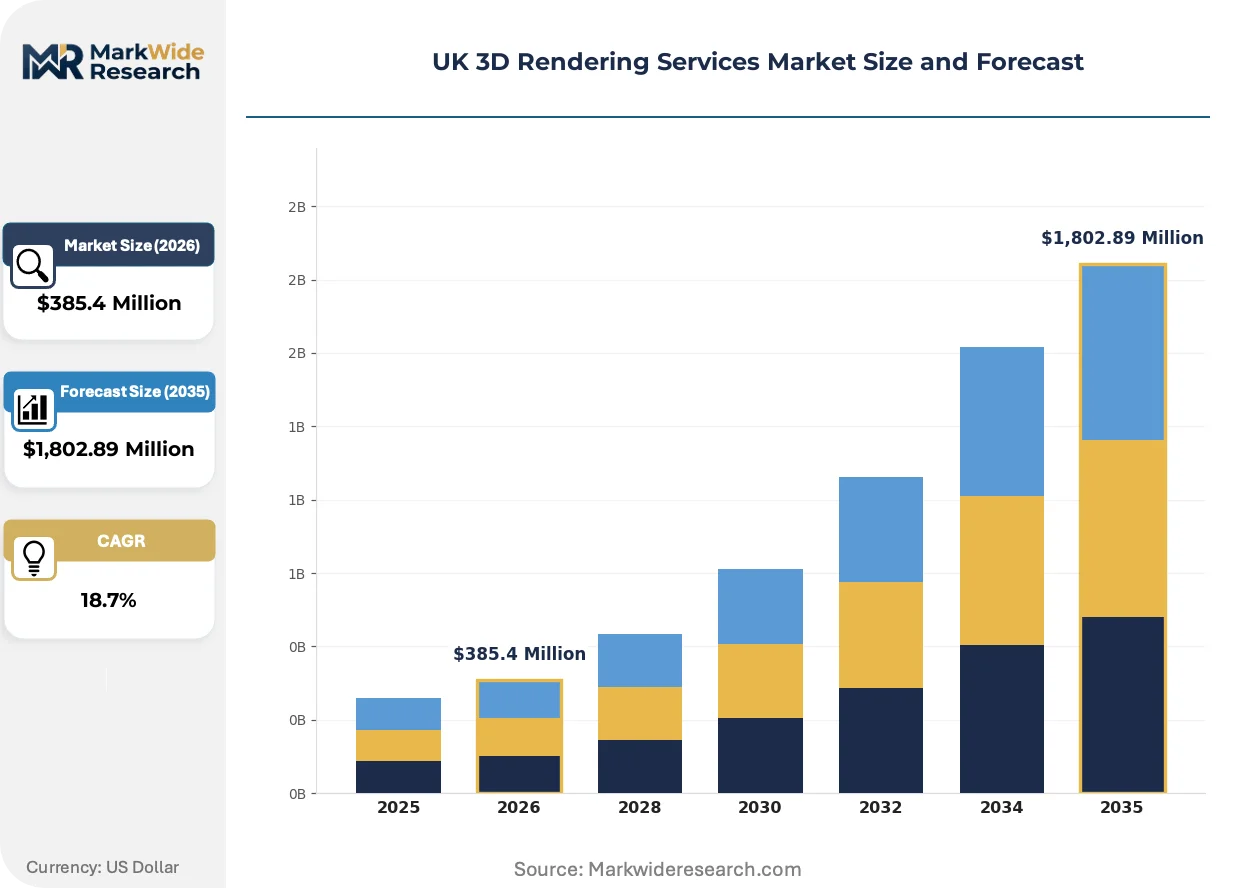
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,802.89 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Architectural Visualization, Product Rendering, Animation, Virtual Reality Industry Vertical: Architecture, Real Estate, Advertising, Gaming Delivery Model: On-Demand, Subscription, Project-Based, Retainer End User: Design Firms, Marketing Agencies, Developers, Retailers |
| Companies Covered | Curved Axis, RealRender3D, Chasing Illusions Studio, Hayes Davidson, Render4tomorrow, iCreate, Powerkh, Invedus, North Made Studio Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK 3D Rendering Services Market Trends and Innovations
Edge computing architectures are redistributing computational workloads across distributed render nodes, enabling smaller studios to compete on turnaround speed without capital-intensive on-premise infrastructure investments.
Real-time path tracing is miniaturizing the hardware footprint required for cinema-quality output. Boutique Manchester studios are adopting compact NVIDIA RTX-powered workstations to displace rack-mounted CPU render farms. This compression is democratizing photorealistic capability and eroding the scale advantage previously held by London's largest visualization houses.
MHCLG building safety case guidance is mandating visual documentation standards for higher-risk residential structures. Developers must now submit annotated 3D models demonstrating fire safety system routing and compartmentation. Visualization providers serving London's residential tower pipeline are retooling pipelines to generate compliance-ready deliverables that satisfy building control scrutiny.
Retained service agreements are displacing transactional project billing across South East design consultancies. Firms serving commercial property developers are negotiating annual visualization subscriptions that bundle priority scheduling and dedicated asset libraries. This shift is most visible among practices with recurring relationships with institutional landlords seeking portfolio-standardized visual identity systems.
UK 3D Rendering Services Market Segmentation
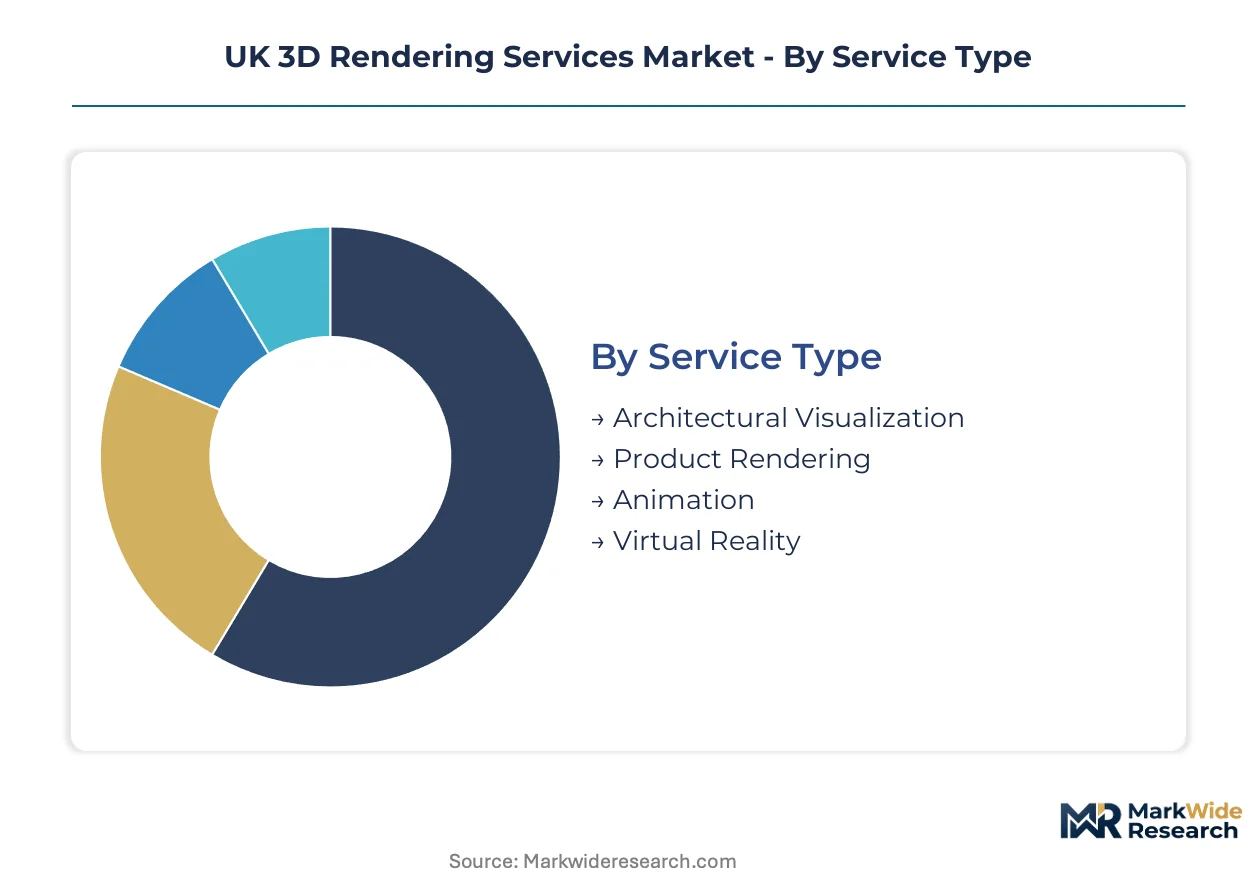
Service configuration in the UK 3D rendering market determines procurement patterns, margin structure, and client retention mechanics. Segment boundaries are blurring as real-time pipelines compress delivery timelines and subscription models displace transactional billing.
Service Type:
Channel mix varies sharply by output complexity, with architectural visualization flowing through design consultancy partnerships while product rendering concentrates in direct-to-brand digital agency relationships.
- Architectural Visualization:Photorealistic exterior and interior imagery generated from BIM workflows, employing ray-tracing engines for material accuracy. Demand clusters among London and Manchester practices serving speculative commercial developments where Building Regulations Part L compliance visualization is now mandatory. Thermal and daylighting simulation capabilities are becoming procurement differentiators.
- Product Rendering:Physically accurate digital product photography for e-commerce and campaign assets, typically using studio HDRI lighting and subsurface scattering for material fidelity. FMCG brands in the South East are shifting above-the-line budgets toward these digital-first deliverables, collapsing traditional photography timelines from weeks to days.
- Animation:Time-based visualization spanning flythrough sequences to narrative storytelling for stakeholder presentations.
- Virtual Reality:Immersive walkthrough environments enabling spatial navigation through head-mounted displays or browser-based WebXR.
By volume, architectural visualization leads. By growth pace, virtual reality is climbing the fastest as pre-leasing requirements in Greater London standardize immersive experiences.
Industry Vertical:
Cost tier stratification separates heritage conservation commissions commanding premium rates from volume-driven residential marketing imagery.
- Architecture:Design practices requiring visualization for planning submissions, client presentations, and competition entries. London studios serving tall building applications face intensified visual impact documentation requirements from local planning authorities.
- Real Estate:Developers leveraging pre-construction visualization for off-plan sales and investor relations. Manchester's expanding commercial corridor is driving demand for speculative office visualizations that support forward-funding negotiations.
- Advertising:Campaign asset production for digital and print media, spanning automotive configurators to FMCG pack shots.
- Gaming:Environment and prop visualization for interactive entertainment, though UK service providers capture limited share against in-house studio capacity.
Architecture commands the highest project values. Advertising is expanding most quickly as brand procurement shifts from photography to synthetic imagery.
Delivery Model:
Customer type determines contract structure, with institutional landlords favoring predictable expenditure while speculative developers retain project-based flexibility.
- On-Demand:Ad-hoc rendering capacity accessed through cloud platforms or freelance networks for surge workloads and tight deadlines.
- Subscription:Monthly recurring agreements bundling priority scheduling, asset library access, and standardized output formats. South East design consultancies are piloting these arrangements with visualization partners to convert lumpy operational expenditure into predictable budgets.
- Project-Based:Fixed-scope engagements with defined milestones, deliverables, and acceptance criteria, still dominant among one-off development proposals.
- Retainer:Annual agreements securing dedicated studio capacity and portfolio-standardized visual identity systems for repeat clients.
Project-based engagements still dominate transaction counts. Subscription and retainer models are gaining share fastest among practices with recurring developer relationships.
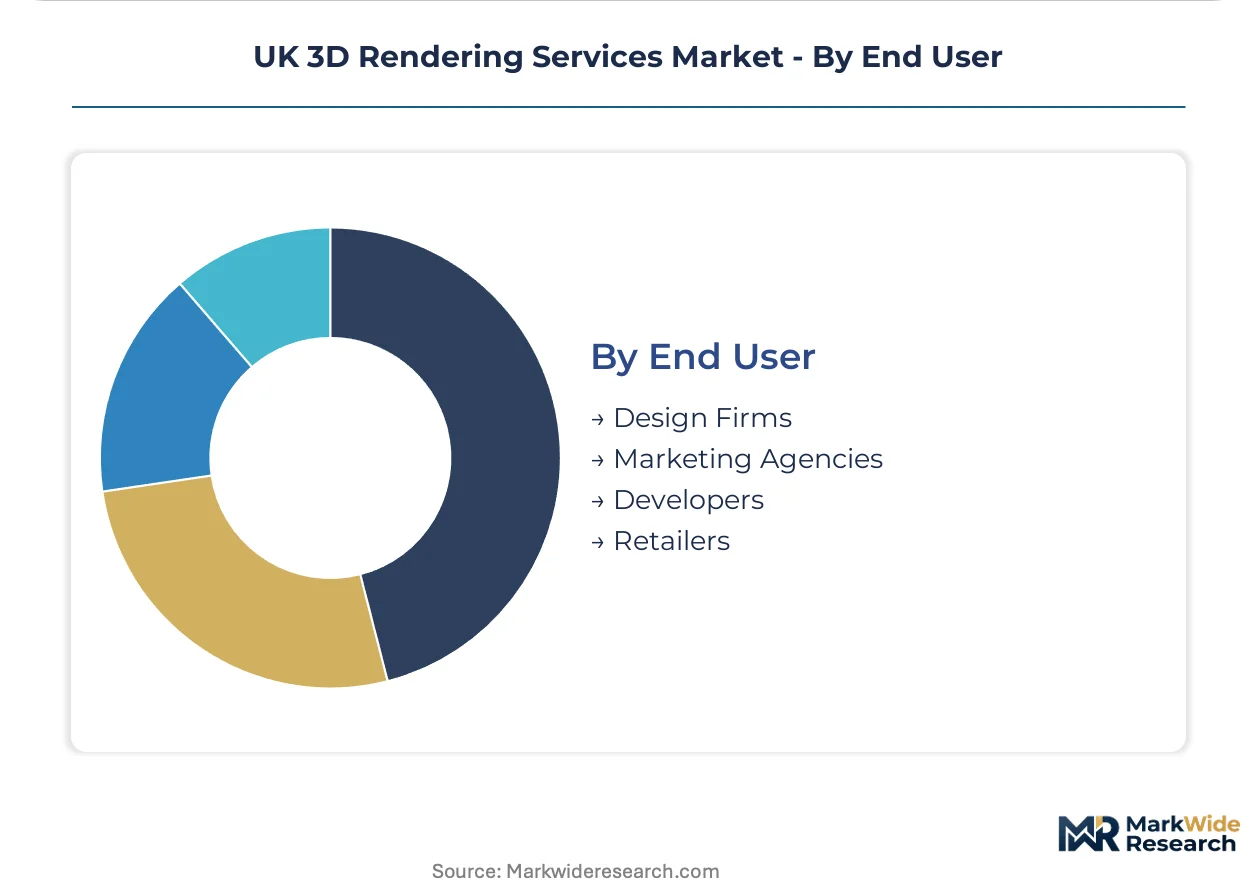
End User:
Geography shapes service requirements, with London-based users demanding same-day iteration cycles while regional practices accept extended timelines.
- Design Firms:Architectural and interior design practices requiring visualization as a project delivery component. Heritage England documentation for listed building consent is creating specialized demand for historically accurate material reconstruction.
- Marketing Agencies:Creative services firms integrating 3D assets into broader campaign production, spanning digital advertising to experiential installations.
- Developers:Property companies using visualization for planning, sales, and investor communications. Pre-leasing requirements in Greater London's institutional office sector are standardizing immersive virtual walkthroughs as contractual preconditions.
- Retailers:Brands deploying product visualization for e-commerce, augmented reality try-on, and catalog production.
Design firms represent the largest addressable base. Developers are expanding their visualization budgets most aggressively as planning requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UK 3D rendering services market exhibits limited cross-border trade activity, with domestic studios serving primarily local architectural and real estate clients while importing specialized software licenses and GPU hardware from US and Asian suppliers.
London and the South East
Commercial property developers in Canary Wharf and the City of London mandate immersive virtual walkthroughs as pre-leasing preconditions. Building Regulations Part L compliance visualization drives procurement from design consultancies. Curved Axis and Hayes Davidson anchor high-end architectural commissions across the capital.
Greater Manchester
Speculative office developments in Spinningfields and MediaCityUK accelerate demand for real-time rendering pipelines. The Greater Manchester Combined Authority's spatial framework intensifies visual impact documentation requirements. RealRender3D occupies a central position in the region's expanding commercial visualization corridor.
West Midlands
Birmingham's Big City Plan and Coventry's urban regeneration schemes generate steady architectural visualization volume. Local planning authorities increasingly require photorealistic daylighting simulations for major applications. Smaller studios in the region compete on turnaround speed rather than premium output quality.
Scotland
Edinburgh's heritage conservation sector demands historically accurate material reconstruction for listed building consent applications. Historic Environment Scotland's technical standards shape procurement criteria for photogrammetric documentation. Specialized providers serve the niche intersection of conservation and visualization.
Wales
Cardiff's commercial development pipeline and Swansea's coastal regeneration projects sustain mid-tier rendering demand. Welsh Government planning policy emphasizes visual impact assessment for renewable energy infrastructure. Regional studios leverage lower operational costs to undercut London pricing on standard residential marketing imagery.
UK 3D Rendering Services Market Competitive Landscape
Listed visualization groups compete with private specialist studios across talent access and project selectivity dimensions. The vendor base stratifies into three tiers: premium heritage-focused boutiques, mid-market commercial generalists, and volume-driven residential marketing factories. Strategic differentiation concentrates on real-time pipeline capability, subscription service packaging, and Building Regulations compliance expertise. Competitive moves center on technical artist recruitment and retained client agreement conversion.
Within the heritage-specialist tier, Hayes Davidson exemplifies premium positioning through conservation-sector expertise. Curved Axis and RealRender3D occupy complementary geographic anchor positions across London and Manchester respectively. These three entities represent distinct competitive archetypes: conservation credibility, capital-market proximity, and regional scale efficiency.
| Leading Market Players |
|---|
| Curved Axis |
| RealRender3D |
| Chasing Illusions Studio |
| Hayes Davidson |
| Render4tomorrow |
| iCreate |
| Powerkh |
| Invedus |
| North Made Studio Ltd |
| Others |
Pricing and Supply Chain Analysis
GPU-as-a-service cloud rendering is displacing capital-intensive on-premise render farms, simultaneously redistributing supply geography toward US hyperscaler data centers and compressing pricing economics for mid-tier UK studios previously protected by hardware scale advantages.
Pricing Analysis
Commercial property developers anchor project-based pricing structures across London and Manchester visualization markets. Premium-mid-economy pricing differentiation separates heritage conservation commissions from volume residential marketing imagery, with thermal simulation certification and Building Regulations Part L compliance expertise commanding rate premiums. Pricing pressure stems from GPU supply concentration and Autodesk subscription escalations that outpace client billing acceptance. Regional studios outside London's talent pool exhibit highest price sensitivity due to compressed margins on standard architectural visualization deliverables.
Supply Chain Analysis
Taiwan and South Korea anchor GPU fabrication for professional visualization silicon, with NVIDIA's foundry partnerships creating single-source vulnerability for UK render farm operators. Supply chains draw from US hyperscaler cloud platforms, German precision optics for photogrammetry hardware, and Japanese storage components for asset pipeline infrastructure. Tariff exposure on semiconductor imports from Asia-Pacific manufacturing hubs elevates input cost volatility. Distribution runs through direct procurement relationships between visualization studios and authorized hardware resellers, supplemented by cloud rendering credits purchased through NVIDIA partner networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Unreal Engine technical artist scarcity constrains pipeline conversion velocity across UK visualization studios, with Manchester and Birmingham practices particularly exposed to London's talent suction as real-time rendering mandates intensify.
For Market Incumbents: Shield premium positioning by embedding Building Regulations Part L compliance visualization into retained service agreements, converting one-off project relationships into recurring revenue streams. Acquire Unreal Engine pipeline capability through targeted technical artist recruitment in Manchester's expanding media corridor, defending against cloud-native entrants offering GPU-as-a-service rendering without legacy workflow overhead.
For New Entrants and Emerging Players: Anchor in Heritage England documentation niche, where photogrammetric reconstruction and historically accurate material rendering command rate premiums protected by specialized expertise barriers. Target Edinburgh and Scotland's conservation sector with compliance-driven service packaging, leveraging lower operational costs against London incumbents while building credential portfolio for broader architectural visualization expansion.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-market visualization groups consolidating regional studio networks across Greater Manchester and the West Midlands. Long-term viability hinges on subscription model conversion success and real-time pipeline integration completion. Monitor NVIDIA RTX workstation adoption curves across target studio portfolios as inflection indicator for competitive positioning sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Real-Time Pipeline Integration | Unreal Engine adoption collapses render timelines from hours to minutes for planning submissions. |
| Subscription Model Conversion | Retained agreements with South East design consultancies transform lumpy project income into predictable monthly recurring revenue. |
| Heritage Specialization Buildout | Photogrammetric reconstruction capability for listed building consent applications commands premium rate protection. |
| Cloud Rendering Partnership | GPU-as-a-service arrangements eliminate capital-intensive render farm investments for mid-tier studios. |
| Technical Artist Acquisition | Unreal Engine talent recruitment in Manchester media corridor accelerates pipeline capability transition. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, software vendor disclosures, and architectural practice procurement data. Primary interviews engaged visualization studio directors, BIM managers at design consultancies, building control officers, and commercial property development executives. Secondary sources encompassed MHCLG building safety guidance documents, BSI digital construction standards, NVIDIA quarterly datacenter revenue disclosures, and Autodesk subscription pricing archives. Bottom-up studio capacity estimates triangulated against top-down addressable market calculations derived from UK construction output statistics and planning application volumes.
Segmentation dimensions modeled span service type, industry vertical, delivery model, and end-user geography across the analysis window. Architectural visualization, product rendering, animation, and virtual reality categories were cross-tabulated against architecture, real estate, advertising, and gaming verticals. Delivery model splits captured on-demand, subscription, project-based, and retainer structures. CAGRs derived from regression analysis of historical studio revenue trajectories, GPU hardware shipment correlations, and planning application growth rates. Industry-specific inputs included Building Regulations Part L implementation timelines and Heritage England consent application volumes.
Material uncertainties — regulatory timeline slippage for BSI digital construction certification, NVIDIA supply allocation volatility, and Unreal Engine talent pool expansion rates — sit outside the modeled envelope. Forecasts reflect assumptions regarding real-time rendering adoption velocity and subscription billing conversion rates among South East design consultancies. Recalibration cycles align with material shifts in MHCLG building safety case guidance and UK-specific digital twin standard emergence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Technology
3D Mobile Mapping Market
3D Technology
3D Reconstruction Market
3D Technology
3D Machine Vision Market
3D Technology
Europe 3D 4D Technology Market
3D Technology
Generative Design Market
3D Technology
Global 3D Rendering Service Market
3D Technology
Visualization and 3D Rendering Software Market
3D Technology
Smartphone 3D Camera Market
3D Technology
3D CAD Market
3D Technology
3D Point Cloud Processing Software Market
3D Technology
3D Reconstruction Technology Market
3D Technology
3D Rendering Market
3D Technology
Global 3D 4D Technology Market
3D Technology
Middle East and Africa 3D 4D Technology Market
3D Technology
Mobile 3D Market
3D Technology
APAC 3D Telepresence Market