
 LAMEA Smartphone 3D Camera Market | 2026-2036
LAMEA Smartphone 3D Camera Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Smartphone 3D Camera Market Insights
Time-of-Flight sensor miniaturization is reshaping how smartphone OEMs integrate depth mapping into slim form factors. Samsung Electronics leverages its semiconductor foundry scale to anchor supply of VCSEL arrays across the LAMEA region. Sony Corporation sustains leadership in image sensor architecture through proprietary stacked CMOS designs. Huawei Technologies navigates component access constraints by deepening in-house production of structured light projectors.
A smartphone 3D camera captures depth information through active or passive triangulation methods, typically employing infrared emitters paired with CMOS receivers operating at 940 nanometers for ambient light rejection. These modules enable real-time spatial mapping for augmented reality overlays, biometric authentication, and computational photography pipelines. Stereo camera configurations currently dominate LAMEA shipment volumes due to lower bill-of-materials costs, while Time-of-Flight modules represent the fastest-growing category as 5G latency improvements unlock cloud-reliant AR applications. Content creators and professional photographers drive premium-tier demand, whereas casual users gravitate toward devices with basic depth-enabled portrait modes.
Brazil's ANATEL certification mandates electromagnetic compatibility testing for all infrared-emitting mobile devices, adding six to eight weeks to product registration timelines. South Africa's ICASA enforces SAR limits that constrain emitter power density in 3D camera modules. Saudi Arabia's CITC and UAE's TDRA are harmonizing device approval pathways under GCC standardization frameworks, streamlining multi-country launches. Stakeholders must monitor evolving spectrum allocation decisions for short-range infrared, as these directly determine permissible depth-sensing range and accuracy specifications in next-generation hardware.
Market Dynamics
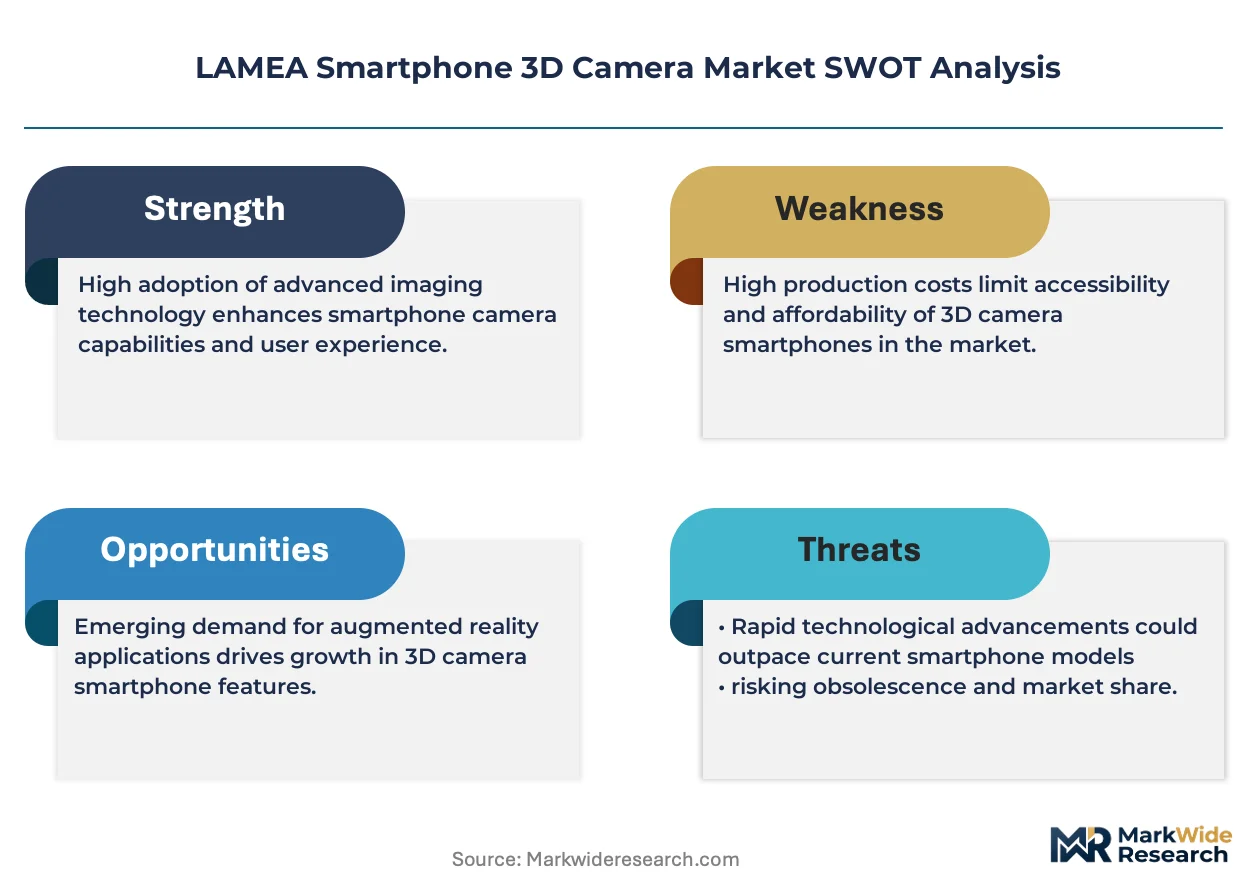
Time-of-Flight sensor miniaturization is compressing module thickness below 3.5 millimeters, forcing OEMs to redesign thermal management architectures around VCSEL emitter arrays. This structural shift favors foundry-scale suppliers with captive semiconductor packaging capabilities.
Growth Catalysts
- 5G spectrum allocations:South Africa's ICASA has released mid-band frequencies enabling sub-20 millisecond latency for cloud-rendered AR. Mobile operators in São Paulo are bundling 3D-capable handsets with premium data plans.
- Content creator tooling:Nigerian production studios are adopting depth-enabled smartphones for virtual set replacement, reducing hardware investment versus dedicated cinema cameras. Lagos-based creator collectives drive bulk procurement of ToF-equipped devices.
- GCC regulatory harmonization:Saudi Arabia's CITC and UAE's TDRA have aligned infrared device certification under unified standards. Multi-country launch timelines for smartphone OEMs have compressed from sixteen weeks to nine.
Market Restraints
- Input cost volatility:Indium phosphide substrates for 940 nanometer VCSELs face price swings tied to rare earth concentrate supply from Chinese refiners. Module BOMs fluctuate 12-18 percent quarter-to-quarter.
- Supply concentration risk:Advanced CMOS image sensor packaging for stacked die architectures concentrates in Taiwanese and South Korean foundries. LAMEA-bound shipments experience 8-10 week lead times during capacity crunches.
- Technical limitation:Direct sunlight interference above 50,000 lux degrades Time-of-Flight accuracy for outdoor AR applications. Structured light alternatives remain prohibitively thick for slim smartphone profiles.
Strategic Opportunities
- Underpenetrated geography:Egypt and Morocco exhibit sub-5 percent 3D camera penetration in mid-tier smartphone segments. Local assembly partnerships with Shenzhen-based sensor integrators could unlock price-competitive SKUs.
- Emerging application:Telemedicine platforms in Kenya are piloting depth-sensing for remote wound measurement and dermatology screening. Clinical validation partnerships with Nairobi hospital networks create first-mover positioning.
- Regulatory tailwind:Brazil's ANATEL is streamlining electromagnetic compatibility testing for devices with sub-500 milliwatt infrared emitters. Fast-track certification paths reward low-power ToF designs.
Industry Challenges
- Calibration expertise scarcity:Precision alignment of stereo baseline configurations requires optomechanical technicians with sub-micron tolerancing skills. São Paulo's technical institutes graduate fewer than 200 qualified specialists annually.
- Certification timeline friction:ANATEL's infrared device registration demands six to eight weeks of electromagnetic compatibility testing. Product launch windows misalign with competitive cycles in other regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Smartphone 3D Camera Market |
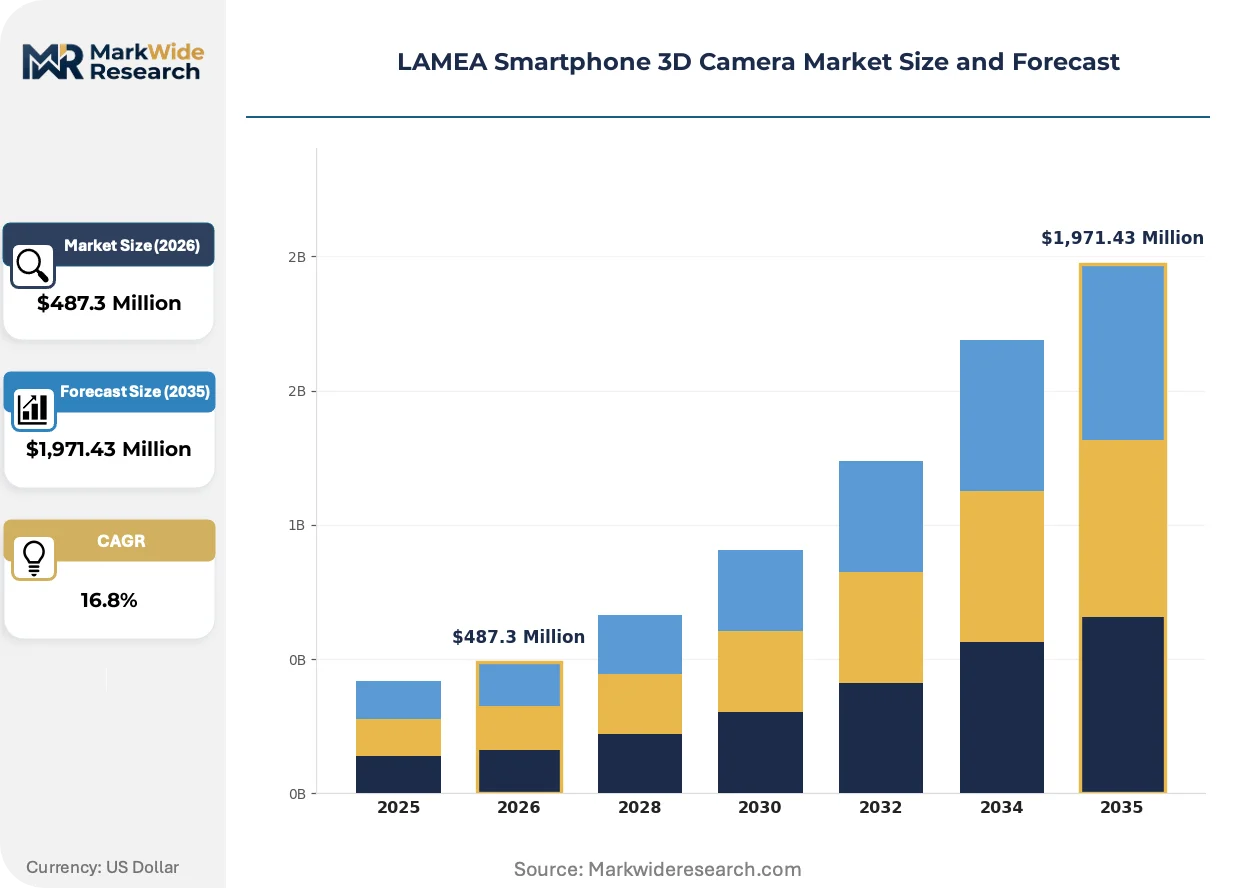
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,971.43 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Camera Technology: Time-of-Flight, Stereo, Structured Light, Lidar End User: Professional Photographers, Content Creators, Casual Users, Businesses Application: Augmented Reality, 3D Modeling, Virtual Reality, Photography Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Wholesale |
| Companies Covered | Samsung Electronics, Sony Corporation, LG Electronics, Huawei Technologies, Apple, Xiaomi Corporation, Oppo, Vivo, Qualcomm, Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Smartphone 3D Camera Market Trends and Innovations
Computational depth pipelines are migrating from dedicated DSP silicon to heterogeneous computing fabrics, altering how smartphone OEMs partition hardware and software investments. This architectural shift is redrawing supplier relationships across the imaging stack.
Direct Time-of-Flight modules with single-photon avalanche diode arrays are virtualizing depth mapping workloads that previously required stereo camera pairs and heavy post-processing. Content creators in Brazil's São Paulo corridor are adopting these modules for real-time volumetric video capture without external depth rigs. The compression of hardware requirements is virtualizing entry barriers for professional-grade spatial content production.
ICASA's phased 5G spectrum releases in South Africa are mandating SAR compliance documentation for all millimeter-wave and infrared-emitting mobile devices. Smartphone OEMs must submit revised emitter power density calculations for each 3D camera variant. Premium-tier devices with higher-output VCSEL arrays face extended review cycles, pushing some manufacturers toward lower-power ToF configurations for initial launches.
Creator economy procurement is fragmenting away from carrier-locked distribution toward direct-to-studio bulk purchasing. Nigerian production houses in Lagos now negotiate volume pricing directly with regional distributors, bypassing traditional retail markups. This channel disintermediation concentrates in markets where mobile operator subsidies remain shallow and enterprise content budgets exceed consumer handset replacement cycles.
LAMEA Smartphone 3D Camera Market Segmentation
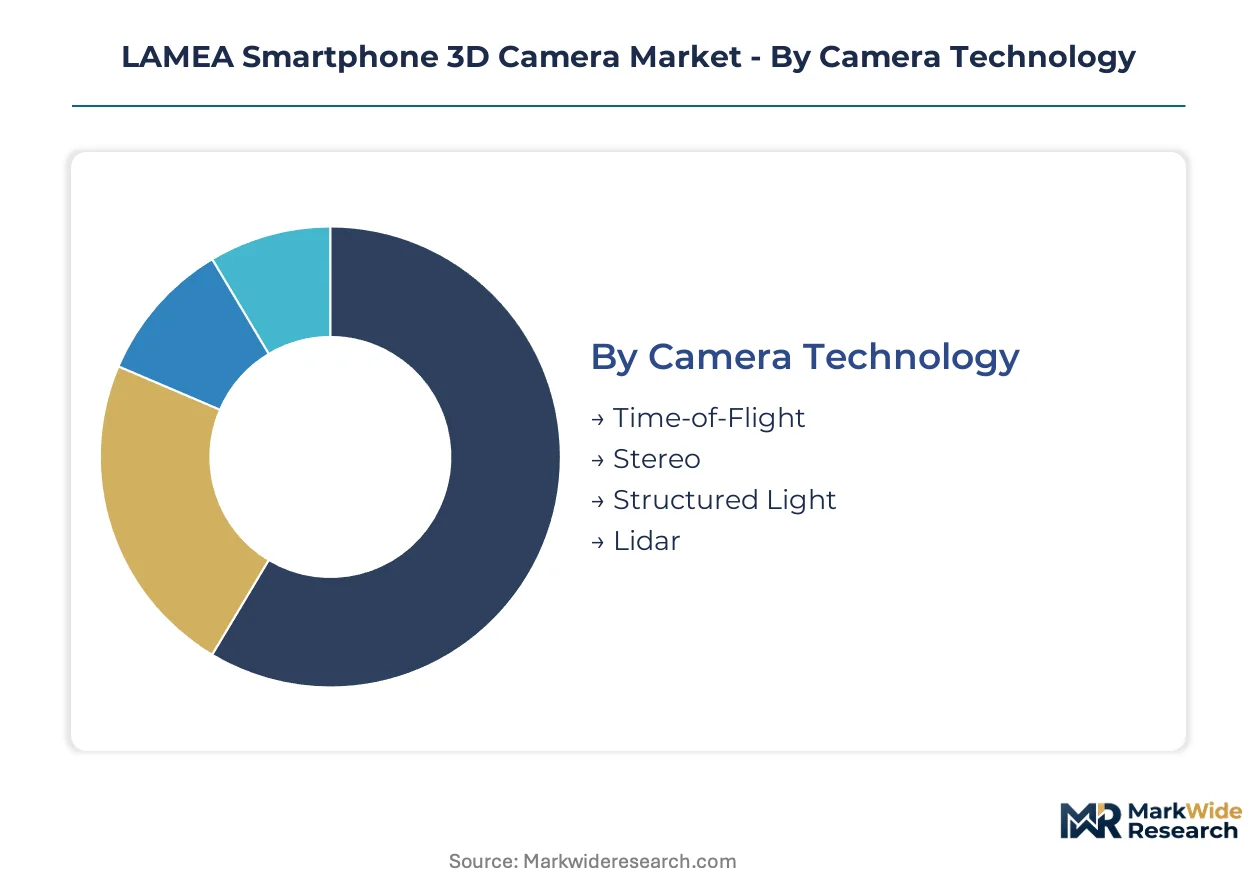
Technology differentiation, user sophistication, and application intensity create distinct commercial pockets within the LAMEA smartphone 3D camera landscape. Each segmentation dimension reveals divergent margin profiles and supply chain requirements that shape go-to-market strategy.
Camera Technology:
Use-case spectrum spans from basic portrait depth effects to professional volumetric capture, with each technology tier demanding different semiconductor packaging and thermal architectures.
- Time-of-Flight:VCSEL emitter arrays paired with single-photon avalanche diodes enable real-time depth mapping at sub-3.5 millimeter module thickness. São Paulo's content creator studios drive premium-tier procurement for cloud-rendered AR workflows over South Africa's emerging 5G networks.
- Stereo:Dual CMOS configurations with fixed baseline separation dominate shipment volumes across Brazil's mid-tier retail channels. Nigerian production houses favor these modules for virtual set replacement where computational post-processing substitutes for hardware depth precision.
- Structured Light:Infrared dot-pattern projectors require thicker housing assemblies, limiting penetration in slim-form-factor flagships.
- Lidar:Scanning solid-state arrays remain confined to ultra-premium SKUs with specialized AR navigation applications.
The dominant share belongs to Stereo, while Time-of-Flight is closing the gap fastest.
End User:
Customer sophistication determines pricing elasticity and replacement cycle velocity across the LAMEA region.
- Content Creators:Lagos-based production collectives negotiate bulk procurement of ToF-equipped devices for real-time volumetric capture, bypassing traditional carrier distribution. Their hardware budgets exceed consumer replacement cycles by 3-4x, concentrating demand in direct-to-studio channels.
- Professional Photographers:São Paulo's commercial imaging specialists require calibrated depth accuracy for client deliverables, driving specification conversations with OEM technical teams.
- Casual Users:Basic portrait-mode functionality satisfies depth-enabled photography needs across Egypt and Morocco's price-sensitive mid-tier segments.
- Businesses:Kenyan telemedicine platforms pilot structured-light configurations for clinical measurement applications.
Content Creators command the steepest expansion trajectory, while Casual Users retain volume concentration.
Application:
Workload intensity varies from lightweight computational photography to compute-heavy spatial computing pipelines.
- Augmented Reality:Real-time overlay rendering demands sub-20 millisecond latency, tethering hardware upgrades to 5G spectrum availability in South Africa and Brazil.
- Photography:Portrait segmentation and bokeh simulation consume the majority of depth-processing cycles across LAMEA-installed base.
- 3D Modeling:Object digitization for e-commerce catalogs drives SME adoption in UAE's retail technology sector.
- Virtual Reality:Spatial video capture for immersive headsets remains nascent outside Saudi Arabia's early-adopter consumer segment.
Photography anchors current utilization, though Augmented Reality is gaining share fastest.
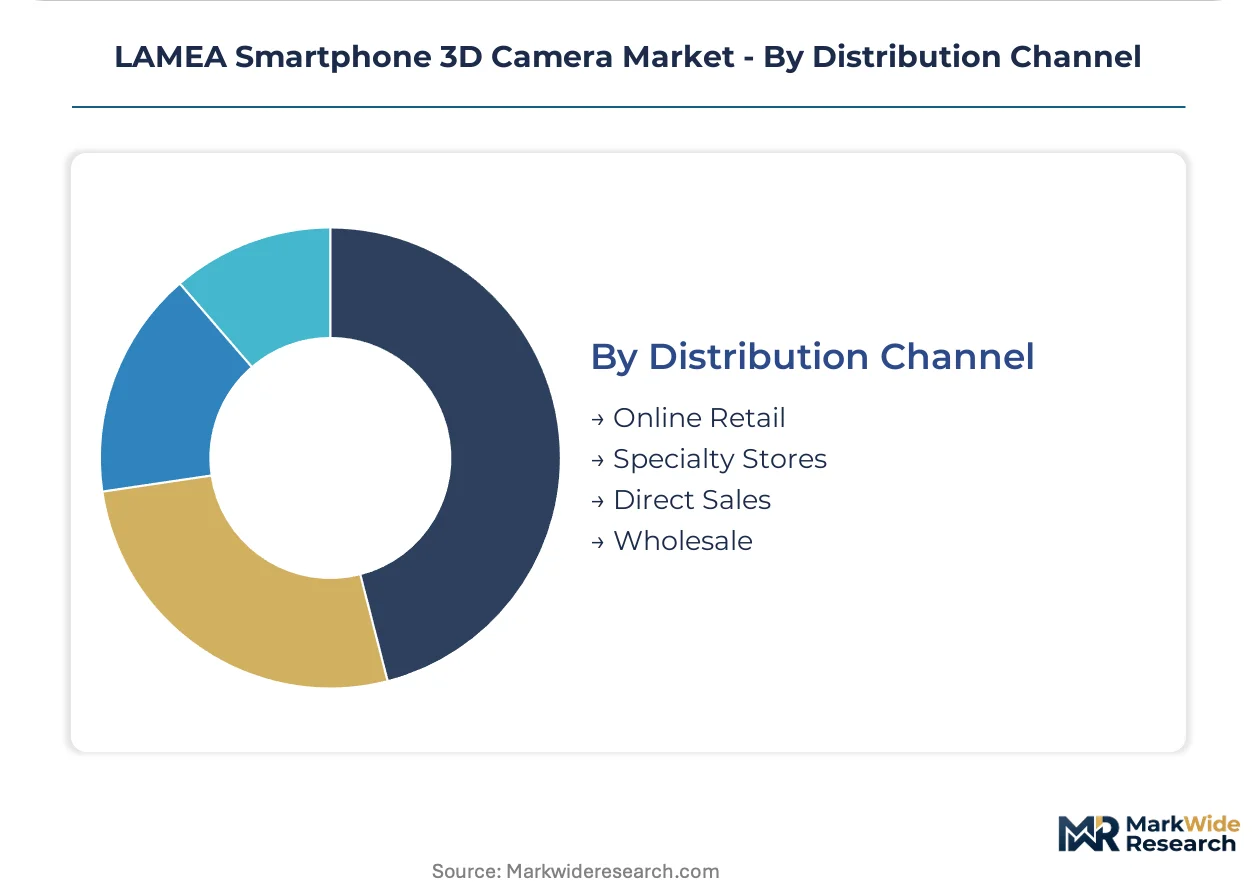
Distribution Channel:
Channel configuration reflects subsidy depth and enterprise procurement maturity across national markets.
- Online Retail:Mercado Livre and Jumia aggregate fragmented demand across Brazil and Nigeria, enabling price-transparent comparison of ToF specifications.
- Direct Sales:Studio-to-OEM negotiations in Lagos and São Paulo bypass retail markups for volume creator contracts.
- Specialty Stores:Premium-tier experiential retail concentrates in Dubai and Johannesburg shopping districts.
- Wholesale:Regional distributors serve mid-tier retail chains in Morocco and Egypt with limited carrier subsidy infrastructure.
Online Retail holds the dominant position, while Direct Sales is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese sensor suppliers export VCSEL arrays and CMOS modules to Brazilian assembly plants serving LAMEA distribution networks. This trade corridor channels hardware through São Paulo's tech corridor for regional redistribution.
Brazil
Content creator studios in São Paulo drive premium-tier procurement of ToF-equipped devices for volumetric video production. ANATEL certification mandates electromagnetic compatibility testing for infrared-emitting devices, extending registration timelines by six to eight weeks. Local assembly partnerships with Shenzhen-based sensor integrators are scaling rapidly in the São Paulo tech corridor.
South Africa
ICASA's 5G spectrum allocations enable sub-20 millisecond latency for cloud-rendered AR applications, accelerating hardware upgrades. SAR limits enforced by the regulator constrain emitter power density in 3D camera modules. Johannesburg's premium retail districts concentrate experiential specialty stores for flagship device launches.
Nigeria
Lagos-based production houses negotiate bulk procurement of depth-enabled smartphones for virtual set replacement workflows. The national communications commission oversees device type approval for infrared-emitting mobile hardware. Creator collectives in Lagos bypass traditional carrier distribution, driving direct-to-studio channel growth.
Saudi Arabia
Early-adopter consumer segments pilot spatial video capture for immersive headset applications. CITC has aligned infrared device certification with UAE's TDRA under GCC standardization frameworks, compressing multi-country launch timelines. Riyadh's retail technology sector shows emerging demand for 3D modeling in e-commerce catalog digitization.
United Arab Emirates
Dubai's shopping districts anchor premium-tier experiential retail for flagship smartphone launches. TDRA harmonization with Saudi CITC streamlines approval pathways for OEMs targeting Gulf markets. The emirate's logistics infrastructure supports regional redistribution of sensor modules to underpenetrated North African markets.
LAMEA Smartphone 3D Camera Market Competitive Landscape
Channel-controlling players compete with product-specialist players across the LAMEA smartphone 3D camera landscape. The vendor base clusters around semiconductor foundries with captive packaging capabilities, imaging sensor architects, and handset OEMs with in-house depth module integration. Three archetypes dominate: foundry-scale suppliers anchoring VCSEL supply, stacked CMOS specialists, and vertically integrated handset manufacturers navigating component access constraints. Competitive moves concentrate on strategic partnerships with regional distributors and technology licensing for depth-sensing pipelines.
Within the foundry-scale tier, Samsung Electronics and Sony Corporation exemplify suppliers with captive semiconductor packaging capabilities. Samsung Electronics leverages its foundry scale to anchor VCSEL array supply across LAMEA, while Sony Corporation sustains leadership in image sensor architecture through proprietary designs. Huawei Technologies occupies a position among handset OEMs deepening in-house production of structured light components to navigate access constraints.
| Leading Market Players |
|---|
| Samsung Electronics |
| Sony Corporation |
| LG Electronics |
| Huawei Technologies |
| Apple |
| Xiaomi Corporation |
| Oppo |
| Vivo |
| Qualcomm |
| Others |
Pricing and Supply Chain Analysis
Taiwanese and South Korean foundry concentration for advanced CMOS packaging concentrates margin capture upstream, while downstream OEMs in Brazil and Nigeria compete on volume procurement terms. This structural asymmetry shapes how price pressure transmits from sensor module suppliers to handset assemblers across the LAMEA corridor.
Pricing Analysis
Next-generation Time-of-Flight modules command premium positioning against prior-generation stereo configurations and emerging structured-light alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under ANATEL and ICASA electromagnetic compatibility tiers. Cost compression in mid-tier stereo modules is intensifying because Nigerian production houses negotiate direct-to-studio volume contracts. Casual users in Egypt and Morocco exhibit highest price sensitivity, while São Paulo content creator studios show lowest elasticity for calibrated depth-accuracy specifications.
Supply Chain Analysis
Extended payment terms from Shenzhen-based sensor integrators to Brazilian assembly partners are lubricating working capital flows through the São Paulo tech corridor. VCSEL emitter arrays and indium phosphide substrates draw from Chinese refiners and Taiwanese packaging houses, with CMOS receivers sourcing from South Korean foundries. Single-source vulnerability concentrates in advanced stacked-die architectures. Distribution runs through Mercado Livre and Jumia platforms aggregating fragmented LAMEA demand, supplemented by direct OEM-to-studio negotiations in Lagos and São Paulo.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. Certification complexity under ANATEL, ICASA, and GCC harmonized standards creates sticky incumbent positions that resist rapid competitive displacement.
For Market Incumbents: Build certification moats through preemptive ANATEL fast-track qualification for sub-500 milliwatt ToF designs. Deepen captive semiconductor packaging partnerships with Taiwanese foundries to secure allocation during capacity crunches. Emerging Chinese sensor suppliers threaten component access leverage. Channel control through direct-to-studio relationships in Lagos insulates against carrier subsidy volatility. For New Entrants and Emerging Players: Mid-tier smartphone segments in Egypt and Morocco represent the most penetrable entry point for price-competitive stereo module SKUs. Kenyan telemedicine pilot programs for clinical depth-sensing applications offer specialized vertical entry with lower certification overhead. Local assembly partnerships with Shenzhen integrators unlock cost positioning against established OEM supply chains. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional distributors controlling Mercado Livre and Jumia platform access. Long-term viability hinges on 5G spectrum allocation velocity and creator economy monetization depth. Watch ICASA phased spectrum release timelines as inflection indicator for hardware upgrade cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| VCSEL Emitter Miniaturization | Samsung Electronics' foundry scale anchors supply security for sub-3.5mm module thickness requirements. |
| Direct-to-Studio Channel Development | Lagos creator collectives bypass retail markups, concentrating procurement power in enterprise content budgets. |
| GCC Regulatory Harmonization | CITC-TDRA alignment compresses multi-country launch timelines from sixteen weeks to nine. |
| Low-Power ToF Certification Path | ANATEL fast-track rewards sub-500 milliwatt designs with accelerated electromagnetic compatibility approval. |
| Telemedicine Application Validation | Nairobi hospital network partnerships create first-mover positioning for clinical depth-sensing hardware. |
Research Methodology
A spread of perspectives from smartphone OEM platform engineers, VCSEL foundry operations managers, ANATEL certification specialists, Lagos content creator studio heads, and Mercado Livre category buyers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through ANATEL regulatory filings, ICASA spectrum allocation notices, GCC standardization framework documents, and customs records tracking sensor module flows through São Paulo's tech corridor. Bottom-up shipment modeling and top-down value estimation triangulated on segment-level outputs.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions spanned camera technology tier, end-user sophistication level, application intensity, and distribution channel configuration. CAGRs derived from installed base penetration curves and replacement cycle velocity by price tier. Forecast inputs incorporated 5G spectrum release schedules and creator economy hardware budget trajectories.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real volatility, Chinese rare earth export policy, or South African 5G deployment cadence would shift the trajectory. Forecasts reflect documented assumptions about module cost curves and regulatory timeline stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Technology
Europe 3D 4D Technology Market
3D Technology
3D Simulation Software Market
3D Technology
Global 3D Virtual Platform Market
3D Technology
3D Scanner Market
3D Technology
North America 3D 4D Technology Market
3D Technology
Glasses Free 3D Tvs Market
3D Technology
Digital Holography Market
3D Technology
3D Rendering Market
3D Technology
3D Reconstruction Technology Market
3D Technology
APAC 3D 4D Technology Market
3D Technology
3D Technology Market
3D Technology
Spatial Computing Market
3D Technology
3D Reconstruction Market
3D Technology
3D Scanning Market
3D Technology
Molecular Modeling Market
3D Technology
Europe 3D Telepresence Market