
 Global Mobile 3D Sensing Market | 2026-2036
Global Mobile 3D Sensing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile 3D Sensing Market Foresight
Project finance tied to dedicated sensor foundry capacity is reshaping competitive entry in mobile 3D sensing, lowering the capital barrier for fabless algorithm developers and module assemblers. Sony Group Corporation leverages its captive CMOS image sensor fabrication to dominate time-of-flight chip supply. STMicroelectronics N.V. specializes in MEMS mirror and laser driver integration for compact lidar engines. Qualcomm Incorporated anchors software-defined depth processing through its Spectra ISP licensing program.
Mobile 3D sensing comprises active and passive optical systems that capture depth information via modulated light projection, stereo disparity, or direct time-of-flight measurement, typically operating at wavelengths between 850 nm and 940 nm for eye-safe near-infrared emission. These systems enable biometric authentication, spatial computing, and real-time environment reconstruction in handheld and wearable devices. Time of Flight technology leads volume shipments due to its maturity in Android flagship smartphones, while Lidar segments capture premium margin pools in AR-enabled devices. Camera Module assemblies concentrate value capture through tight integration with sensor chips and diffractive optical elements.
FCC Part 15 laser product regulations in the United States, CE marking under the EU RoHS directive, and China's GB 7247.1 laser safety standards collectively govern emitter power thresholds and consumer device certification pathways. EMA and FDA biometric data frameworks indirectly shape facial recognition deployment through privacy-informed hardware design requirements. Stakeholders must monitor evolving laser safety classifications and cross-border data governance to anticipate product redesign cycles and regional market access conditions.
Market Dynamics
Project finance for dedicated sensor foundry capacity is compressing capital barriers for fabless algorithm developers, while China's GB standards for energy-efficient semiconductor manufacturing tighten component specifications across the supply base.
Growth Catalysts
- Facial recognition integration:Biometric authentication mandates from EMA and FDA privacy frameworks drive hardware redesign cycles in flagship and mid-tier smartphones.
- GB 7247.1 laser safety standards:China's unified certification pathway accelerates emitter module approval timelines for domestic manufacturers exporting to ASEAN markets.
- Augmented reality spatial computing:Real-time environment reconstruction capabilities pull lidar and time-of-flight volume into AR-enabled wearable devices.
Market Restraints
- Near-infrared emitter cost volatility:Indium gallium arsenide VCSEL substrate pricing fluctuates with gallium metal supply concentration in Chinese refining operations.
- MEMS mirror supply concentration:Diffractive optical element fabrication for compact lidar engines clusters in South Korea's Seoul-Suwon corridor, creating single-geography dependency.
- Eye-safe power thresholds:FCC Part 15 laser product regulations cap emitter output at 940 nm wavelengths, limiting depth measurement range in outdoor applications.
Strategic Opportunities
- India PLI scheme incentives:Production-linked incentive structures for semiconductor assembly and testing attract camera module manufacturers to Gujarat and Tamil Nadu.
- Automotive cabin monitoring:Driver attention sensing and occupant classification systems create pull-through demand for time-of-flight arrays in electric vehicle interiors.
- Software-defined depth processing:ISP licensing programs enable fabless developers to bypass captive fabrication investments through algorithmic differentiation.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous FCC Part 15, CE marking under EU RoHS, and GB 7247.1 testing extends product launch cycles by eight to fourteen months.
- Cross-functional talent scarcity:Optomechanical design expertise combining laser physics with MEMS fabrication remains concentrated in legacy telecom and defense supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile 3D Sensing Market |
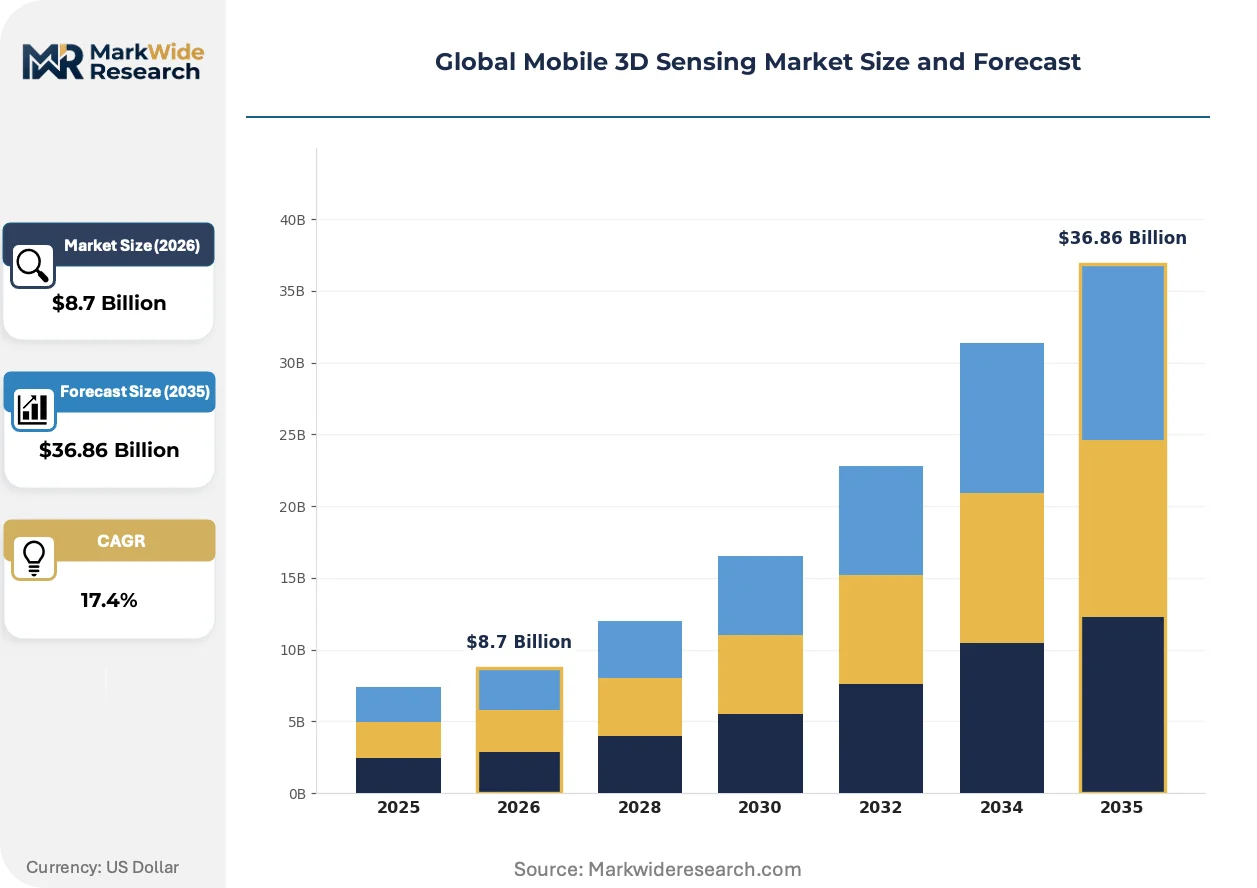
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $36.86 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Time of Flight, Structured Light, Stereo Vision, Lidar, Photometric Stereo Product Type: Camera Module, Sensor Chip, Software Algorithm, Processor Unit, Integrated System Application: Facial Recognition, Gesture Control, Augmented Reality, Object Scanning, Environment Mapping End User: Smartphone Manufacturers, Consumer Electronics Firms, Security Providers, Gaming Developers, Auto Suppliers |
| Companies Covered | Lumentum Holdings Inc., ams AG, Sony Group Corporation, ON Semiconductor Corporation, Himax Technologies, Samsung Electronics Co., Ltd., Infineon Technologies AG, STMicroelectronics N.V., Qualcomm Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile 3D Sensing Market Shifts & Advancements
Active and passive optical depth capture systems are converging toward unified sensor fusion architectures, compressing module footprint while expanding biometric and spatial computing use cases.
Solid-state lidar is hybridizing with time-of-flight arrays in Android flagship smartphones, enabling sub-millimeter depth accuracy for portrait segmentation and AR occlusion handling. Tier-one OEMs in South Korea and China have adopted this dual-mode architecture for 2024-2025 device generations. The convergence is hybridizing module supplier margins by forcing diffractive optical element vendors to qualify for both scanning and flash illumination specifications.
EU AI Act risk classification frameworks now categorize biometric identification systems as high-risk, triggering mandatory conformity assessment procedures for facial recognition hardware sold in European markets. CE marking under the MDR and GDPR alignment requirements extend documentation burdens for emitter power calibration and data governance chipsets. Premium device manufacturers are responding by pre-integrating privacy-preserving depth processing at the sensor edge rather than in host processors.
Buyers are consolidating procurement authority for 3D sensing subsystems under platform-level hardware architects, displacing legacy component-silo sourcing. This concentration compresses supplier negotiation cycles and privileges module assemblers with vertically integrated optical and semiconductor capabilities. The shift is most visible in China's consumer electronics supply base, where Xiaomi and OPPO procurement teams now mandate single-source accountability for camera module performance.
Global Mobile 3D Sensing Market Segmentation
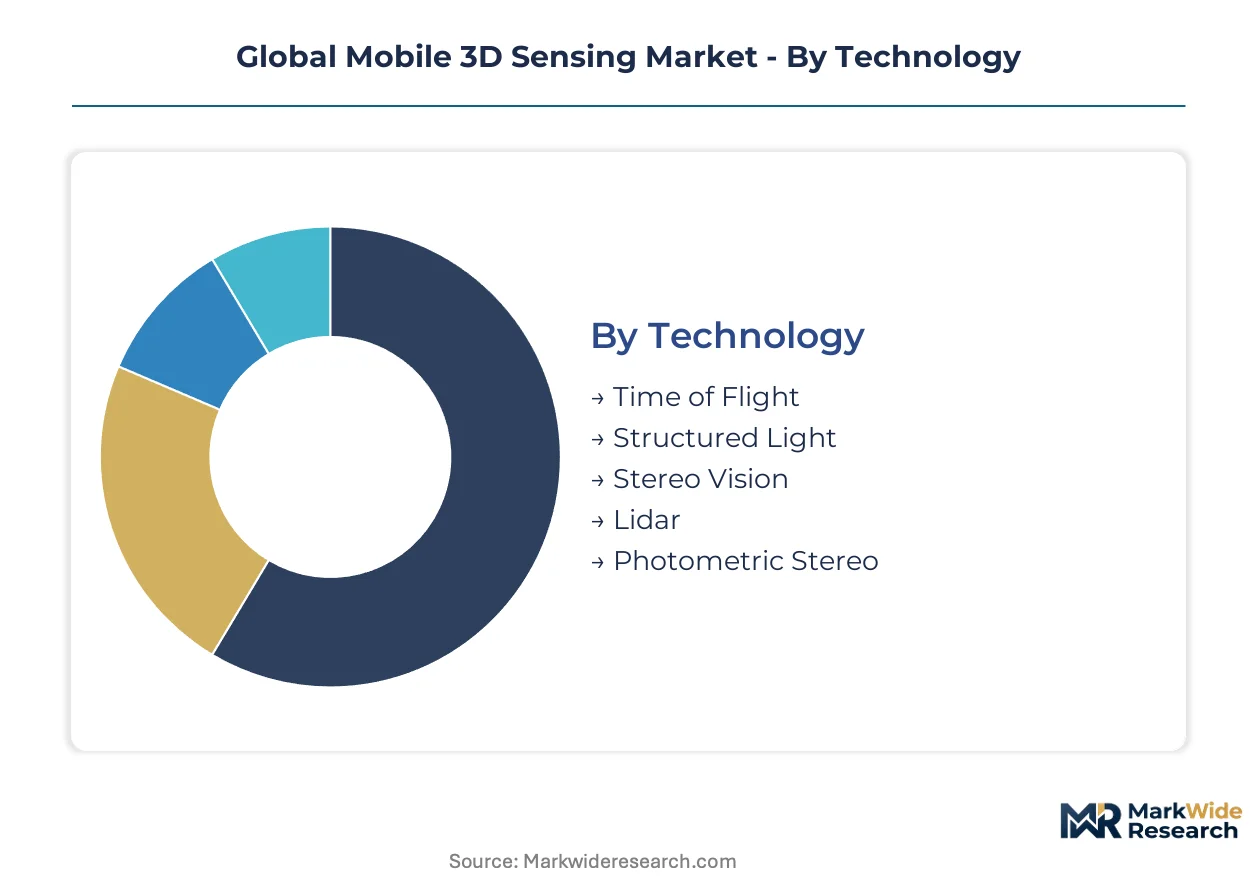
Technology architecture, product form factor, and application use case each exert distinct pricing and procurement logics in mobile 3D sensing. Module buyers consolidate sourcing authority around platform architects, forcing suppliers to qualify across multiple segmentation dimensions simultaneously.
Technology:
Cost tier stratification separates mature volume technologies from emerging premium architectures.
- Time of Flight:Modulated near-infrared illumination captures depth through phase-shift measurement at 850-940 nm wavelengths. South Korea's Seoul-Suwon corridor concentrates VCSEL emitter supply for Android flagship smartphones, though FCC Part 15 power thresholds constrain outdoor range performance.
- Lidar:Solid-state scanning engines with MEMS mirrors achieve sub-millimeter accuracy for AR occlusion and portrait segmentation. China's GB 7247.1 certification pathway accelerates emitter module approval for domestic manufacturers exporting to ASEAN markets.
- Structured Light:Pattern projection systems encode depth through geometric distortion analysis.
- Stereo Vision:Dual-camera disparity calculation operates without active illumination.
- Photometric Stereo:Multi-angle shading reconstruction enables surface normal mapping.
Time of Flight commands the established base. The steepest expansion runs through Lidar.
Product Type:
Application requirements determine whether buyers prioritize optical integration, semiconductor performance, or software flexibility.
- Camera Module:Tight integration of sensor chips with diffractive optical elements captures value through assembly precision. China's Xiaomi and OPPO procurement teams mandate single-source accountability for module performance, displacing legacy component-silo sourcing.
- Sensor Chip:CMOS time-of-flight and SPAD arrays govern depth measurement accuracy and power consumption. Sony Group Corporation leverages captive fabrication to dominate time-of-flight chip supply.
- Software Algorithm:Depth processing and noise reduction code enables differentiation without fabrication investment.
- Processor Unit:Dedicated ISP silicon accelerates point cloud generation.
- Integrated System:Complete optical-electronic-software stacks reduce buyer integration burden.
Camera Module captures the dominant revenue pool. Sensor Chip is climbing the fastest as foundry capacity expands.
Application:
Volume concentration varies sharply between biometric authentication mandates and emerging spatial computing use cases.
- Facial Recognition:Biometric authentication hardware responds to EMA and FDA privacy frameworks requiring hardware-level data protection. EU AI Act high-risk classification triggers mandatory conformity assessment for European market access.
- Augmented Reality:Real-time environment reconstruction pulls lidar and time-of-flight volume into AR-enabled wearables. Qualcomm Spectra ISP licensing enables software-defined depth processing without captive fabrication.
- Gesture Control:Mid-air interaction systems demand low-latency depth streams.
- Object Scanning:Sub-millimeter accuracy applications drive premium module specifications.
- Environment Mapping:Large-scale spatial reconstruction requires extended range and field of view.
Facial Recognition anchors current shipments. Augmented Reality shows the steepest trajectory as spatial computing platforms mature.
End User:
Customer type dictates procurement scale, certification burden, and integration complexity.
- Smartphone Manufacturers:Annual volume requirements exceeding hundreds of millions of units force qualification of multiple module suppliers. Samsung Electronics drives time-of-flight and lidar demand through its Seoul-Suwon supplier ecosystem.
- Auto Suppliers:Driver attention sensing and occupant classification systems create pull-through demand for time-of-flight arrays in electric vehicle cabin monitoring.
- Consumer Electronics Firms:Tablet, laptop, and wearable device makers adopt 3D sensing for differentiated features.
- Security Providers:Access control systems prioritize liveness detection and anti-spoofing performance.
- Gaming Developers:Motion capture and immersive interface requirements drive specialized form factors.
Smartphone Manufacturers dominate procurement volume. Auto Suppliers represent the most rapidly expanding customer category as cabin monitoring mandates spread.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme incentives for semiconductor assembly and testing are attracting camera module manufacturers to Gujarat and Tamil Nadu, while China's GB standards for energy-efficient semiconductor manufacturing tighten component specifications across East Asian supply chains. The United States maintains stringent FCC Part 15 laser product regulations governing emitter power thresholds. Germany's CE marking requirements under EU RoHS and the EU AI Act shape biometric hardware certification for European market access.
United States
Facial recognition hardware redesign cycles respond to FDA privacy frameworks and EMA biometric data requirements. FCC Part 15 laser product regulations cap emitter output at 940 nm wavelengths for consumer device certification. The San Francisco Bay Area and Austin semiconductor corridors concentrate fabless algorithm developers leveraging software-defined depth processing.
China
Domestic manufacturers accelerate emitter module exports to ASEAN markets through streamlined GB 7247.1 certification pathways. MIIT and SAMR enforce GB standards for energy-efficient semiconductor manufacturing across component supply bases. The Yangtze River Delta and Pearl River Delta clusters house vertically integrated camera module assemblers serving Xiaomi and OPPO procurement mandates.
South Korea
Samsung Electronics drives volume demand for time-of-flight and lidar modules across Android flagship smartphone generations. MFDS and METI-aligned standards govern near-infrared emitter safety classifications for wearable device exports. The Seoul-Suwon corridor concentrates VCSEL emitter supply and MEMS mirror fabrication for compact lidar engines.
Germany
Automotive cabin monitoring systems create pull-through demand for time-of-flight arrays in electric vehicle interior sensing applications. CE marking under EU RoHS and the EU AI Act high-risk classification trigger mandatory conformity assessments for biometric identification hardware. Bavaria's automotive electronics cluster anchors supplier relationships with premium OEMs integrating spatial computing platforms.
Japan
Consumer electronics firms adopt 3D sensing for differentiated tablet, laptop, and wearable device features. METI and JIS standards govern optomechanical design specifications for eye-safe near-infrared emission modules. The Kanto region around Tokyo concentrates legacy telecom and defense supply chain talent for laser physics and MEMS fabrication expertise.
Global Mobile 3D Sensing Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated module assemblers and captive fabrication specialists, with fabless algorithm developers compressing capital barriers through software licensing. Three archetypes dominate: CMOS sensor fabricators with captive foundry capacity, MEMS mirror and laser driver integrators for compact engines, and platform-level hardware architects consolidating procurement authority. Competitive moves center on foundry capacity expansion for dedicated sensor production and strategic ISP licensing programs enabling algorithmic differentiation without fabrication investment.
Within the captive fabrication tier, Sony Group Corporation and Samsung Electronics Co., Ltd. exemplify scale-driven sensor chip supply dominance, while STMicroelectronics N.V. occupies a specialized position in MEMS mirror integration. Qualcomm Incorporated anchors software-defined depth processing through licensing architectures that enable fabless developers to bypass capital-intensive fabrication investments. These three entities represent distinct competitive vectors: captive CMOS fabrication, MEMS-laser integration, and algorithmic platform licensing.
| Leading Market Players |
|---|
| Lumentum Holdings Inc. |
| ams AG |
| Sony Group Corporation |
| ON Semiconductor Corporation |
| Himax Technologies |
| Samsung Electronics Co., Ltd. |
| Infineon Technologies AG |
| STMicroelectronics N.V. |
| Qualcomm Incorporated |
| Others |
Supply & Pricing Matrix
The Incheon-Shanghai-Shenzhen maritime corridor's freight rate volatility feeds directly into module assembly economics, amplifying price spreads between GB 7247.1-certified emitter suppliers and uncertified alternatives while compressing margins for fabless algorithm developers lacking captive foundry capacity.
Pricing Analysis
Certification level (CE/FCC/GB-grade) creates the primary spread between premium lidar engines and commodity time-of-flight arrays. Camera module assemblers command per-unit transactional pricing with volume scale discounts for smartphone manufacturers purchasing millions of units annually. Cost compression in mid-tier time-of-flight chips is intensifying because of gallium metal supply concentration in Chinese refining operations. Smartphone manufacturers exhibit the highest price sensitivity, while automotive cabin monitoring integrators accept premium pricing for ISO-compliant reliability.
Supply Chain Analysis
TSMC, Samsung Foundry, and SMIC hold dominant capacity for CMOS image sensor fabrication serving time-of-flight and SPAD array production. Taiwan, South Korea, and China anchor geographic supply concentration for VCSEL emitters, MEMS mirrors, and diffractive optical elements. Raw material dependencies center on indium gallium arsenide substrates, gallium metal feedstock, and specialized glass for optical elements. Single-source vulnerability clusters around Seoul-Suwon corridor MEMS mirror fabrication. Distribution runs through vertically integrated module assemblers delivering directly to platform-level hardware architects at OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobile 3D sensing is approaching a platform-economics inflection where Qualcomm Spectra ISP licensing ecosystems are displacing captive fabrication as the primary value capture mechanism.
For Market Incumbents: Entrench sensor chip supply dominance through captive foundry capacity expansion in Taiwan and South Korea. Sony Group Corporation's CMOS fabrication model demonstrates how backward integration into emitter-grade substrate sourcing neutralizes gallium price volatility. Defend against fabless algorithm developers by pre-integrating privacy-preserving depth processing at the sensor edge ahead of EU AI Act enforcement. For New Entrants and Emerging Players: Pursue automotive cabin monitoring applications where driver attention sensing mandates create pull-through demand without smartphone procurement consolidation. India's Gujarat and Tamil Nadu PLI scheme zones offer the most penetrable geography for camera module assembly entry. License ISP software stacks rather than investing in fabrication to bypass capital barriers. For Investors and Strategic Acquirers: MEMS mirror specialists with dual qualification for scanning and flash illumination specifications represent the highest-conviction acquisition archetype. Long-term viability hinges on supplier positioning within unified sensor fusion architectures rather than discrete technology silos. Watch for tier-one OEM procurement consolidation under single-source accountability mandates as the inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Expansion | Dedicated sensor fabrication lowers capital barriers for fabless developers competing in time-of-flight volume. |
| ISP Licensing Program | Qualcomm Spectra enables algorithmic differentiation without captive CMOS fabrication investments. |
| GB 7247.1 Certification Investment | China's unified pathway accelerates emitter module approval for ASEAN export markets. |
| Automotive Cabin Monitoring Partnership | Electric vehicle interior sensing creates pull-through demand outside smartphone procurement concentration. |
| Privacy-Preserving Edge Integration | EU AI Act high-risk classification mandates hardware-level depth processing ahead of host processor architectures. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with smartphone platform architects, automotive Tier 1 procurement leads, camera module assembly executives, and fabless algorithm developers; and secondary validation through SEC filings, MIIT GB standard publications, EU AI Act regulatory texts, and customs trade records. Bottom-up triangulation across sensor chip shipment data and top-down reconciliation against OEM bill-of-materials disclosures anchored volume estimates.
Forecast inputs span technology architecture, product form factor, application use case, and end-user procurement scale across the projection horizon. CAGRs derive from segment-level growth rate reconciliation against aggregate market value expansion. Modeled variables include VCSEL emitter cost trajectories, foundry capacity utilization rates, and regulatory certification timeline compression.
Sensitivities concentrate around gallium metal supply disruptions, multi-jurisdiction laser safety reclassifications, and platform-level procurement consolidation velocity. Forecasts reflect documented assumptions regarding PLI scheme incentive durability and EU AI Act enforcement timing. Quarterly review of OEM single-source accountability mandates and GB standard revision cycles is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Technology
3D Machine Vision Market
3D Technology
Europe 3D Telepresence Market
3D Technology
3D Geospatial Technologies Market
3D Technology
Molecular Modeling Market
3D Technology
Visualization and 3D Rendering Software Market
3D Technology
APAC 3D 4D Technology Market
3D Technology
3D Mobile Mapping Market
3D Technology
Global 3D Mapping and 3D Modeling Market
3D Technology
Mobile 3D Market
3D Technology
3D Scanner Market
3D Technology
Global 3D Architecture Software Market
3D Technology
3D Rendering Software Market
3D Technology
3D Technology Market
3D Technology
Latin America 3D 4D Technology Market
3D Technology
3D Simulation Software Market
3D Technology
3D Scanning Market