
 Global Consumer IAM Market | 2026-2036
Global Consumer IAM Market Size, Share, and Industry Trends Forecast 2026-2036
Global Consumer IAM Market Foresight
A shift from on-premises single-source deployments to cloud multi-source architectures is pivoting procurement patterns across the Global Consumer IAM Market. Okta leverages its cloud-native platform to anchor enterprise-to-consumer identity pipelines. Microsoft Corporation dominates consumer-facing authentication through embedded Azure AD integrations across productivity and gaming ecosystems. ForgeRock specializes in open-source identity orchestration for regulated industries requiring customizable consent workflows.
Consumer Identity and Access Management encompasses the technologies, policies, and services that verify, authenticate, and authorize individual users accessing digital services, typically incorporating OAuth 2.0, OpenID Connect, and FIDO2 protocols to bind cryptographic credentials to real-world identities. Its primary commercial purpose is to reduce fraud exposure while enabling seamless cross-channel customer journeys for subscription and transaction businesses. Multi-Factor Authentication commands the largest solution-type footprint as SIM-swapping and credential-stuffing attacks proliferate against financial services and streaming applications. Cloud-Based deployment leads the infrastructure mix, though Hybrid configurations are gaining share among banks and telco operators navigating data-residency requirements across multiple jurisdictions. The E-Commerce application segment sustains premium pricing for real-time behavioral biometrics and step-up authentication at checkout.
The EU AI Act and GDPR jointly constrain automated identity-verification systems deployed across European digital services, requiring human-in-the-loop safeguards for high-risk biometric classifications. In the United States, the SEC's cybersecurity disclosure rules and state-level breach-notification laws are accelerating board-level investment in consumer identity resilience. China's NMPA and MIIT enforce facial-recognition consent protocols for consumer apps, fragmenting authentication standardization across APAC deployment strategies. Stakeholders must monitor regulatory divergence between privacy-centric European frameworks and security-first American enforcement postures when architecting multi-region identity stacks.
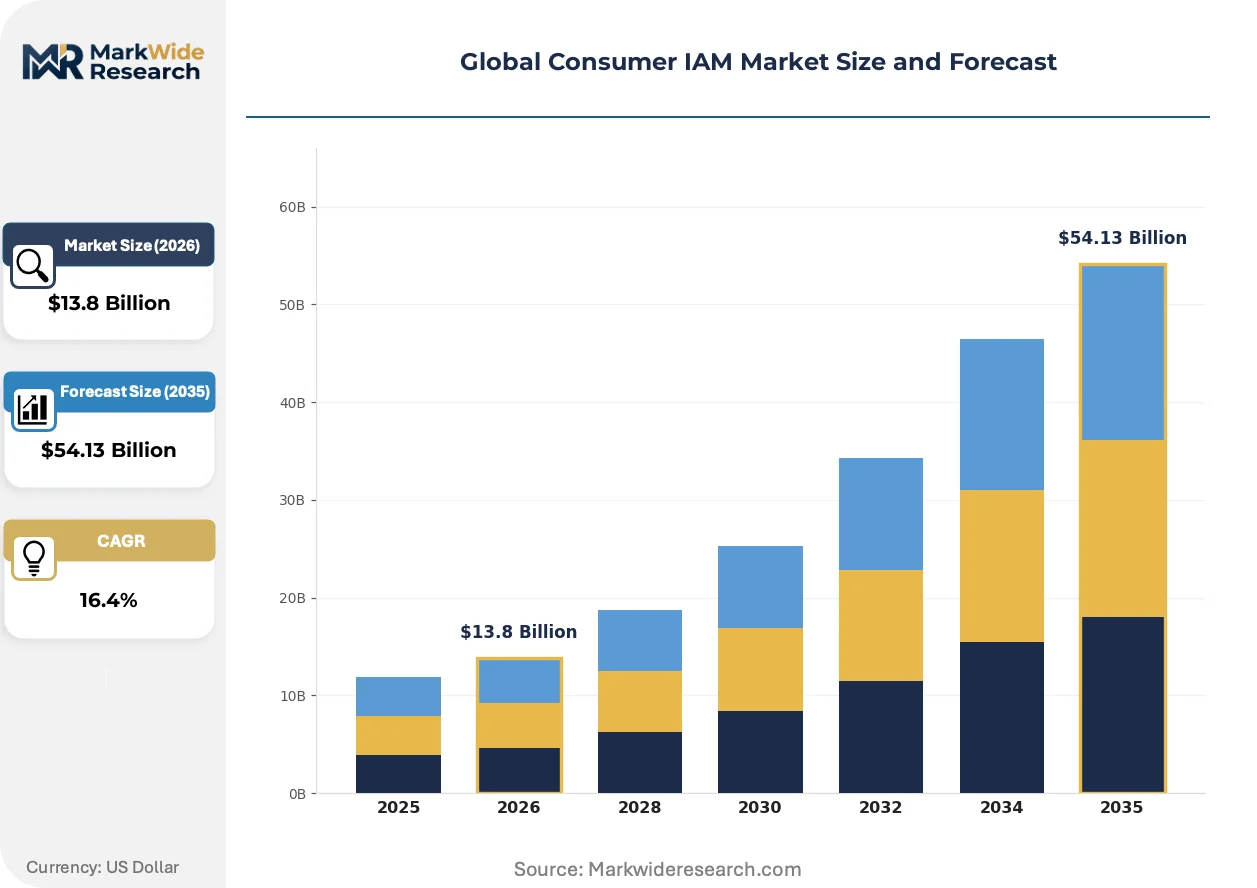
Market Dynamics
Cloud-native multi-source identity architectures are displacing on-premises single-source deployments, forcing vendors to reconfigure authentication pipelines around OAuth 2.0 and FIDO2 protocols while financial services and streaming platforms consolidate procurement at enterprise scale.
Growth Catalysts
- FIDO2 protocol maturation:Cryptographic credential binding now replaces SMS-based verification across US banking apps, eliminating SIM-swapping attack vectors. Financial institutions are mandating hardware-backed authentication for high-value transactions.
- GDPR-EU AI Act convergence:European digital services must automate consent workflows with human-in-the-loop safeguards for biometric classifications, creating procurement urgency for orchestration platforms.
- Streaming platform subscriber protection:Credential-stuffing attacks against US entertainment services are driving multi-factor authentication procurement at scale, with behavioral biometrics deployed at checkout.
Market Restraints
- Data-residency compliance costs:Hybrid deployment configurations are gaining share among banks navigating jurisdictional fragmentation, inflating infrastructure overhead for multi-region operators.
- Facial-recognition standardization gaps:China's NMPA and MIIT enforce consent protocols that diverge from European and American frameworks, complicating authentication stack architecture.
- Biometric storage liability exposure:Irreversible credential compromise from centralized biometric databases creates catastrophic breach risk that cyber insurance carriers are repricing aggressively.
Strategic Opportunities
- India's digital public infrastructure:The country's national identity stack and RBI payment regulations are creating demand for localized consumer IAM integration with Aadhaar-linked verification.
- Behavioral biometrics convergence:Real-time keystroke dynamics and device fingerprinting are merging with step-up authentication to reduce friction in e-commerce checkout flows.
- Embedded finance identity pipelines:Non-financial platforms in the United States are white-labeling bank-grade verification for buy-now-pay-later and marketplace transactions.
Industry Challenges
- Legacy system API fragmentation:Mainframe identity stores at incumbent banks resist real-time synchronization with cloud-native authentication layers, forcing expensive middleware development.
- Consent workflow engineering scarcity:Few development teams possess combined expertise in cryptographic protocols and regulatory interpretation across GDPR, SEC disclosure rules, and state breach laws.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Consumer IAM Market |
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $54.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Single Sign-On, Multi-Factor Authentication, Identity Governance, Access Management, Privileged Account Management Deployment Model: Cloud-Based, On-Premises, Hybrid, Private Cloud, Hosted Application: E-Commerce, Digital Media, Financial Services, Telecommunications, Education Platforms End User: Online Retailers, Streaming Services, Banks, Telco Operators, Educational Institutions |
| Companies Covered | Okta, Akamai Technologies, IBM Corporation, LoginRadius, ForgeRock, Microsoft Corporation, Ping Identity, Broadcom, Salesforce, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Consumer IAM Market Shifts & Advancements
Passwordless authentication is compressing deployment timelines while regulatory fragmentation forces architectural flexibility. Vendors are racing to embed identity verification into transaction flows without adding friction.
Decentralized identity wallets built on verifiable credentials are expanding into European digital service deployments. German automotive manufacturers and Dutch banking consortia are piloting self-sovereign authentication for customer data portability. This architecture is expanding into regulatory compliance by eliminating centralized honeypots of personal information.
The EU AI Act's high-risk system classification is mandating human review for automated biometric verification across French and German digital services. E-commerce platforms must maintain audit trails for algorithmic identity decisions or face operational suspension. Retail banking applications in Italy and Spain are responding by deploying hybrid human-machine verification queues.
Subscription businesses are unbundling identity protection from core service pricing, creating standalone authentication tiers. US streaming platforms and fintech applications are testing usage-based verification fees for premium account security. This model is most visible in California and New York, where breach-notification laws have sensitized consumers to credential protection value.
Global Consumer IAM Market Segmentation
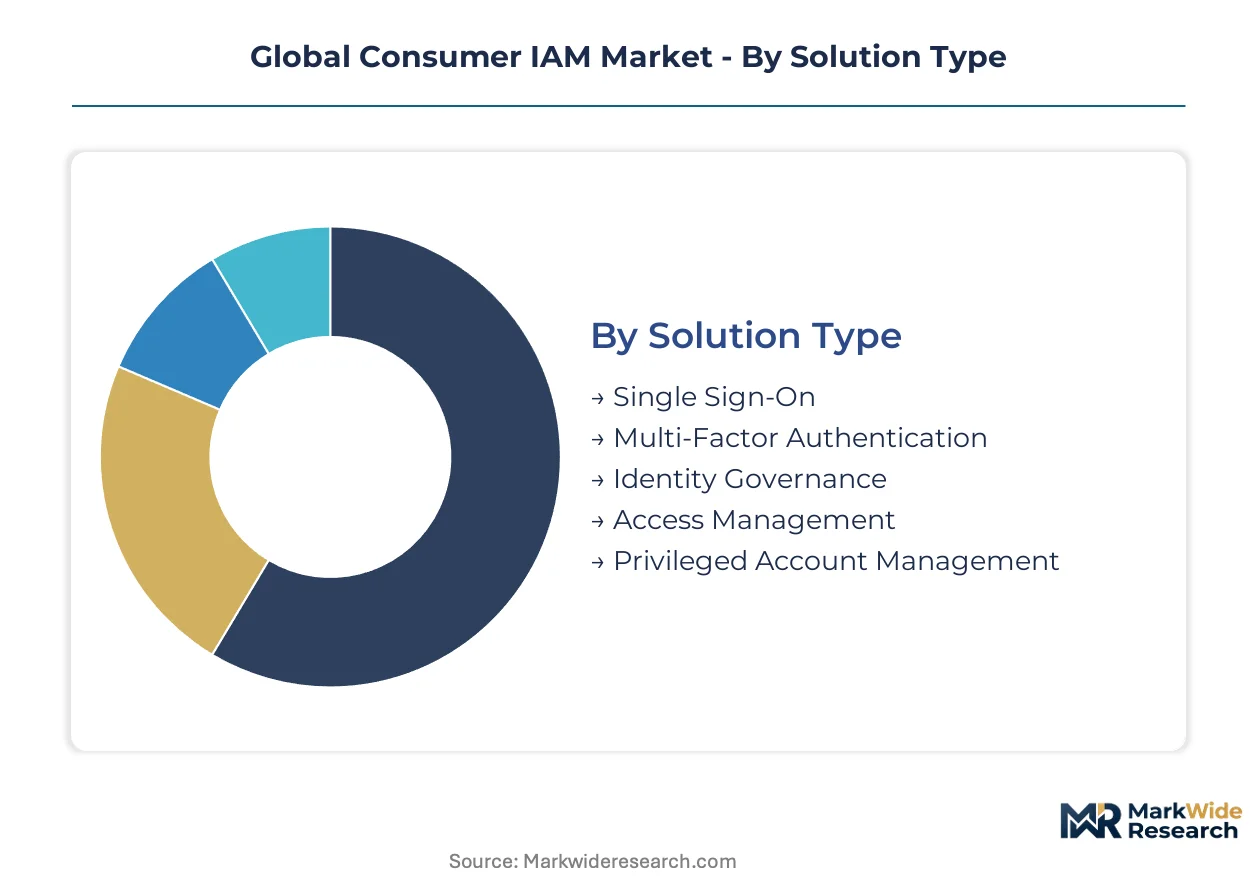
Consumer IAM procurement patterns diverge sharply across solution architectures, deployment topologies, and sector-specific compliance burdens. Financial institutions and streaming platforms drive divergent specification requirements, forcing vendors to maintain parallel product roadmaps. Segmentation clarity enables precise matching of authentication intensity to transaction risk profiles.
Solution Type:
GDPR and EU AI Act compliance obligations concentrate most heavily on biometric-enabled segments, with FIDO2 certification becoming mandatory for high-assurance financial deployments.
- Multi-Factor Authentication:Combines possession-based tokens with inherence factors like fingerprint or facial recognition to bind cryptographic credentials to verified identities. US banking applications and streaming platforms in California and New York are mandating hardware-backed FIDO2 keys for account recovery, eliminating SMS-based verification vulnerable to SIM-swapping attacks.
- Identity Governance:Orchestrates consent workflows, access certifications, and policy enforcement across distributed identity stores. European digital services subject to GDPR-EU AI Act convergence require human-in-the-loop safeguards for automated biometric classifications, driving procurement of customizable governance platforms.
- Single Sign-On:Federates authentication across service portfolios using OAuth 2.0 and OpenID Connect protocols.
- Access Management:Enforces real-time authorization decisions at API gateways and application perimeters.
- Privileged Account Management:Secures high-risk administrative credentials with session recording and just-in-time elevation.
Multi-Factor Authentication sits at the top of the volume ranking, with Identity Governance climbing the fastest.
Deployment Model:
Cost tiering separates hyperscaler-native deployments from infrastructure requiring dedicated compliance engineering for data-residency mandates.
- Cloud-Based:Delivers identity services through multi-tenant SaaS architectures with elastic scaling and continuous feature deployment. US fintech startups and streaming platforms in Los Angeles and Seattle are consolidating procurement at enterprise scale, leveraging pre-integrated OAuth 2.0 and FIDO2 protocol stacks.
- Hybrid:Distributes authentication logic across cloud-native layers and on-premises identity stores to satisfy jurisdictional data-residency requirements. German and French banks navigating GDPR territoriality rules are deploying split architectures with sensitive biometric templates retained in-country.
- On-Premises:Maintains complete identity infrastructure within controlled data centers.
- Private Cloud:Delivers dedicated tenant isolation on managed infrastructure.
- Hosted:Provides managed service delivery without multi-tenant resource sharing.
Cloud-Based deployments command the largest installed base, though Hybrid configurations are expanding most quickly among regulated operators.
Application:
Application-specific risk profiles determine authentication intensity, with payment-adjacent segments requiring step-up verification at transaction points.
- Financial Services:Demands bank-grade identity verification for account origination, transaction authorization, and fraud prevention. US institutions responding to SEC cybersecurity disclosure rules are accelerating investment in real-time behavioral biometrics for wire transfer authentication.
- E-Commerce:Deploys friction-reducing authentication at checkout to minimize cart abandonment. European merchants are integrating GDPR-compliant consent automation with one-click payment flows, particularly in German and Dutch marketplaces.
- Digital Media:Protects subscriber credentials against credential-stuffing attacks.
- Telecommunications:Secures customer portals and device provisioning systems.
- Education Platforms:Verifies student identity for credential issuance and examination integrity.
Financial Services leads segment revenue, while E-Commerce is gaining share fastest through embedded finance integration.
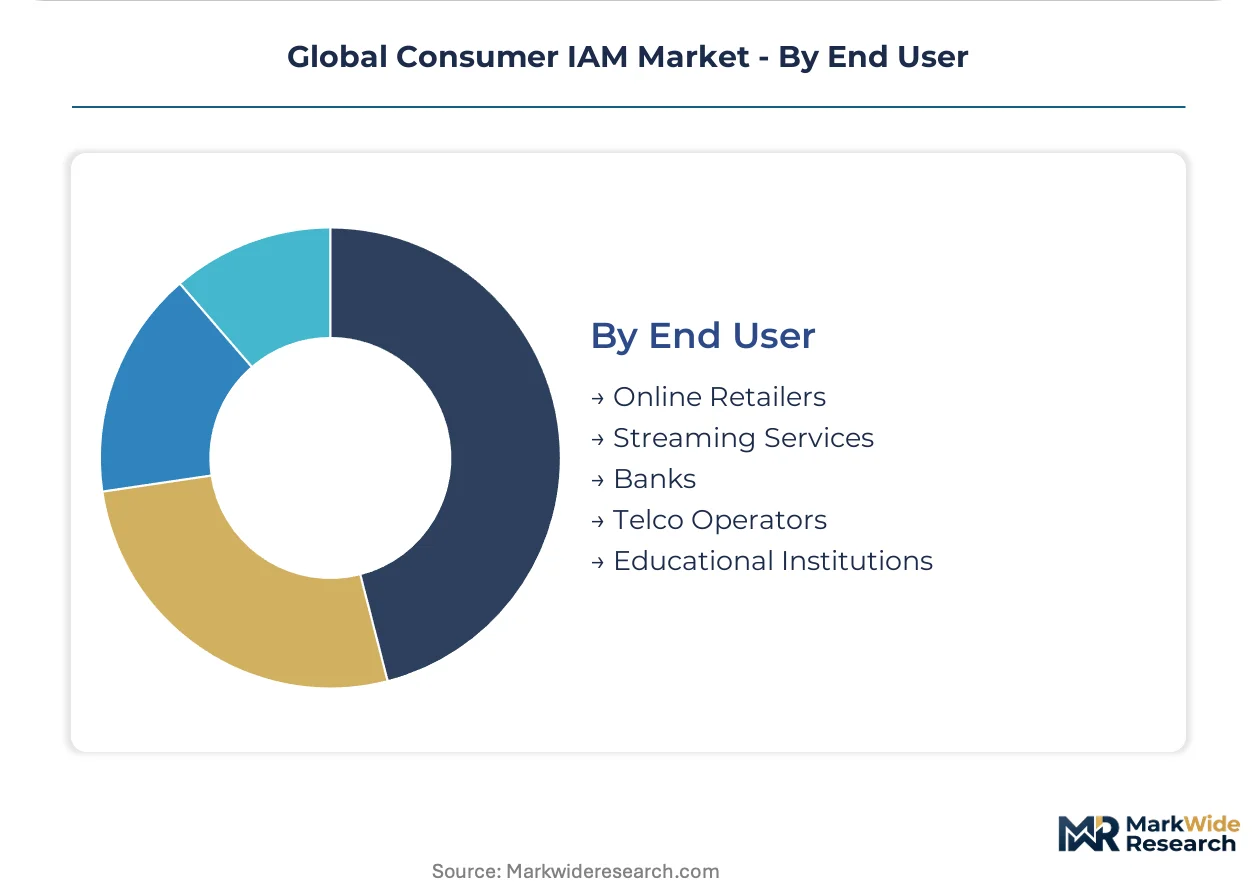
End User:
End-user scale and breach exposure determine procurement sophistication, with consumer-facing platforms prioritizing seamless recovery workflows.
- Banks:Require comprehensive identity stacks spanning onboarding, authentication, and fraud detection. Institutions in Italy and Spain are deploying hybrid human-machine verification queues to satisfy EU AI Act high-risk system classifications for biometric verification.
- Streaming Services:Balance account sharing controls against subscriber friction. US entertainment platforms are testing usage-based verification fees for premium security tiers in California and New York, where breach-notification laws have sensitized consumers to credential protection value.
- Online Retailers:Prioritize checkout conversion with risk-based step-up triggers.
- Telco Operators:Secure customer data against SIM-swapping and account takeover.
- Educational Institutions:Verify learner identity for remote examination and credential issuance.
Banks anchor the highest authentication spending per user, with Streaming Services showing the steepest expansion trajectory in multi-factor authentication deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between privacy-centric European frameworks and security-first American enforcement is creating compliance-cost arbitrage, with vendors relocating orchestration engineering to jurisdictions where biometric consent requirements impose lighter architectural burdens.
United States
SEC cybersecurity disclosure rules and state-level breach-notification laws in California and New York are accelerating board-level investment in consumer identity resilience. Financial institutions in Manhattan and Los Angeles are mandating hardware-backed FIDO2 authentication for wire transfers. Streaming platforms in Seattle are testing usage-based verification fees for premium security tiers.
Germany
GDPR territoriality rules and EU AI Act high-risk system classifications are forcing banks to deploy split architectures with biometric templates retained in-country. German automotive manufacturers in Bavaria are piloting self-sovereign identity wallets for customer data portability. Frankfurt-based financial institutions are deploying hybrid human-machine verification queues.
China
NMPA and MIIT facial-recognition consent protocols are fragmenting authentication standardization across APAC deployment strategies. Consumer app developers in Beijing and Shenzhen must implement localized verification flows that diverge from European and American frameworks. Shanghai-based fintech platforms are navigating strict data-residency mandates for biometric storage.
India
RBI payment regulations and the national Aadhaar identity stack are creating demand for localized consumer IAM integration. Mumbai and Bangalore fintech startups are building Aadhaar-linked verification pipelines for account origination. Hyderabad-based IT services firms are exporting identity orchestration expertise to Middle Eastern markets.
United Kingdom
Post-Brexit divergence from EU AI Act enforcement is creating regulatory uncertainty for biometric verification deployments. London financial services firms are maintaining GDPR-aligned consent workflows while monitoring divergence from European standards. Edinburgh-based banking consortia are investing in cloud-native authentication layers for cross-border transaction authorization.
Global Consumer IAM Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue embedded finance and decentralized identity adjacencies. The vendor base clusters around three maturity tiers: hyperscaler-integrated platforms, open-source orchestration specialists, and vertical-specific authentication providers. Strategic archetypes include cloud-native pipeline builders, consent-automation engineers, and behavioral biometric integrators. Competitive moves concentrate on OAuth 2.0 protocol standardization and FIDO2 certification racing.
Within the cloud-native tier, Okta and Microsoft Corporation anchor enterprise-to-consumer identity pipelines through multi-tenant SaaS architectures. ForgeRock exemplifies the open-source orchestration archetype, occupying a position among vendors serving regulated industries requiring customizable consent workflows. These three entities represent distinct competitive vectors: hyperscaler ecosystem embedding, platform-native scalability, and regulatory-specialist configuration.
| Leading Market Players |
|---|
| Okta |
| Akamai Technologies |
| IBM Corporation |
| LoginRadius |
| ForgeRock |
| Microsoft Corporation |
| Ping Identity |
| Broadcom |
| Salesforce |
| Others |
Supply & Pricing Matrix
Identity orchestration engineering talent clusters in Bangalore and Hyderabad, with labor-cost differentials between Indian development centers and European implementation teams widening pricing-tier spreads across cloud-native and hybrid deployment categories.
Pricing Analysis
Distributor margins for FIDO2 hardware security keys compress pricing by 15-25 points before reaching financial services end-users. Pricing stratifies across premium FIDO2-certified, standard OAuth-integrated, and economy SMS-based authentication tiers, with certification grade and volume scale as primary differentiation drivers. Cost compression in the economy tier is intensifying because telecom operators are deprecating SMS-based verification. Fintech startups show highest price sensitivity; regulated banks prioritize certification over cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based semiconductor fabrication for FIDO2 secure element chips. Hardware authentication module production draws from Taiwan, China, and South Korea, with cryptographic processor supply anchored in Taiwanese foundries. Supply chain risk centers on tariff exposure affecting cross-border hardware shipments. Distribution runs through hyperscaler marketplaces and direct enterprise licensing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
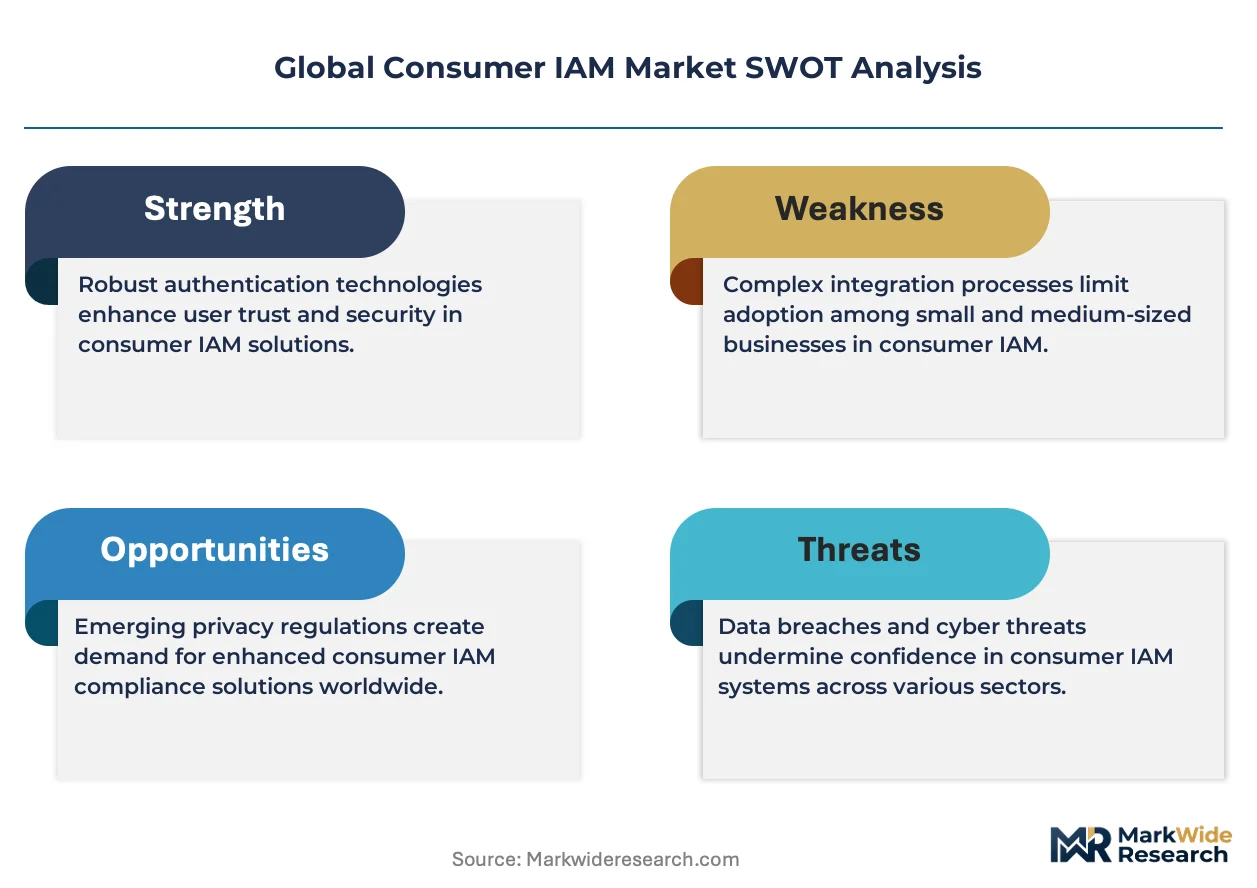
This market functions as a stable compounder, with regulatory mandate expansion across GDPR-EU AI Act convergence driving steady procurement growth regardless of macroeconomic cycles.
For Market Incumbents: Lock in FIDO2 certification racing to preempt emerging cloud-native challengers. Expand vertical integration into behavioral biometrics R&D to defend against specialized fraud-detection entrants. Deepen channel control through hyperscaler marketplace exclusivity arrangements.
For New Entrants and Emerging Players: The mid-market price-point gap between premium FIDO2 deployments and economy SMS alternatives offers white-space entry. Target India's Aadhaar-linked verification segment as the most penetrable geography. Pursue embedded finance identity pipelines as the primary go-to-market angle.
For Investors and Strategic Acquirers: Cloud hyperscalers represent the most active acquirer category in this space, seeking identity orchestration capabilities for platform stickiness. Long-term viability rests on consolidation of consent-automation engineering talent. Monitor EU AI Act enforcement intensity as the key inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FIDO2 Certification Acquisition | Banking regulators in Germany and France now mandate hardware-backed authentication for wire transfers. |
| Consent-Automation Platform Integration | GDPR-EU AI Act convergence requires human-in-the-loop safeguards for biometric verification workflows. |
| Behavioral Biometrics Partnership | E-commerce platforms in California deploy keystroke dynamics to reduce checkout friction. |
| Aadhaar-Linked Verification Pipeline | RBI payment regulations drive localized identity orchestration for Indian fintech account origination. |
| Self-Sovereign Identity Wallet Development | German automotive manufacturers pilot verifiable credentials for customer data portability compliance. |
Research Methodology
Multiple input streams — primary interviews, regulatory filing analysis, and hyperscaler capex disclosures — were reconciled to construct segment-level estimates. Chief information security officers, identity platform engineers, and financial services compliance leads provided operational validation. Secondary sources included SEC cybersecurity disclosure filings, EU AI Act implementation guidance, and RBI payment regulation circulars. Bottom-up deployment counts and top-down vendor revenue triangulation anchored value estimates.
Data-stream reconciliation across deployment models, solution architectures, and end-user verticals structured the analytical framework. Segmentation dimensions modeled encompass cloud-native versus hybrid infrastructure, FIDO2 versus legacy protocol adoption, and financial services versus streaming platform demand patterns. CAGRs were derived from protocol migration curves and regulatory mandate timelines. Behavioral biometrics integration rates and consent-automation procurement velocity served as industry-specific forecast inputs.
Caveats apply where EU AI Act enforcement divergence or NMPA facial-recognition protocol shifts could materially shift the outlook. Forecasts reflect assumptions about FIDO2 protocol maturation and cross-border data-residency negotiation outcomes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Endpoint Detection and Response [EDR] Market
Security Software
Private Virtual Communications for Police Network Market
Security Software
Asia-Pacific Encryption Software Market
Security Software
Global Cloud IAM Market
Security Software
Public Key Infrastructure (PKI) Market
Security Software
Global Data Privacy Management Software Tools Market
Security Software
Global Consumer Identity and Access Management Market
Security Software
AD-Blocking Software Market
Security Software
Anti-Fraud Management System Market
Security Software
Endpoint Detection and Response Market
Security Software
United States Lawful Interception Market
Security Software
Cloud Intrusion Protection Software Market
Security Software
Japan Mobile Biometrics Market
Security Software
Phone Antivirus Software Market
Security Software
Asia Pacific Video Management System Market
Security Software
Global Anti-Spam Software Market