
 Digital Holography Market | 2026-2036
Digital Holography Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Holography Market Intelligence
Platform licensing revenue is narrowing as hardware vendors bundle software tools directly with digital holographic microscopy systems. Leia Inc. leverages its light-field display architecture to dominate automotive and consumer electronics channels. Phase Holographic Imaging anchors its position through continuous R&D intensity in live-cell imaging applications. Holoxica Limited specializes in scientific visualization systems for research laboratories across Europe.
Digital holography captures and reconstructs three-dimensional optical wavefronts using interferometric recording and numerical processing, typically achieving sub-micron depth resolution across fields of view from millimeters to centimeters. The technique enables non-contact, full-field measurement of surface topography, transparent specimen morphology, and dynamic biological processes without physical sectioning or staining. Biomedical imaging applications command the largest revenue pool, while material testing segments exhibit the fastest growth as aerospace and semiconductor manufacturers adopt in-line holographic inspection. Digital holographic microscopes concentrate margin pools at the premium instrument tier, whereas wavefront sensors compete primarily on price-performance in industrial automation settings.
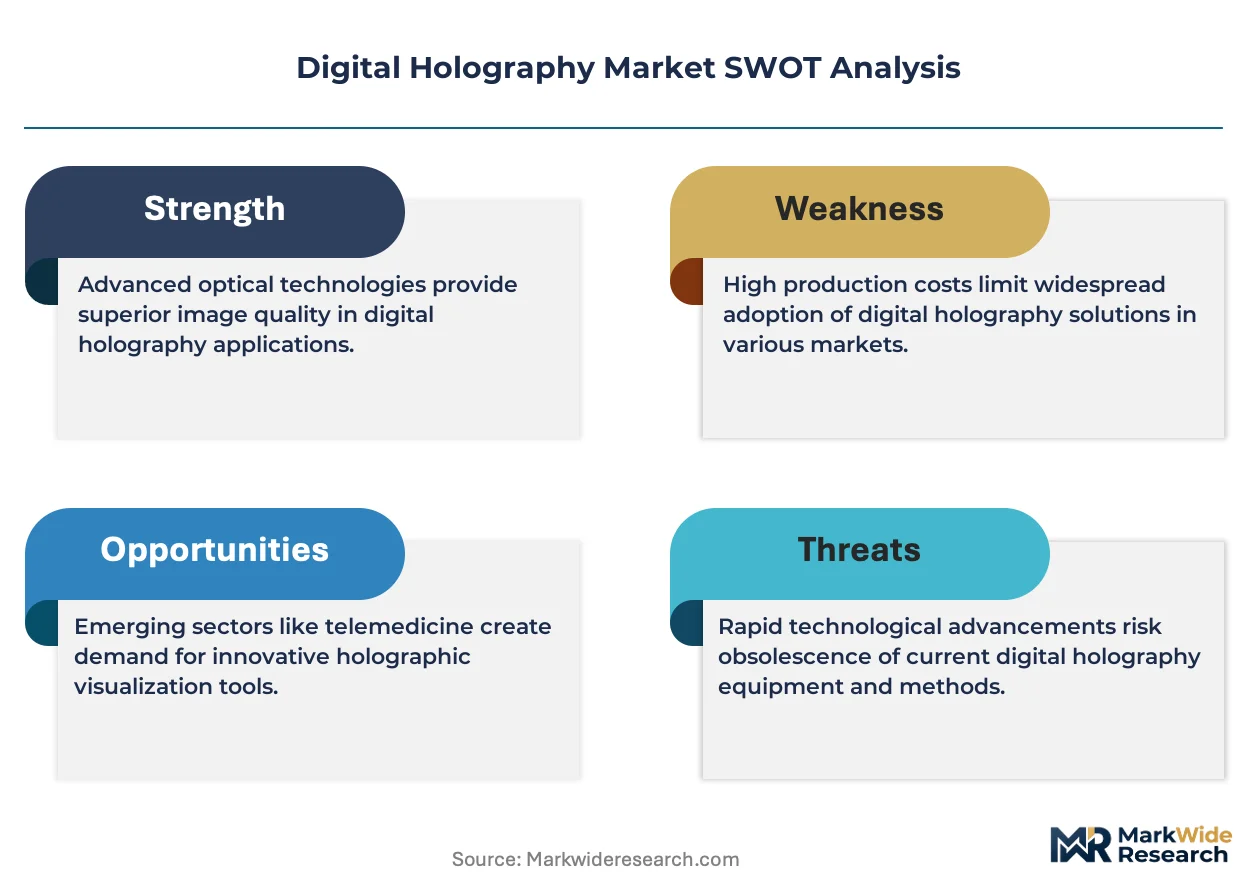
The FDA regulates holographic medical devices under 510(k) and De Novo pathways, while the EU Medical Device Regulation (MDR) mandates clinical performance documentation for holographic surgical planning tools. ISO 10993 biocompatibility standards and IEC 60601 electrical safety requirements shape product development roadmaps for healthcare-facing holography vendors. Stakeholders must monitor evolving reimbursement codes for holography-assisted surgical procedures as a determinant of hospital procurement velocity.
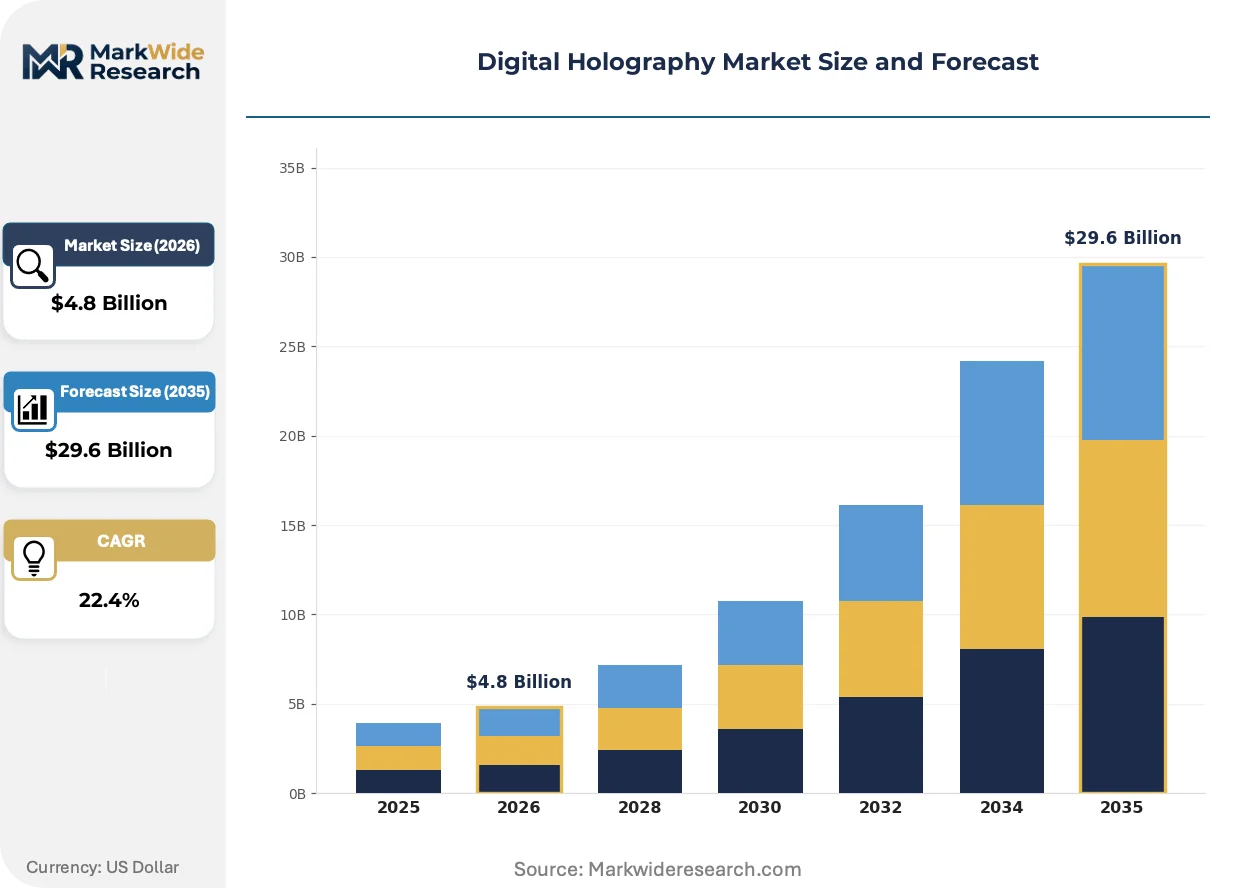
Market Dynamics
FDA 510(k) clearance acceleration for holographic surgical planning tools is compressing commercialization timelines and forcing incumbent imaging vendors to reconfigure R&D roadmaps around interferometric wavefront capture systems.
Growth Catalysts
- Biomedical imaging demand:Academic medical centers in the United States are expanding holographic visualization procurement for pathology review and preoperative surgical planning, driven by Medicare reimbursement momentum for precision-guided procedures.
- REACH compliance tailwinds:EU manufacturers replacing destructive material testing with non-contact holographic inspection to satisfy RoHS substance restrictions and reduce chemical waste disposal liabilities.
- Semiconductor inline inspection:Taiwan and South Korea foundries are deploying sub-micron holographic metrology for wafer-level defect detection, displacing slower stylus profilometry in advanced node production.
Market Restraints
- Laser source cost volatility:Coherent light generation components account for disproportionate hardware BOM exposure, with solid-state laser diode supply concentrating among Japanese and German component specialists.
- Computational throughput barriers:Real-time wavefront reconstruction demands GPU clusters that exceed capital budgets of mid-tier research institutions, limiting addressable market penetration.
- MDR clinical documentation burdens:EU Medical Device Regulation mandates for holographic surgical planning tools extend regulatory approval cycles and inflate quality management system costs for smaller vendors.
Strategic Opportunities
- India diagnostic imaging gap:Tier-2 and Tier-3 hospital networks lack pathology infrastructure that holographic remote consultation systems could address, pending CDSCO device registration pathway clarity.
- Automotive HUD convergence:Light-field display architectures are merging with augmented reality windshields, creating aftermarket upgrade demand among German and Japanese premium vehicle segments.
- PLI scheme alignment:India's production-linked incentive framework for electronics manufacturing offers cost offsets for domestic holographic component assembly, attracting contract manufacturers from optical subsystem suppliers.
Industry Challenges
- Interferometry specialist scarcity:Wavefront physics and numerical reconstruction algorithm development require PhD-level talent pools concentrated at select German and Swiss research institutes, constraining vendor scaling velocity.
- Legacy PACS integration friction:Hospital IT departments face middleware complexity when connecting holographic imaging workstations to existing DICOM archive infrastructure, extending sales cycles and implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Holography Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $29.6 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interferometers, Digital Holographic Microscopes, Wavefront Sensors, Optical Coherency Tomography Application: Biomedical Imaging, Material Testing, Optical Measurement, Data Storage End User: Healthcare Institutions, Research Laboratories, Manufacturing Companies, Defense Agencies Technology: Active Optics, Phase-Shifting Interferometry, Fourier Transform Holography, Digital In-line Holography |
| Companies Covered | Lyncee Tec, RealView Imaging, EON Reality, Holoxica Limited, Geola Digital, Leia Inc., Phase Holographic Imaging, Holotech Switzerland, Ovizio Imaging Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Holography Market Strategic Shifts & Innovations
Computational holography is collapsing the traditional separation between image capture and display hardware, enabling software-defined optical systems that reconfigure function through algorithmic updates rather than physical component swaps.
Deep learning-based phase retrieval algorithms are collapsing reconstruction latency from minutes to milliseconds, allowing semiconductor fabs in Taiwan and South Korea to deploy holographic inspection at full production line speeds. Memory manufacturers now specify neural-network-accelerated wavefront processing as a procurement requirement, compressing competitive differentiation around inference throughput rather than optical hardware specifications alone.
EU MDR Article 10 clinical performance documentation requirements are forcing holographic surgical device vendors to sponsor prospective validation studies, shifting competitive advantage toward firms with established hospital research partnerships. German notified bodies have published guidance interpreting holographic navigation as Class IIa or IIb depending on tissue penetration depth, creating regulatory segmentation that favors established imaging conglomerates with quality management infrastructure.
Academic medical center procurement committees are consolidating vendor relationships around integrated visualization platforms, displacing standalone holographic microscope specialists who lack enterprise IT support contracts. United States health system GPOs now bundle holographic pathology review licenses with existing digital slide scanner agreements, compressing margins for pure-play hardware vendors and favoring software-anchored pricing models.
Digital Holography Market Segmentation
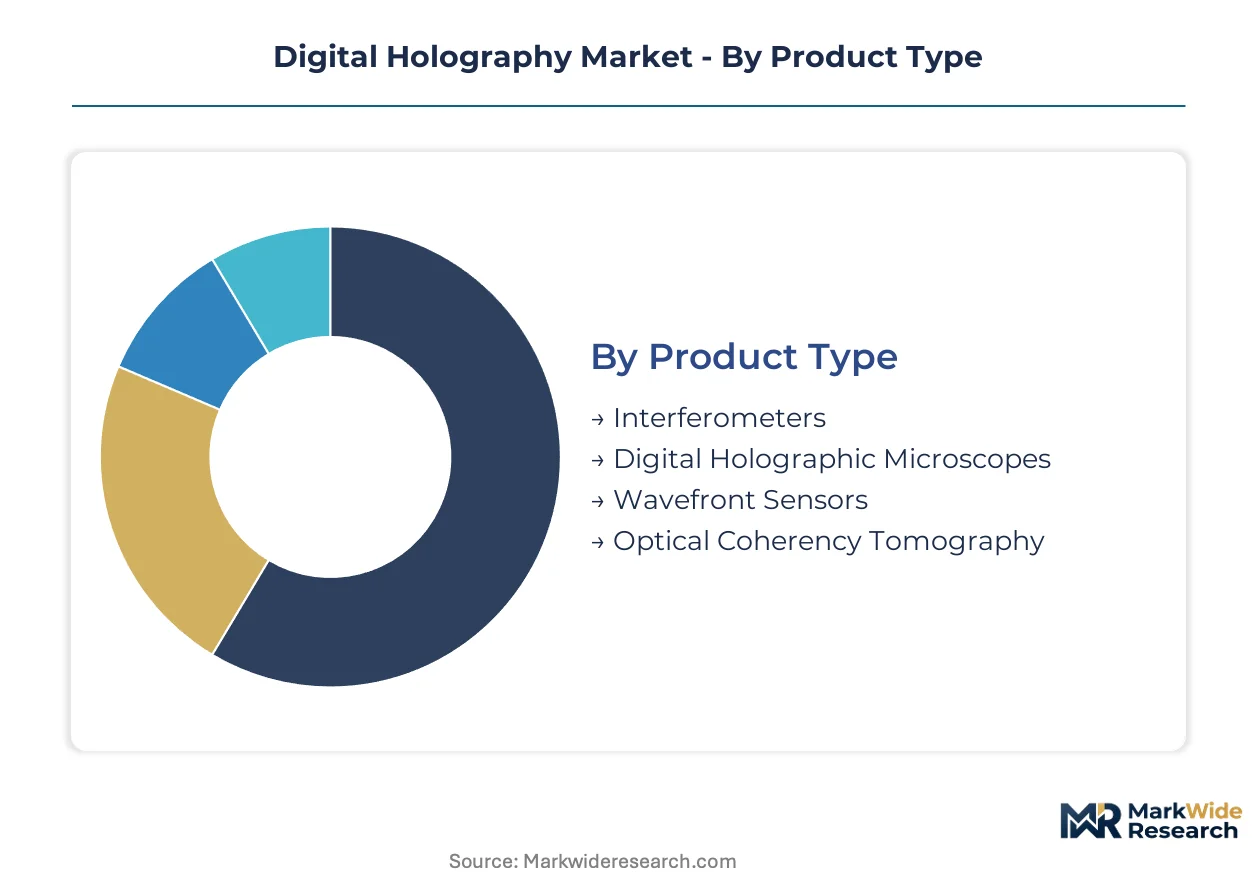
Digital holography vendors configure product portfolios across four intersecting dimensions that determine pricing architecture and sales cycle complexity. Technology selection drives hardware BOM structure, while end-user procurement patterns separate capital-intensive instrument sales from recurring software licensing arrangements.
Product Type:
Mature interferometric platforms anchor installed base maintenance revenue, while emerging wavefront sensor architectures penetrate industrial automation at price points unreachable by laboratory-grade systems.
- Interferometers:These systems measure optical path differences through reference beam interference, achieving nanometer-scale surface topography resolution. Semiconductor fabs in Taiwan and South Korea specify phase-shifting variants for wafer flatness verification, though laser source cost volatility constrains mid-tier manufacturer adoption.
- Digital Holographic Microscopes:Full-field imaging instruments capture live-cell dynamics without fluorescent staining or physical sectioning. Academic medical centers in the United States concentrate procurement for pathology review workflows, driven by Medicare reimbursement momentum for precision-guided diagnostic procedures.
- Wavefront Sensors:Compact devices quantify aberrations in real time for adaptive optics systems. Defense research facilities represent concentrated demand.
- Optical Coherency Tomography:Cross-sectional imaging modality using low-coherence interferometry for tissue morphology assessment. Ophthalmology clinics drive clinical adoption.
Interferometers retain volume leadership; wavefront sensors hold the steepest expansion curve.
Application:
Cost tier separation distinguishes premium biomedical installations from price-sensitive material testing deployments that compete against legacy stylus profilometry.
- Biomedical Imaging:Non-contact visualization of transparent specimens and tissue structures enables surgical planning and pathology review. Hospital procurement committees in Germany and Switzerland prioritize systems with FDA 510(k) or EU MDR clearance, compressing vendor selection to established imaging conglomerates with quality management infrastructure.
- Material Testing:Surface roughness and defect characterization for aerospace components and electronic substrates. REACH compliance tailwinds in the European Union accelerate displacement of destructive testing methods, as manufacturers seek RoHS-aligned inspection workflows that eliminate chemical waste disposal liabilities.
- Optical Measurement:Precision metrology for lens manufacturing and optical assembly alignment. Photonics component suppliers concentrate demand.
- Data Storage:Holographic recording for high-density archival applications. Research-stage commercialization limits near-term revenue contribution.
Biomedical imaging commands premium pricing; material testing exhibits the most rapid volume scaling.
End User:
Customer type segmentation separates enterprise IT integration requirements from standalone laboratory procurement patterns.
- Healthcare Institutions:Hospitals and diagnostic clinics deploy holographic visualization for surgical navigation and pathology review. United States health system GPOs bundle software licenses with existing digital slide scanner agreements, compressing margins for pure-play hardware vendors.
- Research Laboratories:Academic and government facilities drive technology validation and algorithm development. German and Swiss institutes concentrate interferometry specialist talent pools.
- Manufacturing Companies:Inline inspection deployment for quality control automation. Taiwan and South Korea foundries specify sub-micron resolution for advanced node semiconductor production.
- Defense Agencies:Adaptive optics and target identification systems. Procurement cycles extend due to classified program requirements.
Healthcare institutions dominate absolute spending; manufacturing companies expand procurement most aggressively.
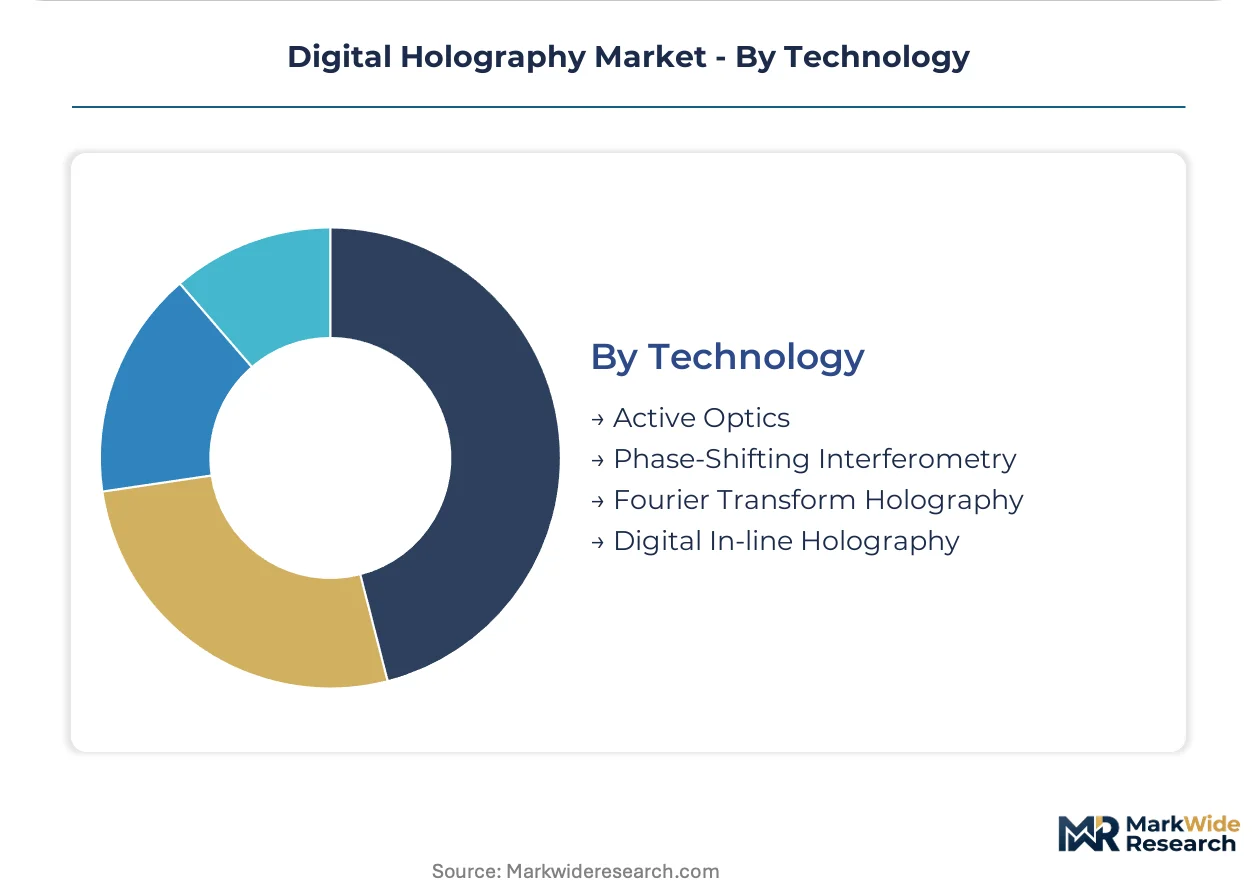
Technology:
Margin structure separates software-defined computational architectures from hardware-intensive active optics platforms requiring precision mechanical actuators.
- Active Optics:Real-time wavefront correction through deformable mirrors and tip-tilt stages. Astronomical observatories and laser weapon systems concentrate demand.
- Phase-Shifting Interferometry:Multiple frame capture with controlled phase increments enables high-precision surface measurement. Precision optics manufacturers in Japan and Germany anchor commercial deployment.
- Fourier Transform Holography:Frequency-domain reconstruction algorithms reduce computational throughput requirements. Deep learning acceleration is collapsing latency from minutes to milliseconds.
- Digital In-line Holography:Single-beam geometry simplifies optical configuration for portable and field-deployable systems. Environmental monitoring and particle characterization applications drive adoption.
Phase-shifting interferometry maintains installed base dominance; Fourier transform holography gains share fastest through neural network acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for digital holography diverge sharply across geographies: United States hospitals prioritize surgical planning visualization, while East Asian foundries drive inline metrology adoption and European manufacturers emphasize REACH-compliant material inspection workflows.
United States
Academic medical centers in Massachusetts and California anchor holographic pathology procurement, with Medicare reimbursement codes for precision-guided procedures accelerating hospital IT integration. FDA 510(k) clearance pathways compress commercialization timelines for surgical navigation devices. Boston's Longwood Medical Area concentrates vendor research partnerships.
Germany
Precision optics manufacturers in Jena and Oberkochen deploy phase-shifting interferometry for lens surface verification, displacing legacy stylus methods. EU MDR Article 10 clinical documentation requirements extend regulatory cycles for holographic surgical tools. Munich's medical technology cluster hosts notified body expertise for Class IIa/IIb device classification.
South Korea
Semiconductor foundries in Hwaseong and Pyeongtaek specify sub-micron holographic wafer inspection for advanced node production. MFDS medical device registration creates parallel pathways for clinical holography vendors. Seoul's Gangnam district concentrates display technology R&D for automotive HUD applications.
Japan
Solid-state laser diode suppliers in Hamamatsu and Yokohama concentrate critical holographic illumination component production. METI funding for optical manufacturing competitiveness supports domestic wavefront sensor development. Tokyo's Odaiba district hosts defense research facilities driving adaptive optics procurement.
India
Tier-2 hospital networks in Gujarat and Tamil Nadu lack pathology infrastructure addressable through holographic remote consultation systems. CDSCO device registration pathway clarity remains pending for commercial deployment. Bengaluru's electronics manufacturing cluster attracts PLI scheme-aligned optical component assembly.
Digital Holography Market Key Industry Players
Capability concentration sits with specialized interferometry developers; scale advantage sits with diversified imaging conglomerates. The vendor base stratifies across three tiers: premium instrument specialists commanding maintenance revenue, mid-tier wavefront sensor suppliers competing on price-performance, and software-defined computational platforms eroding hardware margins. Strategic moves center on hospital GPO bundling agreements and neural network acceleration partnerships.
Within the light-field display architecture tier, Leia Inc. and Holoxica Limited exemplify divergent specialization vectors—automotive HUD convergence versus scientific visualization systems. Phase Holographic Imaging occupies a position in the live-cell imaging segment. These three entities represent distinct competitive archetypes: consumer electronics channel dominance, European research laboratory anchoring, and biomedical R&D intensity respectively.
| Leading Market Players |
|---|
| Lyncee Tec |
| RealView Imaging |
| EON Reality |
| Holoxica Limited |
| Geola Digital |
| Leia Inc. |
| Phase Holographic Imaging |
| Holotech Switzerland |
| Ovizio Imaging Systems |
| Others |
Cost & Logistics Intelligence
Laser source cost volatility in Japanese and German solid-state diode supply chains compresses margin spreads between premium interferometric platforms and mid-tier wavefront sensors, forcing hardware vendors to bundle software licenses as a pricing anchor while concentrating procurement leverage among foundry-scale buyers in Taiwan and South Korea.
Pricing Analysis
Long-term offtake agreements dominate semiconductor metrology procurement, with Taiwan and South Korea foundries locking multi-year holographic inspection system contracts that displace spot-market purchasing. Price differentiation rests on resolution certification tiers and GPU-accelerated reconstruction throughput. Cost compression in mid-tier research instrumentation intensifies as GPU cluster requirements exceed capital budgets, while hospital GPOs in the United States exhibit lowest price sensitivity due to Medicare reimbursement buffers for precision-guided surgical procedures.
Supply Chain Analysis
Tariff exposure between Japan and Germany for solid-state laser diodes dominates component sourcing risk for holographic hardware vendors. Manufacturing concentrates in Japan, Germany, and Taiwan, with optical assembly feeding from Swiss precision mechanics and South Korean display foundries. Single-source vulnerability sits with Hamamatsu and Yokohama diode suppliers. Distribution runs through direct enterprise sales for healthcare institutions and OEM-integrated channels for automotive HUD applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PhD-level wavefront physics talent pools concentrated at German and Swiss research institutes constrain vendor scaling velocity, creating defensive moats for incumbents with established academic partnerships while fragmenting competitive positioning among software-defined entrants lacking optical hardware heritage.
For Market Incumbents: Entrench hospital GPO bundling relationships before Medicare reimbursement codes for holography-assisted procedures mature, locking out standalone microscope specialists lacking enterprise IT support infrastructure. Acquire neural-network acceleration capabilities to defend margin position against computational holography entrants eroding hardware differentiation through algorithmic updates rather than component innovation. For New Entrants and Emerging Players: Establish a beachhead in India's Tier-2 hospital pathology gap pending CDSCO device registration clarity, leveraging PLI scheme cost offsets for domestic optical component assembly. Target holographic remote consultation systems as the most penetrable application, partnering with Bengaluru electronics manufacturers to bypass incumbent distribution channels. For Investors and Strategic Acquirers: The market sits at a regulatory-validation phase that favors established imaging conglomerates with FDA 510(k) and EU MDR quality management infrastructure over pure-play hardware vendors facing clinical documentation burdens. Acquisition targets should display live-cell imaging R&D intensity or light-field display patent portfolios. Watch for Medicare reimbursement code finalization as the inflection signal for hospital procurement velocity acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital GPO Bundling Agreement | Locks procurement relationships with United States health systems before reimbursement codes mature. |
| Neural Network Acceleration Partnership | Collapses holographic reconstruction latency from minutes to milliseconds for Taiwan foundry deployment. |
| CDSCO Registration Pathway Investment | Positions holographic remote consultation systems for India's Tier-2 hospital infrastructure gap. |
| EU MDR Notified Body Engagement | Secures Class IIa/IIb classification guidance from Munich medical technology cluster expertise. |
| PLI Scheme Optical Assembly Alignment | Captures cost offsets for domestic holographic component manufacturing in Bengaluru electronics cluster. |
Research Approach
Desk research of FDA 510(k) clearance databases, EU MDR notified body guidance documents, and semiconductor foundry capex disclosures preceded structured interviews with hospital procurement committee chairs, biomedical engineering directors, GPO contracts managers, and interferometry specialists at German research institutes. Secondary validation drew from ISO 10993 biocompatibility filings, IEC 60601 electrical safety registrations, and Medicare reimbursement code proposals. Bottom-up instrument shipment estimates triangulated against top-down healthcare IT spending allocations.
Assumptions held fixed include FDA and EU MDR regulatory pathway timelines, laser diode supply concentration patterns, and GPU cluster cost trajectories across the projection horizon. Segmentation dimensions modeled encompass product type, application, end user, and technology tier. CAGRs derived from installed base growth rates weighted by replacement cycle timing and software licensing attach rates. Forecast inputs incorporated Medicare reimbursement momentum and REACH compliance displacement of destructive testing methods.
Sensitivities concentrate around CDSCO registration pathway clarity for India commercialization, MFDS medical device approval timelines in South Korea, and solid-state laser diode tariff exposure between Japan and Germany. Forecasts reflect these documented assumptions. Material shifts in FDA De Novo classification criteria for holographic surgical navigation or EU MDR Article 10 clinical performance documentation requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Technology
Visualization and 3D Rendering Software Market
3D Technology
3D Machine Vision Market
3D Technology
Global 3D Architecture Software Market
3D Technology
APAC 3D Telepresence Market
3D Technology
Middle East and Africa 3D 4D Technology Market
3D Technology
3D Rendering Software Market
3D Technology
3D Rendering Market
3D Technology
Global 3D Virtual Platform Market
3D Technology
Global 3D Rendering Service Market
3D Technology
3D Scanning Market
3D Technology
Glasses Free 3D Tvs Market
3D Technology
UK 3D Rendering Services Market
3D Technology
3D CAD Market
3D Technology
North America 3D 4D Technology Market
3D Technology
3D Photogrammetry Software Market
3D Technology
3D Mobile Mapping Market