
 3D Printing CAD Software Market | 2026-2036
3D Printing CAD Software Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing CAD Software Market Insights
Germany is fragmenting as a design-software demand center as mid-sized manufacturers diversify suppliers beyond incumbent PLM vendors. Autodesk Inc. leverages cloud-native architecture to capture subscription renewals from engineering teams adopting distributed workflows. Siemens Industry Software Inc. anchors its position through deep integration with hardware-agnostic print preparation tools. PTC Inc. differentiates by embedding generative design algorithms that feed directly into metal powder-bed machines.
3D printing CAD software comprises digital design environments that generate, manipulate, and export geometric data formats compatible with additive manufacturing hardware, typically supporting lattice generation, build-orientation optimization, and support-structure automation for industrial production workflows. Cloud-based software and subscription-based delivery models are capturing the fastest expansion as IT procurement teams prioritize OpEx flexibility and remote collaboration infrastructure over perpetual desktop licenses. Aerospace and automotive applications concentrate margin pools where AS9100 and IATF 16949 compliance requirements demand traceable design-to-part genealogy.
The U.S. Food and Drug Administration regulates patient-specific implant design files as Class II medical devices, compelling healthcare software vendors to validate algorithmic outputs under 21 CFR Part 820 quality-system requirements. Europe's Medical Device Regulation and CE marking framework extend similar conformity obligations to surgical planning software distributed across EU member states. Stakeholders must monitor evolving ISO/ASTM standards for process parameter qualification as regulatory bodies harmonize digital design-file integrity with physical part certification protocols.
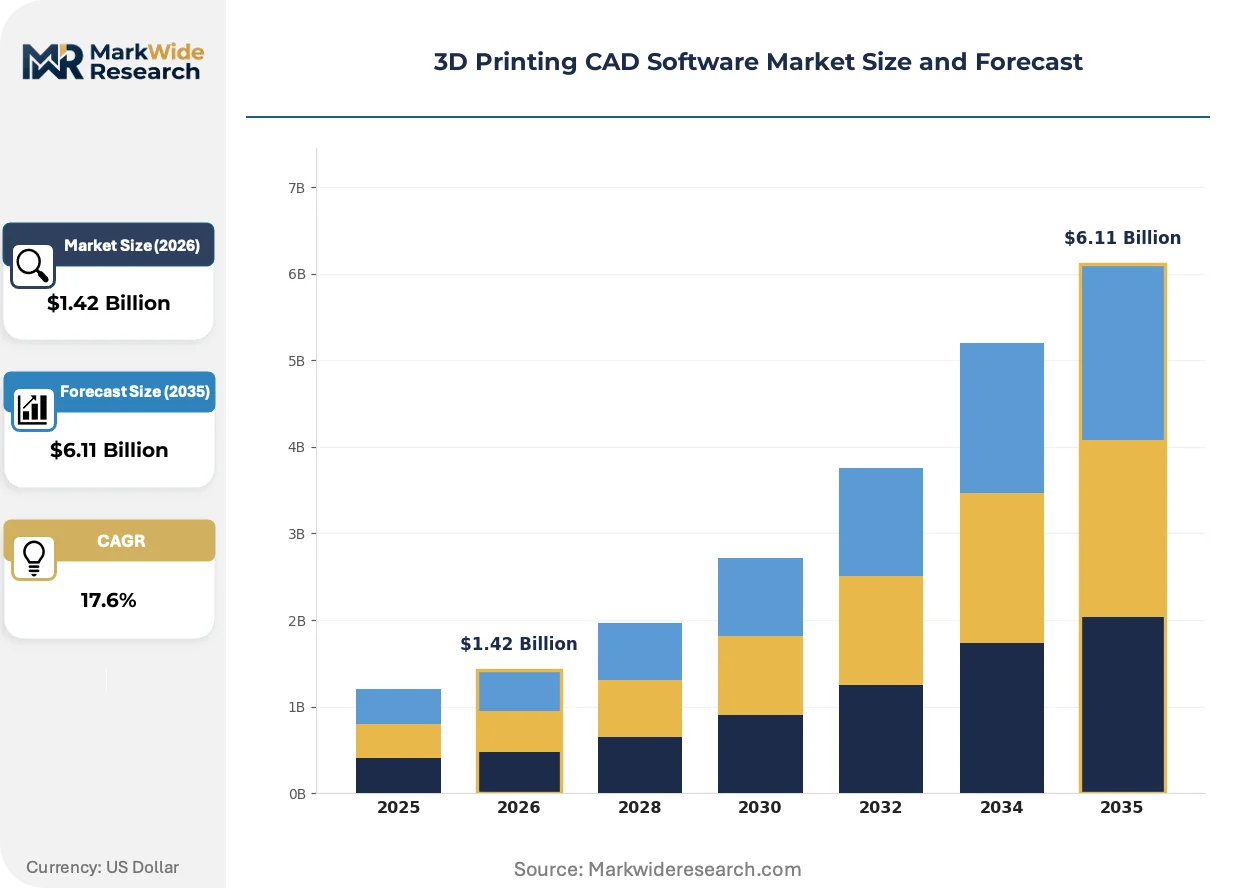
Market Dynamics
Topology-optimized lattice generation is compressing design iteration cycles from weeks to hours, forcing incumbent vendors to rearchitect kernel solvers for GPU-native computation or cede aerospace and medical implant workflows to cloud-native entrants.
Growth Catalysts
- ISO/ASTM 52900 Interoperability Mandates:Standardized additive manufacturing data formats eliminate vendor lock-in, enabling Mittelstand manufacturers in Germany to mix simulation tools from competing suppliers within unified CAD-to-print pipelines.
- AS9100D Traceability Requirements:Aerospace primes now demand design-file genealogy tracking from initial topology study through final build verification, expanding subscription attach rates for audit-ready cloud platforms.
- Metal Powder-Bed Fusion:Heat-transfer simulation modules that predict residual stress and distortion in titanium and Inconel builds have become non-negotiable for qualified production, pulling specialized solver licenses into enterprise agreements.
Market Restraints
- GPU Compute Cost Volatility:Cloud-native simulation workloads depend on NVIDIA A100/H100 availability, with spot-price spikes in Q3 2023 forcing mid-sized vendors to throttle concurrent user seats.
- Legacy PLM Integration Friction:Siemens Teamcenter and Dassault ENOVIA dominance in automotive and aerospace creates switching costs that anchor procurement decisions even when specialized additive tools offer superior lattice algorithms.
- Open-Source Substitutes:Blender's Geometry Nodes and FreeCAD's FEM workbenches now handle basic support-structure generation, capturing price-sensitive education and prototyping segments.
Strategic Opportunities
- India PLI Scheme for Medical Devices:Domestic implant manufacturers qualifying under production-linked incentives require validated surgical planning software, creating first-mover advantage for vendors achieving CDSCO software-as-medical-device registration.
- Digital Twin Convergence:Real-time build-chamber sensor feeds linked to pre-process simulation models enable closed-loop parameter adjustment, differentiating platforms that integrate melt-pool monitoring APIs.
- Outcome-Based Licensing:Per-part royalty models tied to successful build completion are displacing fixed annual seats among contract manufacturers serving fragmented orthopedic and dental markets.
Industry Challenges
- Computational Geometry Talent Scarcity:Kernel development for non-manifold mesh healing and watertight STL repair requires rare expertise in discrete differential geometry, constraining vendor R&D velocity.
- FDA 510(k) Software Validation Timelines:Patient-specific implant design tools face 12-18 month clearance cycles under 21 CFR Part 820, compressing commercialization windows for algorithmic innovations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing CAD Software Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $6.11 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial Software, Open Source Software, Cloud-based Software, Desktop Software Application: Aerospace, Automotive, Healthcare, Education User Type: Professional Designers, Engineers, Hobbyists, Enterprises Delivery Model: Subscription-based, One-time Purchase, Freemium, Enterprise Licensing |
| Companies Covered | Dassault Systèmes SE, Autodesk Inc., Siemens Industry Software Inc, PTC Inc., Hexagon AB, Bentley Systems Inc., Bricsys NV, ZWSOFT Co. Ltd., Trimble Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing CAD Software Market Trends and Innovations
Generative design algorithms are collapsing the boundary between structural optimization and manufacturing-process simulation, forcing vendors to unify disciplines that historically operated in separate software stacks.
Implicit modeling kernels based on signed distance fields are digitizing the representation of complex lattice structures and variable-density infill patterns. Medical device manufacturers adopting these representations for porous titanium hip cups have reduced file sizes by orders of magnitude versus traditional mesh formats. This compression is digitizing the transfer of design intent between surgical planning stations and metal powder-bed systems.
Europe's Medical Device Regulation (MDR) Annex XVI expansion now captures patient-matched surgical guides and implant design software as Class IIa devices. Swissmedic and Germany's BfArM have issued parallel guidance requiring algorithmic validation documentation for machine-learning-assisted anatomical segmentation. Orthopedic software vendors are responding by embedding deterministic rule-based engines that bypass black-box neural networks for critical dimension calculations.
Engineering teams are consolidating vendor relationships around platforms offering unified subscription tiers spanning CAD, simulation, and print preparation. This bundling is displacing point-solution procurement patterns where specialized lattice tools supplemented incumbent PLM seats. The shift is most visible among German automotive suppliers integrating additive workflows for topology-optimized electric vehicle motor housings.
3D Printing CAD Software Market Segmentation
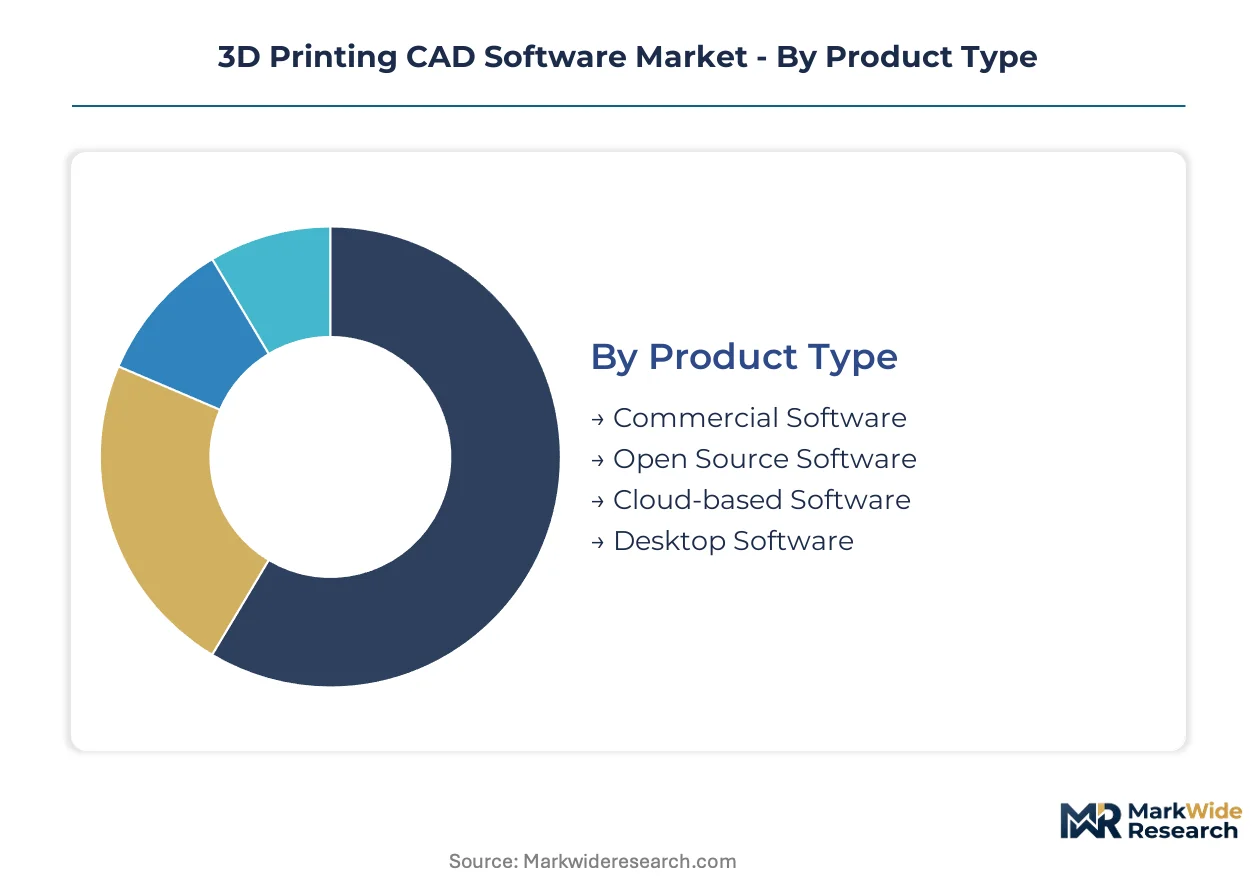
Segmentation in 3D printing CAD software reveals how procurement criteria diverge across technical sophistication levels and compliance obligations. License structures and deployment architectures determine vendor selection more than raw feature counts in aerospace and medical implant workflows.
Product Type:
After-sales service intensity varies dramatically across deployment architectures, with cloud-native platforms demanding continuous DevOps support while desktop licenses require sporadic patch management.
- Cloud-based Software:Browser-native architectures with automatic kernel updates eliminate version fragmentation across distributed engineering teams. German automotive suppliers adopting these platforms for topology-optimized electric motor housings prioritize ISO/ASTM 52900 data interoperability over localized solver performance.
- Commercial Software:Perpetual-license desktop suites with deep PLM integration anchor procurement decisions at aerospace primes despite longer iteration cycles. AS9100D traceability requirements pull these installations into enterprise agreements with mandatory audit-log retention.
- Open Source Software:Community-maintained FEM workbenches and mesh repair tools capture education and prototyping segments.
- Desktop Software:Offline-capable installations persist in facilities with restricted network security protocols.
Commercial software holds the largest share; momentum sits with cloud-based platforms.
Application:
Regulatory density determines pricing tolerance, with medical and aerospace applications commanding specialized solver premiums over general mechanical design.
- Aerospace:Topology optimization for lattice-structured brackets and heat exchangers demands GPU-native kernel solvers capable of compressing design cycles from weeks to hours. FAA certification requirements for flight-critical components mandate traceable design-file genealogy from initial study through build verification.
- Healthcare:Patient-specific implant design tools face FDA 510(k) validation timelines of 12-18 months under 21 CFR Part 820, compressing commercialization windows for algorithmic innovations. FDA regulation of design files as Class II medical devices compels deterministic rule-based engines over black-box neural networks.
- Automotive:IATF 16949 compliance requirements drive integration with incumbent PLM systems.
- Education:Price-sensitive institutions gravitate toward open-source substitutes with basic support-structure generation.
Aerospace dominates revenue concentration; healthcare shows the steepest expansion trajectory.
User Type:
Technical depth and procurement authority separate segments, with enterprise buyers consolidating vendor relationships around unified subscription tiers.
- Enterprises:Multi-site engineering organizations bundle CAD, simulation, and print preparation into single vendor relationships, displacing point-solution procurement. IT procurement teams prioritize OpEx flexibility and remote collaboration infrastructure over perpetual desktop licenses.
- Professional Designers:Specialized industrial designers require implicit modeling kernels for complex lattice structures with file-size compression orders of magnitude below traditional mesh formats.
- Engineers:Cross-functional teams need heat-transfer simulation modules predicting residual stress in titanium and Inconel builds.
- Hobbyists:Individual makers drive freemium conversion rates through basic slicing and support generation.
Enterprises command the largest contract values; professional designers are gaining share fastest.
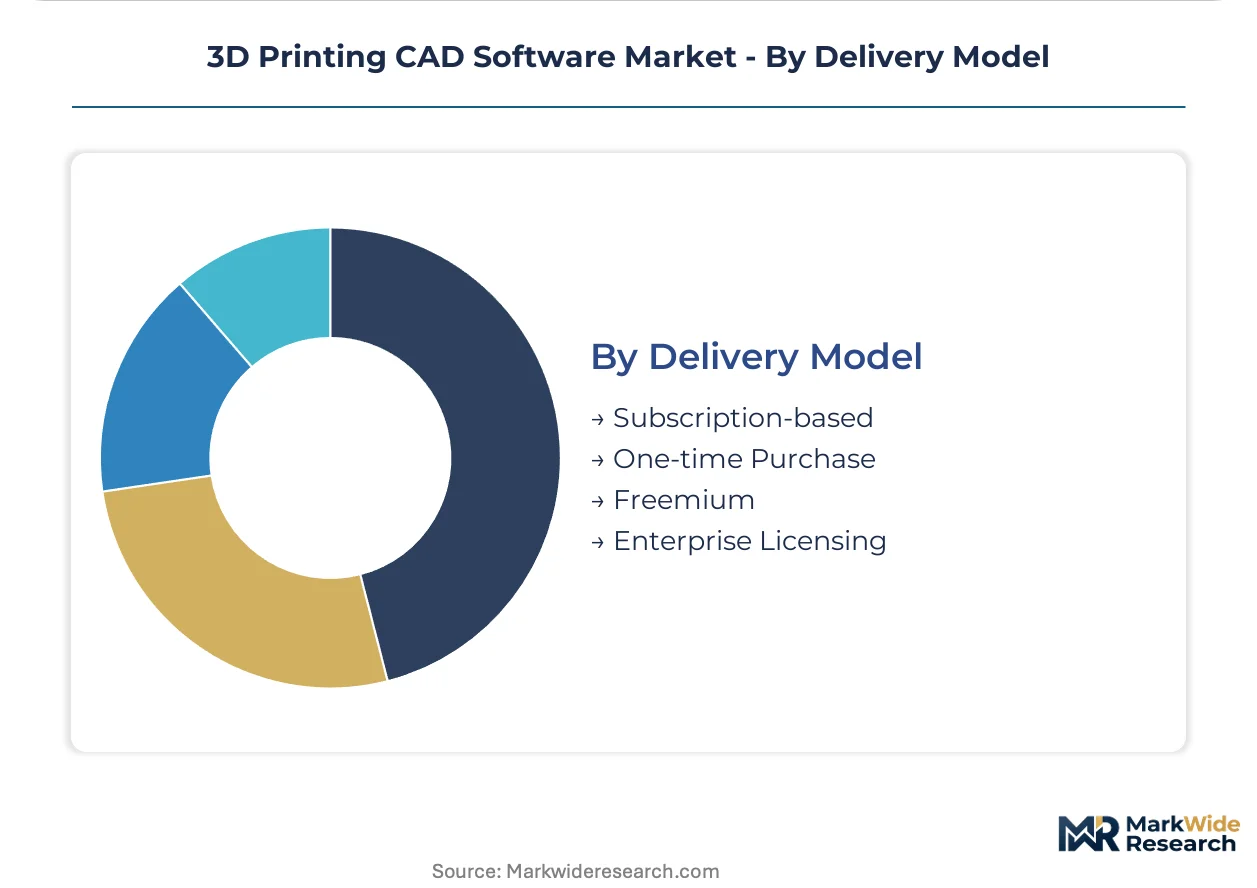
Delivery Model:
Revenue predictability and customer lifetime value differentiate structures, with outcome-based models emerging in contract manufacturing.
- Subscription-based:Monthly or annual recurring revenue models capture IT procurement priorities for OpEx classification and remote collaboration scaling. Autodesk leverages this architecture for distributed engineering team renewals.
- Enterprise Licensing:Multi-year agreements with audit-ready cloud platforms attach simulation and print preparation modules at negotiated rates. Siemens anchors these relationships through Teamcenter integration.
- Freemium:Tiered feature gates convert hobbyist users to paid tiers for advanced lattice generation.
- One-time Purchase:Perpetual licenses persist in regulated environments with frozen validation baselines.
Enterprise licensing holds the largest share; subscription-based models are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Frankfurt-Rhine-Main data corridor anchors European additive manufacturing software traffic, while the Shanghai-Suzhou-Nantong manufacturing belt processes the highest volume of industrial CAD-to-print workflows in Asia-Pacific.
Germany
Industrial Mittelstand firms in Baden-Württemberg and Bavaria drive demand for topology-optimized metal additive production workflows. The BfArM mandates algorithmic validation documentation for patient-matched surgical guides under MDR Annex XVI. Stuttgart's automotive supplier cluster integrates cloud-native CAD platforms for electric motor housing design.
United States
Aerospace primes in Washington State and Texas require AS9100D-traceable design-file genealogy from topology study through build verification. The FDA regulates patient-specific implant design files as Class II medical devices under 21 CFR Part 820. Greater Boston's medical device corridor concentrates surgical planning software vendors pursuing 510(k) clearances.
China
Domestic implant manufacturers under the MIIT's industrial additive manufacturing promotion guidelines seek validated surgical planning tools. NMPA software-as-medical-device registration creates first-mover opportunities for foreign vendors localizing products. The Yangtze River Delta's precision manufacturing cluster adopts heat-transfer simulation modules for titanium aerospace components.
India
Domestic implant manufacturers qualifying under the PLI Scheme for Medical Devices require CDSCO-registered surgical planning software. The production-linked incentive framework subsidizes capital equipment for metal powder-bed systems in orthopedic and dental markets. Maharashtra's Mumbai-Pune industrial corridor concentrates contract manufacturers adopting per-part royalty licensing models.
Japan
METI's additive manufacturing technology roadmap prioritizes closed-loop process control integration between simulation and build monitoring. PMDA guidance on software-as-medical-device classification affects patient-specific orthopedic planning tools. The Nagoya aerospace manufacturing cluster demands GPU-native kernel solvers for Inconel heat exchanger optimization.
3D Printing CAD Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in lattice generation and support-structure automation. The vendor landscape concentrates around three structural tiers: cloud-native entrants with GPU-accelerated solvers, incumbent PLM-anchored suites with deep enterprise integration, and open-source communities capturing education segments. Consolidation pressure intensifies as aerospace and medical procurement teams consolidate vendor relationships around unified subscription tiers. Dominant competitive moves include strategic partnerships linking simulation kernels to hardware-agnostic print preparation tools and technology licensing agreements embedding proprietary lattice algorithms into OEM machine control systems.
Among platform-integrated incumbents, Dassault Systèmes SE and Siemens Industry Software Inc occupy positions anchoring enterprise CAD-to-print pipelines through PLM system dominance. Autodesk Inc exemplifies the cloud-native archetype, representing subscription-based delivery models that capture distributed engineering team renewals. These three entities collectively illustrate how vendor selection increasingly prioritizes OpEx flexibility and remote collaboration infrastructure over perpetual desktop licenses.
| Leading Market Players |
|---|
| Dassault Systèmes SE |
| Autodesk Inc. |
| Siemens Industry Software Inc |
| PTC Inc. |
| Hexagon AB |
| Bentley Systems Inc. |
| Bricsys NV |
| ZWSOFT Co. Ltd. |
| Trimble Inc. |
| Others |
Pricing and Supply Chain Analysis
GPU cluster undercapacity in the Yangtze River Delta during peak simulation workloads compresses vendor margins while simultaneously elevating subscription pricing power for cloud-native platforms with reserved compute allocations.
Pricing Analysis
ISO/ASTM 52900 interoperability mandates dictate the pricing tier structure across deployment architectures. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-grade audit-ready platforms from mid-market cloud subscriptions and open-source education licenses. Price differentiation hinges on AS9100D certification tier and GPU-native solver performance. Cost compression in the standard tier intensifies because Blender Geometry Nodes and FreeCAD FEM workbenches capture prototyping segments. Hobbyists and educational institutions exhibit the highest price sensitivity; aerospace primes with frozen validation baselines demonstrate the lowest.
Supply Chain Analysis
Extended payment terms from German automotive suppliers and supply-chain finance facilities from cloud hyperscalers shape vendor working capital requirements. Software development concentrates in the United States, Germany, and China. Kernel development draws from NVIDIA GPU hardware, implicit modeling research from Swiss academic institutions, and regulatory compliance expertise from FDA-cleared Boston corridor firms. Single-source vulnerability in NVIDIA A100/H100 availability creates procurement risk. Distribution runs through direct enterprise sales teams with PLM integration specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
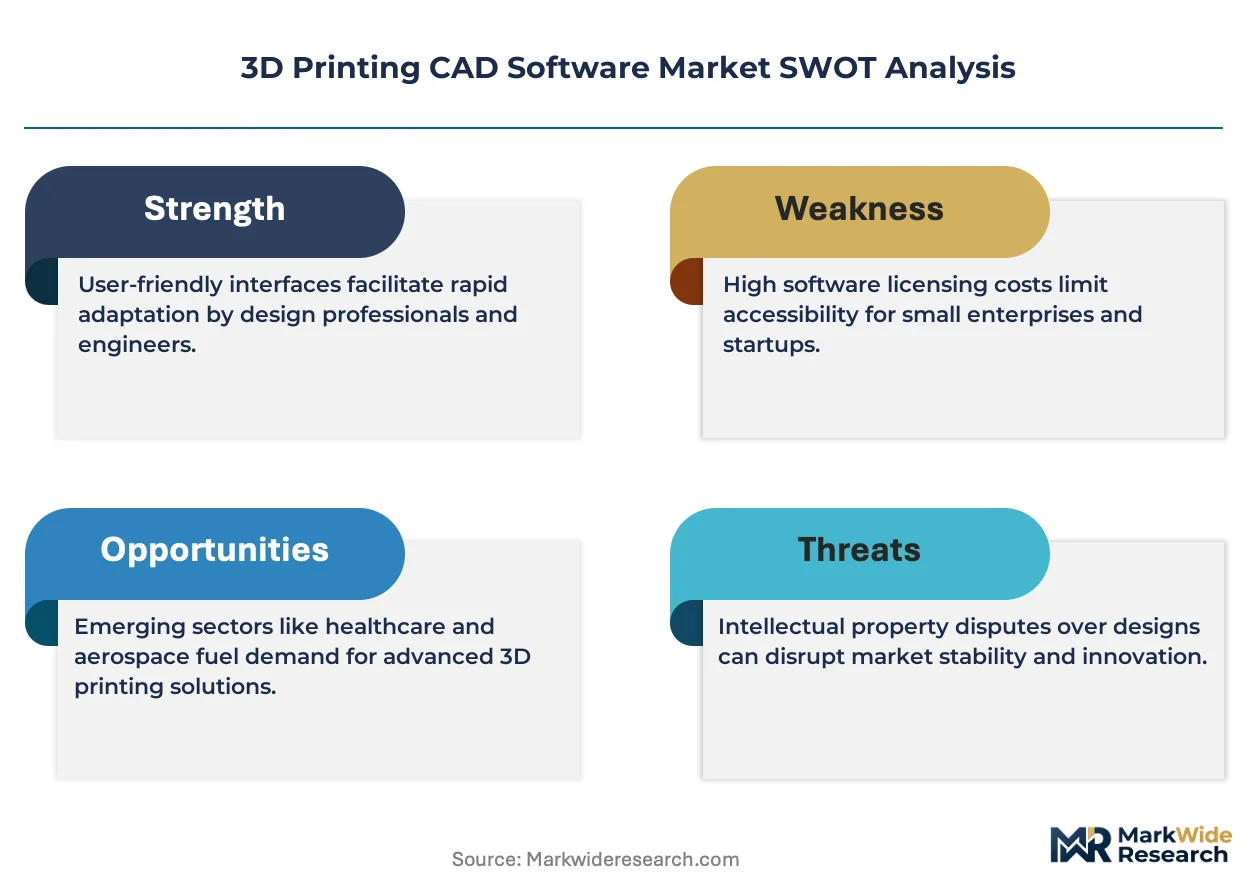
This market functions as a defensive-moat story anchored in regulatory entrenchment. FDA 510(k) validation timelines and ISO/ASTM certification requirements create sticky customer relationships that resist displacement.
For Market Incumbents: Insulate core revenue by embedding generative design kernels directly into OEM machine control systems through technology licensing agreements. Deepen switching costs via Teamcenter and ENOVIA PLM integration that locks aerospace and automotive procurement decisions. Counter cloud-native entrants by reserving GPU cluster capacity with NVIDIA through multi-year framework agreements.
For New Entrants and Emerging Players: Build out specialized solver modules for heat-transfer simulation in titanium and Inconel builds that incumbent kernels handle poorly. Capture white-space in India's PLI Scheme for Medical Devices by achieving CDSCO software-as-medical-device registration before foreign competitors localize. Pursue outcome-based per-part royalty models with Maharashtra contract manufacturers as the beachhead go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cloud-native simulation platforms due to GPU compute reservation requirements. Long-term viability favors vendors with regulatory validation moats and hardware-agnostic print preparation integration. Target acquisition archetypes include implicit modeling kernel specialists with discrete differential geometry talent. Watch NVIDIA GPU spot-price volatility as the inflection indicator for margin compression risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies CAD, simulation, and print preparation into single vendor relationships displacing point solutions. |
| Regulatory Certification Investment | FDA 510(k) and CE marking pathways create defensible market positions in patient-specific implant workflows. |
| Strategic Partnership | Links GPU-accelerated simulation kernels to hardware-agnostic print preparation tools for aerospace adoption. |
| Acquisition of Specialist Firm | Captures implicit modeling kernel expertise for lattice structure file compression in medical applications. |
| Geographic Expansion | Localizes products for CDSCO and NMPA registration in India's PLI Scheme and China's MIIT promotion guidelines. |
Research Methodology
Operator-level perspectives from additive manufacturing engineers, IT procurement officers, PLM integration specialists, and regulatory affairs managers anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) filings, EMA MDR guidance documents, ISO/ASTM standard drafts, and SEC software vendor disclosures. Bottom-up deployment model adoption curves triangulated against top-down aerospace and automotive capital expenditure patterns.
Scenario-bracketing framed the analytical approach across the analysis window. Segmentation dimensions modeled include deployment architecture, organization size, vertical application, integration complexity with incumbent PLM systems, and regional regulatory cluster. CAGRs derived from weighted average of vendor-reported subscription renewals and enterprise licensing attach rates. Industry-specific inputs incorporated GPU compute cost trajectories and ISO/ASTM 52900 adoption timelines.
Sensitivities concentrate around NVIDIA GPU availability shocks, FDA validation timeline extensions, and PLM vendor competitive responses. Forecasts reflect documented assumptions on cloud migration velocity and regulatory harmonization progress. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Technology
APAC 3D Telepresence Market
3D Technology
3D Rendering Software Market
3D Technology
Molecular Modeling Market
3D Technology
3D Scanner Market
3D Technology
3D Point Cloud Processing Software Market
3D Technology
Global 3D Virtual Platform Market
3D Technology
Global 3D Rendering Service Market
3D Technology
Middle East and Africa 3D 4D Technology Market
3D Technology
3D Simulation Software Market
3D Technology
Global Mobile 3D Sensing Market
3D Technology
3D Rendering Market
3D Technology
APAC 3D 4D Technology Market
3D Technology
Latin America 3D 4D Technology Market
3D Technology
Generative Design Market
3D Technology
Global 3D Mapping and 3D Modeling Market
3D Technology
Mobile 3D Market