
 APAC 3D 4D Technology Market | 2026-2036
APAC 3D 4D Technology Market Size, Share, and Industry Trends Forecast 2026-2036
APAC 3D 4D Technology Market Outlook
Fragmentation among automotive tier-one suppliers across China and India is recalibrating procurement patterns for production-grade additive systems. Samsung Electronics Co., Ltd. leverages its semiconductor fabrication expertise to dominate high-resolution stereolithography equipment. Stratasys Ltd. anchors industrial polymer printing through localized service networks in Singapore and Australia. Dassault Systèmes SE competes via software-integrated digital twin platforms that bridge design-to-manufacture workflows for regional OEMs.
APAC 3D 4D Technology encompasses additive manufacturing systems, programmable smart materials, and spatial visualization platforms that construct or manipulate objects across three physical dimensions with time-responsive or simulation-capable fourth-dimensional properties. Fused Deposition Modeling systems process thermoplastic filaments through heated extrusion nozzles at layer resolutions typically ranging from 50 to 400 microns, serving both functional prototyping and end-use part production. Software Solutions capture expanding margin pools as manufacturers prioritize digital thread continuity from CAD geometry to machine instruction codes. Medical Devices application demand outpaces aerospace prototyping in revenue velocity across tertiary hospitals in Seoul, Tokyo, and Shanghai.
China's MIIT enforces GB standards for industrial additive equipment safety and material traceability, while Japan's METI coordinates JIS certification pathways for medical device additive manufacturing. South Korea's MFDS regulates patient-specific implant qualification, tightening biocompatibility documentation requirements for titanium and PEEK constructs. Australia's TGA alignment with MDR-equivalent frameworks affects import access for European-built 4D printing systems. Stakeholders must monitor divergence between national standards bodies and assess whether dual-certification strategies or localized R&D partnerships offer faster market access across these jurisdictions.
Market Dynamics
China's MIIT GB standards for additive manufacturing safety and material traceability are compressing certification timelines while fragmenting procurement patterns across automotive tier-one suppliers in India and China.
Growth Catalysts
- Patient-specific implant fabrication:South Korea's MFDS and Japan's METI coordinate accelerated JIS certification pathways for titanium and PEEK constructs in tertiary hospitals across Seoul and Tokyo.
- Software-integrated digital twin platforms:Regional OEMs bridge design-to-manufacture workflows through spatial visualization platforms that manipulate objects across three physical dimensions with time-responsive properties.
- 4D-responsive materials:Aerospace suppliers in Japan's precision engineering clusters integrate programmable smart materials into next-generation component design for responsive structural adaptation.
Market Restraints
- Biocompatibility documentation requirements:South Korea's MFDS tightens qualification standards for patient-specific implants, extending validation cycles for titanium and PEEK constructs.
- Import access barriers:Australia's TGA alignment with MDR-equivalent frameworks restricts European-built 4D printing systems from entering the domestic market without localized recertification.
- Layer resolution limitations:Fused Deposition Modeling systems processing thermoplastic filaments face technical ceilings at 50-400 micron ranges, constraining high-precision medical device applications.
Strategic Opportunities
- Underpenetrated tertiary hospital networks:Medical device application demand in Shanghai's hospital clusters outpaces current aerospace prototyping revenue velocity, creating white space for equipment vendors.
- Dual-certification strategies:Stakeholders can assess whether localized R&D partnerships across South Korea, Japan, and China offer faster market access than sequential national approvals.
- Semiconductor fabrication expertise transfer:High-resolution stereolithography equipment benefits from precision engineering capabilities developed in adjacent electronics manufacturing clusters.
Industry Challenges
- Skill gaps in 4D material programming:The workforce shortage in programmable smart material design and time-responsive geometry optimization constrains deployment timelines for responsive component systems.
- Integration complexity with legacy CAD systems:Digital thread continuity from CAD geometry to machine instruction codes requires middleware development that many regional manufacturers lack in-house.
- Divergence between national standards bodies:China's MIIT, Japan's METI, and South Korea's MFDS maintain non-harmonized certification pathways, forcing redundant testing protocols for multi-market equipment vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC 3D 4D Technology Market |
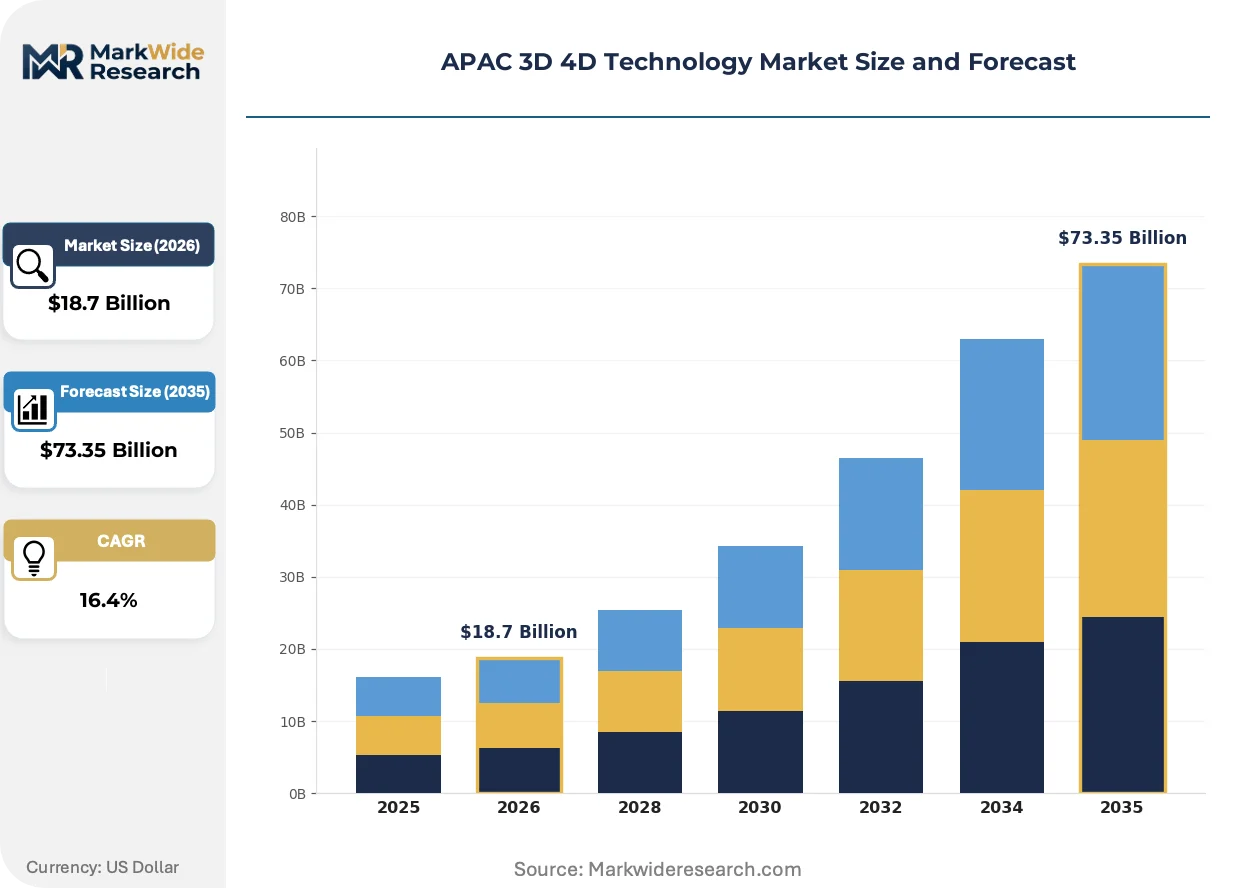
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Printing, 4D Printing, Software Solutions, Printing Materials Application: Prototyping, Aerospace, Automotive, Medical Devices End User: Manufacturers, Healthcare Providers, Educational Institutions, R&D Centers Technology: Fused Deposition Modeling, Stereolithography, Digital Light Processing, Material Jetting |
| Companies Covered | Samsung Electronics Co., Ltd., LG Electronics Inc., Sony Corporation, Autodesk, Inc., Dassault Systèmes SE, Stratasys Ltd., 3D Systems Corporation, Hexagon AB, Canon, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC 3D 4D Technology Market Strategic Shifts
Programmable material systems and regulatory harmonization pressures are actively restructuring how additive manufacturing equipment moves from prototype validation to production-scale deployment across the region.
Shape-memory polymers and hydrogel composites are converging with traditional additive manufacturing platforms to enable components that respond to thermal, electrical, or moisture stimuli after fabrication. Medical device manufacturers in Seoul and Tokyo are piloting these materials for stent and orthopedic applications at compressed development cycles. This convergence is collapsing the boundary between static implant fabrication and adaptive therapeutic devices.
Japan's METI coordinates with JIS standards bodies to streamline medical device additive manufacturing certification, reducing documentation burdens for titanium and PEEK constructs. Industrial consequence includes faster turnaround for patient-specific implant approvals in tertiary hospitals. Aerospace prototyping segments in Nagoya and Fukuoka are responding by reallocating R&D budgets toward medical device qualification pathways.
Hospital procurement committees in Shanghai, Seoul, and Tokyo are consolidating vendor relationships around full-service digital thread providers rather than discrete equipment purchases. Equipment financing and service bundling are displacing capital expenditure models in mid-tier hospital networks. This behavioral shift is most visible in South Korea's tertiary hospital clusters, where MFDS-qualification status now dominates supplier selection criteria over equipment specifications alone.
APAC 3D 4D Technology Market Segmentation
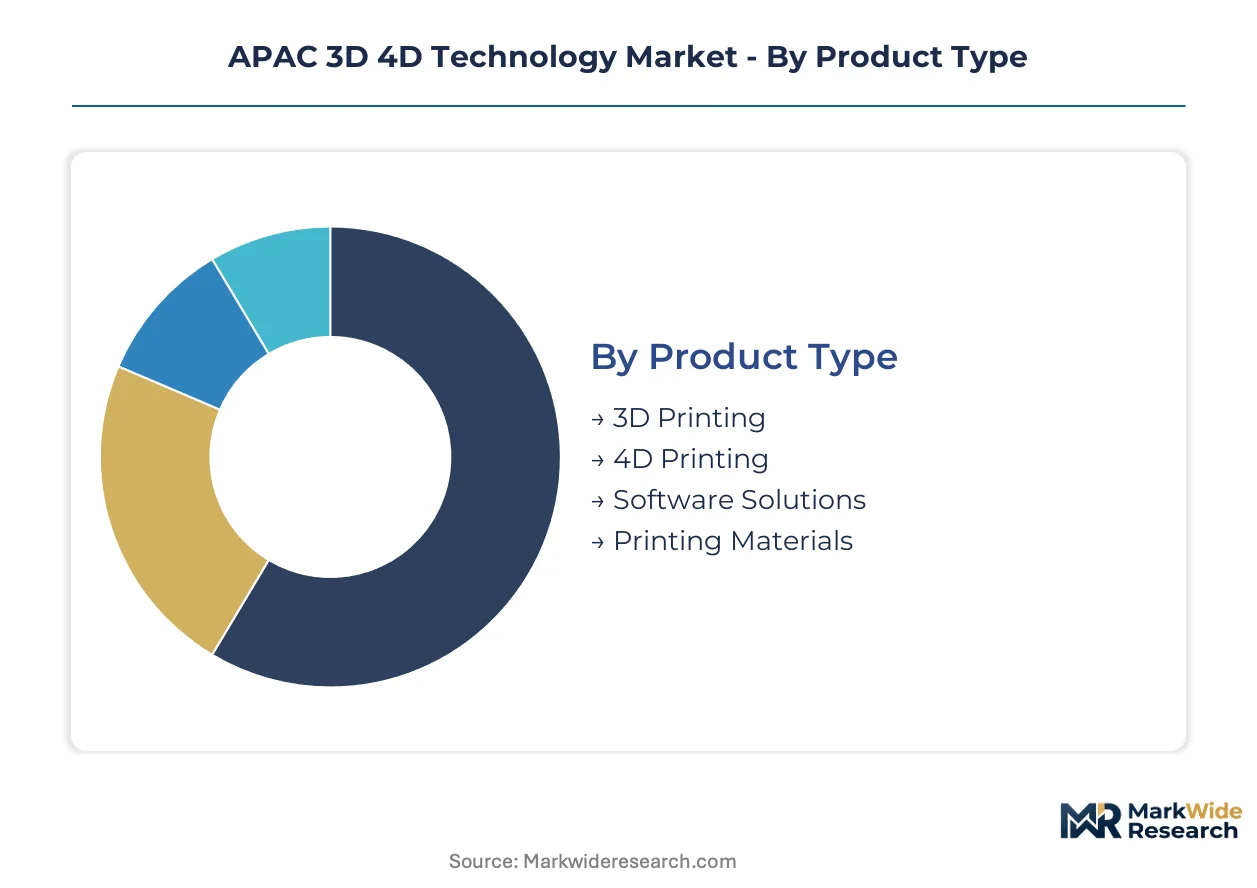
APAC 3D 4D Technology market segmentation reveals how supply-side capabilities diverge across hardware, materials, and software layers. Equipment vendors and material suppliers compete on fundamentally different margin structures, forcing distinct investment priorities across each category.
Product Type:
Supply concentration in precision hardware manufacturing clusters across Japan and South Korea shapes competitive dynamics across product categories.
- 3D Printing:Industrial additive systems process metals, polymers, and ceramics through layer-wise fabrication at resolutions spanning 50-400 microns. Demand concentrates in Japan's precision engineering clusters where aerospace suppliers integrate production-grade systems into qualified supply chains. China's MIIT GB standards compress certification timelines for domestic equipment while fragmenting procurement patterns among automotive tier-one suppliers.
- 4D Printing:Programmable smart materials enable time-responsive structural adaptation through shape-memory polymers and hydrogel composites. Seoul and Tokyo medical device manufacturers pilot stent and orthopedic applications at compressed development cycles, collapsing boundaries between static implants and adaptive therapeutic devices.
- Software Solutions:Digital thread platforms bridge CAD geometry to machine instruction codes, capturing expanding margin pools as manufacturers prioritize design-to-manufacture continuity.
- Printing Materials:Titanium and PEEK constructs dominate patient-specific implant fabrication, with biocompatibility documentation requirements tightening under South Korea's MFDS and Japan's METI coordination.
Today's leader: 3D Printing. Tomorrow's challenger: 4D Printing.
Application:
End-use demand patterns split between high-volume prototyping and regulated production environments with divergent qualification burdens.
- Medical Devices:Patient-specific implant fabrication outpaces aerospace prototyping in revenue velocity across tertiary hospitals in Seoul, Tokyo, and Shanghai. Hospital procurement committees consolidate vendor relationships around full-service digital thread providers rather than discrete equipment purchases.
- Aerospace:Prototyping segments in Nagoya and Fukuoka reallocate R&D budgets toward medical device qualification pathways as METI streamlines JIS certification. Component suppliers integrate 4D-responsive materials into next-generation designs for adaptive structural performance.
- Prototyping:Functional verification workflows across automotive and consumer electronics sectors absorb entry-level Fused Deposition Modeling systems at 50-400 micron resolutions.
- Automotive:Tier-one supplier fragmentation across China and India recalibrates procurement patterns for production-grade additive systems with localized service requirements.
Medical Devices commands current premium pricing. Aerospace prototyping faces margin compression from qualification pathway competition.
End User:
Customer sophistication tiers separate capital-intensive manufacturers from service-dependent healthcare and research institutions.
- Manufacturers:Industrial OEMs deploy production-grade systems for end-use part fabrication, prioritizing equipment financing and service bundling over capital expenditure models. Samsung Electronics leverages semiconductor fabrication expertise to dominate high-resolution stereolithography equipment.
- Healthcare Providers:Tertiary hospital networks in Shanghai, Seoul, and Tokyo select suppliers based on MFDS-qualification status over equipment specifications alone, consolidating around full-service digital thread providers.
- R&D Centers:Applied research institutions pilot 4D material programming and time-responsive geometry optimization, constrained by workforce shortages in programmable smart material design.
- Educational Institutions:Training facilities absorb entry-level systems for workforce development, though skill gaps in middleware development for legacy CAD integration persist.
Manufacturers drive equipment volume. Healthcare Providers determine margin expansion through service bundling.
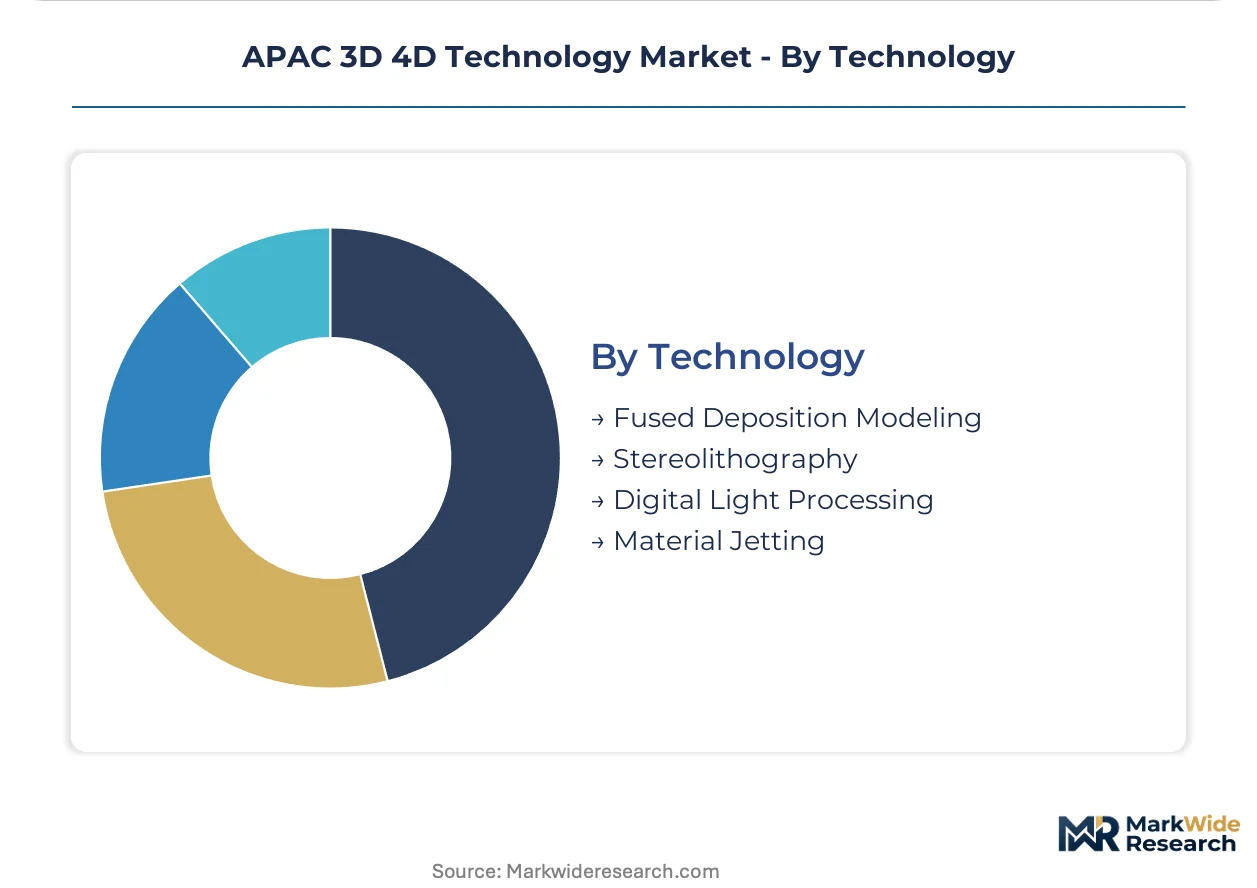
Technology:
Process maturity curves separate established deposition methods from emerging light-based systems with distinct resolution and throughput tradeoffs.
- Stereolithography:High-resolution light-polymerization systems achieve finest layer resolutions through ultraviolet laser or projector exposure of photosensitive resins. Semiconductor fabrication expertise from adjacent electronics clusters transfers directly into equipment precision capabilities.
- Fused Deposition Modeling:Heated extrusion nozzles process thermoplastic filaments at 50-400 micron resolutions, serving functional prototyping and select end-use production with technical ceilings constraining high-precision medical applications.
- Digital Light Processing:Projector-based photopolymerization enables faster layer curing than point-source stereolithography, attracting mid-tier manufacturers balancing resolution against throughput.
- Material Jetting:Drop-on-demand deposition of build and support materials enables multi-material geometries with soluble support removal, though equipment costs limit adoption to specialized applications.
Stereolithography holds precision leadership. Digital Light Processing gains share fastest in throughput-sensitive segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT certification compression contrasts with Japan's METI-coordinated JIS pathways, creating divergent market access velocities across Northeast Asia's additive manufacturing clusters.
China
Domestic equipment vendors capture share as GB standards compress industrial system certification timelines. MIIT's additive manufacturing safety mandates accelerate domestic qualification while fragmenting procurement among automotive tier-one suppliers. Yangtze River Delta precision manufacturers integrate production-grade systems into qualified supply chains for medical device exports.
Japan
Precision engineering clusters in Nagoya and Tokyo drive aerospace prototyping demand for 4D-responsive materials. METI coordinates with JIS standards bodies to streamline medical device additive manufacturing certification, reducing documentation burdens for titanium constructs. Kansai region suppliers reallocate R&D budgets toward patient-specific implant qualification pathways.
South Korea
Tertiary hospital networks in Seoul accelerate patient-specific implant fabrication revenue velocity past aerospace prototyping. MFDS tightens biocompatibility documentation requirements for titanium and PEEK constructs, extending validation cycles. Busan-Ulsan industrial corridors absorb high-resolution stereolithography equipment through semiconductor fabrication expertise transfer.
Australia
Import-dependent hospital networks face access barriers as TGA alignment with MDR-equivalent frameworks restricts European-built 4D printing systems. Localized recertification requirements favor Asia-Pacific equipment vendors with existing conformity infrastructure. New South Wales and Victoria research institutions pilot programmable smart material applications under constrained procurement budgets.
India
Automotive tier-one supplier fragmentation recalibrates procurement patterns for entry-level Fused Deposition Modeling systems. Maharashtra and Gujarat manufacturing clusters prioritize functional prototyping over production-grade additive deployment. Skill gaps in middleware development for legacy CAD integration constrain digital thread adoption among mid-tier industrial OEMs.
APAC 3D 4D Technology Market Competitive Environment
Japanese and South Korean producers anchor the precision equipment tier; European and North American specialists hold software-integrated platform positions. The vendor base separates into three strategic archetypes: semiconductor-fabrication heritage precision hardware manufacturers, full-service digital thread providers, and localized industrial polymer printing networks. Competitive moves concentrate on strategic partnerships bridging design-to-manufacture workflows and geographic expansion through regional service center establishment.
Among diversified electronics conglomerates, Samsung Electronics Co., Ltd. occupies a position reflecting semiconductor fabrication expertise transfer into high-resolution equipment categories. Stratasys Ltd. and 3D Systems Corporation exemplify the industrial polymer printing archetype through localized service network presence across Singapore and Australia. Dassault Systèmes SE represents the software-integrated platform tier, anchoring digital twin workflows for regional OEMs.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| LG Electronics Inc. |
| Sony Corporation |
| Autodesk, Inc. |
| Dassault Systèmes SE |
| Stratasys Ltd. |
| 3D Systems Corporation |
| Hexagon AB |
| Canon, Inc. |
| Others |
Value Chain & Pricing Dynamics
Titanium powder feedstock costs cascade through three distinct pricing tiers as they move from Chinese sponge producers through Japanese precision equipment manufacturers to Korean implant fabricators serving Seoul's tertiary hospital networks.
Pricing Analysis
Capacity additions in South Korea's Busan-Ulsan corridor are reshaping price floors for high-resolution stereolithography equipment, compressing margins for imported systems. Pricing stratifies across MFDS-qualification tiers, JIS-certified precision grades, and standard industrial configurations. Cost compression in entry-level Fused Deposition Modeling runs through automotive tier-one supplier consolidation in India and China. Hospital procurement committees in Shanghai exhibit lowest price sensitivity, prioritizing digital thread service bundling over equipment capital expenditure.
Supply Chain Analysis
China's MIIT domestic-content mandates for industrial additive systems are reshaping sourcing patterns, forcing multinational vendors toward localized assembly partnerships. Supply concentrates in Japan's Nagoya precision clusters, South Korea's semiconductor-adjacent fabrication corridors, and China's Yangtze River Delta equipment hubs. Photopolymer resin formulations, titanium powder specifications, and precision motion control components anchor upstream dependencies. Single-source vulnerability concentrates in high-purity titanium sponge processing. Distribution runs through hospital procurement committees, automotive Tier 1 supplier technical centers, and aerospace qualification pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The APAC 3D 4D Technology market reads as a late-cycle quality story where hospital procurement committees in Seoul and Tokyo now prioritize MFDS-qualification status and JIS certification tiers over base equipment specifications.
For Market Incumbents: Deploy semiconductor fabrication expertise transfer as the anchor lever for stereolithography precision leadership. Incumbents must deepen backward integration into titanium powder processing to secure implant-grade material supply against Chinese sponge export controls. Channel control through localized service center density in Singapore and Australia defends position against European 4D printing system entrants facing TGA recertification barriers.
For New Entrants and Emerging Players: Hospital procurement committees represent the most penetrable channel partner type for digital thread platform vendors without legacy equipment installed bases. New entrants should target Australia's import-constrained hospital networks where TGA alignment with MDR-equivalent frameworks blocks European competitors. White space concentrates in middleware development for legacy CAD integration at India's mid-tier automotive OEMs. A software-first go-to-market angle bypasses capital-intensive equipment manufacturing requirements.
For Investors and Strategic Acquirers: Consolidation pressure builds where dual-certification capabilities span China's MIIT GB standards, Japan's METI-coordinated JIS pathways, and South Korea's MFDS biocompatibility requirements. Long-term viability favors full-service digital thread providers with captive qualification expertise across multiple regulatory jurisdictions. Acquisition target archetypes include stereolithography equipment specialists with semiconductor heritage and 4D material programming R&D teams. The signal to watch is METI-JIS harmonization progress compressing medical device additive manufacturing approval timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Partnership | Accelerates market access across MIIT, METI, and MFDS jurisdictions for equipment vendors. |
| Digital Thread Platform Integration | Captures hospital procurement committee preference for service-bundled vendor relationships in Seoul. |
| Semiconductor Expertise Transfer | Leverages Samsung Electronics precision capabilities into stereolithography equipment resolution leadership. |
| 4D Material Programming R&D | Addresses workforce shortages constraining shape-memory polymer deployment in Tokyo medical device clusters. |
| Localized Service Network Expansion | Defends industrial polymer printing share against Stratasys through Singapore-Australia density. |
Study Parameters
Coverage spans China, Japan, South Korea, Australia, and India, with primary inputs from each national cluster triangulated against secondary validation. The research combines structured interviews with hospital procurement managers, biomedical engineers at tertiary facilities, additive manufacturing equipment procurement leads at automotive Tier 1 suppliers, and regulatory affairs specialists navigating MIIT GB standards. Secondary sources include MIIT additive manufacturing safety filings, METI JIS certification pathway documentation, MFDS biocompatibility guidance releases, and customs records tracking titanium powder trade flows. Bottom-up equipment shipment analysis and top-down healthcare capital expenditure surveys provide cross-verification.
Granularity-level modeling disaggregates revenue across 3D printing hardware, 4D programmable materials, software solutions, and printing materials, with further splits by stereolithography, Fused Deposition Modeling, Digital Light Processing, and Material Jetting technology categories. End-use segmentation captures medical devices, aerospace prototyping, automotive, and prototyping applications. CAGRs derive from equipment replacement cycle analysis, hospital procurement budget trajectories, and regulatory approval velocity assumptions. Industry-specific inputs include semiconductor fabrication capacity transfer rates into precision equipment manufacturing and shape-memory polymer pilot program expansion timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MIIT-JIS-MFDS regulatory harmonization progress, titanium powder supply disruptions, and 4D material programming workforce development velocity. Forecasts reflect documented assumptions regarding certification timeline compression, hospital procurement centralization trends, and aerospace-to-medical device R&D budget reallocation patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Technology
3D Scanning Market
3D Technology
3D Photogrammetry Software Market
3D Technology
North America 3D 4D Technology Market
3D Technology
Global 3D Rendering Service Market
3D Technology
Europe 3D 4D Technology Market
3D Technology
3D Reconstruction Market
3D Technology
Mobile 3D Market
3D Technology
3D Printing CAD Software Market
3D Technology
Glasses Free 3D Tvs Market
3D Technology
Global 3D Mapping and 3D Modeling Market
3D Technology
Global 3D Architecture Software Market
3D Technology
3D Scanner Market
3D Technology
3D CAD Market
3D Technology
Smartphone 3D Camera Market
3D Technology
3D Simulation Software Market
3D Technology
Global 3D 4D Technology Market