
 Contactless 3D Laser Scanner Market | 2026-2036
Contactless 3D Laser Scanner Market Size, Share, and Industry Trends Forecast 2026-2036
Contactless 3D Laser Scanner Market Insights
Aftermarket service revenue is tilting toward software subscription and recalibration contracts as hardware margins compress. Hexagon AB leverages its metrology software stack to sustain recurring income from installed scanner bases. FARO Technologies anchors its competitive position through channel control in North American industrial distribution. RIEGL Laser Measurement Systems specializes in long-range terrestrial scanning for mining and infrastructure survey applications.
Contactless 3D laser scanners employ non-contact optical triangulation, time-of-flight, or phase-shift measurement principles to capture dense point clouds with micron to millimeter precision without physical probe contact. These instruments serve quality assurance, reverse engineering, and dimensional verification functions across discrete manufacturing and built-environment workflows. Handheld scanner deployments dominate field-based architecture and heritage documentation where portability constrains stationary platform adoption. Phase shift technology occupies the fastest-expanding margin pool in automated inline inspection cells serving automotive powertrain manufacturing. Mobile scanner integration with SLAM algorithms is displacing total station methods in construction progress monitoring.
The EU Machinery Directive and CE marking requirements enforce electromagnetic compatibility and laser safety classifications for scanner deployment in European industrial environments. FDA 21 CFR Part 820 quality system regulations shape calibration traceability standards for contactless scanners used in medical device dimensional verification. China's GB standards and SAMR metrology certification create compliance thresholds for imported scanning equipment. Stakeholders must monitor evolving interoperability protocols between point cloud processing platforms and building information modeling ecosystems.
Market Dynamics
Phase-shift measurement systems are capturing the fastest-expanding margin pool in automated inline inspection cells, compressing hardware margins and forcing vendors toward software subscription and recalibration contracts for recurring revenue defense.
Growth Catalysts
- EU Machinery Directive:CE marking and electromagnetic compatibility mandates for industrial laser safety classifications are accelerating replacement cycles in German and French manufacturing facilities.
- Time-of-flight adoption:Aerospace manufacturers in Germany and the United States are expanding procurement for turbine blade inspection applications requiring micron-level precision.
- SLAM algorithm integration:Mobile scanner deployments are displacing total station methods in construction progress monitoring across California's defense-aerospace cluster.
Market Restraints
- Input cost volatility:Precision optical components and laser diode supply concentrate in East Asian foundries, exposing European and North American integrators to freight and tariff shocks.
- Technical limitation:Time-of-flight systems struggle with surface reflectivity variations on polished medical implants, restricting deployment in FDA-regulated device fabrication.
- Regulatory friction:China's GB standards and SAMR metrology certification create multi-month approval delays for imported scanning equipment.
Strategic Opportunities
- Underpenetrated geography:India's industrial corridor shows nascent demand for heritage documentation and infrastructure survey applications using handheld platforms.
- Technology convergence:Integration of SLAM algorithms with phase-shift hardware is enabling real-time point cloud registration without external positioning infrastructure.
- Regulatory tailwind:FDA 21 CFR Part 820 quality system regulations are mandating calibration traceability standards that favor vendors with embedded metrology software stacks.
Industry Challenges
- Skill gap in point cloud processing:Shortage of technicians trained in mesh optimization and dimensional verification workflows constrains deployment velocity in automotive powertrain cells.
- Certification timeline compression:CE marking and FDA device traceability requirements are extending validation periods for new scanner platforms by 40-60 percent.
- Integration complexity:Interoperability gaps between proprietary point cloud formats and building information modeling ecosystems force custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contactless 3D Laser Scanner Market |
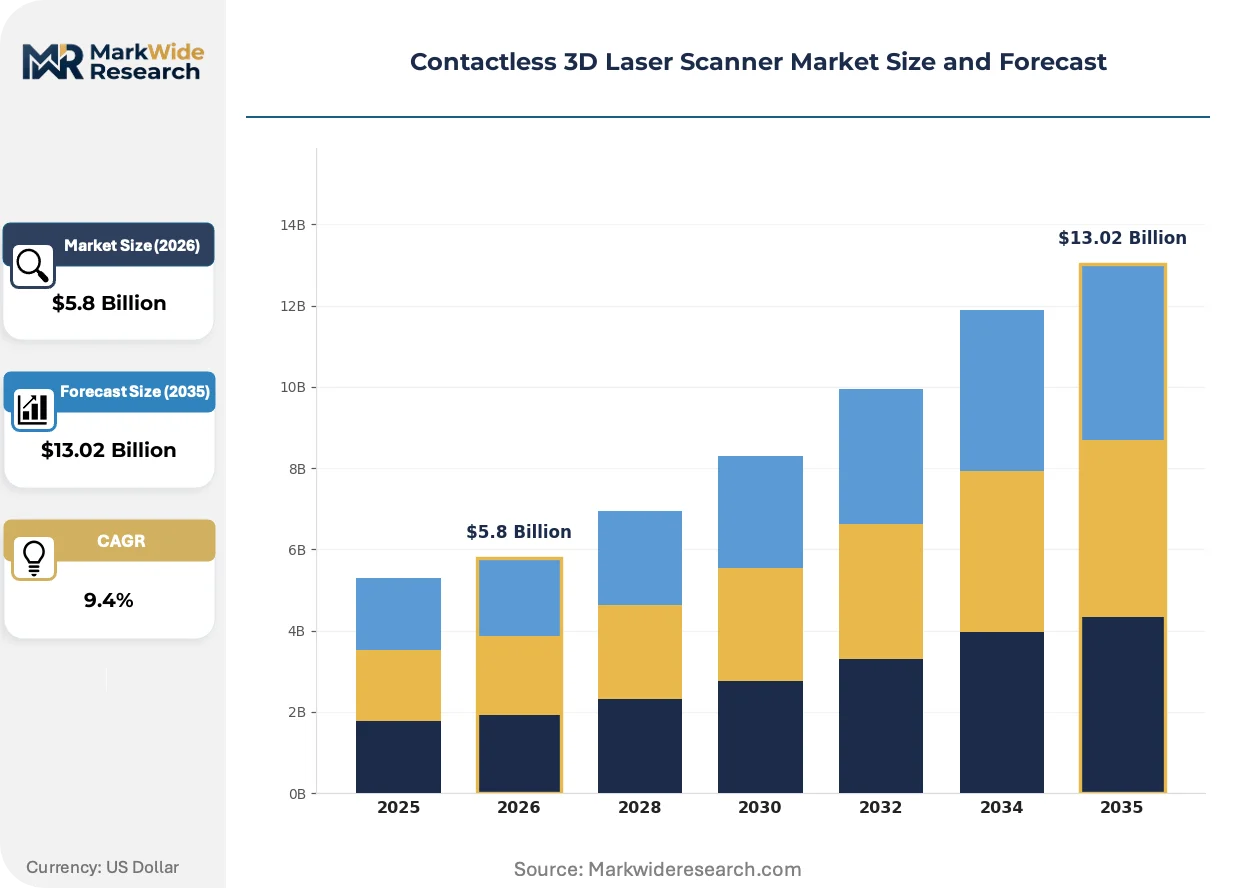
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $13.02 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Scanner, Stationary Scanner, Desktop Scanner, Mobile Scanner Application: Architecture, Construction, Heritage Preservation, Virtual Reality End User: Manufacturing, Education, Healthcare, Entertainment Technology: Time-of-Flight, Phase Shift, Triangulation, Structured Light |
| Companies Covered | Hexagon AB, FARO Technologies, Creaform, Carl Zeiss AG, Nikon Corporation, Trimble Inc., Topcon Corporation, RIEGL Laser Measurement Systems, Leica Geosystems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contactless 3D Laser Scanner Market Trends and Innovations
Software-defined measurement workflows and algorithmic point cloud processing are compressing hardware differentiation and tilting competitive advantage toward vendors with captive metrology software stacks.
Phase-shift technology is virtualizing quality assurance workflows in automotive powertrain manufacturing by enabling sub-100-micron inspection without physical fixturing. Tier-one suppliers in Bavaria's industrial corridor are deploying these systems at line speed, eliminating offline CMM bottlenecks. The technology is virtualizing dimensional verification from a discrete metrology function into an inline process control layer.
EU Machinery Directive laser safety classifications and electromagnetic compatibility mandates are reshaping product architecture decisions for European deployment. Scanner OEMs must now engineer dual-use platforms satisfying both industrial automation and heritage documentation use cases under unified certification frameworks. Medical device fabricators face the strictest compliance burden as FDA 21 CFR Part 820 traceability requirements converge with CE marking obligations.
Aftermarket service unbundling is fragmenting buyer-vendor relationships as hardware margins compress and recalibration contracts displace capital purchase models. Industrial distributors in North America are losing attachment revenue to direct software subscription channels. This pattern is most visible in California's defense-aerospace cluster, where prime contractors now specify multi-year calibration service levels in initial procurement tenders.
Contactless 3D Laser Scanner Market Segmentation
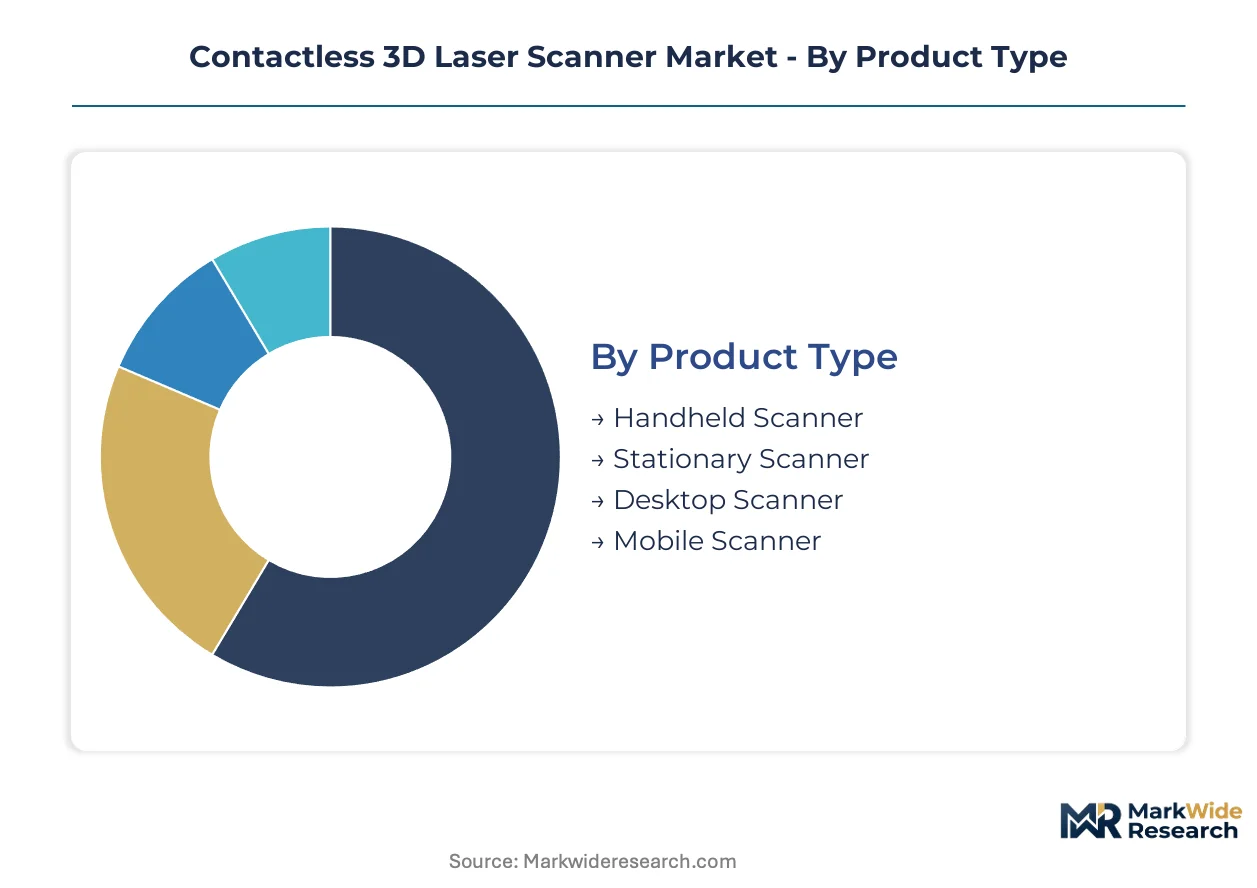
Segmentation in contactless 3D laser scanning reveals divergent hardware architectures and deployment contexts that shape vendor R&D allocation. Each dimension—product form factor, application environment, end-user vertical, and underlying measurement principle—carries distinct margin profiles and certification requirements.
Product Type:
The use-case spectrum spans field portability demands against precision requirements in controlled factory environments.
- Handheld Scanner:Battery-powered units with integrated inertial measurement units enable single-operator capture in confined spaces. Heritage documentation teams in Bavaria deploy these for cathedral façade surveys where scaffolding access is restricted. Battery thermal management under EU Machinery Directive electromagnetic compatibility rules is extending product development cycles.
- Stationary Scanner:Fixed-coordinate systems mounted on granite surface plates achieve sub-10-micron repeatability for turbine blade inspection. Aerospace manufacturers in Germany anchor automated cells with these platforms, though floor space constraints in legacy facilities limit retrofit adoption.
- Desktop Scanner:Compact enclosures with automated turntables target dental implant and jewelry workflows. The compact footprint suits university maker spaces and small-batch medical device fabricators.
- Mobile Scanner:Vehicle-mounted systems with SLAM algorithms displace total station methods in California highway corridor surveys. Integration complexity with legacy GIS platforms constrains deployment velocity.
The dominant share belongs to stationary systems, while mobile configurations are closing the gap fastest.
Application:
Cost tier differentiation separates capital-intensive industrial metrology from budget-constrained cultural heritage workflows.
- Architecture:As-built documentation for building information modeling drives demand for millimeter-accurate point clouds. Firms in California's defense-aerospace cluster specify scanners with direct Revit interoperability.
- Construction:Progress monitoring and earthwork volume calculations favor mobile platforms with real-time registration. German infrastructure contractors face CE marking compliance for laser safety classifications on job sites.
- Heritage Preservation:Non-contact capture of fragile artifacts and monuments requires low-power laser classifications. Bavarian museum networks are standardizing on handheld units for digitization campaigns.
- Virtual Reality:Photorealistic environment scanning for immersive content creation prioritizes color texture fidelity over dimensional precision. Entertainment studios in Los Angeles drive specification for integrated photogrammetry.
Construction applications command the highest hardware expenditure per deployment, whereas heritage preservation shows the steepest expansion trajectory in unit volumes.
End User:
Customer type determines procurement authority structures and service contract attachment rates.
- Manufacturing:Automotive powertrain suppliers in Bavaria deploy phase-shift systems at line speed for inline dimensional verification. FDA-regulated medical device fabricators impose calibration traceability requirements that favor vendors with embedded metrology software.
- Education:University engineering programs and technical colleges generate recurring demand for training-grade equipment. Budget constraints favor desktop and entry-level handheld configurations.
- Healthcare:Custom orthotic fabrication and surgical planning applications require biocompatible scanning environments. German clinics navigate both CE marking and DIN medical device standards.
- Entertainment:Film production and game development studios prioritize capture speed and texture resolution. California-based visual effects houses drive demand for multi-sensor fusion platforms.
Manufacturing retains the dominant procurement value, with healthcare climbing fastest as FDA traceability mandates deepen scanner integration into quality systems.
Technology:
Measurement principle selection trades off range, precision, and surface material compatibility.
- Time-of-Flight:Pulsed laser systems measure distance via photon return timing, enabling 100-meter-plus range for mining and infrastructure survey. Aerospace manufacturers in Germany and the United States specify these for large turbine casting inspection.
- Phase Shift:Continuous-wave interferometry achieves sub-100-micron precision at shorter ranges. Automotive powertrain manufacturers favor this technology for automated inline cells where speed dominates absolute accuracy.
- Triangulation:Stereo camera-laser arrangements suit high-resolution scanning of small objects. Jewelry and dental applications in Switzerland leverage these for micron-level surface capture.
- Structured Light:Projected pattern deformation enables rapid full-field capture without mechanical scanning. Consumer-facing entertainment and education markets show rising adoption.
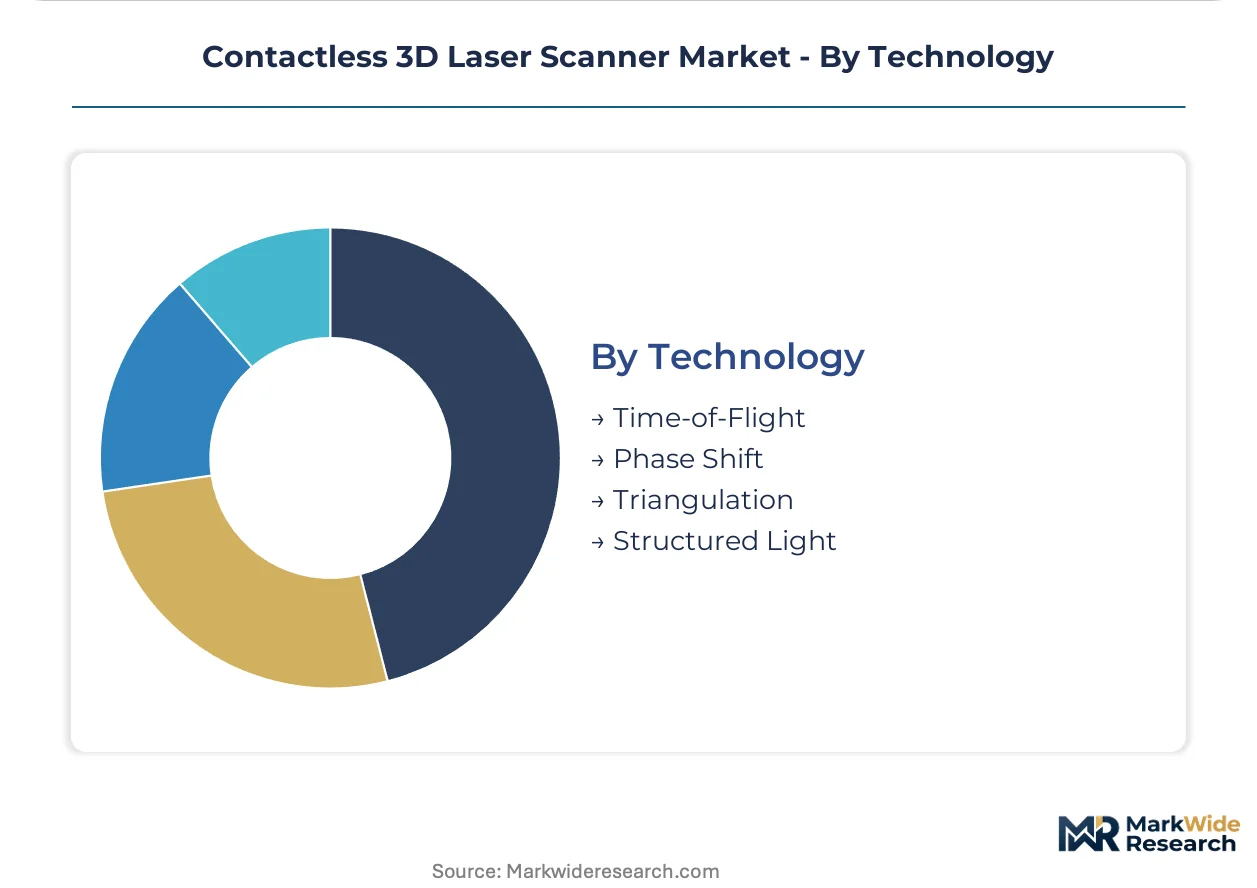
Phase shift holds the dominant installed base, while structured light is gaining share fastest in cost-sensitive volume segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German aerospace manufacturers demonstrate the lowest price elasticity, absorbing premium time-of-flight systems for turbine blade inspection, while Indian heritage documentation teams operate at the highest sensitivity, prioritizing handheld portability over precision specifications.
United States
California's defense-aerospace cluster drives concentrated procurement of mobile scanners with SLAM algorithms for construction progress monitoring. FDA 21 CFR Part 820 quality system regulations mandate calibration traceability standards that deepen software attachment rates. Prime contractors in the San Diego-Tijuana corridor now specify multi-year recalibration service levels in initial tenders, compressing distributor margins.
Germany
Bavaria's industrial corridor anchors European demand for phase-shift systems in automotive powertrain inline inspection cells. EU Machinery Directive CE marking and electromagnetic compatibility rules extend product development cycles for dual-use platforms. Aerospace manufacturers in Munich and Augsburg expand time-of-flight procurement for large turbine casting verification, eliminating offline CMM bottlenecks.
China
Dual carbon goals and infrastructure digitization accelerate mobile scanner deployment for mining survey and highway corridor documentation. SAMR metrology certification and GB standards create multi-month approval delays for imported equipment, favoring domestic assembly partnerships. Yangtze River Delta integrators face input cost volatility from concentrated East Asian optical component supply.
India
Nascent demand for heritage documentation and infrastructure survey applications concentrates in state archaeology departments and private conservation firms. BIS certification requirements for imported metrology equipment remain less stringent than EU or US equivalents, enabling faster deployment of training-grade handheld units. Mumbai and Delhi conservation teams prioritize battery thermal management and confined-space portability over absolute precision.
Japan
METI industrial digitization initiatives accelerate phase-shift adoption in precision manufacturing workflows serving automotive and electronics supply chains. JIS standards for laser safety classifications align closely with EU Machinery Directive frameworks, simplifying dual-market product architecture. Nagoya-based tier-one suppliers deploy automated inline cells at line speed, virtualizing dimensional verification into process control layers.
Contactless 3D Laser Scanner Market Competitive Landscape
Metrology software specialists and hardware-anchored distributors split the market along recurring-revenue versus capital-sale fault lines. The vendor base concentrates into three strategic archetypes: integrated platform providers with captive software stacks, distribution-controlled hardware specialists, and long-range terrestrial scanning pure-plays. Consolidation pressure is accelerating through M&A activity targeting point cloud processing capabilities and direct service channel buildouts.
Among Nordic-anchored integrated platform providers, Hexagon AB exemplifies the software-centric archetype leveraging metrology stacks to sustain recurring income from installed bases. FARO Technologies occupies a position within the North American distribution-controlled tier, while RIEGL Laser Measurement Systems represents the long-range terrestrial specialization anchored in Austrian laser measurement engineering. These three patterns illustrate how competitive positioning increasingly depends on service contract attachment rather than hardware differentiation alone.
| Leading Market Players |
|---|
| Hexagon AB |
| FARO Technologies |
| Creaform |
| Carl Zeiss AG |
| Nikon Corporation |
| Trimble Inc. |
| Topcon Corporation |
| RIEGL Laser Measurement Systems |
| Leica Geosystems |
| Others |
Pricing and Supply Chain Analysis
Tariff exposure on precision optical components concentrates in East Asian foundries and compresses margin pools across European and North American integrators, forcing pricing stratification across premium, standard, and economy tiers while reshaping sourcing footprints toward dual-vendor strategies.
Pricing Analysis
Software subscription and recalibration contracts drive lifetime value as hardware margins compress across all tiers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated metrology stacks from training-grade handheld units, with certification grade and after-sales service bundling as primary differentiation levers. Price erosion runs through mid-tier stationary systems as phase-shift technology commoditizes. Heritage documentation teams in India exhibit highest price sensitivity, while German aerospace manufacturers absorb premium time-of-flight systems with minimal elasticity.
Supply Chain Analysis
Export-control restrictions on high-precision laser diodes and interferometric sensors limit flows from German and Japanese specialty manufacturers to Chinese integrators. Component sourcing draws from Taiwan for CMOS sensors, Germany for precision optics, and Japan for laser diodes. Single-source vulnerability concentrates in EUV-grade optical coatings. Distribution runs through North American industrial distributors losing attachment revenue to direct software channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Contactless 3D laser scanning is approaching a platform-economics inflection where point cloud processing interoperability determines competitive survival, with Revit and BIM ecosystem integration emerging as the decisive ecosystem shift.
For Market Incumbents: Insulate recurring revenue streams by deepening embedded metrology software stacks and capturing calibration traceability mandates from FDA and EU Machinery Directive compliance. Threats from SLAM-algorithm pure-plays and open-source point cloud processors demand defensive certification investments and channel control consolidation in California's defense-aerospace cluster. For New Entrants and Emerging Players: Pursue India's heritage documentation corridor and construction progress monitoring segments where price sensitivity and portability requirements favor training-grade handheld platforms over precision-validated systems. A direct-to-conservation-firm go-to-market angle bypasses entrenched industrial distributor relationships. For Investors and Strategic Acquirers: Point cloud processing software specialists with BIM interoperability capabilities represent the highest-conviction acquisition archetype for long-term viability across the next decade. Watch for inflection signals in multi-year calibration service level specifications appearing in initial procurement tenders from prime contractors.| Strategic Initiative | Industry Significance |
|---|---|
| Software Stack Integration | Captures FDA 21 CFR Part 820 calibration traceability mandates deepening recurring revenue. |
| SLAM Algorithm Development | Displaces total station methods in California construction progress monitoring applications. |
| CE Marking Acceleration | Compresses product development cycles for dual-use platforms under EU Machinery Directive. |
| Heritage Documentation Partnership | Opens India's state archaeology department procurement channels for handheld platforms. |
| Metrology Certification Investment | Creates compliance barriers against low-cost structured light entrants in medical device fabrication. |
Research Methodology
Cross-validation between primary interviews with metrology equipment manufacturers and secondary validation through FDA 510(k) filings anchors the qualitative findings. Stakeholder roles include quality assurance directors at automotive powertrain suppliers, biomedical engineers at FDA-regulated device fabricators, heritage conservation technologists at Bavarian museum networks, and aftermarket service heads at North American industrial distributors. Secondary sources comprise EU Machinery Directive compliance databases, SAMR metrology certification records, SEC 10-K equipment revenue disclosures, and customs trade data on optical component flows. Bottom-up scanner deployment tallies triangulate against top-down manufacturing value-chain estimates.
Calibration against historical phase-shift and time-of-flight adoption curves refines the analytical framework across the projection horizon. Segmentation dimensions span product form factor, measurement principle, end-use vertical, and regional regulatory cluster. CAGRs derive from installed base replacement cycles and inline inspection cell penetration rates. Industry-specific inputs include turbine blade inspection procurement patterns from German aerospace manufacturers and SLAM algorithm integration timelines from California construction monitoring firms.
Sensitivities concentrate around export-control tightening on precision optics, EU Machinery Directive laser safety reclassifications, and FDA traceability mandate expansion. Forecasts reflect documented assumptions on technology substitution rates and certification timeline compression. Material shifts in optical component tariff structures or SAMR approval timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Technology
North America 3D 4D Technology Market
3D Technology
Global 3D Mapping and 3D Modeling Market
3D Technology
3D CAD Market
3D Technology
3D Rendering Market
3D Technology
APAC 3D 4D Technology Market
3D Technology
Spatial Computing Market
3D Technology
3D Geospatial Technologies Market
3D Technology
Visualization and 3D Rendering Software Market
3D Technology
Global 3D Rendering Service Market
3D Technology
APAC 3D Telepresence Market
3D Technology
Smartphone 3D Camera Market
3D Technology
Middle East and Africa 3D 4D Technology Market
3D Technology
Latin America 3D 4D Technology Market
3D Technology
Mobile 3D Market
3D Technology
Global 3D 4D Technology Market
3D Technology
Generative Design Market