
 Digital Graphic Printing Market | 2026-2036
Digital Graphic Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Graphic Printing Market Outlook
China is fragmenting as domestic manufacturers expand UV-curable inkjet capacity in Dongguan and Shenzhen. HP Inc. leverages its thermal inkjet patent portfolio to sustain North American service revenue. Canon Inc. anchors Japanese precision-engineering demand through its imagePROGRAF production lines. Durst Phototechnik AG competes in superwide-format industrial segments with single-pass architectures.
Digital graphic printing encompasses non-contact image deposition systems that apply aqueous, solvent, UV-curable, or latex inks onto vinyl, fabric, paper, or plastic substrates at resolutions typically exceeding 600 dpi for commercial visual communication. Inkjet printers dominate volume shipments due to lower capital thresholds and substrate versatility, while UV printers command premium positioning through instant-cure chemistry that eliminates drying infrastructure. Advertising applications absorb the largest installed base, though packaging represents the fastest-growing demand pool as brand owners pursue shorter run lengths and variable-data customization.
EPA VOC regulations and REACH substance restrictions are forcing ink reformulation toward low-migration UV and water-based chemistries, reshaping R&D allocation across formulation suppliers and OEMs. China's GB standards and the EU Green Deal both mandate reduced environmental footprints in printing operations, tightening market access for non-compliant equipment. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded technology investments.
Market Dynamics
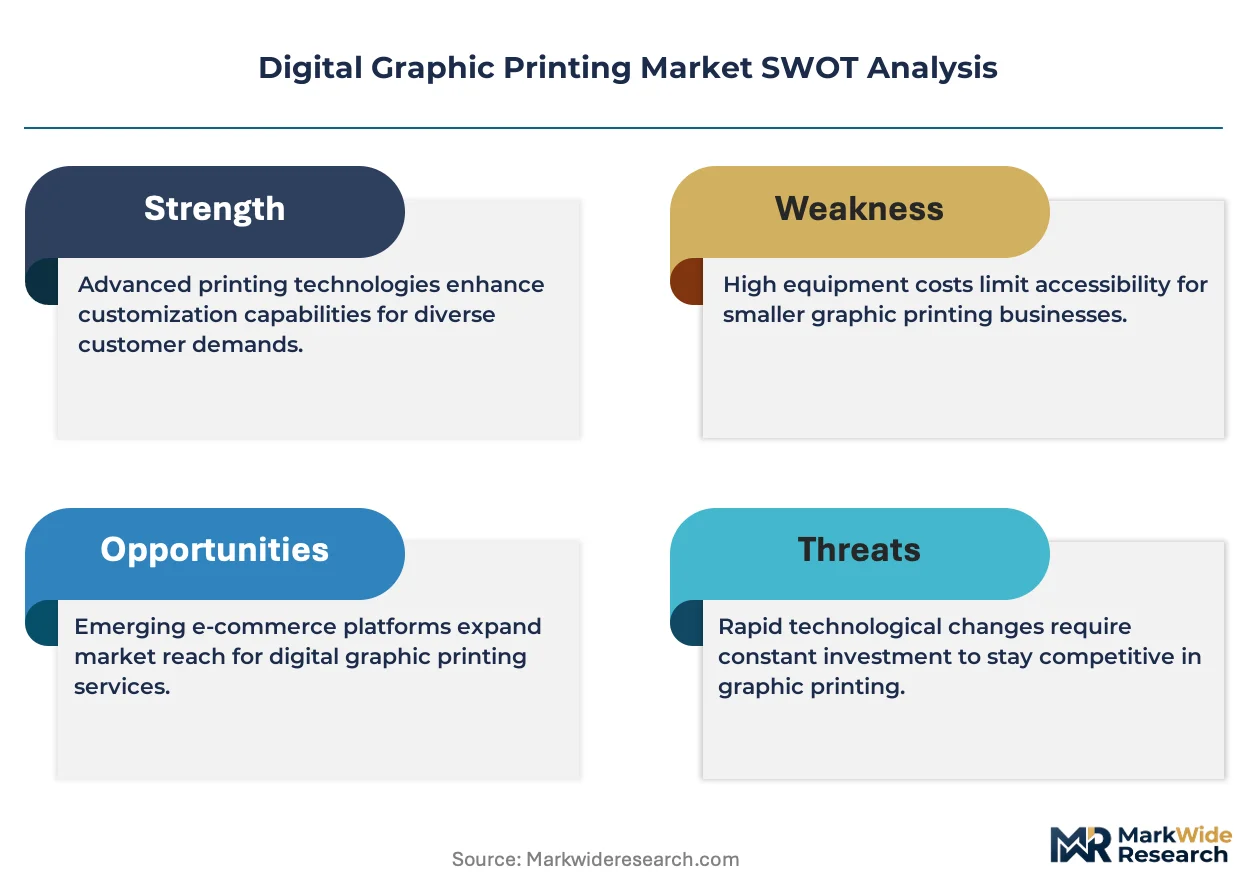
UV-curable ink chemistry is compressing solvent-based equipment lifecycles as EPA VOC thresholds tighten and brand owners demand instant-cure workflows. This single force cascades through formulation R&D, OEM hardware roadmaps, and print-service procurement criteria.
Growth Catalysts
- REACH substance restrictions:European ECHA mandates are accelerating ink reformulation toward low-migration UV and water-based chemistries, forcing equipment upgrades across commercial print shops.
- Wide-format inkjet adoption:Advertising agencies in China are deploying superwide systems for outdoor signage campaigns, absorbing capacity from traditional screen-printing operations.
- Packaging run-length compression:Brand owners across food and beverage verticals are shifting from flexographic long runs to digital short runs with variable-data customization.
Market Restraints
- Pigment and photoinitiator cost volatility:Raw material concentration among Chinese specialty chemical suppliers creates input price instability for UV ink formulators.
- Capital intensity of single-pass architectures:Industrial UV printer investments exceed aqueous systems by multiples, freezing out mid-tier print-service providers.
- Technical limitation in flexible packaging:UV-curable adhesion on low-surface-energy films remains inferior to solvent-based alternatives for high-performance barrier applications.
Strategic Opportunities
- India's PLI scheme for manufacturing:Domestic production incentives are attracting UV printer assembly investments to serve South Asian packaging demand.
- E-commerce corrugated customization:On-demand box printing with digital inkjet is penetrating fulfillment center networks previously served by pre-printed substrates.
- EU Green Deal operational mandates:Carbon footprint disclosure requirements are favoring digital workflows over energy-intensive analog alternatives in European commercial print.
Industry Challenges
- Color management specialist scarcity:ICC profile development and substrate-specific calibration expertise is concentrating among aging technician cohorts.
- Certification timeline compression:Migration testing for food-contact packaging under EFSA and FDA frameworks is extending product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Graphic Printing Market |
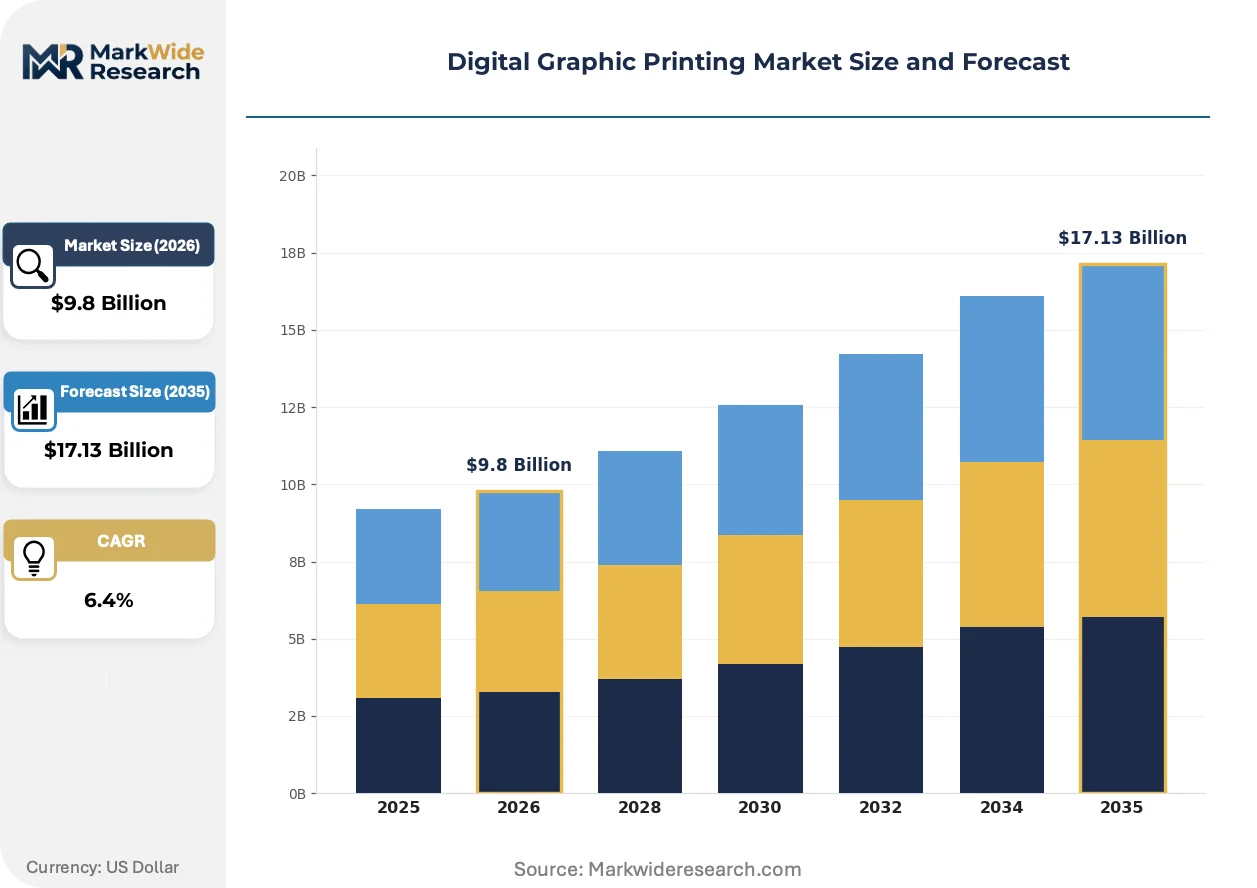
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inkjet Printers, Laser Printers, UV Printers, Eco-Solvent Printers Media Type: Vinyl, Fabric, Paper, Plastic Application: Advertising, Packaging, Signage, Textile End User: Retailers, Manufacturers, Advertising Agencies, Educational Institutions |
| Companies Covered | HP Inc., Canon Inc., Xerox Holdings Corporation, Ricoh Company Ltd., Seiko Epson Corporation, Konica Minolta Inc., Durst Phototechnik AG, Landa Corporation Ltd., Fujifilm Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Graphic Printing Market Strategic Shifts
Single-pass UV inkjet architectures are compressing cost-per-print economics while water-based latex systems expand substrate compatibility. These parallel developments are fragmenting equipment vendor strategies across speed-versus-versatility trade-offs.
High-speed single-pass UV systems are rendering obsolete multi-pass flatbed workflows in industrial decoration segments. Automotive and appliance manufacturers are adopting these architectures for direct-to-object customization at line speeds. The technology is rendering obsolete drying infrastructure investments and compressing floor-space requirements in high-volume operations.
EPA VOC emission thresholds are forcing solvent-based ink phase-outs across US commercial print facilities. Formulation suppliers are redirecting R&D toward water-based pigment dispersions with near-zero volatile content. Wide-format signage shops in California and Texas are most affected, accelerating equipment refresh cycles ahead of compliance deadlines.
Brand-owner procurement teams are unbundling hardware acquisition from consumable supply agreements. Print-service providers are responding with equipment-agnostic ink sourcing strategies that prioritize total cost of ownership over bundled vendor contracts. This pattern is most visible in European commercial print, where multi-vendor shop floors are becoming standard.
Digital Graphic Printing Market Segmentation
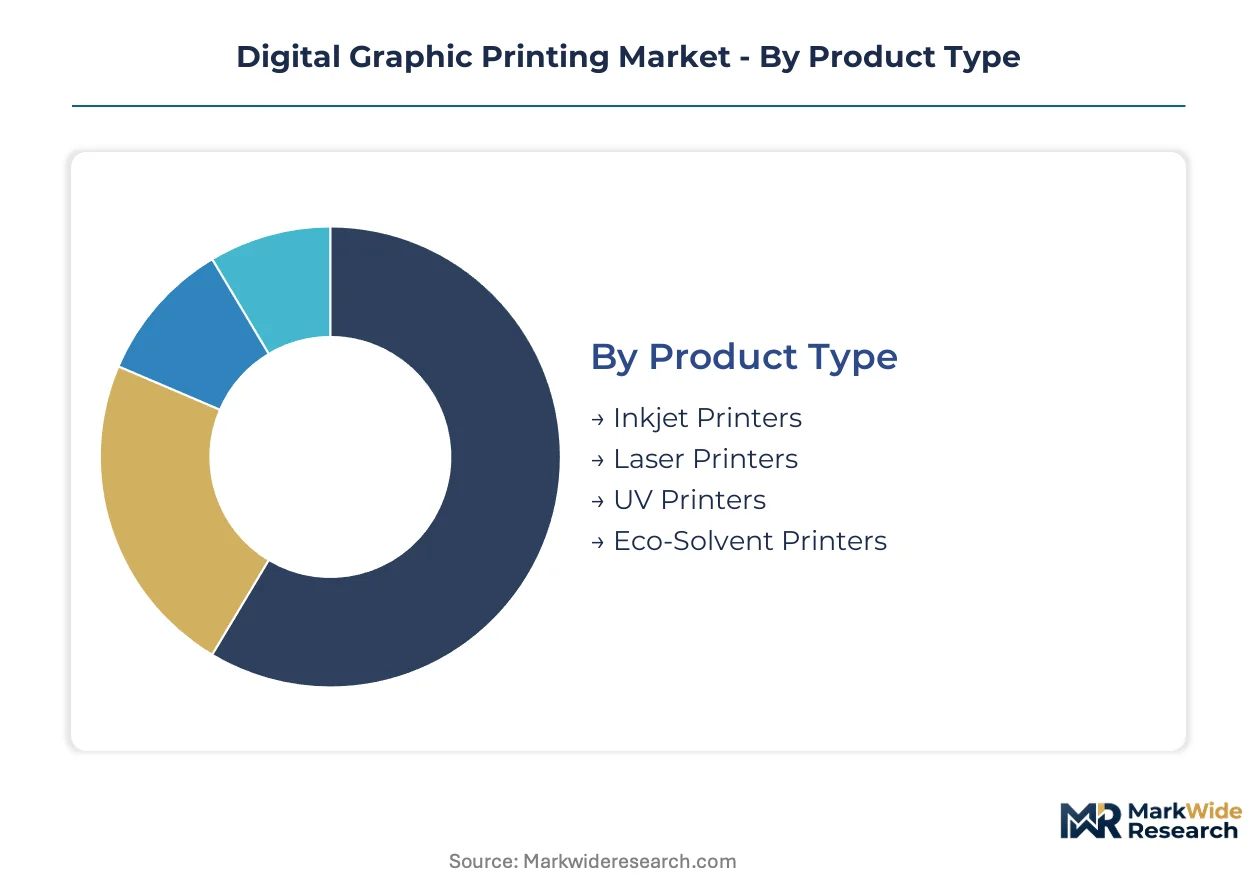
Segmentation in digital graphic printing reveals how substrate versatility, ink chemistry, and end-use requirements fragment procurement decisions across equipment categories. Understanding these divisions exposes where technology investments concentrate and where margin compression threatens vendor positioning.
Product Type:
Use-case spectrum spans entry-level aqueous systems for office graphics to industrial single-pass UV architectures for automotive decoration.
- UV Printers:Instant-cure photopolymer chemistry eliminates drying infrastructure and enables direct-to-object printing on rigid substrates. Demand clusters in Guangdong province automotive and appliance manufacturers seeking line-speed customization. EPA VOC thresholds are accelerating solvent-to-UV migration in US commercial print facilities.
- Inkjet Printers:Drop-on-demand thermal or piezoelectric deposition dominates volume shipments through lower capital thresholds and substrate adaptability. Advertising agencies in China absorb the largest installed base for wide-format signage production. Thermal inkjet patent portfolios sustain North American service revenue for established OEMs.
- Laser Printers:Electrophotographic imaging delivers precision at lower operating costs for high-volume document and short-run graphic applications.
- Eco-Solvent Printers:Mild-solvent formulations bridge aqueous and aggressive solvent chemistries for outdoor durability with reduced ventilation requirements.
The dominant share belongs to Inkjet Printers, while UV Printers is closing the gap fastest.
Media Type:
Substrate selection dictates ink compatibility, curing infrastructure, and finished-product durability specifications.
- Vinyl:Calendered and cast PVC formulations dominate outdoor signage and vehicle wrap applications through weather resistance and dimensional stability. REACH substance restrictions are forcing phthalate-free plasticizer migrations in European supply chains. California and Texas wide-format shops face compressed equipment refresh cycles ahead of compliance deadlines.
- Fabric:Polyester and cotton textiles enable soft signage, exhibition graphics, and direct-to-garment production with dye-sublimation or pigment ink compatibility. On-demand textile printing is penetrating European commercial print networks previously served by screen-printing operations.
- Paper:Coated and uncoated stocks retain cost advantages for indoor graphics, packaging prototypes, and commercial document production.
- Plastic:PET, PP, and polycarbonate substrates serve rigid packaging, point-of-purchase displays, and industrial labeling with specific surface energy requirements for ink adhesion.
Vinyl commands the largest volume position, though Fabric is expanding most quickly as soft signage displaces rigid alternatives.
Application:
End-use differentiation separates high-volume standardized production from customized short-run workflows.
- Advertising:Billboards, transit graphics, and point-of-sale materials absorb the historical installed base through campaign-driven refresh cycles. China's industrial clusters in Zhejiang province drive domestic equipment procurement for outdoor signage campaigns.
- Packaging:Corrugated, folding carton, and flexible film applications represent the steepest expansion trajectory as brand owners compress run lengths and demand variable-data customization. E-commerce fulfillment center networks are adopting on-demand box printing with digital inkjet systems.
- Signage:Architectural and wayfinding graphics require weather durability and regulatory compliance for public installation.
- Textile:Apparel, home furnishings, and soft signage applications leverage dye-sublimation and direct-to-fabric technologies for design flexibility.
Advertising retains the dominant revenue share, while Packaging is gaining share fastest.
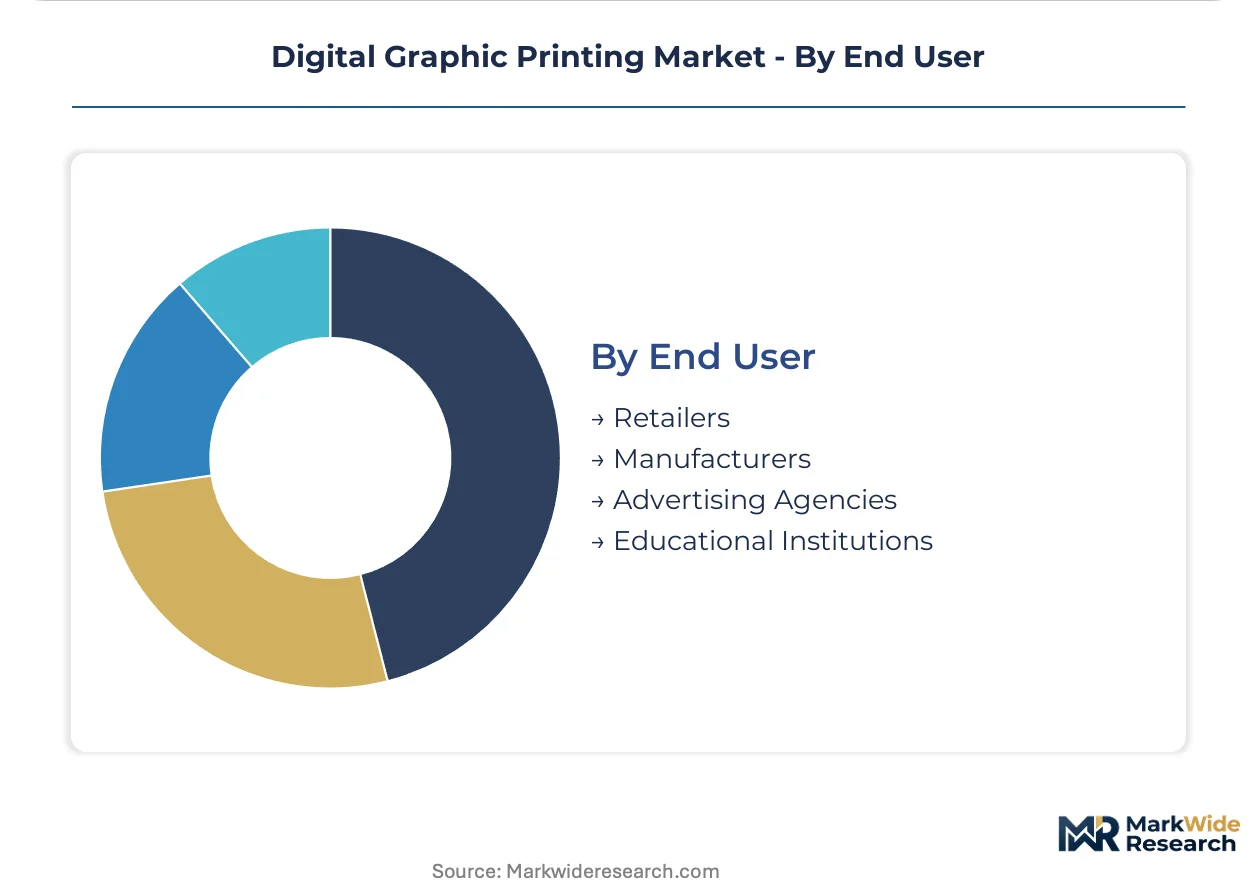
End User:
Procurement authority varies between brand-owner direct investment and outsourced print-service provider relationships.
- Advertising Agencies:Campaign-driven volume purchasers prioritize color consistency and rapid turnaround for client presentation materials. These organizations are deploying superwide-format systems for outdoor signage campaigns across Chinese metropolitan markets.
- Manufacturers:In-house decoration departments in automotive, appliance, and consumer goods sectors adopt single-pass UV architectures for direct-to-object customization at production line speeds. India's PLI scheme for manufacturing is attracting UV printer assembly investments to serve South Asian packaging demand.
- Retailers:In-store and e-commerce fulfillment operations require on-demand signage and customized packaging for promotional campaigns.
- Educational Institutions:Research facilities and campus print shops demand versatile systems for instructional materials and presentation graphics.
Advertising Agencies hold the largest procurement volume, while Manufacturers are closing the gap fastest through in-house production investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing concentrates in East Asian industrial corridors, while formulation chemistry and brand-owner demand distribute across North American and European regulatory jurisdictions. Chinese production clusters supply hardware to emerging print-service networks in South Asia and Southeast Asia. Regional differentiation stems from emission standards, packaging run-length requirements, and domestic industrial policy incentives.
United States
EPA VOC thresholds are accelerating solvent-to-UV equipment migrations across California and Texas wide-format shops. Brand owners in food and beverage verticals compress packaging run lengths, demanding variable-data customization capabilities. Midwestern fulfillment center networks adopt on-demand corrugated printing systems for e-commerce box customization.
Germany
REACH substance restrictions and ECHA mandates force ink reformulation toward low-migration UV chemistries across commercial print facilities. The EU Green Deal operational mandates favor digital workflows over analog alternatives in commercial decoration. Bavarian automotive manufacturers deploy single-pass UV architectures for direct-to-object production line customization.
China
Guangdong and Zhejiang province industrial clusters drive domestic equipment procurement for outdoor signage campaigns. GB standards and MEE environmental mandates tighten market access for non-compliant printing equipment. Dongguan and Shenzhen manufacturers expand UV-curable inkjet capacity to serve domestic and export demand.
India
PLI scheme production incentives attract UV printer assembly investments to serve South Asian packaging demand. Maharashtra and Gujarat packaging converters shift from flexographic long runs to digital short-run workflows. Domestic brand owners pursue shorter run lengths with variable-data customization for regional market differentiation.
Japan
METI industrial standards and precision-engineering requirements sustain demand for high-resolution production systems. Kanto region commercial print networks maintain premium positioning through color management specialization. Osaka-based manufacturers anchor domestic demand for imagePROGRAF-class production equipment.
Digital Graphic Printing Market Competitive Environment
Japanese precision-engineering specialists and German industrial-systems fabricators split the market across distinct technology vectors. The vendor base organizes around three strategic archetypes: thermal inkjet patent licensors, piezoelectric deposition specialists, and single-pass UV architecture developers. Competitive moves concentrate on equipment-agnostic ink sourcing strategies and geographic assembly expansion through production-linked incentive schemes.
Among Japanese-headquartered precision manufacturers, Canon Inc. and Seiko Epson Corporation exemplify the thermal and piezoelectric deposition archetypes respectively. HP Inc. occupies a position within the North American service-revenue tier, leveraging patent portfolios for sustained aftermarket positioning. Durst Phototechnik AG represents the European industrial-systems archetype, anchoring superwide-format segments through single-pass architectural development.
| Leading Market Players |
|---|
| HP Inc. |
| Canon Inc. |
| Xerox Holdings Corporation |
| Ricoh Company Ltd. |
| Seiko Epson Corporation |
| Konica Minolta Inc. |
| Durst Phototechnik AG |
| Landa Corporation Ltd. |
| Fujifilm Holdings Corporation |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Rotterdam maritime corridor's freight volatility compresses margins for UV ink formulators sourcing photoinitiators from Chinese specialty chemical clusters. This logistics cost instability feeds downstream into three-tier pricing structures that separate premium single-pass UV systems from mid-tier aqueous equipment and economy solvent-based alternatives.
Pricing Analysis
REACH substance restrictions dictate the pricing tier structure across European commercial print facilities. Three-tier pricing separates premium single-pass UV architectures from standard multi-pass flatbed systems and economy aqueous alternatives. Price differentiation rests on certification grade for food-contact compliance and volume scale of consumable offtake. Cost compression in mid-tier equipment is intensifying because brand owners unbundle hardware from ink supply agreements. Small-format print-service providers exhibit highest price sensitivity, while automotive manufacturers demonstrate lowest sensitivity due to line-speed customization requirements.
Supply Chain Analysis
Foxconn and Jabil Electronics hold contract-manufacturing capacity for industrial printer control systems and precision deposition heads. Component assembly concentrates in China, Taiwan, and Vietnam, while ink formulation draws from German and Japanese specialty chemical suppliers. Raw material dependencies include photoinitiators from Chinese suppliers, piezoelectric printheads from Japanese manufacturers, and precision linear motion systems from German fabricators. Single-source vulnerability in photoinitiator supply creates exposure to input price spikes. Distribution runs through authorized dealer networks for equipment and direct bulk contracts for consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as packaging run-length compression creates niche demand for mid-tier digital systems between industrial single-pass and entry-level aqueous categories.
For Market Incumbents: Insulate service revenue streams by deepening thermal inkjet patent licensing in North American markets and expanding certified technician networks for color management specialization. Threat from equipment-agnostic ink sourcing strategies demands consolidation of consumable supply agreements through performance-based contracting. Capacity addition in India's PLI-subsidized assembly corridors anchors geographic diversification against Chinese supply concentration. For New Entrants and Emerging Players: Build out regional service capabilities in South Asian packaging corridors where Maharashtra and Gujarat converters shift from flexographic to digital workflows. India's domestic production incentives create the most penetrable geography for UV printer assembly investments. Go-to-market angle centers on food-contact compliance certification bundled with variable-data customization training for brand-owner procurement teams. For Investors and Strategic Acquirers: EPA VOC threshold enforcement reshapes the acquisition landscape by accelerating solvent-to-UV equipment refresh cycles across California and Texas print facilities. Long-term viability favors targets with established low-migration UV formulation portfolios and single-pass architectural development capabilities. Signal to monitor: migration testing timeline compression under EFSA and FDA frameworks as indicator of regulatory compliance moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photoinitiator Supply | Captive sourcing from Chinese specialty chemical clusters reduces input price volatility for UV ink formulators. |
| Single-Pass UV Architecture Development | Line-speed customization capabilities at Guangdong automotive manufacturers displace multi-pass flatbed workflows. |
| Food-Contact Compliance Certification Investment | EFSA and FDA migration testing capabilities extend product launch cycles but create switching costs for brand owners. |
| Regional Assembly Expansion via PLI Schemes | Domestic production incentives in India attract UV printer investments to serve South Asian packaging demand. |
| Equipment-Agnostic Ink Sourcing Platform | Unbundled consumable procurement strategies prioritize total cost of ownership over bundled vendor contracts in European commercial print. |
Study Parameters
Cross-validation between equipment OEM technical documentation and formulation supplier R&D roadmaps anchors the qualitative findings. Primary interviews with print-service provider operations directors, brand-owner packaging procurement managers, ink formulation technical directors, and wide-format shop floor technicians combined with secondary validation from EPA enforcement databases, ECHA substance restriction registers, SEC equipment manufacturer filings, and Chinese customs trade data. Bottom-up installed base estimates and top-down addressable market calculations triangulate volume and value outputs.
Calibration against historical equipment shipment data and consumable offtake patterns shapes the projection framework across the analysis window. Segmentation dimensions span ink chemistry type, substrate compatibility tier, end-use application, and regional regulatory cluster. CAGRs derive from weighted average of equipment replacement cycles and consumable attach rate assumptions. Forecast inputs include VOC compliance deadline schedules and packaging run-length compression trajectories in food and beverage verticals.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese domestic manufacturers or accelerated EPA enforcement timelines would shift outcomes. Quarterly review of photoinitiator spot pricing and EFSA migration testing queue lengths is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Digital Franking Machine Market
Printing Technology
Dye-Sublimation Printing Machines Market
Printing Technology
Global Computer to Plate Printing System Market
Printing Technology
Global Barcode Printer Market
Printing Technology
Hardcopy Peripherals and Printing Consumables Market
Printing Technology
Global Web to Print Software Market
Printing Technology
Digital Printing Market
Printing Technology
Professional Printers Market
Printing Technology
Large Character Printers Market
Printing Technology
North America Commercial Printing Market
Printing Technology
Digital Fabric Printer Market
Printing Technology
Global Microprinting Market
Printing Technology
Print Equipment Market
Printing Technology
Card Printer Ribbons Market
Printing Technology
Computer-To-Plate and Computer-To-Press Systems Market
Printing Technology
Barcode Printers and Consumables Market