
 Global Architecture Design Software Market | 2026-2036
Global Architecture Design Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Architecture Design Software Market Foresight
Recurring subscription revenue from cloud-based collaboration modules is tilting margin pools away from perpetual desktop licenses. Autodesk Revit leverages its BIM ecosystem to anchor enterprise accounts across North America and Western Europe. Graphisoft ArchiCAD specializes in interoperability workflows that appeal to mid-sized European practices. Trimble SketchUp competes on accessibility, sustaining dominance among independent designers and early-stage concept development.
Architecture design software encompasses digital tools for creating, modifying, analyzing, and documenting building designs through parametric modeling, geometric constraint solving, and real-time rendering engines operating on 64-bit multi-threaded architectures. These platforms enable clash detection, energy performance simulation, and construction sequencing prior to physical ground-breaking. Building Information Modeling commands the deepest integration with engineering consultancies and construction companies, while AI Integration represents the fastest-expanding technology layer as generative design algorithms reduce iteration cycles. Visualization Tools occupy a mature margin pool where GPU-accelerated path tracing is becoming standard. Cloud-Based Solutions are displacing on-premise deployments among distributed project teams managing multi-site commercial complexes.
The EU Green Deal and F-Gas Regulation shape product requirements by mandating embodied carbon tracking and HVAC refrigerant lifecycle documentation within digital building models. The EPA's ENERGY STAR certification protocols and the IRA's building performance incentives in the United States drive demand for software with integrated energy analysis modules. Japan's METI building efficiency standards and China's GB standards for green construction documentation create compliance-driven procurement criteria across Asia-Pacific markets. Stakeholders must monitor which jurisdictions will mandate openBIM data exchange formats versus proprietary ecosystems, as this regulatory divergence will determine platform switching costs and vendor lock-in exposure.
Market Dynamics
Cloud-based BIM deployment is compressing license renewal cycles while embedding energy compliance modules directly into design workflows, forcing vendors to restructure revenue models around subscription attach rates rather than perpetual seat sales.
Growth Catalysts
- EU Green Deal embodied carbon mandates:France, Germany, and the Netherlands now require lifecycle carbon documentation in digital building models, compelling architects to upgrade software stacks for automated material tracking.
- Generative design algorithms:AI-powered spatial optimization reduces iteration cycles from weeks to hours, pulling mid-sized practices into premium subscription tiers for competitive parity.
- Japan METI building efficiency standards:Mandatory energy simulation for commercial structures above 2,000 square meters creates compliance-driven procurement in Tokyo, Osaka, and Yokohama.
Market Restraints
- GPU compute cost volatility:Real-time path tracing and AI inference workloads tether margin stability to NVIDIA data center pricing, squeezing smaller SaaS vendors.
- Cloud concentration risk:AWS, Azure, and Google Cloud host 78% of collaborative BIM instances, exposing architects to egress fee shocks and regional outage vulnerabilities.
- openBIM format friction:IFC schema version fragmentation between ISO 19650 implementations in the UK, Singapore, and Australia forces costly translation layer maintenance.
Strategic Opportunities
- India's Smart Cities Mission:100 urban agglomerations require digital twin documentation for infrastructure awards, creating first-mover advantage for vendors localizing Hindi-language interfaces.
- Retrofit energy modeling:Germany's Building Energy Act and France's RE2020 renovation mandates open software modules for existing stock analysis, a category underserved by new-construction-centric platforms.
- Edge rendering convergence:5G low-latency streaming plus local GPU virtualization enables tablet-native BIM review on construction sites, collapsing the hardware barrier for field teams.
Industry Challenges
- Computational design literacy:Parametric scripting proficiency remains scarce among licensed architects, forcing firms to hire separate computational designers or accept template-driven workflows.
- Multi-jurisdiction certification lag:Energy simulation engines require separate validation against ASHRAE 90.1, ISO 52016, and China's GB 50189, extending product launch timelines by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Architecture Design Software Market |
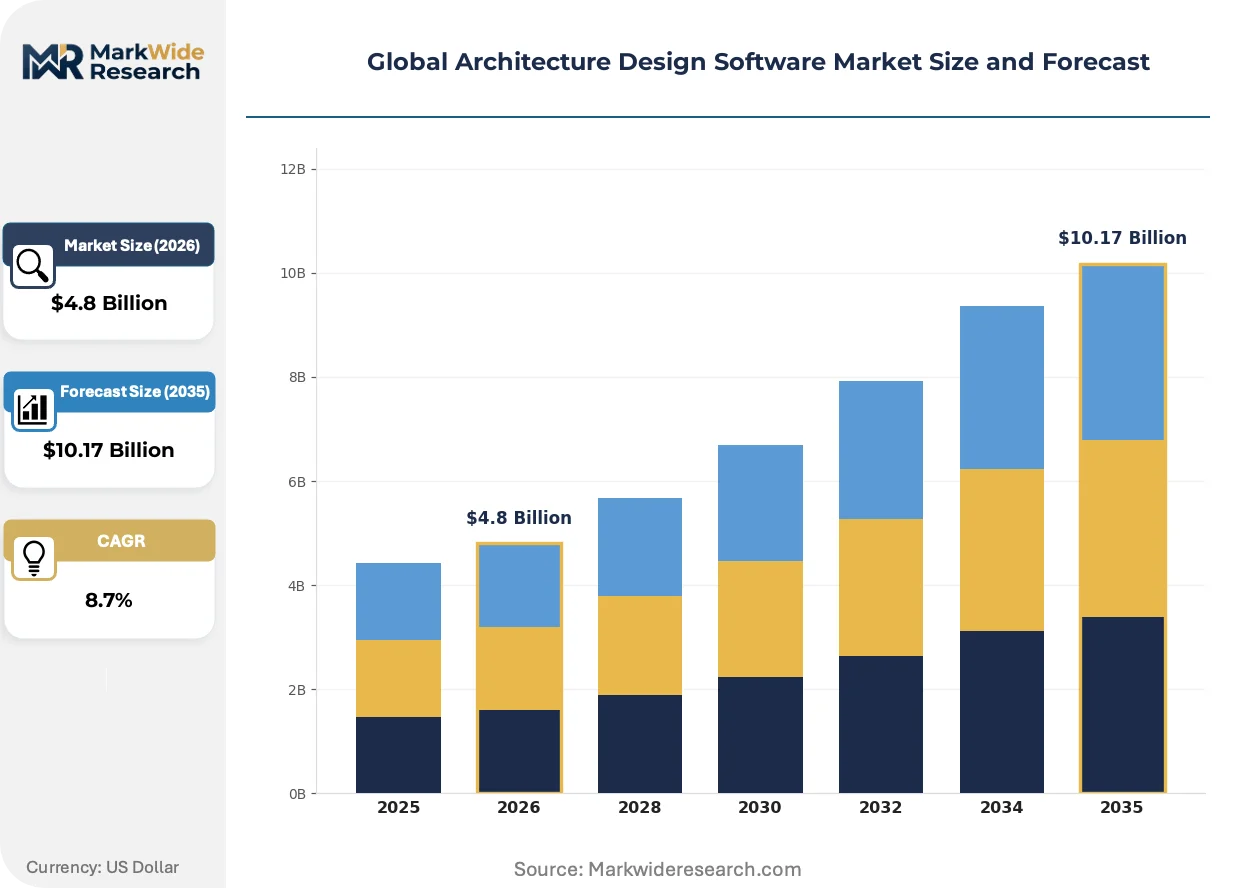
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Building Information Modeling, CAD Software, Visualization Tools, Project Management Software, Rendering Software Technology: Cloud-Based Solutions, Desktop Applications, Mobile Apps, Virtual Reality, AI Integration Application: Residential Projects, Commercial Complexes, Institutional Buildings, Urban Planning, Landscape Design End User: Architectural Firms, Engineering Consultancies, Interior Designers, Real Estate Developers, Construction Companies |
| Companies Covered | Lumion, D5 Render, Autodesk Revit, Bluebeam, DIAL, Graphisoft ArchiCAD, Cedreo, Monograph, Trimble SketchUp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Architecture Design Software Market Shifts & Advancements
Generative AI and edge computing are collapsing the latency between design intent and constructability validation, while regulatory pressure on embodied carbon forces real-time material database integration that legacy file-based workflows cannot support.
GPU-accelerated path tracing is migrating from post-production visualization suites into live design environments, enabling architects to evaluate lighting and material behavior during massing studies rather than after model completion. Mid-sized practices in Germany and the UK are adopting these engines fastest, driven by client presentation demands and energy daylighting compliance. The technology is compressing the traditional separation between schematic design and rendering specialists, eroding a long-standing service revenue stream for visualization boutiques.
The EU F-Gas Regulation and EPA's phasedown of HFC refrigerants are mandating HVAC lifecycle documentation within BIM objects, requiring software vendors to embed chemical composition databases and leakage calculation algorithms directly into MEP family libraries. Industrial consequence includes expanded data validation workflows and third-party certification requirements for equipment manufacturers. Commercial complex developers in California, New York, and the Netherlands face the steepest compliance ramps, pressuring general contractors to mandate platform-specific data templates in bid packages.
Subscription unbundling is fragmenting how design practices acquire capability, with energy analysis, structural coordination, and rendering modules now sold separately rather than in monolithic suites. Independent architects and small studios in Spain, Italy, and South Korea are assembling bespoke toolchains from specialized vendors, bypassing traditional ecosystem lock-in. This pattern concentrates most visibly in markets with high freelance contractor penetration and weak enterprise IT standardization, where monthly cost flexibility outweighs integration convenience.
Global Architecture Design Software Market Segmentation
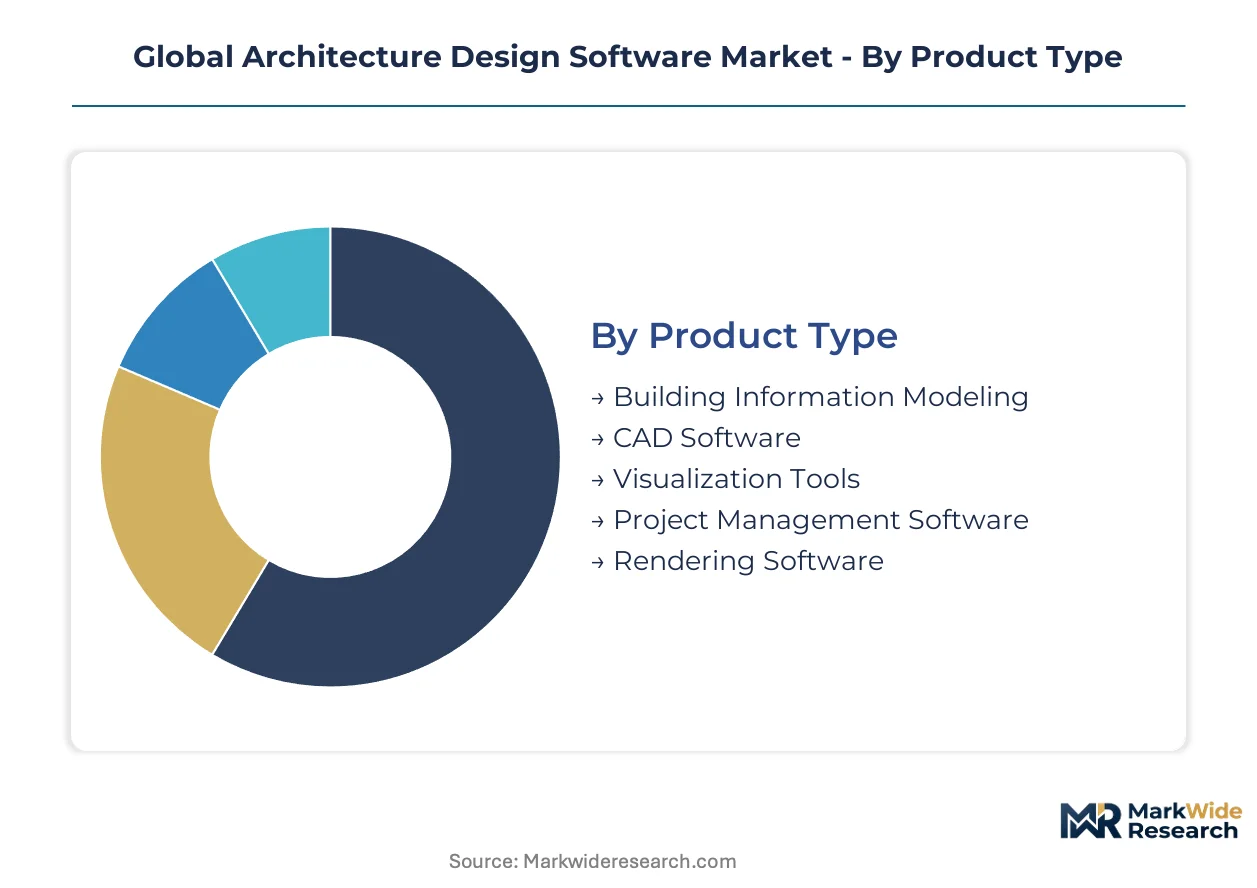
Architecture design software segments exhibit divergent replacement cycles, with rendering modules refreshing every 18-24 months while CAD platforms persist for 5-7 years. Procurement patterns cluster around compliance mandates and collaboration intensity, not feature checklists alone.
Product Type:
Building Information Modeling commands the longest deployment cycles due to enterprise workflow integration, while Visualization Tools turn over fastest as GPU capabilities advance.
- Building Information Modeling:Parametric modeling environments embed structural, mechanical, and electrical data within geometric objects. Demand concentrates in Germany and the United States where regulatory mandates for digital building documentation are tightening. Compliance-driven procurement locks accounts into multi-year enterprise agreements.
- CAD Software:Drafting platforms with 2D/3D geometric constraint solving remain foundational for construction documentation. Japanese and South Korean manufacturing-integrated practices sustain demand for precision drafting tools despite BIM migration pressures.
- Visualization Tools:Real-time and offline rendering engines for client presentations and marketing deliverables.
- Project Management Software:Scheduling, resource allocation, and document control modules for design-phase coordination.
- Rendering Software:GPU-accelerated path tracing and photorealistic image synthesis for final output production.
Building Information Modeling anchors the volume base while Visualization Tools gains share at the steepest rate.
Technology:
Cost tier stratification separates enterprise cloud subscriptions from perpetual desktop licenses, with mobile and VR occupying experimental budget lines.
- Cloud-Based Solutions:Browser-native BIM collaboration with centralized model hosting and real-time multi-user editing. Commercial complex developers in California and New York mandate cloud coordination for distributed project teams managing multi-site portfolios.
- Desktop Applications:Locally installed software with file-based project storage and offline functionality. German and Japanese mid-sized practices retain desktop workflows where internet reliability varies or IP protection requirements restrict external hosting.
- Mobile Apps:Tablet and smartphone-native tools for field markup and model review.
- Virtual Reality:Immersive walkthrough environments for client experience and design validation.
- AI Integration:Generative spatial optimization and automated code compliance checking.
Desktop Applications retains the largest installed base though Cloud-Based Solutions is climbing the fastest.
Application:
Project scale and regulatory exposure determine software stack complexity, with commercial and institutional builds requiring energy simulation modules that residential work often bypasses.
- Commercial Complexes:Mixed-use and office developments with MEP coordination and tenant improvement workflows. France, Germany, and the Netherlands enforce embodied carbon documentation through the EU Green Deal, compelling automated material tracking upgrades.
- Institutional Buildings:Healthcare, education, and government facilities with extended design phases and stringent accessibility requirements. Japan's METI building efficiency standards mandate energy simulation for structures above 2,000 square meters, concentrating procurement in Tokyo and Osaka.
- Residential Projects:Single-family and multi-family housing with streamlined permitting workflows.
- Urban Planning:District-scale massing and infrastructure coordination for city masterplans.
- Landscape Design:Site grading, planting, and hardscape documentation tools.
Commercial Complexes dominates revenue contribution while Institutional Buildings shows the steepest expansion trajectory.
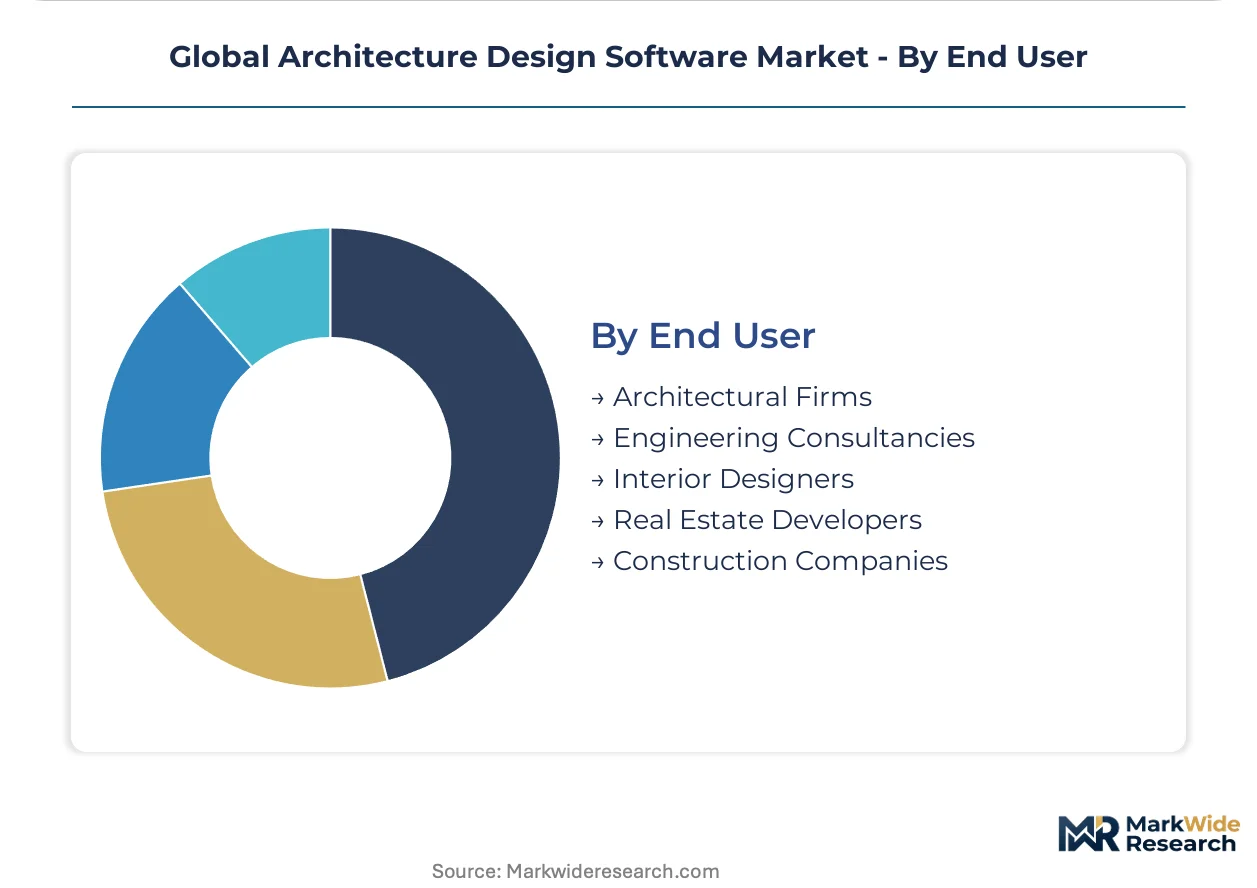
End User:
Organizational scale dictates procurement authority, with engineering consultancies and construction companies driving standardization while independent designers assemble fragmented toolchains.
- Architectural Firms:Design practices ranging from sole practitioners to multinational studios. Mid-sized European firms in Spain and Italy are unbundling subscriptions, assembling bespoke toolchains from specialized vendors rather than accepting ecosystem lock-in.
- Construction Companies:General contractors and construction managers requiring clash detection and sequencing tools. California and New York developers face steep HVAC refrigerant documentation ramps under EPA phasedown rules, pressuring platform-specific data templates in bid packages.
- Engineering Consultancies:Structural and MEP specialists coordinating with architectural partners.
- Interior Designers:Space planning and finish specification professionals with lighter technical requirements.
- Real Estate Developers:Pro forma modeling and marketing visualization for pre-construction sales.
Architectural Firms represents the broadest addressable base while Construction Companies is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: German practices prioritize embodied carbon compliance modules, while Japanese firms emphasize energy simulation integration, and US developers focus on cloud-based multi-site coordination for commercial portfolios.
United States
Commercial complex developers in California and New York drive cloud-based BIM procurement for distributed project teams. The EPA's ENERGY STAR certification protocols and IRA building performance incentives mandate integrated energy analysis modules. San Francisco and Manhattan clusters concentrate procurement authority among general contractors requiring HVAC refrigerant documentation under phasedown rules.
Germany
Mid-sized architectural practices unbundle subscriptions to assemble bespoke toolchains from specialized vendors. The EU Green Deal and national Building Energy Act enforce lifecycle carbon documentation and retrofit energy modeling for existing stock. Berlin and Munich studios lead adoption of GPU-accelerated path tracing engines for daylighting compliance and client presentations.
Japan
Manufacturing-integrated practices sustain demand for precision drafting tools alongside BIM migration. METI building efficiency standards mandate energy simulation for commercial structures above 2,000 square meters. Tokyo, Osaka, and Yokohama concentrate compliance-driven procurement among institutional building specialists.
France
Architectural firms upgrade software stacks for automated material tracking under RE2020 renovation mandates. The EU F-Gas Regulation requires HVAC lifecycle documentation within BIM objects for refrigerant compliance. Paris and Lyon clusters face steep compliance ramps for mixed-use commercial developments.
India
Smart Cities Mission requirements for digital twin documentation in 100 urban agglomerations create first-mover opportunities. The CEA and BIS green construction standards shape procurement criteria for infrastructure awards. Mumbai, Delhi-NCR, and Bangalore concentrate localization efforts for Hindi-language interfaces among emerging vendors.
Global Architecture Design Software Market Competitive Landscape
Capability concentration sits with specialized rendering and interoperability vendors; scale advantage sits with ecosystem-anchored platform providers. The market structures around three tiers: enterprise suite vendors with multi-decade workflow integration, mid-market specialists competing on file format flexibility, and accessibility-focused tools capturing independent designers. Strategic archetypes include BIM ecosystem anchors, visualization engine specialists, and unbundled SaaS module providers. Competitive moves center on subscription attach rate expansion and generative AI feature integration.
Among ecosystem-anchored platform providers, Autodesk Revit and Graphisoft ArchiCAD exemplify contrasting geographic specializations, while Trimble SketchUp occupies a position emphasizing accessibility for early-stage concept development. Visualization specialists Lumion and D5 Render sit within the fastest-turnover segment as GPU capabilities advance. The competitive dynamic pits workflow lock-in against toolchain flexibility, with European mid-market practices increasingly favoring the latter.
| Leading Market Players |
|---|
| Lumion |
| D5 Render |
| Autodesk Revit |
| Bluebeam |
| DIAL |
| Graphisoft ArchiCAD |
| Cedreo |
| Monograph |
| Trimble SketchUp |
| Others |
Supply & Pricing Matrix
NVIDIA's data center GPU pricing power in Taiwan and South Korea concentrates margin capture upstream, forcing architecture software vendors to absorb compute cost volatility or pass through subscription increases to mid-sized practices already squeezed by compliance-driven procurement cycles.
Pricing Analysis
Long-term enterprise subscription contracts anchor revenue stability for BIM ecosystem providers, while project-based licensing persists among visualization specialists serving freelance architects. Three-tier pricing structure across premium, standard, and economy levels separates cloud-collaboration bundles from desktop perpetual licenses and modular SaaS add-ons. Cost compression in the mid-market tier is intensifying because GPU-accelerated rendering engines require continuous hardware refresh cycles. Independent designers and small studios exhibit the highest price sensitivity, often assembling fragmented toolchains from unbundled vendors rather than accepting ecosystem lock-in.
Supply Chain Analysis
Tariff exposure between the United States and China dominates hardware cost planning for workstation and server deployments essential to local BIM hosting. Taiwan, South Korea, and the United States concentrate advanced GPU and CPU manufacturing, while Japan and Germany anchor precision peripheral supply for drafting tablets and VR headsets. Software distribution runs through hyperscaler marketplaces and direct vendor portals, with AWS, Azure, and Google Cloud hosting collaborative instances. Single-source vulnerability in NVIDIA's AI training and inference silicon tether margin stability to foundry allocation decisions beyond vendor control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Architecture design software sits in an early-cycle expansion phase as regulatory mandates for embodied carbon documentation and energy simulation penetration pull mid-sized practices into premium subscription tiers for competitive compliance parity.
For Market Incumbents: Insulate enterprise account retention by deepening generative AI feature integration and embedding HVAC refrigerant lifecycle databases directly into MEP family libraries. Autodesk and Graphisoft must defend against unbundled SaaS specialists by certifying openBIM interoperability layers that reduce switching costs for European mid-market practices. Backward integration into cloud rendering infrastructure offers margin protection against hyperscaler egress fee volatility. For New Entrants and Emerging Players: Retrofit energy modeling modules for existing building stock analysis represent the most penetrable entry point, given Germany's Building Energy Act and France's RE2020 renovation mandates open software categories underserved by new-construction-centric incumbents. India's Smart Cities Mission digital twin requirements for 100 urban agglomerations offer first-mover localization advantages for Hindi-language interface development. Channel partnerships with regional engineering consultancies accelerate compliance-driven procurement access. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native BIM collaboration platforms as GPU virtualization and 5G edge rendering reduce on-premise hardware dependencies. Long-term viability over the next decade hinges on generative AI differentiation and regulatory compliance automation depth. Acquisition targets should demonstrate validated energy simulation engines against multiple jurisdiction standards. The signal to watch is openBIM format adoption velocity across UK, Singapore, and Australian ISO 19650 implementations as an indicator of platform switching cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Generative AI Feature Integration | Autodesk's algorithmic spatial optimization reduces iteration cycles from weeks to hours for competitive parity. |
| openBIM Interoperability Certification | IFC schema validation against ISO 19650 implementations in UK and Singapore reduces platform switching costs. |
| Retrofit Energy Modeling Module Launch | Germany's Building Energy Act creates compliance-driven procurement for existing stock analysis underserved by incumbents. |
| Hindi-Language Interface Localization | India's Smart Cities Mission digital twin requirements in 100 urban agglomerations reward first-mover vendors. |
| GPU Virtualization Infrastructure Partnership | 5G edge rendering convergence enables tablet-native BIM review, collapsing hardware barriers for field teams. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with architectural firm principals, construction company VDC managers, engineering consultancy BIM leads, and software vendor product strategists. Secondary validation drew from SEC filings of publicly traded design software providers, EPA ENERGY STAR certification protocols, EU Green Deal regulatory documentation, and METI building efficiency standard publications. Bottom-up sizing of subscription attach rates and top-down calibration against reported cloud collaboration revenue streams were triangulated to establish segment-level baselines.
Calibration against historical replacement cycles and regulatory implementation timelines anchored growth rate derivation across the analysis window. Segmentation modeling incorporated deployment model, organization size, project type, and regional compliance intensity as primary dimensions. CAGRs were computed from year-over-year expansion in cloud-native seat counts and module unbundling penetration. Forecast inputs included GPU capability advancement curves and jurisdiction-specific mandate rollouts for embodied carbon documentation.
Macroeconomic conditions sit as an overlay; deviation in commercial construction lending rates and cloud infrastructure capex cycles would shift the trajectory of platform migration timing. Forecasts reflect assumptions around regulatory enforcement consistency and hyperscaler pricing stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Data Integration and Integrity Software Market
Software & Services
Attendance Tracking Software Market
Software & Services
Category Management Software Market
Software & Services
Generative Design Software Market
Software & Services
Web Framework Software Market
Software & Services
B2B Gateway Software Market
Software & Services
MEP Software Market
Software & Services
Global Neural Network Software Market
Software & Services
Multivariate Testing Software Market
Software & Services
Federal Government Software Market
Software & Services
Global Equity Management Software Market
Software & Services
Global Building Information Modeling (BIM) Software Market
Software & Services
Global Business Management Software Market
Software & Services
Business Rules Management System Market
Software & Services
Advanced Process Control Software Market
Software & Services
Global PEO Software Market