
 Mobile 3D Market | 2026-2036
Mobile 3D Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile 3D Market Analysis
ISO 13485 certification for medical-grade 3D visualization is redrawing competitive boundaries in healthcare applications. Apple Inc. leverages its proprietary depth-sensing stack to anchor premium smartphone positioning. Samsung Electronics Co. Ltd. dominates OLED panel supply for stereoscopic displays across multiple device tiers. Qualcomm Technologies Inc. competes through integrated Snapdragon spatial computing platforms that reduce OEM design cycles.
Mobile 3D encompasses portable devices and software systems that generate, render, or perceive three-dimensional visual content using stereoscopic displays, depth-sensing camera arrays, or holographic projection units with sub-millimeter spatial accuracy. These systems serve gaming immersion, surgical visualization, remote collaboration, and spatial commerce by converting flat interfaces into volumetric experiences. Smartphones and AR glasses command the largest revenue pools as hardware-software integration tightens, while holography remains nascent with concentrated R&D investment. Gaming and healthcare applications are absorbing the majority of developer resources, with education trailing due to procurement cycle length.
FDA clearance requirements for diagnostic 3D imaging on mobile platforms constrain product timelines in the United States, while the EU AI Act and GDPR impose biometric data handling rules on European depth-sensing deployments. FCC equipment authorization governs radio-frequency emissions for AR glasses in the United States, creating additional testing burdens for manufacturers. Stakeholders must track which certification body moves first on unified spatial computing standards, as regulatory alignment will determine cross-border product portability and R&D allocation priorities.
Market Dynamics
The Mobile 3D market is being fundamentally restructured by the convergence of depth-sensing hardware commoditization and tightening biometric data regulations, forcing vendors to rebuild software stacks around privacy-preserving computation rather than raw sensor performance.
Growth Catalysts
- EU AI Act biometric governance:The regulation's risk-based classification of depth-sensing applications is accelerating investment in on-device processing architectures that eliminate cloud data exposure.
- Surgical visualization demand:Medical-grade 3D imaging for pre-operative planning is pulling ISO 13485-certified mobile systems into hospital procurement pipelines.
- Seoul display cluster concentration:South Korea's vertically integrated OLED and microLED fabrication ecosystem is compressing panel costs for stereoscopic smartphone displays.
Market Restraints
- Input cost volatility:Rare earth element prices for VCSEL emitters in structured-light depth sensors fluctuate with Chinese export quota policies.
- Supply concentration risk:Advanced OLED panel fabrication for high-refresh stereoscopic displays concentrates among three South Korean suppliers.
- Technical limitation:Outdoor performance degradation in time-of-flight depth sensing under direct sunlight constrains AR glasses use cases.
Strategic Opportunities
- Underpenetrated education procurement:Extended sales cycles in K-12 institutional purchasing leave room for subscription-based 3D content platforms.
- Technology convergence:Neural radiance fields (NeRF) combined with mobile depth sensing enable real-time 3D scene reconstruction without dedicated LiDAR hardware.
- Regulatory tailwind:South Korea's MFDS fast-track approval pathway for AI-assisted diagnostic imaging reduces time-to-market for healthcare 3D applications.
Industry Challenges
- Certification timeline compression:FDA 510(k) clearance for diagnostic 3D imaging on mobile platforms requires parallel hardware and software validation tracks.
- Integration complexity:Legacy hospital PACS infrastructure demands custom DICOM interoperability layers for mobile 3D visualization systems.
- IP licensing friction:Patent thickets around structured-light pattern generation create royalty stacking for emerging depth-sensing vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile 3D Market |
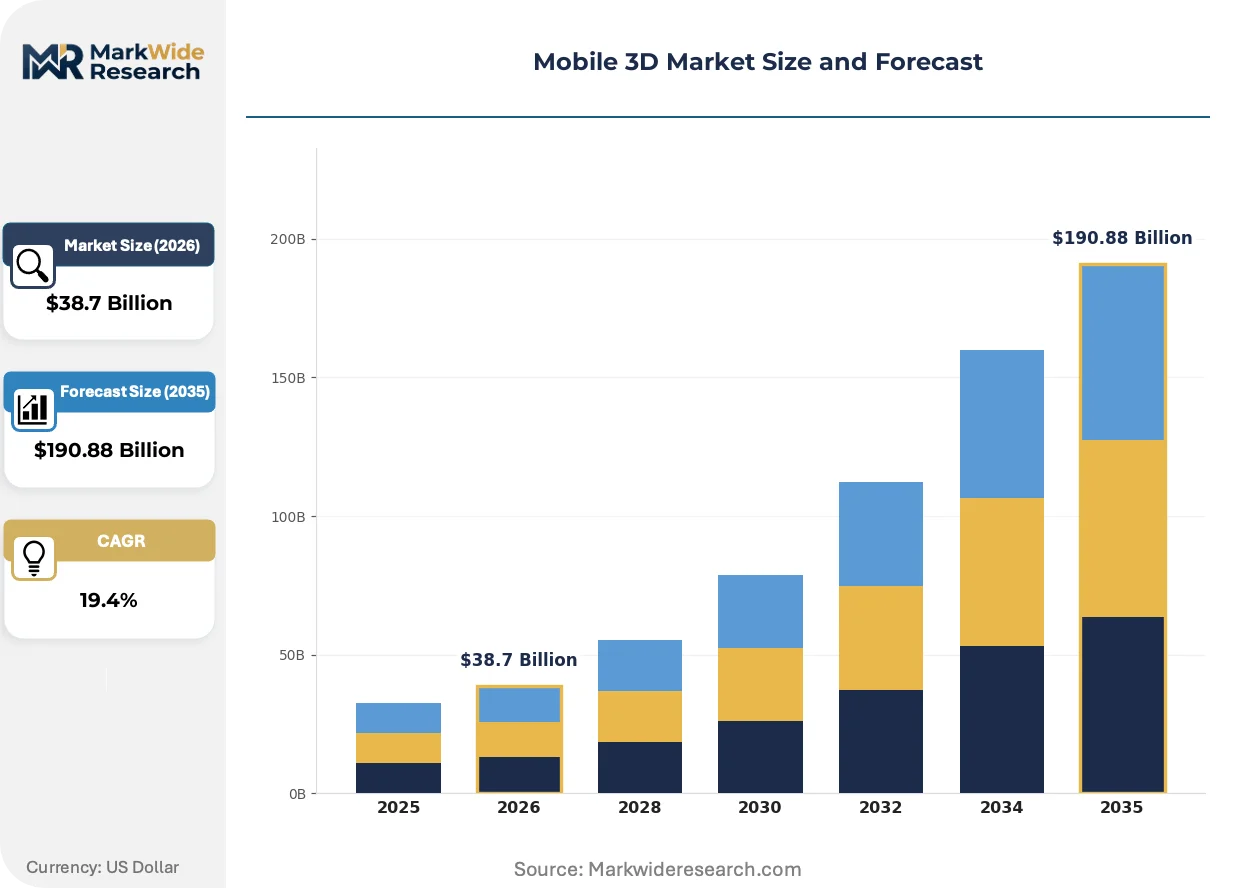
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $190.88 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Tablets, AR Glasses, Accessories Technology: 3D Rendering, Stereoscopic, Depth Sensing, Holography Application: Gaming, Education, Healthcare, Virtual Tours End User: Consumers, Enterprises, Educators, Developers |
| Companies Covered | Apple Inc., Samsung Electronics Co. Ltd., Qualcomm Technologies Inc., NVIDIA Corporation, LG Electronics, HTC Corporation, Intel Corporation, 3M Company, Sony Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile 3D Market Emerging Trajectories
Active depth-sensing architectures are splintering into competing technical approaches, each optimized for distinct power-performance tradeoffs in battery-constrained mobile form factors.
Time-of-flight sensor arrays is fragmenting across three competing implementations: direct, indirect, and frequency-modulated continuous-wave. Automotive LiDAR suppliers are repurposing indirect time-of-flight chips for AR glasses, while smartphone OEMs favor direct time-of-flight for portrait-mode depth mapping. This technical divergence is fragmenting the supplier base and forcing component vendors to maintain multiple process nodes simultaneously.
GDPR Article 35 data protection impact assessments now explicitly cover depth-sensing biometric capture in European consumer devices. The regulation mandates privacy-by-design documentation before market entry, extending product development timelines by eight to fourteen months. Medical device manufacturers are responding by segregating European SKUs with dedicated secure enclaves that disable cloud synchronization entirely.
Enterprise buyers are unbundling hardware procurement from software licensing for mobile 3D visualization systems. Industrial maintenance teams now source tablets from consumer channels while purchasing surgical-grade visualization software through specialized medical distributors. This bifurcation is most pronounced in Germany, where hospital procurement groups negotiate software contracts independently of device purchasing committees.
Mobile 3D Market Segmentation
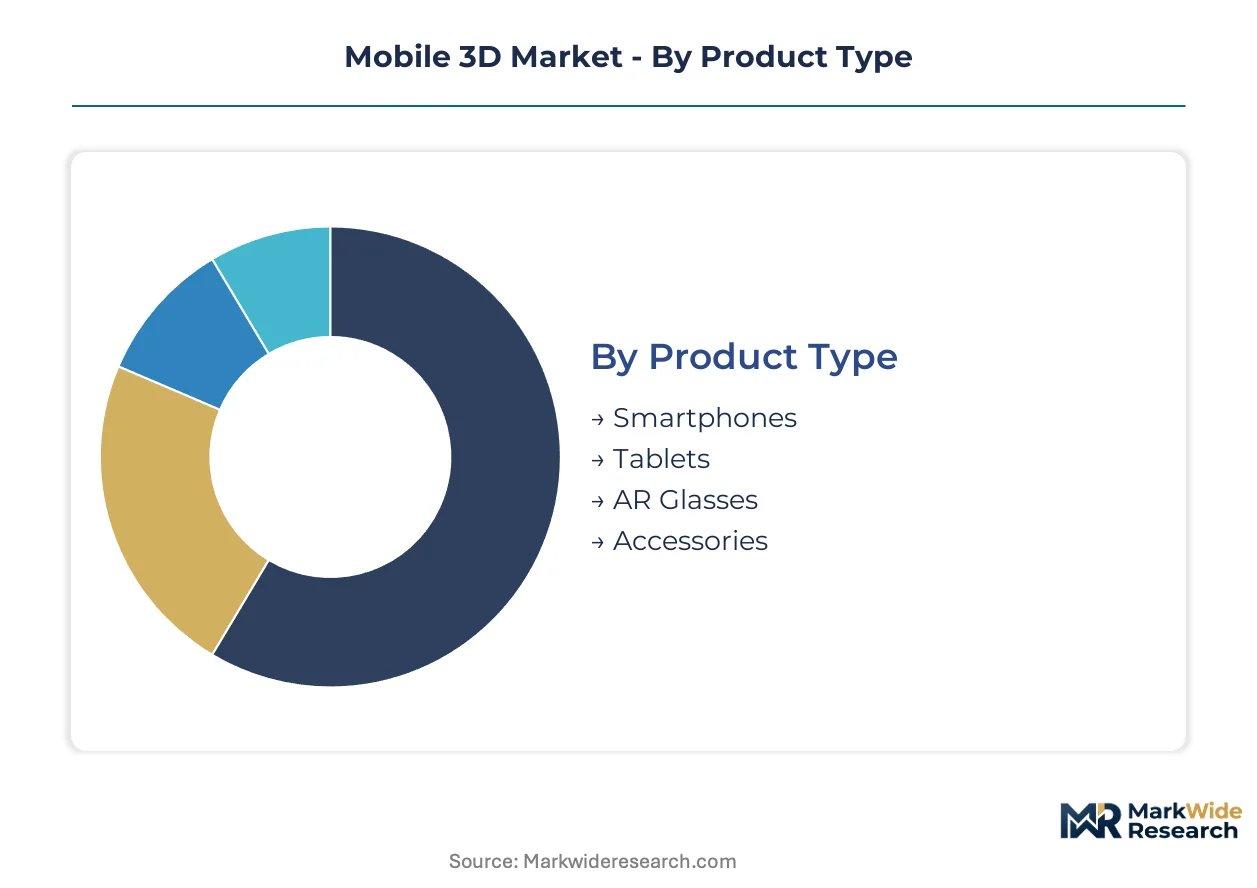
Mobile 3D segmentation reveals divergent supply chain footprints across product categories. Export-led segments cluster around South Korean display fabrication, while domestic-assembly categories concentrate in regional consumer electronics hubs.
Product Type:
Smartphones and AR glasses ship globally from South Korean and Chinese assembly lines, whereas tablets and accessories source more regionally.
- Smartphones:Stereoscopic OLED panels with 120Hz refresh rates dominate flagship tier specifications. Demand concentrates in Seoul's vertically integrated display cluster, driven by compressed panel costs from microLED process improvements.
- AR Glasses:Waveguide optics combined with time-of-flight depth sensors create severe thermal management constraints. Export volumes track Qualcomm Snapdragon spatial computing platform availability, with FCC equipment authorization timelines gating US market entry.
- Tablets:Larger form factors accommodate passive 3D lenticular overlays without active depth sensing.
- Accessories:Clip-on depth-sensing modules and stereoscopic viewers represent aftermarket entry points.
Smartphones hold the largest share; momentum sits with AR Glasses.
Technology:
Cost tier stratification separates premium active-sensing stacks from economy passive-display alternatives.
- 3D Rendering:Real-time GPU acceleration pipelines convert 2D assets into volumetric scenes through neural upscaling. Enterprise demand clusters in German industrial maintenance applications, constrained by legacy PACS interoperability requirements.
- Depth Sensing:Structured-light and time-of-flight architectures compete for battery-constrained mobile form factors. VCSEL emitter supply volatility from Chinese rare earth export policies constrains cost predictability.
- Stereoscopic:Dual-panel OLED configurations with precision alignment layers.
- Holography:Diffractive waveguide prototypes remain R&D-concentrated with minimal commercial volume.
Depth Sensing captures current revenue concentration; 3D Rendering climbs the fastest.
Application:
Volume distribution skews heavily toward consumer entertainment, while margin accrues to regulated medical deployments.
- Gaming:Stereoscopic content pipelines absorb majority developer resources across Unity and Unreal Engine mobile builds. South Korean studios lead volumetric asset production, driven by domestic 5G infrastructure enabling cloud-rendered 3D streaming.
- Healthcare:ISO 13485-certified surgical visualization systems command hospital procurement premiums. FDA 510(k) clearance timelines constrain US product launches, while MFDS fast-track pathways accelerate South Korean market entry.
- Education:Extended K-12 procurement cycles delay institutional adoption.
- Virtual Tours:NeRF-based scene reconstruction reduces hardware requirements for real estate and cultural heritage applications.
Gaming holds the largest share; Healthcare gains share fastest.
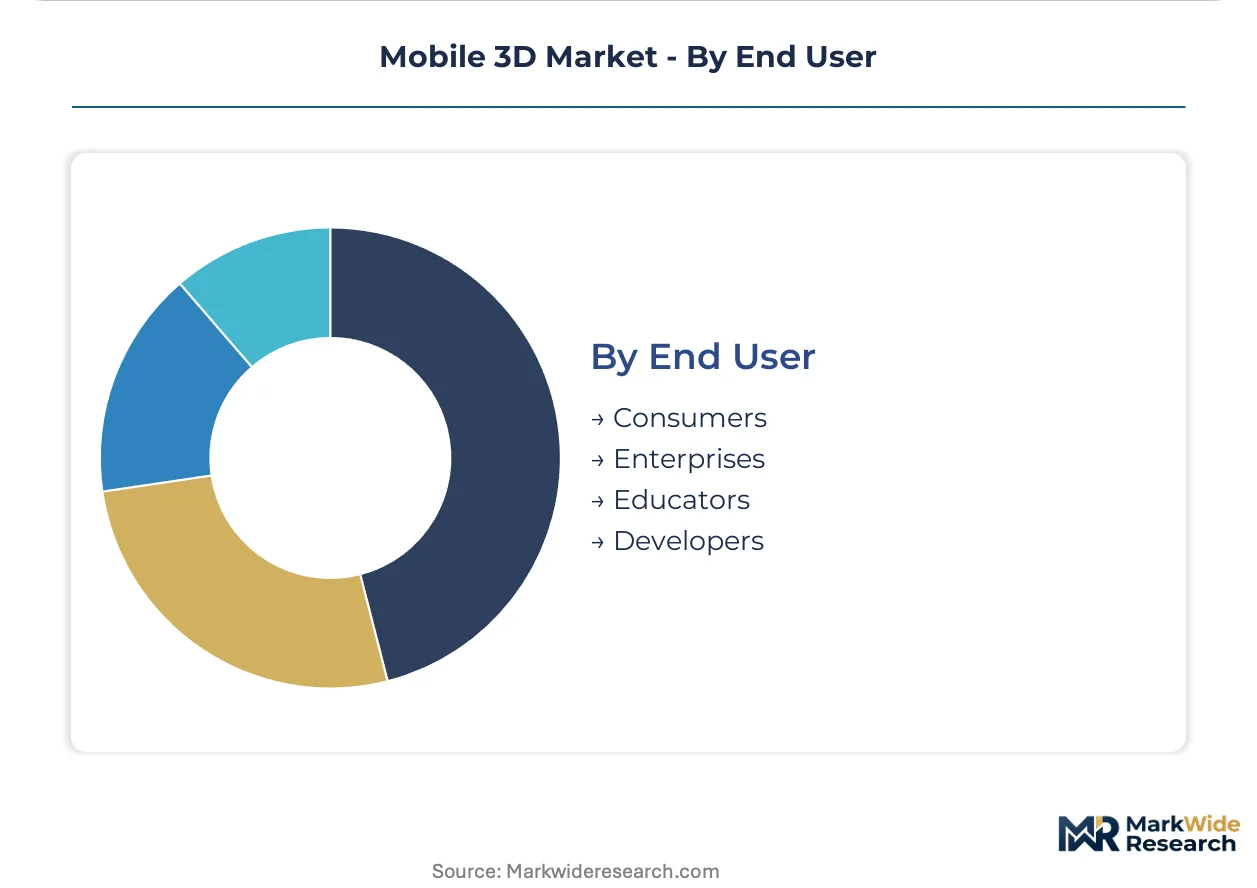
End User:
Customer type determines procurement channel bifurcation between consumer retail and specialized distributor networks.
- Consumers:Premium smartphone upgrades drive replacement cycles through depth-sensing camera differentiation. German hospital procurement committees now unbundle device purchasing from software licensing, fragmenting traditional vendor relationships.
- Enterprises:Industrial maintenance teams source hardware through consumer channels while purchasing surgical-grade visualization software separately.
- Educators:Institutional purchasing committees favor subscription-based 3D content platforms over capital expenditure models.
- Developers:Toolchain licensing for spatial computing SDKs concentrates revenue with platform owners.
Consumers hold the largest share; Enterprises show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's MFDS fast-track pathway for AI-assisted diagnostic imaging accelerates healthcare 3D application approvals, while the EU AI Act's biometric governance rules reshape European depth-sensing deployment architectures. National regulatory divergence is fragmenting product roadmaps across major economies.
United States
FDA 510(k) clearance timelines for diagnostic 3D imaging on mobile platforms constrain product launches, with parallel hardware and software validation tracks extending development cycles. FCC equipment authorization governs radio-frequency emissions for AR glasses, creating additional testing burdens for manufacturers. Silicon Valley and Austin host concentrated R&D operations for spatial computing platforms.
Germany
Hospital procurement committees unbundle hardware purchasing from software licensing, fragmenting traditional vendor relationships in surgical visualization systems. GDPR Article 35 mandates privacy-by-design documentation for depth-sensing biometric capture, extending product development timelines. Bavaria's industrial maintenance sector drives enterprise demand for mobile 3D visualization tools.
South Korea
Seoul's vertically integrated OLED and microLED fabrication ecosystem compresses panel costs for stereoscopic smartphone displays. MFDS fast-track approval reduces time-to-market for AI-assisted diagnostic imaging applications. Domestic 5G infrastructure enables cloud-rendered 3D streaming for gaming studios.
China
MIIT standards govern structured-light depth sensor emissions for consumer devices, with rare earth export quota policies creating VCSEL emitter supply volatility. Dual carbon goals pressure manufacturing energy intensity in display fabrication. Shenzhen and Shanghai anchor hardware assembly clusters for stereoscopic device exports.
Japan
METI promotes spatial computing adoption through industrial digitalization incentives targeting manufacturing maintenance applications. PMDA regulatory frameworks for software-as-a-medical-device constrain mobile diagnostic imaging deployments. Tokyo and Osaka concentrate gaming studio resources for volumetric asset production.
Mobile 3D Market Vendor Landscape
Player mix skews toward integrated platform vendors with captive semiconductor design capabilities. The competitive structure concentrates around three tiers: premium ecosystem owners controlling full hardware-software stacks, panel specialists dominating display supply, and component vendors supplying depth-sensing modules across OEM customers. Strategic moves center on vertical integration into emitter fabrication and cross-licensing patent portfolios for structured-light pattern generation.
Within the premium ecosystem tier, Apple Inc. and Samsung Electronics Co. Ltd. occupy positions defined by proprietary depth-sensing integration and captive OLED supply respectively. Qualcomm Technologies Inc. represents the component-platform archetype, supplying integrated spatial computing solutions that reduce OEM design cycles. These three entities exemplify divergent approaches to hardware-software coupling in battery-constrained mobile form factors.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics Co. Ltd. |
| Qualcomm Technologies Inc. |
| NVIDIA Corporation |
| LG Electronics |
| HTC Corporation |
| Intel Corporation |
| 3M Company |
| Sony Corporation |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory cycles for VCSEL emitter modules expose pricing power asymmetries between South Korean display integrators and Chinese component assemblers, with ISO 13485-certified medical tiers commanding substantial premiums over consumer-grade alternatives.
Pricing Analysis
Certification level creates the primary spread across pricing tiers, with FDA-cleared diagnostic imaging systems and ISO 13485-certified surgical visualization platforms sitting well above consumer AR glasses. Three-tier pricing structure across premium, standard, and economy levels stratifies by depth-sensing accuracy and panel refresh specifications. Cost compression in mid-tier smartphone depth-sensing modules is intensifying because Qualcomm Snapdragon spatial computing platform licensing standardizes hardware reference designs. Enterprise healthcare buyers show least price sensitivity due to procurement committee unbundling of software licenses from device costs, while K-12 education committees remain most sensitive to capital expenditure thresholds.
Supply Chain Analysis
Port congestion at Busan and Shanghai-Ningbo trade lanes disrupts inbound waveguide optics shipments from German precision glass manufacturers, forcing AR glasses assemblers to absorb elevated air freight premiums. Supply concentrates in South Korea for OLED microdisplays, China for VCSEL emitter fabrication and final device assembly, and Japan for diffractive optical elements. The chain rests on rare earth element feedstock from Chinese export quota-controlled sources, precision lithography equipment from Dutch and Japanese suppliers, and specialized epoxy resins for display lamination. Single-source vulnerability around Seoul's three-fabricator OLED cluster creates concentration risk. Distribution runs through medical device distributors for hospital systems and consumer electronics retail for smartphone upgrades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobile 3D demand cycles track smartphone replacement cadences and hospital capital expenditure approvals, with current positioning reflecting post-pandemic healthcare infrastructure refresh momentum.
For Market Incumbents: Secure captive supply of VCSEL emitters through backward integration or long-term offtake agreements with Chinese rare earth processors, insulating margin structures from export quota volatility. Deepen ISO 13485 certification moats in surgical visualization to defend against emerging entrants targeting MFDS fast-track pathways in South Korea. For New Entrants and Emerging Players: MFDS fast-track approval for AI-assisted diagnostic imaging offers the most penetrable regulatory entry point, enabling time-to-market compression against FDA-constrained US competitors. Target German hospital procurement committees with standalone software licensing models that bypass hardware bundling requirements, and pursue NeRF-based scene reconstruction tools for virtual tour applications where hardware requirements remain minimal. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because spatial computing SDK control concentrates developer ecosystem rents with integrated hardware-software vendors. Acquisition targets should emphasize patent portfolios around structured-light pattern generation and secure enclave architectures for GDPR-compliant European deployments. Watch for EU AI Act enforcement actions against cloud-dependent depth-sensing architectures as the inflection signal for on-device processing premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Secure Enclave Architecture Development | GDPR Article 35 compliance enables European market entry without cloud synchronization liabilities. |
| Neural Radiance Field Integration | Real-time 3D reconstruction reduces LiDAR hardware dependency for mid-tier smartphone penetration. |
| ISO 13485 Certification Investment | Hospital procurement premium access justifies parallel software-hardware validation track costs. |
| Snapdragon Platform Partnership | Qualcomm spatial computing integration compresses OEM design cycles and accelerates time-to-revenue. |
| Seoul Display Cluster Sourcing | Vertically integrated OLED fabrication locks in panel cost advantages for stereoscopic refresh specifications. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with gaming studio technical directors, hospital biomedical engineers, AR hardware product managers, and medical device regulatory affairs specialists; and secondary validation through FDA 510(k) clearance databases, MFDS approval registries, EU AI Act implementation guidance, SEC filings from display panel manufacturers, and customs trade data for VCSEL emitter flows. Bottom-up smartphone and AR glasses shipment estimates triangulated against top-down healthcare IT expenditure projections.
Across the analysis window, the forecasting framework modeled volume and value trajectories across product type, technology architecture, application segment, and end-user category, with additional granularity on certification tier and regional regulatory cluster. CAGRs derived from historical penetration curves adjusted for replacement cycle compression and hospital procurement cycle normalization. Key inputs included Seoul display cluster capacity expansion announcements, Qualcomm Snapdragon platform release cadences, and EU AI Act biometric governance implementation timelines.
Decision-makers should treat outputs as directional under assumptions of stable rare earth export policies and continued Seoul OLED fabrication concentration; material deviation would warrant model refresh. Specific risks include MFDS pathway suspension, FCC equipment authorization timeline extension, and GDPR Article 35 enforcement variance across member states. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Technology
Molecular Modeling Market
3D Technology
Contactless 3D Laser Scanner Market
3D Technology
Generative Design Market
3D Technology
3D Printing CAD Software Market
3D Technology
Visualization and 3D Rendering Software Market
3D Technology
3D Point Cloud Processing Software Market
3D Technology
3D Reconstruction Technology Market
3D Technology
3D Photogrammetry Software Market
3D Technology
3D CAD Market
3D Technology
3D Rendering Market
3D Technology
3D Mobile Mapping Market
3D Technology
Global 3D Architecture Software Market
3D Technology
3D Scanner Market
3D Technology
Digital Holography Market
3D Technology
3D Rendering Software Market
3D Technology
APAC 3D 4D Technology Market