
 3D Scanning Market | 2026-2036
3D Scanning Market Size, Share, and Industry Trends Forecast 2026-2036
3D Scanning Market Analysis
Silicon photomultiplier arrays are hardening the performance economics of portable 3D scanning systems, displacing legacy CCD-based architectures in cost-sensitive deployments. Creaform Inc. leverages proprietary self-positioning technology to dominate handheld measurement workflows in automotive plants. Hexagon AB anchors its competitive stance through backward integration into metrology software and CAD interoperability layers. FARO Technologies, Inc. specializes in construction and public safety applications, occupying a distinct channel position against industrial-focused rivals.
3D scanning captures geometric surface data through laser, optical, or structured light projection, reconstructing point clouds with spatial resolutions reaching single-digit microns for precision metrology. The technology serves industrial quality assurance, digital twin creation, and heritage preservation by converting physical artifacts into manipulable CAD models. Laser scanners lead product type revenues due to their penetration in heavy manufacturing and civil engineering survey workflows. Structured light systems represent the fastest-expanding technology segment, driven by healthcare dental digitization and consumer product design studios seeking sub-hundred-micron accuracy without probe contact. Photogrammetry endures in entertainment and large-scale architecture where passive capture suffices.
FDA 510(k) clearance requirements govern medical scanning devices deployed for surgical planning and orthotic fabrication in the United States. The EU AI Act and CE marking framework under MDR and REACH constrain algorithmic processing features and material composition of scanning hardware sold across European markets. ISO 10360 calibration standards enforce traceable measurement uncertainty declarations, shaping procurement specifications for aerospace and automotive tier-one suppliers. Stakeholders must monitor convergence between optical scanning and real-time computational photonics, as on-device processing redefines competitive differentiation in field-portable systems.
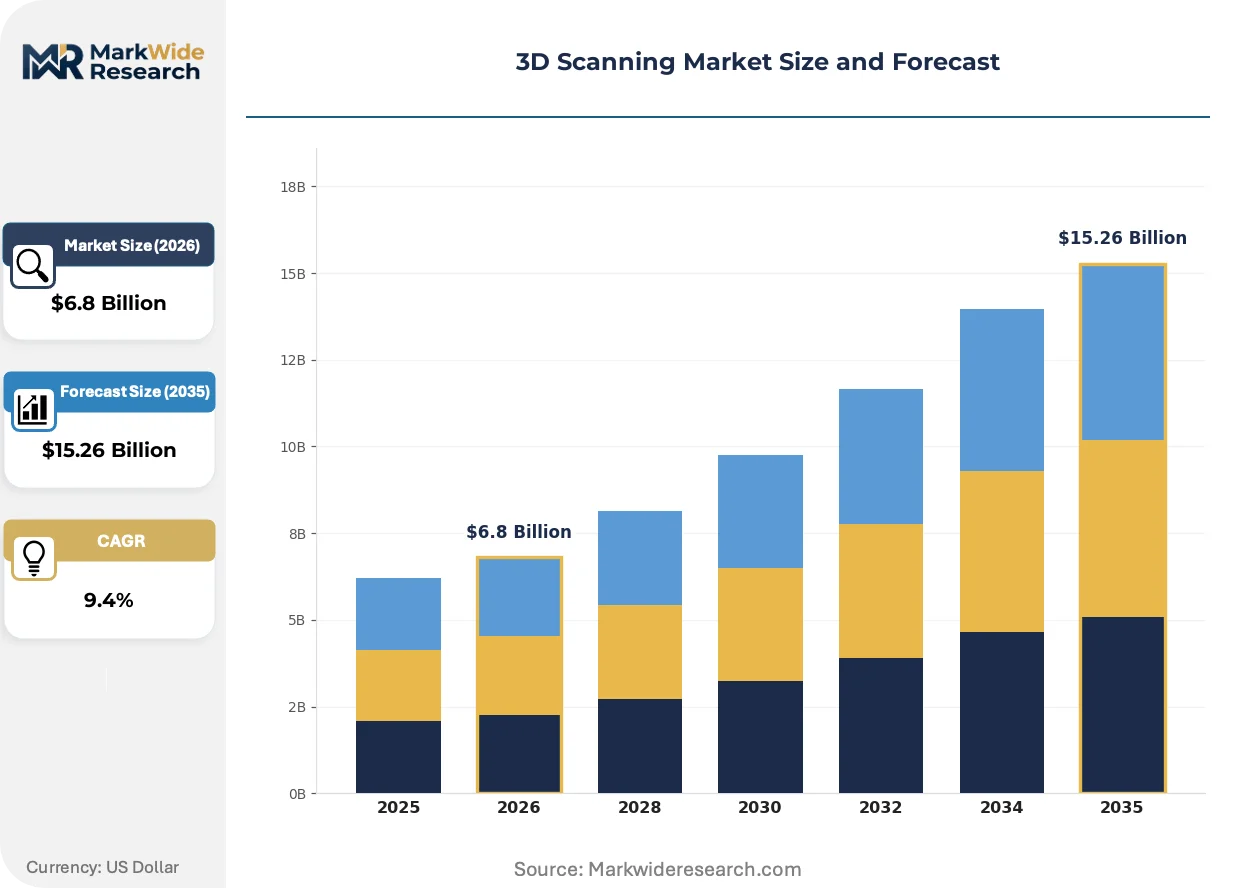
Market Dynamics
Silicon photomultiplier arrays are hardening performance economics of portable systems, displacing legacy CCD architectures and forcing hardware makers to reconfigure supply chains around solid-state photodetector sourcing.
Growth Catalysts
- EU AI Act compliance mandates:CE marking requirements for measurement instruments under MDR are tightening thresholds, forcing equipment upgrades across automotive and aerospace supply chains in Germany, France, and Italy.
- Electric vehicle battery enclosure validation:Automotive OEMs in Stuttgart, Wolfsburg, and Munich are expanding metrology-grade scanning for thermal runaway containment geometry verification.
- Structured light dental digitization:Healthcare providers in Switzerland and the Netherlands are deploying sub-hundred-micron accuracy systems for orthodontic and implant workflows, bypassing probe-contact limitations.
Market Restraints
- Silicon photodetector supply concentration:Foundry capacity for SPMPD arrays concentrates in Taiwan and South Korea, exposing European and North American scanner OEMs to single-source risks.
- ISO 10360 calibration infrastructure gaps:Traceable measurement uncertainty declarations require accredited laboratories that remain scarce in Eastern European and Latin American markets.
- Photogrammetry substitution in entertainment:Passive capture methods endure for large-scale architecture and film production, capping price realizations for entry-level laser systems.
Strategic Opportunities
- India PLI scheme for precision manufacturing:Production-linked incentives for automotive and electronics sectors are creating first-mover openings for metrology-grade scanner deployment in Pune and Chennai industrial corridors.
- Real-time computational photonics convergence:On-device point cloud processing is collapsing hardware footprints, enabling field-portable systems to penetrate mining survey and disaster response applications previously served by tripod-mounted units.
- Heritage preservation digitization mandates:National museum conservation programs in Italy, Greece, and Japan are institutionalizing 3D archival standards, creating recurring revenue streams for structured light service providers.
Industry Challenges
- Multi-physics simulation talent scarcity:Optical calibration engineers capable of integrating thermal drift compensation with photon-counting algorithms command premium wages, constraining R&D expansion at mid-tier manufacturers.
- FDA 510(k) timeline compression:Surgical planning device clearances now average 180 days, forcing medical scanner developers to front-load clinical validation spending before revenue recognition.
- CAD interoperability fragmentation:Proprietary point cloud formats from dominant metrology software vendors create integration friction for automotive tier-one suppliers running multi-CAD environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Scanning Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Scanners, Optical Scanners, Triangulation Scanners, Structured Light Scanners Technology: Time of Flight, Photogrammetry, Structured Light, Laser Triangulation End User: Aerospace, Manufacturing, Healthcare, Entertainment Application: Digital Modelling, Quality Control, Reverse Engineering, Product Design |
| Companies Covered | Creaform Inc., Carl Zeiss Optotechnik GmbH, Hexagon AB, Nikon Corporation, Artec 3D, FARO Technologies, Inc., Autodesk, Inc., GOM GmbH, 3D Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Scanning Market Emerging Trajectories
Computational photonics and on-device processing are collapsing the traditional boundary between capture hardware and analysis software, redefining competitive differentiation around edge intelligence rather than sensor specifications alone.
Solid-state photodetector arrays are consolidating the portable 3D scanning architecture stack, replacing vacuum-tube photomultipliers and legacy CCD sensors with compact, low-voltage alternatives. Automotive plants in Germany's industrial corridor are adopting handheld units with integrated SPMPD arrays for inline gap-and-flush measurement, eliminating darkroom calibration requirements. This consolidation is compressing bill-of-materials costs and enabling battery-powered operation in previously inaccessible production environments.
The EU AI Act algorithmic transparency requirements are reshaping procurement specifications for scanning systems deployed in medical and safety-critical applications. CE marking under MDR now demands documented decision pathways for any automated feature extraction, forcing vendors to segregate AI-enabled functions from base metrology firmware. French and German healthcare procurement agencies are prioritizing vendors with pre-validated human-in-the-loop architectures, creating compliance-driven vendor selection criteria.
Outcome-based service contracts are displacing perpetual license sales in enterprise metrology deployments, particularly among automotive OEMs managing multi-site quality networks. Tier-one suppliers in Bavaria and Baden-Württemberg are negotiating per-inspection pricing for dimensional validation, transferring capital risk to scanner vendors. This model is concentrating service capability requirements in vendor organizations, favoring integrated hardware-software providers with regional calibration laboratory networks.
3D Scanning Market Segmentation
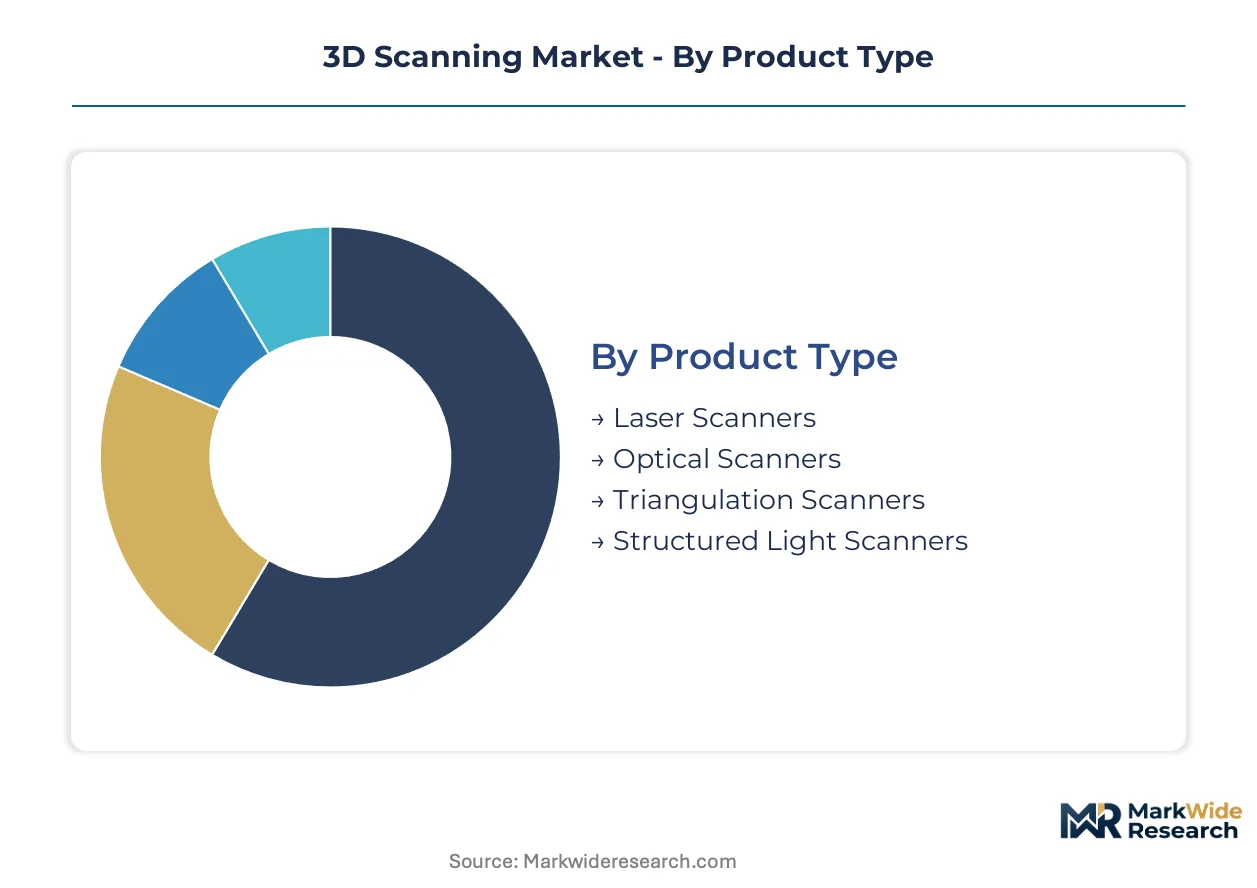
Segmentation in 3D scanning reveals how hardware architectures align with precision requirements and deployment constraints. Product type and technology choices determine whether systems operate as standalone metrology stations or embed directly into production lines.
Product Type:
Laser and optical scanners dominate standalone metrology deployments, while structured light systems embed most readily into automated manufacturing cells.
- Laser Scanners:These systems project coherent light beams to capture geometric data across long working distances with high point density. Demand concentrates in German automotive plants for inline gap-and-flush measurement during final assembly verification.
- Structured Light Scanners:Projecting patterned illumination onto surfaces enables sub-hundred-micron capture without probe contact. Swiss and Dutch healthcare providers deploy these for orthodontic digitization, bypassing traditional impression workflows.
- Optical Scanners:Passive imaging systems capture surface reflectance for texture mapping in entertainment and heritage preservation applications.
- Triangulation Scanners:Short-range precision units calculate surface coordinates through angular displacement measurement, serving precision machining verification in Bavarian toolmaking clusters.
Laser scanners lead volumes today; structured light systems are gaining share fastest.
Technology:
Technology selection tracks the trade-off between capture speed and absolute accuracy, with time-of-flight systems sacrificing precision for range.
- Time of Flight:Measuring light pulse return times enables centimeter-level accuracy across hundreds of meters. Civil engineering surveyors in Norway and Switzerland deploy these for infrastructure monitoring where range outweighs precision requirements.
- Laser Triangulation:Angular displacement calculation delivers single-digit micron resolution for metrology-grade validation. Aerospace suppliers in Toulouse and Hamburg rely on these for turbine blade dimensional certification.
- Structured Light:Phase-shift pattern projection achieves sub-hundred-micron accuracy without moving parts, accelerating dental and consumer product design workflows.
- Photogrammetry:Multi-camera passive capture reconstructs large-scale geometry from overlapping images, persisting in film production and architectural documentation where contactless operation at distance matters.
Laser triangulation commands premium pricing; structured light is climbing the fastest.
End User:
End-user segmentation reflects divergence between safety-critical certification requirements and commercial flexibility.
- Manufacturing:Automotive OEMs in Stuttgart, Wolfsburg, and Munich anchor demand for metrology-grade systems validating electric vehicle battery enclosure geometries against thermal runaway containment specifications.
- Aerospace:Tier-one suppliers in Toulouse and Hamburg require ISO 10360-traceable systems for airframe component certification, with procurement specifications mandating documented measurement uncertainty.
- Healthcare:FDA 510(k) clearance governs surgical planning deployments in the United States, while Swissmedic and national regulators across Europe enforce MDR compliance for clinical digitization hardware.
- Entertainment:Film studios and game developers in Los Angeles and Tokyo leverage photogrammetry for asset creation, prioritizing speed over metrology-grade precision.
Manufacturing leads volumes today; healthcare is expanding most quickly.
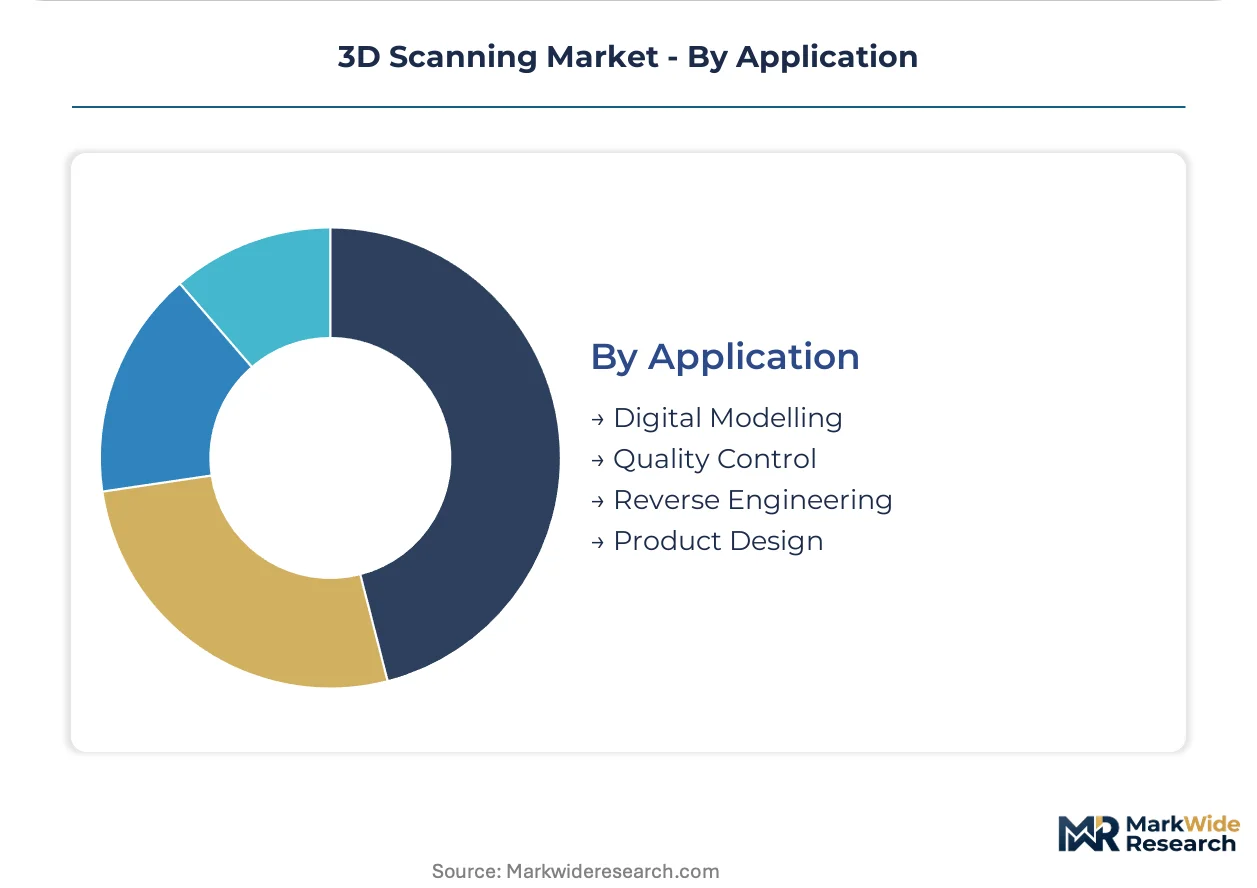
Application:
Application segmentation separates one-time digitization workflows from recurring quality assurance processes.
- Quality Control:Inline dimensional validation during production requires sub-micron repeatability and automated pass-fail reporting. German automotive plants integrate these systems directly into assembly line PLCs.
- Reverse Engineering:Capturing legacy part geometries for CAD reconstruction serves aftermarket aerospace and industrial equipment markets where original design data has degraded.
- Digital Modelling:Creating manipulable 3D assets from physical artifacts supports heritage preservation mandates in Italy, Greece, and Japan.
- Product Design:Iterative form exploration in consumer goods studios leverages rapid capture for design validation before tooling commitment.
Quality control leads volumes today; digital modelling is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial corridor anchors global 3D scanning demand through automotive OEMs and aerospace suppliers clustering around precision engineering hubs in Stuttgart, Wolfsburg, and Munich.
United States
FDA 510(k) clearance governs surgical planning and orthotic fabrication deployments across hospital networks. The IRA's domestic manufacturing incentives are accelerating metrology-grade scanner adoption in electric vehicle battery plants. Detroit and Austin industrial corridors concentrate demand for inline dimensional validation systems serving automotive and electronics sectors.
Germany
EU AI Act compliance mandates and CE marking under MDR are forcing equipment upgrades across automotive and aerospace supply chains. KBA certification requirements for measurement instruments tighten procurement specifications. Stuttgart, Wolfsburg, and Munich anchor demand for thermal runaway containment geometry verification in electric vehicle battery enclosures.
China
MIIT industrial upgrading programs and GB standards for precision measurement equipment are expanding domestic scanner production capacity. Dual carbon goals are accelerating metrology deployment in battery manufacturing. Yangtze River Delta and Pearl River Delta clusters concentrate demand for structured light systems in consumer electronics and automotive applications.
Japan
METI's manufacturing competitiveness initiatives and JIS calibration standards enforce traceable measurement uncertainty declarations. PMDA regulates medical scanning devices for surgical planning. Kanto and Kansai industrial regions concentrate aerospace and precision machinery demand, with Tokyo and Osaka serving as procurement centers for metrology-grade systems.
India
PLI scheme production-linked incentives for automotive and electronics sectors are creating first-mover openings for metrology-grade scanner deployment. BIS certification requirements for measurement instruments shape import specifications. Pune and Chennai industrial corridors concentrate emerging demand for quality control systems serving precision manufacturing investments.
3D Scanning Market Vendor Landscape
Global majors compete with regional champions across metrology software integration and photodetector supply chain control. The vendor base stratifies between integrated hardware-software providers and component specialists, with consolidation pressure intensifying around calibration laboratory networks. Three archetypes dominate: full-stack metrology platforms, handheld measurement specialists, and photonics component suppliers. M&A activity concentrates on software interoperability assets and regional service capability expansion.
Within the full-stack tier, Hexagon AB and FARO Technologies, Inc. exemplify divergent positioning strategies. Hexagon anchors backward integration into metrology software and CAD interoperability layers, while FARO occupies a distinct channel position against industrial-focused rivals through construction and public safety specialization. Creaform Inc. represents the handheld measurement archetype, leveraging proprietary self-positioning technology to dominate automotive plant workflows. Carl Zeiss Optotechnik GmbH sits within the precision optics tier, drawing on captive optical component expertise to serve aerospace certification requirements.
| Leading Market Players |
|---|
| Creaform Inc. |
| Carl Zeiss Optotechnik GmbH |
| Hexagon AB |
| Nikon Corporation |
| Artec 3D |
| FARO Technologies, Inc. |
| Autodesk, Inc. |
| GOM GmbH |
| 3D Systems, Inc. |
| Others |
Supply Flow & Price Mechanics
Metrology-grade certification tiers versus portable field units create a sharp bifurcation in both procurement economics and component sourcing strategies, with ISO 10360-traceable systems commanding premium positions through captive calibration laboratory networks while cost-optimized handheld units feed from commodity photodetector supply channels in Taiwan and South Korea.
Pricing Analysis
Silicon photodetector wafer costs pass through directly to scanner OEM bill-of-materials, compressing margins on entry-level structured light systems while premium laser triangulation units absorb input volatility through long-term foundry contracts. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-certified systems with documented measurement uncertainty from automotive inline units and consumer-grade dental scanners. Pricing pressure stems from SPMPD array supply concentration in East Asian foundries. Healthcare procurement committees show lowest price sensitivity due to FDA 510(k) clearance requirements, while consumer product design studios drive hardest bargaining on per-unit hardware costs.
Supply Chain Analysis
Refurbishment flows for metrology-grade systems extend asset lifecycles in German automotive plants, with certified pre-owned scanners trading through Hexagon and FARO service networks at 40-60% of replacement cost. Component manufacturing concentrates in Taiwan, South Korea, and Germany, with solid-state photodetector arrays sourcing from TSMC and Samsung foundries while precision optical assemblies feed from Carl Zeiss and Nikon captive production. Single-source vulnerability in SPMPD wafer supply exposes European and North American OEMs to geopolitical disruption. Distribution runs through direct enterprise sales for manufacturing accounts, with healthcare and construction segments served by specialized VAR channels with embedded calibration capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications are hardening across all end-use segments as EU AI Act compliance mandates and FDA 510(k) clearance requirements institutionalize premium-tier procurement criteria, rewarding vendors with pre-validated metrology firmware and documented algorithmic transparency.
For Market Incumbents: Hedge against photodetector supply concentration by securing dual-source agreements with Taiwan and South Korean foundries, while consolidating regional calibration laboratory networks to defend service revenue streams from emerging cloud-based metrology challengers. Backward integration into metrology software stacks remains essential for CAD interoperability defense. For New Entrants and Emerging Players: Direct-to-dental-practice digital channels bypass entrenched distribution control in European healthcare markets, offering sub-hundred-micron structured light systems on subscription pricing to orthodontic workflows in Switzerland and the Netherlands. Target India's PLI scheme corridors in Pune and Chennai for first-mover manufacturing quality control deployments. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier scanner OEMs lack captive photonics expertise and regional service infrastructure. Long-term viability favors integrated hardware-software platforms with ISO 10360-accredited calibration networks. Monitor FDA 510(k) clearance timeline compression and EU AI Act implementation rigor as inflection signals for medical segment margin pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Laboratory Network Expansion | ISO 10360 traceability requirements in German aerospace and automotive procurement specifications mandate regional accreditation coverage. |
| Silicon Photodetector Supply Diversification | Dual-source agreements with Taiwan and South Korean foundries reduce single-point vulnerability in SPMPD array procurement. |
| Metrology Software Stack Integration | Backward integration into CAD interoperability layers defends against proprietary point cloud format fragmentation. |
| Outcome-Based Service Contract Deployment | Per-inspection pricing transfers capital risk to vendors while capturing recurring revenue from Bavarian automotive tier-one suppliers. |
| On-Device Computational Photonics Development | Edge intelligence capabilities collapse hardware footprints for mining survey and disaster response field applications. |
Methodological Framework
Direct dialogue with metrology equipment procurement managers at German automotive OEMs, biomedical engineers at Swiss healthcare systems, optical calibration specialists at aerospace tier-one suppliers, and aftermarket service directors at scanner distributors grounded qualitative findings in operational reality. Secondary validation drew from FDA 510(k) clearance databases, EU MDR technical documentation filings, ISO 10360 accreditation registries, and customs trade data for photodetector component flows. Bottom-up demand modeling triangulated against top-down market sizing across product type, technology, and end-use segmentation dimensions.
Bottom-up unit economics analysis across laser, structured light, and optical scanner architectures reconciled with top-down spending patterns from automotive, aerospace, and healthcare procurement budgets throughout the projection horizon. Modeled segmentation dimensions included product type, technology, end-user vertical, application workflow, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating technology substitution rates and compliance-driven replacement cycles. Industry-specific forecast inputs encompassed EU AI Act implementation timelines and FDA 510(k) clearance velocity trends.
Geopolitical disruption in Taiwan Strait semiconductor supply, abrupt tightening of EU MDR enforcement posture, and accelerated photogrammetry substitution in entertainment applications are the dominant revision risks to modeled demand. Forecasts embed assumptions regarding continued foundry capacity expansion and stable regulatory interpretation of algorithmic transparency requirements. Practitioners should monitor SPMPD wafer pricing volatility, CE marking audit intensity, and passive capture technology advancement for early signals of forecast deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Technology
UK 3D Rendering Services Market
3D Technology
3D Photogrammetry Software Market
3D Technology
3D Point Cloud Processing Software Market
3D Technology
Molecular Modeling Market
3D Technology
Smartphone 3D Camera Market
3D Technology
3D Printing CAD Software Market
3D Technology
Glasses Free 3D Tvs Market
3D Technology
Global 3D Mapping and 3D Modeling Market
3D Technology
3D Simulation Software Market
3D Technology
Mobile 3D Market
3D Technology
3D Rendering Market
3D Technology
Contactless 3D Laser Scanner Market
3D Technology
Digital Holography Market
3D Technology
Global Mobile 3D Sensing Market
3D Technology
3D Scanner Market
3D Technology
Global 3D Architecture Software Market