
 Global 3D Rendering Service Market | 2026-2036
Global 3D Rendering Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global 3D Rendering Service Market Foresight
Pipeline artist shortages across North America and Western Europe is unwinding delivery timelines for photorealistic architectural projects. DBOX sustains premium positioning through proprietary workflows for luxury real estate developers. PixelPool leverages cloud-native infrastructure to serve mid-market manufacturing clients without dedicated render farms. Neoscape anchors its competitive position through deep specialization in unbuilt property marketing across major metropolitan corridors.
3D rendering services encompass the computational transformation of wireframe models into photorealistic or stylized imagery through ray-tracing, rasterization, or path-tracing algorithms executed on CPU and GPU clusters, typically outputting frames at resolutions from 1080p to 8K with physically accurate lighting simulation. These services enable stakeholders to evaluate designs, market properties, and prototype products without physical fabrication. Cloud rendering now leads service type adoption as elastic compute eliminates capital-intensive farm ownership, while real-time rendering represents the fastest-expanding segment driven by Unreal Engine and Unity adoption in automotive and AEC workflows. Architecture visualization remains the dominant application by revenue, though virtual reality deployments for property walkthroughs are capturing disproportionate growth investment from construction firms and media agencies.
FDA oversight of medical device visualization, EU AI Act provisions affecting generative render pipelines, and China's GB standards for digital content distribution each reshape compliance burdens and market access conditions for cross-border service providers. ISO 27001 certification increasingly functions as a de facto procurement gate for enterprise clients handling sensitive product designs. Stakeholders must monitor evolving data residency requirements as sovereign cloud mandates proliferate across jurisdictions with significant AEC and manufacturing bases.
Market Dynamics
GPU virtualization standards from Khronos Group are compressing compute barriers for mid-sized architectural visualization agencies, redistributing competitive capability across service tiers previously separated by capital-intensive render farm ownership.
Growth Catalysts
- EU AI Act provisions:Generative render pipeline compliance requirements in Europe are accelerating enterprise investment in certified service providers with documented data provenance controls.
- Automotive OEM mandates:German manufacturers now require real-time render pipelines for design reviews, pulling demand toward Unreal Engine and Unity service specialists.
- Cloud-native infrastructure:Elastic compute adoption eliminates capital-intensive farm ownership for mid-market manufacturing clients in North America.
Market Restraints
- Pipeline artist shortages:Talent scarcity across North America and Western Europe unwinds delivery timelines for photorealistic architectural projects.
- ISO 27001 certification costs:De facto procurement gates for enterprise clients handling sensitive product designs impose compliance burdens on smaller service providers.
- Sovereign cloud mandates:Data residency requirements proliferating across jurisdictions with significant AEC bases fragment cross-border service delivery.
Strategic Opportunities
- Virtual reality deployments:Property walkthroughs for construction firms and media agencies capture disproportionate growth investment in unpenetrated metropolitan corridors.
- Medical device visualization:FDA oversight creates compliance-specialist white space for service providers with validated rendering pipelines.
- China's GB standards:Digital content distribution mandates open localized partnership opportunities for foreign providers meeting certification requirements.
Industry Challenges
- Ray-tracing specialist recruitment:Path-tracing algorithm expertise remains concentrated among senior technical artists, constraining team scaling.
- Legacy CAD integration:Rasterization workflow compatibility with established architectural software suites requires bespoke pipeline engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 3D Rendering Service Market |
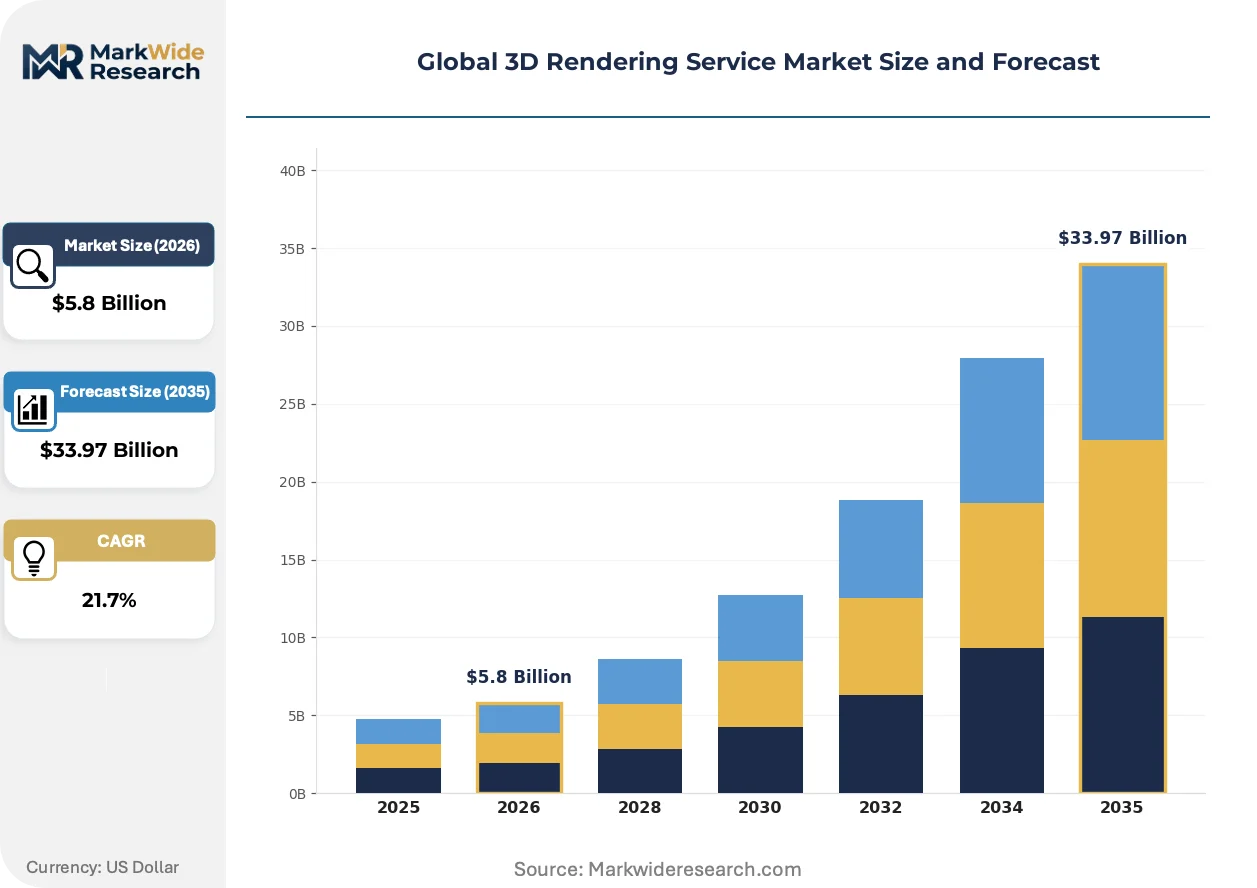
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $33.97 Billion |
| CAGR (2026 – 2036) | 21.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cloud Rendering, On-Premise Rendering, Hybrid Rendering, Real-Time Rendering, Batch Rendering Application: Architecture Visualization, Product Prototyping, Animation & Film, Advertising & Marketing, Virtual Reality End User Industry: Construction Firms, Manufacturing Companies, Media Agencies, Educational Institutions, Entertainment Studios Deployment Model: Public Cloud, Private Cloud, Dedicated Servers, Edge Computing, Colocation |
| Companies Covered | Maverick Frame Studio, NoTriangle Studio, DBOX, PixelPool, Render4tomorrow Studio, Neoscape, Arktek 3D Studio, Brick Visual, ThePro3DStudio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 3D Rendering Service Market Shifts & Advancements
Real-time rendering engines are compressing production cycles across automotive and AEC workflows, while regulatory compliance frameworks reshape procurement criteria for cross-border service contracts.
Neural rendering pipelines using AI-accelerated denoising and light transport simulation are fragmenting traditional CPU-bound ray-tracing service tiers. Automotive design studios in Germany and Japan adopt these tools for overnight iteration cycles previously requiring week-long farm queues. The technology is fragmenting price-performance benchmarks across premium and mid-market service segments.
China's GB standards for digital content distribution now mandate traceability metadata for all commercial render outputs. Foreign service providers must establish localized infrastructure partnerships to maintain market access. Medical device and automotive visualization segments face the steepest compliance adaptation curves.
Subscription-based render credit systems displace perpetual farm licensing among mid-sized architectural practices. Channel relationships with software distributors in France and the United Kingdom now prioritize usage-based pricing over hardware procurement. This shift concentrates buyer power among platforms with elastic capacity guarantees.
Global 3D Rendering Service Market Segmentation
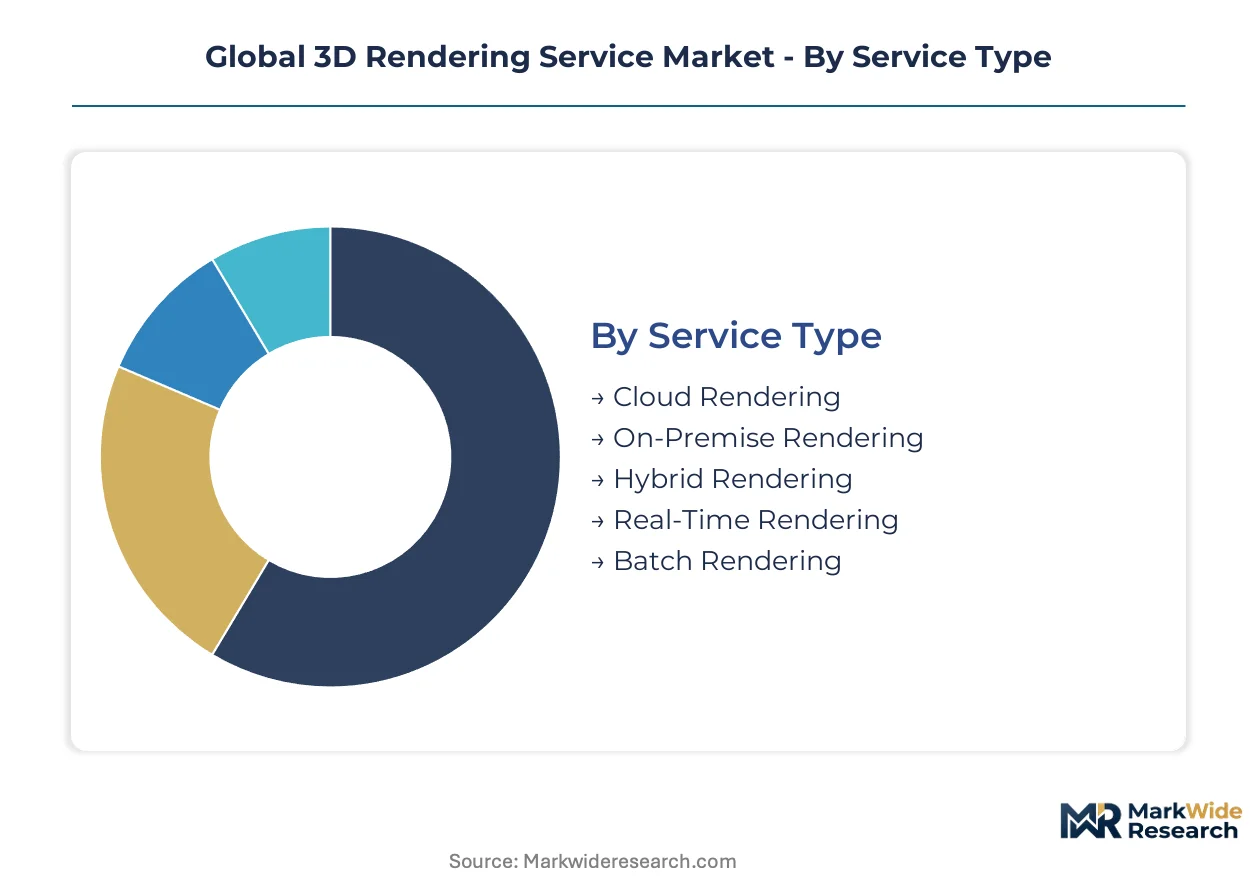
3D rendering service demand fragments across compute modalities, visual output requirements, and client technical maturity. Substitution pressures from neural rendering and game-engine pipelines are redrawing competitive boundaries between traditional service tiers.
Service Type:
Neural denoising tools and real-time engines are compressing substitution windows for batch-processed CPU rendering, redistributing value toward elastic and interactive compute models.
- Cloud Rendering:Elastic GPU clusters execute ray-tracing and path-tracing workloads without client-side farm ownership. North American architectural practices now default to usage-based models, eliminating capital recovery cycles for hardware depreciation.
- Real-Time Rendering:Unreal Engine and Unity pipelines output interactive frames at 60fps for automotive design reviews. German OEM mandates are pulling demand from offline batch services toward engine-specialist providers with blueprint integration expertise.
- On-Premise Rendering:Captive CPU/GPU farms serve defense contractors and IP-sensitive product designers in Japan with air-gapped security requirements.
- Hybrid Rendering:Combines local pre-visualization with cloud final-frame execution for mid-sized animation studios managing variable pipeline loads.
- Batch Rendering:Overnight queue-based processing for feature-film VFX sequences requiring 8K+ resolution with physically accurate light transport.
Cloud rendering anchors the volume base while real-time rendering gains share at the steepest rate.
Application:
Client procurement maturity varies sharply across use cases, with unbuilt property marketing commanding premium pricing and virtual reality deployments absorbing disproportionate platform investment.
- Architecture Visualization:Photorealistic exterior and interior imagery for pre-construction sales collateral. North American luxury developers now require 48-hour turnaround on design revisions, compressing traditional 2-week farm queues.
- Virtual Reality:Walkthrough deployments for construction firms and media agencies capture platform investment in unpenetrated metropolitan corridors across France and the United Kingdom.
- Product Prototyping:Manufacturing clients in Germany validate industrial designs without physical fabrication, integrating with Siemens NX and Dassault CATIA workflows.
- Animation & Film:Feature and episodic content pipelines in Japan and South Korea require path-tracing accuracy for character rendering.
- Advertising & Marketing:Campaign imagery for consumer brands with shorter creative cycles and lower technical specification thresholds.
Architecture visualization commands the revenue concentration while virtual reality expands most quickly as headset penetration crosses enterprise procurement thresholds.
End User Industry:
Technical staffing depth and procurement sophistication create tiered service relationships, with construction and manufacturing clients consolidating spend among certified providers.
- Construction Firms:Pre-sales visualization for speculative development and municipal approval processes. ISO 27001 certification functions as a de facto gate for enterprise clients handling sensitive project designs.
- Manufacturing Companies:Automotive and industrial equipment designers in Germany and Japan mandate real-time pipeline integration for cross-functional design reviews.
- Media Agencies:Campaign asset production with compressed timelines and variable technical requirements.
- Entertainment Studios:Feature film and episodic content with established vendor relationships and proprietary pipeline requirements.
- Educational Institutions:Curriculum visualization and research applications with constrained procurement budgets.
Construction firms anchor the volume base while manufacturing companies gain share at the steepest rate.
Deployment Model:
Data residency mandates and latency requirements are fragmenting infrastructure choices across jurisdictions with significant AEC and manufacturing bases.
- Public Cloud:Shared GPU instances with elastic scaling for variable render workloads. China's GB standards for digital content distribution now mandate traceability metadata, forcing localized partnership structures.
- Private Cloud:Dedicated tenant environments for healthcare and defense visualization with HIPAA and ITAR compliance requirements in the US.
- Edge Computing:Distributed nodes for real-time automotive design reviews requiring sub-20ms latency between studio and compute.
- Dedicated Servers:Single-tenant hardware for IP-sensitive product development with contractual exclusivity guarantees.
- Colocation:Client-owned hardware in third-party facilities balancing capital control with operational outsourcing.
Public cloud anchors the volume base while private cloud gains share at the steepest rate amid sovereign data mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA oversight of medical device visualization shapes procurement criteria for enterprise clients across the United States. German automotive OEM mandates and China's GB standards for digital content distribution each redirect service provider investment toward certified infrastructure.
United States
Luxury real estate developers in New York and Los Angeles now demand 48-hour turnaround on design revisions. HIPAA compliance requirements for healthcare visualization push providers toward private cloud deployments with air-gapped security. Greater Boston anchors specialized medical device rendering pipelines serving FDA-regulated clients.
Germany
Automotive OEMs in Stuttgart and Munich mandate real-time render pipelines for cross-functional design reviews. EU AI Act provisions on generative render pipeline compliance accelerate enterprise investment in certified providers. Bavaria concentrates Unreal Engine and Unity service specialists with blueprint integration expertise.
China
GB standards for digital content distribution mandate traceability metadata for all commercial render outputs. MIIT cloud certification requirements force localized infrastructure partnerships for foreign providers. Shanghai and Shenzhen host the steepest compliance adaptation curves for medical device and automotive visualization segments.
United Kingdom
Channel relationships with software distributors in London prioritize usage-based pricing over hardware procurement. GDPR data residency requirements fragment cross-border service delivery for construction firms handling sensitive project designs. Manchester and Birmingham emerge as cost-competitive alternatives to capital-based visualization studios.
Japan
Defense contractors and IP-sensitive product designers in Tokyo require air-gapped security with captive CPU/GPU farms. METI industrial policy supports domestic rendering infrastructure for automotive and manufacturing workflows. Osaka and Nagoya anchor real-time pipeline integration serving Siemens NX and Dassault CATIA users.
Global 3D Rendering Service Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with proprietary workflow differentiation separating premium positioning from commodity service provision. Cloud-native infrastructure and real-time engine expertise now define capability boundaries more sharply than raw compute ownership. Three archetypes dominate: luxury real estate specialists with bespoke pipelines, mid-market manufacturing enablers leveraging elastic capacity, and automotive-focused real-time integrators. Consolidation pressures favor acquisition of engine-specialist teams, while geographic expansion through localized infrastructure partnerships addresses data residency mandates.
Within the premium-tier vector, DBOX exemplifies positioning through proprietary workflows for luxury real estate developers. PixelPool occupies a position among cloud-native specialists serving mid-market manufacturing clients without dedicated render farms. Neoscape anchors the unbuilt property marketing specialization across major metropolitan corridors. These three represent divergent strategic bets on workflow ownership, infrastructure elasticity, and vertical focus respectively.
| Leading Market Players |
|---|
| Maverick Frame Studio |
| NoTriangle Studio |
| DBOX |
| PixelPool |
| Render4tomorrow Studio |
| Neoscape |
| Arktek 3D Studio |
| Brick Visual |
| ThePro3DStudio |
| Others |
Supply & Pricing Matrix
ISO 27001 certification functions as a simultaneous gate for supply qualification and price differentiation, separating enterprise-grade providers with documented data provenance from commodity render farms competing on per-frame rates. German automotive OEMs and US healthcare clients pay premiums for certified pipelines while mid-market architectural practices default to elastic cloud credits.
Pricing Analysis
Project-based contracts dominate premium architectural visualization while subscription render credits capture mid-market manufacturing clients. Pricing stratifies across certified enterprise tiers, ISO 27001-compliant providers, and uncertified commodity farms. Cost compression in batch-rendered CPU services intensifies as neural denoising tools displace traditional farm queues. Price-sensitive buyers cluster among independent architects and educational institutions, while defense contractors and luxury developers exhibit minimal elasticity.
Supply Chain Analysis
Render queue backlogs now stretch 48-72 hours for high-resolution architectural frames during peak demand windows. GPU hardware concentrates in Taiwan, South Korea, and the United States. NVIDIA A100 and H100 clusters draw from TSMC foundry output and SK Hynix memory supply. Single-source vulnerability in advanced node semiconductor fabrication threatens capacity expansion timelines. Distribution runs through hyperscaler marketplaces and direct channel relationships with visualization software distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise capital expenditure cycles in construction and automotive are inflecting upward, pulling 3D rendering demand through its trough. This cyclical recovery concentrates procurement among certified providers with elastic capacity guarantees.
For Market Incumbents: Consolidate through acquisition of Unreal Engine and Unity specialist teams as automotive OEMs mandate real-time pipeline integration. Defend margin position by deepening proprietary workflow moats in luxury real estate verticals where DBOX and Neoscape anchor premium positioning. ISO 27001 certification investment gates enterprise construction contracts worth multiples of uncertified project revenue. For New Entrants and Emerging Players: Differentiate on FDA-validated medical device visualization pipelines, a compliance-specialist white space with concentrated buyer power in Greater Boston. Target China's GB standards-compliant localization partnerships as foreign providers face MIIT certification barriers. Go-to-market through Shanghai and Shenzhen infrastructure partnerships rather than direct cloud marketplace listings. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native service tiers as GPU virtualization standards from Khronos Group compress render farm ownership requirements. Long-term viability favors platform plays with elastic capacity guarantees over captive hardware models. Watch Unreal Engine and Unity blueprint integration expertise as the inflection signal for acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Real-Time Engine Specialists | Captures German automotive OEM mandates for Unreal Engine and Unity integration. |
| ISO 27001 Certification Investment | Opens enterprise construction procurement gates handling sensitive project designs. |
| Localized China Infrastructure Partnership | Enables GB standards compliance for traceability metadata on commercial render outputs. |
| FDA-Validated Pipeline Development | Creates compliance moat in medical device visualization serving regulated healthcare clients. |
| Neural Rendering Capability Integration | Compresses overnight iteration cycles for Japanese automotive design studios. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across architectural visualization studios, automotive design departments, and healthcare visualization teams. Primary interviews captured pipeline directors at DBOX, PixelPool, and Neoscape alongside procurement leads at German OEMs and US construction firms. Secondary validation drew from Khronos Group GPU virtualization standards, FDA medical device guidance documents, and China's GB digital content distribution mandates. Bottom-up service provider revenue triangulation against top-down end-user expenditure patterns anchored market sizing.
Across the analysis window, forecasts modeled service type segmentation across cloud, real-time, and batch rendering modalities alongside application dimensions in architecture visualization, virtual reality, and product prototyping. CAGRs derived from elastic compute adoption curves and real-time engine penetration rates in automotive workflows. Neural rendering displacement timelines and sovereign cloud mandate proliferation served as industry-specific sensitivity inputs.
Material uncertainties — regulatory enforcement intensity of EU AI Act provisions, TSMC advanced node allocation for GPU fabrication, and German automotive capex inflection timing — sit outside the modeled envelope. Forecasts reflect assumptions on certification adoption rates and hyperscaler capacity expansion commitments. Revision becomes warranted when GPU virtualization standard adoption crosses enterprise procurement thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Technology
Latin America 3D 4D Technology Market
3D Technology
3D Reconstruction Market
3D Technology
3D Technology Market
3D Technology
3D Point Cloud Processing Software Market
3D Technology
3D Machine Vision Market
3D Technology
Europe 3D 4D Technology Market
3D Technology
Mobile 3D Market
3D Technology
3D Scanning Market
3D Technology
3D Mobile Mapping Market
3D Technology
Generative Design Market
3D Technology
3D Simulation Software Market
3D Technology
3D Rendering Software Market
3D Technology
3D Scanner Market
3D Technology
Global Mobile 3D Sensing Market
3D Technology
LAMEA Smartphone 3D Camera Market
3D Technology
3D CAD Market