
 North America 3D 4D Technology Market | 2026-2036
North America 3D 4D Technology Market Size, Share, and Industry Trends Forecast 2026-2036
North America 3D 4D Technology Market Analytics
Multi-source component procurement is decoupling from the single-vendor legacy that dominated early 3D printing hardware supply chains. 3D Systems Corporation leverages captive resin formulations and direct metal laser sintering platforms to sustain technology leadership in healthcare and aerospace tooling. Stratasys, Inc. anchors industrial polymer printing through its extensive service bureau network across the United States and Mexico.
3D 4D technology encompasses volumetric visualization, additive fabrication, spatial motion capture, and time-variant holographic display systems operating through stereoscopic rendering, structured light projection, or photopolymerization processes with layer resolutions below 50 microns, serving functions from preoperative anatomical modeling to real-time immersive entertainment. Display technology and projectors occupy the largest installed base across cinema and theme park deployments, though scanners and software command superior margin profiles in metrology and digital twin workflows. Manufacturing applications of 3D printing and motion capture are expanding fastest as automotive and aerospace OEMs qualify flight-critical and drivetrain components for serial production.
FDA device regulations, FCC spectrum allocations for wireless VR systems, and OSHA additive manufacturing safety standards collectively shape product development cycles and facility certification requirements across the United States. Health Canada and Mexico's national standards body add parallel compliance layers for cross-border equipment deployment. Stakeholders must monitor how evolving FDA guidance on patient-specific implants intersects with state-level digital health privacy statutes to anticipate certification timelines and liability exposure.
Market Dynamics
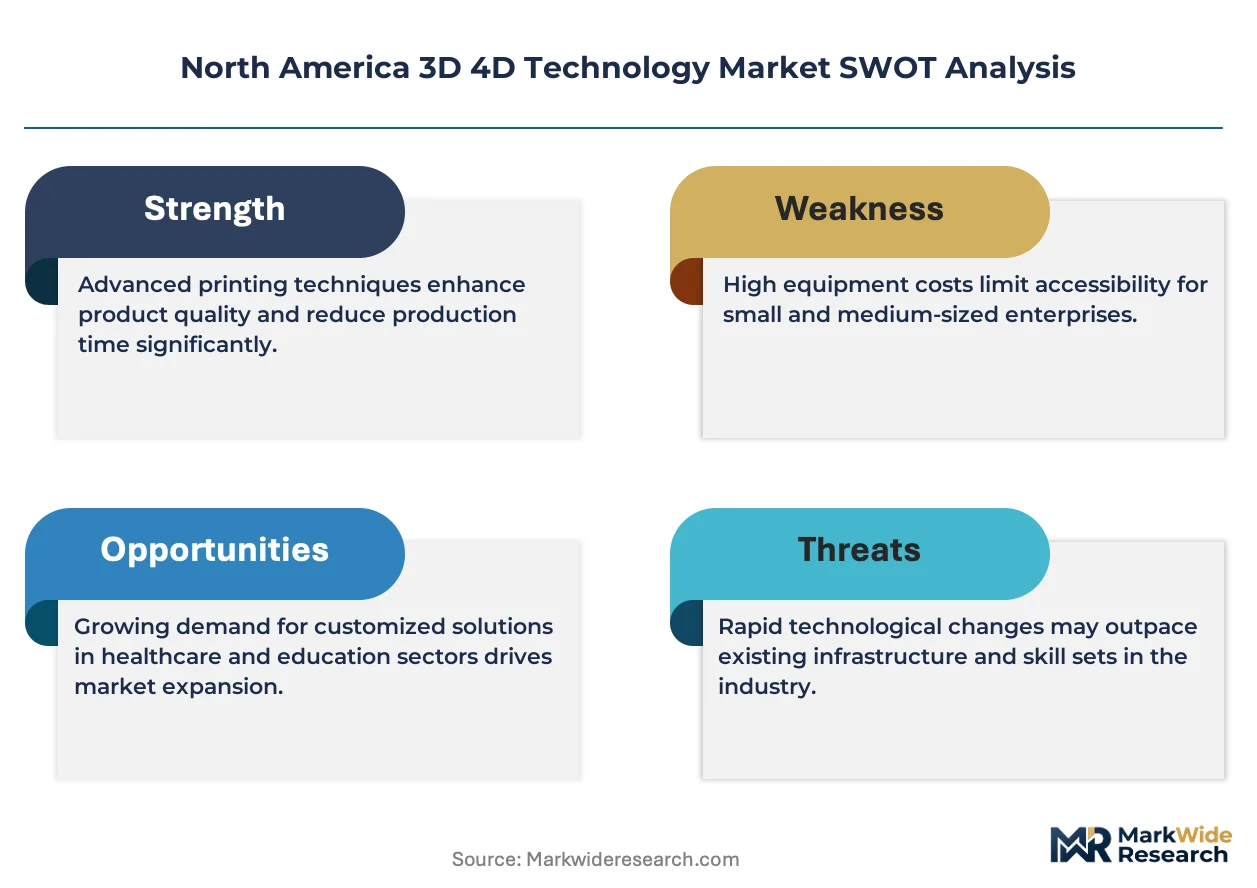
FDA's evolving guidance on patient-specific 3D-printed implants is compressing product development cycles while elevating compliance costs for healthcare hardware vendors across the United States and Canada.
Growth Catalysts
- Preoperative Surgical Planning:Hospitals in California and Texas are deploying 3D-printed anatomical models for complex cardiac and orthopedic procedures, reducing operative time and improving patient outcomes.
- OSHA Additive Manufacturing Standards:Clarified safety protocols for metal powder handling and laser operations are accelerating facility certifications and industrial adoption across the United States.
- Photopolymerization Advances:Sub-50 micron layer resolution in resin-based systems is displacing traditional injection molding for short-run medical device components and dental prosthetics.
Market Restraints
- Captive Resin Supply Concentration:Proprietary photopolymer formulations from a limited supplier base in the northeastern United States create input cost volatility and lock-in risk for healthcare 3D printing operations.
- FCC Spectrum Allocation Uncertainty:Unlicensed wireless VR and holographic display systems face interference constraints and certification delays for theme park and cinema deployments.
- Health Canada Parallel Compliance:Cross-border equipment deployment requires redundant testing and documentation, extending timelines for United States-based manufacturers entering Canadian healthcare markets.
Strategic Opportunities
- Mexico Manufacturing Integration:Automotive OEMs in Nuevo León and Baja California are qualifying 3D-printed tooling and jigs for serial production, creating demand for localized service bureau networks.
- Digital Twin Convergence:Integration of motion capture data with real-time holographic displays is opening immersive training applications for aerospace maintenance and emergency response simulation.
- State-Level Digital Health Privacy Statutes:Evolving patient data protection frameworks in California and New York are creating compliance-as-a-service revenue streams for 3D imaging software vendors.
Industry Challenges
- Biocompatibility Certification Timelines:FDA 510(k) clearance for novel photopolymer resins in long-term implant applications requires 18-36 month validation cycles, compressing R&D ROI windows.
- Metrology Talent Scarcity:Shortage of technicians qualified in structured light scanning and point cloud processing is constraining digital twin deployment velocity in aerospace supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America 3D 4D Technology Market |
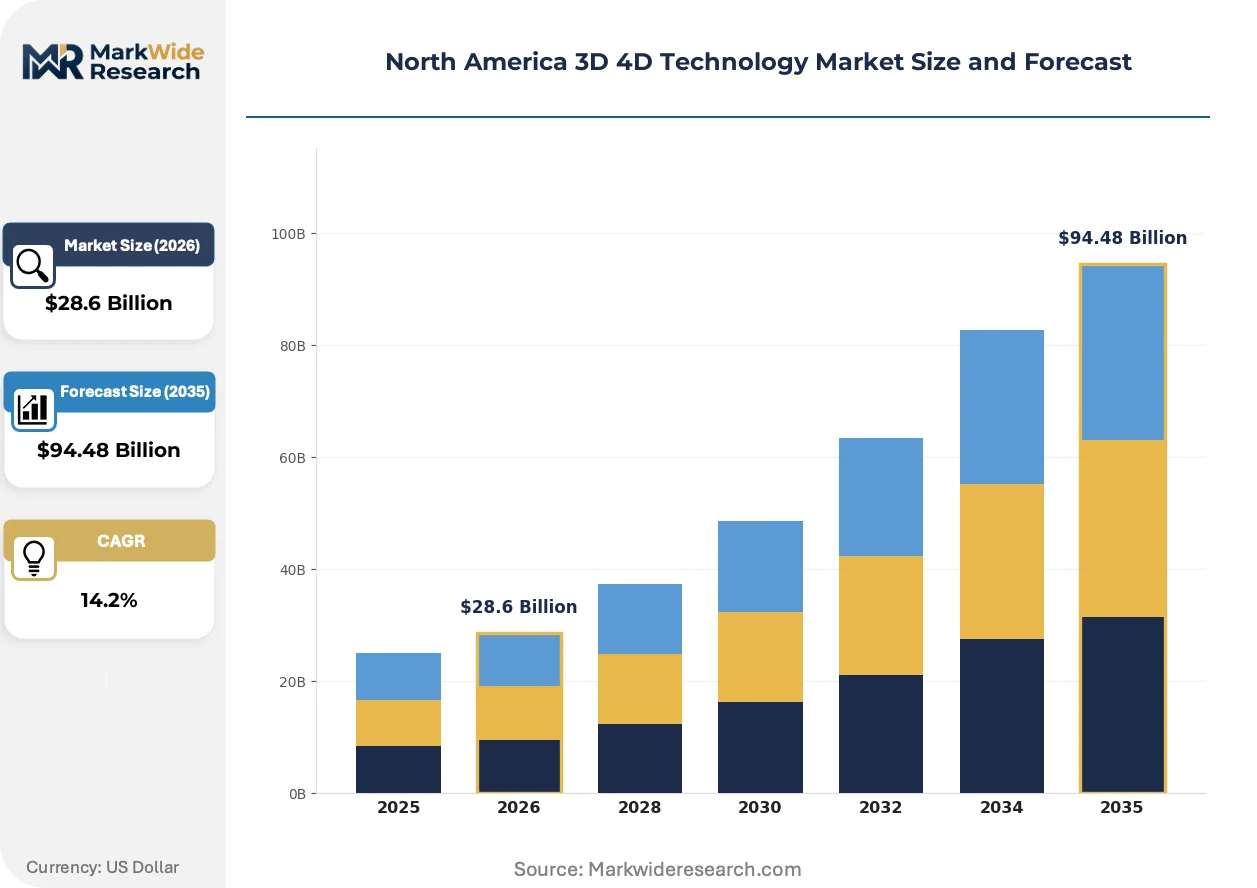
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $94.48 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
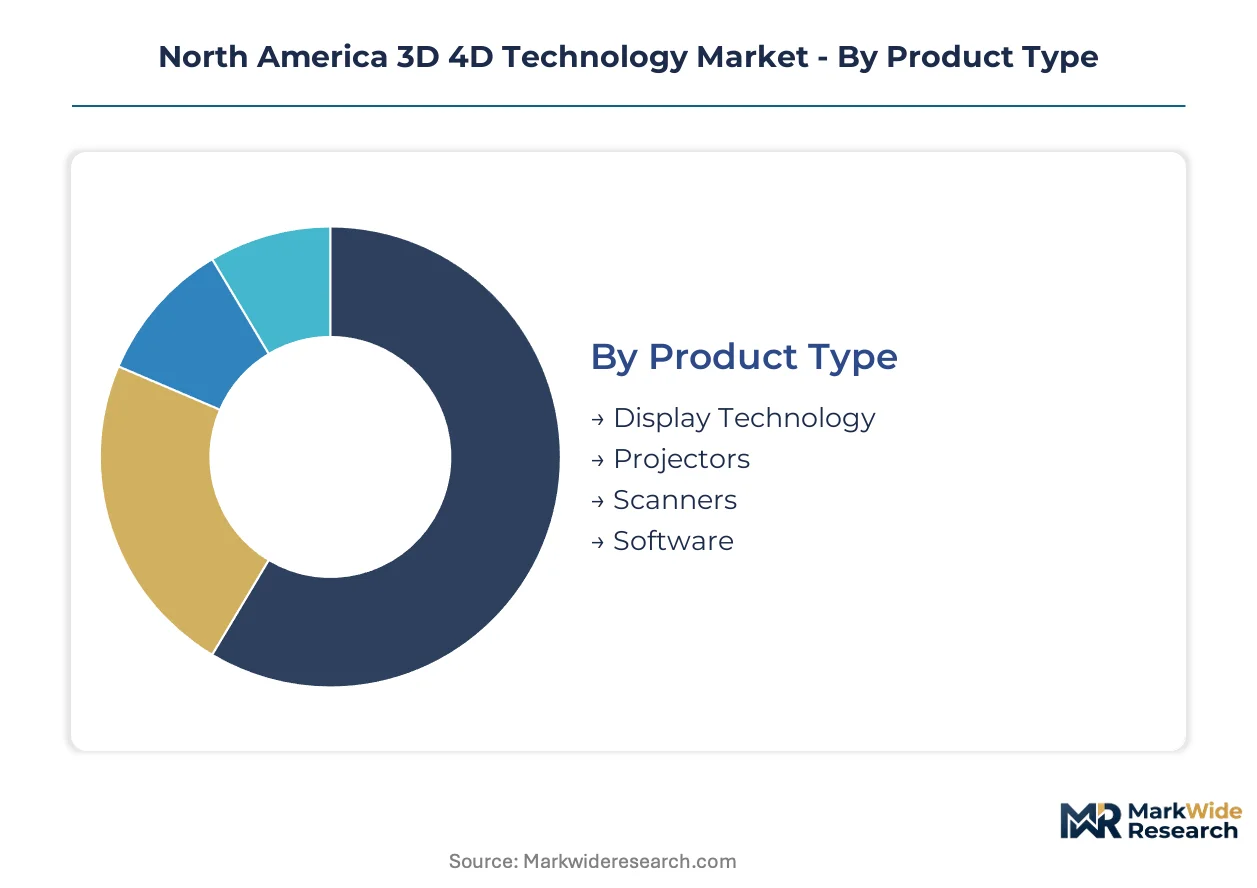
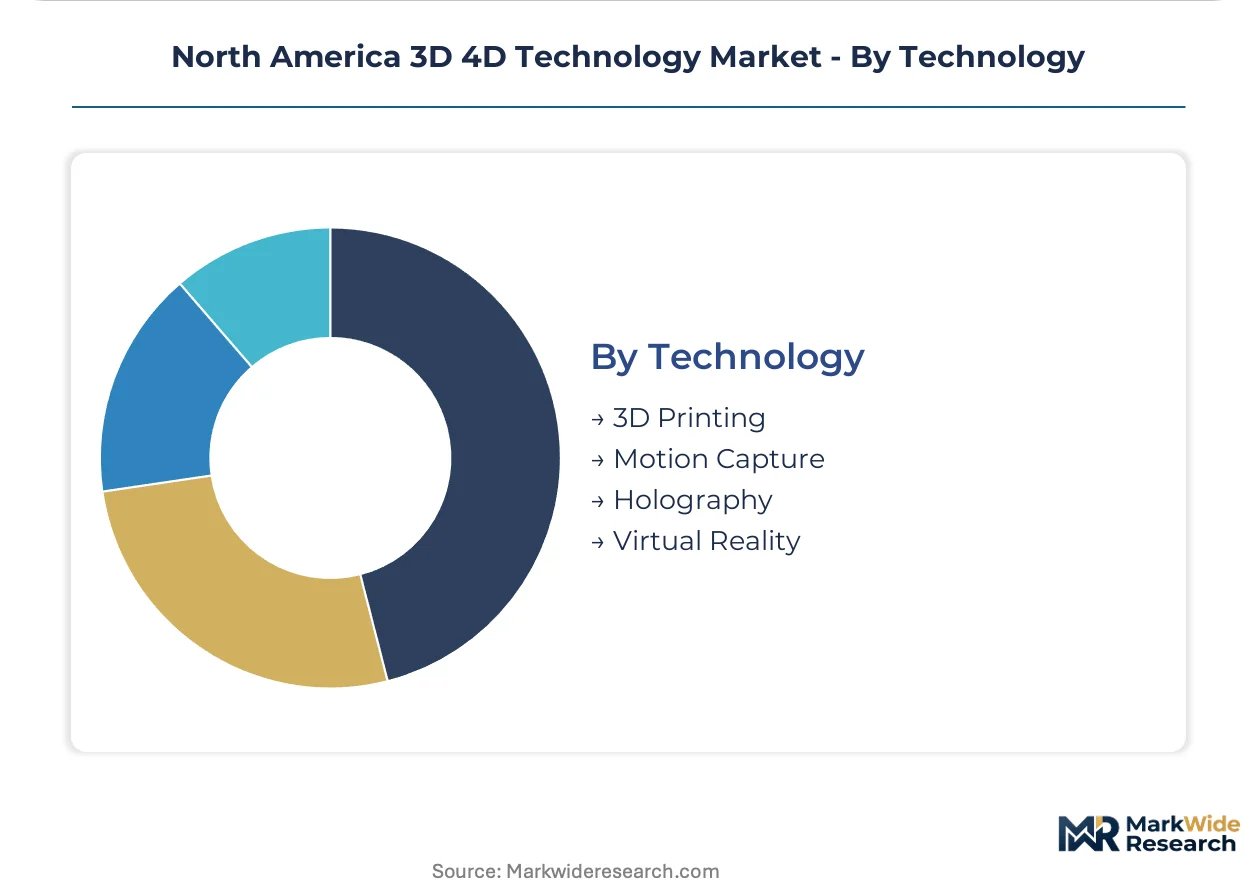
| Segmentation | Product Type: Display Technology, Projectors, Scanners, Software Application: Entertainment, Healthcare, Education, Manufacturing End User: Retail, Film Industry, Medical Institutions, Educational Institutions Technology: 3D Printing, Motion Capture, Holography, Virtual Reality |
| Companies Covered | 3D Systems Corporation, Dolby Laboratories, Inc., Samsung Electronics Co., Ltd., LG Electronics Inc., Barco N.V., Stratasys, Inc., Autodesk, Inc., Sony Corporation, FARO Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America 3D 4D Technology Market Evolving Landscape
Multi-material deposition and real-time process monitoring are converging to enable flight-critical component qualification, while regulatory clarity on software-as-a-medical-device reshapes competitive boundaries.
Continuous liquid interface production is overtaking conventional layer-by-layer stereolithography in dental and audiology applications. Orthodontic labs in California and Florida are adopting these systems to compress production cycles for clear aligner molds from hours to minutes. The technology is overtaking legacy equipment by eliminating peel-force defects and enabling transparent material properties previously unattainable with vat polymerization.
FDA's updated guidance on 3D-printed medical devices establishes patient-matched device categories with modified predicate requirements. The framework reduces premarket notification burdens for anatomical models while elevating scrutiny for load-bearing implants. Canadian hospitals and United States academic medical centers are responding by segregating procurement workflows between visualization tools and permanent implant hardware.
Film studios and visual effects houses are consolidating vendor relationships around integrated hardware-software bundles for 4D display systems. Premium holography procurement in Los Angeles and Vancouver is shifting from component sourcing to outcome-based performance contracts covering installation, content pipeline integration, and maintenance. This bundling is most visible in theme park deployments where operators demand guaranteed uptime for motion-platform synchronized experiences.
North America 3D 4D Technology Market Segmentation
Technology buyers across North America fragment sharply by procurement sophistication and compliance burden. Hospital systems, film studios, and automotive OEMs operate on fundamentally different evaluation timelines and vendor qualification criteria.
Product Type:
Hardware buyers prioritize resolution specifications and service network density; software purchasers weight integration depth and regulatory documentation.
- Display Technology:Volumetric and autostereoscopic panels dominate cinema and theme park deployments across California and Florida. Demand concentrates in Los Angeles entertainment corridors where operators demand sub-100ms latency for motion-platform synchronization.
- Projectors:Structured light and laser-based systems serve metrology workflows in aerospace supply chains. Texas and Washington state manufacturers drive replacement cycles as FCC spectrum clarity enables wireless holographic transmission.
- Scanners:Structured light and photogrammetry systems capture anatomical and industrial geometries.
- Software:Point cloud processing and digital twin platforms command recurring revenue models.
Volume sits with Display Technology; growth tilts toward Software.
Application:
End-use economics determine technology selection more than hardware specifications.
- Entertainment:4D cinema and immersive experience operators in Vancouver and Orlando deploy integrated motion-platform and holographic systems. Premium procurement concentrates where operators guarantee uptime through outcome-based performance contracts.
- Healthcare:Preoperative anatomical modeling and surgical planning drive resin-based 3D printing adoption. FDA's evolving patient-specific implant guidance is compressing product development cycles for United States and Canadian hospital systems.
- Education:Medical schools and technical institutes deploy motion capture for procedural training.
- Manufacturing:Automotive and aerospace OEMs qualify flight-critical components for serial production.
Entertainment captures installed base leadership; Healthcare climbs the fastest on regulatory tailwinds.
End User:
Procurement authority and budget cycles vary dramatically across institutional categories.
- Retail:Augmented reality fitting rooms and holographic product displays attract capital from flagship operators in New York and Toronto. Deployment accelerates where landlords subsidize experiential technology to drive foot traffic.
- Film Industry:Visual effects houses in Los Angeles and Vancouver consolidate vendor relationships around bundled hardware-software-content pipelines. Premium holography procurement shifts from component sourcing to guaranteed performance outcomes.
- Medical Institutions:Academic medical centers and community hospitals operate on diverging FDA compliance timelines.
- Educational Institutions:Universities and technical colleges prioritize training system durability and curriculum integration.
Film Industry anchors revenue concentration; Medical Institutions gain share fastest on surgical planning adoption.
Technology:
Underlying process physics determines addressable market boundaries and margin structures.
- 3D Printing:Photopolymerization and direct metal laser sintering serve dental, orthopedic, and aerospace tooling applications. Sub-50 micron layer resolution is displacing injection molding for short-run medical device components.
- Motion Capture:Optical and inertial systems feed real-time data into holographic displays for immersive training. Integration with digital twin platforms opens aerospace maintenance and emergency response simulation markets.
- Holography:Volumetric and light-field displays enable glasses-free 3D visualization.
- Virtual Reality:Head-mounted and cave-based systems serve design review and therapeutic applications.
3D Printing holds volume leadership; Motion Capture shows steepest expansion trajectory on convergence with holographic display systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Photopolymer resin manufacturing clusters in the northeastern United States supply feedstock for healthcare 3D printing operations across the continent. FDA device regulations and Health Canada compliance frameworks create divergent certification pathways for cross-border equipment deployment. Mexico's automotive manufacturing corridors are accelerating adoption of additive tooling for serial production.
United States
California's entertainment technology corridor drives premium holography procurement for film studios and theme park operators. FDA evolving guidance on patient-specific implants compresses product development cycles while elevating compliance scrutiny for load-bearing medical hardware. Texas and Washington state aerospace manufacturers qualify flight-critical components through structured light metrology and direct metal laser sintering platforms.
Canada
Health Canada parallel compliance requirements extend equipment certification timelines for United States-based manufacturers entering Canadian healthcare markets. British Columbia and Ontario academic medical centers segregate procurement workflows between anatomical visualization tools and permanent implant hardware. Vancouver visual effects houses consolidate vendor relationships around integrated 4D display and motion capture bundles.
Mexico
Automotive OEMs in Nuevo León and Baja California qualify 3D-printed tooling and jigs for serial production, creating localized demand for service bureau networks. Mexico's national standards body adds compliance layers for cross-border equipment deployment in manufacturing corridors. Mexico City Metro medical institutions deploy resin-based anatomical modeling for surgical training applications.
North America 3D 4D Technology Market Competitive Landscape
Global majors compete with regional champions across technology licensing and service network density. The vendor base organizes around three tiers: integrated hardware-software platforms, specialized component fabricators, and captive resin formulators. Strategic archetypes include entertainment-focused display integrators, healthcare-certified additive manufacturers, and industrial metrology specialists. Dominant competitive moves involve geographic expansion through service bureau acquisition and technology licensing agreements that bridge hardware and content pipeline integration.
Within the integrated platform tier, 3D Systems Corporation and Stratasys, Inc. represent contrasting approaches to healthcare and industrial market penetration. Dolby Laboratories, Inc. occupies a position exemplifying entertainment technology convergence. Samsung Electronics Co., Ltd. and LG Electronics Inc. anchor the display hardware segment. Autodesk, Inc. sits within the software and digital workflow archetype alongside FARO Technologies, Inc. in metrology systems.
| Leading Market Players |
|---|
| 3D Systems Corporation |
| Dolby Laboratories, Inc. |
| Samsung Electronics Co., Ltd. |
| LG Electronics Inc. |
| Barco N.V. |
| Stratasys, Inc. |
| Autodesk, Inc. |
| Sony Corporation |
| FARO Technologies, Inc. |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up service bureau networks across the United States and Mexico are consolidating regional additive manufacturing capacity, tightening pricing discipline through captive resin supply agreements and outcome-based performance contracting for healthcare and entertainment deployments.
Pricing Analysis
Warranty and service bundling separates premium hardware-software integrators from unbundled component vendors in this market. Three-tier pricing structure across premium, standard, and economy levels tracks FDA certification tier and resolution specification, with photopolymer systems commanding spreads based on biocompatibility validation. Cost compression in economy-tier display hardware is intensifying because of commoditized projector sourcing from Asian manufacturing clusters. Hospital systems exhibit highest price sensitivity due to capital budget constraints, while film studios prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Dual-sourcing requirements mandated by aerospace OEMs and academic medical centers are fragmenting photopolymer resin procurement across northeastern United States formulators and German specialty chemical suppliers. Hardware assembly draws from Taiwan and South Korea for precision optics, while metal powder feedstock sources from Canada and Pennsylvania. Single-source vulnerability concentrates in proprietary resin formulations protected by trade secret law. Distribution runs through direct sales forces for enterprise healthcare accounts and integrator channels for entertainment deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous liquid interface production is displacing conventional stereolithography in dental and audiology workflows, compressing production cycles and resetting equipment replacement timelines across North American orthodontic labs.
For Market Incumbents: Anticipate regulatory fragmentation between FDA patient-matched device categories and Health Canada parallel compliance as the primary threat to cross-border revenue streams. Prioritize backward integration into photopolymer formulation to defend margin position against resin cost volatility. Accelerate service bureau acquisition in Nuevo León and Baja California to anchor automotive OEM tooling demand before regional champions consolidate. For New Entrants and Emerging Players: The price-point gap between premium holography integrators and economy-tier projector vendors creates white-space for mid-market motion-capture software specialists. Target medical training simulation in Texas and Florida academic centers as the most penetrable segment given compressed FDA timelines for anatomical visualization tools. Pursue compliance-as-a-service partnerships with California and New York digital health privacy frameworks as the primary go-to-market angle. For Investors and Strategic Acquirers: FDA's updated guidance establishing patient-matched device categories is the leading indicator that regulatory clarity will accelerate consolidation among healthcare-certified additive manufacturers. Five-to-ten-year viability favors platforms with captive resin supply and multi-regional service networks over pure-play hardware vendors. Monitor Health Canada adoption velocity of FDA-cleared implant hardware as the inflection signal for cross-border equipment deployment economics.| Strategic Initiative | Industry Significance |
|---|---|
| Service Bureau Network Expansion | Localized production capacity in Mexico automotive corridors reduces logistics costs for tooling procurement. |
| Regulatory Certification Investment | FDA 510(k) pathway for novel photopolymers unlocks long-term implant applications and pricing power. |
| Software Platform Integration | Digital twin convergence with motion capture data opens aerospace maintenance training contracts. |
| Resin Formulation Backward Integration | Captive photopolymer supply insulates margins from northeastern United States supplier concentration. |
| Outcome-Based Performance Contracting | Guaranteed uptime terms align vendor incentives with theme park operator revenue continuity requirements. |
Research Methodology
Independent corroboration across hospital biomedical engineers, aerospace metrology specialists, and film studio technical directors underwrites the qualitative findings in this study. Primary interviews with GPO contracts managers, dental lab operators, and additive manufacturing service bureau owners combined with secondary validation from FDA 510(k) filings, Health Canada device licensing records, and SEC 10-K disclosures from listed hardware vendors. Bottom-up equipment shipment analysis and top-down entertainment capital expenditure tracking provided cross-referenced demand estimation.
Rate-of-change decomposition across technology adoption curves, regulatory approval timelines, and end-use capital cycles structured the analytical framework. Segmentation dimensions modeled include product type, application vertical, end-user institution scale, and underlying process physics. CAGRs were derived from installed base growth rates and replacement cycle compression across the projection horizon. Industry-specific inputs incorporated FCC spectrum allocation clarity for wireless holographic systems and OSHA additive manufacturing safety standard adoption velocity.
Inputs from hospital procurement databases and aerospace supplier qualification records were available through the study window; gaps in Mexico national standards body enforcement timelines introduce uncertainty bands for cross-border manufacturing corridor deployment forecasts. Deviation in FDA guidance implementation on patient-specific implants would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Technology
Molecular Modeling Market
3D Technology
3D Simulation Software Market
3D Technology
Mobile 3D Market
3D Technology
3D Reconstruction Technology Market
3D Technology
Generative Design Market
3D Technology
Global Mobile 3D Sensing Market
3D Technology
Visualization and 3D Rendering Software Market
3D Technology
Digital Holography Market
3D Technology
3D Mobile Mapping Market
3D Technology
Europe 3D 4D Technology Market
3D Technology
Europe 3D Telepresence Market
3D Technology
3D Geospatial Technologies Market
3D Technology
3D Point Cloud Processing Software Market
3D Technology
Global 3D Rendering Service Market
3D Technology
3D Rendering Market
3D Technology
Middle East and Africa 3D 4D Technology Market