
 3D Point Cloud Processing Software Market | 2026-2036
3D Point Cloud Processing Software Market Size, Share, and Industry Trends Forecast 2026-2036
3D Point Cloud Processing Software Market Insights
Subscription-based feature tiers is repositioning how vendors monetize 3D point cloud processing capabilities. Trimble leverages its hardware-software bundling to sustain recurring revenue streams across surveying workflows. Bentley Systems anchors its competitive stance through deep integration with infrastructure lifecycle platforms. Autodesk differentiates by extending cloud-native collaboration tools that reduce on-premises deployment friction.
3D point cloud processing software encompasses algorithms and computational frameworks that ingest, clean, classify, and mesh billions of spatial coordinates captured by LiDAR, photogrammetry, or structured light systems, typically operating on point densities exceeding 100 points per square meter and requiring GPU-accelerated triangulation for real-time visualization. The software serves primarily to transform raw spatial data into actionable geometric models for design validation, asset monitoring, and as-built documentation. Cloud-based deployments are capturing the fastest expansion as engineering firms seek elastic compute for burst processing of billion-point datasets. Machine Learning classification modules command premium pricing due to automated feature extraction capabilities that slash manual labeling time. On-premises installations retain dominance among defense and cultural heritage clients with stringent data sovereignty requirements.
FAA Part 107 rules for commercial drone operations shape aerial LiDAR capture volumes that feed directly into processing software demand. EPA stormwater management guidelines and EU Green Deal digital twin mandates are tightening accuracy requirements for environmental monitoring applications. ISO 19136 geographic markup standards and REACH chemical safety protocols for sensor materials collectively determine hardware-software compatibility thresholds. Stakeholders must monitor how evolving geospatial data privacy frameworks in multiple jurisdictions will reshape cross-border point cloud hosting architectures and licensing models.
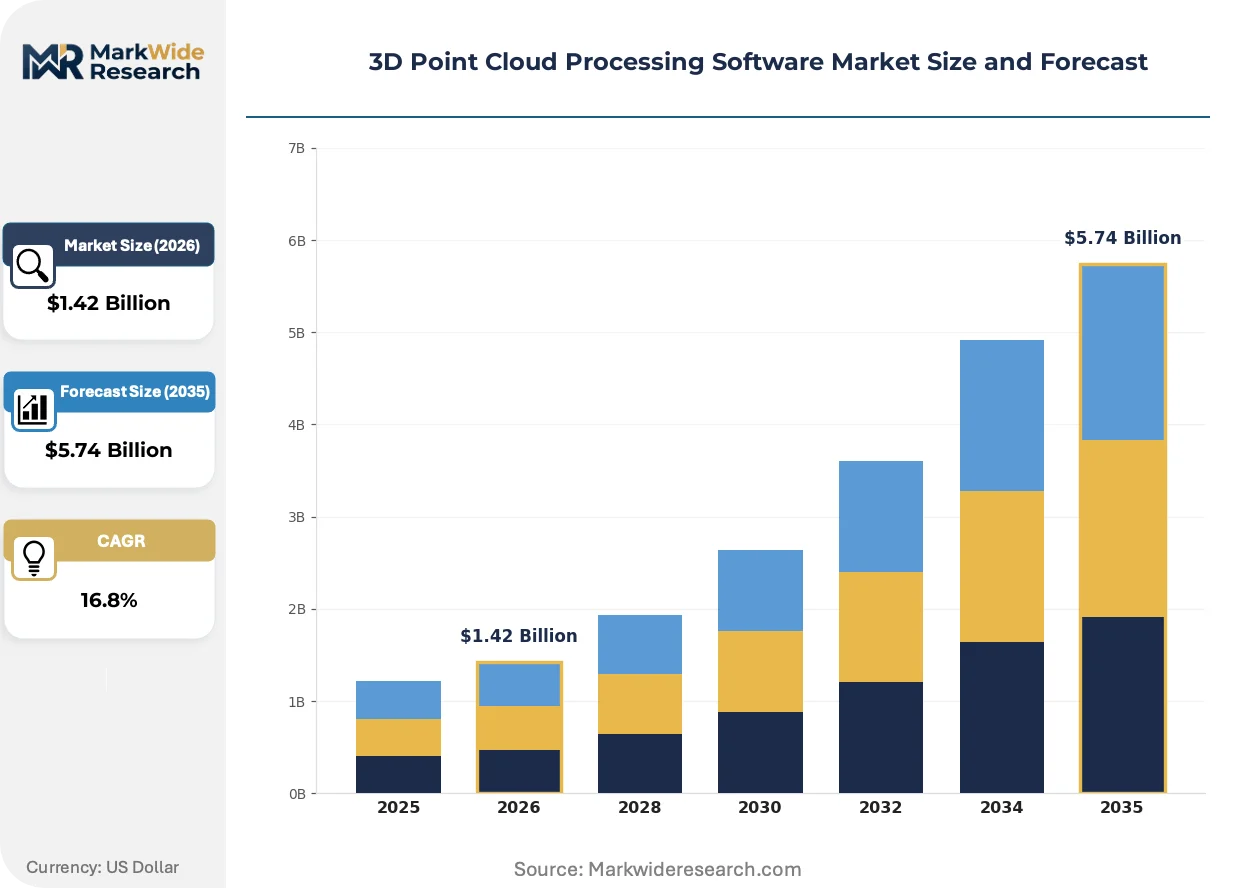
Market Dynamics
GPU-accelerated meshing algorithms are compressing processing timelines from hours to minutes, forcing vendors to rebundle compute costs into subscription tiers rather than perpetual licenses.
Growth Catalysts
- FAA Part 107 expansion:Commercial drone flight altitude waivers are multiplying aerial LiDAR capture volumes, directly expanding downstream software license demand among surveying contractors.
- EU Green Deal digital twin mandates:Infrastructure operators must maintain as-built geometric accuracy for environmental compliance, creating regulatory pull for classification automation.
- Photogrammetry-LiDAR fusion:Hybrid capture workflows are standardizing across heritage documentation projects, requiring software architectures that handle heterogeneous point sources.
Market Restraints
- GPU supply concentration:NVIDIA's dominance in CUDA-optimized data center cards creates input cost volatility for vendors building cloud processing stacks.
- Data sovereignty fragmentation:Cross-border point cloud hosting faces tightening geospatial privacy frameworks in Germany, France, and Switzerland, complicating multi-tenant architectures.
- Open-source substitution:CloudCompare and PDAL libraries are capturing price-sensitive cultural heritage and academic segments, pressuring entry-tier pricing.
Strategic Opportunities
- India's smart city infrastructure:Municipal digital twin programs in Mumbai and Bangalore are underpenetrated by Western software vendors, creating first-mover whitespace.
- REACH sensor compliance:ECHA chemical safety protocols for LiDAR hardware materials are accelerating hardware-software bundling opportunities for compliant integrated platforms.
- Edge-cloud convergence:Field pre-processing on ruggedized GPUs is integrating with cloud burst capacity, enabling new hybrid deployment models for mining and forestry operators.
Industry Challenges
- Geometric algorithm specialization:The talent pool for computational geometry and CUDA optimization remains shallow, extending R&D timelines for real-time triangulation features.
- ISO 19136 certification lag:Geographic markup standard compliance requires 12-18 month validation cycles, delaying product releases for geospatial data exchange modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Point Cloud Processing Software Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $5.74 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premises, Hybrid, Open-Source Technology: Machine Learning, Computer Vision, GIS, Visualization Tools End User: Engineering Firms, Construction Companies, Surveying Services, Geospatial Analysts Application: Urban Planning, Infrastructure Development, Environmental Monitoring, Cultural Heritage |
| Companies Covered | Trimble, Bentley Systems, Leica Geosystems AG, Autodesk, FARO, RIEGL, TerraSolid, Orbit GT, PointCab GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Point Cloud Processing Software Market Trends and Innovations
Neural network architectures are displacing rule-based classification pipelines, compressing feature extraction timelines while elevating compute intensity requirements across deployment models.
Transformer-based point cloud networks are integrating attention mechanisms that weight geometric saliency across billion-point urban scans. Municipal mapping departments in Stuttgart and Munich are piloting these modules for automated building footprint extraction. The technology is integrating semantic segmentation capabilities that previously required manual labeling teams, collapsing labor costs for as-built documentation workflows.
EPA stormwater management guidelines are tightening volumetric accuracy requirements for detention basin monitoring, mandating sub-centimeter point cloud registration. Engineering firms serving US municipal clients must now document uncertainty propagation through processing chains. Civil infrastructure verticals are responding by procuring software bundles that bundle registration validation with mesh generation, consolidating vendor relationships.
Subscription fatigue among mid-size surveying firms is fragmenting purchasing authority from IT departments to project managers with per-job software budgets. Channel partners are replacing direct enterprise sales for firms under fifty seats, unbundling implementation services from license fees. Germany's Mittelstand engineering sector exhibits this pattern most acutely, with Stuttgart-area clusters favoring monthly consumption models over annual commitments.
3D Point Cloud Processing Software Market Segmentation
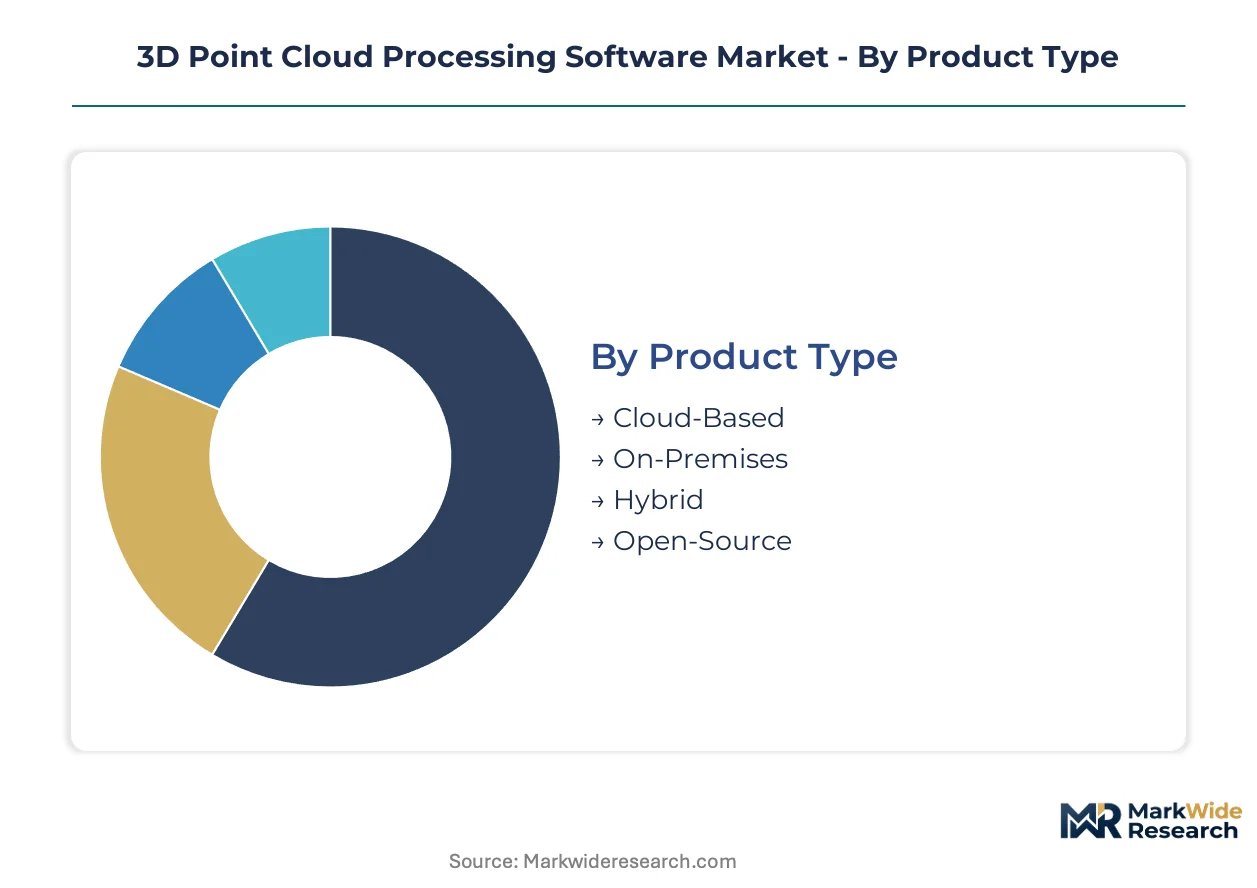
Segmentation in 3D point cloud processing software reveals how capital deployment, technical requirements, and regulatory exposure fragment purchasing behavior across deployment models and end-use verticals. Vendors configure pricing architectures and feature gating around these fault lines.
Product Type:
Capital intensity varies sharply across deployment models, with cloud infrastructure requiring sustained operational expenditure while on-premises installations demand substantial upfront hardware procurement.
- Cloud-Based:Multi-tenant SaaS architectures eliminate local GPU procurement, shifting compute costs to metered subscription tiers. Engineering firms in Stuttgart and Munich are consolidating here as EU Green Deal digital twin mandates drive burst processing needs for billion-point urban scans.
- On-Premises:Perpetual licenses paired with dedicated workstation clusters serve defense contractors and cultural heritage institutions with stringent data sovereignty requirements. German federal procurement guidelines favor this model for classified infrastructure documentation.
- Hybrid:Field pre-processing on ruggedized edge units synchronizes with cloud burst capacity for forestry and mining operators managing intermittent connectivity. This model spreads capital across both asset classes.
- Open-Source:Community-maintained libraries like PDAL and CloudCompare attract academic and price-sensitive heritage segments with zero licensing friction but elevated integration labor.
On-Premises retains the bulk of installed capacity among defense and heritage clients; Cloud-Based is expanding most quickly as municipal digital twin programs proliferate.
Technology:
Technical sophistication determines which segments command premium pricing and which face commoditization pressure from open-source alternatives.
- Machine Learning:Neural classification pipelines automate feature extraction from unstructured point data, collapsing manual labeling timelines. Automated building footprint extraction in Stuttgart municipal departments illustrates commercial traction.
- Computer Vision:Photogrammetry-LiDAR fusion algorithms register heterogeneous capture sources, standardizing across heritage documentation workflows requiring sub-millimeter geometric fidelity.
- GIS:ISO 19136 geographic markup compliance modules enable cross-platform data exchange, though certification cycles extend 12-18 months.
- Visualization Tools:Real-time GPU-accelerated triangulation for billion-point datasets differentiates enterprise tiers from entry-level offerings.
Machine Learning modules capture the steepest pricing premiums; Visualization Tools face the sharpest feature convergence across vendor portfolios.
End User:
Procurement authority fragmentation distinguishes enterprise buyers with centralized IT budgets from project-driven purchasing in mid-size operators.
- Engineering Firms:Subscription fatigue among Germany's Mittelstand sector is shifting purchasing authority from IT departments to project managers with per-job software budgets.
- Construction Companies:As-built documentation requirements for EPA stormwater compliance are bundling registration validation with mesh generation capabilities.
- Surveying Services:FAA Part 107 altitude waivers are multiplying aerial LiDAR capture volumes, directly expanding downstream license demand among US contractors.
- Geospatial Analysts:Municipal mapping departments in Bangalore and Mumbai represent underpenetrated whitespace for Western vendor expansion.
Engineering Firms concentrate the highest seat counts; Surveying Services are gaining share fastest as drone capture volumes accelerate.
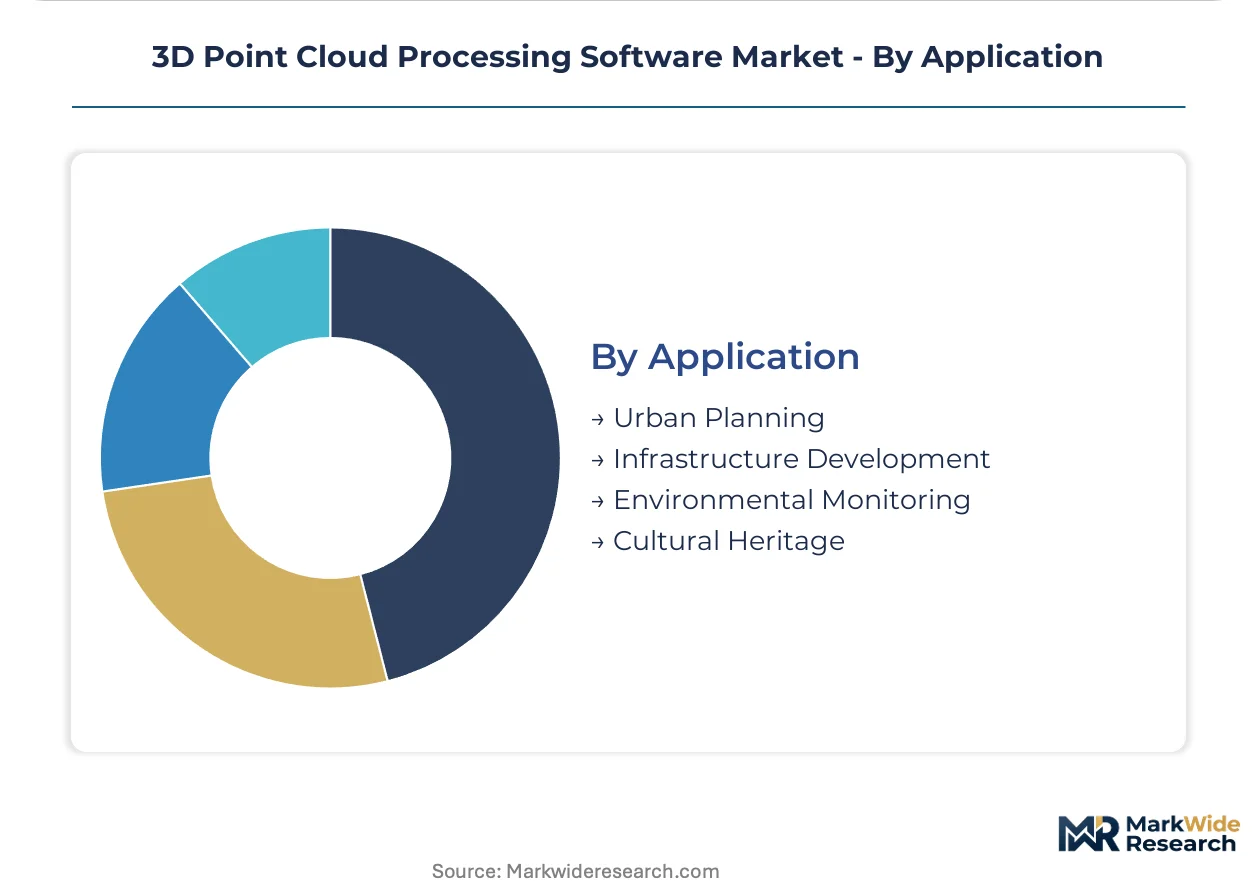
Application:
Regulatory stringency and data sensitivity create divergent vendor selection criteria across use cases.
- Urban Planning:Municipal digital twin programs in Munich and Stuttgart require automated classification for building footprint extraction at city scale.
- Infrastructure Development:Civil engineering verticals are consolidating vendor relationships around bundled registration validation and mesh generation for detention basin monitoring.
- Environmental Monitoring:EPA stormwater guidelines and EU Green Deal mandates tighten volumetric accuracy requirements, propagating uncertainty documentation through processing chains.
- Cultural Heritage:Data sovereignty concerns and open-source substitution pressure dominate this price-sensitive segment with limited cloud migration appetite.
Infrastructure Development absorbs the dominant share of enterprise license value; Environmental Monitoring is climbing the fastest as compliance deadlines tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of 3D point cloud processing software concentrates in the United States and Germany, while consumption spreads across surveying-intensive economies with infrastructure digitization mandates.
Germany
Engineering clusters in Munich and Stuttgart are driving enterprise license expansion as Mittelstand firms adopt cloud-based processing for EU Green Deal compliance. ECHA REACH protocols for LiDAR sensor materials accelerate hardware-software bundling opportunities. Stuttgart-area surveying contractors favor monthly consumption models over annual commitments.
United States
FAA Part 107 altitude waivers are multiplying aerial LiDAR capture volumes among surveying contractors serving municipal stormwater compliance. EPA guidelines tighten volumetric accuracy requirements for detention basin monitoring. Engineering firms in California and Texas are consolidating vendor relationships around bundled registration validation tools.
India
Municipal digital twin programs in Mumbai and Bangalore represent underpenetrated whitespace for Western software vendors. The country's smart city infrastructure investments are expanding procurement authority to municipal mapping departments. Karnataka's engineering services sector is piloting hybrid cloud-edge deployments for intermittent connectivity environments.
France
CNIL geospatial data privacy frameworks are reshaping cross-border point cloud hosting architectures for defense and heritage clients. EU Green Deal digital twin mandates are tightening accuracy requirements for environmental monitoring applications. Lyon-based surveying cooperatives are negotiating data sovereignty clauses in SaaS contracts.
Japan
METI infrastructure lifecycle management standards are propagating through civil engineering software procurement guidelines. JIS geographic data exchange requirements extend ISO 19136 certification timelines for imported platforms. Osaka-area construction consortia are demanding real-time GPU-accelerated triangulation for billion-point urban scans.
3D Point Cloud Processing Software Market Competitive Landscape
Top-tier vendors anchor the premium enterprise tier, while mid-market specialists and open-source communities occupy lower price bands. The vendor base organizes around three strategic archetypes: hardware-software bundlers leveraging sensor integration, platform integrators embedding point cloud tools within infrastructure lifecycles, and cloud-native specialists monetizing elastic compute. M&A activity targets ML classification capabilities, while strategic partnerships address data sovereignty fragmentation across European markets.
Among hardware-origin bundlers, Trimble and Leica Geosystems AG exemplify the integrated sensor-to-software model. Within the platform integration tier, Bentley Systems and Autodesk occupy positions anchored to infrastructure design ecosystems. TerraSolid represents the specialized classification automation segment. Each archetype faces pressure from open-source substitution in price-sensitive academic and heritage segments.
| Leading Market Players |
|---|
| Trimble |
| Bentley Systems |
| Leica Geosystems AG |
| Autodesk |
| FARO |
| RIEGL |
| TerraSolid |
| Orbit GT |
| PointCab GmbH |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between ISO 19136-validated enterprise tiers and open-source alternatives manifests in both subscription bundling and compute infrastructure sourcing. Vendors serving Munich engineering clusters meter GPU burst capacity through SaaS tiers, while heritage institutions in France negotiate perpetual licenses with dedicated workstation clusters to satisfy CNIL data sovereignty requirements.
Pricing Analysis
Margin tightening in cloud-native tiers reflects NVIDIA CUDA card supply volatility and the need to absorb compute costs into subscription models. Three-tier pricing structure across premium, standard, and economy levels differentiates by ML classification depth and registration validation bundled with mesh generation. Price differentiation hinges on automated feature extraction capabilities versus manual labeling workflows. Academic and cultural heritage segments exhibit highest price sensitivity, while defense contractors accept premium positioning for air-gapped deployments.
Supply Chain Analysis
Dual-sourcing requirements for GPU acceleration hardware mandate qualification of both NVIDIA data center cards and AMD ROCm-compatible alternatives among enterprise SaaS vendors. Software production concentrates in the United States, Germany, and Japan, with cloud infrastructure provisioning distributed across regional hyperscaler zones. Raw material dependencies span semiconductor lithography equipment, rare earth elements for sensor magnetics, and high-bandwidth memory modules. Single-source vulnerability in CUDA optimization toolchains threatens processing stack stability. Distribution runs through direct enterprise sales for large engineering firms and channel partners serving Germany's Mittelstand sector.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around ML classification capabilities as open-source substitution pressures entry-tier margins and forces weaker vendors toward acquisition or exit.
For Market Incumbents: Hedge against CloudCompare and PDAL encroachment by deepening CUDA optimization moats and acquiring specialist classification automation firms. Lock in Stuttgart-area engineering clusters through hardware-software bundling compliant with ECHA REACH protocols. Channel control investments should target project-manager purchasing authority fragmentation in mid-size surveying firms. For New Entrants and Emerging Players: Enter via municipal digital twin whitespace in Mumbai and Bangalore, where Western vendor penetration remains limited and procurement authority is shifting to mapping departments. Karnataka's hybrid cloud-edge pilot programs offer the most penetrable deployment model. Lead with consumption-based pricing that mirrors monthly project budgeting norms. For Investors and Strategic Acquirers: Re-rating potential sits with ML-native point cloud specialists given EU Green Deal digital twin mandate acceleration across German infrastructure operators. Long-term viability favors vendors with ISO 19136 certification completion and established hyperscaler cloud partnerships. Watch for FAA Part 107 altitude waiver expansion volumes as aerial LiDAR capture inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | ML classification capabilities compress feature extraction timelines for Stuttgart municipal clients. |
| Platform Integration | Deep embedding within Bentley infrastructure lifecycle ecosystems anchors enterprise retention. |
| Geographic Expansion | First-mover positioning in Mumbai smart city programs captures underpenetrated whitespace. |
| Strategic Partnership | Hyperscaler alliances resolve GPU supply concentration for cloud burst capacity provisioning. |
| Product Launch | Transformer-based attention mechanisms automate building footprint extraction at billion-point scale. |
Research Methodology
Multi-period observation of FAA waiver issuance volumes, EU Green Deal procurement timelines, and GPU supply allocation patterns anchored the trend analysis, supplemented by interviews with surveying contractors, municipal mapping directors, platform engineering leads, and hyperscaler solution architects. Secondary validation drew from EPA stormwater compliance filings, ECHA REACH substance databases, ISO certification registries, and hyperscaler capex disclosures. Bottom-up license deployment tracking triangulated against top-down infrastructure investment flow estimates.
Segment-weighting across deployment models, end-user verticals, technology tiers, and regional adoption clusters shaped the analytical framework. CAGRs were derived from elasticity modeling of license volume responses to capture hardware shipment data and regulatory deadline schedules. Forecast inputs incorporated EU Green Deal digital twin mandate phase-in timelines and FAA Part 107 waiver approval velocity across the projection horizon.
Revisions become necessary when ECHA REACH protocol amendments disrupt hardware-software bundling economics, or when CNIL geospatial privacy frameworks extend data localization requirements beyond current SaaS architectures. Deviation in NVIDIA data center card allocation policies would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Technology
Mobile 3D Market
3D Technology
Spatial Computing Market
3D Technology
Middle East and Africa 3D 4D Technology Market
3D Technology
3D Reconstruction Technology Market
3D Technology
3D Printing CAD Software Market
3D Technology
APAC 3D Telepresence Market
3D Technology
3D Reconstruction Market
3D Technology
3D Rendering Software Market
3D Technology
Visualization and 3D Rendering Software Market
3D Technology
3D Rendering Market
3D Technology
Global 3D Architecture Software Market
3D Technology
3D Machine Vision Market
3D Technology
3D CAD Market
3D Technology
North America 3D 4D Technology Market
3D Technology
3D Photogrammetry Software Market
3D Technology
Glasses Free 3D Tvs Market