
 Global Surface Computing Market | 2026-2036
Global Surface Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Surface Computing Market Foresight
REACH compliance in Europe is realigning material sourcing for touchscreen panels, forcing suppliers to certify alternative substrates or exit the value chain. Microsoft Corporation leverages its Azure cloud integration to dominate enterprise collaboration deployments across North American corporate offices. Samsung Electronics Co. Ltd anchors its position through captive OLED supply chains that reduce panel cost volatility for interactive whiteboards. Apple Inc. differentiates via proprietary acoustic wave architectures that limit third-party repair access and sustain premium pricing in museum and hospitality segments.
Surface computing encompasses multi-touch interfaces, gesture recognition systems, and interactive display surfaces that process direct physical manipulation through embedded infrared grids, capacitive layers, or frustrated total internal reflection waveguides. These systems translate tactile or motion inputs into digital commands for real-time visual feedback, serving applications from immersive simulation to collaborative design review. Multi-touch tables command the largest revenue share in surface computing due to entrenched deployment in defense training centers and architectural firms, while gesture recognition devices represent the fastest-expanding category as contactless interfaces gain traction in healthcare and public transit kiosks. Infrared technology retains manufacturing scale advantages for large-format panels, though capacitive methods are displacing legacy acoustic wave approaches in premium consumer electronics.
FCC electromagnetic emissions standards in the United States constrain transmitter design for wireless-enabled surface devices, while the EU Green Deal mandates recyclability quotas for display assemblies sold in member states. China's GB standards for touch panel safety, enforced by SAMR, create parallel certification requirements for vendors seeking access to state-backed smart city procurement. Stakeholders must monitor divergence between European CSRD reporting obligations and emerging U.S. SEC climate disclosure rules, as conflicting compliance architectures will fragment supply chain governance and reshape vendor qualification timelines.
Market Dynamics
Enterprise procurement of multi-touch tables and interactive whiteboards is accelerating as corporate offices rebuild collaboration infrastructure around hybrid work models, pulling capital from traditional conferencing hardware toward surface computing platforms.
Growth Catalysts
- EU AI Act compliance mandates:Biometric-enabled gesture recognition systems face tightened algorithmic transparency requirements, elevating vendor qualification barriers and locking in certified incumbents with dedicated compliance teams.
- Defense simulation contracts:United States federal agencies are expanding procurement of large-format touch surfaces for mission rehearsal and tactical training, anchoring domestic manufacturing capacity.
- OLED substrate diversification:Alternative organic semiconductor formulations are reducing panel cost volatility for interactive whiteboard producers, stabilizing margins across the value chain.
Market Restraints
- Indium tin oxide supply concentration:Touchscreen electrode material sourcing clusters in Chinese processing facilities, exposing vendors to export control volatility and forced technology transfer requirements.
- Acoustic wave technical obsolescence:Legacy surface computing architectures face displacement by capacitive multi-touch layers, stranding specialized manufacturing equipment and repair networks.
- FCC electromagnetic emissions testing:Wireless-enabled surface devices require iterative transmitter redesign cycles, extending product launch timelines by eight to fourteen months.
Strategic Opportunities
- India smart city procurement:State-backed urban digitization programs under the Ministry of Housing and Urban Affairs are creating first-mover advantages for vendors establishing local assembly operations.
- Healthcare contactless interfaces:Gesture recognition deployments in surgical suites and pharmaceutical cleanrooms are opening premium pricing tiers for contamination-resistant input systems.
- EU Green Deal recyclability quotas:Display assembly take-back mandates are rewarding vendors with modular designs and rare-earth recovery capabilities, creating differentiation against disposable competitors.
Industry Challenges
- Embedded systems firmware talent scarcity:Vendors compete for engineers capable of optimizing infrared grid signal processing algorithms, compressing development cycles for next-generation touch latency specifications.
- REACH certification timeline compression:European chemical safety dossier preparation for alternative substrate materials is forcing parallel regulatory track management across multiple product lines.
- Legacy AV infrastructure integration:Surface computing deployments in retrofit corporate environments require custom middleware development to bridge proprietary protocols with existing room control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Surface Computing Market |
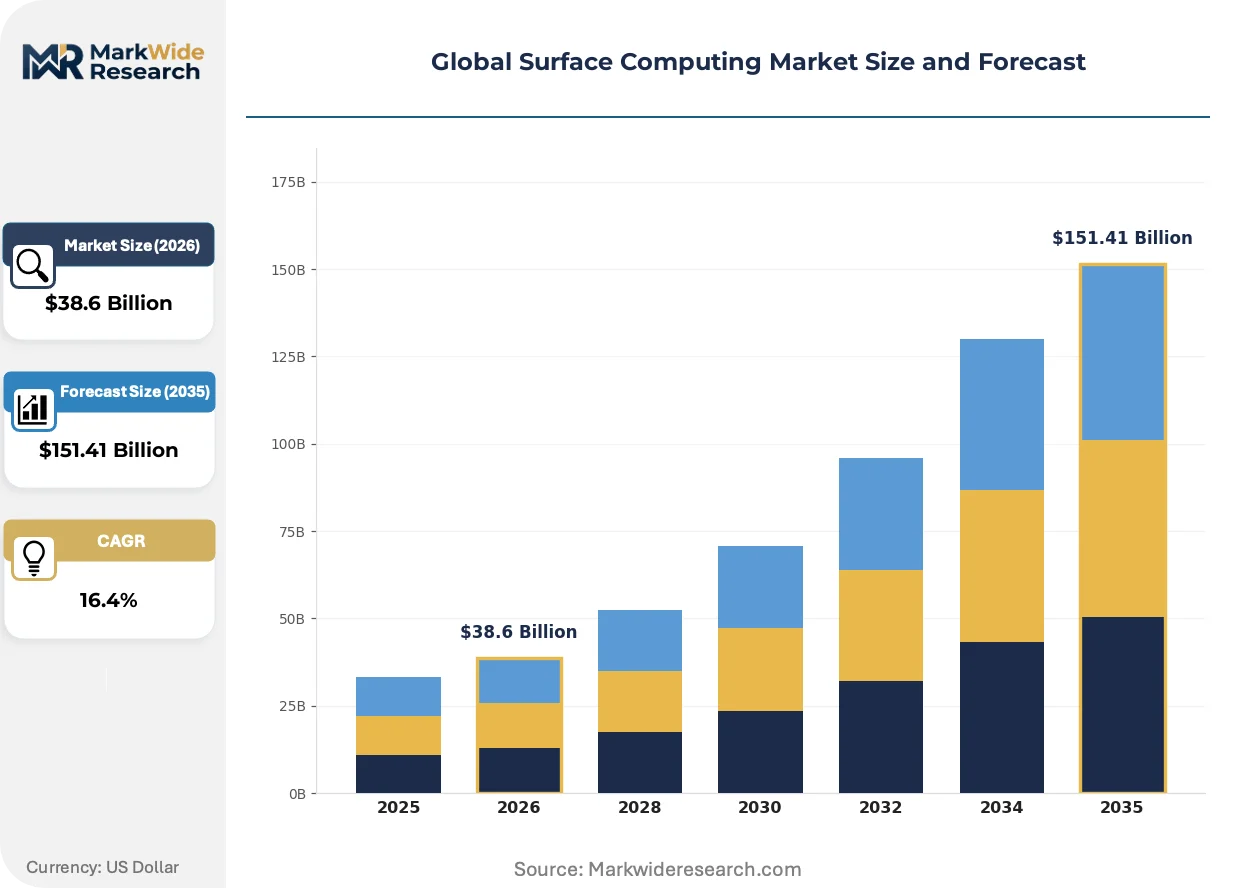
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $151.41 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multi-Touch Tables, Interactive Whiteboards, Gesture Recognition Devices, Touchscreen Panels Technology: Infrared, Optical Imaging, Capacitive, Frustrated Total Internal Reflection, Acoustic Wave Application: Education, Entertainment, Collaboration, Digital Signage, Simulation End User: Corporate Offices, Museums, Hospitality Venues, Government Agencies, Research Facilities |
| Companies Covered | Microsoft Corporation, 3M Co., Apple Inc., Samsung Electronics Co. Ltd, Dell Inc., LG Electronics Inc., Planar Systems Inc., Lenovo Group Ltd., HP Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Surface Computing Market Shifts & Advancements
Surface computing architectures are converging with cloud-native collaboration platforms, compressing the boundary between physical input layers and distributed software services. This integration is reshaping vendor competitive positioning around data sovereignty and latency performance.
Frustrated total internal reflection waveguides are rewriting large-format touch surface economics by eliminating the precision alignment requirements of infrared grid assemblies. Museum and hospitality buyers are adopting these architectures for curved and irregular display geometries previously unreachable by conventional multi-touch tables. The technology is compressing installation timelines from weeks to days while enabling transparent substrate choices that acoustic wave systems cannot match.
CSRD reporting obligations in Europe are forcing surface computing vendors to document scope 3 emissions across touchscreen panel supply chains. Component suppliers without verified carbon accounting are losing qualification status for enterprise procurement frameworks. Manufacturers with captive OLED production or certified recycled substrate programs are capturing preferential supplier status in French and German public sector tenders.
Subscription-based hardware provisioning is displacing capital purchase models in North American corporate offices. Facility managers are unbundling device acquisition from software licensing, shifting toward per-seat monthly arrangements that include predictive maintenance and upgrade cycles. This reconfiguration concentrates buyer power among integrated workplace experience platforms, marginalizing standalone hardware vendors without service orchestration capabilities.
Global Surface Computing Market Segmentation
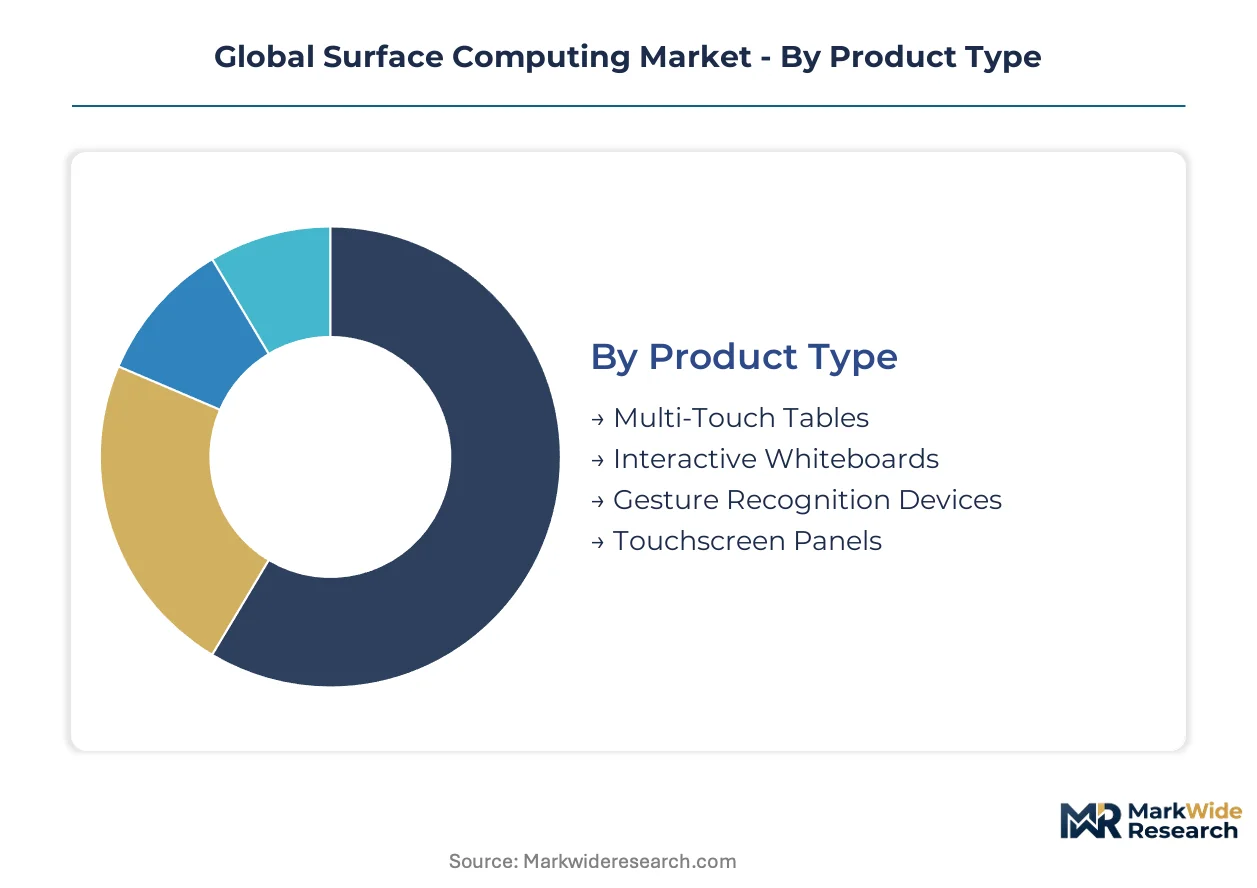
Surface computing procurement patterns diverge sharply across product architectures, with certification requirements and integration complexity fragmenting vendor qualification pathways. Segmentation reveals how technical specifications map to distinct compliance burdens and margin structures across the value chain.
Product Type:
Multi-touch tables require FCC electromagnetic emissions certification for wireless-enabled variants, while interactive whiteboards face EU Green Deal recyclability quotas for display assemblies sold in member states.
- Multi-Touch Tables:Large-format horizontal surfaces deploy infrared grids or frustrated total internal reflection waveguides for collaborative workspaces. Defense training centers in the United States anchor procurement volumes through federal simulation contracts.
- Interactive Whiteboards:Vertical display surfaces integrate capacitive or acoustic wave layers for presentation and annotation. Corporate offices across North America are accelerating replacement of legacy conferencing hardware with these platforms.
- Gesture Recognition Devices:Contactless input systems process motion through optical imaging or depth sensors. EU AI Act compliance mandates tighten algorithmic transparency requirements for biometric-enabled variants.
- Touchscreen Panels:Modular display components supply OEM integration across multiple end-use categories. REACH compliance in Europe forces substrate material recertification for indium tin oxide alternatives.
Multi-touch tables sit at the top of the volume ranking, with gesture recognition devices climbing the fastest.
Technology:
Cost tier stratification separates mature infrared manufacturing from premium capacitive layers, with acoustic wave systems facing technical obsolescence pressures.
- Infrared:Emitter-receiver grid arrays enable large-format touch detection without substrate conductivity requirements. Manufacturing scale advantages persist for defense and museum applications demanding curved geometries.
- Optical Imaging:Camera-based touch detection captures input through corner-mounted sensors. Hospitality venues favor these architectures for transparent overlay installations on irregular surfaces.
- Capacitive:Conductive layer stacks deliver multi-touch precision for consumer-adjacent applications. Samsung's captive OLED supply chains reduce panel cost volatility for interactive whiteboard producers.
- Frustrated Total Internal Reflection:Waveguide architectures eliminate precision alignment requirements of infrared assemblies. Museum and hospitality buyers adopt these for installation timeline compression from weeks to days.
- Acoustic Wave:Piezoelectric transducer systems detect touch through substrate vibration. Legacy equipment and repair networks face displacement as capacitive methods gain share.
Infrared retains manufacturing scale leadership, though frustrated total internal reflection architectures are gaining share fastest in premium segments.
Application:
Application segmentation tracks how surface computing migrates from specialized simulation environments toward mainstream collaboration infrastructure.
- Education:Interactive whiteboards and multi-touch tables replace traditional chalkboards and projection systems. K-12 procurement in the United States concentrates in districts with federal technology modernization grants.
- Entertainment:Immersive touch surfaces deploy in theme parks and experiential retail. Gesture recognition systems enable contactless interaction for hygiene-sensitive public installations.
- Collaboration:Enterprise meeting rooms integrate surface computing with cloud-native platforms. Microsoft's Azure cloud integration dominates corporate office deployments across North America.
- Digital Signage:Wayfinding and advertising surfaces deploy in transportation hubs and retail environments. India's smart city procurement under the Ministry of Housing and Urban Affairs creates first-mover advantages for local assembly operations.
- Simulation:Mission rehearsal and tactical training applications anchor defense agency procurement. United States federal contracts pull investment toward domestic manufacturing clusters.
Collaboration applications command the largest revenue share, with digital signage expanding most quickly in emerging market urban digitization programs.
End User:
Customer type segmentation reveals divergent procurement cycles, with government agencies running multi-year certification processes against corporate offices' shorter replacement timelines.
- Corporate Offices:Hybrid work models drive capital reallocation from traditional conferencing hardware toward surface computing platforms. Subscription-based hardware provisioning is displacing capital purchase models in North America.
- Museums:Curved and irregular display geometries favor frustrated total internal reflection architectures. Apple's proprietary acoustic wave systems sustain premium pricing through limited third-party repair access.
- Hospitality Venues:Check-in kiosks and interactive wayfinding systems deploy gesture recognition for contactless operation. CSRD reporting obligations in Europe force carbon accounting documentation across supply chains.
- Government Agencies:Defense simulation contracts anchor large-format touch surface procurement. FCC electromagnetic emissions standards constrain transmitter design for wireless-enabled deployments.
- Research Facilities:Scientific visualization and collaborative design review drive multi-touch table adoption. Cleanroom-compatible gesture recognition systems command premium pricing in pharmaceutical applications.
Corporate offices generate the highest procurement volumes, with hospitality venues climbing fastest as post-pandemic contactless interface demand persists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Embedded systems firmware engineers cluster in Shenzhen, Bangalore, and Austin, anchoring development centers for touch latency optimization and infrared grid signal processing across the surface computing value chain.
United States
Federal smart building mandates and defense simulation contracts pull procurement toward domestic manufacturing clusters. FCC electromagnetic emissions standards constrain transmitter design for wireless-enabled surface devices. Austin and Boston anchor firmware development centers for next-generation touch latency specifications.
Germany
CSRD reporting obligations force carbon accounting documentation across touchscreen panel supply chains. REACH compliance realigns material sourcing for alternative substrates. Munich and Stuttgart concentrate interactive whiteboard integration for corporate collaboration suites.
China
GB standards for touch panel safety enforced by SAMR create parallel certification requirements for smart city procurement. Indium tin oxide processing facilities cluster in Jiangsu and Guangdong provinces. Shenzhen anchors captive OLED production and firmware engineering for gesture recognition systems.
India
State-backed urban digitization programs under the Ministry of Housing and Urban Affairs create first-mover advantages for local assembly operations. BIS certification requirements filter vendor qualification for digital signage deployments. Bangalore and Hyderabad concentrate embedded systems talent for infrared grid optimization.
Japan
METI industrial standards shape precision alignment requirements for frustrated total internal reflection waveguides. JIS certification protocols govern large-format touch surface exports. Nagoya and Osaka anchor manufacturing scale for museum and hospitality display geometries.
Global Surface Computing Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology layers, creating a tiered structure where captive supply chains and cloud integration capabilities separate premium positioning from commodity hardware. The vendor base spans three strategic archetypes: diversified electronics conglomerates with display panel fabrication, enterprise software platforms with hardware integration, and specialized touch sensor component suppliers. Competitive moves concentrate on strategic partnerships for cloud-native collaboration integration and capacity expansion for OLED substrate diversification.
Within the diversified conglomerate tier, Microsoft Corporation and Samsung Electronics Co. Ltd exemplify contrasting integration strategies. Microsoft leverages Azure cloud infrastructure to anchor enterprise collaboration deployments. Samsung relies on captive OLED supply chains to stabilize panel cost volatility. Apple Inc. occupies a premium-tier position through proprietary acoustic wave architectures. 3M Co. and LG Electronics Inc. represent mid-scale fabricators with component specialization. Dell Inc., Lenovo Group Ltd, and HP Inc. cluster around enterprise hardware distribution channels. Planar Systems Inc. sits within the specialized display integrator segment.
| Leading Market Players |
|---|
| Microsoft Corporation |
| 3M Co. |
| Apple Inc. |
| Samsung Electronics Co. Ltd |
| Dell Inc. |
| LG Electronics Inc. |
| Planar Systems Inc. |
| Lenovo Group Ltd |
| HP Inc. |
| Others |
Supply & Pricing Matrix
Defense procurement agencies in the United States anchor pricing power through multi-year simulation contracts that compress negotiation leverage for large-format touch surface vendors. Subscription-based hardware provisioning in North American corporate offices is displacing capital purchase models, unbundling device acquisition from software licensing and concentrating buyer power among integrated workplace experience platforms.
Pricing Analysis
Bundled service contracts versus unbundled hardware transactions split pricing models across customer tiers. Three-tier pricing structure across premium, standard, and economy levels separates Microsoft's Azure-integrated collaboration suites from standalone interactive whiteboard vendors. Cost compression in mid-tier capacitive panels intensifies because Samsung's captive OLED supply chains stabilize input costs for competitors. Government agencies exhibit lowest price sensitivity due to certification lock-in, while K-12 education districts face acute budget constraints.
Supply Chain Analysis
Single-source vulnerability sits with indium tin oxide processing facilities clustered in Jiangsu and Guangdong provinces. Touchscreen electrode material sourcing draws from Chinese refining capacity, South Korean OLED substrate fabrication, and Japanese precision alignment equipment. Tariff exposure on display components imported under Section 301 classifications threatens margin stability for North American integrators. Distribution runs through direct enterprise sales teams for defense and corporate contracts, with systems integrators handling hospitality and museum deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in surface computing hinges on substrate cost stabilization through captive OLED production and premium-tier migration toward frustrated total internal reflection architectures in museum and hospitality segments.
For Market Incumbents: Anchor compliance capabilities against EU AI Act biometric transparency mandates to lock out uncertified challengers in gesture recognition. Deepen backward integration into alternative organic semiconductor formulations to reduce panel cost volatility. Defend against acoustic wave technical obsolescence by accelerating capacitive layer R&D investment. For New Entrants and Emerging Players: The price-point gap between Microsoft's premium Azure-integrated suites and economy-tier infrared grid tables opens white-space targeting. India's smart city procurement under the Ministry of Housing and Urban Affairs offers the most penetrable geography for local assembly operations. Healthcare contactless interfaces in surgical suites provide a premium go-to-market angle with contamination-resistant positioning. For Investors and Strategic Acquirers: Cloud-native workplace experience platforms are the most active acquirer in this space, seeking hardware integration to complete subscription stacks. Long-term viability favors vendors with modular designs and rare-earth recovery capabilities aligned to EU Green Deal recyclability quotas. Watch for BIS certification timeline compression in India as an inflection signal for emerging market entry windows.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Integration | Microsoft's Azure infrastructure anchors enterprise collaboration deployments across North American corporate offices. |
| Captive OLED Supply Chain Expansion | Samsung's in-house substrate production reduces panel cost volatility for interactive whiteboard manufacturers. |
| EU AI Act Compliance Certification | Algorithmic transparency mandates for biometric gesture recognition elevate vendor qualification barriers. |
| Local Assembly Operations in India | Ministry of Housing and Urban Affairs smart city programs reward first-movers with BIS certification advantages. |
| Frustrated Total Internal Reflection Scale-Up | Museum and hospitality buyers adopt waveguide architectures for curved geometries unreachable by infrared grids. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions with embedded systems firmware engineers, enterprise IT procurement officers, defense simulation contract administrators, and museum technology directors fed into demand-side validation. Secondary sources included FCC electromagnetic emissions filings, EU ECHA REACH dossier databases, SEC 10-K hardware segment disclosures, and SAMR GB standards documentation. Bottom-up vendor revenue aggregation and top-down end-use market sizing provided cross-check triangulation.
Comparable historical reference periods anchored the projection horizon to established adoption curves in enterprise collaboration technology. Segmentation modeling tracked product architecture, input technology, application vertical, and end-user procurement cycle. CAGRs derived from logistic diffusion curves fitted to defense contract award patterns and corporate hardware refresh timelines. OLED substrate cost trajectories and CSRD reporting obligation phase-ins served as industry-specific forecast inputs.
Caveats apply where REACH certification timeline compression or FCC transmitter redesign cycles could materially shift the outlook. Forecasts reflect assumptions about hybrid work model persistence and defense budget allocation continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Enterprise Mobility Management (EMM) Market
Digital Solutions
Queue Management System (QMS) Market
Digital Solutions
Global Personalization Engines Market
Digital Solutions
Digital Onboarding Market
Digital Solutions
Global B2B Buyer Intent Data Tools Market
Digital Solutions
APAC Smart Office Market
Digital Solutions
Global DDI Market
Digital Solutions
Latin America IT Market
Digital Solutions
Construction Design App Market
Digital Solutions
Shipping Software Market
Digital Solutions
Government Open Data Management Platform Market
Digital Solutions
Canada Digital Twin Market
Digital Solutions
Service Lifecycle Management Application Market
Digital Solutions
Business Document Work Process Management Market
Digital Solutions
Global Freight Software Market
Digital Solutions
Global IC Card/Smart Card Market