
 Spatial Computing Market | 2026-2036
Spatial Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Spatial Computing Market Outlook
North American semiconductor foundries is pivoting toward dedicated spatial processing wafer capacity to feed headset and sensor pipelines. Microsoft leverages its Azure cloud backbone to anchor enterprise mixed-reality deployments. Qualcomm Technologies dominates mobile XR chipset architecture, while Meta Platforms competes through vertical control over both hardware and content ecosystems.
Spatial computing fuses computer vision, sensor fusion, and real-time 3D rendering to overlay digital information onto physical environments or construct fully immersive virtual spaces, typically operating at sub-20-millisecond motion-to-photon latency to prevent user disorientation. Its primary purpose spans industrial digital-twin visualization, remote expert guidance, and consumer immersive media. AR Headsets command the largest installed base among product types, though Holographic Displays capture disproportionate margin pools in defense and medical imaging. Cloud-Based deployment is expanding fastest as edge-to-core latency compression improves, while On-Premise solutions retain dominance in regulated manufacturing and automotive verticals.
The EU AI Act and GDPR impose strict algorithmic transparency and biometric data constraints on spatial computing platforms deployed across European healthcare and retail settings. In the United States, FDA scrutiny of AR-guided surgical tools and FCC spectrum allocation for millimeter-wave spatial tracking shape product roadmaps and market access timelines. Stakeholders must weigh regulatory compliance costs against the performance advantages of tighter hardware-software integration as the competitive architecture crystallizes.
Market Dynamics
Enterprise manufacturing clusters in Michigan and Texas are pulling spatial computing hardware into production environments faster than consumer adoption can match, creating a bifurcated demand profile that privileges industrial-grade reliability over entertainment features.
Growth Catalysts
- EU AI Act biometric compliance mandates:Healthcare providers across Germany, France, and Italy must upgrade diagnostic imaging systems to meet algorithmic transparency requirements, forcing replacement cycles for legacy AR surgical planning tools.
- Millimeter-wave spectrum allocation:The FCC's 2023 ruling on 60 GHz and 77-81 GHz bands unlocks sub-centimeter spatial tracking precision for warehouse robotics and automotive assembly lines in the United States.
- Digital-twin visualization demand:Automotive OEMs in Stuttgart, Wolfsburg, and Detroit are deploying mixed-reality environments for pre-production design validation, compressing prototype iteration timelines.
Market Restraints
- Compound semiconductor supply concentration:GaN and InP substrates for optical waveguides concentrate among three Japanese and Taiwanese foundry operators, exposing headset manufacturers to single-source risk.
- Motion-to-photon latency floor:Sub-20-millisecond rendering requirements demand custom ASIC architectures that lock vendors into 18-24 month silicon development cycles.
- GDPR biometric data friction:Retail analytics platforms using spatial eye-tracking face consent-architecture costs that inflate European deployment budgets by 30-40 percent versus North American equivalents.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:The production-linked incentive framework for wearable devices offers 4-6 percent cashback on incremental sales, attracting contract manufacturers to Chennai and Noida.
- Neural interface convergence:Integration of EMG wristbands with AR headsets is opening hands-free control paradigms for sterile surgical environments and hazardous industrial settings.
- Cloud-based deployment tailwinds:Edge-to-core latency compression below 10 milliseconds in South Korea and Japan is enabling streaming-rendered spatial experiences without local GPU capacity.
Industry Challenges
- Optical engineer talent scarcity:Waveguide design and pupil-expansion optics expertise concentrates among alumni of three German and Swiss research institutes, constraining hiring pipelines.
- FDA 510(k) timeline variability:AR-guided surgical navigation tools face 14-22 month review windows that misalign with hardware refresh cycles, forcing parallel product-line maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spatial Computing Market |
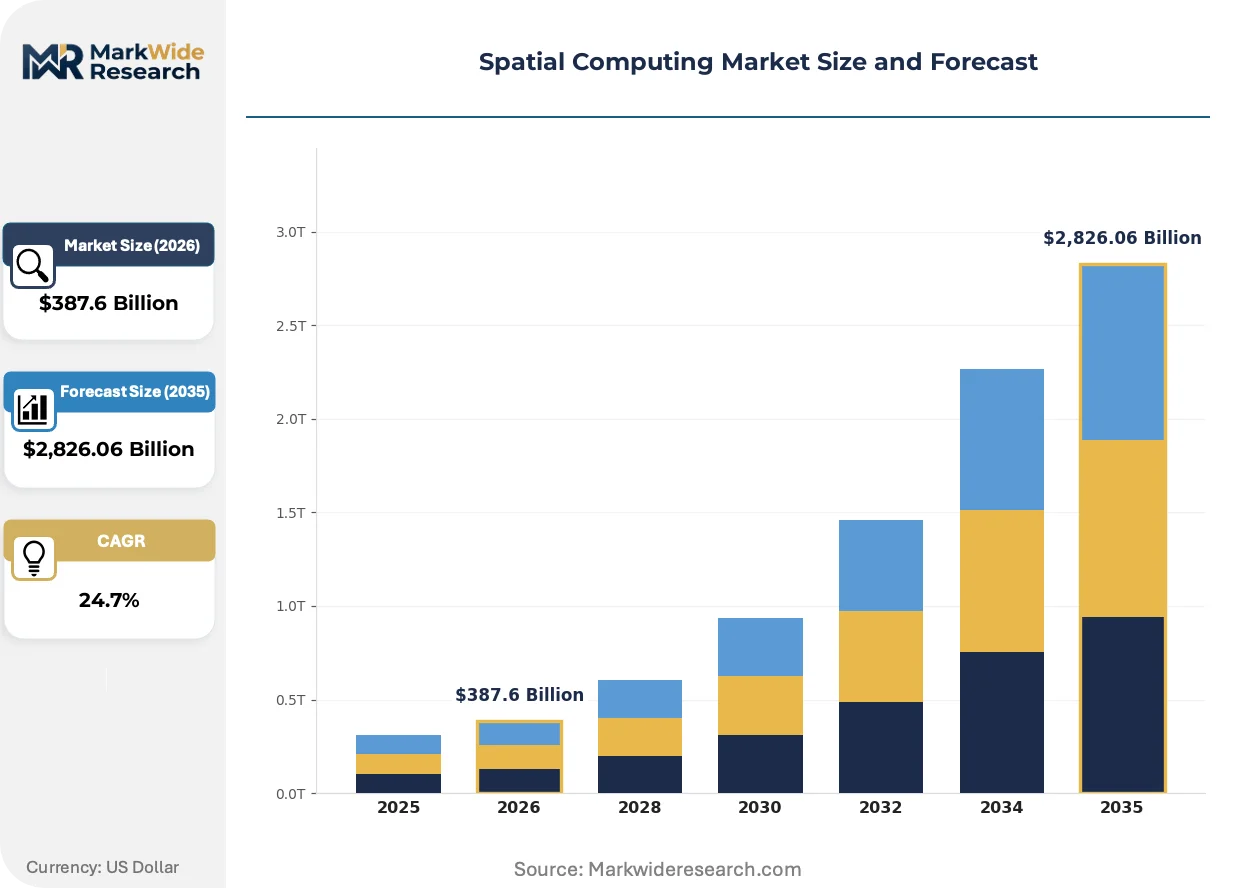
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $2,826.06 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AR Headsets, VR Glasses, Holographic Displays, Gesture Control Devices End User: Education, Healthcare, Retail, Entertainment Deployment: On-Premise, Cloud-Based, Hybrid Solutions, Mobile Apps Industry Vertical: Manufacturing, Real Estate, Tourism, Automotive |
| Companies Covered | Google, Magic Leap, Microsoft, IBM, Amazon, Apple, Qualcomm Technologies, Snap, Meta Platforms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spatial Computing Market Strategic Shifts
Spatial computing architectures are fragmenting into specialized silicon, cloud-rendered pipelines, and biometric-integrated interfaces that each demand distinct engineering competencies from vendors.
Silicon photonics is electrifying optical engine miniaturization for AR headsets. Waveguide-integrated laser sources are shrinking projector modules below 3 cubic centimeters. Automotive HUD manufacturers in Germany and Japan are adopting these architectures to embed spatial overlays directly into windshield glass, bypassing discrete eyewear entirely.
The EU AI Act's conformity assessment requirements for biometric inference systems are forcing algorithmic documentation standards across spatial analytics platforms. Vendors must now maintain technical files tracing training data provenance and decision-boundary logic. Medical imaging software in France and the Netherlands faces the steepest compliance burden, with notified body review periods extending commercialization timelines.
Enterprise procurement of spatial computing hardware is consolidating through IT-OT integration mandates. Manufacturing buyers in Texas and Michigan now require AR headsets to authenticate against existing identity management stacks and stream telemetry to pre-approved cloud tenants. This specification shift favors vendors with mature enterprise software partnerships over consumer-oriented hardware specialists.
Spatial Computing Market Segmentation
Spatial computing vendors must align R&D budgets against divergent hardware physics and software stacks. Each segment demands distinct capital commitments, from custom ASIC development for headsets to edge infrastructure for cloud-rendered experiences.
Product Type:
Capital intensity varies dramatically across form factors, with waveguide optics and micro-display engines driving the steepest upfront engineering costs.
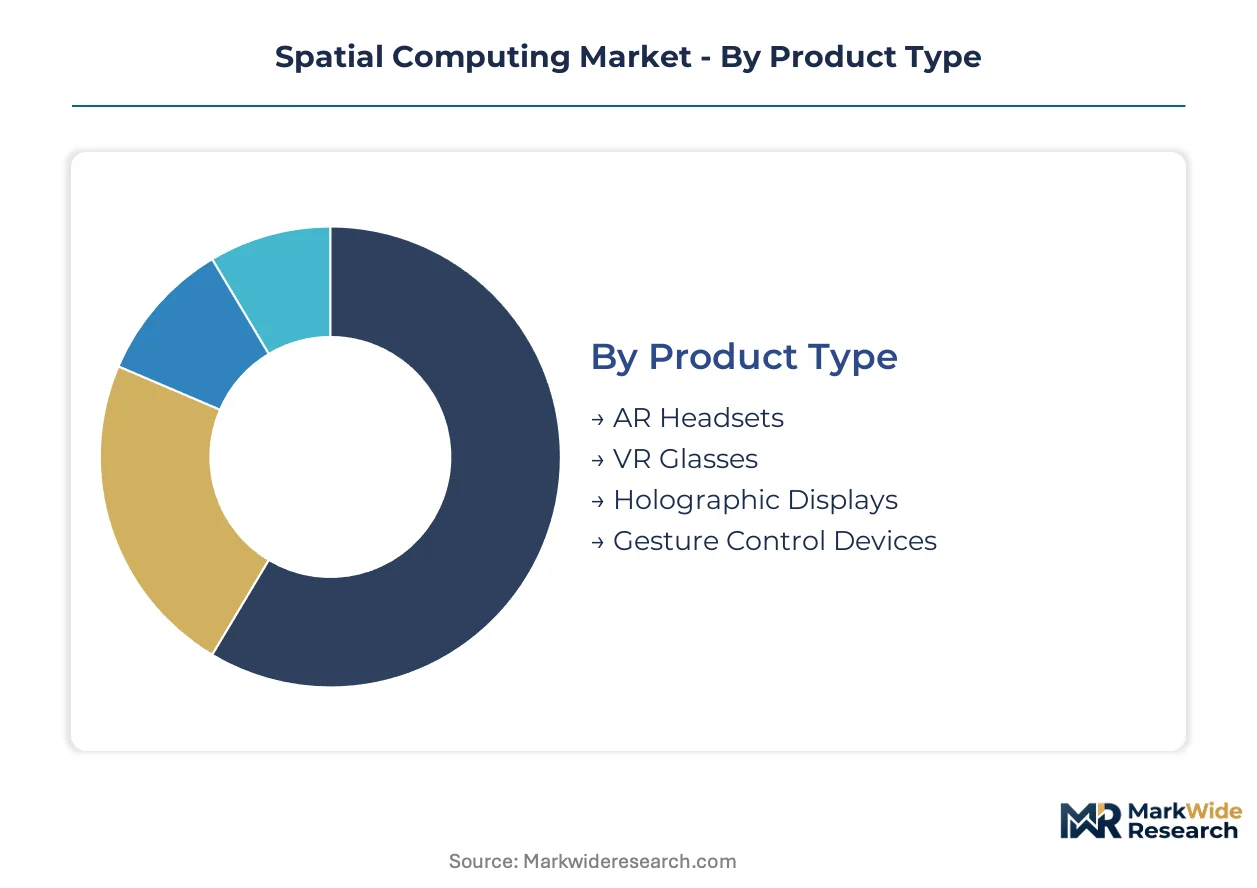
- AR Headsets:Optical see-through architectures combine diffractive waveguides with micro-OLED or LCoS projectors, demanding 18-24 month silicon development cycles. Demand concentrates among enterprise manufacturing clusters in Michigan and Texas, where IT-OT integration mandates favor vendors with mature identity management partnerships.
- Holographic Displays:Volumetric light-field systems require precision optical benches and high-speed rendering farms for medical imaging and defense applications. German automotive HUD manufacturers and Japanese medical device firms capture disproportionate margin pools through windshield-embedded and surgical visualization deployments.
- VR Glasses:Pancake lens stacks and micro-OLED panels reduce headset bulk for consumer immersive media.
- Gesture Control Devices:EMG wristbands and depth cameras enable hands-free manipulation in sterile surgical environments.
Most installed capacity flows through AR Headsets. Expansion is steepest in Holographic Displays.
End User:
Procurement sophistication separates segments, with regulated healthcare buyers imposing documentation burdens that consumer-facing verticals avoid.
- Healthcare:AR surgical planning and remote diagnostic systems must satisfy FDA 510(k) timelines of 14-22 months and EU AI Act algorithmic transparency mandates. German, French, and Italian providers face forced replacement cycles for legacy imaging tools under biometric compliance deadlines.
- Manufacturing:Texas and Michigan factory clusters pull industrial-grade hardware into production environments faster than consumer adoption, privileging reliability over entertainment features.
- Education:K-12 and university deployments prioritize cost scalability and content library breadth.
- Retail:Spatial eye-tracking analytics face GDPR consent-architecture costs that inflate European budgets 30-40 percent above North American equivalents.
Healthcare commands the highest average selling prices. Education shows the steepest volume expansion trajectory.
Deployment:
Latency requirements and data sovereignty rules fragment infrastructure choices across regulated and unregulated use cases.
- Cloud-Based:Edge-to-core compression below 10 milliseconds in South Korea and Japan enables streaming-rendered experiences without local GPU capacity. Enterprise buyers in Texas and Michigan now require telemetry streaming to pre-approved cloud tenants, favoring vendors with mature software partnerships.
- On-Premise:Automotive assembly lines and regulated manufacturing retain local rendering to satisfy data residency and sub-20-millisecond motion-to-photon requirements.
- Hybrid Solutions:Split architectures process sensitive biometric data locally while offloading non-critical rendering to remote infrastructure.
- Mobile Apps:Smartphone-based AR leverages existing device installed bases for lightweight consumer and field-service applications.
On-Premise retains dominance in regulated verticals. Cloud-Based deployment is climbing the fastest.
Industry Vertical:
Digital-twin maturity and design-validation workflows concentrate demand among automotive and manufacturing adopters.
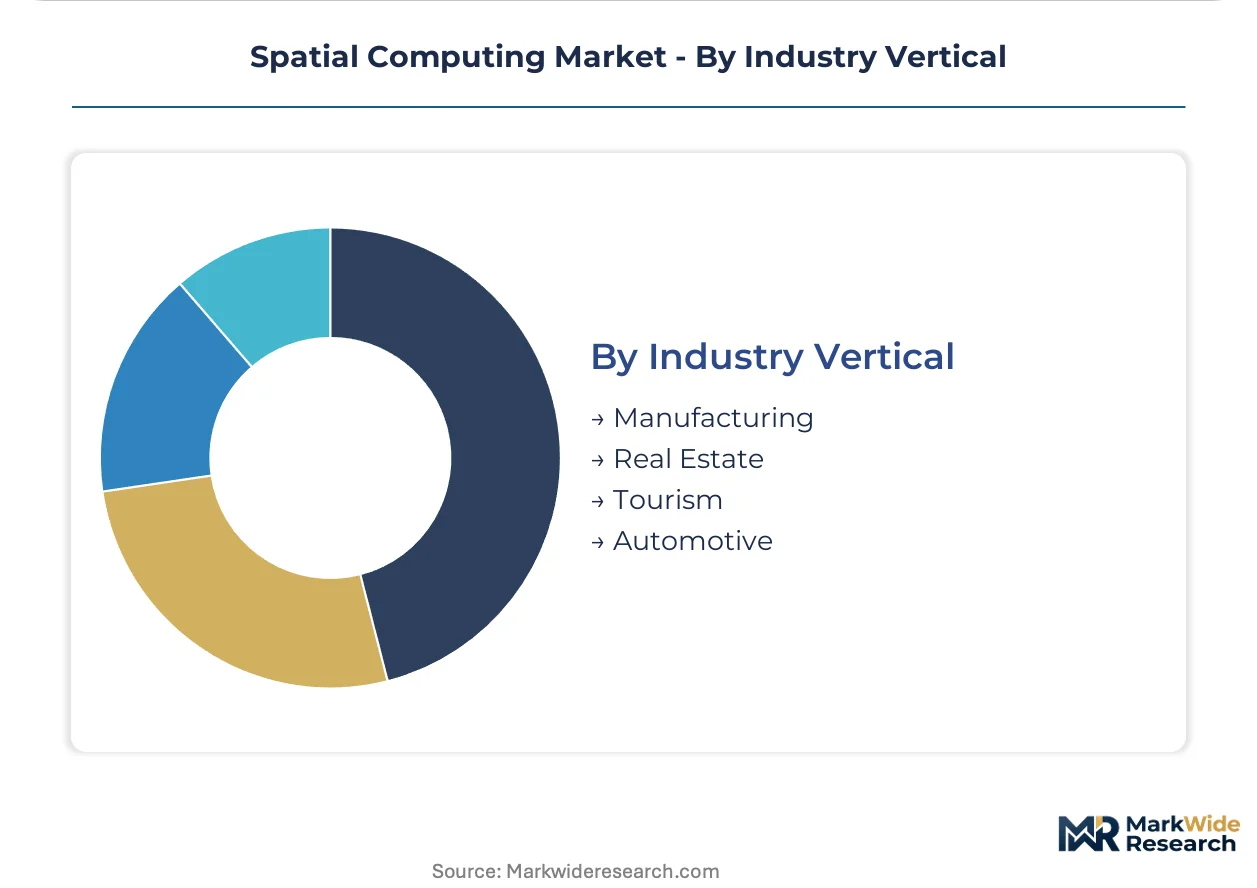
- Automotive:OEMs in Stuttgart, Wolfsburg, and Detroit deploy mixed-reality environments for pre-production design validation, compressing prototype iteration timelines. FCC millimeter-wave spectrum allocations for 60 GHz and 77-81 GHz bands unlock sub-centimeter spatial tracking precision for assembly line robotics.
- Manufacturing:Enterprise procurement through IT-OT integration mandates requires hardware authentication against existing identity stacks, consolidating vendor selection toward enterprise software specialists.
- Real Estate:Virtual property staging and architectural visualization drive cloud-rendered walkthrough adoption.
- Tourism:Immersive cultural heritage experiences and destination marketing fuel mobile AR deployment.
Manufacturing holds the deepest installed base. Automotive shows the most rapid adoption acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials between jurisdictions are redirecting spatial computing hardware assembly toward economies with streamlined conformity pathways. The EU AI Act's biometric compliance burden has compressed European deployment budgets, while Asian production incentives and North American spectrum allocations pull investment in opposing directions.
United States
Michigan and Texas manufacturing clusters drive enterprise headset procurement for factory-floor digital twins. FCC millimeter-wave allocations in 60 GHz and 77-81 GHz bands enable sub-centimeter spatial tracking precision for automotive assembly robotics. Detroit-area OEMs deploy mixed-reality environments for pre-production design validation.
Germany
Automotive HUD manufacturers and medical device firms anchor holographic display demand for windshield-embedded and surgical visualization systems. EU AI Act algorithmic transparency mandates force replacement cycles for legacy AR surgical planning tools across German hospital networks. Stuttgart and Wolfsburg OEMs compress prototype iteration timelines through mixed-reality design workflows.
China
MIIT standards for wearable device electromagnetic compatibility shape domestic product roadmaps. Shenzhen and Shanghai hardware ecosystems feed optical engine miniaturization for AR headsets. The country's national electronics regulator accelerates conformity assessment timelines versus European notified body procedures.
South Korea
Edge-to-core latency compression below 10 milliseconds enables cloud-rendered spatial experiences without local GPU capacity. METI-coordinated infrastructure investments support streaming-rendered enterprise deployments. Seoul Capital Area data centers anchor regional cloud-based spatial computing growth.
India
PLI scheme production-linked incentives for wearable devices offer 4-6 percent cashback on incremental sales. Chennai and Noida contract manufacturers attract spatial computing hardware assembly migration. The national electronics ministry's incentive framework reduces effective compliance costs versus EU AI Act jurisdictions.
Spatial Computing Market Competitive Environment
United States technology conglomerates anchor one tier of spatial computing supply; Taiwanese and Korean semiconductor specialists hold upstream component control. Market structure concentrates around vertically integrated platform operators and dedicated optical hardware developers. Three archetypes dominate: cloud-backed enterprise software integrators, custom silicon architects, and waveguide optics specialists. Competitive moves center on strategic partnerships for IT-OT integration and capacity expansion in GaN substrate fabrication.
Within the vertically integrated tier, Meta Platforms and Apple occupy positions spanning hardware and content ecosystem control. Microsoft exemplifies the cloud-backed enterprise archetype through Azure-anchored mixed-reality deployments. Qualcomm Technologies represents custom silicon dominance in mobile XR chipset architecture.
| Leading Market Players |
|---|
| Magic Leap |
| Microsoft |
| IBM |
| Amazon |
| Apple |
| Qualcomm Technologies |
| Snap |
| Meta Platforms |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between FDA-cleared surgical AR systems and uncertified enterprise training headsets manifests in both margin structures and supply chain sourcing strategies. Premium-tier hardware commands 3-4x component budgets through GaN waveguide substrates and custom ASIC architectures, while commodity-tier devices source off-the-shelf LCoS panels from Shenzhen distributors.
Pricing Analysis
Distributor margin layers absorb 18-25 percent of holographic display ASPs before hospital procurement, compressing vendor net pricing. Three-tier pricing structure across FDA-cleared surgical, enterprise IT-OT integrated, and consumer immersive tiers separates certification-grade from volume-scale from entertainment-optimized hardware. Cost compression in consumer VR glasses intensifies because Meta and Apple subsidize ecosystem capture through hardware loss-leadering. Manufacturing buyers in Michigan and Texas exhibit lowest price sensitivity due to downtime-avoidance value, while K-12 education procurement faces strict per-seat caps.
Supply Chain Analysis
Single-source vulnerability sits with GaN and InP substrate fabrication concentrated among three Japanese and Taiwanese foundry operators. Optical engine assembly draws from China, Taiwan, and South Korea, while precision waveguide lithography rests on German and Swiss equipment. Tariff exposure on compound semiconductor imports threatens headset margin stability. Distribution runs through direct OEM relationships for automotive HUD manufacturers, with enterprise IT channels handling manufacturing cluster deployments in Texas and Michigan.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spatial computing margin expansion hinges on cloud-rendered deployment compression eliminating local GPU costs, while FDA-cleared surgical tiers capture premium pricing through 510(k) barrier protection.
For Market Incumbents: Anticipate neural interface convergence disrupting pure-handset control paradigms by securing EMG wristband technology through acquisition or exclusive licensing. Defend against cloud-native entrants by hardening edge-to-core latency guarantees below 10 milliseconds in South Korea and Japan deployments. Prioritize backward integration into GaN substrate supply through offtake agreements with Taiwanese foundry operators. For New Entrants and Emerging Players: Begin with India's PLI scheme production-linked incentives for wearable device assembly in Chennai and Noida, where 4-6 percent cashback on incremental sales compresses effective manufacturing costs. White-space opportunity concentrates in holographic display medical imaging for French and Dutch hospital networks facing EU AI Act forced replacement cycles. Go-to-market leverage rests on notified body relationships accelerating CE marking timelines versus incumbent documentation burdens. For Investors and Strategic Acquirers: Consolidation pressure builds where optical engineering talent scarcity concentrates among alumni of three German and Swiss research institutes, constraining scaling capacity for waveguide design specialists. Long-term viability favors vertically integrated platform operators with captive cloud infrastructure and content ecosystems over pure hardware vendors. Watch FDA 510(k) backlog clearance rates as inflection signal for surgical AR commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Custom ASIC Development | Sub-20-millisecond motion-to-photon latency requirements lock vendors into 18-24 month silicon cycles. |
| IT-OT Integration Partnership | Enterprise manufacturing buyers in Michigan and Texas require hardware authentication against existing identity stacks. |
| GaN Substrate Offtake Agreement | Compound semiconductor supply concentration among Japanese and Taiwanese foundries demands captive sourcing security. |
| Neural Interface Acquisition | EMG wristband integration opens hands-free control for sterile surgical and hazardous industrial environments. |
| Notified Body Relationship Investment | EU AI Act algorithmic transparency mandates extend review periods for medical imaging software in France and Netherlands. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with AR hardware product managers, semiconductor foundry planning officers, hospital biomedical engineers, and enterprise IT procurement leads with secondary validation against SEC filings, FCC spectrum allocation rulings, EU AI Act implementing texts, and hyperscaler capex disclosures. Bottom-up installed base modeling and top-down TAM segmentation were cross-checked for consistency.
Segment-weighting approaches distributed value across product type, end user, deployment model, and industry vertical dimensions, with regional regulatory cluster effects layered throughout the projection horizon. CAGRs were derived from elasticity-adjusted adoption curves and replacement cycle timing. Forecast inputs included millimeter-wave spectrum allocation implementation pace and EU AI Act biometric compliance deadline enforcement.
Caveats apply where FDA 510(k) timeline variability or compound semiconductor supply disruption could materially shift the outlook. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Technology
APAC 3D Telepresence Market
3D Technology
3D CAD Market
3D Technology
3D Simulation Software Market
3D Technology
3D Rendering Software Market
3D Technology
Global 3D 4D Technology Market
3D Technology
3D Scanning Market
3D Technology
Smartphone 3D Camera Market
3D Technology
Global Mobile 3D Sensing Market
3D Technology
3D Machine Vision Market
3D Technology
3D Mobile Mapping Market
3D Technology
Molecular Modeling Market
3D Technology
North America 3D 4D Technology Market
3D Technology
LAMEA Smartphone 3D Camera Market
3D Technology
APAC 3D 4D Technology Market
3D Technology
Digital Holography Market
3D Technology
Global 3D Mapping and 3D Modeling Market