
 Hydration Supplement Market | 2026-2036
Hydration Supplement Market Size, Share, and Industry Trends Forecast 2026-2036
Hydration Supplement Market Insights
Sports nutritionist labor pools is reorganizing how hydration brands build clinical credibility and athlete trust. PepsiCo leverages its beverage distribution infrastructure to dominate ready-to-drink shelf placement. Abbott Laboratories anchors its position through medical-grade electrolyte science and healthcare channel access. Nestlé competes by extending its nutrition research legacy into performance hydration formulations.
Hydration supplements are formulated products containing electrolytes, carbohydrates, amino acids, or vitamins designed to restore fluid balance and support metabolic function during or after physical exertion, typically manufactured through spray-drying, freeze-drying, or liquid blending processes with osmolality targets between 200 and 400 mOsm/kg for optimal gastric emptying. Ready-to-drink formulations command the largest revenue share due to convenience-driven purchasing among time-constrained consumers, while powder segments attract cost-sensitive athletes seeking customizable dosing. Online retailers represent the fastest-growing distribution channel as direct-to-consumer subscription models reshape repeat purchase economics.
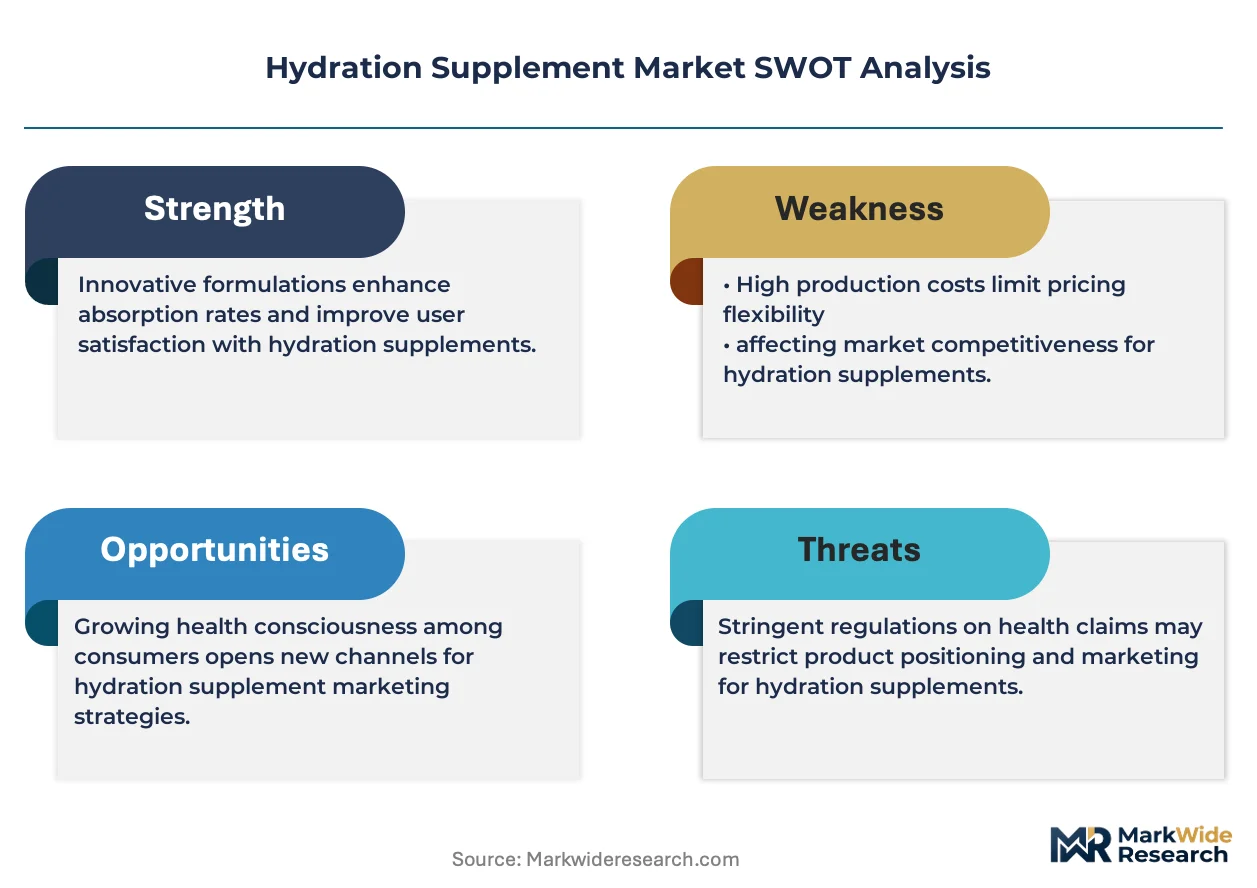
The U.S. FDA's Current Good Manufacturing Practice regulations and the FTC's substantiation requirements for health claims constrain new entrant speed to market while elevating compliance costs for smaller brands. The EU's novel food regulations and EFSA health claim assessments create parallel barriers for cross-border expansion into European markets. Stakeholders must monitor evolving sports drug testing protocols and clean-label certification standards as differentiation levers that will separate premium-positioned brands from commodity competitors.
Market Dynamics
The U.S. FDA's evolving dietary supplement labeling requirements are compressing formulation cycles and forcing brands to rebuild compliance infrastructure ahead of enforcement windows.
Growth Catalysts
- Endurance athletics penetration:Marathon and triathlon participation in the United States, Germany, and Japan is pulling medical-grade electrolyte formulations into amateur consumer segments previously served by basic sports drinks.
- Clean-label certification protocols:NSF Certified for Sport and Informed Sport testing standards are creating procurement filters that disqualify unverified competitors from collegiate and professional team supply chains.
- Spray-drying technology maturation:Advances in low-temperature dehydration are preserving bioactive compounds in powder formats, enabling shelf-stable products with taste profiles matching ready-to-drink alternatives.
Market Restraints
- Input cost volatility:Purified water and natural flavoring extract prices fluctuate with agricultural yield cycles, compressing gross margins for mid-tier brands without long-term supply contracts.
- Supply concentration risk:Electrolyte mineral processing clusters in China's Jiangsu and Shandong provinces create single-source dependencies that amplify disruption exposure during logistics bottlenecks.
- Regulatory friction:The EU's novel food regulations and EFSA health claim assessment timelines delay product launches by 18-24 months for brands seeking cross-border European distribution.
Strategic Opportunities
- Underpenetrated clinical nutrition:Hospital discharge protocols in Japan and South Korea are expanding oral rehydration therapy prescriptions beyond acute care into post-surgical recovery regimens.
- Direct-to-consumer subscription mechanics:Personalized hydration profiling based on sweat sodium testing is enabling recurring revenue models that lock in athlete loyalty through data-driven formulation adjustments.
- Technology convergence:Wearable biometric sensors paired with AI-driven hydration algorithms are creating demand for companion supplement products calibrated to real-time electrolyte loss data.
Industry Challenges
- Formulation science talent scarcity:Sports nutritionists with clinical electrolyte research backgrounds command premium compensation, constraining smaller brands' ability to build credible product development teams.
- Certification timeline compression:WADA and NCAA banned substance testing protocols require batch-level verification that extends quality control cycles and inflates working capital requirements.
- Legacy system integration:ERP platforms designed for conventional beverage manufacturing lack traceability modules for supplement-grade ingredient sourcing, forcing costly custom implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydration Supplement Market |
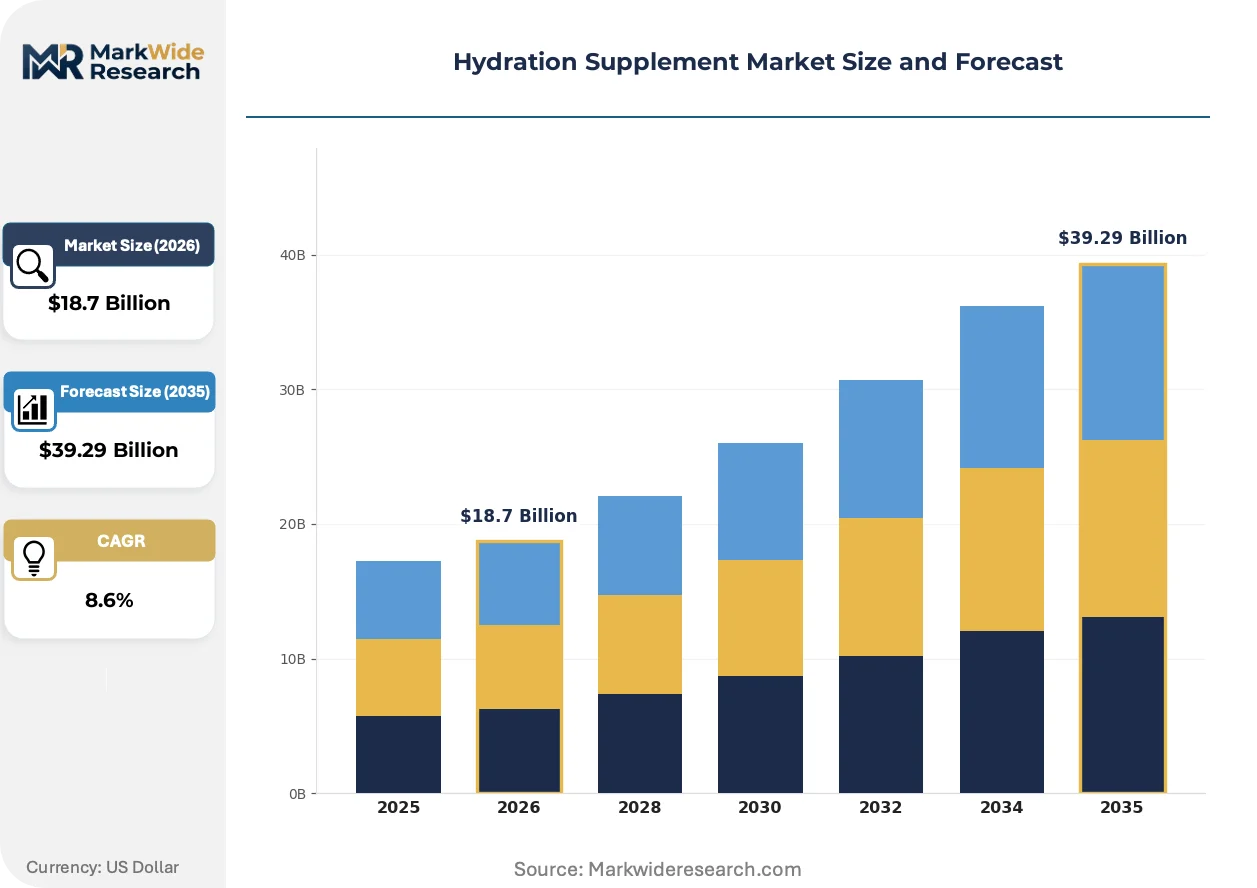
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Form: Powder, Ready-to-Drink, Capsules, Tablets, Liquid Concentrate Ingredient Type: Electrolytes, Vitamins, Natural Extracts, Amino Acids, Minerals End User: Athletes, Outdoor Workers, Elderly, Children, Fitness Enthusiasts Distribution Channel: Online Retailers, Pharmacies, Sports Stores, Supermarkets, Specialty Stores |
| Companies Covered | PepsiCo, The Coca-Cola Company, Nestlé, Abbott Laboratories, Suntory Holdings, Danone, Unilever, Glanbia, Haleon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydration Supplement Market Trends and Innovations
Formulation science, regulatory enforcement, and distribution mechanics are simultaneously rewriting competitive rules across the hydration supplement category.
Precision fermentation-derived electrolytes are decomposing the cost structure of mineral sourcing. Biotechnology startups in California and the Netherlands are producing bioavailable magnesium and potassium compounds without mining extraction. This technology is decomposing incumbent supply chain advantages held by established mineral processors.
REACH regulation amendments targeting microplastic contamination in food-contact materials are forcing packaging redesigns across European markets. Brands must accelerate migration from conventional plastic bottles to aluminum or glass alternatives. Powder formats in Germany and France are gaining share as manufacturers sidestep liquid packaging compliance costs.
Athlete procurement patterns are fragmenting away from retail shelf selection toward direct brand relationships. Subscription platforms and team-specific bulk purchasing agreements are displacing traditional sports nutrition retail in the United States. Collegiate athletic departments in Texas and Florida are consolidating supplier contracts around single-source hydration partners with embedded sports science support.
Hydration Supplement Market Segmentation
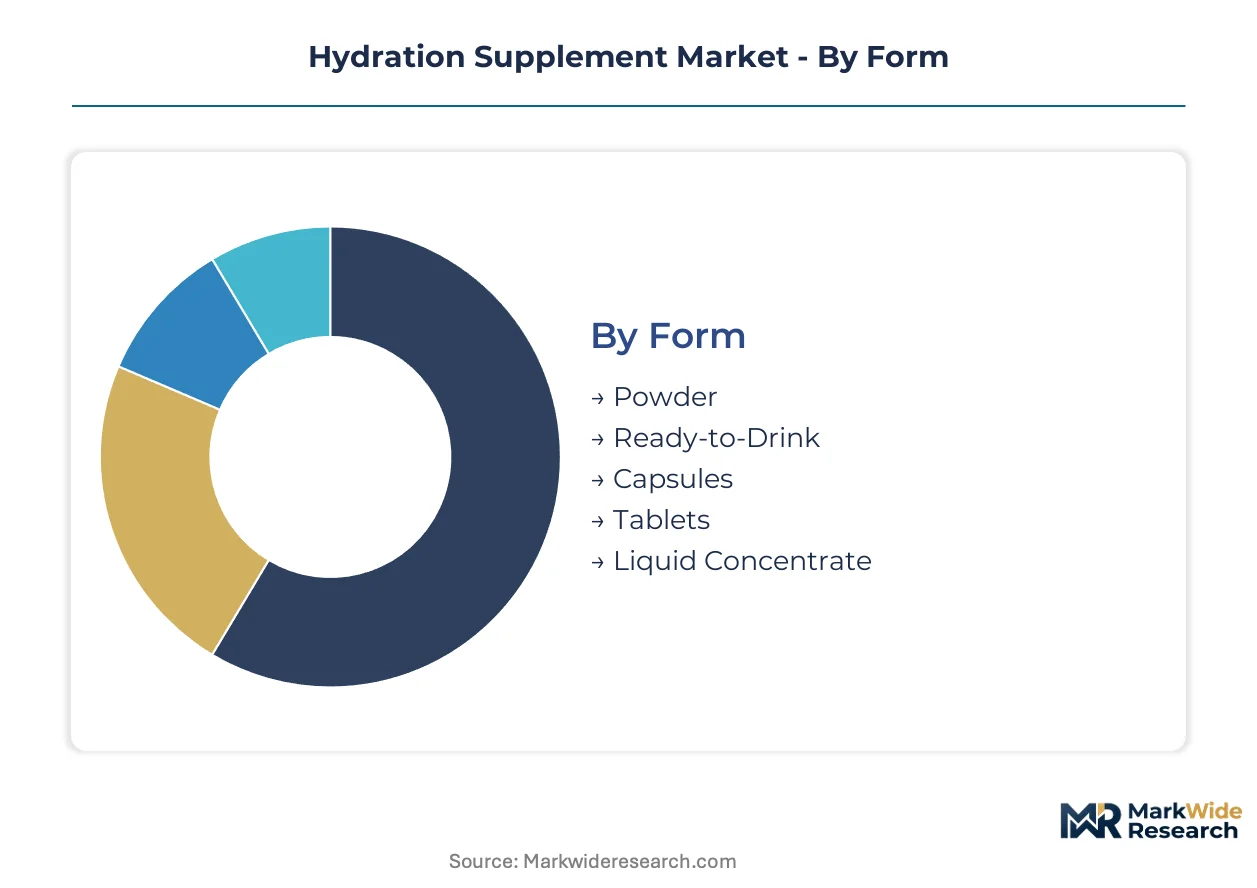
Hydration supplement segmentation reveals divergent vulnerability to substitute products across consumption contexts. Formulation format and channel selection determine which segments face erosion from conventional beverages versus fortified foods.
Form:
Powder formats face the strongest substitution pressure from homemade electrolyte blends and coconut water, while convenience-driven segments defend against commoditization through packaging innovation.
- Ready-to-Drink:Pre-mixed beverages with osmolality calibrated between 200-400 mOsm/kg for optimal gastric emptying. Demand concentrates among time-constrained fitness enthusiasts in the United States where grab-and-go consumption dominates gym and workplace channels. Convenience premiums sustain margin structures despite higher per-serving costs versus powder alternatives.
- Powder:Spray-dried or freeze-dried formulations enabling customizable dosing and extended shelf stability. Amateur endurance athletes in Germany and Japan drive procurement through cost-per-serving optimization and transportability for event-day logistics.
- Capsules:Encapsulated electrolyte blends targeting precise mineral replenishment without flavor systems. Travelers and military personnel prioritize portability and TSA compliance.
- Tablets:Effervescent or solid-dose formats dissolving in water for on-demand preparation. Outdoor workers in Australia favor lightweight storage and reduced packaging waste.
- Liquid Concentrate:Hyper-concentrated solutions requiring dilution prior to consumption. Bulk purchasers and institutional buyers leverage volume economics for team or facility provisioning.
Ready-to-Drink retains volume leadership; Liquid Concentrate holds the steepest expansion curve through institutional contract penetration.
Ingredient Type:
Cost tier stratification separates commodity mineral formulations from premium bioactive compounds, with pricing power concentrated in clinically validated ingredient categories.
- Electrolytes:Sodium, potassium, magnesium, and calcium compounds restoring ionic balance during perspiration. Sodium chloride and potassium citrate formulations dominate amateur athletics in Texas and Florida where heat stress drives replenishment frequency.
- Vitamins:Water-soluble B-complex and vitamin C fortification supporting metabolic energy conversion. Fitness enthusiasts seeking multifunctional products accelerate procurement in United States subscription channels.
- Amino Acids:Branched-chain and essential amino acid inclusion supporting muscle protein synthesis alongside hydration. Endurance athletes in Japan prioritize leucine-enriched formulations for recovery optimization.
- Natural Extracts:Plant-derived compounds including coconut water powder and tart cherry extract. Clean-label seekers in California and the Netherlands drive demand for minimally processed alternatives.
- Minerals:Zinc, manganese, and trace element fortification beyond primary electrolytes. Post-surgical patients in Japanese hospital discharge protocols receive prescribed oral rehydration therapy with expanded mineral profiles.
Electrolytes command the broadest addressable base; Amino Acids are climbing fastest through sports nutrition convergence.
End User:
Application intensity varies dramatically across user types, with professional and occupational segments sustaining premium pricing versus recreational consumers.
- Athletes:Competitive and amateur participants requiring performance-calibrated formulations. Collegiate athletic departments in Texas and Florida consolidate supplier contracts around NSF Certified for Sport verification.
- Outdoor Workers:Agricultural, construction, and utility personnel facing sustained heat exposure. OSHA heat illness prevention programs in the United States drive employer-provisioned hydration protocols.
- Fitness Enthusiasts:Recreational gym-goers and studio practitioners seeking general wellness support. Boutique fitness chains in New York and Los Angeles embed branded hydration into membership experiences.
- Elderly:Age-related thirst impairment and medication-induced dehydration risks. Japanese and South Korean healthcare systems expand oral rehydration therapy into post-discharge regimens.
- Children:Pediatric formulations with adjusted osmolality and flavor profiles. School nutrition programs in France and Germany pilot electrolyte provision during athletic activities.
Athletes anchor revenue concentration; Outdoor Workers are expanding most quickly through occupational safety mandates.
Distribution Channel:
Customer type determines channel selection, with subscription mechanics displacing transactional retail among high-frequency users.
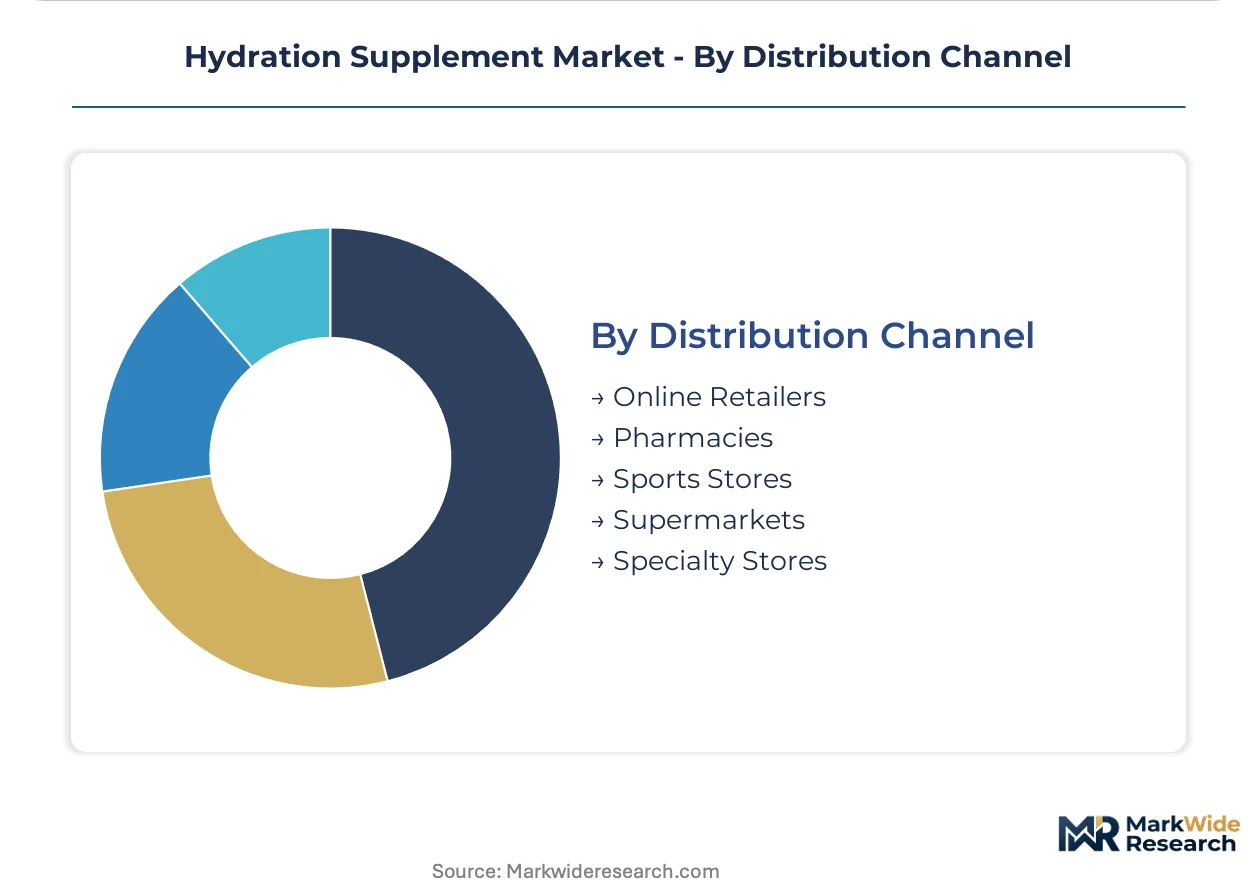
- Online Retailers:Direct-to-consumer platforms and marketplace aggregators enabling personalized profiling. Sweat sodium testing integration locks athlete loyalty through data-driven formulation adjustments in United States subscription models.
- Sports Stores:Specialty retail with embedded staff expertise and sampling programs. Endurance event expos in Germany and Japan generate bulk purchases tied to race calendars.
- Pharmacies:Clinical positioning for medical-grade electrolyte products. Japanese hospital discharge protocols route patients to pharmacy fulfillment for prescribed oral rehydration therapy.
- Supermarkets:Mass-market accessibility for convenience-driven consumers. Ready-to-drink placement competes with conventional sports beverages for impulse purchase.
- Specialty Stores:Curated selection targeting clean-label and certification-focused buyers. Organic and natural product retailers in California prioritize Informed Sport verified inventory.
Online Retailers are gaining share fastest; Sports Stores retain the highest per-transaction value through expert-guided selection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA's evolving dietary supplement labeling requirements anchor the United States as the dominant geography, while regulatory frameworks in Japan, Germany, China, and Australia shape distinct market development trajectories across the forecast window.
United States
Marathon and triathlon participation in Texas and Florida drives medical-grade electrolyte procurement into amateur segments. OSHA heat illness prevention programs mandate employer-provisioned hydration protocols for outdoor workers. Collegiate athletic departments in California and the Southeast consolidate supplier contracts around NSF Certified for Sport verification.
Germany
Endurance event expos in Berlin and Munich generate bulk purchases tied to race calendars. REACH regulation amendments targeting microplastic contamination force packaging migration from plastic bottles to aluminum alternatives. Powder formats in Bavaria and North Rhine-Westphalia gain share as manufacturers sidestep liquid packaging compliance costs.
Japan
Hospital discharge protocols in Tokyo and Osaka expand oral rehydration therapy prescriptions into post-surgical recovery regimens. METI standards for functional food labeling constrain health claim substantiation timelines. Sports nutrition research clusters in Kansai prioritize leucine-enriched formulations for endurance athlete recovery optimization.
China
Fitness culture penetration in Shanghai and Beijing accelerates premium formulation uptake among middle-class consumers. SAMR registration requirements for imported dietary supplements extend product launch timelines. Electrolyte mineral processing clusters in Jiangsu and Shandong provinces create single-source dependencies that amplify disruption exposure.
Australia
Outdoor workers in Queensland and Western Australia favor lightweight tablet formats for reduced packaging waste. The country's national pharmaceutical regulator maintains strict import standards for therapeutic goods. Subscription platforms in Sydney and Melbourne displace traditional sports nutrition retail through direct brand relationships.
Hydration Supplement Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with beverage conglomerates leveraging distribution infrastructure against nutrition science specialists building clinical credibility. The upper tier commands shelf placement economics through captive retail networks, while mid-cap specialists compete on certification depth and athlete endorsement density. Two strategic archetypes dominate: diversified nutrition platforms with healthcare channel access, and beverage incumbents with ready-to-drink manufacturing scale. Competitive moves concentrate on backward integration into electrolyte mineral sourcing and exclusive team supply contracts with collegiate athletic departments.
Within the diversified nutrition tier, Abbott Laboratories and Nestlé occupy positions anchored by medical-grade electrolyte science and legacy nutrition research infrastructure. PepsiCo represents the beverage incumbent archetype, with distribution reach that dominates convenience and gym channel placement. These three companies exemplify the structural divide between clinical credibility strategies and convenience-driven volume capture.
| Leading Market Players |
|---|
| PepsiCo |
| The Coca-Cola Company |
| Nestlé |
| Abbott Laboratories |
| Suntory Holdings |
| Danone |
| Unilever |
| Glanbia |
| Haleon |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between electrolyte processors and ready-to-drink manufacturers lock in both supply access and price visibility across the forecast window, insulating volume buyers from agricultural yield volatility in natural flavoring markets. These arrangements concentrate procurement power among PepsiCo and Abbott Laboratories while forcing mid-tier brands into spot-market exposure for purified water and mineral inputs.
Pricing Analysis
Long-term offtake agreements dominate volume procurement, though spot purchasing persists for natural extract inputs subject to harvest variability. Three-tier pricing structure across premium, standard, and economy levels separates NSF Certified for Sport formulations from basic electrolyte blends and private-label commodity products. Pricing pressure stems from input cost volatility in Chinese mineral processing clusters, compressing margins for brands without captive supply. Amateur endurance athletes exhibit highest price sensitivity, while collegiate athletic departments prioritize certification grade over per-serving cost.
Supply Chain Analysis
Jiangsu and Shandong province processing clusters create single-source chokepoints for magnesium and potassium compounds, amplifying disruption exposure during logistics bottlenecks. Electrolyte mineral sourcing draws from China's coastal industrial zones, with secondary concentration in German chemical processing hubs for pharmaceutical-grade formulations. Raw material dependencies include sodium chloride, potassium citrate, and natural flavoring extracts from agricultural suppliers. Tariff exposure on Chinese mineral imports threatens cost structures for U.S.-based brands. Distribution runs through direct-to-consumer subscription platforms and beverage distributor networks, with institutional contracts gaining share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across this market as athlete procurement patterns fragment away from retail shelf selection toward direct brand relationships, creating niche entry points for specialists with embedded sports science capabilities.
For Market Incumbents: Fortify certification depth against emerging biotechnology entrants producing precision fermentation-derived electrolytes. Invest in backward integration into electrolyte mineral sourcing to reduce dependency on Chinese processing clusters. Expand exclusive team supply contracts with collegiate athletic departments in Texas and Florida to lock out competitor shelf placement. For New Entrants and Emerging Players: NSF Certified for Sport fast-track protocols enable rapid credibility acquisition for brands targeting collegiate procurement channels. White-space targets include post-surgical recovery regimens in Japanese hospital discharge protocols and occupational safety mandates for outdoor workers in Queensland and Western Australia. Sweat sodium testing integration offers a defensible go-to-market angle for subscription-based customer acquisition. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with embedded sports nutritionist teams and existing clean-label certification infrastructure. Long-term viability over the projection horizon favors brands with clinical credibility moats rather than commodity volume plays. Watch for inflection signals in wearable biometric sensor adoption rates, as AI-driven hydration algorithms create demand for companion supplement products.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment | NSF Certified for Sport verification unlocks collegiate and professional team supply chains. |
| Backward Integration | In-house electrolyte mineral processing reduces exposure to Chinese supply concentration. |
| Direct-to-Consumer Launch | Subscription platforms with sweat sodium testing integration lock athlete loyalty through personalization. |
| Sports Science Partnership | Embedded nutritionist teams differentiate premium brands from commodity competitors. |
| Packaging Redesign | Aluminum and glass alternatives address REACH microplastic compliance in European markets. |
Research Methodology
Initial hypotheses were tested against primary input from sports nutritionists, electrolyte formulation scientists, collegiate athletic procurement directors, and beverage distribution channel managers and refined through secondary validation against FDA labeling guidance documents, EFSA health claim assessments, customs trade data for electrolyte mineral imports, and SEC filings from diversified nutrition platforms. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Variance decomposition across form, ingredient type, end user, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate blending with cross-elasticity adjustments for substitute product threats. Forecast inputs included marathon participation trajectories in the United States, Germany, and Japan; OSHA heat illness prevention program expansion; and precision fermentation technology maturation curves.
Decision-makers should treat outputs as directional under assumptions of stable FDA enforcement timelines and continued endurance athletics participation growth; material deviation in regulatory windows or fitness culture penetration would warrant model refresh. Practitioners should keep alternative scenarios live as EU novel food assessment timelines and Chinese mineral export policy evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
Sports Nutrition Ingredients Market
Sports Nutrition
Hydroxymethylbutyrate Supplement Market
Sports Nutrition
Androstenedione Market
Sports Nutrition
North America Sports Drink Market
Sports Nutrition
Taurine Supplements Market
Sports Nutrition
Creatine Market
Sports Nutrition
B2B Sports Nutrition Market
Sports Nutrition
Europe Protein Bar Market
Sports Nutrition
Japan Sports Drink Market
Sports Nutrition
Sports Nutrition Market
Sports Nutrition
Europe Protein Based Sports Drinks Market
Sports Nutrition
UK Sports Nutrition Market
Sports Nutrition
Middle East Sports Drinks Market
Sports Nutrition
GCC Sports Nutrition Market
Sports Nutrition
Africa Sports Drink Market
Sports Nutrition
South America Sports Nutrition Market