
 Germany Automotive LED Lighting Market | 2026-2036
Germany Automotive LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Automotive LED Lighting Market Insights
Optical engineering talent scarcity is reorganizing supplier hierarchies across southern Germany. HELLA GmbH & Co. KGaA leverages captive photonics laboratories in Lippstadt to sustain adaptive beam development. OSRAM GmbH anchors upstream LED chip fabrication, while Robert Bosch GmbH competes through integrated sensor-lighting fusion for automated driving.
Germany Automotive LED Lighting comprises solid-state semiconductor devices emitting electroluminescence across visible and infrared spectra, typically operating at forward voltages of 2-4V with luminous efficacy exceeding 130 lm/W, engineered for exterior and interior vehicular illumination. Headlights and matrix technology command the dominant margin pools as OEMs prioritize glare-free adaptive systems over traditional halogen replacements. Interior lighting segments specialize in ambient cabin architectures, whereas laser technology occupies niche ultra-long-range applications for premium platforms.
KBA enforces UN ECE R48 and R123 homologation standards that dictate beam pattern precision and adaptive activation protocols for all road-legal LED installations. The EU Green Deal's embodied carbon requirements for automotive components are forcing suppliers to document lifecycle emissions across gallium nitride epitaxy and aluminum housing supply chains. Stakeholders must decide whether to deepen in-house III-V semiconductor growth or secure multi-source wafer agreements before next-generation matrix volumes materialize.
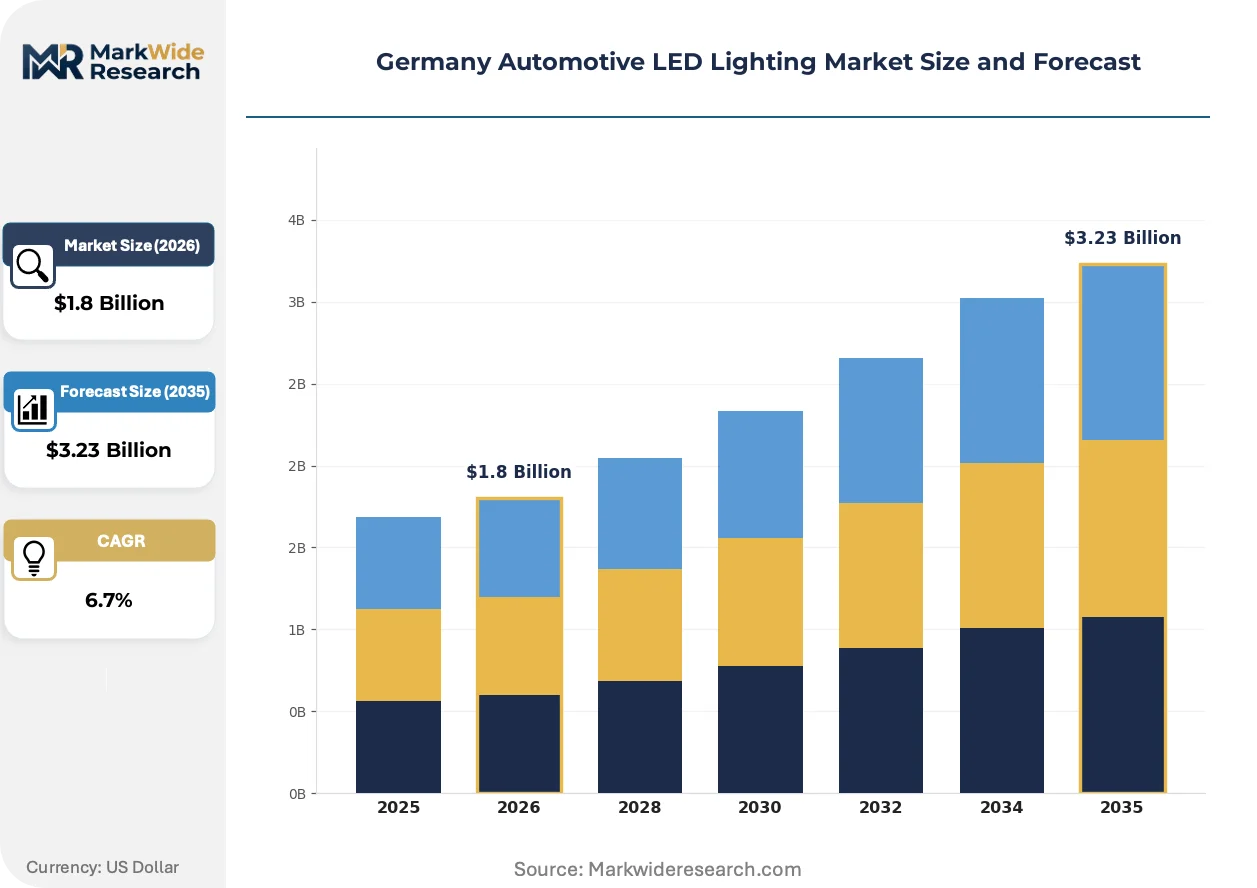
Market Dynamics
KBA homologation compression for glare-free matrix beams is forcing Bavarian and Baden-Württemberg OEMs to compress supplier development cycles from 36 to 24 months, restructuring tier relationships across the Munich-Stuttgart corridor.
Growth Catalysts
- EU Green Deal embodied carbon mandates:Suppliers documenting lifecycle emissions across gallium nitride epitaxy gain preferential OEM qualification status.
- Adaptive headlamp procurement expansion:Premium passenger vehicle platforms in southern Germany are standardizing matrix LED configurations across model lines.
- Sensor-lighting fusion:Automated driving architectures require integrated photonic systems that combine illumination with LiDAR and camera housings.
Market Restraints
- Gallium nitride wafer supply concentration:III-V semiconductor substrate fabrication concentrates among Asian foundries, exposing German module makers to input volatility.
- Optical engineering talent scarcity:Photonics laboratories in Lippstadt and surrounding clusters compete for finite simulation and beam-pattern design specialists.
- Homologation timeline rigidity:UN ECE R48 and R123 certification protocols create fixed validation gates that resist acceleration even with compressed development schedules.
Strategic Opportunities
- Laser technology niche penetration:Ultra-long-range illumination modules for premium platforms remain underdeployed relative to matrix LED saturation.
- Ambient cabin architecture specialization:Interior lighting segments offer white space as OEMs differentiate through programmable color-temperature environments.
- Multi-source wafer agreements:Securing diversified III-V semiconductor supply ahead of next-generation matrix volume ramps insulates against concentration risk.
Industry Challenges
- Homologation cycle compression:KBA validation protocols for adaptive activation must synchronize with compressed 24-month OEM development windows.
- Aluminum housing supply chain documentation:EU Green Deal requirements force tier-two metalwork suppliers to implement carbon accounting systems they lack capability to execute.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Automotive LED Lighting Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headlights, Taillights, Fog Lights, Interior Lighting Technology: Traditional, Adaptive, Matrix, Laser End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Application: Passenger Vehicles, Commercial Vehicles, Two-wheelers, Buses |
| Companies Covered | HELLA GmbH & Co. KGaA, OSRAM GmbH, Valeo, Marelli Holdings Co., Ltd., Grupo Antolin-Irausa, S.A., ams-OSRAM AG, Stanley Electric Co., Ltd., Robert Bosch GmbH, Hyundai Mobis Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Automotive LED Lighting Market Trends and Innovations
Matrix LED architectures are displacing conventional adaptive systems across German premium platforms, while regulatory pressure on embodied carbon restructures upstream semiconductor procurement.
Digital micromirror device technology is displacing traditional LED array switching in next-generation adaptive headlamps. Munich-based OEM engineering centers specify these systems for 2027 platform launches. The technology is displacing incumbent mechanical shutter mechanisms by enabling 25,000-pixel addressability without moving parts.
KBA enforcement of UN ECE R123 glare-free activation protocols tightens beam-pattern precision requirements. German suppliers must demonstrate real-time pedestrian and oncoming vehicle detection integration. Bavarian OEM homologation teams report 18-month validation extensions for non-compliant module submissions.
Procurement consolidation among Stuttgart and Munich OEMs favors suppliers offering combined LED-sensor modules. Traditional discrete lighting vendors without automated driving integration capabilities lose platform access. This concentration is most visible in Baden-Württemberg, where Mercedes-Benz and Porsche procurement teams mandate fused photonic-sensor housings for 2026 architectures.
Germany Automotive LED Lighting Market Segmentation
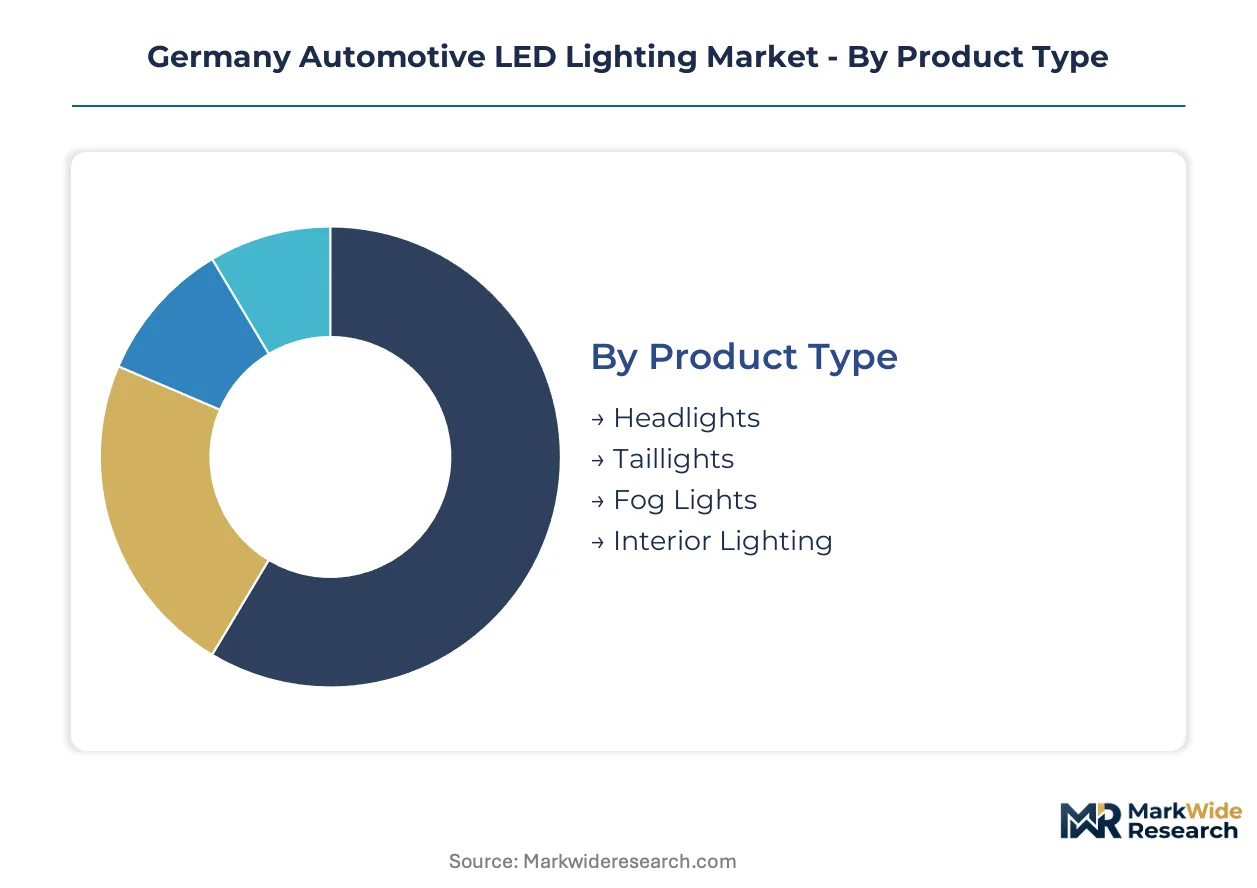
German OEM procurement patterns concentrate margin pools in adaptive exterior systems and premium interior architectures. KBA homologation requirements fragment supplier qualification across each segment boundary.
Product Type:
Headlights and matrix-enabled front lighting systems capture the dominant margin pools across Bavarian and Baden-Württemberg OEM platforms.
- Headlights:Matrix LED configurations with 25,000-pixel addressability dominate premium platform specifications from Munich and Stuttgart engineering centers. Bavarian OEM procurement teams mandate glare-free adaptive activation as standard equipment across mid-tier and above model lines.
- Interior Lighting:Programmable ambient cabin architectures with tunable color temperature differentiate luxury segment offerings. Demand concentrates in Baden-Württemberg where Mercedes-Benz and Porsche specification teams prioritize programmable LED strip integration across door panels and dashboards.
- Taillights:Sequential indicator animation and OLED-style uniformity drive styling differentiation.
- Fog Lights:Integration into full-width front light bars reduces standalone module demand.
The dominant share belongs to Headlights, while Interior Lighting is closing the gap fastest.
Technology:
Cost tier stratification separates premium matrix systems from economy traditional LED replacements.
- Matrix:Digital micromirror device architectures displace mechanical shutters for pixel-level beam control. Munich-based OEM engineering centers specify these systems for platform launches requiring real-time pedestrian masking.
- Adaptive:Camera-integrated beam pivoting remains the volume workhorse for mid-premium segments. Stuttgart procurement favors suppliers combining adaptive hardware with fused sensor housings for automated driving compatibility.
- Laser:Niche ultra-long-range modules serve autobahn-optimized premium platforms.
- Traditional:Halogen replacement volumes concentrate in entry segments and aftermarket channels.
Matrix technology holds the dominant position, though Adaptive systems retain the steepest expansion trajectory in absolute volume terms.
End User:
Application type determines procurement authority and development cycle compression exposure.
- OEMs:Direct specification control over beam pattern architecture and homologation timing. BMW and Mercedes-Benz procurement teams compress supplier development cycles from 36 to 24 months for matrix platform launches.
- Tier-1 Suppliers:Module integration responsibility concentrates among HELLA, Bosch, and OSRAM with captive photonics capabilities.
- Aftermarket Providers:KBA compliance documentation requirements limit viable participants.
- Vehicle Assemblers:Contract manufacturing arrangements for export-focused production.
OEMs command the dominant share, while Tier-1 Suppliers are gaining procurement influence through sensor-lighting fusion capabilities.
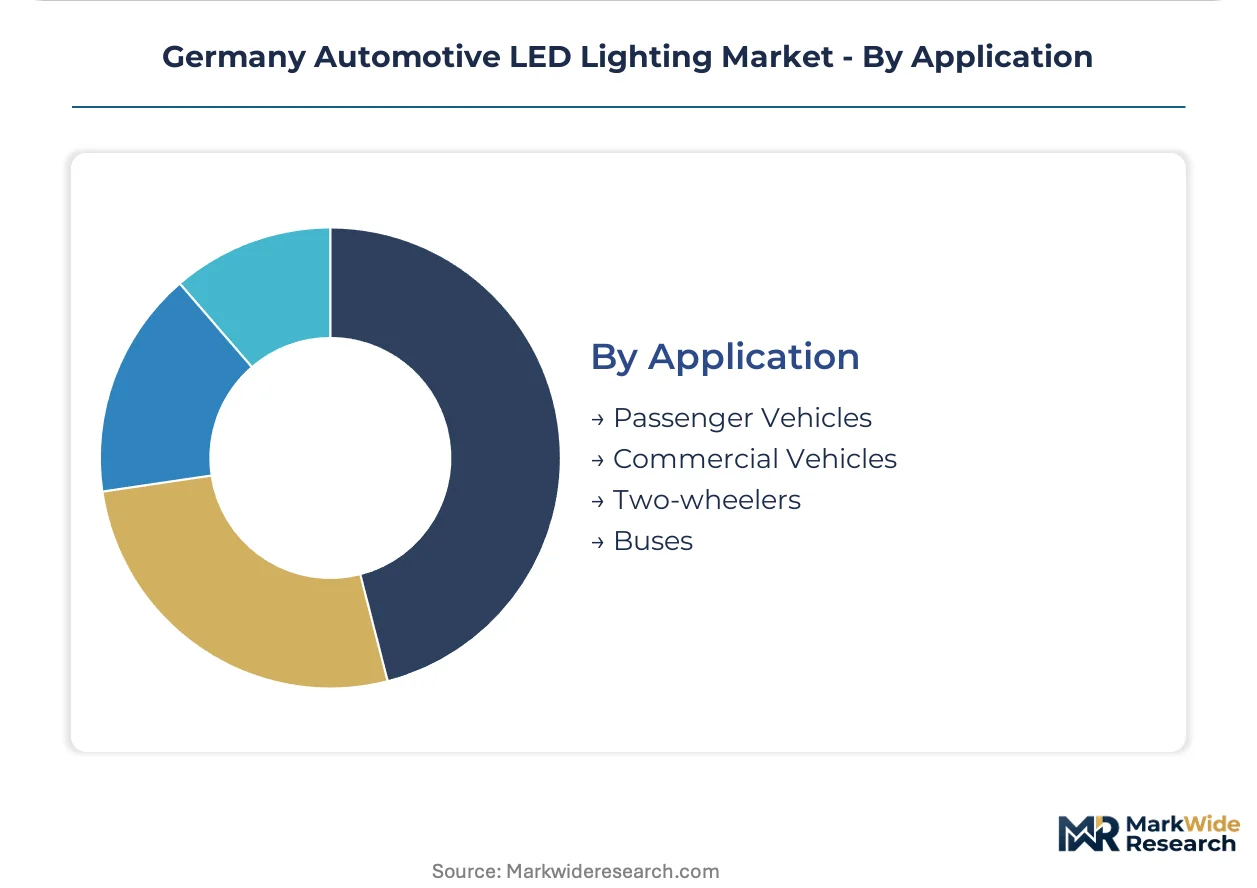
Application:
Volume concentration versus margin extraction splits across passenger and commercial vehicle architectures.
- Passenger Vehicles:Premium platforms in southern Germany standardize matrix LED across model lines. Adaptive headlamp procurement expansion targets Bavarian and Baden-Württemberg production facilities.
- Commercial Vehicles:Durability-focused specifications prioritize thermal management over adaptive complexity.
- Two-wheelers:Compact form factor constraints limit matrix adoption.
- Buses:Interior ambient lighting and destination display integration drive specification.
Passenger Vehicles retain the dominant share, while Commercial Vehicles are expanding most quickly through fleet electrification mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
KBA homologation protocols for glare-free matrix beams anchor regulatory activity across German automotive LED lighting demand centers. State-level procurement patterns concentrate specification authority in southern production corridors.
Bavaria
Munich-based OEM engineering centers mandate 25,000-pixel digital micromirror device architectures for 2027 platform launches. KBA enforcement of UN ECE R123 glare-free activation protocols requires real-time pedestrian masking integration. Ingolstadt supplier clusters concentrate adaptive headlamp module validation facilities serving premium passenger vehicle lines.
Baden-Württemberg
Stuttgart procurement teams compress supplier development cycles from 36 to 24 months for matrix platform launches. EU Green Deal embodied carbon mandates force tier-two metalwork suppliers to implement aluminum housing carbon accounting systems. Karlsruhe photonics laboratories compete for finite beam-pattern simulation specialists.
North Rhine-Westphalia
Lippstadt captive photonics capabilities sustain adaptive beam development for integrated lighting-sensor modules. REACH compliance documentation requirements restructure gallium nitride epitaxy supply chain verification. Dortmund module assembly plants serve export-focused production arrangements for automated driving-compatible architectures.
Hesse
Frankfurt-Rhine-Main logistics corridors facilitate III-V semiconductor wafer import distribution from Asian foundries. German suppliers face input volatility from concentrated substrate fabrication sources. Darmstadt engineering consultancies specialize in UN ECE R48 beam pattern precision certification for tier-one module makers.
Lower Saxony
Wolfsburg-area vehicle assemblers specify durability-focused thermal management over adaptive complexity for volume platforms. Commercial vehicle fleet electrification mandates expand LED taillight and interior bus lighting procurement. Hanover supplier parks concentrate sequential indicator animation module production for styling differentiation.
Germany Automotive LED Lighting Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in German automotive LED lighting supply. Captive photonics laboratories and upstream LED chip fabrication capabilities separate tier-one module integrators from component-dependent competitors. Two strategic archetypes dominate: semiconductor-anchored suppliers controlling gallium nitride epitaxy, and sensor-fusion specialists combining illumination with automated driving housings. Competitive moves concentrate on multi-source wafer agreements and compressed homologation cycle synchronization.
Within the integrated leader tier, HELLA GmbH & Co. KGaA and Robert Bosch GmbH exemplify divergent capability emphases. HELLA occupies a position tied to captive photonics laboratories in Lippstadt. Bosch represents the sensor-lighting fusion archetype for automated driving architectures. OSRAM GmbH anchors upstream LED chip fabrication among German-headquartered competitors. These three entities sit within a structure where semiconductor control and homologation timing expertise determine platform access.
| Leading Market Players |
|---|
| HELLA GmbH & Co. KGaA |
| OSRAM GmbH |
| Valeo |
| Marelli Holdings Co., Ltd. |
| Grupo Antolin-Irausa, S.A. |
| ams-OSRAM AG |
| Stanley Electric Co., Ltd. |
| Robert Bosch GmbH |
| Hyundai Mobis Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
KBA homologation protocols for UN ECE R123 glare-free matrix beams gate both supplier qualification and price differentiation simultaneously. Bavarian and Baden-Württemberg OEM procurement teams award platform access only to module makers bearing validated beam-pattern precision documentation, compressing viable supply bases and concentrating pricing power among photonics-capable tier-ones.
Pricing Analysis
Munich-Stuttgart corridor pricing spreads widen by certification tier rather than component cost alone. Three-tier pricing structure across premium matrix, standard adaptive, and economy traditional LED levels separates KBA-validated suppliers from aftermarket-limited competitors. Price differentiation rests on homologation documentation completeness and real-time pedestrian masking integration. Cost compression in economy halogen replacement tiers is intensifying because Asian module imports erode domestic aftermarket margins. Fleet procurement teams at commercial vehicle assemblers exhibit highest price sensitivity, whereas Mercedes-Benz and Porsche specification engineers prioritize beam-pattern precision over unit cost.
Supply Chain Analysis
Inventory lead times for III-V semiconductor wafers now stretch 26-32 weeks, forcing German module makers to pre-position gallium nitride epitaxy inputs. Taiwan, South Korea, and China concentrate upstream LED chip fabrication, exposing Lippstadt and Dortmund assembly plants to single-source vulnerability from concentrated Asian foundry capacity. Raw material dependencies center on gallium nitride substrates, aluminum housing extrusions, and phosphor conversion materials. Distribution runs through captive OEM supplier parks in Ingolstadt and Stuttgart, with secondary channels serving aftermarket retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Matrix LED platform economics are inflecting toward sensor-fusion interoperability, where photonic module suppliers must integrate LiDAR and camera housings to retain OEM specification authority. This ecosystem shift rewards suppliers with automated driving architecture relationships over discrete lighting specialists.
For Market Incumbents: Consolidate captive photonics laboratory capabilities in Lippstadt and Karlsruhe clusters to defend against sensor-fusion entrants from automated driving tier-ones. Deepen backward integration into gallium nitride epitaxy through multi-source wafer agreements with Taiwanese and South Korean foundries. Prioritize KBA pre-validation investments to compress homologation cycle exposure from 36 to 24 months.
For New Entrants and Emerging Players: Anchor in programmable ambient cabin architectures for Baden-Württemberg luxury platforms, where Mercedes-Benz specification teams seek differentiated LED strip integration across door panels and dashboards. Target white space in laser ultra-long-range modules for autobahn-optimized premium vehicles, a segment underdeployed relative to matrix LED saturation. Pursue go-to-market partnerships with Darmstadt engineering consultancies specializing in UN ECE R48 beam pattern certification.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across digital micromirror device architectures, as 25,000-pixel addressability requirements demand specialized MEMS fabrication capabilities. Long-term viability across the projection horizon favors suppliers combining semiconductor control with homologation timing expertise. Acquisition target archetype: mid-cap module integrators with KBA-validated beam-pattern libraries but lacking sensor-fusion capabilities. Watch for inflection when Stuttgart OEM procurement teams mandate fused photonic-sensor housings as standard specification.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Source Wafer Agreement | Diversifies III-V semiconductor supply away from concentrated Asian foundry exposure for German module makers. |
| KBA Pre-Validation Investment | Compresses homologation cycle timing to match BMW 24-month platform development windows. |
| Sensor-Lighting Fusion Development | Secures Mercedes-Benz and Porsche procurement access for automated driving-compatible architectures. |
| Captive Photonics Laboratory Expansion | Sustains adaptive beam development against optical engineering talent scarcity in southern Germany. |
| EU Green Deal Carbon Documentation | Qualifies aluminum housing suppliers for preferential OEM status under embodied carbon mandates. |
Research Methodology
Desk research of KBA homologation filings, UN ECE regulatory databases, and EU Green Deal implementation guidelines preceded structured interviews with OEM platform engineers, Tier 1 supplier procurement leads, photonics laboratory directors, and aftermarket distribution managers. Secondary validation drew from vehicle production databases, IHS Markit registration data, and SEC filings of listed automotive lighting suppliers. Bottom-up module shipment estimates triangulated against top-down OEM platform content projections.
Variance decomposition across technology, vehicle class, and regional production cluster dimensions anchored the analytical framework. CAGRs were derived from segment-level volume trajectories modeled against KBA validation timeline constraints and matrix LED penetration curves. Key forecast inputs included gallium nitride wafer supply elasticity and Stuttgart-Munich OEM procurement cycle compression rates.
Decision-makers should treat outputs as directional under assumptions of sustained KBA enforcement rigidity and stable III-V semiconductor foundry capacity; material deviation would warrant model refresh. Forecasts embed assumptions regarding EU Green Deal carbon accounting implementation timelines and adaptive headlamp standardization across premium model lines. Revision becomes warranted when gallium nitride wafer lead times or KBA validation queue lengths cross thresholds that disrupt platform launch synchronization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Bluetooth LED Bulb Market
LED
LED Panel Light Drivers Market
LED
Four-Digit 7 Segment LED Displays Market
LED
Middle East LED Lighting Market
LED
LED Control Unit Market
LED
Led Video Walls Market
LED
Africa LED Lighting Market
LED
Pixel Pitch LED Market
LED
US Outdoor LED Lighting Market
LED
Gan Substrate Market
LED
LED Panel Market
LED
Europe LED Packaging Market
LED
Surface Mount PLCC Leds Market
LED
France Indoor LED Lighting Market
LED
India LED Lighting Market
LED
Thailand LED Market