
 US LED Downlight Market | 2026-2036
US LED Downlight Market Size, Share, and Industry Trends Forecast 2026-2036
US LED Downlight Market Intelligence
Aftermarket service revenue is fragmenting across installation, commissioning, and remote diagnostics as contractors seek recurring income beyond fixture sales. Acuity Brands leverages its extensive agent network to sustain specification-grade positioning in commercial projects. Cree Lighting anchors its competitiveness through captive LED chip production and thermal management specialization. Signify Holding differentiates via its Interact smart lighting platform, extending software touchpoints into building management systems.
A US LED downlight is a ceiling-recessed or surface-mounted luminaire employing solid-state LED emitters, typically operating at color temperatures between 2700K and 5000K with efficacy ratings exceeding 90 lumens per watt, designed for general or accent illumination in interior spaces. Recessed downlights dominate residential and commercial volume due to architectural integration and compatibility with insulated ceiling assemblies. Smart lighting technology captures expanding specification interest as building codes mandate networked controls for energy compliance. The hospitality application segment rewards dimmable and tunable-white configurations that support circadian design protocols and guest experience differentiation.
DOE appliance efficiency standards, EPA ENERGY STAR certification requirements, and state-level stretch codes such as California Title 24 collectively mandate minimum efficacy thresholds and networked control readiness for new construction and major renovation. These frameworks accelerate obsolescence of legacy fluorescent and halogen downlight inventories while creating compliance barriers for import-dependent suppliers. Stakeholders must monitor emerging federal Buy America provisions for federally funded infrastructure and building projects, as domestic content rules could reshape supplier qualification and procurement behavior across public-sector channels.
Market Dynamics
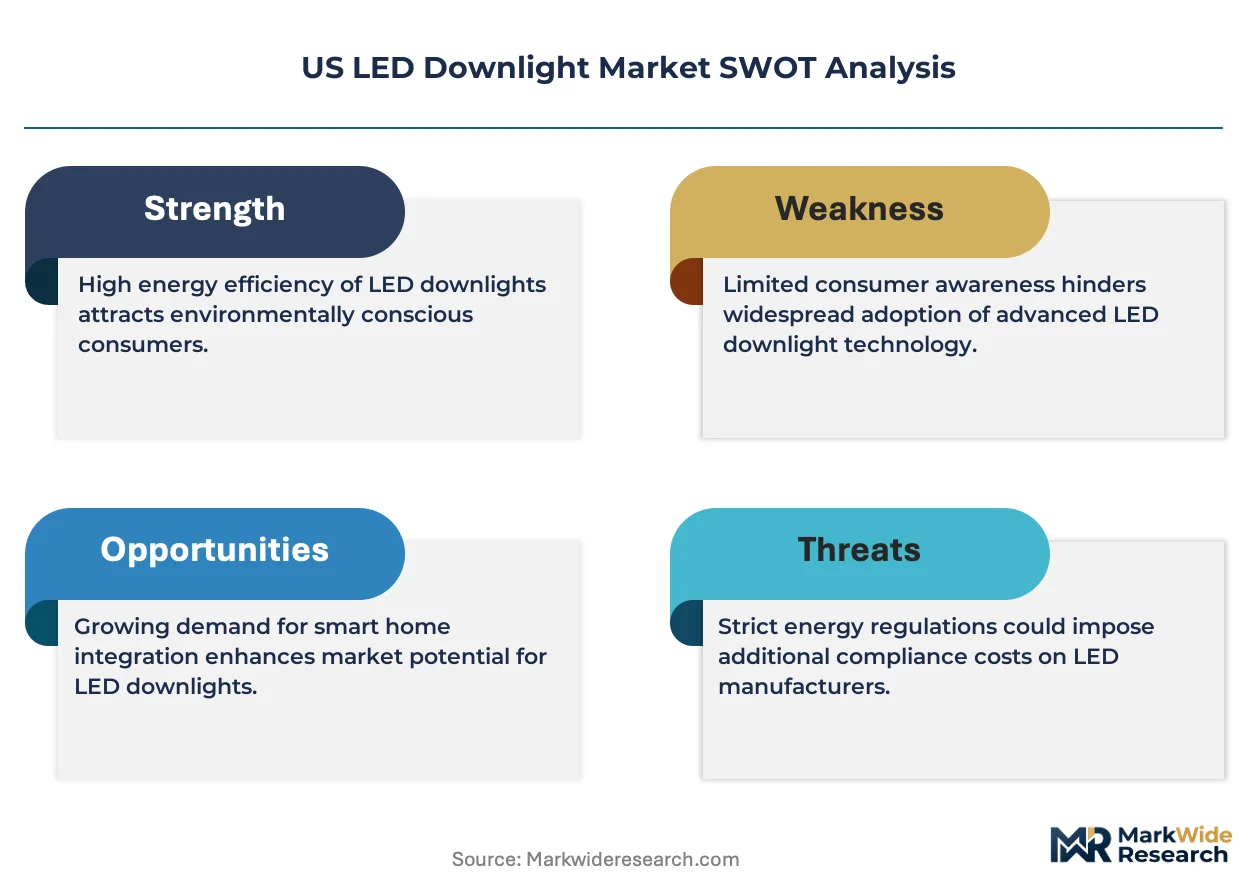
DOE lighting efficiency standards are compressing replacement cycles while tightening minimum efficacy thresholds, forcing manufacturers to redesign thermal management systems and driver architectures ahead of legacy inventory obsolescence.
Growth Catalysts
- Residential Retrofit Momentum:Texas and Florida replacement activity is accelerating fixture turnover as homeowners prioritize energy cost reduction ahead of summer cooling peaks.
- California Title 24 Mandates:The state's stretch code requirements for networked control readiness in new construction are pulling specification-grade demand toward smart-ready downlight platforms.
- LED Chip Thermal Efficiency:Advances in flip-chip packaging and ceramic substrate bonding are enabling higher lumen density without increasing fixture depth, expanding installation flexibility in shallow ceiling plenums.
Market Restraints
- Aluminum Heat Sink Cost Volatility:Extruded aluminum pricing fluctuations directly compress margin structures for mid-tier fixture assemblers lacking long-term supply contracts.
- Driver Component Concentration:Taiwan and China-based power supply manufacturers control critical semiconductor inventory for dimmable drivers, creating single-source vulnerability during capacity constraints.
- Halogen Substitute Persistence:Low-cost GU10 retrofit lamps retain installed base in rental housing and hospitality renovation projects where capital budgets prioritize first-cost minimization over lifecycle efficiency.
Strategic Opportunities
- IRA Tax Credit Capture:The Inflation Reduction Act's commercial building energy efficiency incentives create reimbursement pathways for LED retrofits in federally supported housing and municipal facilities.
- Circadian Lighting Integration:Tunable-white downlights paired with human-centric control protocols are penetrating senior living and healthcare verticals where wellness certification drives specification.
- Direct Contractor Channel Development:Bypassing traditional electrical distribution through integrated procurement platforms allows manufacturers to capture installation-margin value and capture specification data earlier in project timelines.
Industry Challenges
- Controls Integration Complexity:BACnet and DALI protocol interoperability gaps between fixture OEMs and building automation vendors extend commissioning timelines and increase callback rates for commercial installations.
- LM-80 Testing Backlog:Third-party lumen maintenance certification queues at NVLAP-accredited laboratories are delaying product launch schedules for new LED module introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US LED Downlight Market |
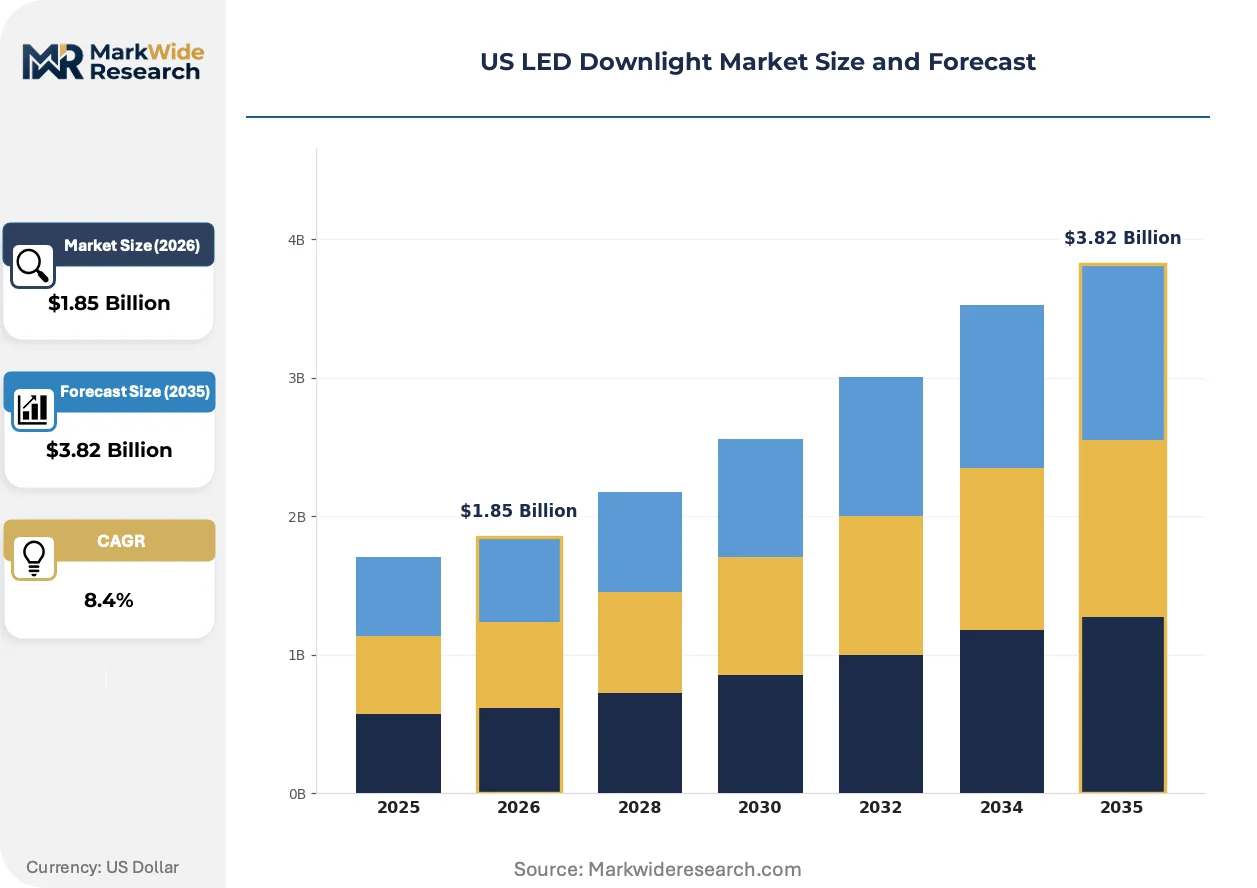
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recessed, Surface-Mount, Adjustable, Wall Wash Application: Residential, Commercial, Retail, Hospitality Technology: Smart Lighting, RGB, Dimmable, Standard End User: Contractors, Distributors, Homeowners, Architects |
| Companies Covered | Acuity Brands Inc., General Electric Company, Cree Lighting, Signify Holding, Eaton Corporation, Hubbell Incorporated, Bridgelux Inc., OSRAM Licht AG, Everlight Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US LED Downlight Market Strategic Shifts & Innovations
Smart lighting platforms are rewiring competitive boundaries as software-enabled control layers displace hardware-centric differentiation, while thermal engineering and optical precision remain the residual manufacturing moats.
Sensor-embedded downlight modules are digitizing ceiling infrastructure by integrating occupancy detection, daylight harvesting, and air quality monitoring into unified fixture assemblies. Hospitality and corporate office specifiers are adopting these converged platforms at accelerated specification rates. The technology is digitizing what had been purely illumination hardware into distributed building data nodes, compressing the addressable market for standalone sensor vendors.
DOE appliance efficiency standards are ratcheting minimum efficacy thresholds upward while mandating standby power limits for connected fixtures. Manufacturers must redesign driver topologies and optical systems to maintain lumen output within constrained wattage budgets. The commercial new construction segment bears the heaviest compliance burden, with specification teams prioritizing products pre-certified to anticipated 2027 rulemakings.
Electrical contractors are consolidating procurement authority through regional buying cooperatives that aggregate project volume for preferential pricing and dedicated inventory pools. Traditional two-step distribution is losing specification influence as these contractor-led entities negotiate directly with fixture manufacturers. The Sun Belt corridor exhibits the most pronounced channel restructuring, where high construction velocity supports cooperative scale formation.
US LED Downlight Market Segmentation
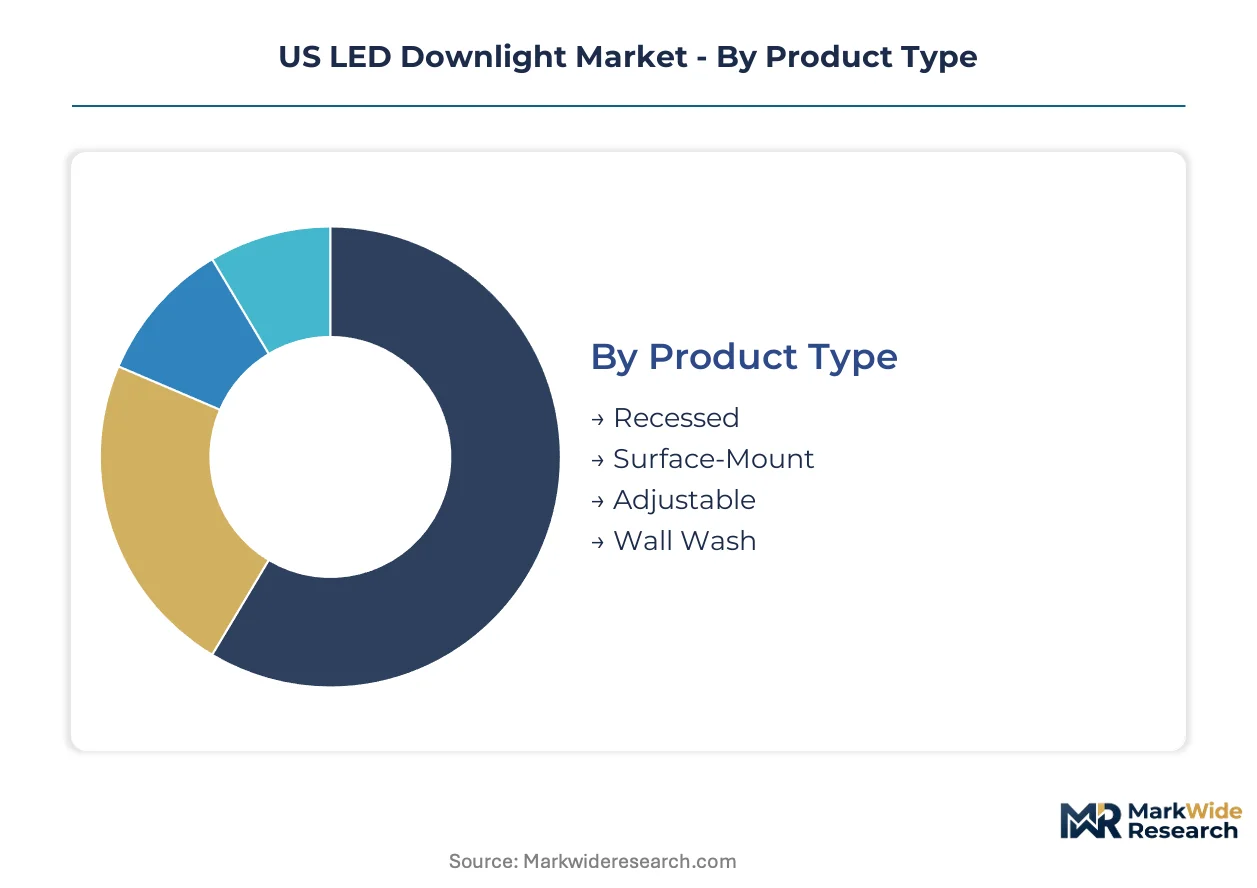
LED downlight segmentation tracks how fixture form factors, control sophistication, and procurement pathways align with distinct project economics. Each dimension carries different margin structures and specification authority, requiring targeted product development and channel strategies.
Product Type:
Cost tier differentiation separates architectural-grade fixtures from commodity replacements, with installation labor and ceiling assembly compatibility driving specification trade-offs.
- Recessed:Ceiling-integrated housings with IC-rated enclosures for direct contact with insulation dominate new residential and commercial construction. Demand concentrates in Texas and Florida where high-velocity building permits outpace national averages, though shallow plenum depths in older structures constrain retrofit adoption.
- Surface-Mount:Low-profile disk fixtures attach directly to junction boxes without housing depth, enabling rapid retrofit in concrete ceiling assemblies and basement applications. The segment gains share fastest in multifamily renovation where minimizing tenant disruption outweighs aesthetic preferences for concealed sources.
- Adjustable:Gimbal or eyeball mechanisms allow post-installation beam direction modification for accent illumination. Common in gallery and museum verticals.
- Wall Wash:Asymmetric optical distributions graze vertical surfaces with uniform illumination. Specified in retail and hospitality for merchandise and artwork emphasis.
Recessed fixtures command the established base. The steepest expansion runs through surface-mount platforms.
Application:
End-use environments impose divergent performance requirements around color quality, control granularity, and operating hour durability.
- Residential:Single-family and multifamily installations prioritize 2700K-3000K warm white temperatures with basic dimming compatibility. Demand clusters in Sun Belt states where cooling-load reduction from efficient lighting supports utility rebate qualification and homeowner payback calculations.
- Commercial:Office and institutional specifications mandate networked control readiness under California Title 24 and equivalent stretch codes. The segment climbs fastest as DOE efficiency standards compress replacement cycles and building automation integration becomes a compliance prerequisite.
- Retail:Merchandise presentation drives high-CRI requirements and tunable-white capability for seasonal color temperature adjustment.
- Hospitality:Guest experience differentiation rewards dimmable and circadian-capable configurations in guest rooms and common areas.
Commercial applications anchor specification-grade volume. Residential retrofits deliver the fastest volume acceleration.
Technology:
Control layer sophistication determines fixture bill-of-materials cost and software recurring revenue potential.
- Smart Lighting:Networked fixtures with embedded sensors and API-accessible control platforms enable occupancy-based dimming, daylight harvesting, and building management system integration. Demand concentrates in commercial new construction where code mandates for networked controls pull specification toward smart-ready platforms.
- Dimmable:Phase-cut or 0-10V driver compatibility supports manual or automated intensity adjustment without full networking infrastructure. The segment retains the broadest addressable market across residential and commercial replacement cycles.
- RGB:Multi-channel LED engines enable saturated color or tunable-white output for experiential and entertainment environments.
- Standard:Fixed-output fixtures without dimming or connectivity capabilities serve cost-minimized replacement and basic new construction.
Dimmable technology holds the installed base majority. Smart lighting platforms capture the steepest specification trajectory.
End User:
Procurement authority shapes pricing transparency, specification influence, and post-sale service attachment rates.
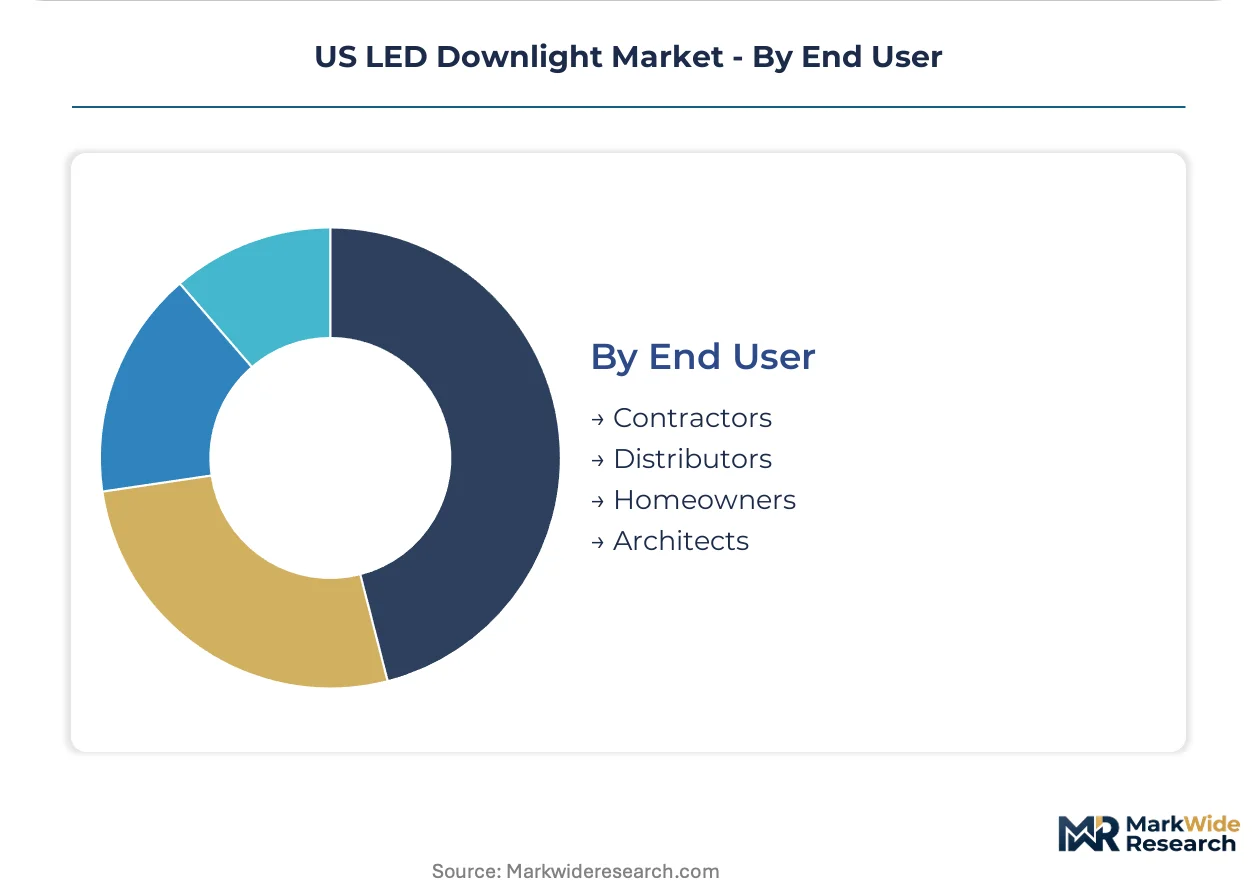
- Contractors:Electrical installation firms aggregate project volume through regional buying cooperatives, negotiating direct manufacturer relationships that bypass traditional distribution markups. The Sun Belt corridor exhibits the most pronounced cooperative formation where construction velocity supports scale aggregation.
- Architects:Design professionals specify fixture performance characteristics and aesthetic integration early in project timelines, creating capture opportunities for manufacturers with agent representation and specification tools. The segment concentrates influence in commercial and hospitality verticals.
- Distributors:Traditional two-step electrical supply houses maintain inventory and credit extension for smaller contractors without cooperative affiliation.
- Homeowners:Direct retail and e-commerce procurement for residential retrofit favors standardized SKUs with installation simplicity.
Contractor cooperatives are consolidating procurement authority fastest. Architect specifications retain the highest margin capture potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across US regions. Sun Belt homeowners prioritize payback periods and utility rebates, while Northeast commercial buyers emphasize specification-grade performance and code compliance regardless of first cost.
Texas
Residential retrofit volume leads national replacement rates as homeowners target cooling-load reduction ahead of summer peaks. Municipal utility rebate programs in Houston and Dallas accelerate fixture turnover. The Dallas-Fort Worth metroplex concentrates contractor cooperative formation where electrical firms aggregate volume for direct manufacturer negotiations.
California
Title 24 stretch codes mandate networked control readiness in new construction, pulling specification-grade demand toward smart-ready platforms. The California Energy Commission enforces standby power limits for connected fixtures. Los Angeles and San Francisco Bay Area construction markets exhibit the densest architect-specified commercial project pipelines.
Florida
Humidity-resistant housing designs command premium positioning in coastal renovation markets. State energy office programs coordinate utility rebate stacking for efficiency upgrades. Miami-Dade and Tampa-St. Petersburg corridors drive fastest multifamily surface-mount retrofit adoption where minimizing tenant disruption shapes procurement decisions.
New York Metro
Deep ceiling plenums in legacy commercial stock constrain recessed fixture compatibility, favoring shallow-profile architectural-grade alternatives. Local Law 97 carbon emission limits tighten building efficiency requirements. Manhattan and Brooklyn commercial renovation markets concentrate specification influence among design professionals with early-project capture authority.
Illinois
Industrial-to-commercial adaptive reuse projects generate specification demand for adjustable and wall-wash configurations. Commonwealth Edison utility incentive programs support LED retrofit in municipal and institutional facilities. Chicago metropolitan area distributors maintain inventory depth for contractor cooperative fulfillment.
US LED Downlight Market Key Industry Players
Capability concentration sits with specification-grade specialists; scale advantage sits with diversified electrical equipment conglomerates. The vendor base organizes around three tiers: captive LED chip producers with thermal engineering depth, full-line lighting manufacturers with distribution breadth, and component-focused suppliers with cost-optimized assembly. Consolidation pressure runs through M&A activity targeting smart lighting software assets and regional distributor acquisitions.
Among diversified industrial conglomerates, General Electric Company and Eaton Corporation occupy positions spanning electrical infrastructure into fixture specification. Acuity Brands Inc. exemplifies the specification-grade specialist archetype with agent-network-dependent commercial project capture. These three anchors represent distinct competitive vectors: conglomerate scale, component integration, and channel-specific specification authority.
| Leading Market Players |
|---|
| Acuity Brands Inc. |
| General Electric Company |
| Cree Lighting |
| Signify Holding |
| Eaton Corporation |
| Hubbell Incorporated |
| Bridgelux Inc. |
| OSRAM Licht AG |
| Everlight Electronics |
| Others |
Cost & Logistics Intelligence
Taiwanese semiconductor foundries and Shenzhen driver assembly clusters dictate downstream pricing power through captive control over dimmable driver ICs and thermal substrate components. Fixture OEMs face margin compression when these hubs throttle capacity, while aluminum extrusion pricing from Guangdong smelters feeds directly into heat sink cost structures.
Pricing Analysis
Commissioning and remote diagnostics service tiers drive lifetime value capture as contractors migrate toward recurring revenue models. Three-tier pricing structure across specification-grade, mid-tier, and commodity replacement levels separates Acuity Brands agent-network premiums from import-dependent economy positioning. Pricing pressure stems from contractor cooperative volume aggregation in Texas and Florida, where aggregated procurement erodes distributor markups. Residential retrofit buyers exhibit highest price sensitivity, while architect-specified commercial projects prioritize Title 24 compliance over first cost.
Supply Chain Analysis
Epoxy resin substrates and flip-chip LED packages from Taiwan, ceramic thermal bonding materials from Japan, and extruded aluminum heat sinks from China anchor upstream feedstock flows. Driver semiconductors draw from TSMC wafer capacity and ON Semiconductor packaging operations, creating single-source vulnerability during foundry allocation cycles. Tariff exposure on Chinese aluminum extrusions and Taiwanese semiconductor components threatens margin stability for mid-tier assemblers lacking long-term supply contracts. Distribution runs through contractor-led buying cooperatives that bypass traditional electrical supply houses in high-velocity Sun Belt construction markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where DOE efficacy standards and California Title 24 mandates create regulatory entrenchment that elevates switching costs for specification-grade incumbents.
For Market Incumbents: Pre-empt halogen substitute persistence in rental housing by embedding tunable-white capability into mid-tier SKUs before commodity competitors achieve thermal management parity. Capture specification data earlier through direct contractor platform integration, neutralizing the threat of cooperative-led procurement disintermediation. Prioritize captive LED chip production to defend margin position against aluminum cost volatility and driver component concentration.
For New Entrants and Emerging Players: Pursue surface-mount retrofit penetration in Florida multifamily renovation, where humidity-resistant housing designs command premium positioning and incumbent coverage remains thin. Target senior living circadian lighting integration as the most penetrable healthcare vertical, where wellness certification protocols favor specialized tunable-white configurations over generalist commercial offerings. Deploy integrated procurement platforms to capture installation-margin value and bypass established distribution tiers.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because DOE efficiency standards and stretch code mandates continuously elevate compliance barriers that favor incumbents with certification infrastructure and thermal engineering depth. Acquisition targets should emphasize smart lighting software assets with BACnet and DALI protocol interoperability, as controls integration complexity extends commissioning timelines and creates sticky customer relationships. Monitor LM-80 testing backlog duration at NVLAP-accredited laboratories as the signal for new LED module introduction velocity and competitive refresh cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Lighting Platform Integration | Signify's Interact platform demonstrates software recurring revenue capture extending into building management systems. |
| Thermal Management Specialization | Cree Lighting's captive LED chip production anchors competitiveness through in-house substrate bonding and heat sink design. |
| Contractor Cooperative Partnership | Acuity Brands leverages agent network density to sustain specification-grade positioning against cooperative procurement consolidation. |
| Circadian Lighting Certification | Tunable-white downlights paired with human-centric protocols penetrate senior living verticals where wellness certification drives specification. |
| Direct Channel Development | Bypassing electrical distribution through integrated procurement platforms captures installation-margin value and specification data capture. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with electrical contractors, lighting specification agents, distributor procurement managers, and DOE regulatory affairs specialists; and secondary validation against EPA ENERGY STAR certification databases, California Energy Commission Title 24 compliance filings, utility rebate program records, and SEC 10-K disclosures from publicly traded lighting manufacturers. Bottom-up fixture shipment aggregation and top-down construction spending allocation were cross-referenced for triangulation.
Forecast inputs considered product type segmentation across recessed, surface-mount, adjustable, and wall-wash configurations; application splits between residential, commercial, retail, and hospitality end-uses; and technology tiers spanning standard, dimmable, RGB, and smart lighting platforms. CAGRs were derived from regression analysis against housing permit velocity, utility incentive program funding levels, and DOE rulemaking timelines across the projection horizon. Industry-specific inputs included thermal efficacy improvement curves and networked control mandate adoption rates.
Sensitivities concentrate around aluminum commodity pricing volatility, Taiwanese foundry capacity allocation for driver semiconductors, and federal Buy America provision expansion for federally funded infrastructure projects. Forecasts reflect documented assumptions regarding efficacy standard implementation schedules and stretch code adoption patterns. Cross-checking against DOE Buildings Energy Data Book and AIA construction billing indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Programmable LED Drivers Market
LED
Africa LED and OLED Displays and Lighting Products Market
LED
UK Indoor LED Lighting Market
LED
Saudi Arabia LED Lights Market
LED
7 Segment LED Displays Market
LED
Light Emitting Diode (LED) Backlight Display Market
LED
Mini LED Display Market
LED
Smart LED Indoor Signage Market
LED
UV LED Market
LED
Philippines LED Market
LED
Asia Pacific Indoor LED Lighting Market
LED
LED Tube Market
LED
Asia Pacific Outdoor LED Lighting Market
LED
South America LED Lighting Market
LED
LED Lighting Controllers Market
LED
Japan LED Lighting Market