
 US Outdoor LED Lighting Market | 2026-2036
US Outdoor LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
US Outdoor LED Lighting Market Insights
The capital-intensity divergence between vertically integrated chip manufacturers and assembly-focused fixture brands is redrawing competitive boundaries in US outdoor illumination. Signify leverages its in-house LED component production to sustain margin compression across municipal tenders. Eaton anchors its position through integrated electrical infrastructure bundling, while Acuity Brands competes via specification-grade architectural positioning in commercial districts.
US Outdoor LED Lighting comprises solid-state luminaires engineered with efficacy ratings exceeding 130 lumens per watt, typically housed in die-cast aluminum or polycarbonate enclosures rated for IP65 or higher ingress protection, designed to replace legacy high-pressure sodium and metal halide installations in exterior environments. Street lights and area lights together constitute the dominant volume segments, with street lights capturing the bulk of municipal capital expenditure and area lights yielding stronger margins in private commercial deployments. Smart lighting technology within the technology dimension is expanding fastest as utilities and cities prioritize networked controls for demand response and outage management.
The Department of Energy's efficacy standards and the EPA's energy performance benchmarks for federal procurement shape minimum product specifications, while local utility rebate programs administered under state public utility commission frameworks directly influence payback calculations for end users. Municipal buyers must weigh stranded asset risk in non-connected fixtures against the operational flexibility that smart-ready architectures provide as grid-interactive capabilities mature.
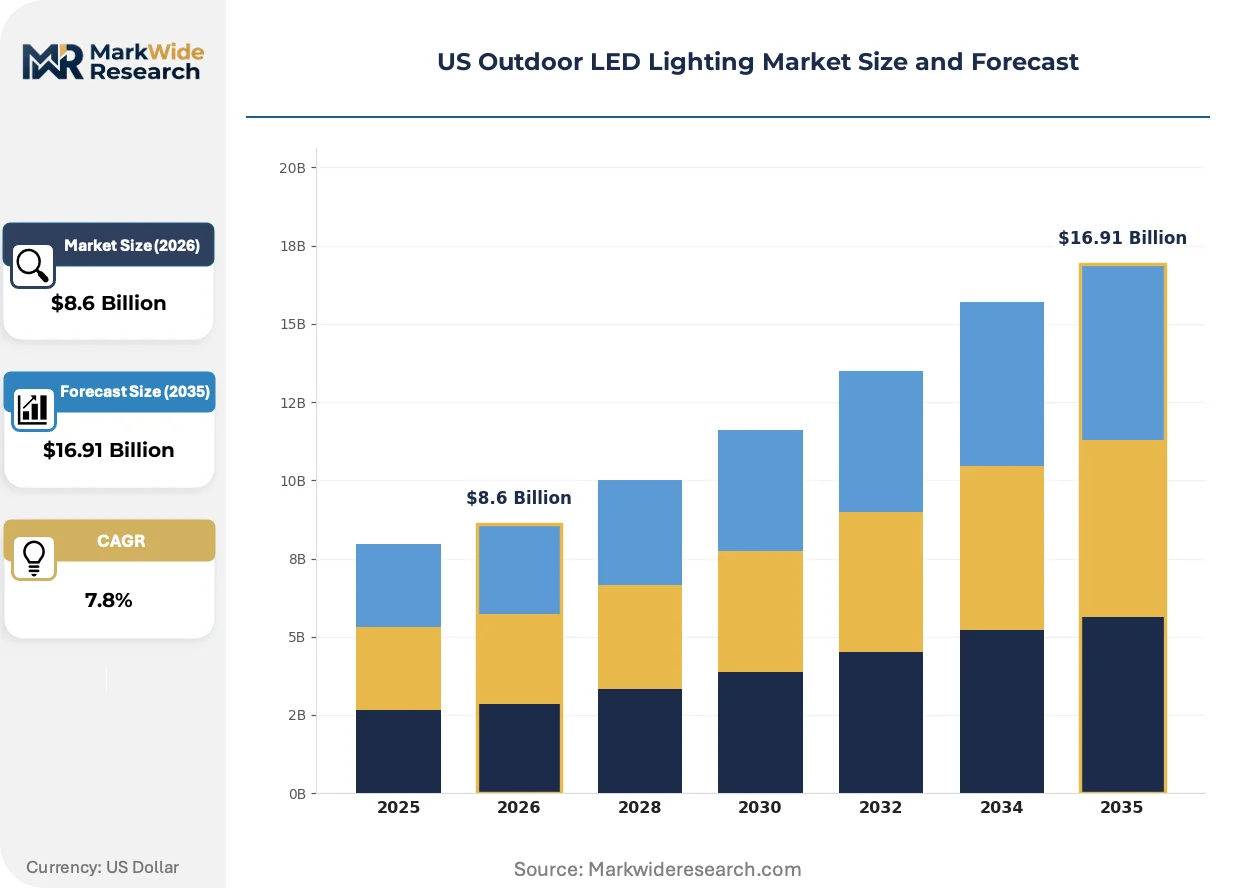
Market Dynamics
The Department of Energy's efficacy mandates are compressing replacement cycles for legacy high-pressure sodium fixtures while networked smart controls rewrite municipal procurement specifications across state and local jurisdictions.
Growth Catalysts
- Utility Rebate Programs:State public utility commission frameworks in California and Texas offset upfront capital costs for highway and parking lot retrofits, accelerating fixture replacement velocity.
- Federal Efficiency Mandates:The Department of Energy's minimum efficacy standards eliminate non-compliant legacy inventory from federal procurement pools, forcing technology upgrades.
- Smart Grid Convergence:Grid-interactive capabilities embedded in street light architectures enable demand response participation and outage management for municipal utilities.
Market Restraints
- Aluminum Die-Cast Input Volatility:Raw material price swings for enclosure-grade aluminum compress margin buffers for assembly-focused fixture brands lacking captive metal supply.
- Chip Supply Concentration:Dominance of Asian substrate manufacturers creates procurement risk for US fixture assemblers without backward integration into LED component production.
- Interoperability Friction:Fragmented communication protocols between smart control vendors strand municipal buyers in single-supplier dependencies.
Strategic Opportunities
- Texas Municipal Expansion:Unconnected rural county infrastructure outside major metro retrofits presents greenfield smart-ready deployment potential.
- Dark Sky Certification Tailwinds:International Dark-Sky Association standards create specification-grade positioning for shielded architectural area lights in commercial districts.
- LiDAR Convergence:Integrated sensor fusion between illumination fixtures and traffic monitoring systems opens new revenue streams for highway corridor deployments.
Industry Challenges
- Network Security Certification:Municipal cybersecurity insurance requirements are extending compliance timelines for connected fixture deployments beyond traditional procurement windows.
- Legacy Electrical Infrastructure Integration:Aging underground conduit systems in northeastern cities complicate smart control retrofitting and drive unplanned engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Outdoor LED Lighting Market |
| Market Size in 2026 | $8.6 Billion |
| Market Size in 2035 | $16.91 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Street Lights, Flood Lights, Area Lights, Garden Lights Application: Parks, Highways, Parking Lots, Commercial Areas Technology: Smart Lighting, Solar Lighting, Motion Sensor, Dimmable End User: Municipalities, Commercial Establishments, Institutions, Homeowners |
| Companies Covered | Acuity Brands, Signify, Eaton, Hubbell, Cree Lighting, Dialight, Current Lighting Solutions, Panasonic Holdings Corporation, LSI Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Outdoor LED Lighting Market Trends and Innovations
Connected lighting architectures are rewriting competitive boundaries as hardware margins compress and software-enabled service layers capture expanding value pools in municipal infrastructure.
Tunable white LED systems are fragmenting the traditional street light specification landscape. These color-temperature-adjustable fixtures enable circadian-friendly urban lighting schemes. Municipal buyers in Arizona and Florida are piloting adaptive melanopic output for residential corridor safety. The technology is fragmenting vendor positioning between commodity efficacy providers and specification-grade wellness lighting specialists.
The EPA's energy performance benchmarks for federal procurement are tightening minimum product specifications annually. Manufacturers must now document embodied carbon and end-of-life recyclability to maintain contract eligibility. Federal facility managers are consolidating vendor pools around full-lifecycle compliance, compressing supplier counts in GSA schedules.
Performance contracting is displacing capital purchase models for large-scale municipal retrofits. Energy service companies assume upfront installation risk and recover returns through guaranteed savings streams. This shift concentrates buyer relationships around financing capability rather than fixture specification alone, favoring electrical infrastructure conglomerates with captive project finance arms.
US Outdoor LED Lighting Market Segmentation
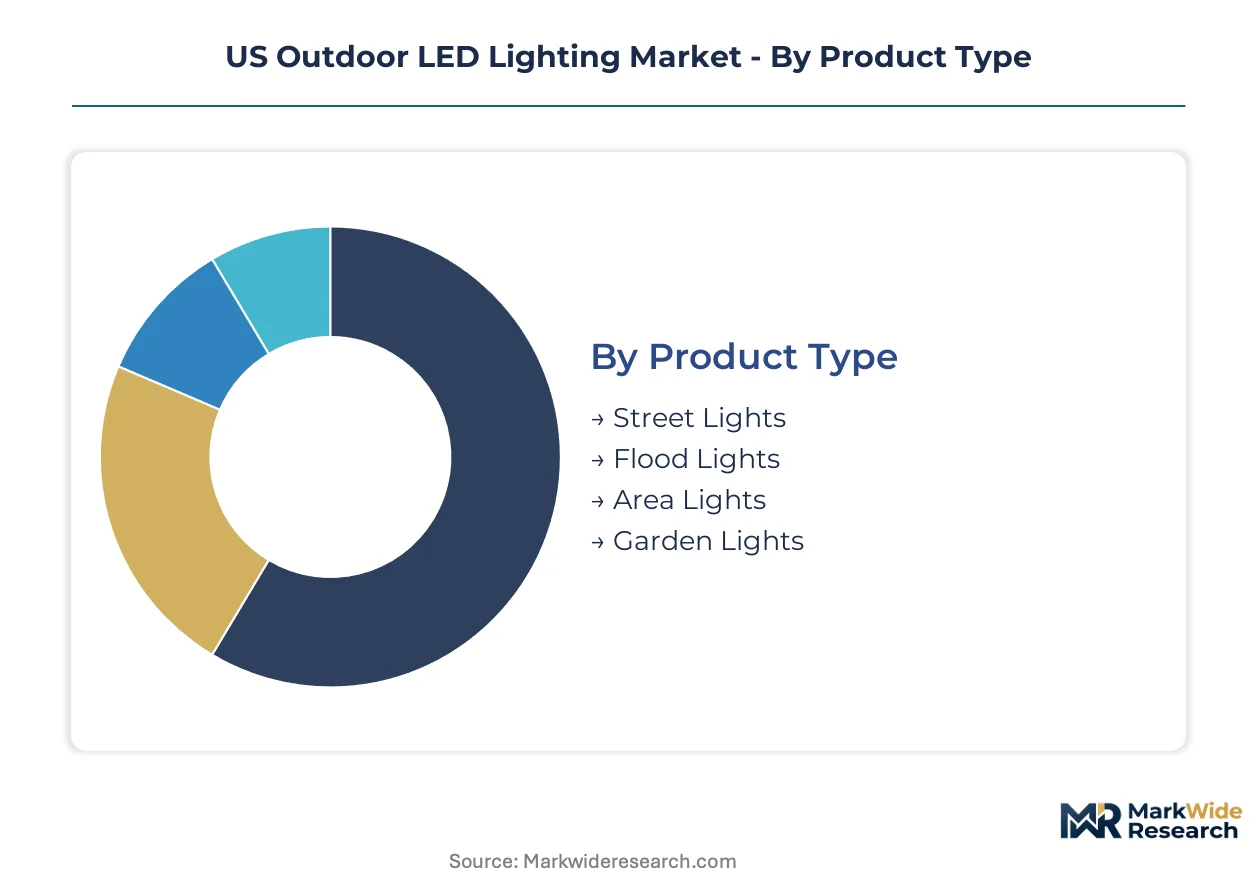
Segmentation reveals how procurement patterns diverge across institutional buyers versus private deployers in US outdoor LED illumination. Municipal capital cycles, utility rebate eligibility, and smart grid readiness create distinct demand profiles that reshape vendor positioning across each dimension.
Product Type:
Street lights and area lights anchor domestic manufacturing capacity, while flood lights and garden lights draw heavier import dependence from Asian assembly operations.
- Street Lights:Die-cast aluminum luminaires rated for IP66 ingress protection and efficacy exceeding 150 lumens per watt, designed for pole-mounted roadway illumination. California and Texas municipal retrofit programs concentrate demand where utility rebates offset capital outlays for high-volume highway corridor deployments.
- Area Lights:Shoebox-style fixtures engineered for parking lot and commercial perimeter applications, typically housing modular LED arrays with 10-year lumen maintenance guarantees. Private commercial buyers in Texas and Florida drive specification-grade procurement where Dark Sky certification commands premium positioning.
- Flood Lights:High-output directional luminaires for building facade and security perimeter illumination.
- Garden Lights:Low-wattage decorative bollards and pathway fixtures for residential landscape integration.
Street lights command the established base. The steepest expansion runs through area lights.
Application:
Highway and parking lot deployments concentrate where state public utility commission frameworks administer the most generous rebate schedules, while parks and commercial districts follow separate capital planning cycles.
- Highways:High-mast and cobra-head fixtures engineered for photometric uniformity across multi-lane corridors, with crash-rated breakaway poles meeting FHWA standards. Texas Department of Transportation county-level retrofit initiatives concentrate demand where unconnected rural infrastructure presents greenfield smart-ready deployment potential.
- Parking Lots:Pole-mounted area lights with occupancy-based dimming controls and networked photocell integration. Commercial property owners in California leverage utility demand response programs to recover upfront fixture costs through operational savings streams.
- Parks:Pedestrian-scale pathway luminaires with wildlife-friendly amber spectral output for ecological sensitivity zones.
- Commercial Areas:Architectural facade and pedestrian street lighting where municipal design guidelines enforce aesthetic coordination.
Highway installations represent the largest addressable volume. Parking lot retrofits are climbing the fastest as private capital accelerates behind performance contracting structures.
Technology:
Smart lighting architectures concentrate development investment among domestic controls specialists, while solar and motion technologies draw component sourcing from overseas module manufacturers.
- Smart Lighting:Networked luminaires with embedded wireless communication enabling remote dimming, outage detection, and grid-interactive demand response. Municipal utilities in California prioritize these capabilities for outage management and peak load reduction, though fragmented communication protocols create single-supplier dependencies.
- Motion Sensor:Passive infrared and microwave detection modules integrated into fixture housings for occupancy-based illumination reduction. Parking lot operators in Texas deploy these for after-hours energy savings where utility rate structures penalize baseline demand.
- Solar Lighting:Off-grid photovoltaic-powered luminaires with battery storage for remote or trenching-prohibited sites.
- Dimmable:Phase-cut and 0-10V control compatibility for basic output adjustment without networked infrastructure.
Smart lighting is gaining share fastest among technology categories. Dimmable fixtures retain the broadest installed base.
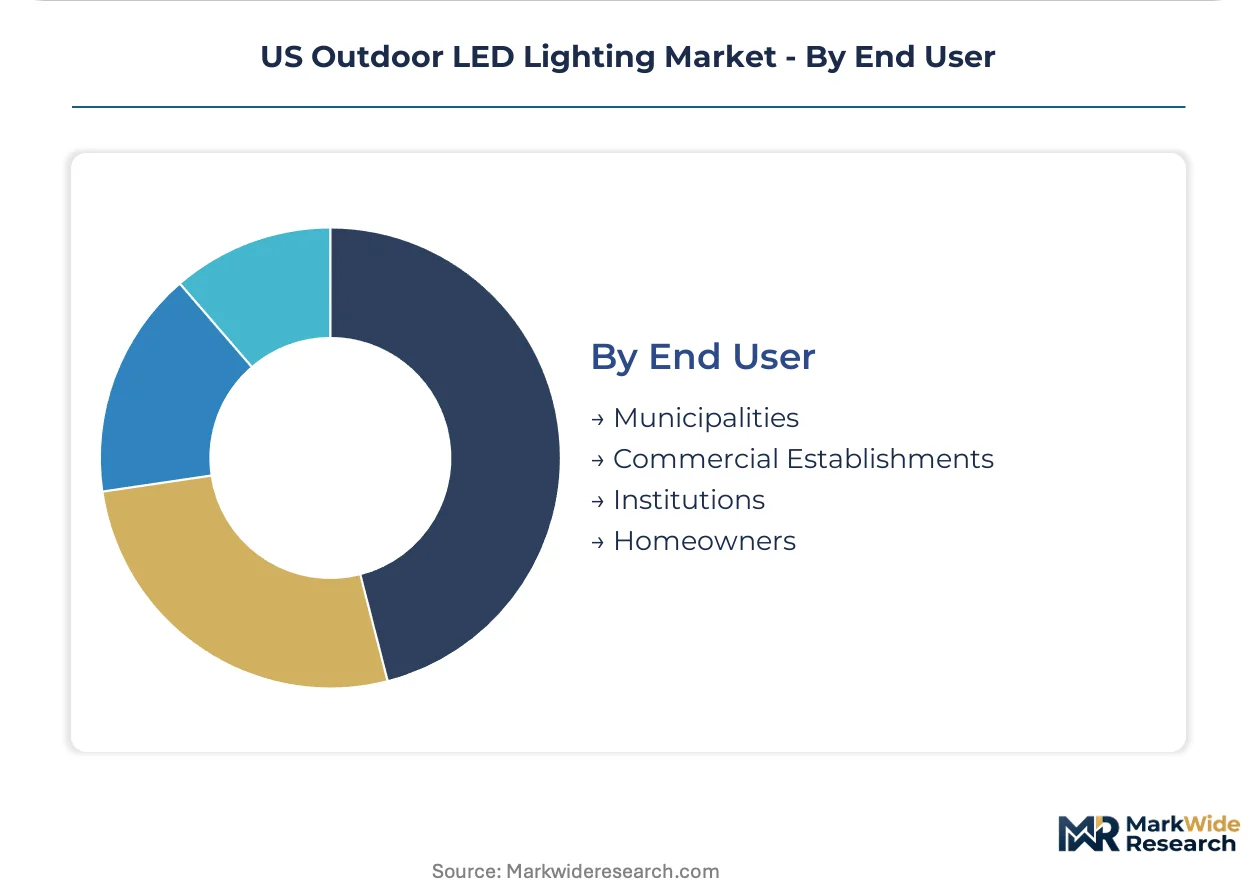
End User:
Municipal procurement dominates volume through formal tender processes, while commercial establishments and institutions operate through more fragmented specification channels.
- Municipalities:City and county agencies procuring through competitive bidding for street light and park illumination networks. California and Texas jurisdictions lead capital deployment where Department of Energy efficacy mandates eliminate non-compliant legacy inventory from federal procurement pools.
- Commercial Establishments:Retail property managers, logistics facilities, and hospitality operators specifying area lights and flood lights through electrical contractor relationships. These buyers concentrate in Sun Belt metros where utility rebate programs accelerate replacement velocity.
- Institutions:University campuses, hospital systems, and federal facilities with sustainability mandates and GSA schedule purchasing authority.
- Homeowners:Residential consumers purchasing garden lights and security flood lights through retail and e-commerce channels.
Municipalities command the established base. Commercial establishments are expanding most quickly as performance contracting displaces capital purchase models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California and Texas municipalities deploy smart-ready architectures at scale while Florida and Arizona buyers prioritize circadian-friendly spectral output for residential corridors, creating divergent procurement patterns across state jurisdictions.
California
Utility rebate programs administered by the California Public Utilities Commission accelerate highway corridor retrofits in Los Angeles and San Diego metros. The state's Title 24 building standards mandate networked lighting controls for new commercial construction. Silicon Valley technology campuses drive specification-grade architectural area light procurement with Dark Sky certification requirements.
Texas
Unconnected rural county infrastructure outside Dallas-Fort Worth and Houston presents greenfield smart-ready deployment potential for Department of Transportation initiatives. The Public Utility Commission of Texas oversees demand response rebate frameworks that offset capital costs for parking lot operators. Austin's municipal sustainability office pilots tunable white systems for circadian-friendly street lighting.
Florida
Commercial property managers in Miami and Tampa leverage utility rebate programs for hurricane-rated fixture retrofits with occupancy-based dimming. The Florida Public Service Commission administers efficiency incentive pools for institutional buyers. Orlando's entertainment district drives architectural facade lighting procurement with IP66 ingress protection specifications.
Arizona
Municipal buyers in Phoenix and Tucson pilot adaptive melanopic output systems for residential corridor safety under state energy office guidelines. The Arizona Corporation Commission regulates utility demand response programs that accelerate smart lighting adoption. Flagstaff's dark sky preservation ordinances create premium positioning for fully shielded area light specifications.
New York
Aging underground conduit systems in New York City complicate smart control retrofitting and drive unplanned engineering costs for municipal utilities. The New York State Energy Research and Development Authority administers rebate frameworks for institutional retrofits. Buffalo's waterfront redevelopment anchors specification-grade architectural lighting procurement with federal infrastructure funding.
US Outdoor LED Lighting Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in US outdoor LED lighting, with Signify and Eaton commanding municipal infrastructure relationships through captive component supply and electrical system bundling respectively. Assembly-focused fixture brands compete on specification-grade positioning in commercial districts where architectural compliance commands premium pricing. Two strategic archetypes dominate: vertically integrated conglomerates with in-house LED chip production, and design-focused specialists leveraging Dark Sky certification for commercial perimeter applications. Competitive moves concentrate on strategic partnerships for smart control interoperability and portfolio diversification into sensor-integrated highway corridor systems.
Among US-based electrical infrastructure conglomerates, Signify, Eaton, and Acuity Brands exemplify contrasting competitive positions. Signify represents the integrated archetype through captive LED component production that sustains margin compression across municipal tenders. Eaton anchors infrastructure bundling relationships where integrated electrical system procurement reduces buyer transaction costs. Acuity Brands occupies specification-grade positioning in commercial districts where architectural coordination requirements filter commodity competitors.
| Leading Market Players |
|---|
| Acuity Brands |
| Signify |
| Eaton |
| Hubbell |
| Cree Lighting |
| Dialight |
| Current Lighting Solutions |
| Panasonic Holdings Corporation |
| LSI Industries |
| Others |
Pricing and Supply Chain Analysis
Department of Energy efficacy mandates gate both supplier qualification and price differentiation simultaneously, compressing margin buffers for assembly-focused brands while rewarding vertically integrated manufacturers with captive LED component production. Municipal procurement pools now stratify around smart-ready architectures and Dark Sky certification tiers, creating non-linear pricing premiums that detach from raw lumen output metrics.
Pricing Analysis
Long-term municipal offtake agreements dominate highway corridor deployments, while spot purchasing persists for private commercial retrofits. Three-tier pricing structure across premium, standard, and economy levels separates specification-grade architectural fixtures with Dark Sky certification from commodity efficacy providers serving volume tenders. Cost compression in the standard tier is intensifying because aluminum die-cast input volatility erodes margin buffers for non-integrated assemblers. Municipal utilities exhibit the highest price sensitivity due to competitive bidding requirements, while institutional buyers with sustainability mandates show relative inelasticity.
Supply Chain Analysis
Taiwan and South Korea anchor LED substrate and chip fabrication, while China dominates die-cast aluminum enclosure manufacturing and polycarbonate lens molding. US fixture assemblers draw from Asian substrate manufacturers for LED components, enclosure-grade aluminum for thermal management housings, and wireless communication modules for smart control integration. Single-source vulnerability concentrates in specialized LED driver integrated circuits, creating procurement risk for brands lacking multi-qualified supplier bases. Distribution runs through electrical contractor channels for municipal and commercial projects, with direct OEM relationships for institutional GSA schedule procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
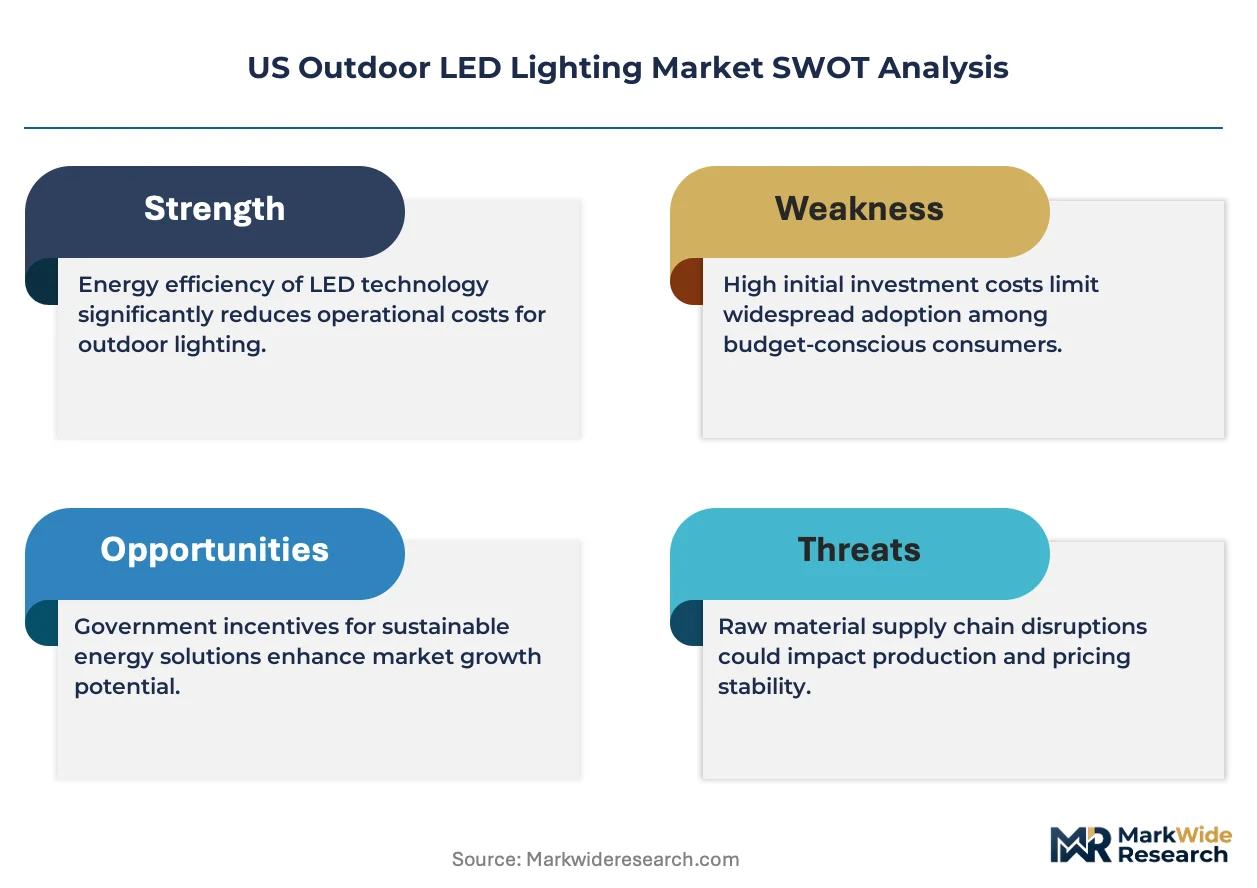
This market sits in early-cycle expansion as unconnected rural county infrastructure in Texas and beyond presents greenfield smart-ready deployment potential that accelerates replacement velocity ahead of traditional capital planning cycles.
For Market Incumbents: Compound infrastructure bundling advantages by integrating electrical system procurement with captive project finance arms, defending against energy service companies that displace capital purchase models. Deepen backward integration into LED component production to sustain margin compression across municipal tenders where efficacy mandates eliminate non-compliant legacy inventory. For New Entrants and Emerging Players: Lead with specification-grade positioning in commercial districts where Dark Sky certification commands premium pricing and architectural compliance filters commodity competitors. Target unconnected rural county infrastructure outside major Texas metros for greenfield smart-ready deployments, penetrating through utility rebate program alignment and demand response capability bundling. For Investors and Strategic Acquirers: Department of Energy efficacy mandate enforcement reshapes the acquisition landscape by compressing supplier counts in federal procurement pools around full-lifecycle compliance capabilities. Long-term viability centers on controls interoperability and sensor-integrated highway corridor systems, with acquisition targets clustering around domestic smart lighting specialists with grid-interactive demand response platforms. Watch municipal cybersecurity insurance requirements as the signal for compliance timeline extensions that concentrate buyer relationships around proven network security certification.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Control Interoperability Partnership | Fragmented communication protocols strand municipal buyers in single-supplier dependencies, creating consolidation pressure. |
| LiDAR Sensor Fusion Integration | Highway corridor deployments with integrated traffic monitoring open new revenue streams beyond illumination hardware. |
| Dark Sky Certification Program | Flagstaff ordinances and Silicon Valley campus requirements create specification-grade positioning for shielded architectural fixtures. |
| Performance Contracting Capability Buildout | Energy service companies assume upfront installation risk, favoring electrical infrastructure conglomerates with captive finance arms. |
| Texas Rural County Expansion | Unconnected infrastructure outside Dallas-Fort Worth presents greenfield smart-ready deployment potential for Department of Transportation initiatives. |
Research Methodology
A spread of perspectives from municipal procurement officers, electrical contractor specification teams, utility demand response program administrators, and LED component manufacturing engineers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against Department of Energy efficacy standard filings, state public utility commission rebate program documentation, and municipal tender databases. Bottom-up fixture shipment analysis triangulated against top-down infrastructure spending forecasts from federal and state transportation authorities.
Segmentation dimensions modeled include product type, application environment, technology architecture, and end-user procurement channel across the projection horizon. CAGRs derived from replacement cycle velocity analysis, utility rebate program expansion trajectories, and smart grid convergence adoption curves. Industry-specific forecast inputs incorporated aluminum die-cast price volatility indices and LED component supply lead time fluctuations.
Forecasts assume regulatory continuity in Department of Energy efficacy mandates and state public utility commission rebate frameworks; material policy shifts would require re-modeling around stranded asset risk in non-connected fixtures. Recalibration cycles align with material shifts in municipal cybersecurity insurance requirements and federal infrastructure funding disbursement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Small Pitch LED Display Market
LED
LED Work Light Market
LED
South America Indoor LED Lighting Market
LED
LED Light Market
LED
France Indoor LED Lighting Market
LED
UK LED Lighting Market
LED
LED Tube Market
LED
Germany Outdoor LED Lighting Market
LED
Light Emitting Diode (LED) Backlight Display Market
LED
LED Display Control Card Market
LED
Dual-Digit 7 Segment LED Displays Market
LED
Mexico LED Lighting Market
LED
Africa LED and OLED Displays and Lighting Products Market
LED
LED Control Unit Market
LED
Outdoor LED Display Market
LED
UK Outdoor LED Lighting Market