
 Semiconductor Clock Market | 2026-2036
Semiconductor Clock Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Clock Market Analytics
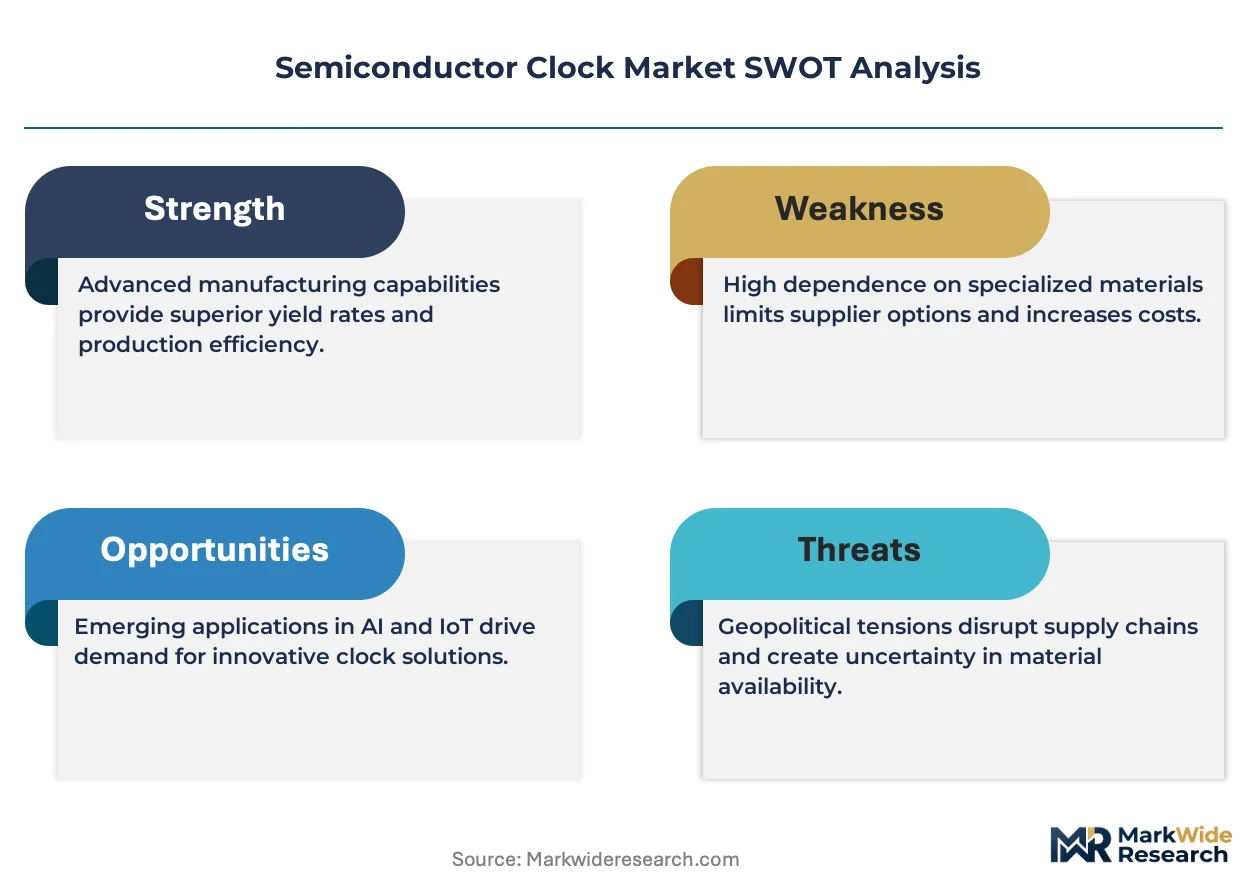
Automotive-grade temperature stability specifications is redrawing competitive boundaries in semiconductor timing. Texas Instruments leverages its integrated manufacturing footprint to sustain supply security for precision oscillators serving advanced driver-assistance systems. SiTime specializes in silicon MEMS-based timing solutions that compete with legacy quartz architectures across 5G infrastructure deployments.
Semiconductor clocks are electronic timing devices that generate stable frequency references through crystal or MEMS resonator oscillation circuits, typically achieving stability measured in parts per million (ppm) over specified temperature ranges. Their primary purpose is synchronizing data transmission, processor execution, and peripheral coordination across electronic systems. CMOS-based timing ICs dominate volume production for consumer electronics, while SiGe technology occupies the fastest-expanding margin pool in telecommunications base stations demanding sub-100 femtosecond jitter performance. Automotive electronics applications anchor the highest specification tiers, with timing oscillators required to withstand vibration profiles and temperature excursions that consumer-grade devices cannot tolerate.
FCC emission rules in the United States, the EU's RoHS and REACH substance restrictions, and China's GB/T electromagnetic compatibility standards collectively shape product certification requirements and market access conditions for clock manufacturers. ECHA's evolving SVHC candidate list forces material composition audits that extend through multi-tier supply chains. Stakeholders must monitor how automotive OEM qualification timelines and foundry capacity allocation for precision timing devices interact to determine available supply and pricing trajectories.
Market Dynamics
Automotive zonal architectures and EU CE marking electromagnetic compatibility mandates are compressing qualification timelines while concentrating precision timing procurement among vertically integrated foundry operators.
Growth Catalysts
- EU CE marking electromagnetic compatibility framework:Stricter emission thresholds are forcing clock precision upgrades across automotive electronics supply chains, expanding specification tiers for timing oscillators.
- 5G infrastructure deployment cycles:Base station densification in East Asian manufacturing clusters is pulling silicon MEMS timing solutions into telecommunications equipment at volume scale.
- Software-defined vehicle platforms:Centralized compute architectures in automotive OEM programs are multiplying clock channel counts per vehicle, escalating absolute demand for automotive-grade temperature-stable oscillators.
Market Restraints
- Quartz crystal supply concentration:Raw material refining and blank manufacturing concentrate in specific East Asian supply nodes, exposing buyers to geographic disruption risk without qualified second sources.
- Automotive qualification timeline friction:AEC-Q100 and AEC-Q200 certification cycles extend 18-24 months, freezing design wins and compressing supplier margins through extended engineering resource allocation.
- MEMS resonator temperature coefficient limitations:Silicon-based timing architectures face fundamental stability constraints against legacy quartz in extreme automotive temperature excursions, limiting substitution velocity.
Strategic Opportunities
- India electronics manufacturing incentives:PLI scheme allocations for semiconductor assembly and test are attracting timing IC packaging investment, creating geographic diversification options beyond East Asian concentration.
- Precision timing for satellite constellations:Low-earth orbit communication networks are emerging as a high-specification demand vertical requiring radiation-hardened clock sources with sub-ppb stability.
- EU Green Deal substance restrictions:REACH SVHC list evolution is accelerating material composition audits, favoring suppliers with established conflict-mineral-free quartz sourcing and transparent supply chain documentation.
Industry Challenges
- Analog-mixed signal design talent scarcity:Precision oscillator architecture expertise concentrates among senior engineers at legacy timing houses, constraining new entrant scaling and inflating compensation benchmarks.
- Multi-tier supply chain audit complexity:ECHA SVHC candidate list expansion forces material traceability through three-to-four tier sub-supplier networks, elevating compliance infrastructure costs disproportionately for mid-scale manufacturers.
- Legacy quartz-integrated system replacement friction:Established telecommunications and automotive platforms embed quartz-based timing subsystems with long depreciation cycles, slowing MEMS substitution despite technical parity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Clock Market |
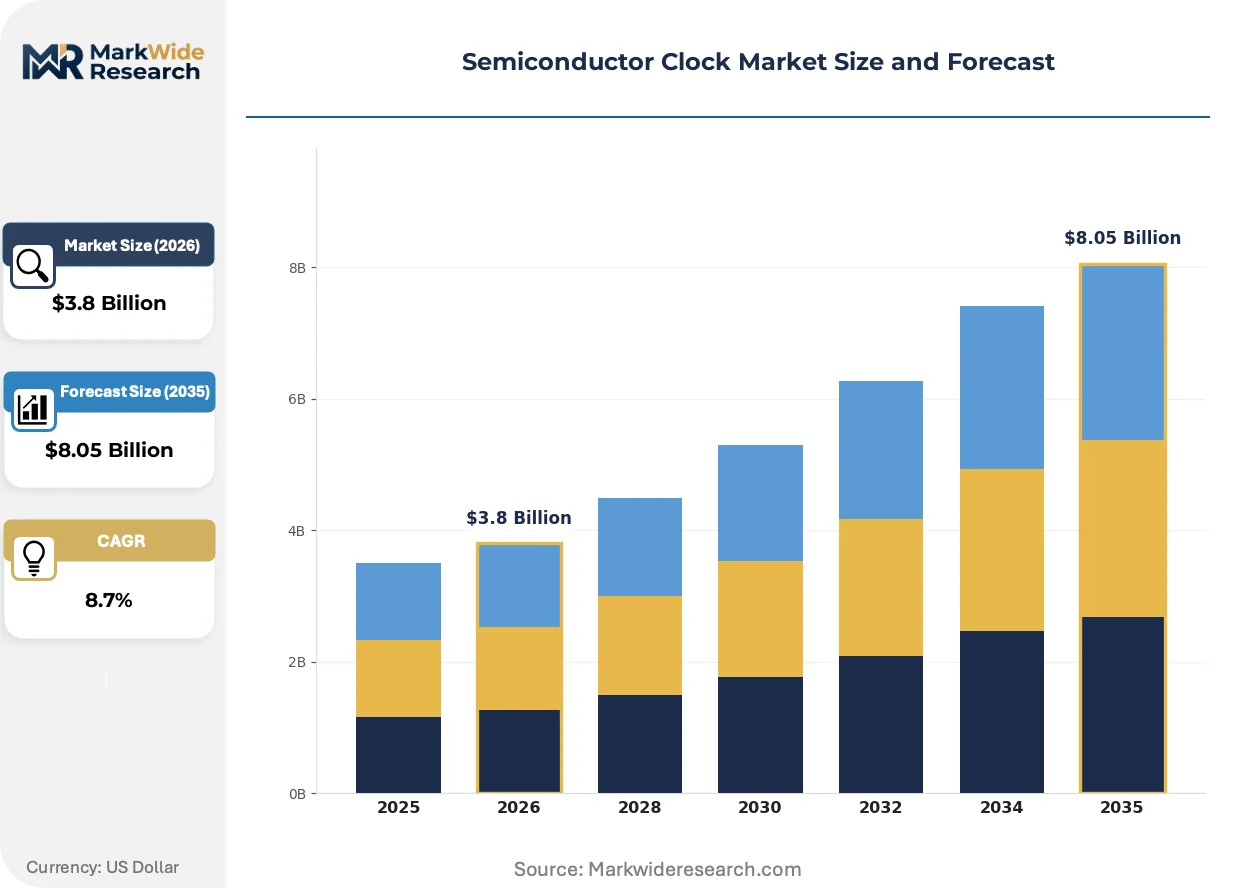
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Clocks, Digital Clocks, Smart Clocks, Timing Oscillators Technology: CMOS, BiCMOS, SiGe, GaAs Application: Consumer Electronics, Automotive Electronics, Telecommunications, Industrial Automation End User: OEMs, Aftermarket Providers, Retailers, Distributors |
| Companies Covered | Seiko Epson Corporation, NXP Semiconductors, STMicroelectronics, Texas Instruments, KYOCERA Corporation, Renesas Electronics Corporation, Microchip Technology, Abracon, SiTime, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Clock Market Evolving Landscape
Silicon MEMS resonator architectures, regulatory substance restrictions, and consolidated procurement models are simultaneously compressing legacy quartz dominance and elevating supply chain transparency requirements.
Silicon MEMS-based timing oscillators leverage semiconductor batch fabrication to achieve cost trajectories impossible with carved quartz blanks. Telecommunications infrastructure OEMs in South Korea and Taiwan are adopting MEMS solutions for 5G macro and small cell deployments where volume economics outweigh absolute stability margins. This fabrication model is displacing quartz crystal supply chains in consumer and industrial timing segments where ppm-grade stability suffices.
EU REACH substance restrictions and ECHA SVHC candidate list expansion are mandating material composition disclosure through multi-tier supply chains. Clock manufacturers must audit resonator coatings, package substrates, and solder materials for restricted substances or face market access denial. Automotive timing suppliers serving German OEM qualification programs are most exposed, accelerating substitution of lead-containing solders and conflict-mineral-sourced quartz.
Automotive electronics OEMs are consolidating precision timing procurement through direct foundry partnerships rather than distributor-mediated sourcing. Tier-1 module suppliers in Detroit and Stuttgart are ceding component selection authority to vehicle platform architects who specify timing architectures at the zonal compute level. This concentration is most visible in battery electric vehicle programs where centralized domain controllers integrate multiple clock domains under single sourcing agreements.
Semiconductor Clock Market Segmentation
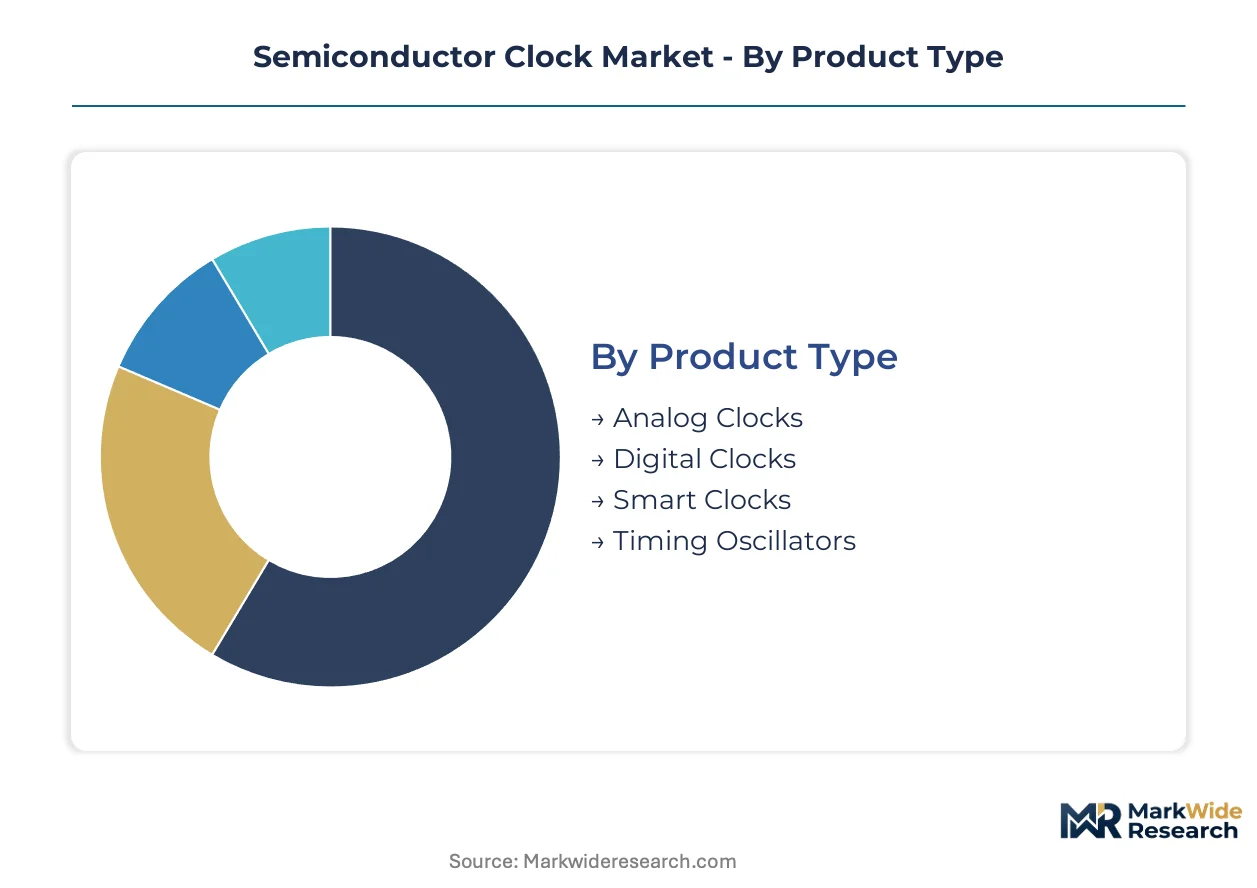
Semiconductor clock segmentation reveals how precision requirements, fabrication economics, and qualification barriers partition margin pools across disparate end-use environments. Understanding these divisions exposes where suppliers can defend pricing power versus where volume commoditization dominates procurement negotiations.
Product Type:
Margin concentration sits with devices serving automotive and telecommunications infrastructure where temperature stability and jitter specifications command qualification premiums.
- Timing Oscillators:Crystal and MEMS-based resonator circuits generate stable frequency references measured in parts-per-million stability across specified temperature ranges. Automotive zonal computing architectures in Germany and Japan are multiplying channel counts per vehicle, concentrating procurement among vertically integrated foundry operators who can guarantee AEC-Q200 qualified supply.
- Smart Clocks:Programmable timing devices integrate frequency synthesis, temperature compensation, and digital control interfaces within single packages. 5G base station densification in South Korea and Taiwan is pulling these solutions into telecommunications equipment where software-defined configurability reduces inventory complexity for network equipment OEMs.
- Digital Clocks:CMOS-based counters and dividers distribute synchronized timing signals across processor subsystems.
- Analog Clocks:Legacy linear oscillator circuits serve cost-sensitive consumer applications where ppm-grade precision exceeds functional requirements.
The dominant share belongs to Timing Oscillators, while Smart Clocks is closing the gap fastest.
Technology:
Process node differentiation separates consumer-grade volume production from telecommunications infrastructure demanding sub-100 femtosecond jitter performance.
- SiGe:Silicon-germanium heterojunction bipolar transistors achieve switching speeds and noise characteristics unattainable in standard CMOS. Telecommunications base station deployments in Taiwan and South Korea specify SiGe timing ICs for optical transport and radio frequency synchronization where phase noise budgets are tightest.
- CMOS:Complementary metal-oxide-semiconductor dominates unit volume through mature fabrication economics and design portability. Consumer electronics manufacturing clusters in China and Vietnam consume CMOS timing devices for smartphones, tablets, and wearables where cost minimization outweighs absolute stability margins.
- BiCMOS:Bipolar-CMOS integration combines analog precision with digital density for mixed-signal timing functions.
- GaAs:Gallium arsenide compound semiconductors serve niche microwave and millimeter-wave applications requiring extreme frequency operation.
CMOS holds the volume base, yet SiGe claims the steepest expansion trajectory as 5G infrastructure buildouts accelerate.
Application:
Specification tiers stratify sharply between consumer electronics tolerating loose stability margins and automotive platforms requiring vibration resistance across temperature extremes.
- Automotive Electronics:Timing devices must withstand vibration profiles and temperature excursions from -40°C to +150°C under AEC-Q100 qualification. Battery electric vehicle programs in Germany, Japan, and the United States are consolidating procurement authority at the zonal compute level, bypassing traditional Tier-1 module suppliers.
- Telecommunications:Base stations, optical transport, and data center switches demand sub-ppb stability with minimal phase noise. Network equipment OEMs in South Korea and Taiwan are adopting silicon MEMS solutions where volume economics outweigh absolute quartz stability margins.
- Consumer Electronics:Smartphones, tablets, and wearables drive unit volume through specification tolerance for wider ppm drift.
- Industrial Automation:Factory control systems and robotics require timing synchronization across distributed sensor networks.
Automotive Electronics commands the premium tier, while Telecommunications is gaining share fastest on infrastructure deployment cycles.
End User:
Procurement authority concentration varies by industry maturity, with automotive OEMs increasingly dictating component selection previously ceded to module suppliers.
- OEMs:Original equipment manufacturers in automotive and telecommunications specify timing architectures at the platform design stage. German and Japanese automotive OEMs now select precision oscillators directly rather than delegating to Tier-1 suppliers, compressing distributor margins and freezing design wins earlier in program timelines.
- Distributors:Arrow, Avnet, and regional specialists maintain inventory buffers for mid-scale manufacturers lacking direct foundry relationships. Industrial automation and legacy telecommunications equipment in the United States and Europe still route substantial procurement through distributor channels where technical support and smaller lot sizes justify markup.
- Aftermarket Providers:Replacement timing components serve repair and refurbishment channels.
- Retailers:Consumer-facing sales of clock modules and development kits address hobbyist and prototyping demand.
OEMs control the specification tier, while Distributors retain leverage in fragmented industrial segments where lot sizes and technical support requirements resist direct sourcing consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision timing IC fabrication concentrates in Taiwan and South Korea, where foundry capacity expansion tracks automotive zonal computing demand. German and Japanese automotive OEMs now source oscillators directly from these clusters, bypassing traditional distribution channels.
United States
Automotive electronics OEMs in Detroit and Austin consolidate procurement authority at the zonal compute level. FCC emission rules shape certification requirements for timing devices entering telecommunications infrastructure. Silicon Valley design houses specialize in MEMS resonator architectures for 5G base station deployments.
Germany
Battery electric vehicle programs in Stuttgart and Munich multiply clock channel counts per vehicle under AEC-Q200 qualification pressure. EU CE marking electromagnetic compatibility mandates force precision upgrades across automotive supply chains. Bavarian automotive clusters source timing oscillators directly from Asian foundries, compressing distributor margins.
China
GB/T electromagnetic compatibility standards enforce clock precision thresholds for domestic automotive electronics. Shenzhen and Shanghai manufacturing clusters consume CMOS timing devices at volume scale for consumer electronics assembly. MIIT industrial policies accelerate domestic MEMS resonator capacity buildout for telecommunications equipment.
South Korea
5G infrastructure densification in Seoul and Suwon pulls silicon MEMS timing solutions into base station equipment. Samsung and SK hynix foundry operations anchor precision timing IC production for export markets. Korean network equipment OEMs specify sub-100 femtosecond jitter performance for optical transport synchronization.
Japan
Automotive timing suppliers in Nagoya and Tokyo face METI pressure to eliminate conflict-mineral-sourced quartz from supply chains. Precision oscillator expertise concentrates among legacy timing houses with decades of analog-mixed signal design heritage. Japanese OEM qualification programs demand vibration resistance across -40°C to +150°C temperature excursions.
Semiconductor Clock Market Competitive Landscape
Concentration sits with vertically integrated semiconductor houses possessing captive foundry capacity and AEC-Q200 qualified manufacturing lines. The vendor base stratifies across three tiers: precision oscillator specialists serving automotive qualification programs, MEMS resonator disruptors attacking telecommunications volume, and diversified analog IC houses leveraging portfolio breadth. Competitive moves center on foundry capacity allocation for automotive-grade temperature stability and direct OEM partnership models that bypass distributor channels.
Among diversified analog semiconductor houses, Texas Instruments and NXP Semiconductors exemplify the integrated manufacturing archetype, while SiTime occupies a distinct position within the MEMS resonator specialization tier. Seiko Epson Corporation and KYOCERA Corporation represent Japanese precision timing heritage, and STMicroelectronics anchors European automotive electronics supply relationships. Renesas Electronics Corporation, Microchip Technology, and Abracon sit within the qualification-heavy automotive timing segment where AEC-Q100 certification cycles freeze design wins.
| Leading Market Players |
|---|
| Seiko Epson Corporation |
| NXP Semiconductors |
| STMicroelectronics |
| Texas Instruments |
| KYOCERA Corporation |
| Renesas Electronics Corporation |
| Microchip Technology |
| Abracon |
| SiTime |
| Others |
Value Network & Pricing Analysis
Foundry scale economies in Taiwan and South Korea establish price floors for automotive-grade timing oscillators while compressing margins for mid-scale CMOS producers serving consumer electronics. Capacity utilization rates at TSMC and Samsung Foundry directly determine premium tier pricing power for AEC-Q200 qualified devices.
Pricing Analysis
EU CE marking electromagnetic compatibility mandates dictate the pricing tier structure across automotive electronics supply chains. Three-tier pricing structure across premium, standard, and economy levels separates AEC-Q200 certified automotive oscillators from industrial-grade devices and consumer CMOS timing chips. Cost compression in consumer-grade segments is intensifying because Chinese assembly houses are internalizing timing IC procurement under vertical integration programs. Automotive OEMs exhibit the lowest price sensitivity due to qualification lock-in effects, while smartphone manufacturers in Vietnam and India drive the hardest volume negotiations.
Supply Chain Analysis
Strait of Malacca transit routes underpin raw quartz crystal logistics from Southeast Asian refiners to East Asian blank manufacturers. Supply concentrates in Taiwan, South Korea, and Japan for precision oscillator fabrication, while China dominates CMOS timing IC assembly and test. Raw material dependencies center on cultured quartz blanks, ceramic package substrates, and palladium-based electrode coatings. Single-source vulnerability runs through East Asian foundry capacity allocation decisions for automotive qualification lines. Distribution runs through direct OEM partnerships for premium tiers and Arrow-Avnet networks for industrial mid-scale buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor clock demand sits in early-cycle expansion as automotive zonal computing architectures multiply channel counts per vehicle. Software-defined vehicle platforms represent the dominant adoption tailwind accelerating specification tier upgrades.
For Market Incumbents: Consolidate AEC-Q200 qualified foundry capacity through long-term offtake agreements with TSMC and GlobalFoundries to defend against MEMS resonator substitution in telecommunications. Lock in direct sourcing relationships with German and Japanese automotive OEMs before platform architects freeze design wins at the zonal compute level. Channel control through distributor bypass agreements protects margin pools from Arrow-Avnet markup compression.
For New Entrants and Emerging Players: Post-sales calibration and field programming services for smart clock deployments represent an under-served layer where legacy timing houses lack software competency. Target India's PLI scheme beneficiaries assembling telecommunications equipment for domestic 5G infrastructure buildouts. A foundry-lite fabless model partnered with Tower Semiconductor's MEMS capabilities offers the most penetrable entry path against vertically integrated incumbents.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among smart clock suppliers with software-defined configurability and multi-year automotive platform contracts. Long-term viability over the next decade hinges on exposure to automotive electrification and satellite constellation timing rather than consumer electronics commoditization. Acquisition candidates with established conflict-mineral-free quartz sourcing and transparent REACH compliance documentation command scarcity premiums. Watch MEMS resonator temperature coefficient breakthroughs as the inflection signal for substitution velocity against legacy quartz.
| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q200 Qualification Investment | Freezes design wins with Stuttgart and Detroit automotive OEMs for 18-24 month cycles. |
| MEMS Resonator R&D Partnership | Accelerates temperature stability parity with quartz for telecommunications base station penetration. |
| Direct OEM Sourcing Agreement | Bypasses Arrow-Avnet distribution layers to capture full margin on automotive-grade oscillators. |
| Conflict-Mineral-Free Sourcing Program | Satisfies ECHA REACH audits and German OEM qualification requirements for supply chain transparency. |
| India PLI Scheme Manufacturing Footprint | Qualifies for government incentives while diversifying geographic risk beyond Taiwan-South Korea concentration. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with automotive platform architects, telecommunications equipment procurement leads, foundry capacity planners, and analog-mixed signal design directors; and secondary validation against SEC 10-K filings, ECHA REACH substance restriction updates, MIIT industrial policy announcements, and customs trade data for quartz crystal imports. Bottom-up triangulation across component-level bill-of-materials analysis and top-down reconciliation against foundry revenue disclosures anchored volume and value estimates.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, fabrication technology, application specification tier, and end-user procurement authority. CAGRs were derived from regression analysis of historical foundry utilization rates and automotive production forecasts. Industry-specific inputs included AEC-Q100/Q200 qualification timeline data and 5G base station deployment schedules from South Korean and Taiwanese network equipment OEMs.
Forecasts assume regulatory continuity in EU CE marking, China GB/T electromagnetic compatibility, and REACH SVHC candidate list evolution; material policy shifts would require re-modeling of automotive qualification barriers and substance restriction compliance costs. Practitioners should keep alternative scenarios live as automotive OEM consolidation of procurement authority and MEMS resonator technical parity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
Chiplets Market
Semiconductors
High Reliability Semiconductor Market
Semiconductors
North America Semiconductor Market
Semiconductors
Global Organic Semiconductor Market
Semiconductors
Compound Semiconductor Market
Semiconductors
Resistive RAM Market
Semiconductors
Indium Phosphide Compound Semiconductor Market
Semiconductors
Discrete Semiconductor Market
Semiconductors
Logic Semiconductor Market
Semiconductors
Asia Pacific Flash Memory Market
Semiconductors
Smartphone Battery Market
Semiconductors
South Korea Discrete Semiconductors Market
Semiconductors
IV-IV Compound Semiconductor Market
Semiconductors
Digital Semiconductors Market
Semiconductors
Organic Electronics Market
Semiconductors
East Asia Automotive Semiconductors Market