
 Readout Integrated Circuits (ROIC) Market | 2026-2036
Readout Integrated Circuits (ROIC) Market Size, Share, and Industry Trends Forecast 2026-2036
Readout Integrated Circuits (ROIC) Market Analytics
The foundry-access gap between fabless design houses and integrated IDMs is reorganizing competitive tiers in ROIC supply. Analog Devices, Inc. leverages in-house BiCMOS fabrication to sustain margin control on multichannel arrays for CT scanners. Texas Instruments Incorporated anchors its position through captive 300mm CMOS capacity serving LIDAR and thermal imaging clients. Hamamatsu Photonics K.K. differentiates via vertical integration from photodiode through ROIC module, dominating spectroscopy instrumentation in Japan and Europe.
Readout Integrated Circuits are mixed-signal ASICs that amplify, integrate, and digitize charge signals from photodetector arrays, typically achieving noise floors below 10 electrons RMS and frame rates exceeding 1000 fps for time-resolved imaging. Their primary purpose lies in converting weak optical or radiation inputs into digital data streams for medical, industrial, and defense imaging systems. CMOS technology leads unit volume due to foundry scalability and on-chip integration of analog front-ends with digital readout engines. Multichannel architectures capture the fastest expansion as flat-panel detectors for digital radiography and fluoroscopy displace legacy CCD-based chains. Thermal imaging applications concentrate margin pools because military and commercial uncooled bolometer arrays demand customized ROICs with non-uniformity correction engines.
FDA 21 CFR Part 1020 governs diagnostic X-ray system performance standards, compelling ROIC suppliers to validate noise-equivalent quanta and detective quantum efficiency metrics for 510(k) submissions. EMA's Medical Device Regulation and China's NMPA technical review guidelines for active implantable and diagnostic imaging devices are harmonizing electromagnetic compatibility and biocompatibility testing burdens across export markets. ISO 13485 quality management requirements further filter supplier qualification for medical OEM procurement. Stakeholders must monitor foundry allocation cycles and dual-source qualification timelines as defense and medical demand converges on constrained 180nm-65nm specialty process nodes.
Market Dynamics
Foundry allocation cycles for specialty 180nm-65nm nodes are compressing qualification timelines as medical imaging OEMs and defense contractors converge on constrained mixed-signal capacity. This supply-side tension forces dual-source strategies and accelerates IDM-fabless tier stratification.
Growth Catalysts
- FDA 510(k) pathway streamlining:Compressed diagnostic imaging device approvals in the United States are accelerating CMOS-based flat-panel detector deployments for digital radiography systems.
- China NMPA registration reforms:Technical review guideline harmonization for active implantable and diagnostic imaging devices is reducing time-to-market for imported ROIC modules.
- Uncooled bolometer arrays:Military and commercial thermal imaging programs are pulling customized ROICs with integrated non-uniformity correction engines.
Market Restraints
- Specialty foundry concentration:Taiwan and South Korea dominate 180nm-65nm mixed-signal capacity, creating single-source vulnerability for fabless ROIC design houses.
- Raw silicon germanium substrate costs:BiCMOS process inputs face price volatility from semiconductor-grade crystal supply constraints.
- ISO 13485 compliance burden:Medical device quality management certification filters supplier qualification, extending OEM procurement cycles.
Strategic Opportunities
- India diagnostic imaging expansion:CDSCO regulatory alignment with IMDRF standards is opening import pathways for CT and digital X-ray detector OEMs.
- Photonics-electronics convergence:Co-packaged optics with CMOS ROICs is creating new product architectures for spectroscopy instrumentation.
- EU MDR Article 10 technical documentation:Harmonized electromagnetic compatibility requirements are simplifying multi-market registration for European medical device suppliers.
Industry Challenges
- Mixed-signal design talent scarcity:Analog front-end and high-speed digital integration expertise concentrates among senior engineers at IDMs and established fabless houses.
- 510(k) substantial equivalence documentation:Noise-equivalent quanta and detective quantum efficiency validation for diagnostic X-ray ROICs demands specialized metrology partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Readout Integrated Circuits (ROIC) Market |
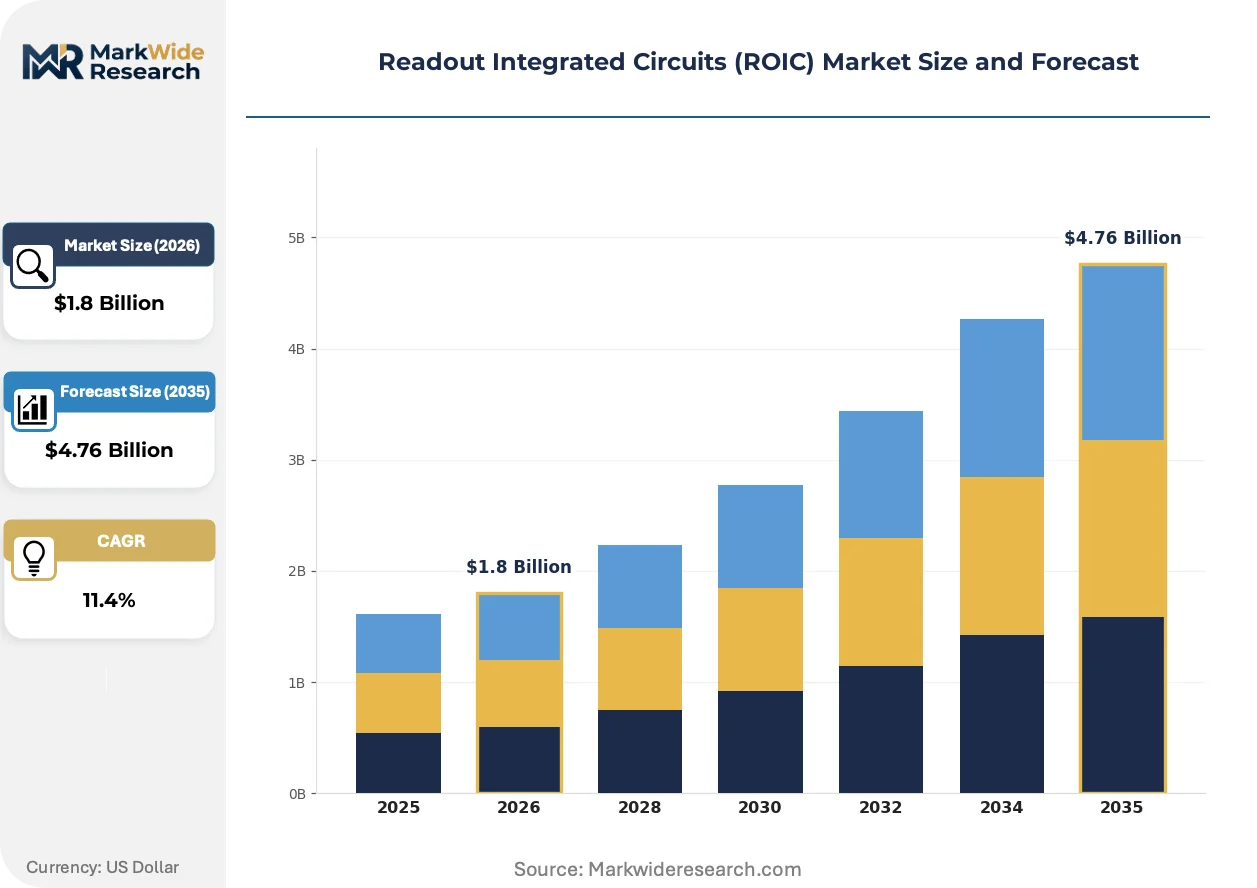
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Speed, Low-Power, Multichannel, Single-Channel End User: Aerospace, Medical Imaging, Consumer Electronics, Industrial Technology: CMOS, Bipolar, BiCMOS, GaN Application: Thermal Imaging, Spectroscopy, X-Ray Imaging, LIDAR |
| Companies Covered | Analog Devices, Inc., BAE Systems plc, Teledyne Technologies Incorporated, Infineon Technologies AG, Raytheon Technologies Corporation, Hamamatsu Photonics K.K., Texas Instruments Incorporated, STMicroelectronics N.V., FLIR Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Readout Integrated Circuits (ROIC) Market Evolving Landscape
Three forces are restructuring ROIC value capture: CMOS process node migration, regulatory harmonization across medical device markets, and procurement model compression toward turnkey detector modules.
Stacked-die 3D integration with through-silicon vias is decomposing traditional wire-bonded multichannel architectures into vertically interconnected sensor-ROIC assemblies. CT scanner OEMs in Germany and Japan are piloting these configurations for slice-count expansion. The technology is decomposing established packaging supply chains and shifting margin pools toward advanced substrate vendors.
EU Medical Device Regulation (MDR) Annex I general safety and performance requirements are tightening electromagnetic compatibility and biocompatibility testing burdens for active implantable imaging devices. ROIC suppliers must now maintain technical documentation across notified body jurisdictions. Flat-panel detector manufacturers serving European hospitals are consolidating certification management under single regulatory affairs functions.
Digital radiography OEMs are unbundling after-sales service contracts from hardware procurement, compressing multi-year maintenance agreements into per-scan or outcome-based arrangements. Independent service organizations in North America are capturing replacement ROIC module revenue previously held by system integrators. This shift is most visible in outpatient imaging centers and mobile X-ray deployments across the United States.
Readout Integrated Circuits (ROIC) Market Segmentation
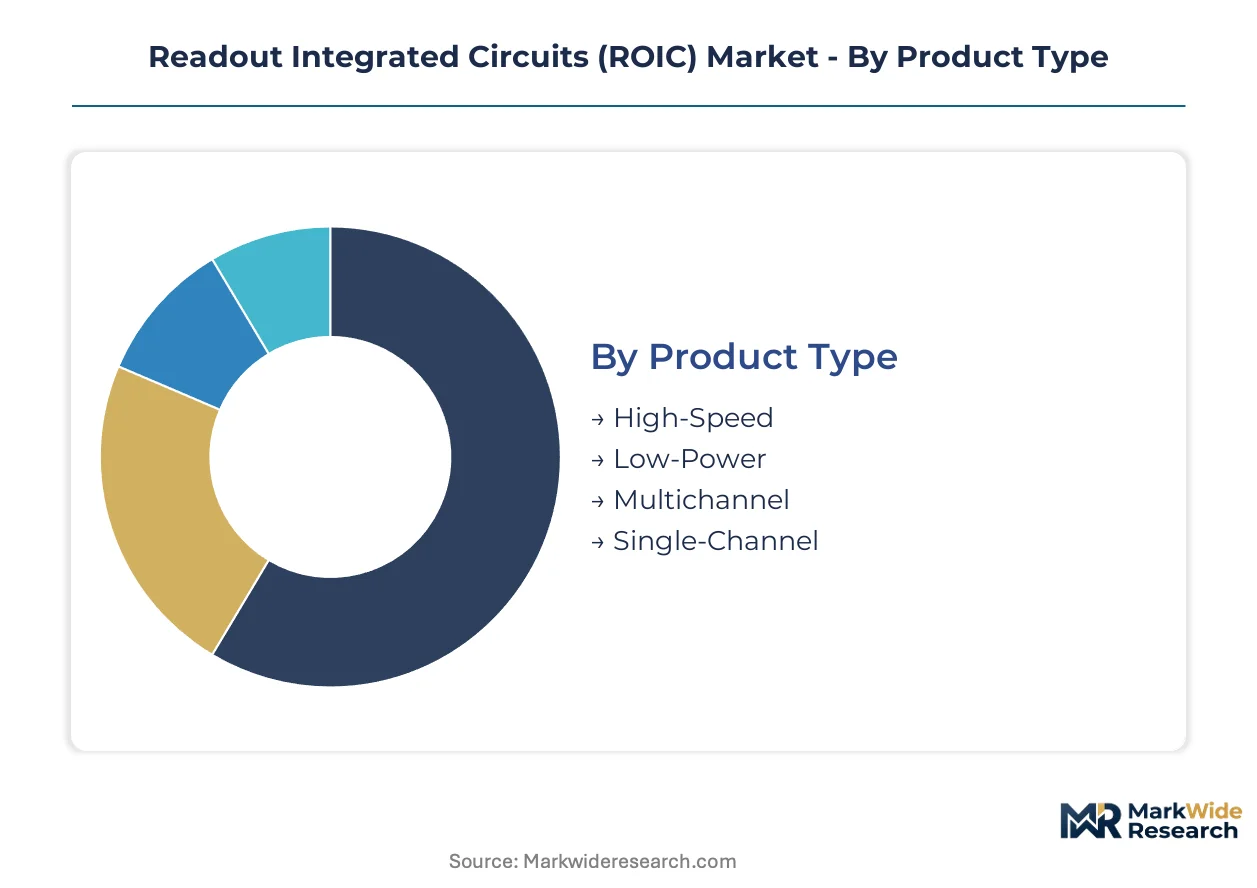
ROIC segmentation reveals how architectural choices map to divergent margin structures across defense, medical, and industrial demand pools. Product type and technology selections determine foundry access tiers, while application focus shapes regulatory compliance burdens and qualification timelines.
Product Type:
Domestic demand in Germany and Japan concentrates on precision multichannel arrays for CT reconstruction, while export-led volumes flow to Shenzhen-Dongguan corridor flat-panel detector manufacturers.
- Multichannel:Architectures integrate 128-1024 parallel readout channels with correlated double sampling circuits, achieving noise floors below 10 electrons RMS. German CT OEMs in Munich and Erlangen anchor procurement for slice-count expansion programs. FDA 510(k) pathway streamlining accelerates US hospital system deployments.
- High-Speed:Frame rate targets exceed 1000 fps through pipelined column-parallel ADC architectures. Time-resolved spectroscopy instrumentation in Japan and Switzerland pulls specialized designs from Hamamatsu and IDM captive fabs.
- Low-Power:Portable X-ray and battery-operated thermal imagers demand sub-100mW dissipation per channel. Wearable medical devices and handheld industrial inspection tools drive qualification.
- Single-Channel:Discrete photodiode readout for laboratory instrumentation and calibration equipment. Niche volumes concentrate in European analytical chemistry and materials science research facilities.
Multichannel holds the largest share; momentum sits with high-speed architectures as time-resolved imaging expands fastest.
End User:
Cost tier stratification separates military thermal imaging programs with non-recurring engineering budgets from price-sensitive consumer electronics volumes.
- Medical Imaging:Flat-panel detectors for digital radiography and fluoroscopy displace legacy CCD chains. CMOS-based deployments scale fastest in North American hospital systems and China's tier-one cities undergoing healthcare infrastructure expansion.
- Aerospace:Satellite payload and space-based imaging demand radiation-hardened designs with extended temperature ranges. European Space Agency programs and US defense contractors qualify suppliers through multi-year development cycles.
- Industrial:Machine vision, process control, and non-destructive testing applications. German automotive manufacturing and Japanese electronics assembly lines drive standard product volumes.
- Consumer Electronics:Smartphone spectral sensors and augmented reality depth cameras. Shenzhen ecosystem manufacturers compress design cycles to 12-18 months.
Medical imaging commands premium pricing; aerospace volumes are climbing the fastest as constellation deployment accelerates.
Technology:
Supply concentration in Taiwan and South Korean foundries shapes access patterns for fabless design houses versus IDM captive capacity.
- CMOS:Dominant unit volume through 180nm-65nm foundry scalability. On-chip integration of analog front-ends with digital readout engines enables cost structures viable for high-volume medical and consumer applications.
- BiCMOS:Combines bipolar transconductance with CMOS density for low-noise precision arrays. Analog Devices leverages in-house fabrication for CT scanner margins.
- Bipolar:Legacy architectures for specialized high-linearity applications. Maintenance volumes concentrate in European analytical instrumentation installed base.
- GaN:Emerging wide-bandgap option for high-temperature and radiation-hard environments. Satellite and aerospace qualification timelines extend 3-5 years.
CMOS holds the largest share; BiCMOS is gaining share fastest as precision medical applications expand.
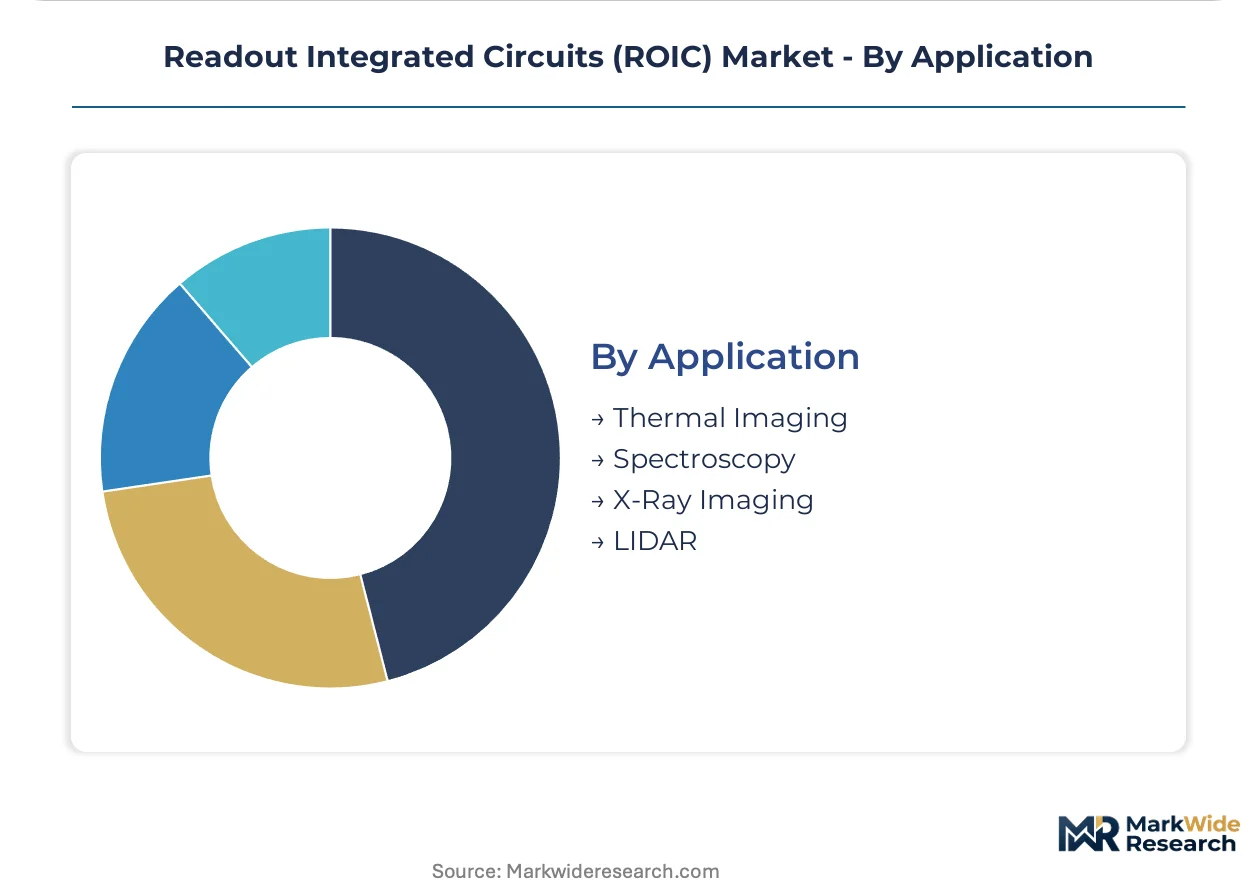
Application:
Customer type divergence separates defense procurement with multi-year development contracts from medical OEM spot-buy patterns for replacement modules.
- Thermal Imaging:Uncooled bolometer arrays demand customized ROICs with integrated non-uniformity correction engines. Military programs in the United States and commercial security applications in China concentrate margin pools.
- X-Ray Imaging:Digital radiography and CT detector modules require validated noise-equivalent quanta metrics. FDA 21 CFR Part 1020 compliance filters supplier qualification.
- Spectroscopy:High-resolution photon counting for analytical chemistry and materials science. Hamamatsu vertical integration from photodiode through module dominates Japan and Europe.
- LIDAR:Automotive and industrial ranging systems pull high-speed time-of-flight architectures. Texas Instruments captive 300mm capacity serves tier-one automotive qualification programs.
Thermal imaging holds the largest share; LIDAR is expanding most quickly as automotive ADAS penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. German precision sensor clusters demand multichannel CT arrays, while China's Shenzhen corridor drives flat-panel detector volumes for digital radiography. The United States concentrates thermal imaging procurement through defense programs.
United States
Defense thermal imaging programs and hospital system digitization pull distinct ROIC specifications. FDA 510(k) pathway streamlining accelerates CMOS-based flat-panel detector deployments for digital radiography. Boston and Austin anchor medical imaging OEM clusters pursuing slice-count expansion in CT reconstruction.
Germany
Precision multichannel arrays for CT reconstruction dominate procurement from Munich and Erlangen industrial zones. EU MDR Annex I requirements tighten electromagnetic compatibility testing burdens for active implantable imaging devices. Bavaria's precision sensor cluster sustains demand for validated noise-equivalent quanta metrics.
China
Shenzhen-Dongguan electronics corridor manufacturers scale CMOS-based detector deployments for domestic digital radiography and CT systems. NMPA medical device registration reforms compress technical review timelines for imported ROIC modules. Tier-one city healthcare infrastructure expansion drives flat-panel detector replacement cycles.
Japan
Time-resolved spectroscopy instrumentation and CT scanner OEMs pull specialized high-speed architectures. PMDA technical review guidelines harmonize with IMDRF standards for diagnostic imaging device approvals. Hamamatsu anchors photonics-electronics convergence from photodiode through module assembly.
South Korea
Foundry capacity at specialty 180nm-65nm nodes serves fabless ROIC design houses and IDM captive requirements. MFDS regulatory alignment with international standards opens import pathways for medical imaging OEMs. Seoul Capital Area concentration of mixed-signal fabrication supports LIDAR and thermal imaging demand.
Readout Integrated Circuits (ROIC) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in ROIC supply structure. Captive fabrication capacity separates IDMs with margin control from fabless houses competing for foundry allocation. Three archetypes dominate: vertically integrated photonics-electronics conglomerates, diversified analog semiconductor IDMs, and defense-aerospace contractors with cleared fabrication. Competitive moves concentrate on dual-source qualification partnerships and 3D stacked-die packaging alliances.
Among diversified analog semiconductor IDMs, Analog Devices, Inc. and Texas Instruments Incorporated exemplify the integrated fabrication archetype. Hamamatsu Photonics K.K. occupies a distinct position spanning photodiode production through module assembly. Defense-aerospace contractors with cleared fabrication capabilities, represented by BAE Systems plc, sit within a tier serving radiation-hardened and extended temperature range specifications.
| Leading Market Players |
|---|
| Analog Devices, Inc. |
| BAE Systems plc |
| Teledyne Technologies Incorporated |
| Infineon Technologies AG |
| Raytheon Technologies Corporation |
| Hamamatsu Photonics K.K. |
| Texas Instruments Incorporated |
| STMicroelectronics N.V. |
| FLIR Systems, Inc. |
| Others |
Value Network & Pricing Analysis
CMOS process migration from 180nm to 65nm specialty nodes is displacing legacy BiCMOS architectures in high-volume medical imaging, simultaneously shifting foundry procurement toward Taiwan and South Korean capacity while compressing per-channel pricing economics for fabless design houses competing against IDM captive fabrication.
Pricing Analysis
Long-term offtake agreements with medical imaging OEMs anchor premium multichannel array pricing, while spot procurement for replacement modules in digital radiography systems compresses margins. Price differentiation separates FDA-validated CT detector tiers from unregistered industrial thermal imaging volumes. Pricing pressure intensifies as Shenzhen-Dongguan flat-panel manufacturers consolidate procurement under outcome-based service contracts. Consumer electronics buyers exhibit highest price sensitivity; defense thermal imaging programs demonstrate lowest.
Supply Chain Analysis
TSMC and Samsung Foundry specialty node allocation serves as the primary chokepoint for fabless ROIC design houses seeking mixed-signal capacity. Raw silicon germanium substrate supply draws from semiconductor-grade crystal producers in Germany and Japan. Single-source vulnerability concentrates in Taiwan's 180nm-65nm mixed-signal foundry base. Distribution runs through turnkey detector module integrators serving hospital systems and defense contractors directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stacked-die 3D integration with through-silicon vias is disrupting established wire-bonded packaging chains, creating acquisition opportunities for substrate specialists and compressing qualification timelines for CT scanner slice-count expansion programs.
For Market Incumbents: Secure dual-source qualification partnerships with advanced packaging vendors before 3D stacked-die architectures become mandatory for slice-count expansion in CT reconstruction. Invest in captive BiCMOS capacity retention as fabless competitors face foundry allocation constraints at specialty nodes. Defend against pricing erosion from Shenzhen-based flat-panel detector manufacturers by embedding ROIC modules within multi-year service contracts. For New Entrants and Emerging Players: Lead with photonics-electronics convergence architectures targeting spectroscopy instrumentation gaps left by Hamamatsu's vertical integration focus. Target India's diagnostic imaging expansion as CDSCO regulatory alignment with IMDRF standards opens import pathways with compressed technical review timelines. Pursue co-packaged optics partnerships with CMOS foundries to bypass established module assembly tiers. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors advanced packaging specialists and regulatory-affairs-consolidated platform companies over pure-play fabless design houses. Acquisition targets should demonstrate validated FDA 510(k) submission experience or EMA MDR technical documentation capabilities. Monitor NMPA registration reform implementation velocity as the signal for China's import pathway expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| 3D Stacked-Die Packaging Partnership | Enables slice-count expansion for German and Japanese CT OEMs while decomposing legacy wire-bond supply chains. |
| FDA 510(k) Dual-Source Qualification | Reduces single-source vulnerability for medical imaging OEMs facing mixed-signal foundry allocation constraints. |
| Photonics-Electronics Convergence Development | Creates new product architectures for spectroscopy instrumentation beyond Hamamatsu's vertical integration scope. |
| India CDSCO Regulatory Alignment Investment | Opens diagnostic imaging import pathways as technical review guidelines harmonize with IMDRF standards. |
| BiCMOS Captive Capacity Retention | Sustains margin control for precision CT arrays against fabless competitors dependent on Taiwan foundry allocation. |
Research Methodology
Cross-validation between primary interviews with ROIC design engineers, medical imaging OEM procurement directors, and foundry account managers anchors the qualitative findings. Secondary validation draws from FDA 510(k) submission databases, EMA MDR technical documentation filings, and SEMI capacity tracking reports. Bottom-up channel checks with Shenzhen-Dongguan flat-panel detector manufacturers triangulate against top-down semiconductor equipment spending analysis.
Sensitivity analysis across specialty foundry utilization rates, NMPA registration reform implementation timelines, and 3D packaging yield curves informs the projection framework. Segmentation dimensions include product architecture, end-use application, process technology node, and geographic regulatory cluster. CAGRs derive from installed base replacement cycles and new system deployment trajectories. Forecast inputs incorporate CT scanner slice-count expansion roadmaps and uncooled bolometer array military procurement schedules.
Underlying assumptions cover sustained FDA 510(k) pathway streamlining, Taiwan foundry capacity allocation stability, and China healthcare infrastructure expansion continuity, with deviation risk concentrated in specialty node supply disruptions and EU MDR notified body capacity constraints. Practitioners should keep alternative scenarios live as geopolitical foundry access conditions and regulatory harmonization progress evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
NFC Reader Ics Market
IC (Integrated Circuits)
PFC Control IC Market
IC (Integrated Circuits)
Global Interface IC Market
IC (Integrated Circuits)
Global Application Specific Industrial Analog IC Market
IC (Integrated Circuits)
Audio Power Amplifier IC Market
IC (Integrated Circuits)
Application Specific Integrated Circuit Market
IC (Integrated Circuits)
GNSS IC Market
IC (Integrated Circuits)
Isolated Interface Chip Market
IC (Integrated Circuits)
Automotive Special Purpose Logic IC Market
IC (Integrated Circuits)
Energy Metering IC Chip Market
IC (Integrated Circuits)
Communication Special Purpose Logic IC Market
IC (Integrated Circuits)
Global Consumer Standard Logic IC Market
IC (Integrated Circuits)
China Analog IC Market
IC (Integrated Circuits)
Mixed-Signal Microcontroller Market
IC (Integrated Circuits)
Integrated Circuit Market
IC (Integrated Circuits)
Global Photonic Integrated Circuits (PIC) Market