
 Global Narrowband IoT Market | 2026-2036
Global Narrowband IoT Market Size, Share, and Industry Trends Forecast 2026-2036
Global Narrowband IoT Market Outlook
3GPP Release 13 compliance is reorganizing the competitive landscape for module suppliers seeking carrier network approval. Huawei Technologies Co., Ltd leverages its integrated chipset-to-cloud stack to dominate infrastructure tenders across Asian telecom operators. Qualcomm Technologies, Inc. sustains R&D intensity in multimode LTE-M/NB-IoT modems that anchor premium pricing in the North American carrier ecosystem. Nokia Corporation competes through Open RAN-aligned baseband solutions that extend its position in European utility smart grid contracts.
Narrowband IoT refers to a low-power wide-area cellular technology operating in licensed spectrum below 1 GHz with 200 kHz channel bandwidth, designed to enable long-battery-life connectivity for devices transmitting small data payloads intermittently. The technology serves industrial asset monitoring, utility meter reading, and agricultural sensor networks where terrestrial coverage depth matters more than bandwidth. Hardware modules currently lead solution revenue as unit volumes scale, while cloud platforms represent the fastest-expanding margin pool as enterprises seek managed device lifecycle services. Smart metering applications dominate current deployment value, though asset tracking is gaining traction in logistics fleets requiring geofenced alerts across national boundaries.
The EU's Cybersecurity Act and CE marking requirements under the Radio Equipment Directive shape product certification costs and timeline risk for vendors entering European markets. The FCC in the United States governs spectrum allocation and device authorization, while China's MIIT administers NB-IoT band licensing and GB standards compliance for domestic module production. Stakeholders must monitor evolving 3GPP release roadmaps and regional certification divergence to align R&D bets with addressable market access.
Market Dynamics
3GPP Release 14 and Release 15 feature roadmaps are fragmenting module vendor R&D budgets as carriers demand coexistence between NB-IoT and LTE-M protocols, forcing silicon suppliers to maintain dual-mode firmware stacks or risk disqualification from infrastructure tenders.
Growth Catalysts
- Utility smart metering mandates:Germany's Bundesnetzagentur and France's Enedis are accelerating replacement cycles for electromechanical meters, creating module procurement pull through 2030.
- REACH and RoHS substance restrictions:European environmental compliance is filtering out legacy 2G module suppliers unable to certify lead-free solder processes, consolidating qualified vendor pools.
- Agricultural sensor densification:Brazil's soybean belt and India's Punjab region are deploying soil moisture monitors at scale, prioritizing licensed-spectrum reliability over unlicensed LoRa alternatives.
Market Restraints
- Spectrum auction costs:India's TRAI and Brazil's Anatel have raised 700 MHz and 800 MHz access fees, compressing carrier capex available for NB-IoT base station densification.
- Module supply concentration:Greater Shenzhen's PCB substrate and RF front-end component ecosystem controls 60-70% of global module bill-of-materials, exposing buyers to single-region disruption risk.
- LTE-M protocol substitution:North American carriers are prioritizing higher-throughput LTE-M for fleet tracking, displacing NB-IoT in mobile asset applications where handoff capability matters.
Strategic Opportunities
- Indonesia's archipelago coverage gaps:The country's 17,000-island geography favors satellite-NB-IoT hybrid networks for fisheries and palm oil plantation monitoring.
- EU Cybersecurity Act certification:Common Criteria evaluation schemes are creating first-mover advantage for module vendors achieving EN 303 645 compliance before 2027 enforcement windows.
- 5G RedCap convergence:Mid-band RedCap chipsets are enabling NB-IoT module suppliers to address industrial video sensor applications previously unreachable at 200 kHz bandwidth.
Industry Challenges
- RF systems engineering scarcity:Module vendors in Germany and Japan report 18-month hiring timelines for sub-1 GHz antenna tuning specialists capable of certifying to 3GPP coexistence requirements.
- Carrier certification queue compression:AT&T and Verizon testing backlogs now extend 9-14 months for new module SKUs, delaying revenue recognition for hardware launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Narrowband IoT Market |
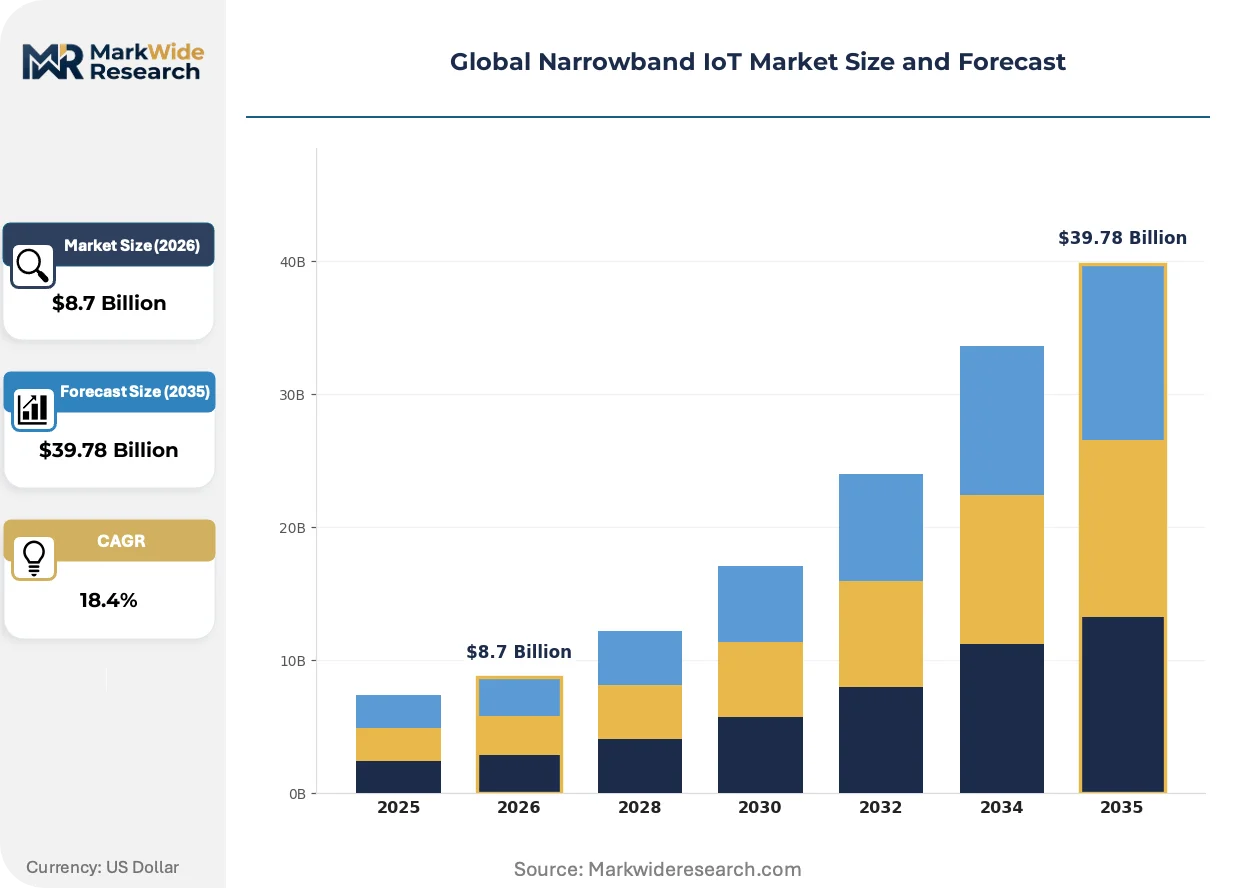
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Smart Metering, Asset Tracking, Wearable Devices, Smart Agriculture Technology: NBIoT, LTE-M, Sigfox, LoRaWAN End User: Utilities, Transportation, Healthcare, Retail Solution: Hardware, Software, Connectivity Services, Cloud Platforms |
| Companies Covered | Huawei Technologies Co., Ltd, Qualcomm Technologies, Inc., Nokia Corporation, Telefonaktiebolaget LM Ericsson, AT&T, Verizon Communications Inc., Sierra Wireless, u-blox, Quectel Wireless Solutions Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Narrowband IoT Market Strategic Shifts
Silicon vendors are collapsing discrete component counts through system-in-package integration, while regulatory pressure on embodied carbon is reshaping module manufacturing geography and test house location strategies.
Chip-scale antenna-in-package technology is decomposing traditional module assembly workflows by embedding matching networks and filters directly onto die substrates. Agricultural OEMs in Australia's Murray-Darling Basin are specifying these integrated modules for irrigation valve controllers. The shift is compressing final assembly labor costs and reducing failure points in high-humidity field deployments.
CSRD corporate sustainability reporting obligations are forcing European module buyers to document Scope 3 emissions from Taiwanese foundry partners. Hardware procurement teams at German automotive Tier 1s now require carbon footprint disclosures alongside technical datasheets. The compliance burden is favoring vertically integrated suppliers with captive wafer fabrication and renewable energy contracts.
Buyers are unbundling device management platforms from hardware procurement, treating cloud connectivity stacks as separate vendor decisions. Japanese industrial conglomerates are piloting multi-carrier SIM orchestration services that switch NB-IoT attachments based on real-time signal strength. The decoupling is most advanced in Germany's Ruhr industrial corridor, where machinery OEMs negotiate module hardware and platform subscriptions through distinct procurement workflows.
Global Narrowband IoT Market Segmentation
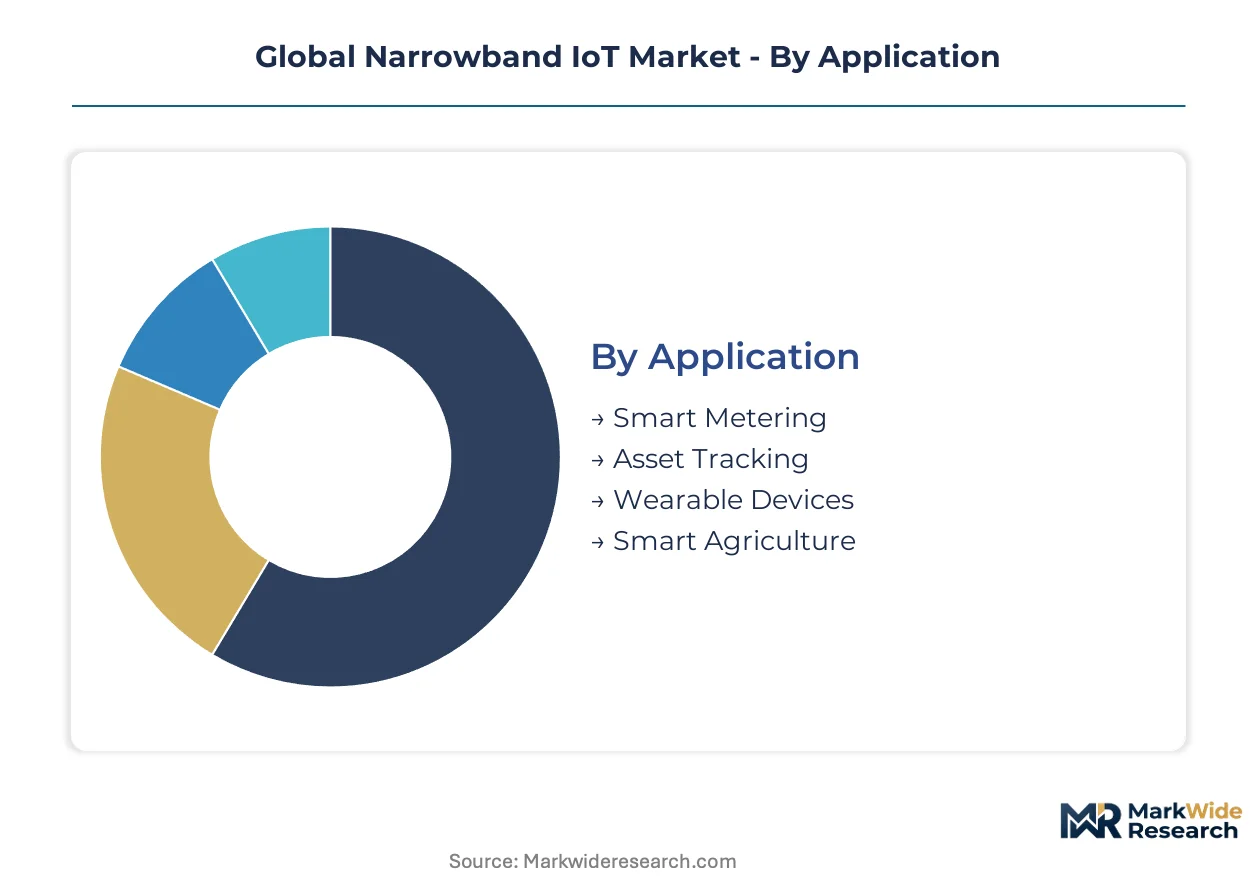
Narrowband IoT procurement patterns diverge sharply across application contexts, with utility mandates driving volume while logistics requirements reshape module specifications. Technology choices determine addressable spectrum access and carrier certification pathways. End-user verticals impose distinct latency, security, and lifecycle cost constraints that filter qualified vendor pools.
Application:
Margin pools concentrate in deployments requiring multi-year device lifecycles and managed service overlays rather than transactional hardware sales.
- Smart Metering:Electromechanical meter replacement cycles in Germany and France mandate IP68-rated modules with 15-year battery autonomy. Bundesnetzagentur tender specifications favor vendors offering integrated cryptographic key provisioning for remote firmware updates.
- Asset Tracking:Logistics fleets crossing European borders require seamless carrier handoff capabilities that strain pure NB-IoT implementations. Container monitoring in Rotterdam and Hamburg ports is rotating toward LTE-M hybrids for real-time geofenced alerts.
- Wearable Devices:Medical alert pendants in Japan specify sub-10mA sleep currents to achieve 30-day recharge intervals.
- Smart Agriculture:Soil moisture arrays in Australia's Murray-Darling Basin prioritize licensed-spectrum reliability over unlicensed alternatives for irrigation valve control.
Smart Metering holds installed capacity. Asset Tracking is rotating up the share rankings.
Technology:
Carrier infrastructure roadmaps determine which protocols secure base station software upgrade priority and certification queue placement.
- NBIoT:200 kHz channel bandwidth enables deep indoor penetration for utility basement meter installations. Asian telecom operators in China and South Korea have prioritized NB-IoT over LTE-M for fixed sensor networks, concentrating R&D investment in Release 14 power-saving mode enhancements.
- LTE-M:Higher throughput and mobility support attract fleet management deployments requiring voice fallback and seamless handoff. North American carriers have steered transportation customers toward LTE-M, displacing NB-IoT in mobile asset applications.
- Sigfox:Ultra-narrowband unlicensed operation suits low-cost, low-duty-cycle sensor networks in France where the operator maintains dedicated infrastructure.
- LoRaWAN:Private gateway deployment models appeal to agricultural cooperatives seeking network autonomy without carrier subscription dependencies.
NBIoT holds installed capacity. LTE-M is rotating up the share rankings.
End User:
Procurement authority centralization varies—utilities consolidate at national scale while healthcare fragments across hospital systems and home care networks.
- Utilities:State-mandated smart grid investments in Germany and France create predictable module demand with stringent cybersecurity qualification timelines. Enedis specifications require Common Criteria evaluation against EN 303 645 baseline requirements.
- Transportation:Fleet operators in North America demand multimode modems capable of attaching to whichever carrier presents strongest signal at highway speeds.
- Healthcare:Remote patient monitoring in Japan falls under PMDA device regulations, adding clinical validation costs to connectivity module procurement.
- Retail:Cold chain monitoring for grocery distribution centers in the United Kingdom specifies temperature loggers with FCC and CE dual certification for cross-border logistics.
Utilities hold installed capacity. Healthcare is rotating up the share rankings.
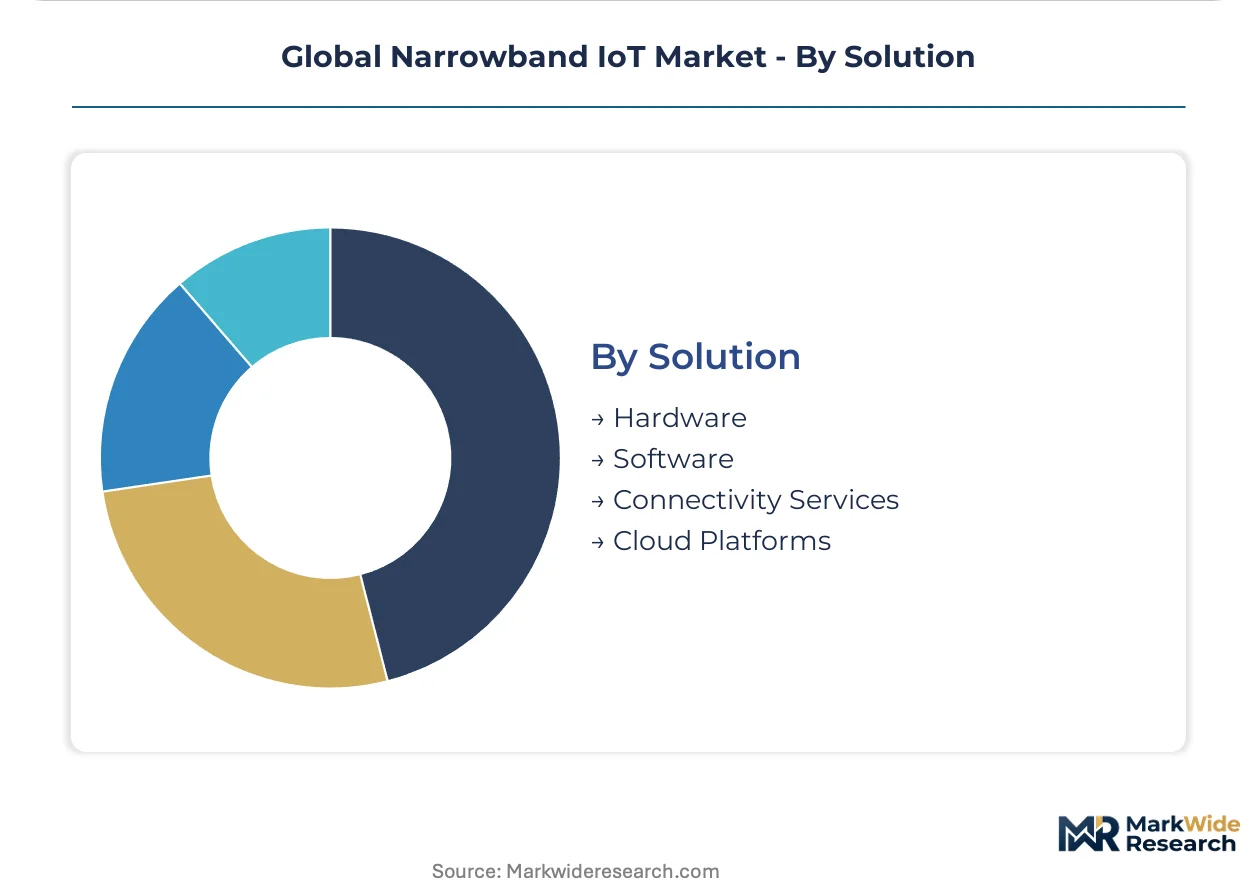
Solution:
Revenue recognition timing separates hardware-centric vendors from those capturing recurring platform fees across device lifecycles.
- Hardware:Module assemblies incorporating RF front-ends, baseband processors, and embedded SIMs dominate upfront project capex. German automotive Tier 1s now require carbon footprint disclosures from Taiwanese foundry partners under CSRD Scope 3 reporting obligations.
- Software:Firmware over-the-air update orchestration and cryptographic lifecycle management represent expanding margin pools as device counts scale.
- Connectivity Services:Multi-carrier SIM orchestration allows Japanese industrial conglomerates to switch attachments based on real-time signal strength.
- Cloud Platforms:Device management unbundling is most advanced in Germany's Ruhr corridor, where machinery OEMs negotiate hardware and platform subscriptions through distinct procurement workflows.
Hardware holds installed capacity. Cloud Platforms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility procurement teams in Germany, China, and the United States drive the majority of module volume, with carrier certification timelines and national smart grid mandates determining vendor access. Industrial automation clusters in Japan and agricultural sensor deployments in Brazil round out the five-country demand concentration.
Germany
Bundesnetzagentur smart meter rollout mandates and Ruhr industrial corridor machinery OEMs anchor European demand. REACH and RoHS substance restrictions filter out legacy 2G suppliers, consolidating qualified vendor pools. Bavaria's automotive Tier 1s now require CSRD Scope 3 carbon disclosures from Taiwanese foundry partners.
China
MIIT band licensing for 800 MHz spectrum and GB standards compliance shape domestic module production. Shenzhen's PCB substrate ecosystem controls 60-70% of global bill-of-materials, exposing buyers to single-region disruption risk. Yangtze River Delta telecom operators prioritize NB-IoT over LTE-M for fixed sensor networks.
United States
FCC device authorization and spectrum allocation govern carrier certification queues now extending 9-14 months for new module SKUs. AT&T and Verizon testing backlogs delay revenue recognition for hardware launches. Midwest utility cooperatives and California agricultural sensor networks drive regional deployment variation.
Japan
METI industrial IoT subsidies and PMDA device regulations for remote patient monitoring add clinical validation costs to connectivity procurement. Kanto region medical alert pendant manufacturers specify sub-10mA sleep currents. Osaka-based industrial conglomerates pilot multi-carrier SIM orchestration services.
Brazil
Anatel 700 MHz auction costs compress carrier capex available for base station densification. Soybean belt soil moisture monitors deploy at scale, prioritizing licensed-spectrum reliability over unlicensed LoRa alternatives. São Paulo logistics operators rotate toward LTE-M hybrids for container monitoring.
Global Narrowband IoT Market Competitive Environment
Player mix skews toward integrated chipset-to-cloud stacks and multimode modem specialists competing for carrier infrastructure tenders. Market structure concentrates around three strategic archetypes: silicon vendors with captive R&D pipelines, module assemblers leveraging Greater Shenzhen component ecosystems, and telecom operators bundling connectivity with managed device platforms. Competitive moves center on dual-mode firmware stack maintenance and Open RAN-aligned baseband certification.
Within the integrated infrastructure tier, Huawei Technologies Co., Ltd and Qualcomm Technologies, Inc. exemplify divergent geographic positioning—one anchoring Asian operator tenders through vertical stack control, the other sustaining premium positioning in North American carrier ecosystems through multimode R&D intensity. Nokia Corporation occupies a position bridging European utility requirements with Open RAN alignment, representing the legacy equipment vendor archetype adapting to cloud-native baseband demands.
| Leading Market Players |
|---|
| Huawei Technologies Co., Ltd |
| Qualcomm Technologies, Inc. |
| Nokia Corporation |
| Telefonaktiebolaget LM Ericsson |
| AT&T |
| Verizon Communications Inc. |
| Sierra Wireless |
| u-blox |
| Quectel Wireless Solutions Co., Ltd |
| Others |
Value Chain & Pricing Dynamics
3GPP Release 14 certification timelines gate both vendor qualification and module price stratification simultaneously, compressing margins for suppliers caught in extended carrier testing queues while rewarding early movers with premium positioning in smart metering tenders. Buyers in Germany's Ruhr corridor unbundle hardware from platform subscriptions, forcing module vendors to compete on upfront unit economics alone.
Pricing Analysis
Cost-plus contracts with Taiwanese foundry indexation dominate module procurement, tying unit prices to substrate and RF component spot markets. Pricing stratifies across Common Criteria certified, CE-marked, and uncertified tiers, with German utilities paying premiums for EN 303 645 compliance. Cost compression in standard-grade modules intensifies as Shenzhen assemblers absorb margin erosion from 9-14 month carrier certification delays. Price sensitivity peaks among agricultural cooperatives in Brazil's soybean belt, while German automotive Tier 1s prioritize carbon disclosure compliance over unit cost.
Supply Chain Analysis
China and Taiwan anchor substrate fabrication and RF front-end production, with South Korea supplying advanced baseband silicon. Module assembly draws from Greater Shenzhen's PCB ecosystem, Japanese precision components, and German antenna tuning expertise. Single-region concentration in 700-800 MHz power amplifier sourcing creates tariff exposure risk as trade policy shifts. Distribution runs through carrier-certified module distributors, direct OEM procurement, and telecom operator bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where 3GPP certification entrenchment and carrier relationship switching costs protect incumbent positions against modular competition.
For Market Incumbents: Compound carrier certification queue advantages by pre-positioning dual-mode LTE-M/NB-IoT firmware stacks before Release 15 mandates harden. Expand captive wafer fabrication in Taiwan to secure substrate supply against single-region disruption. Deepen Open RAN baseband alignment with European utility tenders to defend against Huawei's integrated stack pressure. For New Entrants and Emerging Players: Device management platform unbundling creates white-space for pure-play connectivity orchestrators serving Japanese industrial conglomerates with multi-carrier SIM switching. Target Indonesia's archipelago fisheries monitoring with satellite-NB-IoT hybrid solutions where infrastructure gaps exclude established module vendors. Pursue agricultural sensor densification in India's Punjab region through licensed-spectrum reliability positioning against LoRa alternatives. For Investors and Strategic Acquirers: EN 303 645 enforcement windows reshape the acquisition landscape toward Common Criteria-certified module vendors with established German utility relationships. Five-to-ten year viability favors vertically integrated suppliers with captive foundry access and renewable energy contracts satisfying CSRD Scope 3 disclosure requirements. Monitor carrier certification queue compression as the signal indicating margin recovery timing for hardware-centric targets.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Mode Firmware Stack Development | Qualcomm's multimode R&D sustains premium positioning in AT&T and Verizon certification queues. |
| Common Criteria Certification Investment | Early EN 303 645 compliance creates first-mover advantage in Bundesnetzagentur smart meter tenders. |
| Captive Wafer Fabrication Expansion | Vertical integration into Taiwanese substrate production secures supply against Greater Shenzhen concentration risk. |
| Multi-Carrier SIM Orchestration Launch | Platform unbundling captures recurring revenue from Japanese industrial conglomerates piloting signal-strength switching. |
| Satellite-NB-IoT Hybrid Network Deployment | Indonesia's 17,000-island geography favors fisheries monitoring solutions unreachable by terrestrial infrastructure alone. |
Study Parameters
A standing panel of module vendor product managers, carrier certification engineers, German utility procurement leads, and Taiwanese foundry operations directors provided ongoing calibration against secondary validation from 3GPP release documentation, FCC equipment authorization databases, EU Cybersecurity Act implementation guidance, and SEC filings from listed semiconductor suppliers. Bottom-up module shipment aggregation triangulated against top-down carrier capex disclosure analysis.
Consistency checks validated volume and value outputs against carrier base station deployment disclosures, smart meter tender award announcements, and agricultural sensor pilot program budgets across the projection horizon. Segmentation modeling spanned application context, protocol technology, end-user vertical, and solution component type. CAGRs derived from logistic diffusion curves fitted to utility mandate timelines and infrastructure replacement cycles, with sensitivity testing against spectrum auction cost variation and certification queue duration shifts.
Underlying assumptions cover 3GPP release roadmap adherence, carrier infrastructure upgrade prioritization, and regulatory enforcement timeline consistency, with deviation risk concentrated in single-region supply disruption and trade policy fragmentation. Recalibration cycles align with material shifts in carrier certification queue lengths, cybersecurity standard enforcement dates, and foundry capacity allocation announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
North America Internet of Things Devices Market
Internet of Things (IoT)
Europe IoT Market
Internet of Things (IoT)
IoT IAM Market
Internet of Things (IoT)
LPWAN in the Consumer IoT Market
Internet of Things (IoT)
LAMEA Bluetooth 5.0 Market
Internet of Things (IoT)
Internet of Things in BFSI Market
Internet of Things (IoT)
Location of Things Market
Internet of Things (IoT)
Internet of Things (IoT) in Utilities Market
Internet of Things (IoT)
IoT in Chemical Industry Market
Internet of Things (IoT)
M2M Communication Market
Internet of Things (IoT)
Industrial IoT Platform Market
Internet of Things (IoT)
IoT Integration Market
Internet of Things (IoT)
IoT Communication Protocol Market
Internet of Things (IoT)
Massive IoT Market
Internet of Things (IoT)
Airport Internet of Things Market
Internet of Things (IoT)
Internet of Medical Things (Iomt) Market