
 Global IoT Engineering Services Market | 2026-2036
Global IoT Engineering Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global IoT Engineering Services Market Intelligence
Software-defined maintenance is decoupling hardware lifecycle value from upfront equipment sales in industrial IoT deployments. Tata Consultancy Services leverages its automotive and electronics vertical depth to anchor long-term managed service contracts. Accenture competes through systems integration at scale across energy and utility networks. IBM differentiates via Watson IoT analytics layered into predictive maintenance offerings for manufacturing clients.
IoT engineering services encompass the design, integration, validation, and ongoing optimization of connected device ecosystems, sensor networks, edge computing nodes, and cloud data pipelines that operate at latency thresholds below 50 milliseconds for real-time control applications. These services enable industrial asset monitoring, autonomous system coordination, and operational data monetization across physical-digital boundaries. Cloud-based deployment architectures now capture the fastest expansion within the deployment dimension as manufacturers prioritize scalable infrastructure over capital-intensive on-premise installations. Managed services within solution offerings sustain the deepest margin pools due to recurring revenue structures and multi-year client retention mechanics. Smart manufacturing dominates the use case hierarchy, though connected transportation accelerates as fleet operators retrofit logistics assets with telematics and predictive diagnostics.
FDA cybersecurity guidance for connected medical devices, FCC Part 15 rules governing unlicensed radio frequency emissions from IoT hardware, and EU Cybersecurity Act certification frameworks collectively elevate compliance costs while creating barriers for unqualified service entrants. Japan's METI IoT security guidelines and China's GB/T standards for industrial internet platforms add further jurisdictional complexity for cross-border engineering engagements. Stakeholders must monitor evolving certification reciprocity agreements between regulatory regimes to optimize delivery center placement and client contract structuring.
Market Dynamics
Software-defined maintenance architectures are decoupling hardware lifecycle value from upfront equipment sales, forcing engineering service providers to restructure contract economics around recurring revenue pools rather than capital project milestones.
Growth Catalysts
- EU AI Act compliance mandates:Industrial operators across Germany and France require certified algorithmic transparency for predictive maintenance systems, creating sustained demand for validation engineering services through 2035.
- Edge computing latency requirements:Real-time control applications demanding sub-50 millisecond response times are driving sensor network redesign and distributed compute node deployment in automotive and electronics manufacturing facilities.
- Japan METI IoT security guidelines:Mandatory security-by-design protocols for connected industrial assets are accelerating firmware engineering and penetration testing engagements among Japanese automotive suppliers.
Market Restraints
- Semiconductor component volatility:Discrete sensor and microcontroller supply concentration in Taiwan and South Korea creates procurement risk for hardware-integrated service deliverables.
- Cross-border certification reciprocity gaps:Absence of mutual recognition between EU Cybersecurity Act frameworks and China's GB/T industrial internet standards forces redundant testing cycles for multinational deployments.
- Legacy OT-IT integration friction:Proprietary industrial control protocols in brownfield manufacturing plants constrain cloud-native architecture adoption and extend implementation timelines.
Strategic Opportunities
- India industrial automation underpenetration:PLI scheme incentives for electronics manufacturing are attracting greenfield facility investments requiring full-stack IoT engineering from design through managed services.
- Digital twin convergence with physics simulation:Combined deployment of asset virtualization and finite element analysis is opening premium service tiers for aerospace and energy equipment manufacturers.
- Subscription-based managed services:Multi-year remote monitoring contracts with predictive analytics overlays are displacing transactional integration projects in United States utility networks.
Industry Challenges
- Embedded systems security engineering scarcity:Shortage of professionals combining firmware development expertise with FDA cybersecurity guidance implementation for connected medical devices.
- Multi-jurisdictional compliance orchestration:Simultaneous adherence to FCC Part 15 radio emissions rules, GDPR data localization requirements, and Japan's METI guidelines strains project management bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IoT Engineering Services Market |
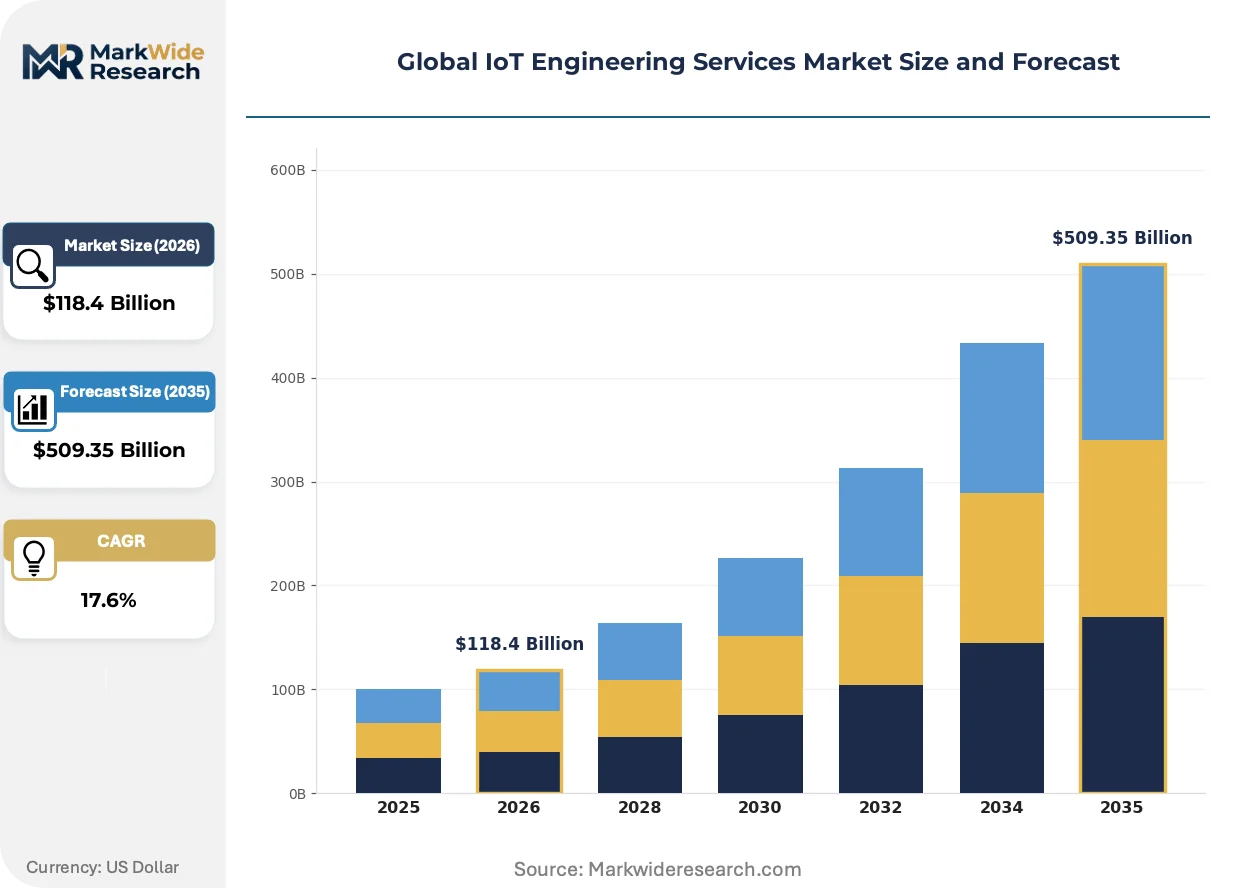
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $509.35 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing, Fog Computing Solution Offering: System Integration, Consulting, Managed Services, Custom Development, Maintenance & Support Use Case: Smart Manufacturing, Connected Transportation, Building Automation, Precision Agriculture, Energy Management End User Industry: Telecommunications, Utilities, Consumer Electronics, Government Agencies, Defense |
| Companies Covered | Tata Consultancy Services, Capgemini, Cognizant, Infosys, Accenture, IBM, Cisco Systems, Tech Mahindra, HCL Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IoT Engineering Services Market Strategic Shifts & Innovations
Digital thread architectures are collapsing traditional boundaries between design engineering, deployment, and operational optimization, enabling continuous feedback loops that reshape how industrial clients contract for technical services.
Digital twin platforms are integrating physics-based simulation with live sensor telemetry to enable predictive degradation modeling for rotating equipment in oil and gas facilities. Midstream operators in the United States are adopting these capabilities at scale to compress maintenance windows and reduce unplanned outage frequency. The technology is integrating operational and information technology domains that previously operated in organizational silos, forcing engineering service providers to restructure delivery teams around cross-functional expertise.
The EU AI Act's risk-based classification system for machine learning applications in industrial settings is mandating conformity assessments and post-market monitoring protocols. Engineering service providers must now embed algorithmic audit trails and explainability documentation into predictive maintenance solutions. German automotive manufacturers and their tier-one suppliers face the steepest compliance burden, driving consolidation of vendor relationships toward partners with demonstrated regulatory navigation capabilities.
Performance-based contracting is displacing time-and-materials arrangements for complex IoT integration projects, with payment tied to measurable uptime or efficiency improvements rather than deliverable completion. Industrial asset owners in Japan and the United States are piloting these structures for smart manufacturing deployments, transferring operational risk to service providers. This shift concentrates contract awards among engineering firms with balance sheet capacity to underwrite outcome guarantees and maintain multi-year operational commitments.
Global IoT Engineering Services Market Segmentation
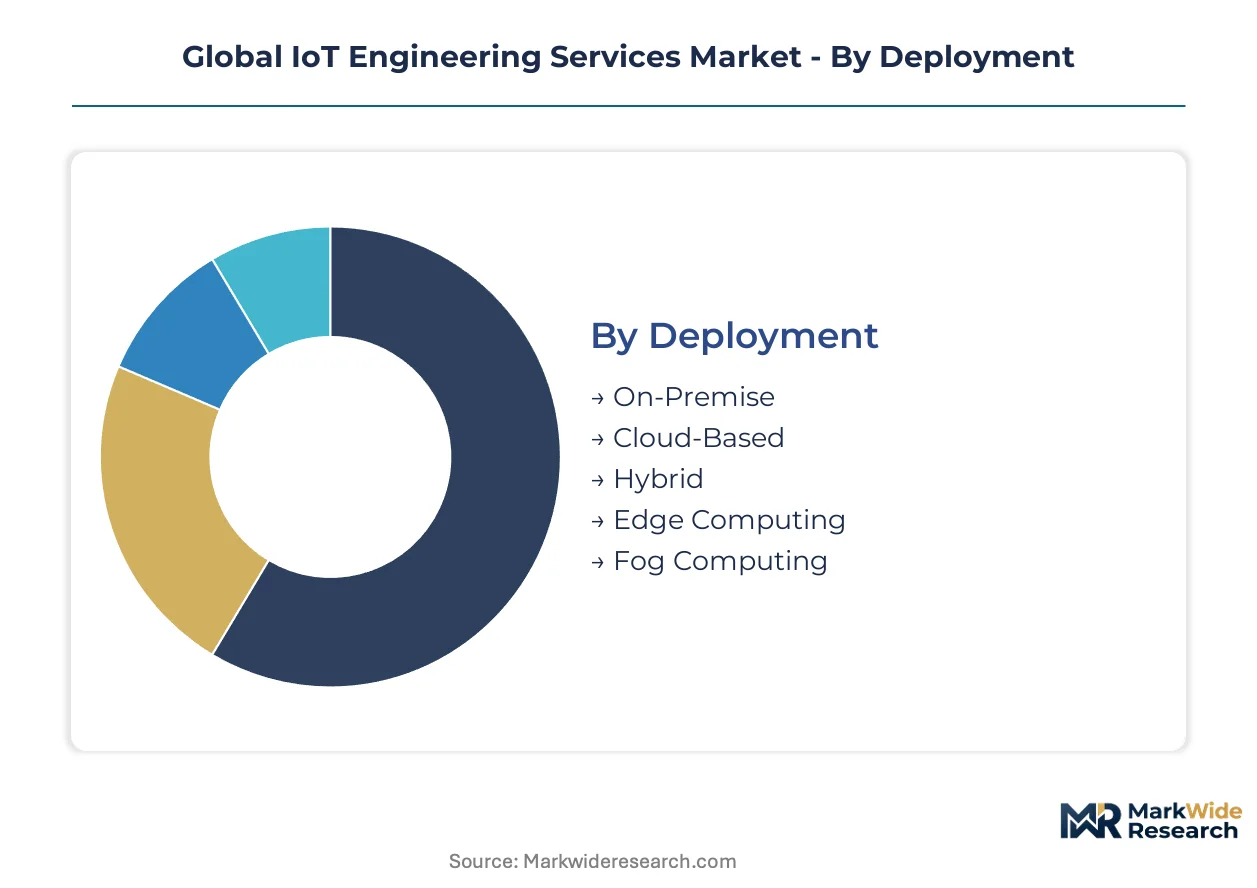
Engineering service providers structure pricing and delivery models around deployment architecture, solution depth, and vertical application. Certification requirements for EU AI Act algorithmic transparency and FDA cybersecurity guidance fragment contract economics across segments.
Deployment:
EU AI Act conformity assessments apply selectively—cloud-based architectures face GDPR data localization audits while edge computing nodes trigger FCC Part 15 radio emissions testing in United States deployments.
- On-Premise:Capital-intensive infrastructure requiring ISO 27001 certification for data center operations. German automotive manufacturers retain these deployments for proprietary design data protection despite higher total cost of ownership.
- Cloud-Based:Scalable subscription architectures with shared security responsibility models. United States utility networks are migrating monitoring workloads here to displace capital expenditure with operational expenditure structures.
- Hybrid:Workload-specific partitioning between private and public infrastructure. Japanese industrial operators favor this model for sensitive production data isolation.
- Edge Computing:Sub-50 millisecond latency nodes for real-time control. METI security-by-design protocols mandate firmware engineering validation for Japanese automotive supplier deployments.
- Fog Computing:Distributed compute layers between edge and cloud. Energy sector applications in Germany require CE marking for industrial control integration.
Leading the category by volume: Cloud-Based. Growing fastest: Edge Computing.
Solution Offering:
Margin structures diverge sharply—recurring managed services generate multi-year retention while custom development remains project-bound and price-competitive.
- System Integration:Multi-vendor technology orchestration demanding cross-protocol expertise. United States energy utilities contract these services at scale for AMI (Advanced Metering Infrastructure) consolidation.
- Consulting:Strategic advisory for IoT roadmap definition and vendor selection. German manufacturers engage these services to navigate EU AI Act risk classification for predictive maintenance algorithms.
- Managed Services:Remote monitoring with predictive analytics overlays and uptime guarantees. Japanese automotive suppliers are displacing transactional integration projects with multi-year operational contracts.
- Custom Development:Bespoke firmware and application engineering for proprietary hardware. FDA cybersecurity guidance compliance elevates costs for connected medical device engagements.
- Maintenance & Support:Post-deployment optimization and security patch management. India's electronics manufacturing PLI beneficiaries require these services for greenfield facility commissioning.
Deepest margin pool: Managed Services. Most price-pressured: Custom Development.
Use Case:
Application maturity determines contract duration—smart manufacturing commands 5-7 year managed service terms while precision agriculture remains pilot-heavy with annual renewals.
- Smart Manufacturing:Industrial asset monitoring and autonomous system coordination with digital twin integration. German automotive OEMs and tier-one suppliers represent the largest contract value concentration.
- Connected Transportation:Fleet telematics and predictive diagnostics for logistics retrofit. United States midstream operators are adopting these capabilities to compress maintenance windows.
- Building Automation:HVAC and lighting optimization through sensor network deployment. Japan's commercial real estate sector drives demand for energy efficiency compliance.
- Precision Agriculture:Soil monitoring and autonomous equipment coordination. India's agricultural technology subsidies are accelerating pilot-to-production transitions.
- Energy Management:Grid balancing and distributed generation optimization. United States utilities deploy these solutions under performance-based contracting structures.
Most mature contract structures: Smart Manufacturing. Steepest expansion trajectory: Connected Transportation.
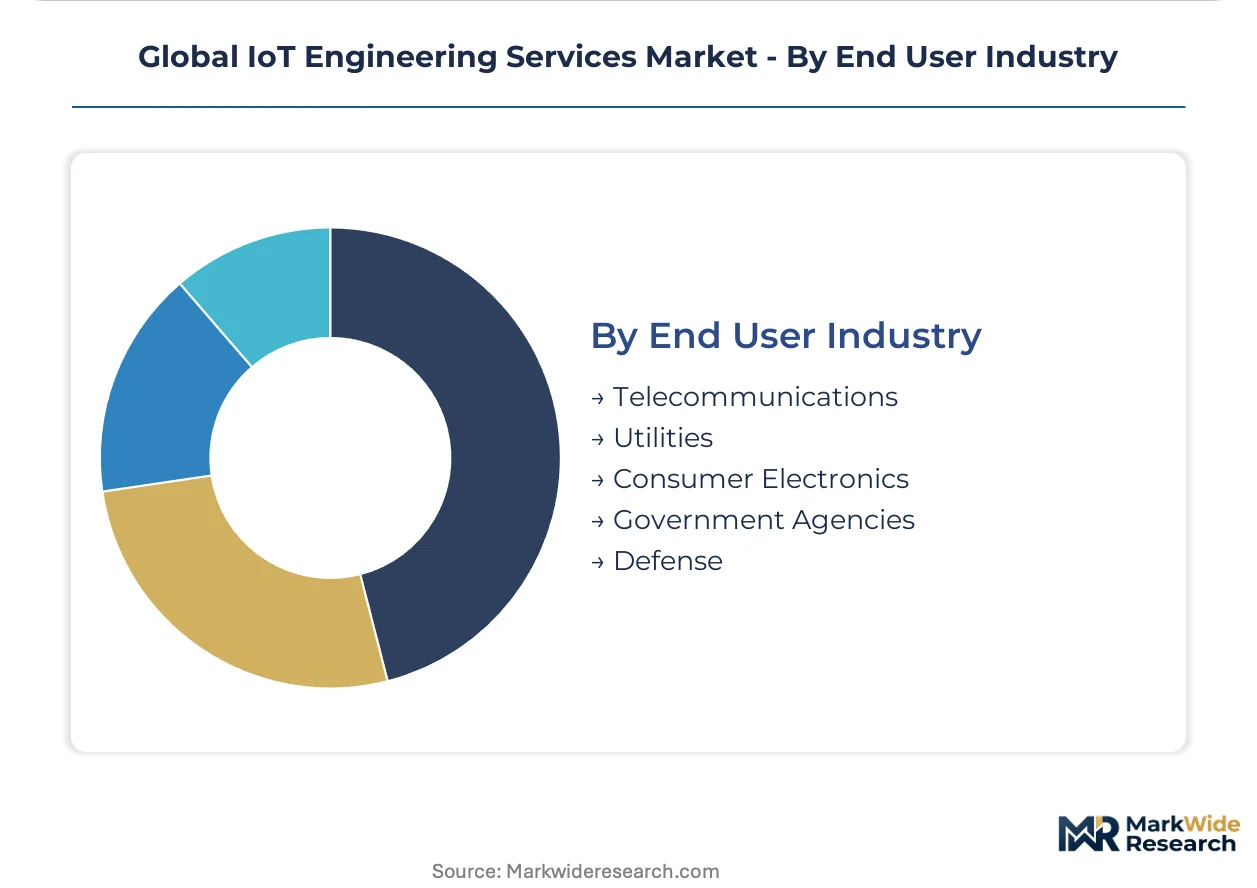
End User Industry:
Procurement sophistication varies—telecommunications carriers issue RFPs with 50+ technical criteria while government agencies prioritize domestic content requirements.
- Telecommunications:Network infrastructure monitoring and customer premise equipment management. Japanese carriers require METI IoT security guideline compliance for all vendor engagements.
- Utilities:Smart grid and AMI deployment with FERC reliability standards alignment. United States investor-owned utilities consolidate vendor relationships around systems integration scale.
- Consumer Electronics:Connected device ecosystem design and cloud platform integration. German manufacturers face EU AI Act post-market monitoring obligations for voice-enabled products.
- Government Agencies:Smart city and public infrastructure monitoring with data sovereignty requirements. India's municipal corporations are issuing tenders under national cybersecurity frameworks.
- Defense:Secure communications and battlefield asset tracking with ITAR/EAR export control constraints. United States primes require cleared personnel for subsystem engineering.
Largest average contract value: Telecommunications. Fastest procurement cycle acceleration: Utilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors industrial IoT engineering demand through Germany's automotive manufacturing corridor, where tier-one suppliers deploy edge computing nodes for real-time quality control. The EU AI Act's algorithmic transparency mandates are reshaping service procurement across European industrial clusters.
Germany
Automotive OEMs in Baden-Württemberg and Bavaria drive predictive maintenance system deployments requiring EU AI Act conformity assessments. The country's Federal Motor Transport Authority enforces strict validation protocols for connected vehicle systems. Munich-based engineering centers specialize in digital twin integration for aerospace equipment manufacturers.
United States
Utility networks across Texas and California are migrating AMI workloads to cloud architectures under FERC reliability standards. The FCC's Part 15 rules govern unlicensed radio emissions testing for edge device deployments. Houston midstream operators adopt fleet telematics to compress maintenance windows in petrochemical corridors.
Japan
Automotive suppliers in Aichi Prefecture face METI IoT security-by-design mandates for connected industrial assets. The Ministry of Economy, Trade and Industry requires firmware engineering validation for production equipment. Toyota City suppliers consolidate vendor relationships around multi-year managed service contracts with predictive analytics overlays.
India
Electronics manufacturing clusters in Karnataka and Tamil Nadu absorb full-stack IoT engineering for greenfield PLI scheme facilities. The Bureau of Indian Standards issues cybersecurity framework compliance requirements for industrial internet platforms. Bengaluru technology parks attract systems integration contracts for semiconductor fabrication equipment monitoring.
China
Industrial internet platforms in the Yangtze River Delta comply with GB/T standards for equipment connectivity and data interoperability. The Ministry of Industry and Information Technology enforces dual carbon goals through energy management system mandates. Shanghai manufacturing zones deploy edge computing nodes for sub-50 millisecond latency control applications.
Global IoT Engineering Services Market Key Industry Players
Capital-heavy systems integrators compete with asset-light consulting specialists for contract economics in IoT engineering services. The vendor base stratifies across three tiers: global technology conglomerates with balance sheet capacity for performance guarantees, mid-scale regional specialists with vertical industry depth, and boutique firmware engineering shops serving medical device certification requirements. Dominant competitive moves include M&A for regulatory compliance capabilities and strategic partnerships to bridge OT-IT integration gaps.
Within the global technology tier, Tata Consultancy Services and Accenture occupy positions shaped by automotive and energy vertical anchoring respectively. IBM sits within the analytics-specialist archetype through Watson IoT platform integration. These three exemplify how scale-driven players structure multi-year managed service contracts around recurring revenue pools rather than capital project milestones.
| Leading Market Players |
|---|
| Tata Consultancy Services |
| Capgemini |
| Cognizant |
| Infosys |
| Accenture |
| IBM |
| Cisco Systems |
| Tech Mahindra |
| HCL Tech |
| Others |
Cost & Logistics Intelligence
EU Cybersecurity Act certification gates qualified supply access and premium-tier pricing power, forcing engineering service providers to absorb compliance costs or pass them to buyers seeking algorithmic transparency guarantees under the EU AI Act. Tier-one automotive manufacturers in Germany pay sustained premiums for validated firmware engineering while price-sensitive industrial operators in India prioritize PLI-scheme subsidized domestic delivery.
Pricing Analysis
Outcome-based pricing tied to uptime guarantees and predictive maintenance yield anchors contract structures for United States utility networks and Japanese automotive suppliers. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade—EU AI Act conformity assessments command top rates, ISO 27001 middle tiers, and uncertified project work bottom rates. Cost compression in the custom development tier is intensifying because FDA cybersecurity guidance implementation requires scarce embedded systems security engineers. Procurement teams at German automotive OEMs exhibit lowest price sensitivity due to regulatory non-compliance exposure, while India's greenfield electronics manufacturers negotiate aggressively on systems integration fees.
Supply Chain Analysis
CE marking and FCC Part 15 radio emissions certification gate supplier qualification, concentrating qualified hardware-integrated service delivery among providers with established testing laboratory relationships. Semiconductor component supply draws from Taiwan, South Korea, and Japan for discrete sensors and microcontrollers essential to edge computing node deployment. Single-source vulnerability in advanced microcontroller fabrication creates procurement risk for sub-50 millisecond latency control applications. Distribution runs through direct enterprise sales for managed services contracts, while systems integration projects route via systems integrator and OEM channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded systems security engineering scarcity props pricing for certified service tiers, creating supply-constrained contract economics that favor incumbents with established training pipelines and university partnerships.
For Market Incumbents: Anticipate margin compression from boutique firmware engineering shops acquiring medical device certification capabilities by locking multi-year exclusive supplier agreements with Japanese automotive tier-ones. Vertical integration into semiconductor procurement through direct foundry relationships mitigates Taiwan supply concentration risk for edge computing hardware-integrated deliverables.
For New Entrants and Emerging Players: Launch via cloud-native managed services subscriptions targeting India's PLI-scheme electronics manufacturing clusters where full-stack engineering demand outruns established provider capacity. Precision agriculture in India offers the most penetrable application vertical, with annual renewal pilot structures allowing proof-of-concept entry before smart manufacturing competition.
For Investors and Strategic Acquirers: Consolidation of EU AI Act compliance capabilities among mid-scale regional specialists is the leading indicator that regulatory navigation expertise is becoming a scarce acquisition target. The 5-10 year viability window favors engineering firms with demonstrated algorithmic audit trail implementation and post-market monitoring infrastructure. Watch for METI guideline reciprocity negotiations with EU Cybersecurity Act frameworks as the signal for cross-border delivery center optimization plays.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Compliance Capability Acquisition | EU AI Act algorithmic transparency mandates concentrate vendor relationships toward certified providers. |
| Edge Computing Node Deployment Scale-Up | Sub-50 millisecond latency requirements in German automotive facilities drive sensor network redesign demand. |
| Managed Services Subscription Conversion | United States utility networks displace transactional projects with multi-year remote monitoring contracts. |
| India Delivery Center Expansion | PLI scheme greenfield investments in Karnataka and Tamil Nadu absorb full-stack engineering capacity. |
| Digital Twin Platform Integration | Aerospace equipment manufacturers in Munich pay premium rates for physics-simulation convergence services. |
Research Approach
Multi-period observation of industrial automation investment flows, regulatory certification timelines, and edge computing deployment metrics anchored the trend analysis, supplemented by interviews with IoT platform engineering directors, automotive procurement leads, utility AMI program managers, and medical device regulatory affairs specialists. Secondary validation drew from SEC 10-K filings of systems integrators, EU AI Act implementation guidance documents, METI IoT security guideline updates, and Bureau of Indian Standards framework notifications. Bottom-up project pipeline aggregation and top-down industrial automation spend estimates were triangulated to constrain forecast variance.
Segment-weighting across deployment architecture, solution offering depth, use case maturity, and end-user industry procurement sophistication shaped the analytical framework over the projection horizon. Deployment models distinguished capital-intensive on-premise from scalable cloud-based and latency-critical edge computing configurations. Solution offerings weighted recurring managed services against project-bound custom development. CAGRs were derived from fitted growth curves against observed industrial automation spend patterns and regulatory compliance cost trajectories. Forecast inputs included semiconductor lead time volatility indices and cross-border certification reciprocity negotiation status.
Semiconductor supply disruption, EU AI Act enforcement variance across member states, and METI guideline reciprocity delays are the dominant revision risks to modeled outcomes. A model refresh is warranted upon material change in edge computing hardware availability or algorithmic transparency audit requirement scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
North America IoT Device Market
Internet of Things (IoT)
Lora and Lorawan IoT Connectivity Market
Internet of Things (IoT)
Global Embedded Security for Internet of Things Market
Internet of Things (IoT)
Global Narrowband IoT Market
Internet of Things (IoT)
Asia-Pacific Massive IoT Market
Internet of Things (IoT)
Solar Based Internet of Things (IoT) Market
Internet of Things (IoT)
IoT Market
Internet of Things (IoT)
Internet of Things (IoT) Connected Cars Market
Internet of Things (IoT)
IoT Platform Market
Internet of Things (IoT)
IoT Network Management Market
Internet of Things (IoT)
IoT Software Engineering Market
Internet of Things (IoT)
Smart Pool Systems Market
Internet of Things (IoT)
IIOT Gateway for Utility Market
Internet of Things (IoT)
IoT Integration Services Market
Internet of Things (IoT)
Massive Machine Type Communication Market
Internet of Things (IoT)
Narrowband IoT Enterprise Application Market