
 Consumer Internet of Things (IoT) Market | 2026-2036
Consumer Internet of Things (IoT) Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Internet of Things (IoT) Market Insights
Gallium nitride is realigning power management economics across consumer IoT hardware by shrinking adapter footprints and cutting thermal overhead. Samsung Electronics leverages in-house semiconductor foundries to control GaN supply for its SmartThings ecosystem. Amazon anchors cloud-to-edge latency through custom silicon in Echo and Ring devices. Xiaomi competes on manufacturing scale, pumping out connected appliances at cost points Western rivals struggle to match.
Consumer Internet of Things denotes networked physical objects embedded with sensors, actuators, and connectivity modules—typically operating on 2.4 GHz Wi-Fi, Bluetooth 5.0, or sub-GHz mesh protocols—that exchange data with cloud platforms and user interfaces to automate environmental control, health tracking, or security monitoring. Smart home devices command the largest installed base though health monitoring devices capture margin pools through recurring subscription attach rates; wearable technology sits in a maturing phase as fitness tracking commoditizes while cellular-enabled watches gain traction. Bluetooth dominates short-range pairing for wearables and health peripherals, yet Zigbee and Thread are displacing legacy Wi-Fi in whole-home automation backbones where mesh resilience matters.
FCC Part 15 rules in the United States govern unlicensed radio emissions from IoT transmitters, while the EU AI Act and GDPR impose algorithmic transparency and data minimization duties on connected products processing biometric or behavioral signals. Japan's METI enforces JIS standards for interoperability and cybersecurity labeling of home networking equipment. Stakeholders must track how fragmented national certification regimes fragment go-to-market timelines and prioritize modular hardware architectures that can absorb regional radio and encryption variations without full redesigns.
Market Dynamics
Matter protocol standardization is dismantling interoperability barriers that historically locked consumers into single-vendor ecosystems, while GaN semiconductor adoption compresses power adapter form factors and thermal budgets across device categories.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements for biometric data processing are forcing manufacturers to invest in edge-AI architectures that reduce cloud dependency and latency.
- Sub-GHz mesh protocol deployment:Thread and Zigbee networks are penetrating whole-home automation backbones where Wi-Fi congestion previously limited reliability.
- Health monitoring hardware bundling:Ecosystem players in China are attaching connected medical peripherals to smartphone and appliance purchases at mass-market price points.
Market Restraints
- GaN wafer supply concentration:Foundry capacity for gallium nitride power semiconductors remains concentrated among Asian substrate suppliers, creating input cost volatility for adapter manufacturers.
- FCC Part 15 certification friction:Unlicensed radio emission testing requirements in the United States extend product launch timelines by four to six months for multi-protocol devices.
- Bluetooth beacon saturation:Dense urban RF environments are degrading pairing reliability for wearables, creating performance ceilings that Wi-Fi Direct cannot economically address.
Strategic Opportunities
- Cellular-enabled wearable transition:eSIM integration in smartwatches is opening subscription revenue pools as fitness tracking commoditizes and users seek standalone connectivity.
- India BIS certification pathway:Mandatory cybersecurity labeling for home networking equipment creates first-mover advantages for compliant foreign manufacturers.
- Matter-over-Thread convergence:Unified application-layer protocols are enabling cross-brand automation scenarios that were technically impossible under proprietary hub architectures.
Industry Challenges
- Embedded systems security engineering talent:Firmware hardening against side-channel attacks requires specialized skill sets that command premium compensation in tight labor markets.
- Multi-regional radio module integration:Modular hardware architectures must absorb variations in sub-GHz frequency allocations without full mechanical redesigns for each certification regime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Internet of Things (IoT) Market |
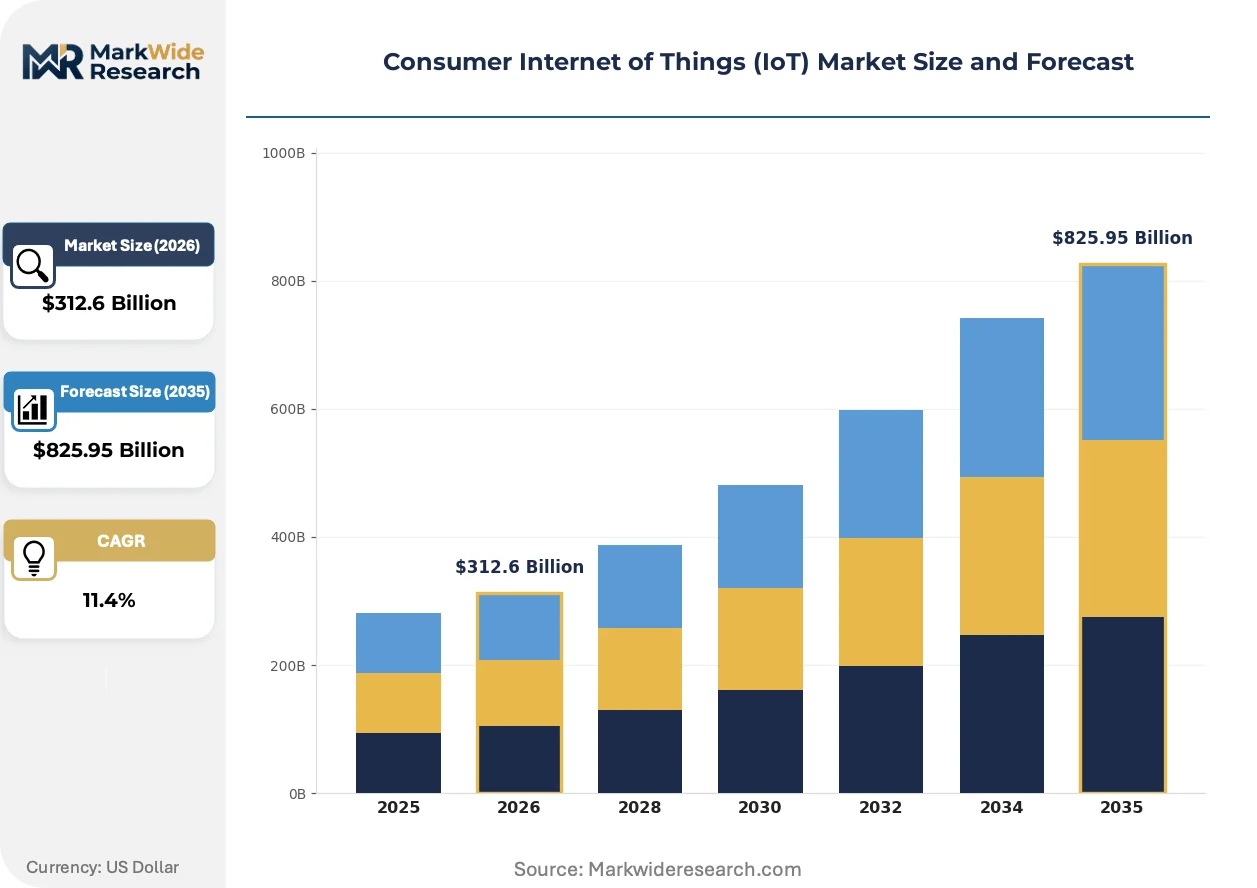
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $825.95 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Home Devices, Wearable Technology, Connected Appliances, Health Monitoring Devices Technology: Bluetooth, Wi-Fi, Zigbee, Cellular Application: Home Automation, Health & Fitness, Smart Cities, Asset Tracking End User: Consumers, Retailers, Healthcare Providers, Urban Planners |
| Companies Covered | Samsung Electronics, Xiaomi, Amazon, Netgear, TP-Link, Google, Philips, Belkin, Apple, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Internet of Things (IoT) Market Trends and Innovations
Edge-AI inference is migrating from cloud data centers to device-local silicon, while regulatory pressure on biometric data handling accelerates privacy-preserving computation architectures.
Thread mesh networking is overtaking legacy Wi-Fi as the backbone protocol for whole-home automation. The protocol operates at sub-GHz frequencies with self-healing topology. Residential integrators are specifying Thread for new construction projects. This shift is compressing BOM costs by eliminating dedicated hub hardware.
GDPR data minimization mandates are forcing architectural changes in voice assistant platforms. Manufacturers must now process wake-word detection locally rather than streaming ambient audio. Smart speaker and security camera segments are responding with dedicated neural processing units that handle biometric classification without cloud exposure.
Subscription attach rates are displacing hardware margin capture as the primary revenue model in health monitoring. Device vendors are unbundling continuous glucose monitoring and sleep staging analytics from initial purchase prices. This pivot is most visible in North American and Western European markets where insurance reimbursement pathways exist for remote patient monitoring.
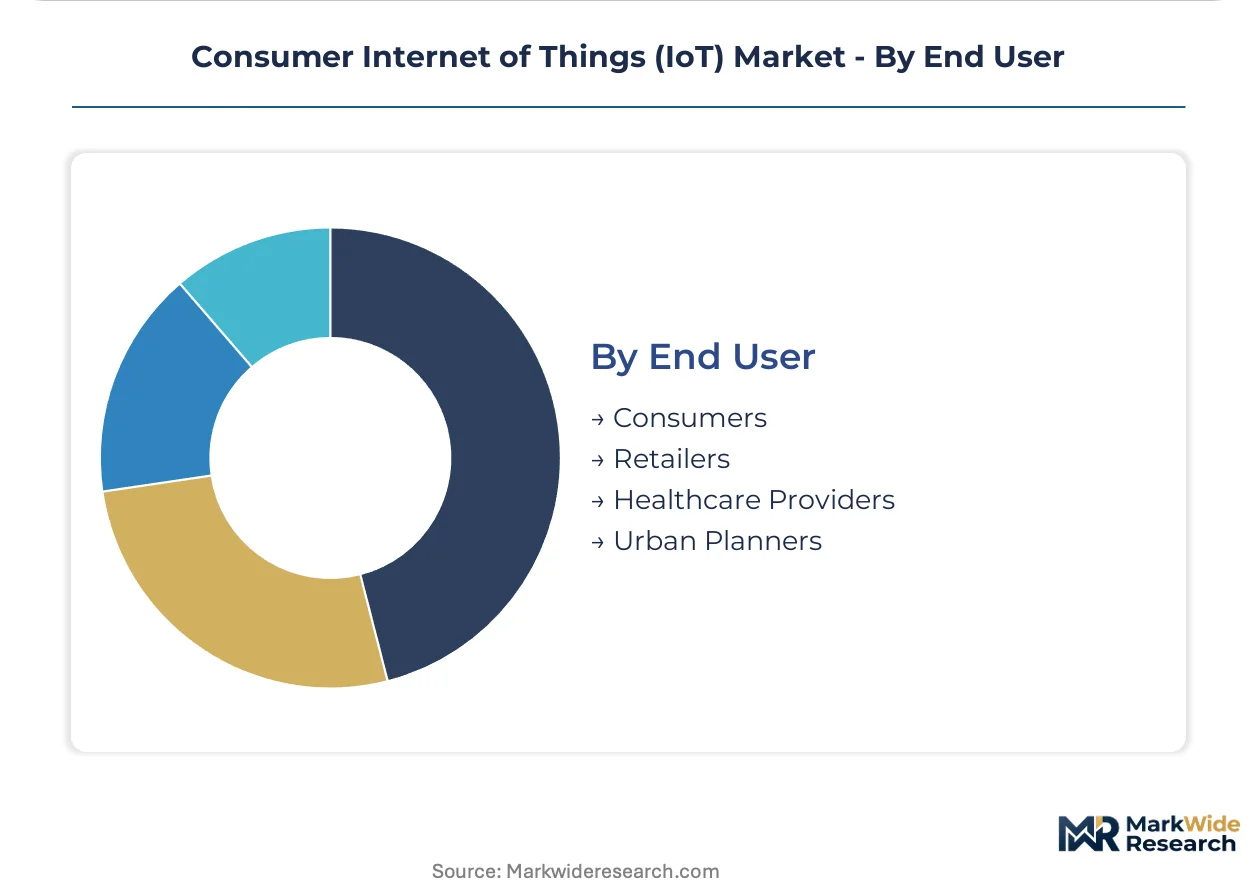
Consumer Internet of Things (IoT) Market Segmentation
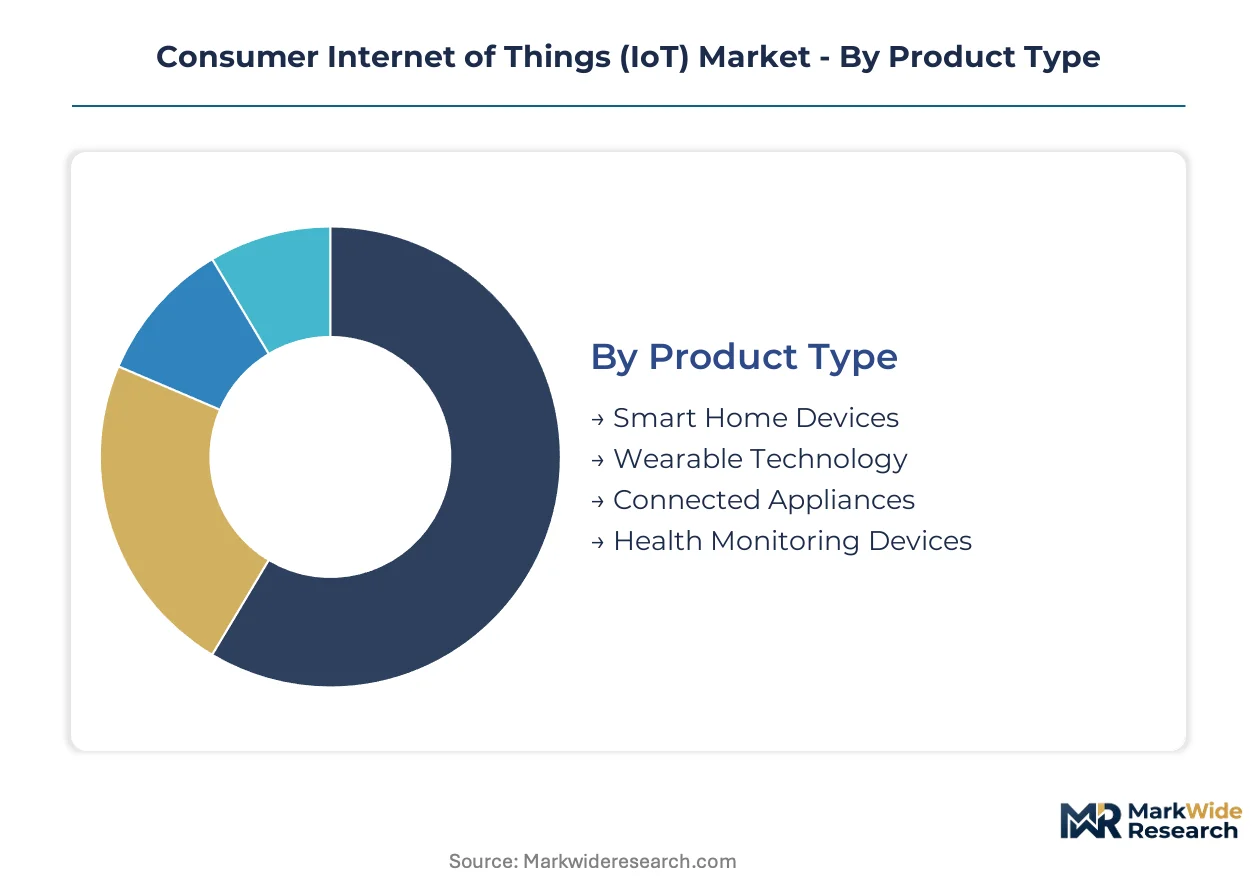
Consumer IoT purchasing decisions hinge on interoperability assurance and ecosystem lock-in risk. Buyers weigh protocol compatibility against subscription attach rates and hardware refresh cycles. Segmentation reveals where margin pools concentrate versus where volume manufacturing scales.
Product Type:
Residential buyers prioritize ecosystem coherence over single-device performance when allocating connected home budgets.
- Smart Home Devices:Hubs, lighting controllers, and climate systems operating on Matter-over-Thread backbones. Demand clusters in North American new construction where builders pre-specify whole-home automation packages to reduce callback warranty exposure.
- Wearable Technology:Fitness bands and smartwatches with biometric sensors. China dominates manufacturing volume through Shenzhen ecosystem suppliers, though cellular-enabled watches with eSIM integration are gaining share fastest in Western European insurance-reimbursed wellness programs.
- Connected Appliances:Refrigerators, ovens, and laundry units with cloud-connected diagnostics. White-goods manufacturers embed Wi-Fi modules primarily for predictive maintenance telemetry and consumable replenishment triggers.
- Health Monitoring Devices:Continuous glucose monitors, blood pressure cuffs, and sleep staging hardware. Subscription unbundling of analytics from hardware purchase is restructuring revenue capture toward recurring clinical data services.
Smart Home Devices lead on scale; Health Monitoring Devices lead on momentum.
Technology:
Protocol selection determines power budget, range, and cloud dependency architecture for device engineers.
- Bluetooth:Short-range 2.4 GHz protocol dominating wearables and health peripheral pairing. Dense urban RF saturation in Tokyo and New York is degrading beacon reliability, pushing manufacturers toward LE Audio and Auracast broadcast topologies.
- Wi-Fi:High-throughput 2.4/5 GHz connectivity for cameras and streaming devices. Congestion in multi-dwelling units is ceding whole-home automation backbone share to mesh alternatives.
- Zigbee:Sub-GHz mesh protocol with self-healing topology. Thread convergence through Matter standardization is preserving Zigbee installed base while constraining greenfield deployment growth.
- Cellular:LTE-M and NB-IoT modules enabling standalone wearable connectivity. eSIM integration is unlocking subscription revenue pools as fitness tracking commoditizes and users seek phone-independent operation.
Bluetooth leads on installed base; Cellular climbs the fastest as standalone connectivity displaces smartphone-tethered architectures.
Application:
Use-case specificity dictates sensor fusion requirements and regulatory compliance burdens for product developers.
- Home Automation:Environmental control, security, and energy management systems. EU AI Act biometric processing mandates are forcing edge-AI migration for voice assistants and camera analytics.
- Health & Fitness:Activity tracking, sleep staging, and clinical vital sign monitoring. GDPR data minimization rules require local neural processing for wake-word and biometric classification without cloud exposure.
- Smart Cities:Street lighting, waste management, and environmental sensing infrastructure. Municipal procurement cycles and fragmented vendor certification regimes extend deployment timelines.
- Asset Tracking:Bluetooth and UWB tags for personal belongings and logistics. Ultra-wideband precision positioning is penetrating high-value item recovery applications.
Home Automation leads on revenue concentration; Health & Fitness shows steepest expansion trajectory through insurance reimbursement pathways.
End User:
Customer type determines pricing tolerance, support expectations, and procurement channel preferences.
- Consumers:Individual purchasers acquiring devices through retail and direct-to-consumer channels. Xiaomi ecosystem bundling in China drives mass-market penetration at cost points Western rivals cannot match.
- Retailers:Electronics merchants and home improvement chains curating private-label connected product assortments. Inventory risk concentrates in seasonal categories with rapid protocol obsolescence.
- Healthcare Providers:Hospital systems and clinics deploying remote patient monitoring hardware. Reimbursement coding alignment determines device procurement velocity in North American markets.
- Urban Planners:Municipal authorities specifying networked infrastructure for public service optimization. Budget cycles and multi-vendor interoperability requirements complicate specification standardization.
Consumers lead on volume; Healthcare Providers lead on margin capture through recurring service attach rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors consumer IoT manufacturing through vertically integrated electronics clusters that supply component modules to global brands. The city houses the densest concentration of Wi-Fi chipset vendors, power adapter foundries, and connected appliance assembly lines. This production gravity shapes procurement patterns for device makers across three continents.
United States
FCC Part 15 certification requirements for unlicensed radio emissions extend product launch timelines for multi-protocol devices by four to six months. The Federal Communications Commission governs 2.4 GHz and 5 GHz spectrum allocation for Wi-Fi and Bluetooth transmitters. Seattle hosts Amazon's hardware engineering operations for Echo and Ring devices, where custom silicon development targets cloud-to-edge latency reduction.
China
Xiaomi and Huawei ecosystem bundling drives mass-market penetration of connected appliances and health monitoring hardware at cost points Western rivals cannot match. MIIT enforces GB standards for cybersecurity labeling and radio equipment type approval. Shenzhen's electronics corridor supplies gallium nitride power semiconductors and Thread mesh modules to global device manufacturers.
Germany
GDPR data minimization mandates and EU AI Act biometric processing requirements are forcing edge-AI architectural migrations for voice assistants and security cameras. The Federal Network Agency regulates sub-GHz frequency allocations for Zigbee and Thread deployments. Munich clusters industrial automation vendors expanding into residential IoT through Matter protocol standardization.
Japan
METI enforces JIS standards for interoperability and cybersecurity labeling of home networking equipment, accelerating local certification for foreign manufacturers. Tokyo's dense urban RF environment degrades Bluetooth beacon reliability, pushing wearable makers toward LE Audio broadcast topologies. Osaka hosts precision component suppliers for health monitoring device sensors.
India
BIS mandatory cybersecurity labeling for home networking equipment creates first-mover advantages for compliant foreign manufacturers entering the market. The Bureau of Indian Standards governs radio equipment certification and electromagnetic compatibility testing. Bangalore clusters software engineering talent for firmware development and embedded systems security engineering.
Consumer Internet of Things (IoT) Market Competitive Landscape
Global majors compete with regional champions across protocol standardization and ecosystem lock-in dimensions. The vendor base organizes into three tiers: semiconductor-integrated hardware giants, platform-anchored cloud service providers, and contract-manufacturing scale players. Strategic archetypes include captive foundry operators controlling gallium nitride supply, ecosystem bundlers attaching devices to smartphone sales, and subscription-first health monitoring specialists. Dominant competitive moves center on Matter protocol certification racing and edge-AI silicon co-development partnerships.
Within the semiconductor-integrated tier, Samsung Electronics exemplifies captive supply chain control through in-house gallium nitride foundry operations. Xiaomi occupies a position as the archetypal ecosystem bundler, leveraging manufacturing scale in Shenzhen to compress hardware cost structures. Amazon anchors the platform-centric vector, deploying custom silicon across Echo and Ring devices to minimize cloud dependency. These three players represent distinct competitive logics: upstream component control, downstream volume manufacturing, and vertical service integration.
| Leading Market Players |
|---|
| Samsung Electronics |
| Xiaomi |
| Amazon |
| Netgear |
| TP-Link |
| Philips |
| Belkin |
| Apple |
| Others |
Pricing and Supply Chain Analysis
EU AI Act algorithmic transparency mandates gate qualified supply for premium-tier health monitoring devices, as manufacturers must invest in edge-AI silicon to access reimbursement-eligible price points in Western European markets. This regulatory filter concentrates premium pricing power among vendors with captive neural processing unit supply, while cost-optimized tiers compete on Shenzhen-sourced module economics.
Pricing Analysis
GaN wafer cost pass-through from concentrated Asian substrate suppliers is compressing adapter margins across smart home device tiers. Three-tier pricing structure across Matter-certified premium, legacy protocol standard, and unbranded economy levels separates vendors by FCC Part 15 certification investment and cloud-to-edge latency performance. Pricing pressure stems from Xiaomi ecosystem bundling in China, which anchors global floor prices for connected appliances. Healthcare providers show lowest price sensitivity due to insurance reimbursement pathways, while retail consumers in India and Southeast Asia drive volume at thin hardware margins.
Supply Chain Analysis
Reverse-logistics flows for health monitoring hardware—particularly continuous glucose monitor refurbishment and sleep sensor remanufacturing—are concentrating in Shenzhen and Dongguan facilities serving Western subscription-service vendors. GaN power semiconductors and Thread mesh modules draw from Taiwan foundry and South Korea packaging operations, with final assembly clustering in China's Pearl River Delta. Single-source vulnerability in gallium nitride substrate supply creates input cost volatility for adapter manufacturers. Distribution runs through Amazon and Alibaba platform ecosystems for direct-to-consumer channels, while healthcare provider procurement flows through GPO and hospital system contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU AI Act compliance costs in Germany and manufacturing scale economies in China, where Shenzhen production clusters absorb regulatory investment through volume amortization.
For Market Incumbents: Lock in Matter protocol certification racing to defend hub architecture revenue against Thread-native entrants. Captive gallium nitride foundry supply secures adapter margin pools threatened by substrate cost volatility. Edge-AI silicon co-development partnerships with Taiwan semiconductor vendors reduce cloud dependency exposure under GDPR data minimization mandates.
For New Entrants and Emerging Players: Rural healthcare providers in India represent the most penetrable buyer archetype, as BIS cybersecurity labeling creates first-mover advantages against delayed Western compliance. White-space targets include cellular-enabled wearable standalone connectivity for phone-independent operation, and Matter-over-Thread retrofit controllers for legacy Wi-Fi installations. Go-to-market through telecom eSIM bundling bypasses retail channel concentration.
For Investors and Strategic Acquirers: Roll-up economics work for health monitoring subscription-platform specialists because insurance reimbursement coding alignment creates sticky recurring revenue pools with low customer acquisition cost replication. Five-to-ten year viability hinges on FDA and CE marking pathway execution for clinical-grade biometric classification. Monitor EU AI Act enforcement variance across member states as inflection indicator for edge-AI architecture investment returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Cross-brand interoperability unlocks smart home device replacement cycles previously locked in proprietary hubs. |
| Edge-AI Silicon Development | Local neural processing units satisfy GDPR biometric data rules without cloud exposure penalties. |
| Cellular eSIM Integration | Standalone wearable connectivity captures subscription revenue as fitness tracking commoditizes. |
| GaN Supply Captivity | In-house gallium nitride foundry control insulates adapter margins from Asian substrate volatility. |
| Healthcare Reimbursement Alignment | FDA and CMS coding pathways transform hardware sales into recurring clinical data service contracts. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with smart home platform engineers, health monitoring device product managers, FCC certification consultants, and hospital procurement officers with secondary validation. Regulatory filings with the FCC, EU AI Act implementation guidance, MIIT GB standard updates, and BIS cybersecurity labeling circulars anchored bottom-up triangulation against top-down market sizing.
Segment-weighting across product type, connectivity protocol, and application dimensions drove analytical framework construction over the projection horizon. Smart home devices, wearable technology, connected appliances, and health monitoring hardware each carried distinct growth trajectories derived from installed base expansion and subscription attach rate modeling. Matter protocol adoption curves, GaN semiconductor cost trajectories, and insurance reimbursement pathway penetration served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; health monitoring devices with established FDA clearance pathways carry tighter precision than emerging Matter-certified product categories. Forecasts reflect documented assumptions regarding regulatory enforcement timing and protocol standardization velocity. Practitioners should monitor EU AI Act biometric processing guidance releases and FCC Part 15 testing backlog reports for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Airline IoT Market
Internet of Things (IoT)
UK IoT Software Market
Internet of Things (IoT)
Wireless Connected Devices Market
Internet of Things (IoT)
IoT Lpwans Market
Internet of Things (IoT)
Global Machine-To-Machine (M2M) Connections Market
Internet of Things (IoT)
IoT in Retail Market
Internet of Things (IoT)
IoT at Workplace Market
Internet of Things (IoT)
Internet of Things (IoT) in Healthcare Market
Internet of Things (IoT)
Internet of Things (IoT) Platform Market
Internet of Things (IoT)
Global Internet of Things (IoT) Software Market
Internet of Things (IoT)
Europe Industrial IoT Market
Internet of Things (IoT)
Industrial IoT Platform Market
Internet of Things (IoT)
Smart Connected Device Market
Internet of Things (IoT)
Global Open IoT Platform Market
Internet of Things (IoT)
IoT Data Management Market
Internet of Things (IoT)
Maritime Internet of Things Market