
 Global IoT Connectivity Market | 2026-2036
Global IoT Connectivity Market Size, Share, and Industry Trends Forecast 2026-2036
Global IoT Connectivity Market Foresight
Chinese module manufacturers is restructuring supply chains as domestic chip fabrication expands. Cisco leverages its enterprise networking installed base to dominate industrial gateway deployments. Sierra Wireless anchors North American cellular LPWA through carrier-certified module portfolios. Telit competes in Europe with vertically integrated hardware-to-cloud stacks.
IoT connectivity encompasses the protocols, infrastructure, and managed services that enable machine-to-machine data exchange across distributed sensor networks, typically operating at latency thresholds below 100 milliseconds for real-time control applications. Cellular LPWA and satellite connectivity command premium pricing in remote asset tracking where terrestrial infrastructure fails, while Wi-Fi and Bluetooth segments face margin compression from commoditized consumer-grade chipsets. Managed services and platform-as-a-service offerings capture disproportionate value as manufacturing plants and utilities providers outsource network operations complexity rather than building in-house competencies.
The FCC in the United States governs spectrum allocation for unlicensed IoT bands, while the EU AI Act and GDPR impose algorithmic transparency and data residency requirements on connected device ecosystems. Japan's METI drives industrial IoT standardization through its Connected Industries framework, shaping procurement specifications for regional manufacturers. Stakeholders must weigh sovereign cloud mandates against cross-border platform economics when selecting infrastructure partners.
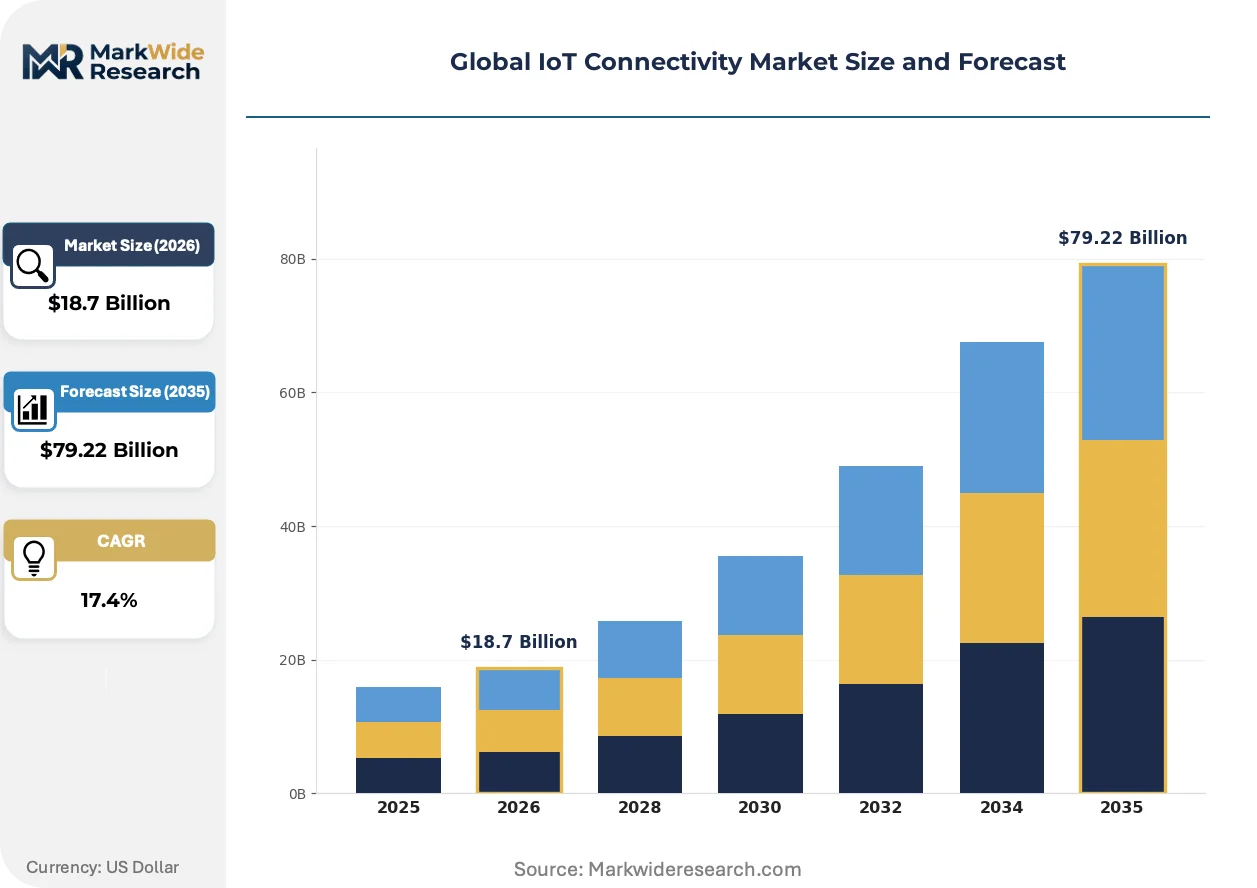
Market Dynamics
The EU AI Act and GDPR compliance obligations are forcing platform providers to embed privacy-by-design architectures, restructuring how connectivity stacks handle data residency and algorithmic transparency across distributed sensor networks.
Growth Catalysts
- Cellular LPWA mandates:Automotive OEMs in Germany face expanding connected vehicle regulations that require real-time telemetry transmission. This pulls demand for low-power wide-area modules into production lines.
- Industrial IoT clusters:Machinery manufacturers in Stuttgart and Munich are deploying private 5G networks for sub-100 millisecond control applications. Factory automation drives module procurement at scale.
- EU Green Deal integration:Energy utilities must report carbon intensity across distributed assets. Satellite-connected sensors enable remote monitoring of transmission infrastructure where terrestrial coverage fails.
Market Restraints
- Semiconductor supply concentration:Domestic chip fabrication in China is restructuring supply chains, creating friction for non-Chinese module vendors seeking cost-competitive silicon.
- Input cost volatility:Lithium and rare earth price swings directly impact battery-dependent cellular module economics, compressing margins on low-end LPWA devices.
- Regulatory fragmentation:Japan's METI Connected Industries framework diverges from EU standardization, forcing dual-certification investments for vendors serving both markets.
Strategic Opportunities
- Underpenetrated satellite-terrestrial convergence:Remote asset tracking in Brazilian agriculture and Australian mining presents white space where hybrid connectivity bundles command premium positioning.
- Regulatory tailwind from CSRD:EU corporate sustainability reporting mandates require granular supply chain visibility. This creates pull for sensor-to-cloud platforms with embedded audit trails.
- Edge-AI integration:Convergence of on-device inference with 5G slicing enables predictive maintenance applications. Manufacturing plants in South Korea are piloting this architecture for semiconductor fabrication equipment.
Industry Challenges
- Embedded systems security expertise gap:Platform providers struggle to recruit firmware engineers capable of implementing hardware-rooted trust architectures mandated by GDPR and EU AI Act requirements.
- Multi-protocol certification timelines:Modules requiring simultaneous PTCRB, GCF, and regional carrier approvals face 14-18 month validation cycles, delaying revenue recognition.
- Legacy SCADA integration friction:Utilities and manufacturing plants with decades-old control systems encounter protocol translation complexity when overlaying IP-based IoT connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IoT Connectivity Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $79.22 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Connectivity Type: Cellular LPWA, Satellite, Wi-Fi, Bluetooth, Zigbee, Ethernet Solution Offering: Managed Services, Platform as a Service, Network as a Service, Security Solutions, Analytics Solutions, Device Management Use Case: Smart Cities, Precision Farming, Asset Tracking, Energy Management, Environmental Monitoring, Smart Metering Customer Type: Manufacturing Plants, Smart Buildings, Transportation Operators, Retail Chains, Utilities Providers, Logistics Firms |
| Companies Covered | Verizon, Arm, Sierra Wireless, Spectrum, Samsara, Semtech, Cisco, PTC, Telit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IoT Connectivity Market Shifts & Advancements
Private 5G networks and edge-native architectures are actively restructuring how industrial buyers procure connectivity, shifting from carrier-managed subscriptions toward in-house spectrum ownership and distributed compute.
RedCap (Reduced Capability) 5G is electrifying industrial sensor deployments by stripping non-essential bandwidth for cost-sensitive monitoring applications. Automotive Tier-1 suppliers in Germany are adopting RedCap modules for predictive maintenance on welding robots. This technology is compressing the price-performance gap between LTE-M and full 5G, enabling mass deployment of video-capable sensors without premium cellular economics.
The EU AI Act's risk-based classification system is mandating algorithmic transparency logs for high-stakes IoT applications. Industrial gateway vendors must now embed explainability features into edge analytics stacks. Automotive and healthcare device manufacturers face the steepest compliance burden, with German OEMs restructuring procurement specifications to exclude black-box AI components from connected vehicle subsystems.
Outcome-based network service contracts are displacing traditional per-module pricing in manufacturing verticals. German machinery clusters now demand guaranteed latency SLAs rather than hardware ownership, shifting vendor relationships toward performance-guaranteed managed services. This pattern is most visible in Stuttgart's automotive supplier ecosystem, where plant operators outsource end-to-end connectivity operations to platform specialists.
Global IoT Connectivity Market Segmentation
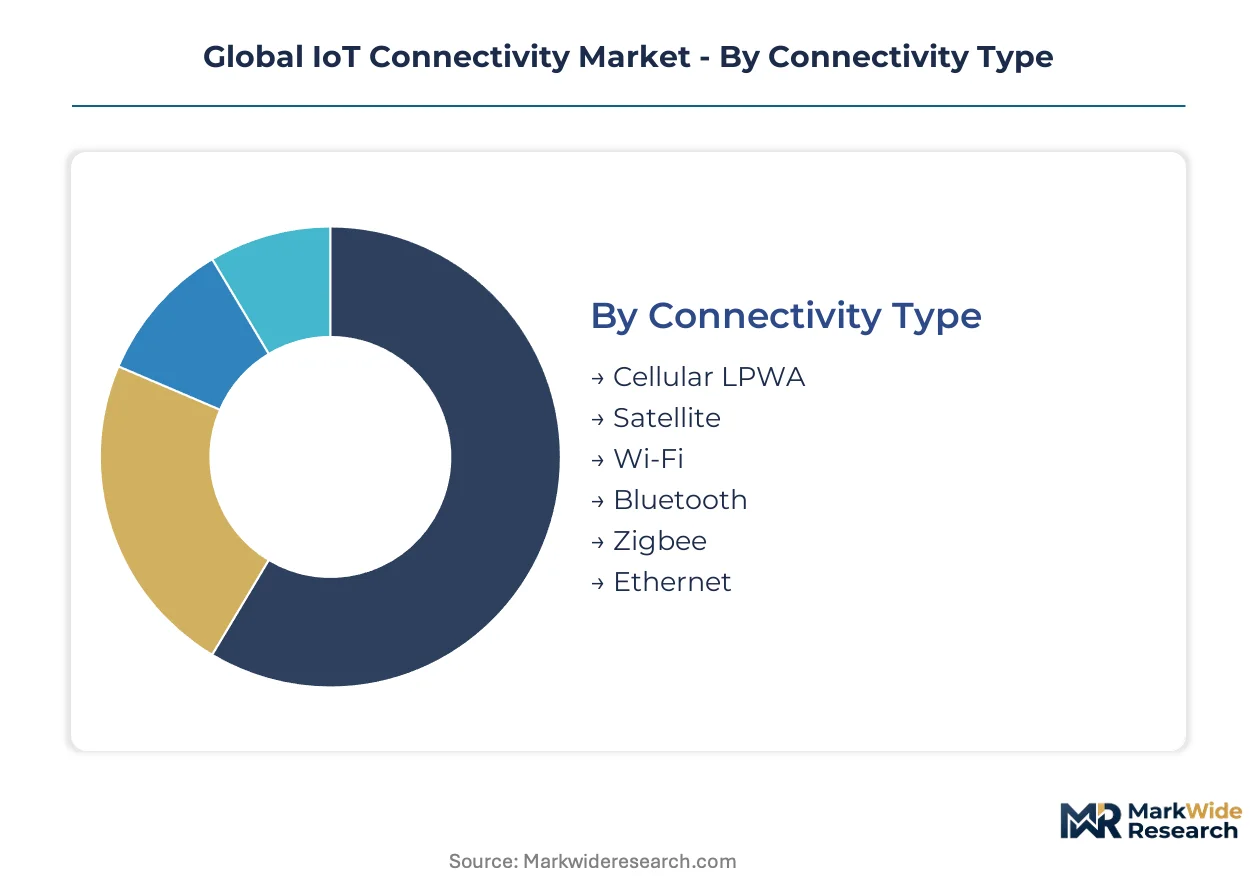
IoT connectivity procurement decisions pivot on certification complexity, latency requirements, and operational ownership models. Segmentation reveals how vendor portfolios align with divergent buyer risk appetites and infrastructure maturity across industrial verticals.
Connectivity Type:
PTCRB and GCF certifications dominate cellular segments, while unlicensed protocols face lighter regulatory burdens but steeper interoperability testing.
- Cellular LPWA:Low-power wide-area protocols including LTE-M and NB-IoT operate in licensed spectrum with guaranteed quality-of-service. German automotive OEMs pull these modules into connected vehicle production lines to satisfy real-time telemetry mandates from regulators like KBA.
- Satellite:Non-terrestrial networks deliver coverage in Brazilian agriculture and Australian mining where cellular infrastructure fails. Hybrid satellite-terrestrial bundles command premium positioning for remote asset tracking applications requiring 99.9% uptime guarantees.
- Wi-Fi:Unlicensed 2.4 GHz and 5 GHz bands serve high-bandwidth indoor applications. Smart building deployments in South Korea leverage Wi-Fi 6 for dense sensor backhaul.
- Bluetooth:Short-range protocols dominate consumer-grade proximity sensing. Retail chains deploy Bluetooth Low Energy beacons for indoor positioning and footfall analytics.
- Zigbee:Mesh networking standard for home automation and smart metering clusters. European utilities favor Zigbee for AMI deployments requiring multi-hop reliability.
- Ethernet:Wired connectivity for factory floor control systems demanding sub-10 millisecond latency. Stuttgart machinery manufacturers specify industrial Ethernet for deterministic motion control.
Leading the category by volume: Cellular LPWA. Growing fastest: Satellite.
Solution Offering:
Margin structures diverge sharply between hardware-centric and service-led revenue models.
- Managed Services:End-to-end network operations outsourcing including monitoring, troubleshooting, and SLA enforcement. German machinery clusters in Stuttgart now demand guaranteed latency contracts rather than module ownership.
- Platform as a Service:Cloud-native connectivity middleware with API-driven device onboarding. Manufacturing plants outsource provisioning complexity to avoid building in-house DevOps competencies.
- Network as a Service:Subscription-based access to private 5G or carrier infrastructure. South Korean semiconductor fabs pilot NaaS for flexible spectrum allocation.
- Security Solutions:Hardware-rooted trust architectures and firmware encryption. GDPR and EU AI Act compliance obligations force embedded security investments.
- Analytics Solutions:Edge and cloud-based inference engines for predictive maintenance. Edge-AI integration is gaining share fastest in automotive Tier-1 supplier ecosystems.
- Device Management:Lifecycle tools for over-the-air updates and certificate rotation. Utilities with decades-old SCADA systems encounter protocol friction when overlaying IP-based management stacks.
Highest margin capture: Managed Services. Steepest expansion trajectory: Platform as a Service.
Use Case:
Application-specific latency and data residency requirements reshape procurement specifications.
- Smart Cities:Multi-protocol deployments spanning traffic sensors, air quality monitors, and public safety cameras. Barcelona and Singapore municipalities consolidate vendor relationships to reduce interoperability overhead.
- Precision Farming:Soil moisture and yield monitoring across dispersed agricultural plots. Brazilian soy producers combine satellite connectivity with cellular fallback for plantation-wide coverage.
- Asset Tracking:Real-time location systems for high-value cargo and fleet vehicles. Australian mining operators pay premiums for hybrid connectivity in remote Pilbara regions.
- Energy Management:Grid-edge optimization and demand response orchestration. EU Green Deal carbon reporting mandates pull sensor deployments into transmission infrastructure.
- Environmental Monitoring:Distributed sensors for water quality, emissions, and noise pollution. Japan's METI Connected Industries framework shapes procurement specifications for regional deployments.
- Smart Metering:AMI infrastructure for consumption tracking and dynamic pricing. German utilities accelerate rollouts to meet CSRD supply chain visibility requirements.
Deepest deployment maturity: Smart Metering. Fastest regulatory tailwind: Energy Management.
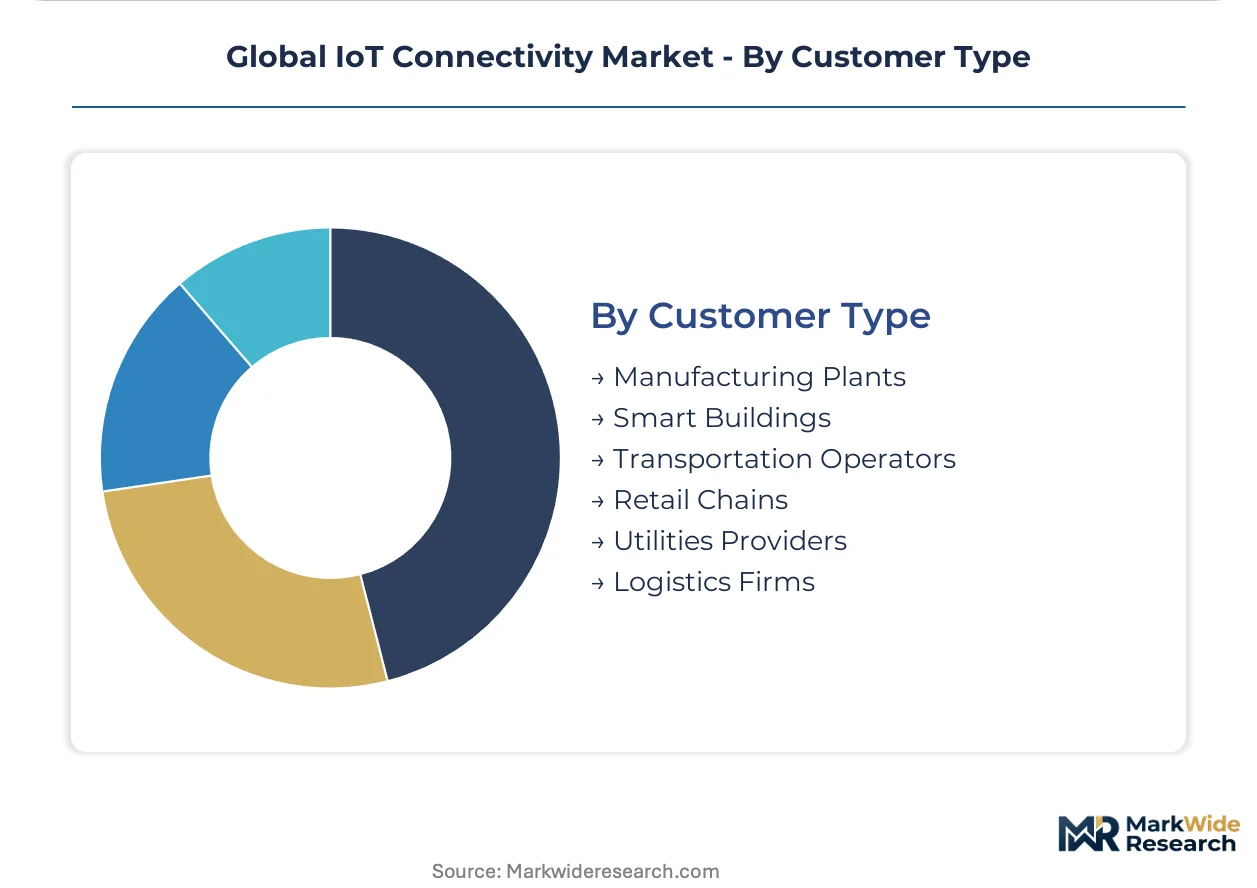
Customer Type:
Buyer sophistication and in-house technical capacity determine outsourcing willingness.
- Manufacturing Plants:Private 5G networks and edge-native architectures dominate. Munich and Stuttgart automotive suppliers adopt RedCap modules for welding robot predictive maintenance.
- Smart Buildings:Integrated BMS platforms combining HVAC, lighting, and access control. Singapore commercial real estate developers specify outcome-based energy performance contracts.
- Transportation Operators:Fleet telematics and connected vehicle infrastructure. German automotive OEMs face expanding connected vehicle regulations from KBA and EU bodies.
- Retail Chains:Inventory tracking, cold chain monitoring, and customer analytics. Dense urban deployments favor Wi-Fi and Bluetooth economics over cellular.
- Utilities Providers:Grid modernization and renewable integration. Satellite-connected sensors enable remote monitoring where terrestrial coverage fails.
- Logistics Firms:Cross-border shipment visibility and warehouse automation. 14-18 month multi-protocol certification timelines delay module procurement for global operators.
Largest contract values: Manufacturing Plants. Fastest procurement cycle compression: Transportation Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon fabrication capacity in Taiwan and South Korea anchors semiconductor supply for cellular modules. Module assembly concentrates in Shenzhen and Dongguan corridors. European automotive OEMs pull premium connectivity demand through Stuttgart and Munich industrial clusters.
United States
Verizon and AT&T operate nationwide LTE-M and NB-IoT networks serving fleet telematics and smart meter deployments. The FCC governs unlicensed spectrum allocation for 2.4 GHz and 5 GHz IoT bands. Manufacturing plants in Michigan and Ohio deploy private 5G networks for welding robot predictive maintenance.
Germany
Automotive OEMs in Stuttgart and Munich drive cellular LPWA module procurement for connected vehicle mandates. The KBA enforces real-time telemetry transmission requirements under EU vehicle type-approval frameworks. Machinery manufacturers in Baden-Württemberg operate private 5G networks for sub-100 millisecond control applications.
China
Domestic chip fabrication expansion is restructuring supply chains for cost-competitive cellular modules. MIIT standardizes industrial IoT protocols through national connected manufacturing initiatives. Module assembly clusters in Shenzhen and Dongguan serve export demand for LPWA devices.
Japan
Semiconductor fabrication equipment manufacturers pilot edge-AI integration with 5G slicing for predictive maintenance. METI drives industrial IoT standardization through its Connected Industries framework. Manufacturing plants in Nagoya and Osaka deploy sensor-to-cloud platforms with embedded audit trails.
Brazil
Soy producers in Mato Grosso and Goiás combine satellite connectivity with cellular fallback for plantation-wide coverage. ANVISA regulates connected medical device data flows under national health surveillance frameworks. Mining operators in the Carajás region pay premiums for hybrid satellite-terrestrial connectivity bundles.
Global IoT Connectivity Market Competitive Landscape
Global majors compete with regional champions across certification complexity and carrier relationship depth. The vendor base stratifies between full-stack platform providers, hardware-specialist module vendors, and carrier-managed service operators. Three archetypes dominate: enterprise networking incumbents leveraging installed base, cellular specialists with PTCRB-certified portfolios, and vertically integrated hardware-to-cloud stack providers. Competitive moves center on private 5G network deployment partnerships and edge-native architecture development.
Among North American cellular specialists, Sierra Wireless anchors carrier-certified module portfolios. Cisco represents the enterprise networking incumbent archetype. Telit occupies a position within European vertically integrated stacks. These three exemplify divergent strategic positioning across hardware depth, carrier relationships, and cloud platform integration.
| Leading Market Players |
|---|
| Verizon |
| Arm |
| Sierra Wireless |
| Spectrum |
| Samsara |
| Semtech |
| Cisco |
| PTC |
| Telit |
| Others |
Supply & Pricing Matrix
Firmware engineering talent concentration in Stuttgart and Munich creates labor-cost differentials that widen pricing-tier spreads between premium managed-service bundles and economy hardware-only modules. Platform providers with embedded security expertise command substantial premiums over commodity module vendors lacking GDPR-compliant audit architectures.
Pricing Analysis
Warranty and multi-year SLA bundling separates premium cellular LPWA offerings from unbundled hardware transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—PTCRB/GCF dual-certified modules capture margin premiums over single-protocol alternatives. Cost compression in economy Wi-Fi and Bluetooth chipsets is intensifying because Chinese domestic fabrication expands output. Manufacturing plants with private 5G deployments show least price sensitivity; retail chains deploying consumer-grade proximity sensors exhibit highest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale automotive demand in Germany while distributor networks serve fragmented smart building deployments across South Korea. Silicon supply concentrates in Taiwan and South Korea; module assembly clusters in Shenzhen and Dongguan. Rare earth and lithium inputs feed battery-dependent cellular economics. Single-source vulnerability in advanced node semiconductors creates chokepoint exposure for European gateway vendors. Distribution runs through carrier-certified partnerships in North America and vertically integrated hardware-to-cloud stacks in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor fabrication capacity constraints prop module pricing, with advanced node allocation favoring automotive OEMs over industrial sensor vendors. Supply scarcity in firmware security talent reinforces premium capture for compliant platform providers.
For Market Incumbents: Deepen carrier certification moats by accelerating PTCRB/GCF timeline compression to offset 14-18 month validation cycles threatening revenue recognition. Invest in captive edge-AI silicon design to defend against Chinese module vendors achieving cost parity through domestic fabrication expansion. Prioritize GDPR-compliant firmware architectures as regulatory enforcement intensifies.
For New Entrants and Emerging Players: The premium-to-economy pricing gap in satellite-terrestrial hybrid bundles offers entry leverage for Brazilian agriculture and Australian mining deployments where incumbent coverage remains thin. Target precision farming and remote asset tracking with outcome-based connectivity contracts rather than hardware-centric positioning. Partner with regional carriers for rapid certification rather than pursuing multi-protocol approvals independently.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated platform providers given EU AI Act compliance obligations forcing buyer consolidation toward full-stack vendors. Five-to-ten year viability favors specialists with embedded security IP and private 5G deployment credentials over pure-play hardware vendors. Monitor RedCap module adoption rates in German automotive Tier-1 supplier ecosystems as inflection signal for mass industrial sensor deployment economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Private 5G Network Deployment | Stuttgart machinery manufacturers achieve sub-100 millisecond control latency for welding robot automation. |
| Edge-AI Silicon Integration | South Korean semiconductor fabs pilot predictive maintenance with on-device inference and 5G slicing. |
| Regulatory Certification Fast-Track | Reduced PTCRB/GCF timelines enable earlier revenue recognition for cellular LPWA module vendors. |
| Satellite-Terrestrial Bundle Launch | Brazilian soy producers and Australian mining operators pay premiums for 99.9% uptime guarantees. |
| GDPR-Compliant Firmware Architecture | EU AI Act transparency mandates force automotive OEMs to exclude black-box AI from procurement specifications. |
Research Methodology
SEC filings, carrier infrastructure deployment disclosures, and EU regulatory compliance databases formed the secondary backbone for market sizing. Primary interviews with cellular module procurement directors, private 5G network engineers, and industrial IoT platform architects validated demand assumptions. Conversations with KBA regulatory specialists and METI standardization officials clarified certification timeline impacts. Bottom-up module shipment analysis triangulated against top-down connectivity service revenue estimates across the analysis window.
Historical trendline analysis of cellular LPWA adoption in German automotive production informed projection elasticity. Segmentation modeling spanned connectivity protocol, solution offering tier, use case latency requirements, and customer type sophistication. CAGRs derived from regression against connected vehicle mandate implementation schedules and CSRD reporting obligation phases. Forecast inputs incorporated RedCap module cost curves and satellite constellation capacity expansion trajectories.
Inputs from carrier network operators and semiconductor foundry customers were available through the study window; gaps in private 5G deployment run-rate data introduce uncertainty bands around manufacturing plant adoption assumptions. Forecasts reflect documented assumptions regarding EU regulatory enforcement intensity and Chinese domestic chip fabrication yield progression. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Smart Pool Systems Market
Internet of Things (IoT)
IoT Solutions Market
Internet of Things (IoT)
Internet of Things (IoT) Platform Market
Internet of Things (IoT)
Smart Sound and Gateway Market
Internet of Things (IoT)
Wi-Fi Smart Scale Market
Internet of Things (IoT)
LPWAN in the Consumer IoT Market
Internet of Things (IoT)
GCC Indoor LBS Market
Internet of Things (IoT)
Connected IoT Devices Market
Internet of Things (IoT)
IoT in Automotive Market
Internet of Things (IoT)
IoT Device Management Market
Internet of Things (IoT)
Asia-Pacific Massive IoT Market
Internet of Things (IoT)
IoT Gateway Hardware and Software Market
Internet of Things (IoT)
IoT Software Engineering Market
Internet of Things (IoT)
Middle East and Africa IoT Node and Gateway Market
Internet of Things (IoT)
IoT Platform Market
Internet of Things (IoT)
Cellular Machine to Machine Market