
 Flexible Pipes for Oil and Gas Market | 2026-2036
Flexible Pipes for Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Pipes for Oil and Gas Market Insights
API 17J qualification is redrawing competitive boundaries for composite unbonded flexible pipes. TechnipFMC sustains dominance through integrated engineering-to-installation capabilities across deepwater basins. Prysmian Group anchors European supply for high-voltage dynamic umbilical systems. National Oilwell Varco leverages aftermarket service networks to extend equipment life cycles in mature offshore provinces.
Flexible pipes for oil and gas are multi-layered conduits combining polymer barriers, steel armor wires, and anti-wear fabrics, designed to withstand internal pressures exceeding 10,000 psi while accommodating vessel motion and seabed topography. Composite product types are capturing margin pools as operators seek weight reduction for ultra-deepwater tension-leg platforms. Subsea installation types command premium positioning due to longer qualification cycles and integrated testing requirements that limit supplier entry. Flexible riser technology leads deployment volumes, though flowline systems are expanding in tieback architectures for marginal field development.
API standards, NORSOK U-001 for subsea production systems, and Brazil's ANP regulatory frameworks collectively dictate material traceability, fatigue testing protocols, and field qualification durations. These requirements compress the viable supplier base while extending contract tenures for incumbents with certified manufacturing lines. Stakeholders must weigh composite material transitions against steel-armor proven performance as field depths push equipment boundaries.
Market Dynamics
API 17J qualification requirements are compressing the supplier base for unbonded flexible pipes while deepwater operators in Brazil's pre-salt basins demand higher-pressure dynamic riser systems. This regulatory tightening concentrates certified manufacturing capacity among incumbent producers with established testing protocols.
Growth Catalysts
- Pre-salt field development:Petrobras-led projects in Brazil's Santos Basin require high-pressure dynamic riser systems for ultra-deepwater production, creating sustained demand for qualified flexible pipe manufacturers.
- API 17J specification evolution:The American Petroleum Institute's tightening composite material qualification standards are elevating technical barriers that favor suppliers with integrated engineering-to-installation capabilities.
- Tieback architecture expansion:Marginal field operators are deploying flexible flowline systems to connect subsea wells to existing host facilities, extending field economics without new platform construction.
Market Restraints
- Steel armor wire cost volatility:Input material price fluctuations for high-tensile steel wires compress margin predictability for pipe manufacturers locked into long-term frame agreements.
- Supplier concentration in Western Europe:Qualified manufacturing lines for high-voltage dynamic umbilical systems cluster among a handful of integrated energy service companies, limiting buyer negotiation leverage.
- Thermoplastic composite fatigue limitations:Unbonded flexible pipes with polymer pressure barriers face endurance testing gaps at extreme pressure-temperature combinations beyond current API validation databases.
Strategic Opportunities
- West African deepwater expansion:Emerging offshore provinces off Angola and Nigeria lack established flexible pipe supply chains, creating first-mover positioning for qualified manufacturers with local content partnerships.
- Electrification convergence:Integration of high-voltage power cables within dynamic umbilical systems combines subsea power distribution with production control, enabling all-electric subsea processing architectures.
- Brazil ANP local content incentives:Regulatory mandates for domestic manufacturing participation in pre-salt projects create joint venture pathways for technology holders seeking access to high-volume deployment programs.
Industry Challenges
- API 17J fatigue testing timelines:Extended qualification durations for new composite material formulations delay product commercialization and tie up capital in non-revenue-generating certification programs.
- Deepwater installation vessel scarcity:Specialized reel-lay and carousel vessels capable of handling ultra-long flexible pipe strings command premium day rates that inflate project economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Pipes for Oil and Gas Market |
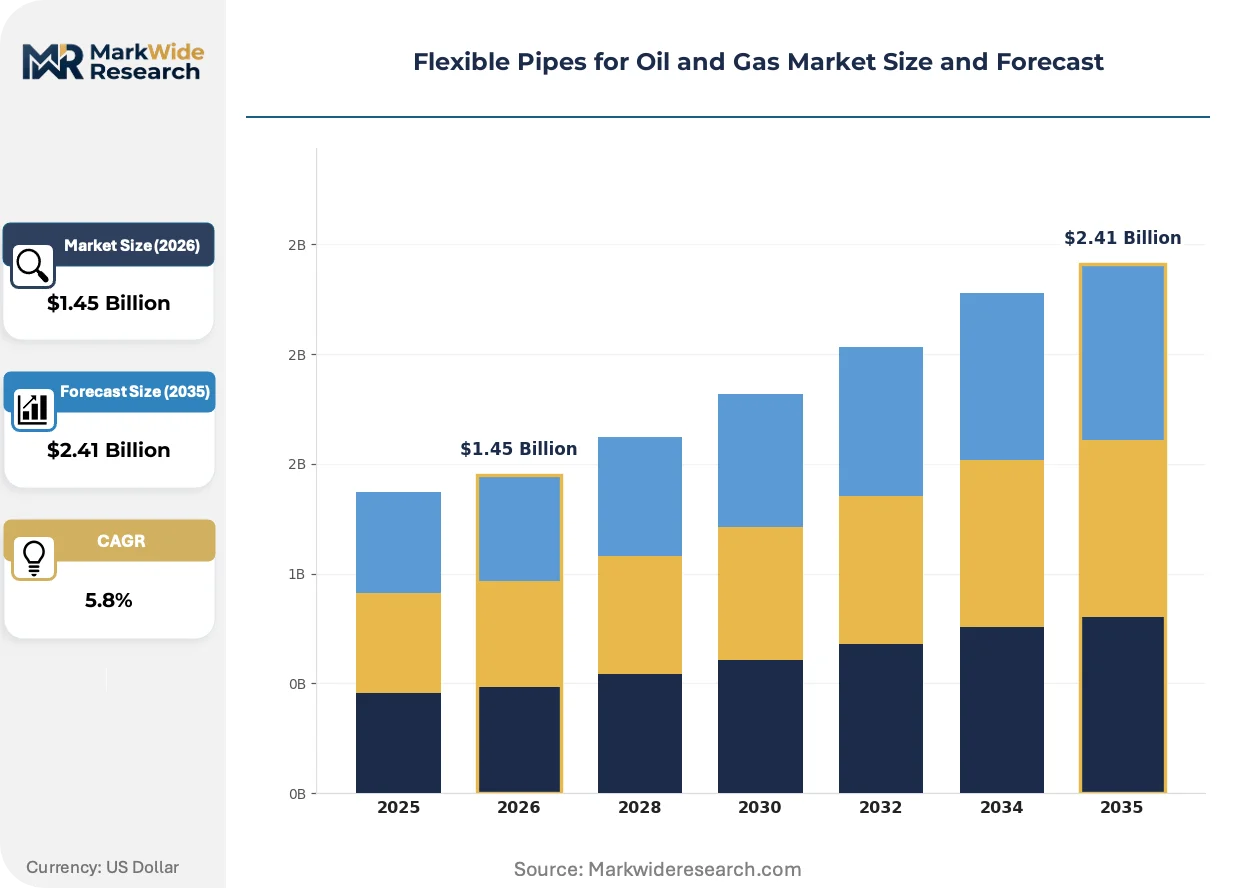
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $2.41 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel, Polyethylene, Composite, Thermoplastic Installation Type: Onshore, Offshore, Subsea, Hybrid End User: Exploration, Production, Refining, Distribution Technology: Flexible Risers, Jumper Lines, Flowlines, Umbilicals |
| Companies Covered | TechnipFMC PLC, National Oilwell Varco, Prysmian Group, Shawcor Ltd, Airborne Oil & Gas, Magma Global Ltd, ContiTech AG, SoluForce, FlexSteel Pipeline Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Pipes for Oil and Gas Market Trends and Innovations
Carbon fiber reinforcement is penetrating flexible pipe architectures as operators seek weight reduction for tension-leg platform applications. Material substitution patterns are redrawing performance boundaries across deepwater system designs.
Thermoplastic composite pressure barriers are decomposing traditional steel-armor dominance in ultra-deepwater riser applications. Operators in Brazil's pre-salt fields are specifying hybrid architectures that combine polymer sealing layers with reduced steel content. This material transition is decomposing established supply relationships as composite qualification capabilities become the decisive vendor selection criterion.
REACH chemical registration requirements in Europe are constraining polymer compound formulations used in anti-wear and insulation layers. Manufacturers must reformulate material specifications to maintain market access. Subsea production system suppliers with European manufacturing footprints are absorbing compliance costs into qualification budgets, compressing margins for non-integrated competitors.
Integrated service contracting is consolidating procurement decisions for flexible riser systems under single-source engineering-to-installation agreements. Operators are unbundling component supply from installation services less frequently. Brazil's pre-salt project tenders exhibit this pattern most acutely, with Petrobras preferring turnkey contractors bearing full system performance risk.
Flexible Pipes for Oil and Gas Market Segmentation
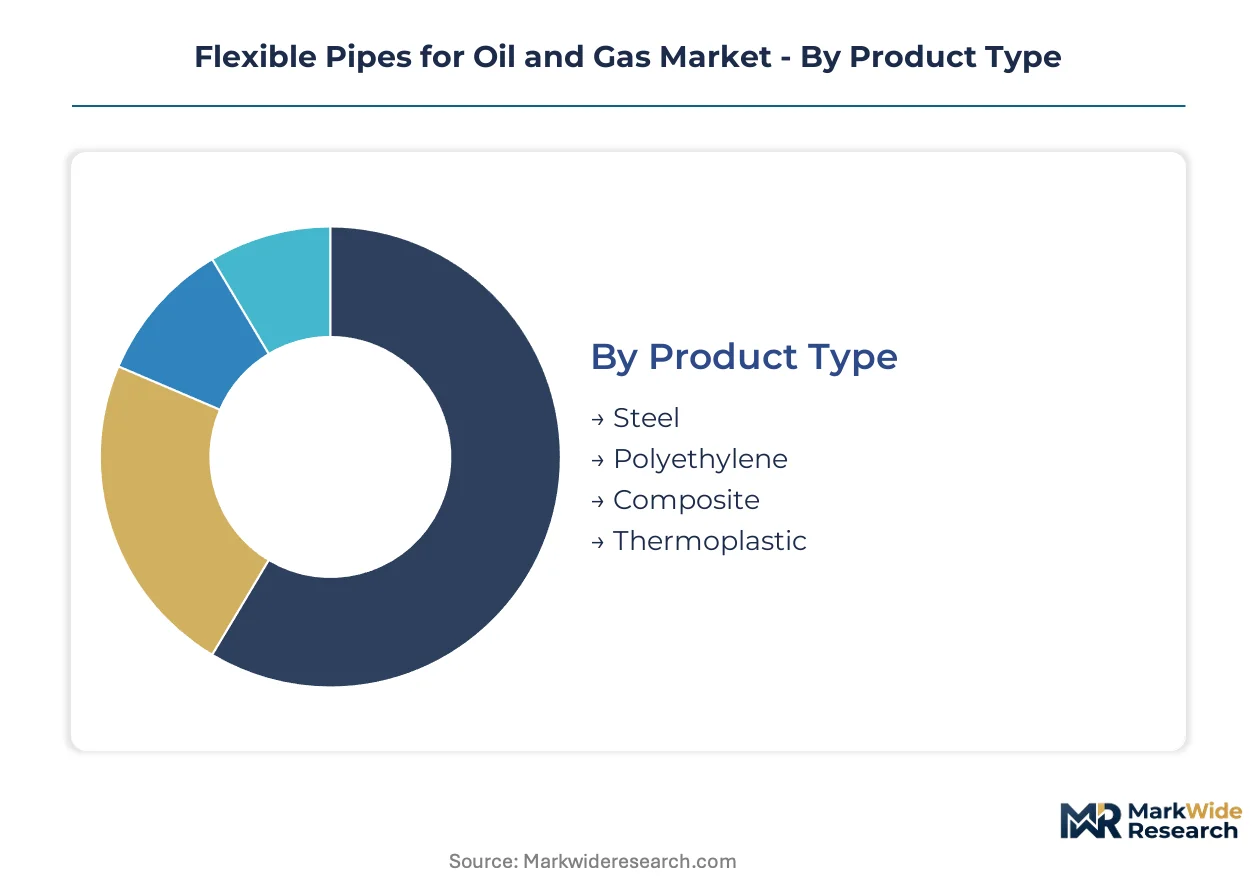
Segmentation in flexible pipes reveals how material choices, installation environments, and system architectures determine supplier capabilities and contract structures. Each dimension carries distinct qualification burdens and margin profiles that reshape competitive boundaries across deepwater basins.
Product Type:
Composite and thermoplastic formulations are displacing steel-armor dominance as ultra-deepwater tension-leg platforms demand weight reduction. Substitution pressure concentrates where API 17J qualification timelines and fatigue performance gaps create vendor selection bottlenecks.
- Steel:High-tensile carbon steel armor wires provide proven pressure containment exceeding 10,000 psi in dynamic riser applications. Brazil's pre-salt operators specify steel-reinforced architectures for high-pressure production systems where fatigue databases are mature and installation protocols standardized.
- Composite:Carbon fiber and glass-reinforced polymer pressure barriers reduce top-tension loads by 40-60% versus steel equivalents. Petrobras-led projects in Santos Basin are driving specification shifts toward hybrid composite-steel architectures for ultra-deepwater tension-leg platform tiebacks.
- Polyethylene:Cross-linked and high-density polyethylene barriers serve as primary fluid containment layers in medium-pressure flowline systems.
- Thermoplastic:Polyamide and PVDF pressure sheaths offer chemical resistance in sour service environments with reduced permeation rates.
Steel anchors the volume base while composite gains share at the steepest rate.
Installation Type:
Cost tier stratification separates subsea installations commanding premium engineering margins from onshore deployments competing on fabrication efficiency. Application criticality determines where integrated service contracting concentrates procurement leverage.
- Subsea:Reel-lay and carousel vessel installation of ultra-long flexible pipe strings requires integrated engineering-to-installation capabilities with full system performance risk transfer. Petrobras pre-salt tenders favor turnkey contractors bearing qualification, manufacturing, and offshore installation liability.
- Offshore:Platform-based flexible riser systems connect subsea wellheads to floating production facilities in dynamic marine environments. West African deepwater provinces off Angola and Nigeria exhibit supply chain gaps that inflate vessel day rates and extend project timelines.
- Onshore:Pipeline gathering systems and processing facility interconnects use standardized flexible pipe specifications with shorter qualification cycles.
- Hybrid:Combined subsea-to-shore architectures integrate multiple installation methodologies across bathymetric transitions.
Subsea commands the highest margin tier while offshore delivers the largest absolute contract value.
End User:
Customer type fragmentation separates capital-intensive production operators from exploration-focused drillers with diverging procurement priorities and contract tenures.
- Production:Field development operators in Brazil's pre-salt basins require 25-year design life flexible riser systems with integrated high-voltage dynamic umbilical capabilities for all-electric subsea processing.
- Exploration:Drilling contractors specify temporary flowline and jumper systems for appraisal well testing with shorter qualification requirements.
- Refining:Onshore processing facilities use flexible pipe for tank farm interconnects and unit tie-ins where space constraints prohibit rigid piping.
- Distribution:Midstream operators deploy flexible flowlines for marginal field tiebacks to existing pipeline infrastructure.
Production absorbs the dominant share of qualified manufacturing capacity while distribution exhibits the most price-sensitive procurement patterns.
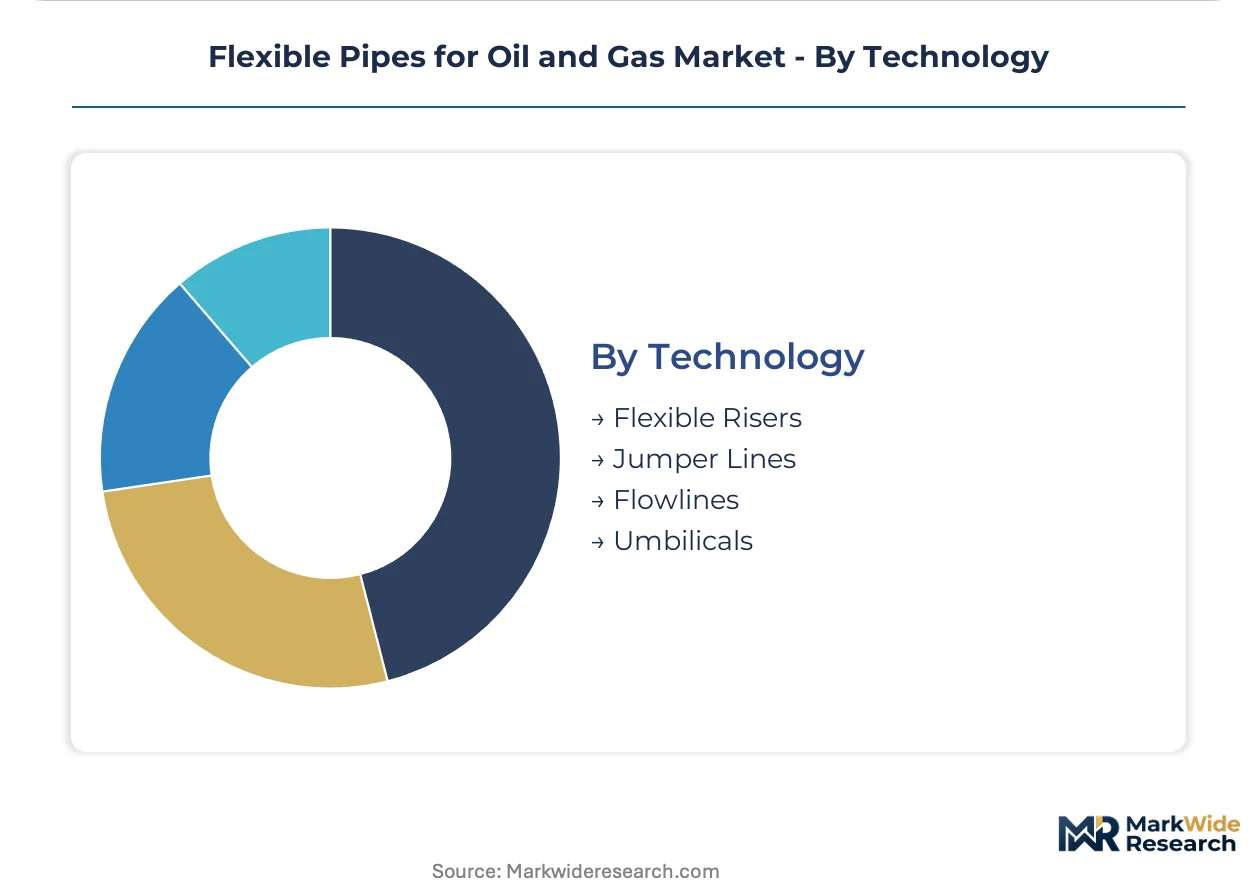
Technology:
Maturity gradients separate established flexible riser architectures from emerging umbilical integration technologies with unproven field performance at extreme pressure-temperature combinations.
- Flexible Risers:Dynamic pipe systems connecting subsea wellheads to floating production vessels accommodate vessel motion through helical steel armor wire configurations. These systems dominate deployment volumes in Brazil's pre-salt fields where API 17J qualification requirements compress the certified supplier base.
- Umbilicals:Integrated high-voltage power and control cable systems enable all-electric subsea processing architectures. Electrification convergence in Norway's North Sea developments is driving specification shifts toward combined power-distribution and production-control systems.
- Flowlines:Static flexible pipe systems transport production fluids between subsea infrastructure and host facilities.
- Jumper Lines:Short-length flexible connectors span gaps between subsea manifolds, trees, and flowline terminations.
Flexible risers anchor the installed base while umbilicals are climbing the fastest on electrification convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Niterói subsea equipment cluster underwrites Brazil's dominance in flexible riser deployment, while Norway's Mongstad supply base anchors North Sea deepwater engineering capabilities.
Brazil
Petrobras-led pre-salt developments in the Santos Basin drive demand for high-pressure dynamic riser systems exceeding 10,000 psi. ANP local content mandates require domestic manufacturing participation, compressing procurement options for foreign suppliers. The Niterói-Rio de Janeiro industrial corridor concentrates reel-lay vessel operations and composite pipe qualification facilities serving ultra-deepwater tension-leg platforms.
Norway
Equinor's Johan Sverdrup electrification project integrates high-voltage dynamic umbilicals with flexible riser systems for all-electric subsea processing. NORSOK U-001 standards dictate material traceability and fatigue testing protocols that extend field qualification timelines. The Mongstad supply base near Bergen hosts specialized carousel vessels and integrated engineering contractors serving North Sea brownfield redevelopment.
United States
Gulf of Mexico ultra-deepwater operators deploy flexible flowlines in Lower Tertiary tieback architectures connecting marginal fields to existing spar platforms. BSEE well control regulations and API 17J qualification requirements elevate technical barriers for new market entrants. Houston's Energy Corridor concentrates engineering procurement offices for integrated service contractors managing full-system performance risk.
United Kingdom
North Sea decommissioning schedules and remaining field life extensions sustain aftermarket demand for flexible pipe integrity management and replacement campaigns. HSE offshore safety case requirements mandate documented fatigue life assessments for aging riser installations. Aberdeen's subsea technology cluster hosts specialist inspection contractors and flexible pipe recertification facilities serving mature basin operators.
Angola
TotalEnergies and BP deepwater developments off the Kwanza Basin lack established flexible pipe supply chains, inflating vessel day rates and extending project timelines. The national petroleum regulator's local content frameworks create joint venture pathways for qualified manufacturers with fabrication partnerships. Luanda's port infrastructure constraints force reliance on reel-lay vessels mobilized from Brazil or West African hubs.
Flexible Pipes for Oil and Gas Market Competitive Landscape
Listed leaders compete with private specialists across integrated service contracting, with public energy service companies commanding premium valuations for engineering-to-installation capabilities while private fabricators capture niche composite qualification segments. Market structure concentrates certified manufacturing capacity among a handful of incumbents with established API 17J testing protocols. Three archetypes dominate: integrated turnkey contractors bearing full system risk, specialized composite material developers, and aftermarket service providers extending equipment life cycles. Competitive dynamics center on strategic partnerships for local content compliance and technology licensing for thermoplastic composite pressure barriers.
Within the integrated service tier, TechnipFMC PLC and National Oilwell Varco exemplify archetypes of full-system risk bearing and aftermarket network leverage respectively. Prysmian Group occupies a position bridging European high-voltage umbilical supply with electrification convergence trends. These three represent distinct strategic postures: turnkey engineering-to-installation dominance, mature basin service intensity, and power-cable integration specialization.
| Leading Market Players |
|---|
| TechnipFMC PLC |
| National Oilwell Varco |
| Prysmian Group |
| Shawcor Ltd |
| Airborne Oil & Gas |
| Magma Global Ltd |
| ContiTech AG |
| SoluForce |
| FlexSteel Pipeline Technologies Inc. |
| Others |
Pricing and Supply Chain Analysis
Carbon fiber substitution for steel armor wires is redrawing procurement economics while compressing supplier margins through extended API 17J qualification timelines and concentrated manufacturing footprints in Western Europe. Buyers face asymmetric pricing power as certified composite capacity clusters among integrated service contractors with captive testing facilities.
Pricing Analysis
Certification level under API 17J and NORSOK U-001 creates the primary spread between premium subsea installations and standardized onshore flowlines. Project-based long-term contracting dominates, with price differentiation resting on fatigue database maturity and integrated installation liability. Cost compression in composite tiers is intensifying because thermoplastic formulation R&D absorbs margin without immediate volume offset. Distribution operators exhibit the highest price sensitivity, while Petrobras-led production projects accept premium positioning for full-system performance guarantees.
Supply Chain Analysis
Reel-lay vessel availability at the Port of Niterói and Mongstad supply base constitutes a chokepoint that inflates project economics for West African developments lacking established logistics corridors. Manufacturing concentrates in Norway, Brazil, and France, with raw material dependencies spanning high-tensile steel wire from Germany, carbon fiber from Japan, and polymer compounds subject to REACH registration constraints. Single-source vulnerability runs through specialized carousel vessel operators. Distribution feeds from integrated engineering-to-installation contractors rather than component fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API 17J qualification scarcity and reel-lay vessel bottlenecks create asymmetric returns for stakeholders with certified manufacturing lines and integrated offshore capabilities. The gap between composite material developers and full-system installers defines competitive mobility.
For Market Incumbents: Secure extended frame agreements with Petrobras and Equinor that bundle qualification, manufacturing, and installation liability under single-source contracts. Expand backward integration into carbon fiber pre-preg supply to offset steel wire cost volatility and capture margin from material substitution trends. Lock in carousel vessel access through joint ownership or decade-long charter commitments before West African demand inflates day rates further. For New Entrants and Emerging Players: Lead with thermoplastic composite pressure barrier specialization targeting Angola and Nigeria, where supply chain gaps and local content mandates create penetrable procurement windows. Partner with Brazilian fabrication yards for ANP compliance without full qualification investment. Position around sour service chemical resistance as a differentiated entry point against steel-armor incumbents. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated engineering-to-installation contractors with API 17J certified lines and captive vessel access. Long-term viability rests on electrification convergence capabilities combining high-voltage umbilical integration with flexible riser systems. Monitor carbon fiber fatigue database completion as the inflection signal for composite share acceleration versus steel.| Strategic Initiative | Industry Significance |
|---|---|
| API 17J Certification Investment | Compresses viable supplier base while extending contract tenures for qualified manufacturers serving Brazil's pre-salt fields. |
| Joint Venture with Brazilian Fabricators | Unlocks ANP local content compliance for foreign technology holders seeking Petrobras tender access. |
| Carbon Fiber Pre-preg Backward Integration | Captures margin from material substitution while reducing exposure to steel wire price volatility. |
| Carousel Vessel Charter Lock-in | Secures installation capacity before West African demand inflates day rates and extends project timelines. |
| High-Voltage Umbilical Integration | Positions for Equinor-led electrification convergence in Norway's all-electric subsea processing architectures. |
Research Methodology
Operator-level perspectives from subsea project engineers, procurement leads at integrated oil companies, flexible pipe manufacturing directors, reel-lay vessel operators, and ANP regulatory affairs specialists anchored the qualitative base. Secondary validation drew from API specification documents, NORSOK U-001 standards, ANP local content directives, Petrobras tender disclosures, and Equinor supplier qualification records. Bottom-up field deployment estimates and top-down energy service company revenue triangulation formed the quantitative foundation.
Sensitivity analysis across material substitution scenarios, vessel day rate assumptions, and qualification timeline variations shaped the analytical framework. Segmentation dimensions modeled include product type, installation environment, end-user category, and technology maturity. CAGR derivation rested on project pipeline visibility from pre-salt developments, North Sea electrification programs, and West African exploration campaigns. Industry-specific inputs incorporated fatigue testing duration assumptions and composite pressure barrier adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained Brent price support for deepwater project sanctioning or prolonged vessel scarcity would require recalibration. Forecasts reflect documented assumptions regarding API 17J timeline stability and ANP local content enforcement intensity. Practitioners should keep alternative scenarios live as electrification convergence timelines and carbon fiber qualification database completion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Geothermal Drill Bits Market
Oil & Gas
Oil and Gas Well Conductor Installation Services Market
Oil & Gas
Oil Field Drill Bits Market
Oil & Gas
North America Directional Drilling Services Market
Oil & Gas
Oil and Gas Processing Seals Market
Oil & Gas
Canada LNG Market
Oil & Gas
Global Fracking Chemicals Market
Oil & Gas
Malaysia Oil and Gas Midstream Market
Oil & Gas
Marine Oil Water Separators Market
Oil & Gas
Europe Hydraulic Fracturing Fluids Market
Oil & Gas
Gold Mining Market
Oil & Gas
Spacer Fluid Market
Oil & Gas
United States Oil and Gas Pipeline Maintenance, Repair, Overhaul (MRO) Market
Oil & Gas
United Kingdom Oil and Gas Midstream Market
Oil & Gas
North America Wireline Logging Services Market
Oil & Gas
Oil & Gas Static and Rotating Equipment Market