
 Leak Detection for Oil & Gas Market | 2026-2036
Leak Detection for Oil & Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Leak Detection for Oil & Gas Market Insights
Fiber-optic sensing is pivoting from niche subsea use to onshore pipeline economics, displacing legacy pressure-point methods across midstream networks. Honeywell International Inc. leverages integrated control platforms to anchor positions in refinery leak monitoring. Emerson Electric Co. sustains R&D intensity in acoustic detection arrays for storage terminals. Siemens AG competes through geographic dominance in European gas utility retrofit programs.
Leak detection for oil and gas encompasses systems that identify hydrocarbon releases through pressure deviation analysis, acoustic signature recognition, or optical absorption spectroscopy, typically achieving detection thresholds below 0.1% volumetric loss for methane. These installations protect personnel, prevent environmental contamination, and minimize product loss across hydrocarbon infrastructure. Optical fiber technology leads in offshore platform deployments where electromagnetic interference excludes electrical alternatives, while infrared sensors dominate portable inspection protocols for gas utilities. Fixed systems represent the mature revenue base with replacement cycles driving steady demand, though integrated solutions combining multiple sensing modalities capture expanding margin pools from operators seeking unified dashboards.
PHMSA mandates in the United States enforce integrity management protocols for hazardous liquid and gas transmission pipelines, directly shaping sensor procurement specifications and validation frequencies. The EPA's methane emissions regulations under the Clean Air Act compound compliance obligations, particularly for storage facilities and gathering lines. EMA guidelines and EU methane strategy frameworks in Europe impose parallel measurement accuracy standards. Stakeholders must monitor evolving detection threshold requirements and determine whether platform consolidation or sensor diversification offers superior capital efficiency under tightening enforcement.
Market Dynamics
PHMSA integrity management mandates are compressing replacement cycles for legacy pressure-point monitoring systems, forcing pipeline operators toward fiber-optic and acoustic arrays that deliver continuous coverage rather than intermittent sampling.
Growth Catalysts
- Methane emissions frameworks:EPA regulations under the Clean Air Act impose measurement accuracy thresholds that obsolete manual inspection protocols, mandating automated detection across storage facilities and gathering lines.
- Shale basin density:Permian and Bakken operators require kilometer-scale monitoring networks as lateral lengths extend and pad drilling concentrates surface infrastructure.
- Fiber-optic maturation:Distributed acoustic sensing costs have fallen below legacy pressure-transducer arrays for pipelines exceeding fifty kilometers, flipping total-cost-of-ownership calculations.
Market Restraints
- Specialized silica supply:Optical fiber production depends on high-purity germanium and chlorine precursors concentrated in Chinese and German chemical processing clusters, exposing sensor manufacturers to input volatility.
- Electromagnetic interference limitations:Electrical alternatives remain excluded from subsea platform deployments, constraining solution portfolios for integrated offshore contractors.
- Validation protocol friction:PHMSA requires third-party certification of detection thresholds, extending procurement timelines for novel sensor modalities.
Strategic Opportunities
- Carbon capture integration:CO2 transport pipelines for enhanced oil recovery projects in Texas and Alberta lack mature leak detection standards, creating first-mover positioning for multi-species sensing platforms.
- Hydrogen infrastructure preparation:European gas utility retrofit programs under EU methane strategy frameworks are testing sensor arrays for hydrogen-natural gas blends, opening adjacent specification channels.
- Edge computing convergence:Onboard processing at sensor nodes reduces bandwidth requirements for remote pipelines, enabling coverage in bandwidth-constrained jurisdictions.
Industry Challenges
- Interoperability gaps:SCADA integration for multi-vendor sensor networks requires custom protocol bridges, inflating commissioning costs and timeline risk for midstream operators.
- Field calibration expertise:Distributed fiber-optic systems demand technicians trained in optical time-domain reflectometry, a skill set concentrated among submarine cable specialists rather than traditional pipeline maintenance crews.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leak Detection for Oil & Gas Market |
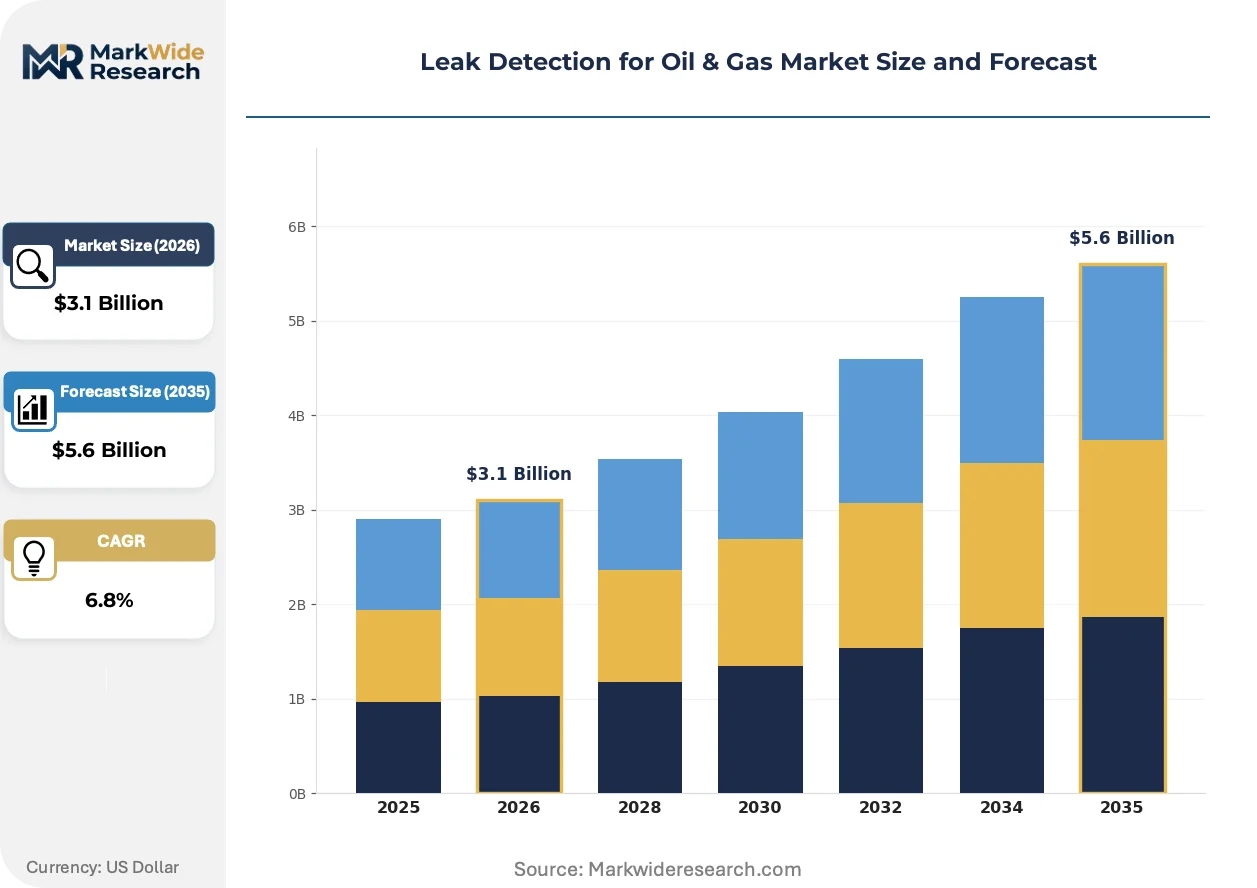
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.6 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Acoustic Sensors, Optical Fiber, Gas Leak Detectors, Infrared Sensors Application: Pipeline Monitoring, Storage Facilities, Offshore Platforms, Refinery Operations End User: Oil Producers, Natural Gas Utilities, Engineering Firms, Environmental Agencies Installation: Fixed Systems, Portable Units, Integrated Solutions, Retrofitting Equipment |
| Companies Covered | Honeywell International Inc., Emerson Electric Co., Siemens AG, Schneider Electric SE, ABB Ltd., FLIR Systems Inc., OptaSense Ltd., Bridger Photonics Inc., Atmos International Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leak Detection for Oil & Gas Market Trends and Innovations
Sensor fusion architectures are displacing single-modality installations as operators demand unified dashboards correlating acoustic, thermal, and pressure signatures into actionable leak coordinates rather than isolated alarms.
Distributed fiber-optic sensing is converging with machine learning inference at the edge, enabling real-time pattern recognition without cloud dependency. Midstream operators in the Permian Basin are deploying these hybrid arrays across gathering networks spanning hundreds of kilometers. The convergence is compressing response latency from hours to minutes, reshaping liability calculations for insurers underwriting pipeline assets.
EU methane strategy frameworks are mandating quarterly leak detection surveys for gas transmission infrastructure, accelerating replacement of annual manual inspection cycles. Operators in Germany and the Netherlands face compressed compliance timelines that favor automated continuous monitoring over periodic crew deployment. Storage terminal specifications are tightening fastest, driving demand for infrared imaging arrays with sub-ppm sensitivity thresholds.
Asset owners are unbundling detection hardware from integrated service contracts, preferring direct procurement of sensor networks with separate software licenses. This procurement fragmentation disrupts traditional bundled offerings from control system vendors. The shift is most pronounced among North American master limited partnerships seeking capital expenditure transparency for investor reporting.
Leak Detection for Oil & Gas Market Segmentation
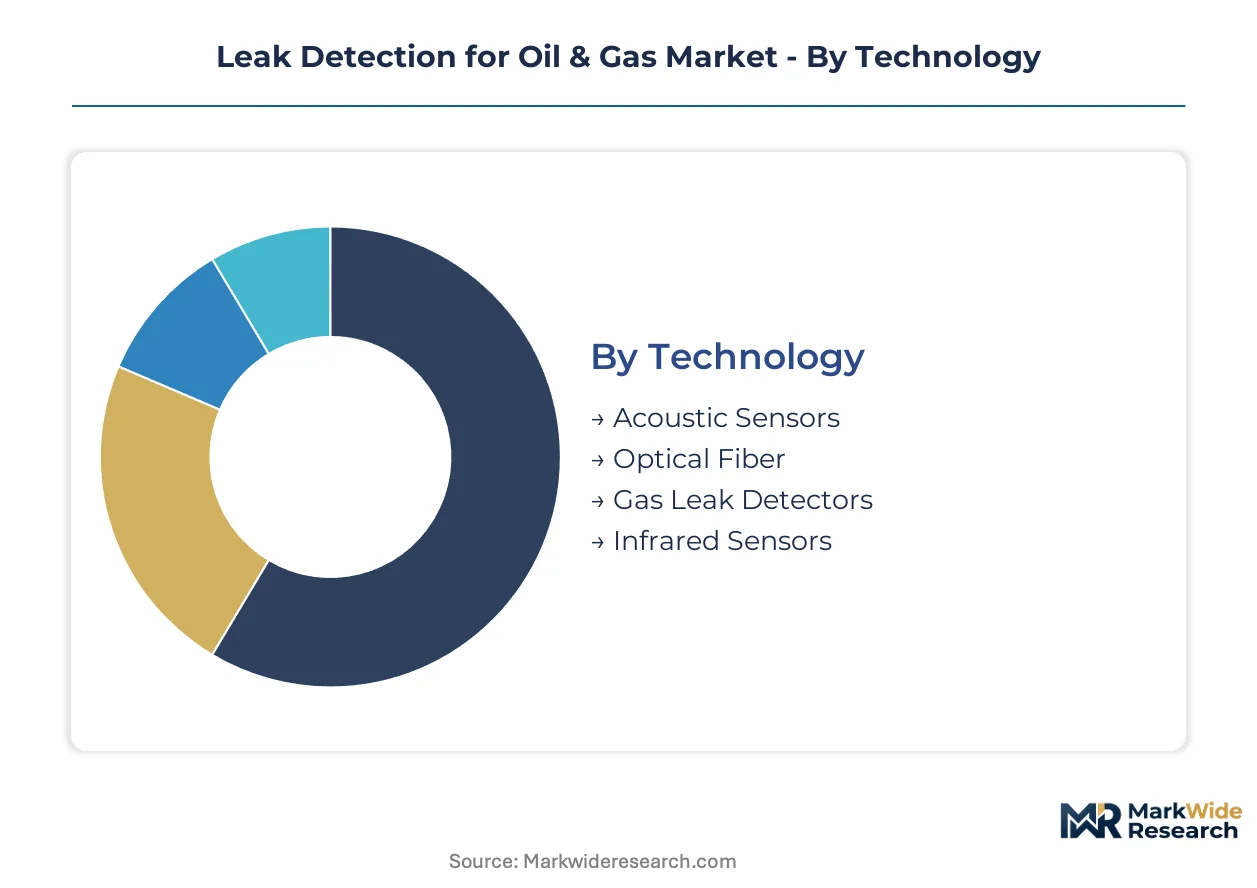
Technology modality determines capital intensity and operational complexity across leak detection procurement. Application context shapes sensor specifications through temperature ranges, pressure ratings, and electromagnetic constraints. End-user sophistication and installation approach further stratify vendor engagement models and service contract structures.
Technology:
Customization depth spans from commodity gas detectors to engineered fiber-optic arrays requiring site-specific calibration protocols.
- Optical Fiber:Distributed acoustic sensing leverages silica waveguides to detect strain and temperature anomalies across kilometer-scale spans. Permian Basin midstream operators deploy these for gathering line coverage where pressure-point methods fail. PHMSA integrity mandates accelerate displacement of legacy electrical alternatives.
- Acoustic Sensors:Piezoelectric arrays capture pressure wave signatures from pipeline ruptures or valve leaks. Storage terminal operators in Alberta favor these for tank farm perimeters where rapid localization outweighs absolute sensitivity. Sensor fusion architectures now combine acoustic nodes with thermal imaging for coordinate precision.
- Infrared Sensors:Optical absorption spectroscopy identifies hydrocarbon plumes through characteristic wavelength attenuation.
- Gas Leak Detectors:Electrochemical and catalytic bead technologies serve portable inspection protocols.
Leading the category by volume: Gas Leak Detectors. Growing fastest: Optical Fiber.
Application:
Volume concentration tracks hydrocarbon infrastructure density, with shale basins and coastal production zones driving disproportionate sensor deployment.
- Pipeline Monitoring:Continuous coverage requirements for transmission and gathering networks span fiber-optic trenching, aerial patrol augmentation, and smart pig correlation. Texas and Alberta shale operators face compressed replacement cycles under evolving EPA methane frameworks. Kilometer-scale lateral extensions multiply sensor node counts per well pad.
- Offshore Platforms:Electromagnetic exclusion zones necessitate fiber-optic or ultrasonic alternatives to electrical sensing. Gulf of Mexico producers specify subsea-rated assemblies with decades-long design life against saltwater corrosion and pressure cycling. Platform integration demands unified SCADA dashboards consolidating drilling, processing, and safety systems.
- Storage Facilities:Tank farm perimeters and underground cavern monitoring combine fixed infrared arrays with periodic handheld verification.
- Refinery Operations:Process unit leak detection integrates with distributed control systems for pressure-vessel and heat-exchanger surveillance.
Dominant by deployment scale: Pipeline Monitoring. Steepest expansion trajectory: Storage Facilities.
End User:
Procurement sophistication separates integrated operators with captive engineering capabilities from compliance-driven agencies requiring turnkey validation.
- Oil Producers:Majors and independents specify multi-species detection platforms spanning methane, hydrogen sulfide, and carbon dioxide for enhanced oil recovery projects. Capital discipline among North American shale operators favors modular sensor networks with software-unbundled pricing. Internal reliability engineering teams increasingly self-perform commissioning.
- Natural Gas Utilities:Distribution network operators face EU methane strategy quarterly survey mandates replacing annual inspection cycles. German and Dutch utilities test hydrogen blend compatibility for sensor arrays ahead of infrastructure transitions. Rate-base treatment of safety capital drives preference for proven technologies with established depreciation schedules.
- Engineering Firms:EPC contractors specify detection systems during front-end engineering design for greenfield projects.
- Environmental Agencies:Regulatory enforcement drives third-party certification demand and validation protocol standardization.
Highest procurement volume: Oil Producers. Expanding most quickly: Natural Gas Utilities.
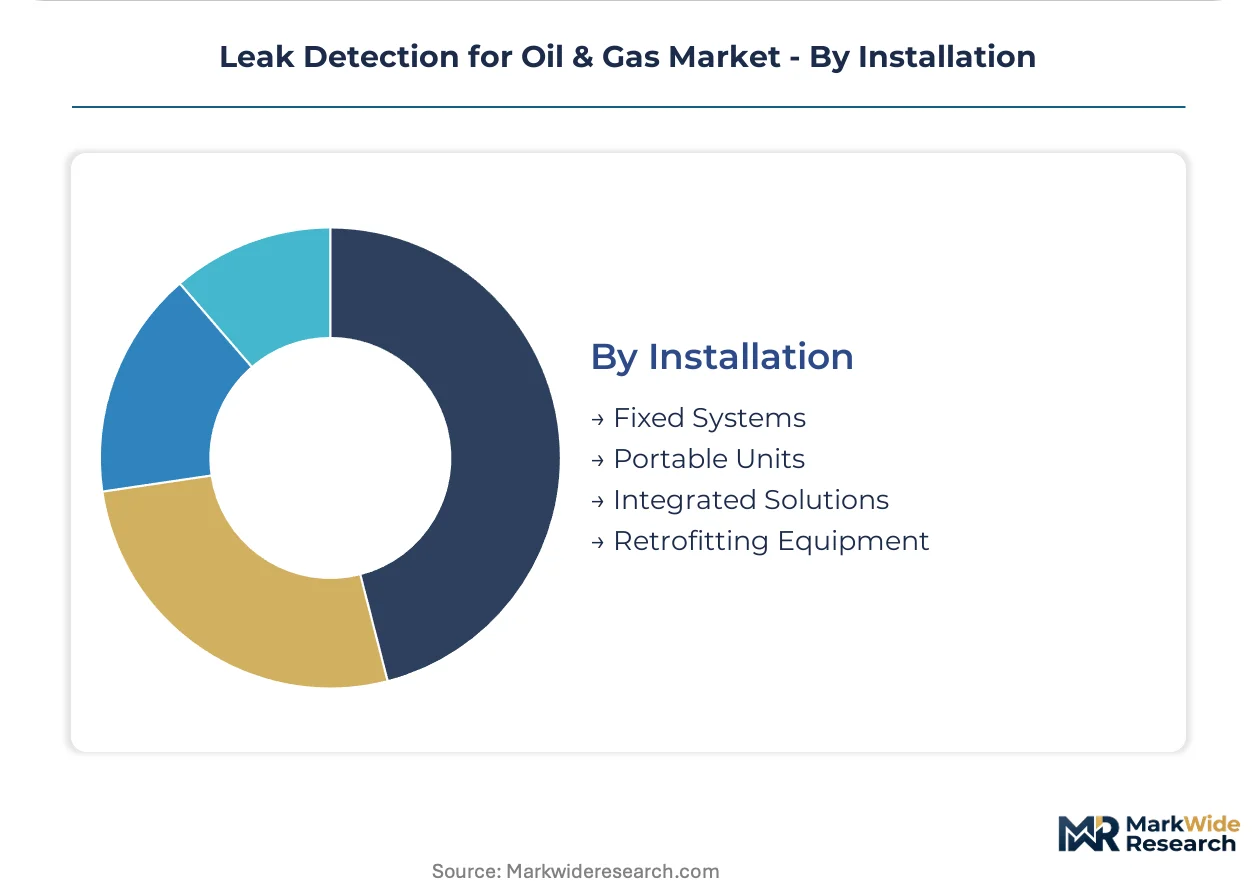
Installation:
Margin structure inverts between mature replacement demand and emerging integrated solution architectures.
- Fixed Systems:Permanent sensor networks constitute the revenue base with replacement cycles tied to PHMSA revalidation intervals. Fiber-optic deployments require specialized optical time-domain reflectometry expertise concentrated among submarine cable technicians rather than traditional pipeline maintenance crews. Commissioning timelines extend when SCADA integration demands custom protocol bridges.
- Integrated Solutions:Multi-modality platforms combining acoustic, thermal, and pressure signatures into unified dashboards capture expanding margin pools. Midstream operators seek consolidated alarm management reducing control room operator cognitive load. Software licensing unbundling from hardware procurement disrupts traditional bundled service contracts.
- Portable Units:Handheld infrared and electrochemical devices serve periodic inspection and emergency response.
- Retrofitting Equipment:Adapter kits and communication gateways extend legacy sensor network utility.
Leading by installed base: Fixed Systems. Gaining share fastest: Integrated Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in shale basins and coastal production zones where pipeline density and regulatory enforcement intersect. The United States, Canada, Germany, China, and Saudi Arabia collectively shape procurement patterns through distinct compliance frameworks and infrastructure investment cycles.
United States
Permian and Bakken operators deploy kilometer-scale fiber-optic networks as lateral lengths extend beyond fifteen kilometers. EPA methane regulations under the Clean Air Act mandate automated detection across storage facilities and gathering lines. Houston hosts the highest concentration of midstream engineering procurement for integrated sensing platforms.
Canada
Alberta oil sands operations require continuous monitoring of steam-assisted gravity drainage pipelines and tailings ponds. The Alberta Energy Regulator enforces leak detection performance standards for thermal in-situ projects. Calgary engineering clusters specialize in cold-climate fiber-optic installations for sub-zero operating conditions.
Germany
Natural gas utilities face compressed compliance timelines under EU methane strategy quarterly survey mandates replacing annual inspection cycles. The Federal Network Agency coordinates hydrogen blend compatibility testing for sensor arrays ahead of infrastructure transitions. Ruhr Valley industrial corridors drive retrofit demand for aging distribution networks.
China
West-East pipeline expansions across Xinjiang and Sichuan provinces require distributed acoustic sensing for seismic zone monitoring. The Ministry of Ecology and Environment tightens fugitive emissions standards for petrochemical clusters. Ningbo-Zhoushan port infrastructure anchors offshore platform sensor procurement for East China Sea developments.
Saudi Arabia
Master Gas System expansions and unconventional gas developments in Jafurah basin demand multi-species detection platforms. The Saudi Standards, Metrology and Quality Organization aligns detection threshold specifications with EPA benchmarks. Dhahran engineering centers specify subsea-rated fiber-optic assemblies for Red Sea offshore platforms.
Leak Detection for Oil & Gas Market Competitive Landscape
Strategic partnerships dominate the current landscape as sensor manufacturers seek SCADA integration capabilities beyond core detection hardware. The vendor base stratifies across three tiers: diversified industrial conglomerates with integrated control platforms, specialized fiber-optic sensing firms with submarine cable heritage, and modular hardware providers pursuing software-unbundled pricing. Two archetypes define competitive positioning: full-stack solution vendors capturing integrated solution margins, and component specialists supplying into third-party system integration. Technology licensing agreements and geographic expansion into carbon capture and hydrogen infrastructure represent the dominant competitive vectors.
Among diversified industrial technology providers, Honeywell International Inc., Emerson Electric Co., and Siemens AG exemplify distinct strategic postures. Honeywell occupies a position anchored in refinery control system integration. Emerson represents the acoustic detection specialization archetype for storage terminal applications. Siemens sits within the European gas utility retrofit program channel, reflecting geographic concentration in EU methane compliance markets. These three entities illustrate how scale, regional focus, and technology modality differentiate competitive positioning without requiring identical capability portfolios.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Emerson Electric Co. |
| Siemens AG |
| Schneider Electric SE |
| ABB Ltd. |
| FLIR Systems Inc. |
| OptaSense Ltd. |
| Bridger Photonics Inc. |
| Atmos International Ltd. |
| Others |
Pricing and Supply Chain Analysis
Optical time-domain reflectometry technicians concentrated in submarine cable hubs of Japan and the United Kingdom command wage premiums that propagate into fiber-optic deployment pricing tiers. Labor-cost differentials between these specialist clusters and conventional pipeline maintenance markets widen spreads between premium engineered arrays and standard pressure-transducer replacements.
Pricing Analysis
Volume concentrates in fixed-system replacements while margin pools accrue to integrated multi-modality platforms. Three-tier pricing structure across premium, standard, and economy levels separates PHMSA-validated fiber-optic arrays with third-party certification from unbundled hardware procurement and basic gas detector units. Cost compression in standard-tier pressure-transducer replacements intensifies as Chinese manufacturers expand electrochemical sensor output. Midstream master limited partnerships exhibit highest price sensitivity due to capital expenditure transparency demands, while offshore platform operators show lowest sensitivity given electromagnetic exclusion constraints.
Supply Chain Analysis
Single-source vulnerability sits with high-purity germanium precursor processing concentrated in Chinese and German chemical clusters. Silica waveguide production draws from specialty fiber draw towers in the United States, Japan, and the Netherlands. Chlorine and germanium tetrachloride feedstocks hinge on semiconductor industry demand cycles, creating commodity price volatility exposure. Distribution runs through control system integrators and EPC contractors rather than direct sensor manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment where technician training bottlenecks in optical time-domain reflectometry sustain pricing power for qualified installation providers.
For Market Incumbents: Deepen captive training pipelines for fiber-optic commissioning expertise to lock out modular hardware competitors seeking software-unbundled entry. Expand backward integration into germanium precursor supply through long-term offtake agreements with Chinese chemical processors. PHMSA validation protocol friction protects incumbent positions against novel sensor modalities.
For New Entrants and Emerging Players: Capture carbon capture transport pipeline specifications in Texas and Alberta where multi-species detection standards remain undefined. Target storage facility infrared array procurement in Germany and the Netherlands facing compressed EU methane strategy compliance timelines. Lead with edge-computing-enabled sensor nodes reducing bandwidth requirements for remote Permian Basin gathering networks.
For Investors and Strategic Acquirers: Re-rating potential sits with fiber-optic sensing specialists possessing submarine cable heritage given convergence with machine learning inference at the edge. Long-term viability centers on hydrogen blend compatibility positioning ahead of European gas utility infrastructure transitions. Watch for PHMSA detection threshold requirement revisions as inflection indicator for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Species Sensing Platform Development | Positions vendors for CO2 transport pipeline specifications in Texas enhanced oil recovery projects. |
| Edge Computing Convergence | Enables real-time pattern recognition without cloud dependency across bandwidth-constrained Permian Basin networks. |
| Hydrogen Blend Compatibility Testing | Opens adjacent specification channels under EU methane strategy frameworks in German and Dutch utility programs. |
| SCADA Integration Capability Acquisition | Resolves interoperability gaps inflating commissioning costs for midstream operator multi-vendor deployments. |
| Specialized Technician Training Programs | Addresses field calibration expertise scarcity concentrated among submarine cable specialists rather than pipeline crews. |
Research Methodology
Independent corroboration across pipeline integrity managers, SCADA integration specialists, and fiber-optic sensing engineers underwrites the qualitative findings. Primary interviews with midstream procurement officers, storage terminal operators, and EPC contractor specification leads combined with secondary validation from PHMSA enforcement databases, EPA methane emissions filings, and EU methane strategy implementation reports. Bottom-up sensor deployment tallies triangulate against top-down infrastructure investment forecasts.
Rate-of-change decomposition separates replacement cycle compression from net capacity additions across the analysis window. Segmentation dimensions span technology modality, application context, end-user sophistication, and installation approach. CAGRs derive from pipeline mileage expansion projections, regulatory mandate implementation schedules, and fiber-optic cost curve trajectories. Shale basin density metrics and electromagnetic constraint prevalence inform regional weightings.
The model holds under steady PHMSA enforcement intensity and continued EPA methane regulation expansion; deviation in federal regulatory rollback or trade restriction escalation on germanium precursors would shift trajectory. Forecasts reflect documented assumptions regarding technician training pipeline expansion rates and sensor fusion architecture adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Asia Pacific Oil Storage Tank Service Market
Oil & Gas
Middle-East and Africa Liner Hanger System Market
Oil & Gas
Russian Federation Oil and Gas Market
Oil & Gas
Middle East and Africa Pipeline Maintenance Market
Oil & Gas
Casing Centralizer Market
Oil & Gas
Australia Oil and Gas Midstream Market
Oil & Gas
Electric Fracking Market
Oil & Gas
Europe Intelligent Pigging Market
Oil & Gas
Malaysia Oilfield Services Market
Oil & Gas
Wireline Logging Services Market
Oil & Gas
Europe Hydraulic Fracturing Market
Oil & Gas
Middle-East Enhanced Oil Recovery Market
Oil & Gas
Tight Gas Market
Oil & Gas
Oilfield Rotary Table Market
Oil & Gas
Downhole Motor Market
Oil & Gas
Nigeria Wireline Logging Services Market