
 Africa Oil and Gas Market | 2026-2036
Africa Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Oil and Gas Market Outlook
Power generation is realigning as the dominant end-use vertical across the Africa oil and gas landscape, pulling investment toward gas-fired infrastructure and away from traditional diesel baseload. TotalEnergies SE leverages its LNG portfolio and pre-salt expertise to anchor positions in Mozambique and Angola. Shell PLC sustains deepwater exploration momentum through its Nigerian and Namibian acreage. Sonatrach dominates North African upstream output through its integrated Saharan field-to-port system.
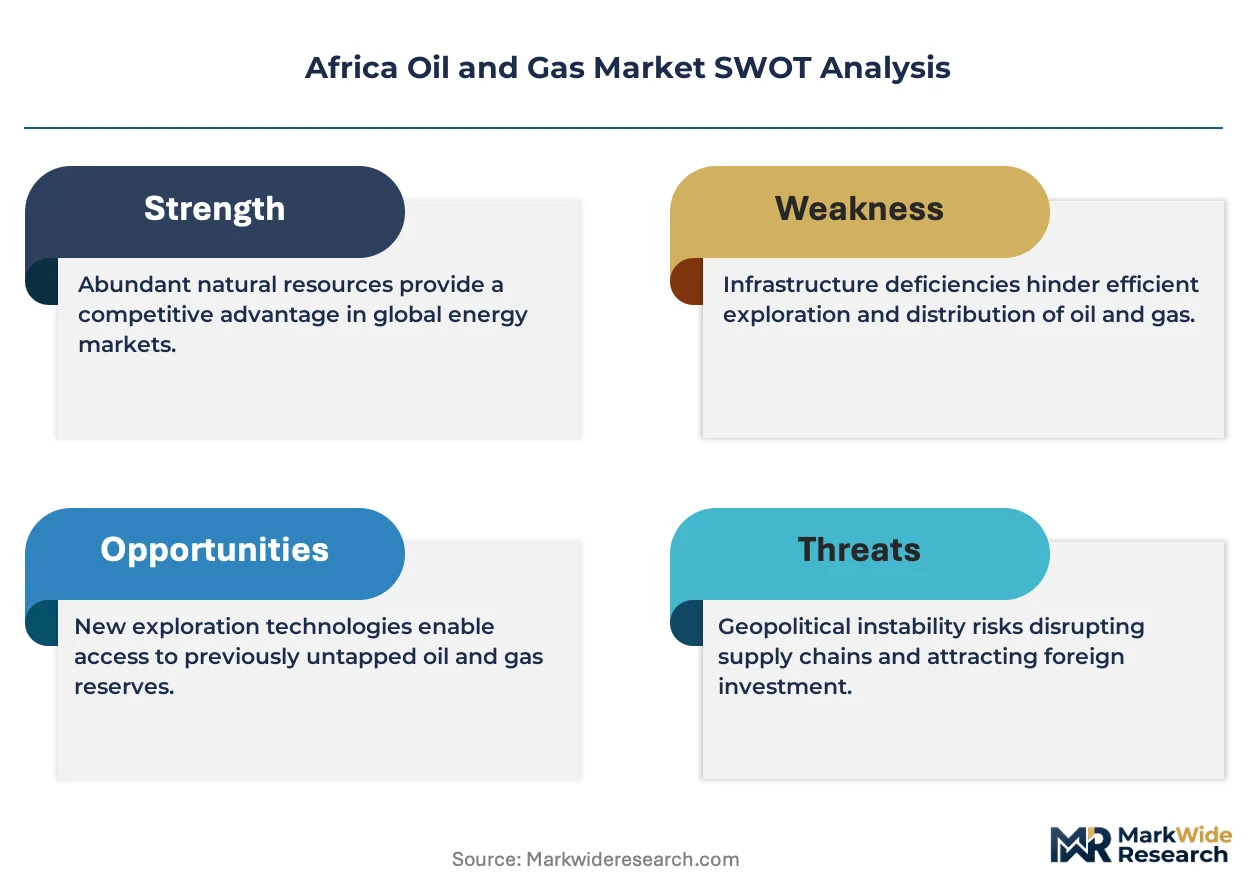
Africa oil and gas encompasses the exploration, production, refining, and distribution of crude petroleum and natural gas resources across the continent, with crude typically classified by API gravity between 20 and 45 degrees and sulfur content ranging from sweet to sour grades. The primary commercial purpose centers on energy supply for electricity generation, industrial process heat, and transportation fuel, plus feedstock for regional petrochemical complexes. Exploration services command premium margins where frontier basins in Namibia and Senegal attract capital, while production segments face maturation challenges in legacy Nigerian onshore fields. Offshore drilling technology is expanding fastest as water-depth capabilities unlock pre-salt and deepwater reserves previously inaccessible to regional operators.
Nigeria's Petroleum Industry Act and Angola's concession reform framework are reshaping fiscal terms, local content requirements, and licensing timelines for international investors across West African upstream blocks. The country's national petroleum regulator enforces environmental compliance standards tied to offshore drilling permits, while Algeria's national oil company operates under distinct hydrocarbon law governing production-sharing contracts. Stakeholders must monitor how fiscal stability clauses and carbon border adjustments interact with project economics in frontier basins.
Market Dynamics
Deepwater drilling capabilities are unlocking pre-salt reserves across West African offshore basins, compressing breakeven costs and redrawing competitive positioning among international operators. This technological shift is pulling capital toward frontier acreage while legacy onshore fields face maturation pressures.
Growth Catalysts
- Power generation demand:Gas-fired baseload capacity is displacing diesel generators across Nigerian and Angolan grids, creating dedicated offtake agreements for associated gas that previously flared.
- Nigeria's Petroleum Industry Act:The fiscal framework stabilizes production-sharing terms and streamlines licensing timelines, reducing regulatory uncertainty for upstream investors in deepwater blocks.
- Pre-salt exploration:Advanced subsea production systems are accessing carbonate reservoirs beneath salt layers in Angola's Kwanza Basin, expanding recoverable reserve estimates.
Market Restraints
- Capital intensity:Deepwater developments require multi-billion-dollar commitments before first oil, constraining participation to majors with balance sheet capacity.
- Local content mandates:Nigeria's Petroleum Industry Act imposes escalating domestic procurement quotas, inflating project costs where indigenous supply chains remain underdeveloped.
- Grid infrastructure gaps:Inadequate transmission networks in Mozambique and Tanzania limit monetization of offshore gas discoveries for power generation.
Strategic Opportunities
- Namibian frontier basins:Recent discoveries in the Orange Basin establish a new petroleum province with favorable fiscal terms and minimal above-ground risk.
- LNG export infrastructure:Mozambique's onshore liquefaction projects create vertical integration pathways from offshore Coral field gas to Asian offtake markets.
- Algerian solar-hybrid fields:Sonatrach's pilot programs integrate photovoltaic arrays with upstream operations, reducing diesel consumption for remote power supply.
Industry Challenges
- Subsea engineering talent:Shortages of specialists in riser design and flow assurance create bottlenecks for deepwater project execution timelines.
- Carbon accounting complexity:Scope 3 emission tracking requirements under emerging climate disclosure frameworks complicate portfolio valuation for African upstream assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Oil and Gas Market |
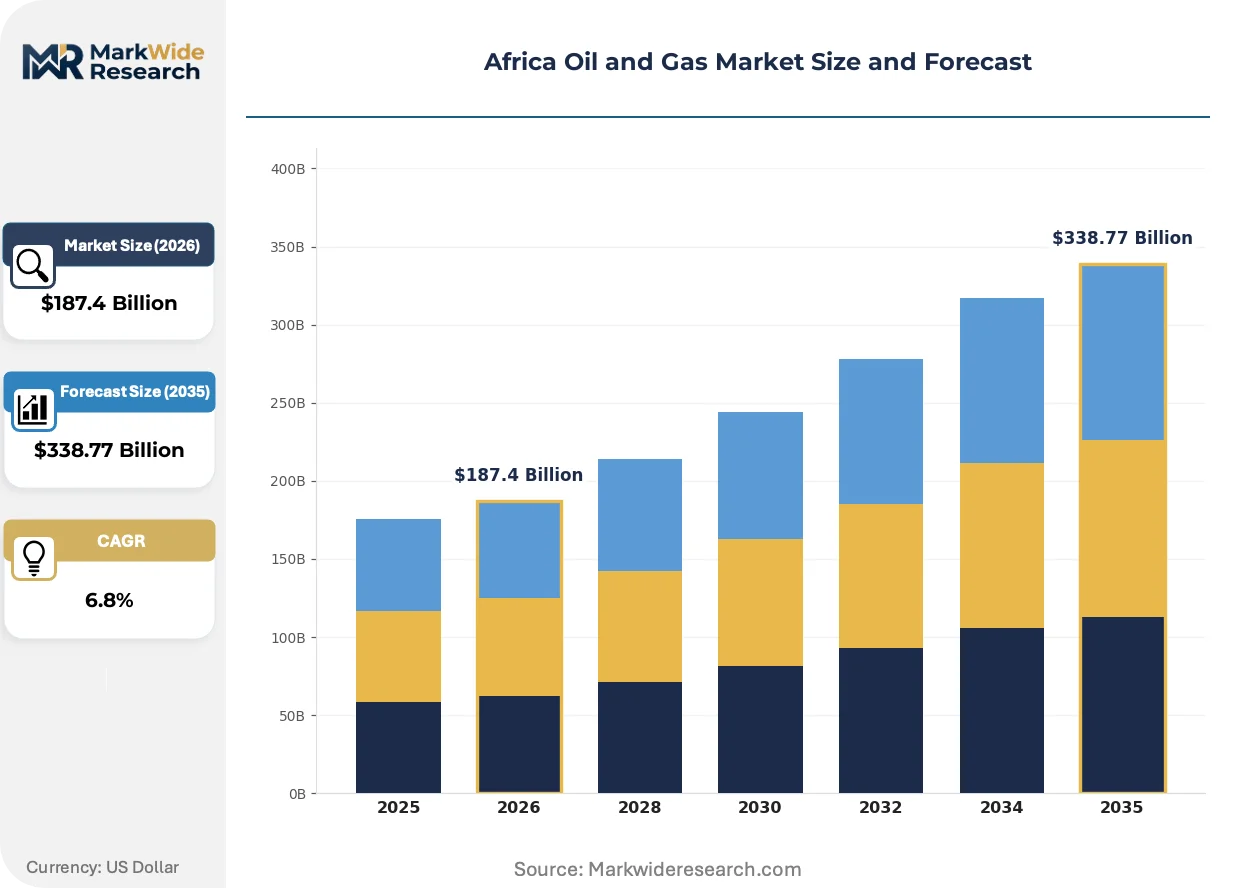
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Exploration, Production, Refining, Distribution End User: Power Generation, Industrial, Automotive, Residential Technology: Enhanced Oil Recovery, Offshore Drilling, Shale Extraction, Gas-to-Liquids Application: Electricity Generation, Heating, Transportation, Petrochemicals |
| Companies Covered | Shell PLC, TotalEnergies SE, Eni SpA, Exxon Mobil Corporation, Nigerian National Petroleum Corporation, Sonatrach, National Oil Corporation of Libya, Sonangol, Equinor, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Oil and Gas Market Strategic Shifts
Digital reservoir characterization and autonomous subsea systems are compressing exploration timelines while environmental monitoring technologies reshape regulatory compliance. These shifts are enabling operators to access deeper horizons with reduced surface footprint.
Reservoir simulation software is integrating machine learning algorithms to process seismic data and optimize well placement in pre-salt formations. Nigerian and Angolan operators are deploying these platforms to reduce dry-hole risk in complex carbonate plays. The technology is integrating geoscience and drilling functions previously handled by separate contractor teams, compressing project cycle times.
Nigeria's Petroleum Industry Act introduces mandatory decommissioning bonds and environmental remediation funds for offshore license holders. These provisions accelerate capital provisioning for end-of-field-life obligations while tightening fiscal discipline among marginal producers. Deepwater operators are responding by front-loading abandonment cost estimates into development economics.
Integrated service contracts are displacing discrete equipment procurement in subsea project development. Major operators in Angola and Mozambique now bundle engineering, procurement, and installation under single-vendor arrangements, transferring execution risk to contractors. This concentration is most visible in ultra-deepwater segments where technical complexity demands unified accountability.
Africa Oil and Gas Market Segmentation
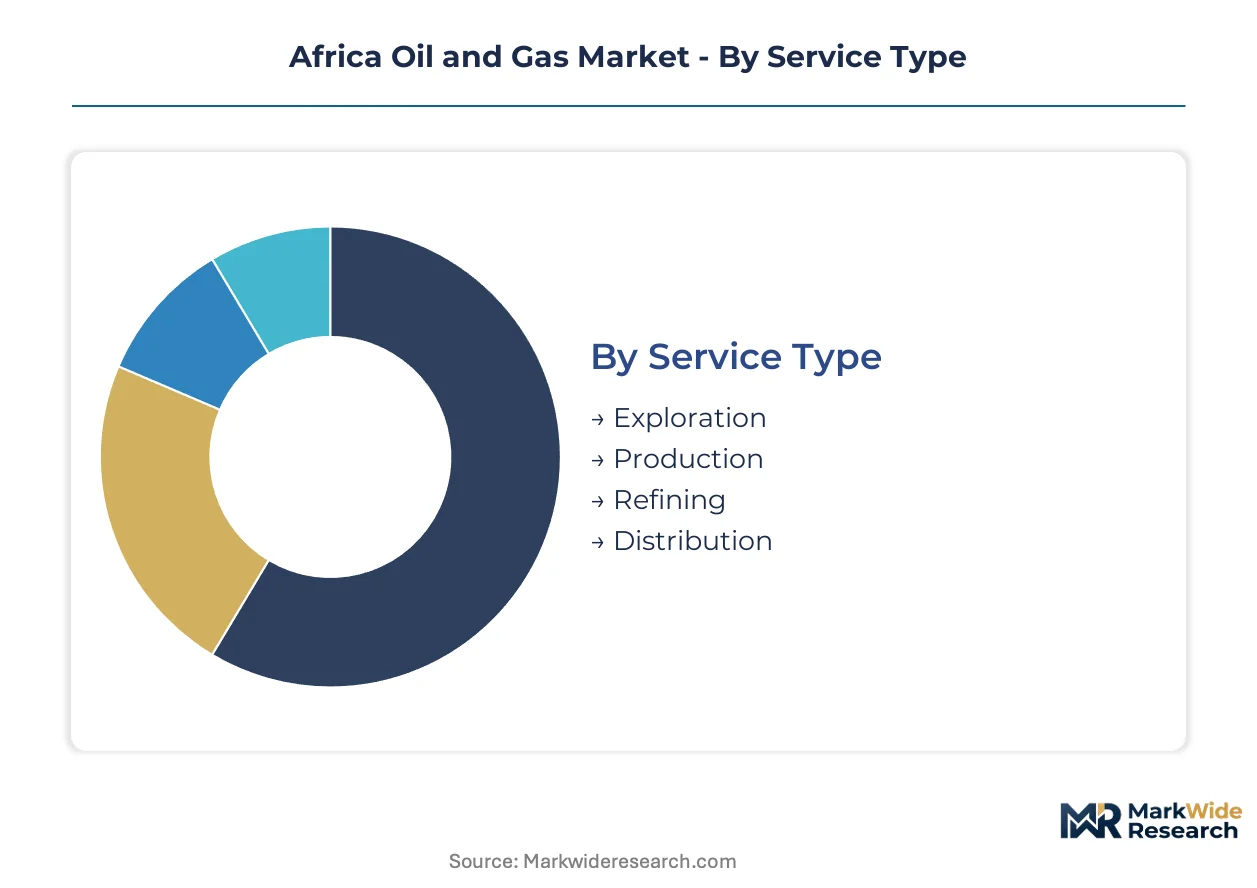
Segmentation in African oil and gas reveals how capital allocation, regulatory pressure, and infrastructure maturity fragment value capture across the value chain. Each dimension exposes distinct margin structures and entry barriers for operators and service providers.
Service Type:
Upstream service concentration in West African offshore basins is pulling specialized capital toward high-specification drilling and subsea installation capabilities.
- Exploration:Seismic acquisition and wildcat drilling in frontier Namibian and Senegalese basins command premium day rates where reservoir uncertainty remains elevated. Demand clusters in deepwater blocks where pre-salt carbonate targets require advanced imaging and extended-reach drilling systems.
- Production:Field development and well intervention services face maturation pressures in Nigerian onshore assets while expanding in Angolan pre-salt clusters. Associated gas capture projects are displacing routine workover contracts as operators prioritize flaring reduction commitments.
- Refining:Downstream processing capacity remains structurally constrained across Sub-Saharan Africa, with Nigerian Dangote refinery and Angolan Lobito complex absorbing regional crude supply that previously exported to European markets.
- Distribution:Product logistics networks concentrate in coastal import terminals serving landlocked Sahelian markets, with pipeline infrastructure gaps forcing high-cost trucking across Nigerian and Kenyan hinterlands.
Today's leader: Production. Tomorrow's challenger: Exploration.
End User:
Power sector offtake agreements are restructuring contract structures away from spot market exposure toward long-term gas supply dedications.
- Power Generation:Grid-connected gas turbines in Nigeria and Angola are displacing diesel baseload capacity, creating dedicated demand for associated gas that previously flared at wellheads. Integrated LNG-to-power projects in Mozambique and Tanzania anchor offshore development economics.
- Industrial:Fertilizer, cement, and steel producers in Egypt and South Africa contract directly for pipeline gas or imported LNG, bypassing national utility intermediaries where regulatory pricing distortions persist.
- Automotive:Compressed natural gas vehicle adoption remains marginal outside Egyptian fleet conversions, constrained by retail refueling infrastructure and gasoline subsidy regimes in major consuming markets.
- Residential:LPG cylinder distribution dominates urban cooking energy in West African cities, with Nigerian and Ghanaian bottling plants serving informal retail networks that national oil companies struggle to formalize.
Power Generation commands contract volume. Industrial buyers negotiate price terms most aggressively.
Technology:
Technology selection tracks water depth and reservoir complexity, with capital intensity filtering participant pools at each tier.
- Enhanced Oil Recovery:Thermal and chemical EOR applications concentrate in mature Algerian and Libyan onshore fields where natural decline rates exceed regional averages. Waterflooding programs in Nigerian coastal assets face funding constraints as operators prioritize greenfield developments.
- Offshore Drilling:Subsea production systems and dynamic positioning rigs unlock Angolan pre-salt and Mozambican deepwater gas reserves, compressing breakeven costs below legacy deepwater benchmarks. Nigerian deepwater licensing rounds specify minimum technical capabilities that exclude marginal contractors.
- Shale Extraction:South African Karoo basin unconventional exploration remains stalled under regulatory moratoria and water access disputes, with no commercial production established despite extensive resource estimates.
- Gas-to-Liquids:Sasol's Secunda complex and Nigerian Escravos plant represent the continent's only operational GTL capacity, converting stranded gas to synthetic diesel and lubricants for premium export markets.
Offshore Drilling absorbs capital fastest. Enhanced Oil Recovery extends field life longest.
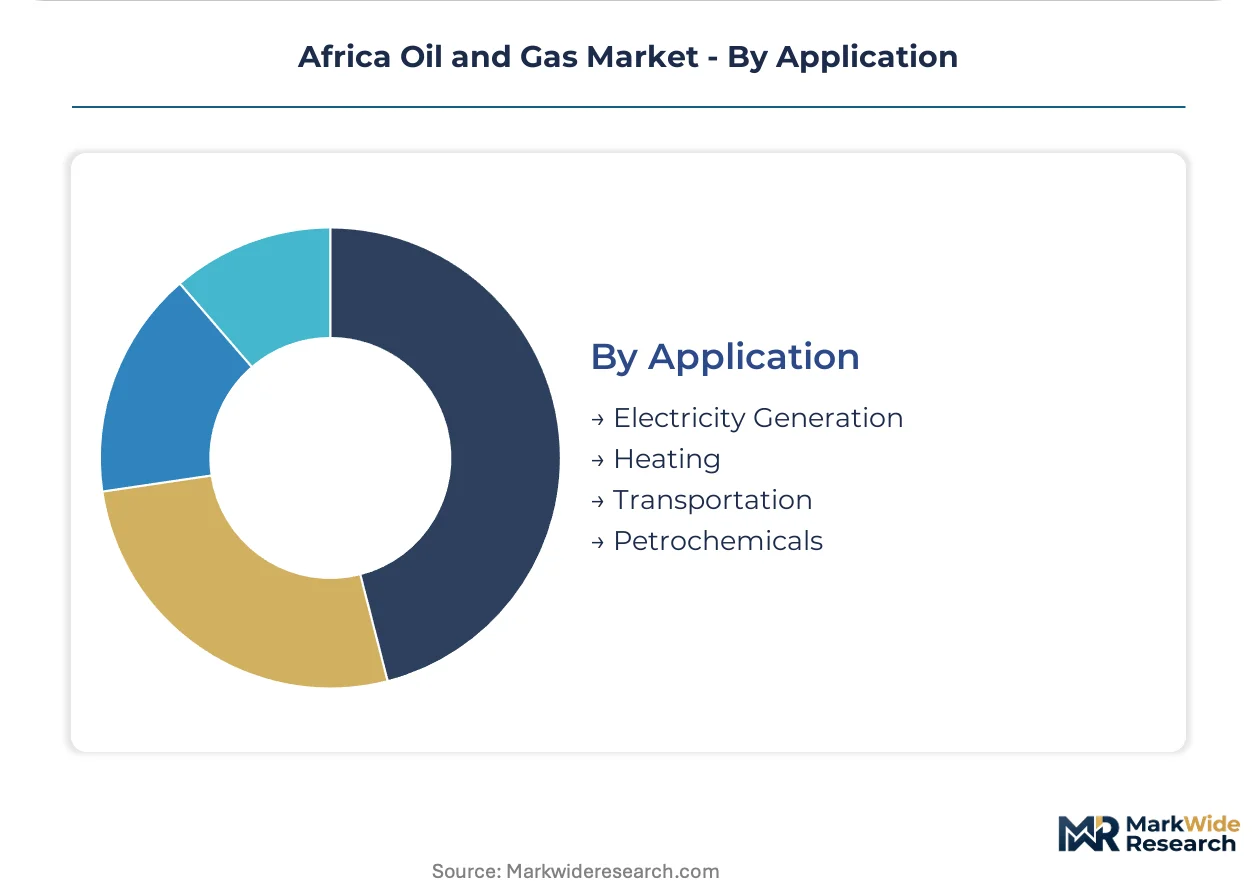
Application:
Application mix determines crude quality requirements and refined product slate, with regional imbalances creating arbitrage opportunities for traders.
- Electricity Generation:Open-cycle gas turbines and combined-cycle plants in Ghana and Côte d'Ivoire anchor regional grid stability, with fuel oil backup capacity retained for dry-season hydropower shortfalls.
- Heating:Industrial process heat in Moroccan phosphates and Tunisian manufacturing consumes light fuel oil and natural gas in parallel, with solar thermal hybrids displacing conventional burners in pilot installations.
- Transportation:Road fuel demand concentrates in Nigerian and Egyptian urban corridors where subsidy regimes distort price signals and incentivize cross-border smuggling into neighboring markets.
- Petrochemicals:Egyptian ethylene crackers and Algerian methanol complexes consume dedicated gas allocations under long-term supply contracts with Sonatrach and EGPC, insulating feedstock costs from spot volatility.
Transportation moves product volume. Petrochemicals capture value-added margin.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
West African offshore basins command capital allocation as exploration budgets pivot toward pre-salt and deepwater targets. Nigeria and Angola anchor upstream investment flows, while East African gas provinces and North African mature fields complete the continental portfolio.
Nigeria
Deepwater licensing rounds under the Petroleum Industry Act attract majors to the Bonga and Egina fields. The Nigerian Upstream Petroleum Regulatory Commission enforces environmental bonds for offshore decommissioning. Lagos-anchored fabrication yards supply subsea manifolds to deepwater developments, though local content quotas inflate procurement timelines.
Angola
Pre-salt carbonate reservoirs in the Kwanza Basin expand recoverable reserve estimates for integrated operators. The National Agency for Petroleum, Gas and Biofuels streamlines concession terms to accelerate project sanctioning. Luanda-based logistics clusters support ultra-deepwater drilling campaigns with specialized marine services.
Mozambique
Offshore Coral field gas feeds onshore liquefaction trains under long-term Asian offtake contracts. The national petroleum regulator coordinates environmental licensing for Rovuma Basin developments. Pemba and Palma port infrastructure expansions address logistics bottlenecks for LNG module assembly.
Algeria
Sonatrach's integrated Saharan field-to-port system dominates North African crude and gas output. The national hydrocarbon law governs production-sharing contract renegotiations for mature onshore concessions. Hassi Messaoud industrial complexes process associated gas for domestic petrochemical feedstock.
Namibia
Orange Basin discoveries establish a new petroleum province with minimal above-ground political risk. The Ministry of Mines and Energy maintains favorable fiscal terms for frontier exploration licenses. Walvis Bay port infrastructure upgrades support offshore supply base operations for deepwater drilling contractors.
Africa Oil and Gas Market Competitive Environment
Portfolio diversification dominates the current landscape as majors rebalance exposure across conventional and frontier acreage. The competitive structure concentrates around integrated national oil companies and international majors with deepwater technical capabilities. Two archetypes define positioning: state-backed vertically integrated operators controlling domestic infrastructure, and technology-led internationals deploying subsea production systems. M&A activity and strategic farm-in arrangements represent the primary competitive moves as players access pre-salt blocks without bearing full exploration risk.
Within the state-backed tier, Sonatrach and Nigerian National Petroleum Corporation exemplify integrated operators with captive pipeline networks and refining assets. Among technology-led internationals, TotalEnergies SE and Shell PLC occupy positions defined by pre-salt drilling expertise and LNG portfolio scale. These entities anchor competitive dynamics through their control of capital-intensive deepwater projects and long-term offtake contracting relationships.
| Leading Market Players |
|---|
| Shell PLC |
| TotalEnergies SE |
| Eni SpA |
| Exxon Mobil Corporation |
| Nigerian National Petroleum Corporation |
| Sonatrach |
| National Oil Corporation of Libya |
| Sonangol |
| Equinor |
| Others |
Value Chain & Pricing Dynamics
Subsea engineering specialists concentrated in Luanda and Lagos fabrication yards drive labor-cost differentials that widen pricing spreads between premium integrated service contracts and economy-tier equipment procurement. Nigerian Petroleum Industry Act local content quotas inflate wage premiums for certified welders and riser designers, compressing margins for contractors unable to source indigenous talent.
Pricing Analysis
Input-cost pass-through dominates contract structures as steel tariffs and day-rate volatility for high-specification drillships feed directly into project economics. Pricing stratifies across premium integrated EPCI bundles, standard discrete equipment procurement, and economy-tier maintenance contracts differentiated by technical complexity and contractor liability exposure. Pricing pressure stems from capital discipline among majors deferring FID timelines in frontier basins. National oil companies exhibit lowest price sensitivity due to captive offtake mandates, while independent operators negotiate hardest on drilling unit costs.
Supply Chain Analysis
Nigeria's Petroleum Industry Act local content mandates reshape sourcing patterns by requiring escalating domestic procurement quotas for subsea manifolds and wellhead systems. Supply concentration rests on South Korean fabrication yards for subsea production systems, Singapore for dynamic positioning rig refurbishment, and indigenous Nigerian yards for lower-complexity structural components. Raw material dependencies center on high-grade steel plate, subsea umbilicals, and dynamic positioning thruster packages. Single-source vulnerability concentrates in subsea control system vendors. Distribution runs through Lagos and Luanda port clusters serving deepwater drilling campaigns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Africa oil and gas functions as a stable compounder anchored by power generation demand that locks in long-term gas offtake contracts across Nigerian and Angolan grids.
For Market Incumbents: To counter pre-salt exploration cost escalation and talent shortages, anchor defensive positions through backward integration into subsea engineering capabilities and captive training academies in Luanda and Port Harcourt. Lock in long-term rig contracts at current day rates before renewal cycles tighten availability.
For New Entrants and Emerging Players: The premium-economy pricing gap in well intervention and maintenance services creates entry space for mid-tier contractors with modular asset-light models. Target marginal Nigerian onshore fields abandoned by majors for production enhancement contracts. Lead with digital reservoir characterization partnerships to differentiate from legacy service incumbents.
For Investors and Strategic Acquirers: Integrated majors with LNG portfolios are the most active acquirer in this space, seeking pre-salt farm-in opportunities without full exploration risk exposure. Long-term viability centers on 5-10 year reserve replacement trajectories in frontier basins. Watch Namibian Orange Basin appraisal drilling as the signal for new province opening.
| Strategic Initiative | Industry Significance |
|---|---|
| Pre-salt Farm-in Agreement | Transfers exploration risk while securing reserve access in Angola's Kwanza Basin. |
| LNG Offtake Contracting | Anchors Mozambique Coral field development economics through Asian buyer commitments. |
| Subsea Engineering Training Academy | Addresses talent bottlenecks for deepwater riser design and flow assurance. |
| Associated Gas Capture Infrastructure | Monetizes previously flared volumes under Nigerian flaring reduction mandates. |
| Digital Reservoir Characterization Platform | Compresses exploration timelines through machine learning seismic processing. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with upstream project managers, subsea procurement leads, national petroleum regulator officials, and drilling contractor operations heads with secondary validation against EIA data, IEA Africa Energy Outlook, national hydrocarbon agency production statistics, and project finance databases. Bottom-up field-level production estimates and top-down macro demand projections were cross-checked for consistency.
Comparable-period anchoring tied forward projections to historical production trajectories across mature Nigerian onshore assets and emerging Angolan pre-salt clusters. The analytical framework modeled segmentation dimensions spanning service type, end-use vertical, technology tier, and water-depth classification. CAGRs were derived from production capacity buildout schedules and demand elasticity assumptions for power generation offtake. Forecast inputs incorporated licensing round timelines and fiscal term stability clauses under the Petroleum Industry Act.
Caveats apply where regulatory revision, carbon border adjustment implementation, or subsea equipment supply disruptions could materially shift the outlook. Forecasts reflect assumptions around project sanctioning timelines and offtake contract durability. A small set of triggers—Namibian appraisal results, Nigerian refinery commissioning, and LNG buyer contract renegotiations—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Canada Oil and Gas Upstream Market
Oil & Gas
Downhole Drilling Tools Market
Oil & Gas
Europe Hydraulic Fracturing Fluids Market
Oil & Gas
Smart Pipeline Pigging Market
Oil & Gas
Upstream Services Market
Oil & Gas
Oil and Gas MIC Testing Market
Oil & Gas
Open Hole Logging Services Market
Oil & Gas
Southeast Asia Oil and Gas Downstream Market
Oil & Gas
North America Artificial Lift Systems Market
Oil & Gas
Malaysia Oil and Gas Pipeline Market
Oil & Gas
South and Central America Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Indonesia Oil and Gas Market
Oil & Gas
Kuwait Oil and Gas Market
Oil & Gas
Oil and Gas Logistics Market
Oil & Gas
Africa Drilling and Completion Fluids Market
Oil & Gas
Drilling Mud Desander and Desilter Market