
 Digital Oil Field Technology Market | 2026-2036
Digital Oil Field Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Oil Field Technology Market Outlook
The EU Green Deal's methane emissions monitoring requirements is shifting procurement priorities across European offshore operators. SLB leverages its integrated DELFI cognitive E&P environment to anchor digital twin deployments across multiple North Sea assets. Halliburton competes through Landmark DecisionSpace 365, which sustains cloud-native reservoir simulation workflows for production optimization. Baker Hughes Company differentiates via its Asset Performance Management suite, which controls predictive maintenance contracts for subsea infrastructure.
Digital Oil Field Technology encompasses the integration of IoT sensors, cloud computing platforms, AI algorithms, and wireless communication networks to automate hydrocarbon exploration, production, and asset management decisions. These systems process real-time downhole pressure, temperature, and flow rate data at edge computing nodes, transmitting filtered intelligence to centralized analytics engines for reservoir optimization and equipment failure prediction. IoT Sensors and AI Algorithms together represent the fastest-expanding technology pairing, as edge-deployed inference models reduce latency for critical well control decisions. Cloud-Based deployment now captures the dominant share of new implementations, though Hybrid architectures retain strong positioning where latency-sensitive drilling operations require localized processing.
The US EPA's methane performance standards and Norway's Petroleum Safety Authority digitalization directives together shape platform retrofit timelines and sensor certification requirements for operators seeking regulatory compliance. REACH chemical restrictions on offshore electronics coatings further constrain component sourcing for North Sea deployments. Stakeholders must monitor evolving EU AI Act risk classifications for automated well control systems, as pending algorithmic transparency mandates could reshape vendor liability structures and procurement specifications.
Market Dynamics
The EU Green Deal's methane emissions monitoring requirements is compressing procurement timelines for real-time leak detection systems across European offshore operators, forcing integrated platform retrofits ahead of regulatory deadlines.
Growth Catalysts
- EU Green Deal methane mandates:Mandatory emissions monitoring is accelerating sensor deployment across North Sea offshore platforms. Operators now prioritize real-time detection infrastructure to meet compliance deadlines.
- Edge computing inference models:Latency reduction for critical well control decisions is expanding AI algorithm deployment at the network edge. This architecture enables autonomous responses without cloud dependency.
- Norway's Johan Sverdrup cluster:Full digital twin deployment across subsurface through topside operations is establishing reference architecture for adjacent field developments. Neighboring operators replicate this integrated asset management model.
Market Restraints
- REACH chemical restrictions:Offshore electronics coatings face constrained component sourcing for North Sea deployments. Suppliers must reformulate protective materials to meet ECHA substance limitations.
- Hybrid architecture capex burden:Latency-sensitive drilling operations require localized processing infrastructure alongside cloud investments. Dual-stack deployment doubles initial hardware expenditure versus pure cloud alternatives.
- Subsea infrastructure supplier concentration:Predictive maintenance contract awards cluster among integrated service providers with captive equipment fleets. Independent operators face exclusion from bundled performance guarantees.
Strategic Opportunities
- EU AI Act algorithmic transparency mandates:Pending vendor liability reclassifications create first-mover advantage for vendors with documented model governance. Procurement specifications will favor suppliers with pre-certified automated well control systems.
- Integrated asset management platform convergence:Cloud-native reservoir simulation workflows are merging with cognitive E&P environments. Vendors controlling both simulation engines and production optimization layers capture expanded contract scope.
- Wireless communication network densification:5G private networks for offshore platforms remain underdeployed outside Norway's advanced fields. Early infrastructure builders secure anchor tenant positions for multi-asset connectivity contracts.
Industry Challenges
- Petroleum Safety Authority digitalization directive compliance:Platform retrofit timelines require synchronized sensor certification across multiple vendor systems. Integration testing delays cascade into operational readiness schedules.
- Subsurface-to-topside data fusion expertise:Reservoir engineers with cross-domain digital twin competency remain scarce. Training pipelines for integrated asset management specialists lag deployment demand by multiple years.
- Legacy SCADA system interoperability:Brownfield installations require protocol translation layers for modern IoT sensor integration. Middleware complexity introduces failure points and maintenance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Oil Field Technology Market |
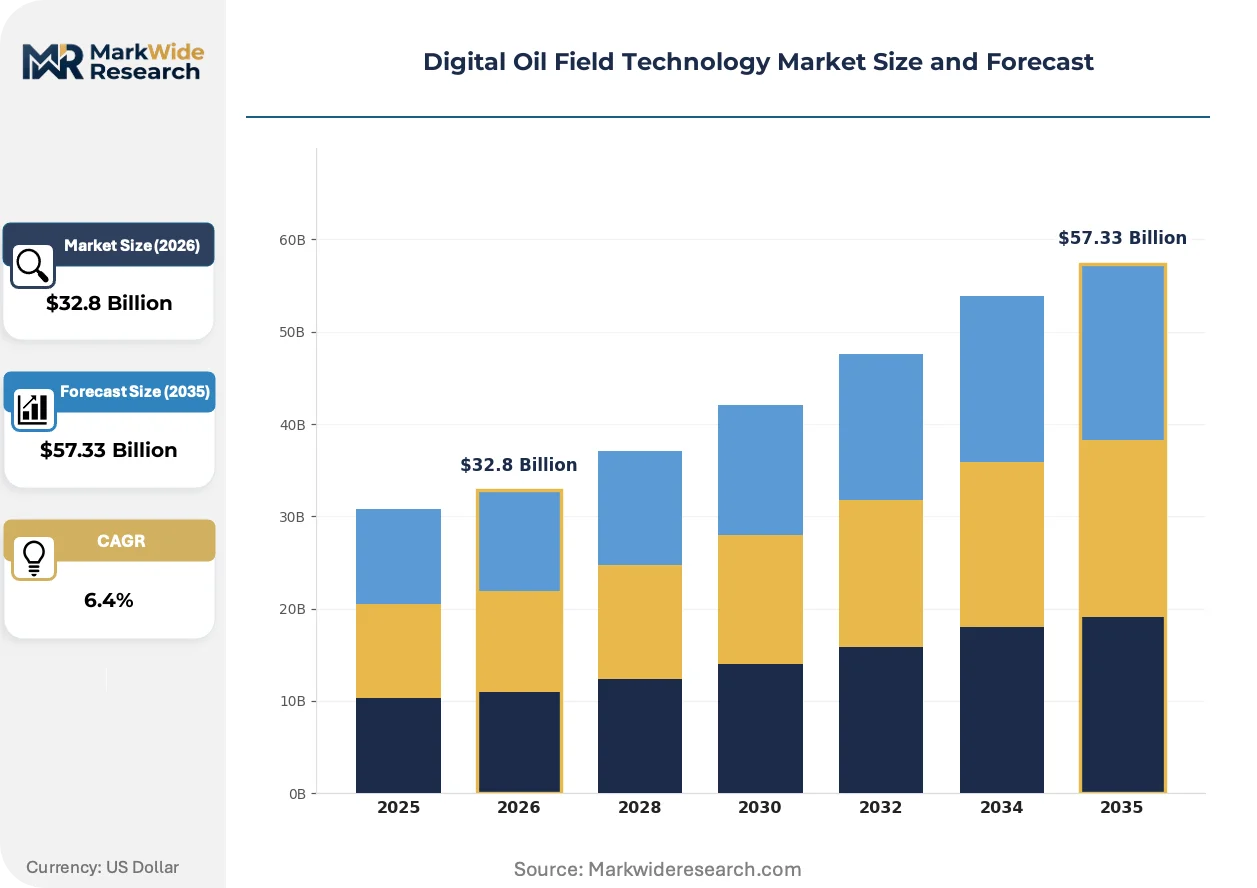
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Data Management, Remote Monitoring, Predictive Analytics, Automation Software Technology: IoT Sensors, Cloud Computing, AI Algorithms, Wireless Communication End User: Exploration Companies, Production Companies, Service Providers, Asset Management Firms Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | SLB, Halliburton, Baker Hughes Company, Weatherford, NOV Inc., Emerson Electric Co., Honeywell International Inc., Pason Systems Corp., Kongsberg Digital, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Oil Field Technology Market Strategic Shifts
Digital twin architectures are absorbing adjacent functionality layers, compressing vendor stacks and reshaping competitive boundaries across reservoir-to-facility workflows.
Edge-deployed AI inference is consolidating wellhead automation decisions previously distributed across cloud and manual intervention layers. Offshore operators in the North Sea now mandate sub-100-millisecond response times for pressure anomaly detection. This latency threshold is consolidating vendor selection around integrated hardware-software providers with captive silicon optimization capabilities.
The EU AI Act's risk classification framework for automated well control systems is forcing algorithmic audit trail investments across European deployments. Vendors must document model training data provenance and decision logic explainability. Subsea infrastructure operators face the steepest compliance burden given the catastrophic consequence ratings assigned to uncontrolled blowout scenarios.
Performance-based contracting is displacing capital equipment sales for sensor and analytics packages. Norwegian operators now specify methane emissions reduction guarantees rather than hardware procurement volumes. This model transfers operational risk to vendors while compressing upfront field development budgets for Equinor-operated clusters.
Digital Oil Field Technology Market Segmentation
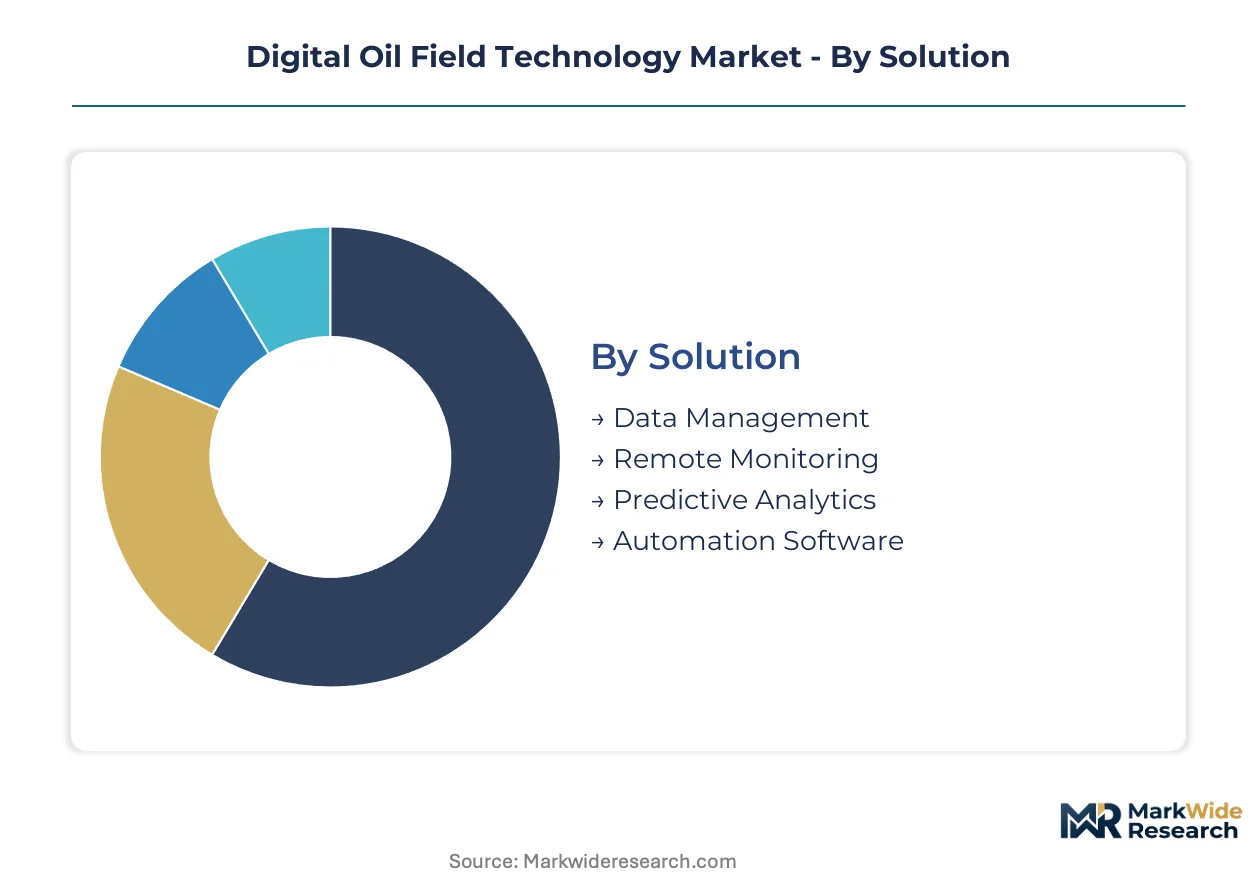
Segmentation in the Digital Oil Field Technology Market reveals distinct procurement patterns across operator types and deployment architectures. Buyers prioritize different solution bundles based on field maturity, regulatory exposure, and infrastructure legacy.
Solution:
Operators differentiate procurement priorities by their position in the field lifecycle and regulatory compliance burden.
- Predictive Analytics:Machine learning models process real-time downhole pressure and flow rate data to forecast equipment failures before critical thresholds. Demand concentrates among production companies operating mature North Sea assets where unplanned downtime costs exceed retrofit investment. EU Green Deal methane mandates accelerate contract awards for emissions prediction modules.
- Data Management:Centralized platforms aggregate subsurface through topside data streams into unified reservoir models. Exploration companies in Norway's Johan Sverdrup cluster deploy these systems to synchronize geological interpretation with drilling execution. Integration complexity with legacy SCADA networks constrains adoption timelines.
- Remote Monitoring:Distributed sensor networks transmit wellhead parameters to onshore control centers, reducing offshore staffing requirements.
- Automation Software:Closed-loop control systems execute pressure and flow adjustments without human intervention for routine optimization.
Data Management leads volumes today; Predictive Analytics is gaining share fastest.
Technology:
Technology selection hinges on latency tolerance and data sovereignty requirements across offshore and onshore operations.
- IoT Sensors:Downhole pressure-temperature gauges and surface flow meters generate the raw data streams powering digital twin architectures. Deployment concentrates in Norway's Equinor-operated fields where full-field sensor coverage enables real-time reservoir optimization. REACH chemical restrictions on offshore electronics coatings constrain supplier qualification.
- AI Algorithms:Edge-deployed inference models execute well control decisions within sub-100-millisecond windows for pressure anomaly response. Production companies prioritize these deployments where cloud latency risks operational safety. EU AI Act algorithmic transparency mandates reshape vendor certification requirements.
- Cloud Computing:Scalable processing infrastructure hosts reservoir simulation and historical data analytics without capital-intensive on-premise hardware.
- Wireless Communication:Private 5G networks and satellite links connect offshore platforms to onshore analytics centers.
Cloud Computing anchors current infrastructure spend; AI Algorithms show the steepest expansion trajectory.
End User:
End user categories reflect divergent risk appetites for capital deployment versus operational outsourcing.
- Production Companies:Integrated operators with captive field portfolios deploy full-stack digital twin environments across subsurface through topside workflows. Norway's Petroleum Safety Authority digitalization directives compress their platform retrofit timelines. These buyers specify integrated asset management platforms with performance-based methane reduction guarantees.
- Service Providers:Drilling contractors and subsea specialists purchase predictive maintenance modules to differentiate equipment rental packages. Predictive maintenance contract concentration among integrated vendors limits independent operator access to bundled performance guarantees.
- Exploration Companies:Focused upstream players prioritize exploration-specific data management and geological modeling solutions.
- Asset Management Firms:Financial investors in oil and gas portfolios deploy monitoring dashboards for portfolio-level risk visibility.
Production Companies dominate contract value; Service Providers are expanding procurement most aggressively.
Deployment:
Deployment architecture selection trades operational autonomy against infrastructure cost and cybersecurity exposure.
- Cloud-Based:Fully hosted solutions eliminate on-premise hardware maintenance and enable rapid scaling across field portfolios. Adoption concentrates among exploration companies and smaller production operators without legacy SCADA investments. Cybersecurity concerns around critical infrastructure connectivity moderate deployment in latency-sensitive applications.
- Hybrid:Split architectures process latency-critical drilling data locally while transmitting filtered aggregates to cloud analytics engines. North Sea operators with brownfield installations favor this model to preserve existing infrastructure while adding modern capabilities. Dual-stack requirements double initial hardware expenditure versus pure cloud alternatives.
- Edge Computing:Localized processing nodes execute AI inference at the wellhead without network dependency for safety-critical decisions.
- On-Premise:Air-gapped installations serve operators with strict data sovereignty or cybersecurity requirements.
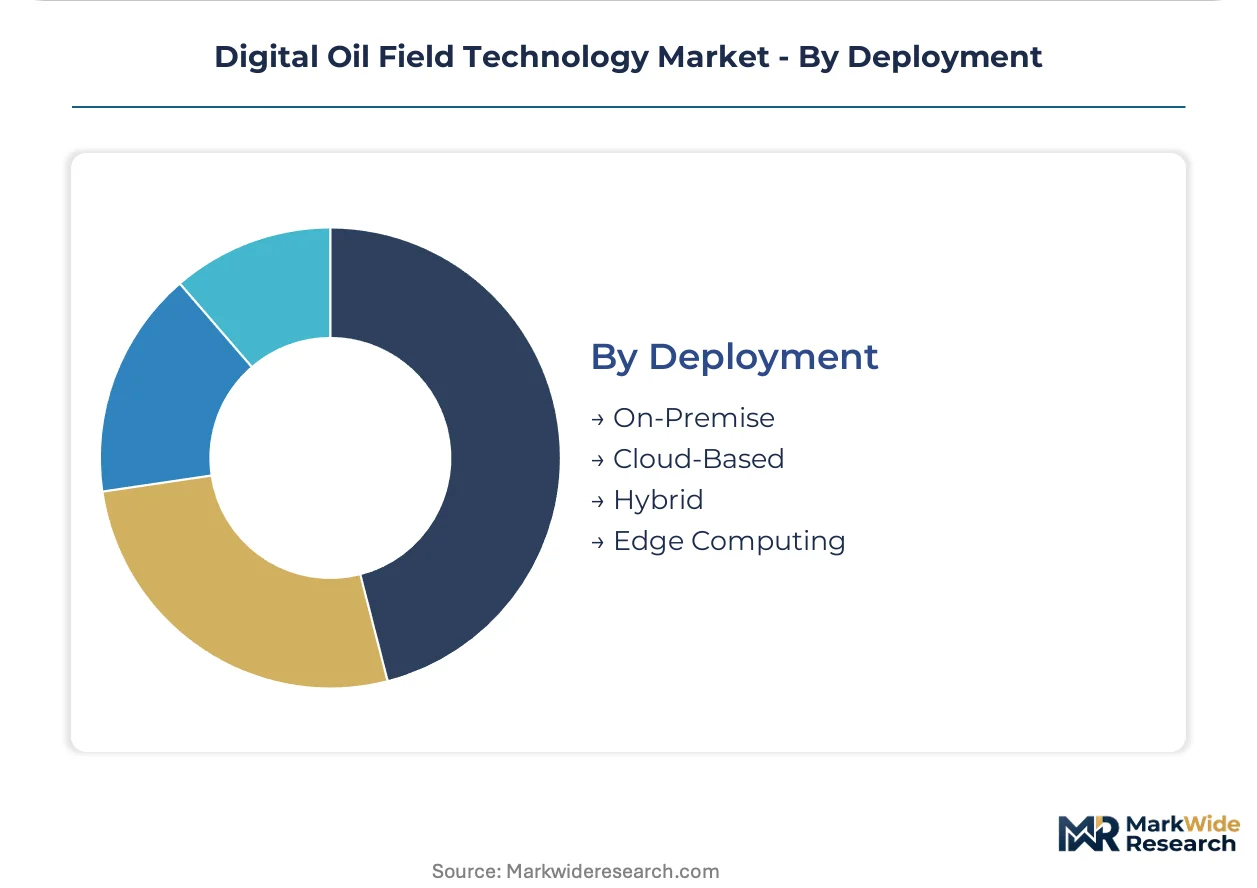
Cloud-Based deployment captures the majority of new implementations; Hybrid architectures are climbing fastest among brownfield retrofits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Digital oil field technology originated in the North Sea during the 1990s integrated operations experiments, then scaled through Norwegian deepwater developments before spreading to US shale basins and Middle East megaprojects. Today deployment patterns track regulatory stringency and field complexity rather than reserve volume alone.
Norway
Equinor's Johan Sverdrup cluster drives full-field digital twin adoption from subsurface through topside operations. The Petroleum Safety Authority's digitalization directives compress platform retrofit timelines for operators seeking operational readiness. Bergen and Stavanger host concentrated vendor engineering centers serving adjacent North Sea developments.
United States
Permian Basin operators deploy edge computing nodes for latency-sensitive drilling decisions across dispersed shale pads. EPA methane performance standards accelerate procurement of real-time leak detection infrastructure. Houston anchors service company headquarters clusters while Midland hosts field-specific technology integration centers.
United Kingdom
Mature North Sea assets prioritize predictive maintenance modules to extend platform economic life against decommissioning timelines. The North Sea Transition Authority's emissions reduction targets reshape capital allocation toward monitoring infrastructure. Aberdeen maintains specialized subsurface-to-topside data fusion expertise pools despite industry contraction.
Saudi Arabia
Saudi Aramco's mega-projects integrate cognitive E&P environments across onshore and offshore developments simultaneously. The national oil company's in-house technology unit drives localization requirements for foreign vendor partnerships. Dhahran's research complex anchors regional digitalization capability building for adjacent Gulf operators.
Brazil
Pre-salt deepwater fields require autonomous well control systems given subsea infrastructure complexity and distance from shore. The national petroleum regulator's safety case requirements mandate redundant sensor coverage for critical pressure barriers. Rio de Janeiro hosts integrated service provider engineering centers serving Campos and Santos basin developments.
Digital Oil Field Technology Market Competitive Environment
Premium-margin players sit above commodity-margin players across solution integration depth, with full-stack digital twin providers commanding pricing power against point-solution vendors. The vendor base clusters around three strategic archetypes: integrated oilfield service conglomerates with captive equipment fleets, industrial automation specialists leveraging cross-sector technology transfer, and pure-play digital natives with cloud-native architectures. Consolidation pressure runs through bundled performance contracts that exclude independent operators from methane reduction guarantee structures. Geographic expansion and technology licensing represent the dominant competitive vectors as vendors seek anchor tenant positions in underdeployed 5G offshore networks.
Within the integrated service tier, SLB, Halliburton, and Baker Hughes Company exemplify archetype positioning through their respective cognitive E&P environments, cloud-native simulation workflows, and asset performance management suites. These Houston-based entities occupy positions shaped by decades of North Sea and Gulf of Mexico deployment experience. Kongsberg Digital represents the regional specialist archetype, leveraging Norwegian regulatory proximity and Johan Sverdrup reference architecture access. Emerson Electric Co. and Honeywell International Inc. anchor the industrial automation crossover segment, transferring process control expertise from downstream and chemical sectors into hydrocarbon production contexts.
| Leading Market Players |
|---|
| SLB |
| Halliburton |
| Baker Hughes Company |
| Weatherford |
| NOV Inc. |
| Emerson Electric Co. |
| Honeywell International Inc. |
| Pason Systems Corp. |
| Kongsberg Digital |
| Others |
Value Chain & Pricing Dynamics
Reservoir engineers with cross-domain digital twin competency concentrated in Norway's Stavanger-Bergen corridor command 40-60% compensation premiums over generalist petroleum software developers, compressing margins for vendors competing on standard analytics tiers while enabling premium pricing for integrated asset management suites.
Pricing Analysis
Performance-based contracting with methane reduction guarantees anchors the dominant pricing structure across North Sea deployments, displacing traditional hardware procurement models. Price differentiation hinges on EU AI Act pre-certification status and bundled predictive maintenance scope. Cost compression in cloud-native simulation tiers is intensifying because hyperscaler infrastructure commoditizes storage and compute. Exploration companies with limited legacy SCADA investments exhibit highest price sensitivity, while Equinor-operated production clusters prioritize outcome guarantees over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with subsea sensor coating suppliers facing REACH substance restrictions, forcing reformulation timelines that cascade into platform retrofit schedules. Component manufacturing concentrates in Germany, Norway, and the United States for high-reliability electronics. Supply chains draw from rare earth elements for downhole pressure gauges, specialized semiconductor substrates for edge computing nodes, and fluoropolymer coatings for offshore corrosion protection. Tariff exposure on Chinese-sourced electronics components threatens margin stability. Distribution runs through integrated service providers with captive equipment fleets, excluding independent operators from bundled performance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital oil field technology procurement functions as a geographic-arbitrage play between Norway's stringent Petroleum Safety Authority digitalization mandates and the US EPA's methane performance standards, with compliance cost differentials favoring vendors with dual-jurisdiction certification capabilities.
For Market Incumbents: Deploy algorithmic audit trail investments to capture EU AI Act first-mover advantage as regulatory compliance becomes a pricing lever. Consolidate subsurface-to-topside data fusion expertise through targeted hiring in Aberdeen and Stavanger to defend against cloud-native entrants. Backward integration into edge computing silicon optimization protects sub-100-millisecond response time guarantees that anchor premium tier positioning. For New Entrants and Emerging Players: Launch via wireless communication infrastructure buildouts for underdeployed 5G private networks outside Norway's advanced fields, securing anchor tenant positions before integrated service providers densify coverage. Target mature North Sea assets in the United Kingdom where predictive maintenance modules address decommissioning timeline pressures with lower competitive density than Norwegian greenfield developments. Emphasize protocol translation layers for legacy SCADA interoperability as the primary technical wedge. For Investors and Strategic Acquirers: Industrial automation specialists with cross-sector process control expertise represent the most active acquirer category in this space, transferring downstream chemical sector capabilities into hydrocarbon production contexts. Acquisition targets with pre-certified automated well control systems and documented model governance frameworks offer defensive positioning against pending vendor liability reclassifications. Monitor EU AI Act implementation timelines as the critical inflection signal for procurement specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Transparency Certification | EU AI Act compliance creates vendor liability differentiation for automated well control systems. |
| 5G Private Network Infrastructure Buildout | Early deployment in underpenetrated offshore fields secures multi-asset connectivity contracts. |
| Subsurface-to-Topside Data Fusion Capability | Cross-domain expertise scarcity in Stavanger-Bergen corridor commands premium labor pricing. |
| Performance-Based Methane Guarantee Contracts | Norwegian operators now specify emissions reduction outcomes rather than hardware volumes. |
| Legacy SCADA Protocol Translation Development | Brownfield retrofit demand in UK North Sea creates middleware revenue streams. |
Study Parameters
Multiple input streams — primary interviews with reservoir engineers and platform asset managers, regulatory filing analysis from the Petroleum Safety Authority and EPA, and vendor contract documentation — were reconciled against secondary validation from EIA production databases, IEA digitalization reports, and SEC disclosures from integrated service providers. Bottom-up field deployment tallies were triangulated with top-down market sizing across solution, technology, end user, and deployment architecture segments.
Historical capital expenditure patterns were cross-referenced against executive panel input from digital transformation leads at Equinor, BP, and Shell to anchor growth assumptions across the projection horizon. Segmentation modeling incorporated solution type, technology pairing, operator category, and deployment architecture dimensions. CAGRs were derived from regression analysis against regulatory mandate timelines and field development sanctioning patterns, with specific weighting for Johan Sverdrup cluster replication effects and EU Green Deal compliance deadlines.
Several conditions sit outside the modeled scope, including potential revisions to REACH chemical restrictions, delays in EU AI Act risk classification finalization, and geopolitical disruptions to subsea equipment supply chains. Forecasts reflect assumptions about continued regulatory enforcement stringency and operator willingness to outsource operational risk through performance-based contracts. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Sidetracking Market
Oil & Gas
Global Upstream Petrotechnical Training Services Market
Oil & Gas
Kuwait Oil and Gas Upstream Market
Oil & Gas
Oilfield Equipment Rental Services Market
Oil & Gas
Oilfield Casing Spools Market
Oil & Gas
Containment and Handling Drilling Waste Management Market
Oil & Gas
Middle East and Africa Drilling Market
Oil & Gas
United States Artificial Lift Systems Market
Oil & Gas
Crude Oil Carriers Market
Oil & Gas
Middle East and Africa Pipeline Maintenance Market
Oil & Gas
North America Seismic Services Market
Oil & Gas
Indonesia Oil and Gas Midstream Market
Oil & Gas
Global Seismic Survey Market
Oil & Gas
Republic of Congo Oil and Gas Market
Oil & Gas
Oil and Gas Data Management Market
Oil & Gas
Gold Mining Market