
 Global Upstream Petrotechnical Training Services Market | 2026-2036
Global Upstream Petrotechnical Training Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Upstream Petrotechnical Training Services Market Intelligence
Brazil's expansion of its pre-salt deepwater exploration is reshaping the competitive positioning for petrotechnical training providers. PetroSkills leverages its extensive geoscience and engineering curriculum to serve major operators in this region. Halliburton competes by integrating its proprietary software training with hands-on operational courses. In parallel, IFP Training specializes in delivering customized programs for national oil companies managing complex reservoir characterization projects, solidifying its niche in government-led initiatives.
Upstream petrotechnical training services encompass specialized educational and vocational programs designed for professionals in the oil and gas exploration and production sector. These services provide instruction on technical disciplines including reservoir simulation, drilling techniques, and well logging interpretation. The primary purpose is to enhance operational efficiency, ensure safety compliance, and maximize hydrocarbon recovery. Among delivery models, blended learning is displacing purely classroom-based instruction. Training focused on production optimization and advanced geoscience skills represents a high-margin service area for providers.
Regulatory frameworks from bodies such as the U.S. Occupational Safety and Health Administration (OSHA) and safety directives from authorities in the United Kingdom and Norway mandate specific training for offshore personnel. These regulations directly influence the curriculum and certification requirements for courses on safety protocols and environmental compliance. Providers' ability to integrate virtual reality and digital twin simulations for complex operational scenarios will increasingly define their market leadership.
Market Dynamics
The central force shaping the market is the industry's pivot toward more technologically complex hydrocarbon extraction, such as in deepwater and unconventional resource plays. This shift necessitates continuous upskilling of the workforce, creating sustained demand for specialized training.
Growth Catalysts
- New Exploration Frontiers:The development of major offshore discoveries in regions like Guyana and Brazil creates intense demand for training services to equip both local and expatriate workforces with specialized deepwater operational skills.
- Digitalization of Operations:The adoption of digital twin technologies and advanced data analytics in reservoir management requires E&P companies to invest heavily in training personnel on new software and simulation platforms.
- Stringent Safety Mandates:Regulations from authorities in the United Kingdom and Norway, alongside OSHA standards in the U.S., compel operators to provide continuous, certified training in well control and offshore survival protocols.
Market Restraints
- High Capital Expenditure:The significant investment required to develop and maintain high-fidelity simulators, such as digital twins for drilling scenarios, creates a high barrier to entry for smaller training providers.
- In-House Program Development:Major exploration and production firms are increasingly developing internal training curricula, particularly for proprietary workflows, reducing the addressable market for external vendors.
- Commodity Price Volatility:Training budgets are highly susceptible to fluctuations in crude oil prices, with operators frequently deferring or canceling non-essential professional development during market downturns to conserve cash flow.
Strategic Opportunities
- Energy Transition Curricula:Developing specialized training modules focused on carbon capture, utilization, and storage (CCUS) and methane emissions management offers a new service line for E&P clients navigating decarbonization goals.
- AI-Integrated Simulation:The convergence of artificial intelligence with traditional reservoir simulation software creates an opportunity to offer advanced predictive modeling and operational optimization training courses.
- African Market Expansion:Providing tailored training programs for national oil companies and local workforces in emerging African oil and gas markets, such as Namibia and Mozambique, represents a significant geographic growth vector.
Industry Challenges
- Instructor Skill Scarcity:A persistent challenge is the shortage of qualified instructors who possess dual expertise in traditional petrotechnical disciplines and emerging fields like data science and machine learning.
- Certification Fragmentation:The absence of universally recognized certification standards for advanced digital oilfield competencies complicates curriculum development and reduces the portability of credentials for professionals across different regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Upstream Petrotechnical Training Services Market |
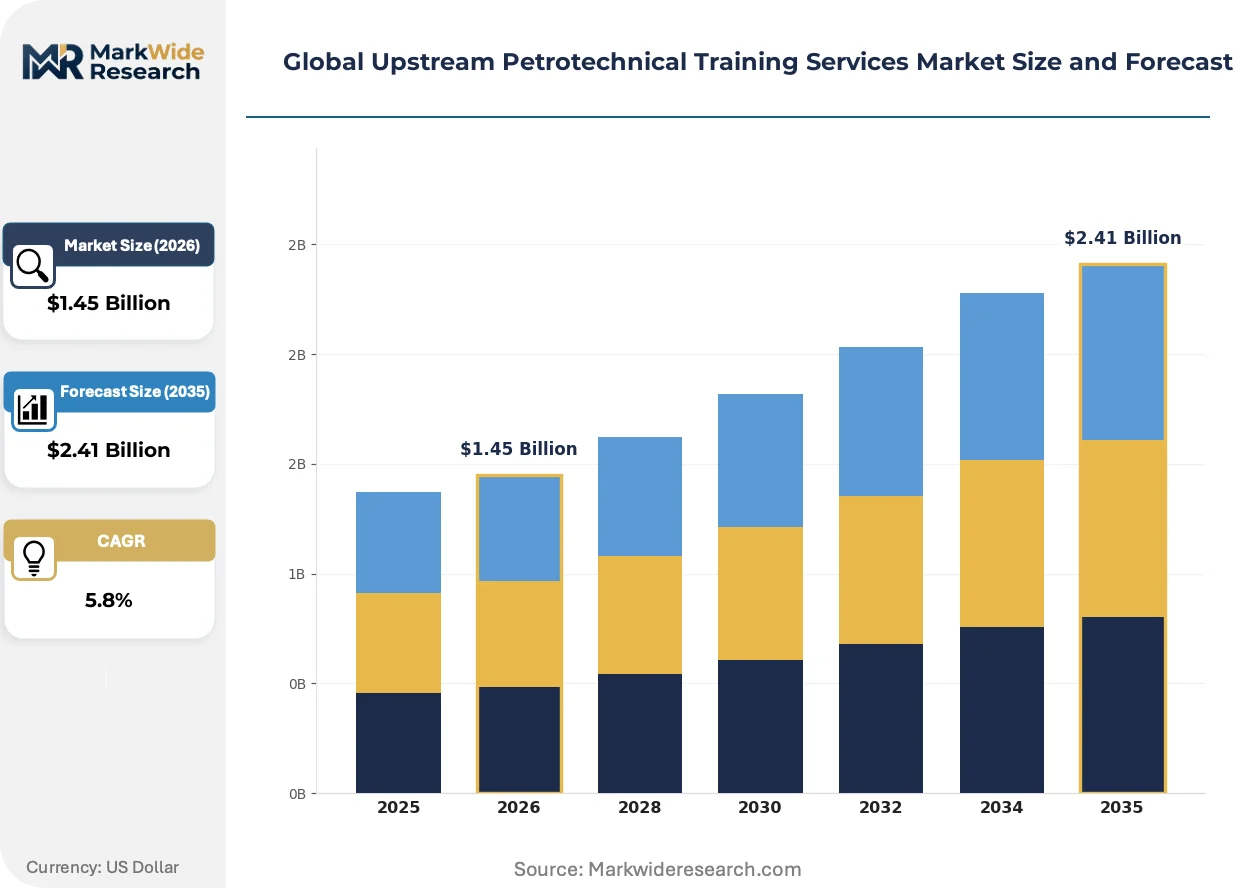
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $2.41 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Reservoir Simulation, Drilling Techniques, Production Optimization, Well Logging, Safety Protocols Delivery Model: Online Learning, Classroom Training, On-site Workshops, Virtual Reality, Blended Learning Client Type: Exploration Firms, Drilling Contractors, Oilfield Services, Government Agencies, Engineering Consultants Training Focus: Geoscience Skills, Engineering Practices, Environmental Compliance, Health & Safety, Project Management |
| Companies Covered | PetroSkills, IHRDC, IFP Training, PetroEdge, Petroknowledge, HOT Engineering, Petrofac Limited, Baker Hughes, Halliburton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Upstream Petrotechnical Training Services Market Strategic Shifts & Innovations
A fundamental shift toward data-centric operations and specialized skill sets is defining the evolution of petrotechnical training. Service providers are adapting curricula to address the convergence of geoscience with digital technologies, driven by operational efficiency and safety imperatives.
Virtual reality and digital twin simulations provide immersive, risk-free environments for complex operational training. Exploration and production companies are adopting these tools to prepare personnel for well control incidents and deepwater equipment handling. This technology is digitizing traditional hands-on learning, allowing for repeatable practice on high-consequence scenarios without physical asset risk or downtime.
Heightened environmental standards, such as stricter emissions monitoring rules from the U.S. Environmental Protection Agency (EPA) and similar bodies in Europe, are creating new training requirements. These regulations compel operators to invest in curriculum focused on methane leak detection and environmental compliance reporting. Offshore production and drilling segments are most impacted, needing certified programs to ensure regulatory adherence.
A clear behavioral shift sees clients moving away from standardized, multi-week courses toward modular, on-demand blended learning formats. This change disrupts providers reliant on fixed-schedule classroom instruction, favoring those with flexible digital content libraries. This preference for customized, just-in-time training is particularly evident among drilling contractors and in new exploration hubs like Guyana, where rapid upskilling is critical.
Global Upstream Petrotechnical Training Services Market Segmentation
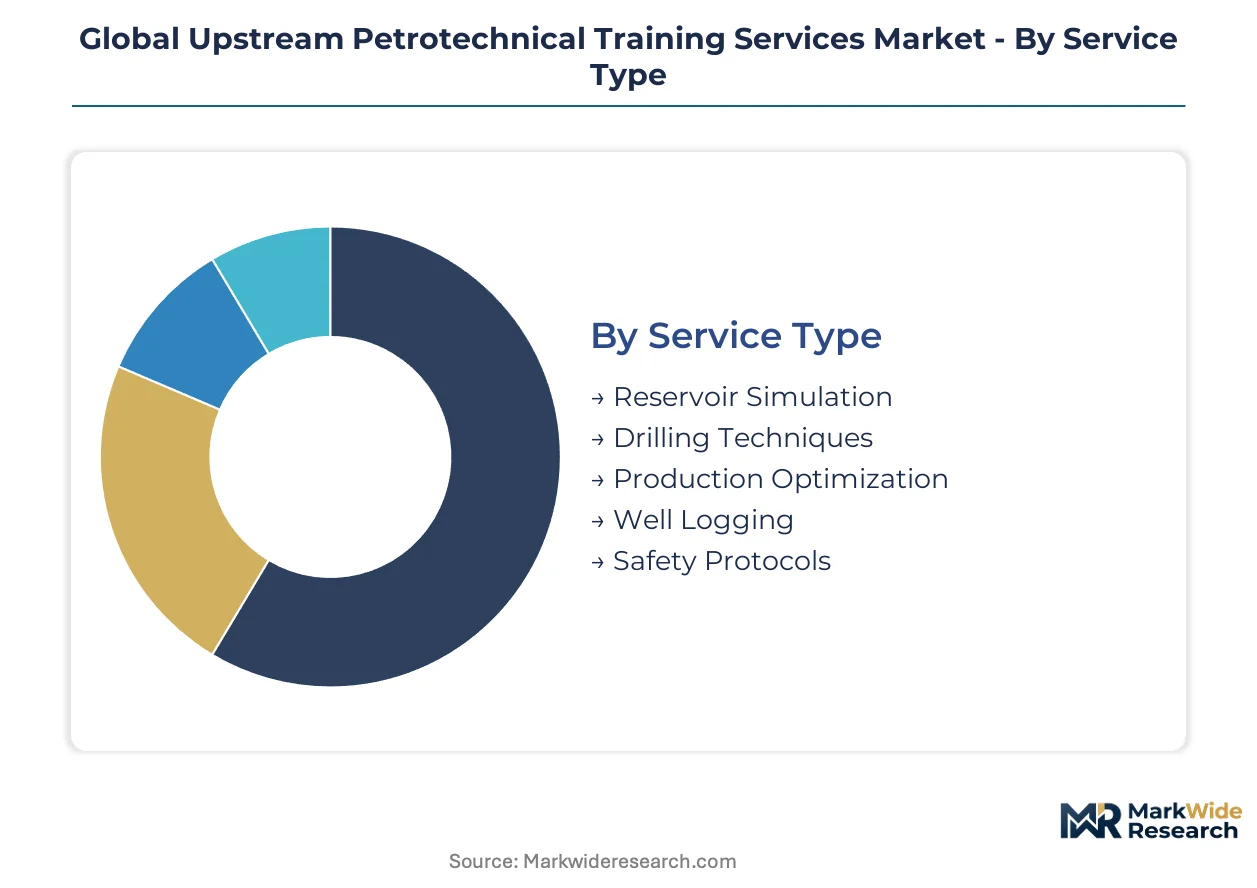
Segmentation analysis provides a granular view of the Global Upstream Petrotechnical Training Services Market, highlighting the diverse needs and operational contexts driving demand. Understanding these segments is crucial for providers to tailor offerings and for clients to identify suitable training solutions. The market exhibits distinct preferences across service types, delivery models, client categories, and training focus areas.
Service Type:
The service type segmentation reveals a blend of mature foundational competencies and emerging specialized areas within petrotechnical training.
- Drilling Techniques:Instruction covers advanced drilling methodologies, wellbore stability, and directional drilling principles. Demand concentrates in new deepwater exploration frontiers like Brazil, driven by the need for complex operational expertise.
- Production Optimization:Programs focus on maximizing hydrocarbon recovery through enhanced oil recovery techniques and artificial lift systems. Demand is strong in mature fields across the North Sea, where operators seek to extend asset lifespan and improve economic viability.
- Reservoir Simulation:Courses cover geological modeling, fluid flow dynamics, and predictive analytics for subsurface reservoirs.
- Well Logging:Training provides expertise in interpreting downhole data, including petrophysical analysis and formation evaluation.
- Safety Protocols:Instruction ensures compliance with regulatory mandates for offshore operations and emergency response.
Drilling Techniques handles the majority of throughput; Production Optimization is the fastest mover on share.
Delivery Model:
Delivery models reflect the industry's drive for flexible, efficient, and immersive learning experiences.
- Blended Learning:Combines online modules with in-person practical sessions, offering flexibility and hands-on application. Demand is high among drilling contractors in Guyana, facilitating rapid skill acquisition for new projects.
- Virtual Reality:Provides immersive, risk-free simulations for complex operational scenarios, such as well control and equipment handling. Adoption is accelerating for deepwater training, driven by safety imperatives and cost-effective practice.
- Online Learning:Self-paced digital courses offer broad accessibility for foundational petrotechnical knowledge.
- Classroom Training:Traditional instructor-led sessions provide structured learning environments for core technical disciplines.
- On-site Workshops:Tailored programs delivered at client locations address specific operational challenges and team-based skill development.
Blended Learning is widely adopted for its flexibility, while Virtual Reality is climbing the fastest in specialized, high-consequence training.
Client Type:
Client types delineate distinct strategic needs and procurement patterns for petrotechnical training services.
- Exploration Firms:Companies focused on discovering new hydrocarbon reserves seek training in advanced geoscience, reservoir characterization, and prospect evaluation. Demand is concentrating in new exploration frontiers such as Namibia, where geological understanding is paramount.
- Drilling Contractors:These clients require specialized training in well control, rig operations, and safety compliance for personnel working on rigs. Demand is particularly strong in active drilling regions like the Gulf of Mexico, driven by strict regulatory mandates.
- Oilfield Services:Providers of equipment and technical support require training in product application, maintenance, and field operations.
- Government Agencies:National oil companies and regulatory bodies seek customized programs for workforce development and compliance with national standards.
- Engineering Consultants:These firms invest in training to maintain expertise in specialized areas like subsea engineering and facility design.
Exploration Firms represent a significant market segment, with Drilling Contractors showing the steepest expansion trajectory due to continuous operational demands.
Training Focus:
Training focus areas reflect critical operational imperatives and evolving regulatory landscapes within the upstream sector.
- Environmental Compliance:Programs cover methane emissions management, spill prevention, and regulatory reporting requirements from bodies like the U.S. Environmental Protection Agency. Demand is increasing across offshore production, driven by heightened environmental standards.
- Health & Safety:Courses ensure adherence to stringent safety mandates, including well control, offshore survival, and emergency response protocols established by authorities in the United Kingdom. Demand is constant across all operational segments, ensuring personnel welfare.
- Geoscience Skills:Curriculum encompasses seismic interpretation, geological modeling, and reservoir characterization for subsurface analysis.
- Engineering Practices:Training covers drilling engineering, production engineering, and facilities design for efficient operations.
- Project Management:Programs develop skills in planning, execution, and oversight of complex upstream oil and gas projects.
Health & Safety remains a foundational training focus, while Environmental Compliance is gaining share fastest due to increasing regulatory scrutiny.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA regulations anchor demand for petrotechnical training services in the United States, driving compliance across the Gulf of Mexico. This regulatory emphasis on safety protocols and environmental standards shapes curriculum development for offshore operations. Global upstream activity demands specialized training for complex resource plays.
United States
Demand for well control training is high due to extensive offshore operations and unconventional resource extraction. OSHA regulations mandate continuous safety certification for all personnel working in the Gulf of Mexico. Houston, Texas, serves as a hub for advanced drilling simulation and deepwater operational training, attracting significant investment.
Brazil
Deepwater pre-salt exploration drives significant demand for specialized petrotechnical skills. ANVISA, Brazil's health surveillance agency, alongside national oil regulations, influences safety and environmental training requirements. Rio de Janeiro is a key center for deepwater engineering and reservoir management training.
Norway
Stringent safety directives from Norwegian authorities compel operators to invest in advanced offshore survival and well intervention training. This regulatory environment fosters a high standard for petrotechnical education. Stavanger acts as a primary hub for North Sea oil and gas training, focusing on subsea technologies.
United Arab Emirates
The UAE's national oil companies require extensive training for production optimization and advanced geoscience skills. MOHAP (Ministry of Health and Prevention) regulations, alongside national energy strategies, guide workforce development. Abu Dhabi is a growing center for petrotechnical education, especially in reservoir management and enhanced oil recovery.
India
Growing domestic exploration and production activities drive demand for foundational drilling and reservoir engineering training. The Directorate General of Hydrocarbons (DGH) sets guidelines for operational safety and technical competency. Mumbai and Gujarat are emerging centers for oil and gas training, supporting both offshore and onshore projects.
Global Upstream Petrotechnical Training Services Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another in the petrotechnical training market. This market exhibits a tiered structure, with global service providers offering comprehensive solutions alongside specialized niche players. Major oilfield service companies often integrate training with their proprietary technologies, creating a distinct archetype focused on hands-on operational expertise. Independent training specialists form another archetype, emphasizing deep technical knowledge. Strategic partnerships and technology licensing represent dominant competitive moves, allowing for expanded geographic reach and specialized content delivery to meet evolving industry demands.
Specialists in integrated petrotechnical solutions include PetroSkills, which anchors its position through extensive geoscience and engineering curricula for global operators. Halliburton, a global oilfield services company, exemplifies the model of integrating proprietary software training with hands-on operational courses, particularly for drilling contractors. IFP Training, a French-based organization, occupies a position focused on delivering customized programs for national oil companies, especially for complex reservoir characterization projects. These providers collectively address the diverse needs of the upstream sector, from foundational skills to advanced digital competencies, supporting continuous professional development across various regions.
| Leading Market Players |
|---|
| PetroSkills |
| IHRDC |
| IFP Training |
| PetroEdge |
| Petroknowledge |
| HOT Engineering |
| Petrofac Limited |
| Baker Hughes |
| Halliburton |
| Others |
Cost & Logistics Intelligence
Overcapacity in foundational petrotechnical training modules, particularly traditional classroom instruction, drives supplier behavior towards differentiation and affects pricing posture. This dynamic encourages providers to invest in advanced delivery models and specialized content to command higher value.
Pricing Analysis
Geographic price spreads for petrotechnical training services reflect local labor costs and regulatory compliance requirements. The dominant pricing model is project-based, where clients contract for customized programs tailored to specific operational needs. Price differentiation stems from the level of customization and the certification authority backing the training. Pricing softness reflects a market where in-house program development increasingly reduces reliance on external vendors. Drilling contractors demonstrate the highest price sensitivity, while exploration firms prioritize specialized expertise over cost.
Supply Chain Analysis
Contractual arrangements with specialized petrotechnical content developers and technology licensors form the core of the training supply chain. Geographic supply concentration for content development centers in the United States, Europe, and the Middle East. Raw material dependencies include access to subject matter experts, advanced simulation software licenses, and specialized training equipment. Single-source vulnerability for cutting-edge simulation technology poses a structural risk. Distribution runs through a hybrid model combining direct sales teams and strategic partnerships with local educational institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The petrotechnical training market presents a platform-economics inflection point, driven by the interoperability of digital twin simulations with traditional classroom content.
For Market Incumbents: Build proprietary content moats through continuous curriculum updates that integrate AI and machine learning into core petrotechnical disciplines. This counters the threat of specialized niche players and in-house program development. Investment in advanced certification pathways, particularly for deepwater and unconventional resource plays, serves as a key lever.
For New Entrants and Emerging Players: Build out niche expertise in areas like methane emissions management and carbon capture, utilization, and storage (CCUS) to target the energy transition segment. Underpenetration in emerging African oil and gas markets, such as Namibia, offers a penetrable geographic white space. A value-based pricing model for outcome-driven training programs provides a compelling go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across advanced simulation technologies and digital twin development, indicating a shift towards high-value intellectual property. Long-term viability over a 5-10 year window favors providers with robust digital content libraries and global delivery capabilities. The ideal acquisition target archetype possesses specialized intellectual property in AI-integrated reservoir modeling. Annual review of deepwater project announcements and training budget allocations is advised to detect inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-Integrated Simulation Modules | Enhances predictive modeling capabilities for complex reservoir characterization. |
| Expand Energy Transition Curricula | Addresses client demand for carbon capture and methane emissions management skills. |
| Form Strategic Partnerships with Tech Firms | Accelerates integration of virtual reality and digital twin technologies into training. |
| Target Emerging African Markets | Captures demand from national oil companies for localized workforce development. |
| Invest in Instructor Skill Development | Mitigates the scarcity of qualified instructors with dual technical and digital expertise. |
Research Approach
Initial hypotheses were tested against primary input from drilling engineers, reservoir geologists, E&P procurement leads, and training managers, then refined through iterative analysis. This involved extensive interviews with industry stakeholders, validated by secondary research from regulatory filings, technical journals, and industry association reports. Both bottom-up and top-down triangulation approaches ensured data consistency and market sizing accuracy.
Demand-supply-balance dynamics were central to modeling the market trajectory across the analysis window. Segmentation dimensions modeled included service type, delivery model, client category, and training focus areas, alongside an industry-specific dimension of resource play complexity. Compound annual growth rates were derived from historical data analysis and projected market drivers. Industry-specific forecast inputs included E&P capital expenditure trends and new exploration frontier development schedules.
Stress conditions across crude oil price volatility and regulatory compliance shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding technological adoption rates and global energy policies. Annual review of deepwater project announcements and training budget allocations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
South Korea Oil and Gas Market
Oil & Gas
Asia Pacific Upstream Oil and Gas Services Market
Oil & Gas
United States Oil and Gas Pipeline Maintenance, Repair, Overhaul (MRO) Market
Oil & Gas
Asia-Pacific Oil and Gas Storage Tank Market
Oil & Gas
Oilfield Services Market
Oil & Gas
LNG Storage Tank Market
Oil & Gas
Brazil Oil and Gas Midstream Market
Oil & Gas
Europe Hydraulic Fracturing Fluids Market
Oil & Gas
United States Liner Hanger System Market
Oil & Gas
Expandable Liner Hanger System Market
Oil & Gas
Well Logging Tools Market
Oil & Gas
Frac Stack Market
Oil & Gas
United States Oil and Gas Separation Market
Oil & Gas
Southeast Asia Oil and Gas Downstream Market
Oil & Gas
Asia-Pacific Oilfield Services Market
Oil & Gas
Egypt Natural Gas Market