
 Global LNG Regasification Terminals Market | 2026-2036
Global LNG Regasification Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
Global LNG Regasification Terminals Market Foresight
Utility-led procurement is unwinding shipper-dominated contracting as power generators seek direct terminal access. Shell plc anchors its position through integrated LNG trading and regasification infrastructure spanning multiple continents. Technip Energies N.V. specializes in engineering large-scale onshore terminals with proprietary cryogenic technology. Samsung C&T Corporation dominates EPC execution for Floating Storage Regasification Unit projects across Asia-Pacific markets.
LNG regasification terminals are industrial facilities that convert liquefied natural gas back to gaseous form through heat exchange systems operating at temperatures near minus 162 degrees Celsius, enabling pipeline injection or direct consumption. Open Loop technology leads installed base due to lower capital intensity, though Closed Loop systems are gaining share in environmentally sensitive coastal zones where thermal discharge restrictions apply. Onshore terminals command the largest share of regasification capacity globally, while Floating Storage Regasification Unit deployment is accelerating fastest among segments as coastal nations prioritize speed-to-market over permanent infrastructure.
The EU Green Deal and F-Gas Regulation shape European terminal development by mandating methane leak detection and imposing carbon border considerations on imported LNG. EPA oversight in the United States enforces air quality standards that influence open-loop versus closed-loop technology selection at Gulf Coast facilities. Japan's METI coordinates terminal siting with power grid planners to ensure seasonal demand flexibility. Stakeholders must monitor how divergent national methane regulations affect terminal technology economics and cross-border equipment certification.
Market Dynamics
Floating Storage Regasification Unit deployment timelines of 18-24 months versus 4-6 years for onshore builds are compressing investment cycles and redirecting capital toward modular infrastructure across coastal Asia and Europe.
Growth Catalysts
- EU Green Deal methane mandates:The EU Green Deal and F-Gas Regulation require leak detection systems at all import facilities, creating upgrade demand for existing terminals and technology specification requirements for new builds.
- Power utility procurement:Southeast Asian power generators in Vietnam, Thailand, and the Philippines are contracting directly for terminal capacity to secure fuel supply for combined-cycle gas turbine expansions.
- FSRU technology maturation:Standardized hull designs and modular regasification skids are reducing project execution risk and enabling faster redeployment between seasonal demand centers.
Market Restraints
- Specialized cryogenic equipment concentration:Submerged combustion vaporizers and cryogenic pumps rely on a limited supplier base concentrated in South Korea and Japan, creating single-source vulnerability.
- Coastal siting restrictions:EPA thermal discharge regulations in the United States and EU Water Framework Directive requirements limit open-loop system deployment in environmentally sensitive estuaries.
- Pipeline interconnection delays:Onshore terminal economics depend on high-pressure transmission access, which faces permitting timelines of 3-5 years in Germany, Italy, and Poland.
Strategic Opportunities
- Small-scale LNG distribution:Bunkering and industrial off-grid supply in Greece, Croatia, and Cyprus offers terminal operators revenue diversification beyond grid injection.
- Carbon capture integration:Post-combustion capture retrofits at regasification facilities align with EU Innovation Fund eligibility and create low-carbon LNG product differentiation.
- Hybrid FSRU-power vessel convergence:Combined regasification and power generation units address electricity access gaps in island nations and remote coastal zones.
Industry Challenges
- Cryogenic welding certification scarcity:Qualified 9% nickel steel welders and ASME Section VIII pressure vessel inspectors command premium wages and extended lead times.
- Legacy SCADA integration:Brownfield terminal automation upgrades must interface with 1990s-era distributed control systems without disrupting continuous operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global LNG Regasification Terminals Market |
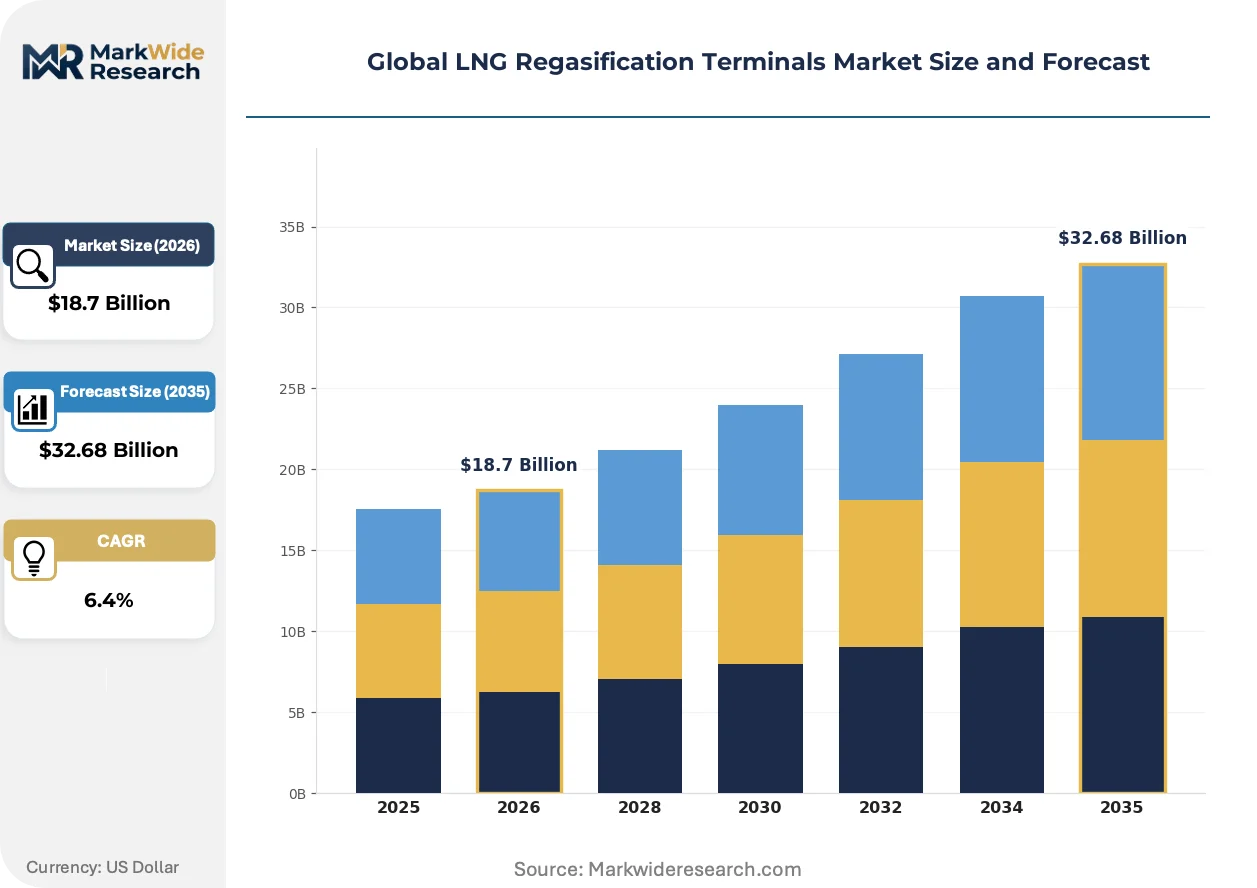
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Terminal Type: Onshore, Floating Storage Regasification Unit, Mini LNG Terminal, Satellite Terminal Technology: Open Loop, Closed Loop, Combined Cycle, Cascade System Application: Power Generation, Marine Fuel Supply, Chemical Processing, City Gas Distribution End User: Energy Utilities, Shipping Companies, Petrochemical Plants, Gas Distributors |
| Companies Covered | Linde plc, Wartsila Oyj ABP, Shell plc, Engie SA, Baker Hughes Company, Technip Energies N.V., Bechtel Corporation, SAIPEM SpA, Samsung C&T Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global LNG Regasification Terminals Market Shifts & Advancements
Terminal technology selection is pivoting from pure cost optimization toward emissions accountability, with methane detection and carbon intensity measurement becoming specification gatekeepers for new capacity.
Closed-loop regasification systems utilizing air-ambient vaporizers and glycol-water heat exchange circuits are displacing open-loop seawater configurations in European and North American markets. German and Polish developers specify these systems to satisfy EU Water Framework Directive thermal discharge limits. The technology premium of 15-20% capital cost is compressing open-loop market share in jurisdictions with strict environmental oversight.
The EU F-Gas Regulation and national methane performance standards in the Netherlands and France now mandate continuous emissions monitoring at all LNG import facilities. Terminal operators must install optical gas imaging and sensor networks covering unloading arms, storage tanks, and flare systems. FSRU projects in the Mediterranean are responding by specifying integrated leak detection packages during newbuild construction rather than retrofitting later.
Utility procurement teams are consolidating terminal access through long-term throughput agreements rather than spot cargo purchases. Japanese power utilities pioneered this model, and Southeast Asian generators are replicating it to secure baseload supply for combined-cycle expansions. Direct terminal contracting displaces traditional shipper-mediated arrangements in Vietnam, Thailand, and Bangladesh procurement workflows.
Global LNG Regasification Terminals Market Segmentation
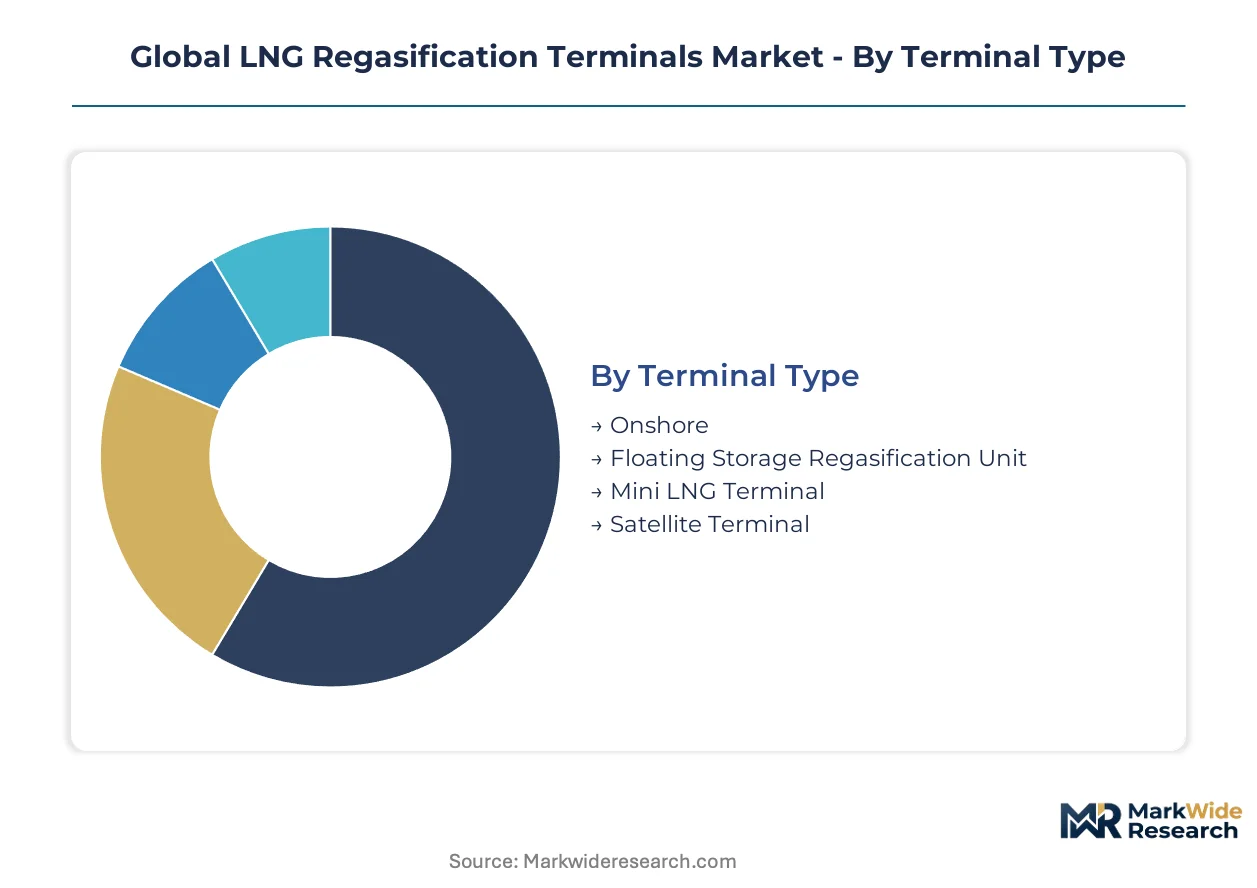
Segmentation reveals how capital allocation and technology choices diverge across deployment contexts. Terminal type determines project timelines and capital intensity, while technology selection increasingly reflects regulatory pressure on thermal discharge and methane emissions.
Terminal Type:
Onshore terminals anchor domestic supply security strategies in Germany, Italy, and Poland, while FSRU deployment concentrates in import-dependent Asian markets seeking speed-to-market.
- Onshore:Permanent concrete structures with storage tanks exceeding 160,000 cubic meters dominate baseload supply in Japan, South Korea, and Taiwan. Japanese utilities at Chita and Higashi Niigata terminals prioritize seasonal demand flexibility through multiple storage tanks and high-pressure sendout capacity.
- Floating Storage Regasification Unit:Converted LNG carriers or purpose-built hulls with onboard regasification skids deploy in 18-24 months versus 4-6 years for onshore builds. Bangladesh, Pakistan, and Turkey have accelerated FSRU adoption to circumvent land acquisition bottlenecks and permanent infrastructure commitments.
- Mini LNG Terminal:Modular shore-based facilities with sub-50,000 ton storage serve industrial clusters and remote power generation in Greece, Croatia, and Cyprus.
- Satellite Terminal:Small-scale receiving facilities connected to parent terminals via LNG trucking or small-diameter pipelines extend distribution networks into secondary demand centers in Spain and Portugal.
Onshore terminals hold the largest share; momentum sits with Floating Storage Regasification Unit deployment.
Technology:
Capital cost differentials and coastal environmental regulations drive technology selection, with premium systems gaining share in EU and North American markets.
- Open Loop:Seawater-based heat exchange systems discharge thermal loads directly into marine environments. Gulf Coast facilities in Texas and Louisiana favor this approach for its lower capital intensity, though EPA thermal discharge restrictions constrain deployment in estuarine zones.
- Closed Loop:Air-ambient vaporizers and glycol-water circuits eliminate marine thermal discharge. German developers at Wilhelmshaven and Brunsbüttel specify closed-loop configurations to satisfy EU Water Framework Directive requirements, accepting a 15-20% capital cost premium.
- Combined Cycle:Integrated power generation captures waste heat from regasification for electricity production, improving overall energy efficiency at large-scale facilities.
- Cascade System:Multi-stage heat exchange utilizing refrigerants or intermediate fluids enables operation in extreme ambient temperature conditions where simple vaporizers underperform.
Open Loop technology commands the largest installed base; Closed Loop systems are expanding most quickly in environmentally regulated jurisdictions.
Application:
Power sector procurement dominates terminal contracting, though marine bunkering and industrial distribution are diversifying revenue streams.
- Power Generation:Combined-cycle gas turbine fuel supply accounts for the majority of terminal throughput in Vietnam, Thailand, and the Philippines, where state utilities contract directly for baseload capacity.
- Marine Fuel Supply:LNG bunkering for container ships and cruise vessels drives small-scale terminal development in Rotterdam, Singapore, and Barcelona, with EU Alternative Fuels Infrastructure Regulation mandating shore-side electricity and LNG availability at major ports.
- Chemical Processing:Feedstock supply for ammonia and methanol production concentrates in Ulsan, South Korea, and Jurong Island, Singapore.
- City Gas Distribution:Residential and commercial heating networks in Japan and South Korea require seasonal demand flexibility through peak-shaving terminal operations.
Power Generation represents the largest application segment; Marine Fuel Supply is climbing the fastest on regulatory mandate.
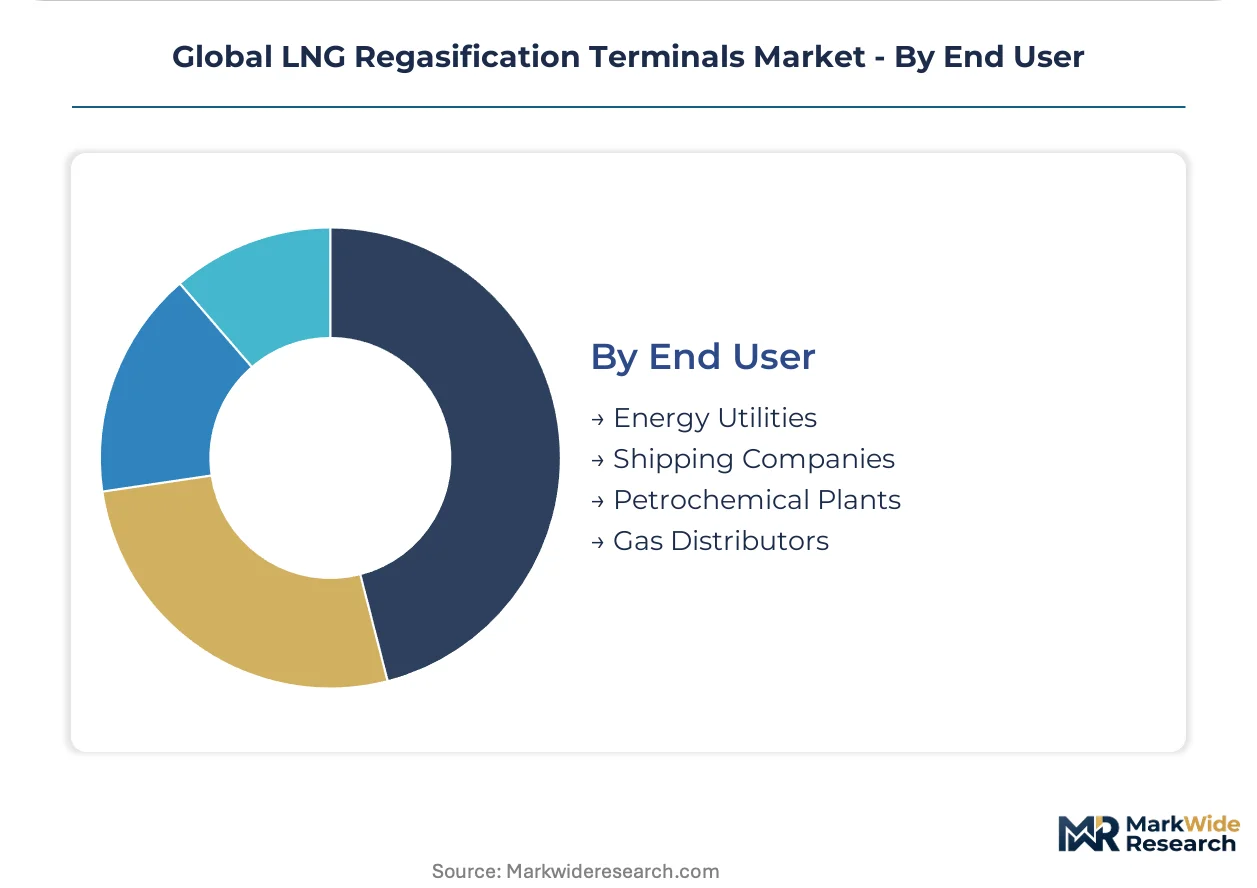
End User:
Procurement patterns are shifting from shipper-mediated arrangements toward direct utility contracting, altering terminal access economics.
- Energy Utilities:State-owned and private power generators in Southeast Asia now contract directly for terminal throughput, displacing traditional oil major intermediaries. Vietnam's EVN and Thailand's EGAT have pioneered long-term regasification agreements.
- Shipping Companies:Container lines and cruise operators are securing dedicated LNG supply contracts at Rotterdam, Singapore, and Barcelona terminals to meet IMO 2020 sulfur regulations and carbon intensity targets.
- Petrochemical Plants:Ammonia and methanol producers in South Korea and Singapore require reliable feedstock access for hydrogen-derived chemical production.
- Gas Distributors:City gas utilities in Japan and South Korea operate seasonal peak-shaving terminals to manage winter heating demand surges.
Energy Utilities hold the largest share; direct contracting momentum is expanding fastest among this segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Wilhelmshaven LNG terminal anchors Germany's pivot from Russian pipeline gas, while Poland's Świnoujście expansion and Italy's Piombino FSRU underpin Mediterranean supply diversification strategies.
Germany
Combined-cycle gas turbine expansions at RWE and Uniper facilities drive terminal demand along the North Sea coast. The EU Green Deal methane mandates require continuous emissions monitoring at all import facilities. Wilhelmshaven and Brunsbüttel terminals specify closed-loop regasification systems to satisfy EU Water Framework Directive thermal discharge limits.
Poland
State utility PGE contracts directly for terminal capacity to fuel 2.5 GW of new gas-fired generation. The country's national energy regulator coordinates terminal siting with transmission system development timelines. Świnoujście terminal expansion and planned Baltic Pipe interconnection concentrate investment in Pomeranian Voivodeship.
Italy
SNAM and Edison procure FSRU capacity to displace declining Algerian pipeline deliveries. The EU F-Gas Regulation shapes technology specifications for leak detection systems at Adriatic terminals. Piombino and Ravenna harbor zones host floating regasification units serving Tuscany and Emilia-Romagna industrial clusters.
Vietnam
EVN and PV Power contract terminal throughput for 14 GW of planned combined-cycle capacity. The Ministry of Industry and Trade coordinates LNG infrastructure with national power development planning. Thị Vải and Cái Mép deepwater ports in Bà Rịa-Vũng Tàu Province anchor southern Vietnam's gas-to-power corridor.
United States
Gulf Coast petrochemical expansions at Cheniere and Venture Global facilities sustain baseload terminal utilization. EPA thermal discharge regulations constrain open-loop system deployment in estuarine zones. Corpus Christi and Lake Charles industrial clusters concentrate cryogenic infrastructure serving Texas and Louisiana chemical processing.
Global LNG Regasification Terminals Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and technology integration dimensions. The vendor base clusters around three tiers: integrated energy majors with trading and infrastructure arms, specialized engineering contractors with proprietary cryogenic technology, and shipyard-affiliated EPC players executing modular FSRU projects. Consolidation pressure favors players with captive LNG supply relationships and multi-continent terminal portfolios. Competitive moves center on FSRU fleet expansion and carbon capture integration partnerships.
Within the integrated energy tier, Shell plc anchors positions through combined trading and regasification infrastructure spanning multiple continents. Technip Energies N.V. and Samsung C&T Corporation exemplify contrasting execution models—respectively specializing in large-scale onshore engineering and floating unit delivery—reflecting how technology maturation has split project risk profiles between permanent and modular infrastructure approaches.
| Leading Market Players |
|---|
| Linde plc |
| Wartsila Oyj ABP |
| Shell plc |
| Engie SA |
| Baker Hughes Company |
| Technip Energies N.V. |
| Bechtel Corporation |
| SAIPEM SpA |
| Samsung C&T Corporation |
| Others |
Supply & Pricing Matrix
Eighteen-to-twenty-four-month FSRU deployment timelines versus four-to-six-year onshore builds concentrate pricing power with hull fabricators in South Korea and cryogenic skid suppliers in Japan, compressing margins for EPC contractors while rewarding integrated players with captive equipment sourcing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs terminal contracting, with closed-loop systems commanding 15-20% capital premiums over open-loop configurations in EU markets. Price differentiation rests on certification grade—ASME Section VIII compliance versus lower-tier pressure vessel standards—and geographic delivery cost to remote coastal zones. Cost compression in standard-tier FSRU charters is intensifying because shipyard slot scarcity in Ulsan and Geoje has compressed availability for converted LNG carriers. State utilities in Southeast Asia exhibit highest price sensitivity due to foreign currency exposure, while Japanese power generators show lowest sensitivity given long-term offtake security mandates.
Supply Chain Analysis
Inventory-to-delivery cycles for submerged combustion vaporizers now stretch fourteen to eighteen months, exposing project timelines to single-source bottlenecks in Osaka and Busan manufacturing clusters. Cryogenic equipment fabrication concentrates in South Korea, Japan, and Germany, with 9% nickel steel plate sourcing anchored in Chinese and Belgian mills. Raw material dependencies span specialized aluminum alloys for heat exchangers, high-nickel stainless steels for cryogenic piping, and precision-machined compressor components. Single-source vulnerability around submerged combustion vaporizer engineering creates supply chain risk. Distribution runs through EPC-led turnkey contracting for onshore terminals and shipyard-affiliated leasing structures for FSRU deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment—manifest in site-specific permits, coastal zone approvals, and grid interconnection agreements—protects incumbent positions against new capacity entrants.
For Market Incumbents: Compound terminal portfolio value through carbon capture integration partnerships that qualify for EU Innovation Fund eligibility, and secure backward integration into cryogenic equipment supply through equity stakes in Korean or Japanese fabricators. Emerging FSRU operators from shipping conversion backgrounds threaten lease rate compression in Mediterranean markets. Capacity addition in German and Polish coastal zones offers geographic diversification against Asian demand cyclicality. For New Entrants and Emerging Players: Lead with small-scale LNG distribution infrastructure in Greece, Croatia, and Cyprus, where industrial cluster demand and marine bunkering growth outpace parent terminal expansion timelines. Hybrid FSRU-power vessel convergence for island nations represents the most penetrable application segment. A build-operate-transfer concession model with national utilities minimizes upfront capital exposure while securing long-term revenue visibility. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified engineering conglomerates seeking to monetize non-core LNG infrastructure assets amid energy transition portfolio rebalancing. Terminal operators with integrated trading arms and multi-continent regasification positions demonstrate superior long-term viability through demand arbitrage capture. Watch FSRU redeployment velocity between European winter peaks and Asian summer demand as the signal indicating utilization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit Integration | Post-combustion capture at Wilhelmshaven and Brunsbüttel terminals qualifies for EU Innovation Fund subsidies. |
| FSRU Fleet Standardization | Modular regasification skids from Samsung Heavy Industries reduce redeployment costs between seasonal demand centers. |
| Utility Direct Contracting | EVN and EGAT long-term throughput agreements displace oil-major intermediaries in Southeast Asian procurement. |
| Closed-Loop Technology Specification | Air-ambient vaporizer adoption at German terminals satisfies EU Water Framework Directive thermal discharge mandates. |
| Methane Detection System Deployment | Optical gas imaging networks at unloading arms and flare systems comply with EU F-Gas Regulation monitoring requirements. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with EPC project directors, utility fuel procurement officers, shipyard commercial managers, and cryogenic equipment engineering leads. Secondary validation drew from FERC facility filings, IEA LNG trade databases, EU TEN-E project registries, and shipyard order books. Bottom-up capacity installation tracking and top-down trade flow modeling were triangulated to reconcile project-level data with regional demand aggregates.
Across the analysis window, volume and value outputs reflect segmented modeling across terminal type, technology configuration, application sector, and end-user procurement pattern. CAGRs were derived from capacity-weighted project pipelines and historical utilization trends. Forecast inputs incorporated seasonal demand flexibility requirements in Japan and South Korea, and EU methane performance standard compliance timelines.
The analysis sits within stated boundaries; outcomes outside sustained European LNG demand displacement of Russian pipeline flows, or accelerated Southeast Asian gas-to-power project commissioning, would require recalibration. Forecasts reflect documented assumptions around FSRU redeployment economics and onshore terminal permitting timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Infrastructure Market
Oil & Gas
Global Upstream Petrotechnical Training Services Market
Oil & Gas
Unconventional Gas Market
Oil & Gas
Planned LNG Market
Oil & Gas
Southeast Asia Oil and Gas Downstream Market
Oil & Gas
Smart Well Market
Oil & Gas
Mexico Oil and Gas Market
Oil & Gas
Angola Oil and Gas Upstream Market
Oil & Gas
Iran Oil and Gas Exploration and Production Market
Oil & Gas
Drilling Mud Desander and Desilter Market
Oil & Gas
Well Completion Market
Oil & Gas
Well Logging Tools Market
Oil & Gas
Central Asia Oil and Gas Market
Oil & Gas
Southeast Asia Oil and Gas EPC Market
Oil & Gas
Europe Natural Gas Market
Oil & Gas
Europe Oilfield Equipment Rental Services Market