
 North America Wireline Logging Services Market | 2026-2036
North America Wireline Logging Services Market Size, Share, and Industry Trends Forecast 2026-2036
North America Wireline Logging Services Market Analytics
Equipment procurement channels between wireline service providers and independent exploration companies is reconfiguring around integrated logging packages that bundle conveyance with real-time data delivery. Schlumberger Limited leverages its technology leadership in resistivity and nuclear logging tools to sustain premium positioning across the Permian and Bakken. Baker Hughes Company anchors its North American wireline presence through manufacturing scale and backward integration into downhole sensor production. Halliburton Company differentiates via geographic dominance in the Gulf of Mexico offshore market where complex well architectures demand specialized open hole logging expertise.
Wireline logging services encompass the deployment of instrumented cables into boreholes to measure formation properties including resistivity, acoustic velocity, gamma ray response, and neutron porosity using tools rated for pressures exceeding 20,000 psi and temperatures above 175°C. These measurements guide completion design, reserve estimation, and production optimization across oil, gas, and geothermal assets. Open hole logging retains the largest revenue share as operators require pre-completion formation evaluation in unconventional horizontal wells, while cased hole logging is expanding fastest as aging well inventories across North America drive demand for corrosion monitoring and cement evaluation services. Electromagnetic and resistivity technologies dominate the technology mix due to their critical role in identifying hydrocarbon-bearing zones, with nuclear logging tools commanding higher margins despite operational complexity from radioactive source handling regulations.
The US EPA enforces methane emissions standards under the Clean Air Act that mandate leak detection and repair programs, directly stimulating demand for production logging and well integrity verification services. OSHA regulates worker exposure to ionizing radiation from nuclear logging sources, shaping tool design and field operational protocols across US onshore and offshore operations. Canada's PMRA and provincial regulators enforce parallel environmental and safety standards that service providers must navigate for cross-border operational compliance. Stakeholders must monitor evolving state-level methane rules in Texas, New Mexico, and Colorado alongside federal standards to anticipate shifts in logging service procurement priorities.
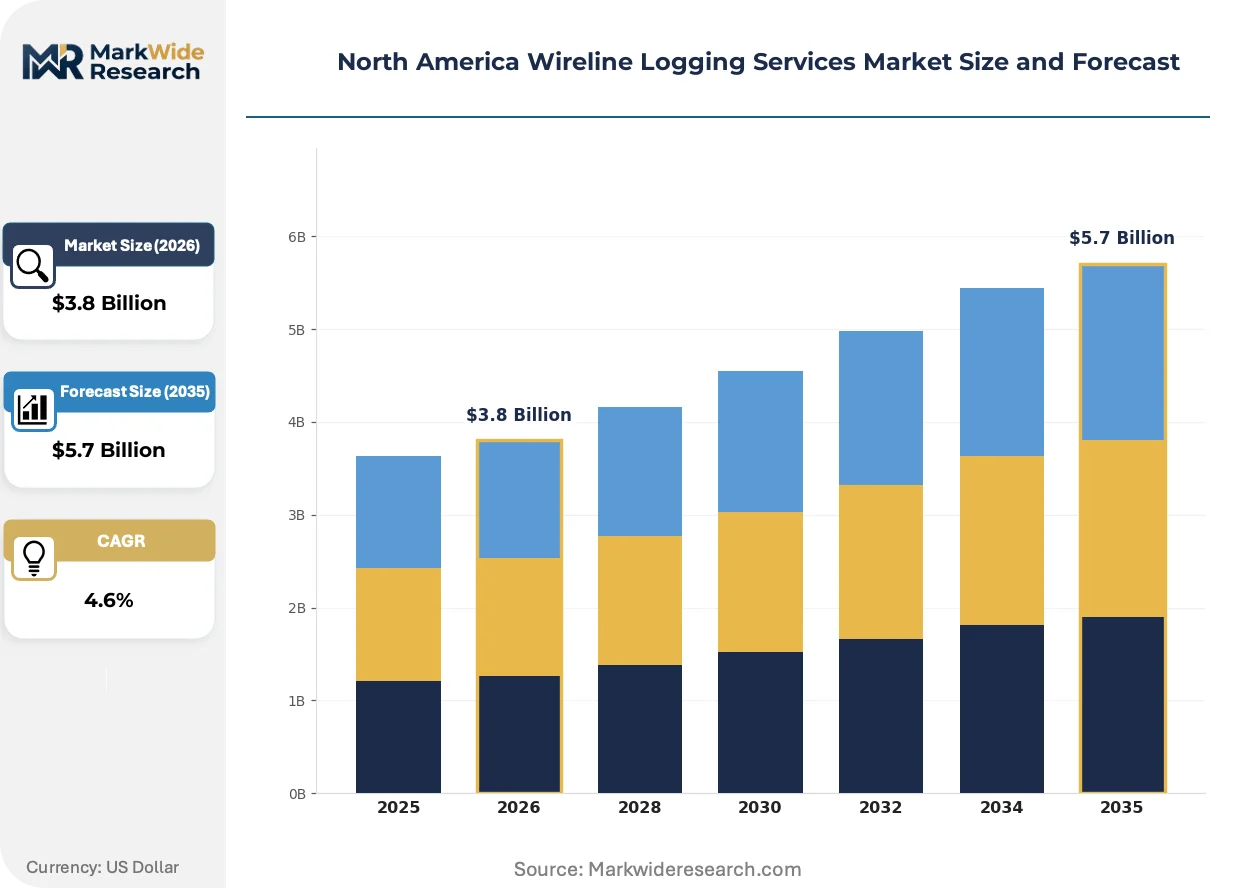
Market Dynamics
EPA methane regulations under the Clean Air Act are compressing well integrity verification timelines, forcing operators to accelerate cased hole logging procurement cycles across the Permian and Bakken formations.
Growth Catalysts
- Delaware Basin Deepening:Operators targeting Wolfcamp and Bone Spring formations below 12,000 feet require high-temperature logging tools rated for 200°C+ environments.
- EPA Methane Rule:Mandatory leak detection and repair programs stimulate demand for production logging and cement evaluation services across US onshore assets.
- Electromagnetic Tool Advancement:Resistivity arrays with azimuthal resolution now guide geosteering decisions in laterals exceeding 15,000 feet.
Market Restraints
- Radioactive Source Handling:OSHA and NRC licensing requirements for neutron porosity tools impose operational friction and extended crew certification timelines.
- Canadian Regulatory Fragmentation:PMRA provincial variations create cross-border compliance complexity for service providers operating in Alberta and British Columbia.
- Tool Manufacturing Concentration:Downhole sensor production concentrates among three integrated suppliers, creating supply vulnerability for independent wireline companies.
Strategic Opportunities
- Geothermal Expansion:Temperature-rated logging suites developed for oil and gas applications transfer to enhanced geothermal systems in Nevada and Utah.
- Real-Time Data Integration:Convergence of wireline telemetry with cloud-based analytics platforms enables remote formation evaluation decisions.
- New Mexico Regulatory Tailwind:State-level methane rules exceed federal baselines, accelerating well integrity verification demand in the Delaware Basin.
Industry Challenges
- Petrophysicist Shortage:Interpretation of complex resistivity and nuclear logs requires specialized expertise that operators struggle to retain.
- Legacy System Integration:Digital logging platforms must interface with decades-old well file formats and proprietary data architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Wireline Logging Services Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Open Hole Logging, Cased Hole Logging, Production Logging, Well Completion Technology: Electromagnetic, Acoustic, Nuclear, Resistivity Application: Oil Extraction, Gas Extraction, Mineral Exploration, Well Integrity End User: Oil & Gas Companies, Mining Companies, Environmental Agencies, Research Institutions |
| Companies Covered | Weatherford International PLC, Superior Energy Services Inc, Schlumberger Limited, Pioneer Energy Services Corp, Nabors Industries Ltd, Baker Hughes Company, Expro Group, NexTier Oilfield Solution Inc, Halliburton Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Wireline Logging Services Market Evolving Landscape
Wireline service delivery is compressing around integrated packages that bundle conveyance, real-time telemetry, and cloud-based interpretation. This convergence is reshaping how operators procure formation evaluation.
Logging-while-tripping technology is migrating from offshore Gulf of Mexico applications to Permian Basin horizontal wells. Unconventional operators now demand continuous formation evaluation without pulling drillpipe, compressing rig time and reducing non-productive time. This shift is displacing conventional open hole logging in laterals where wellbore stability risks limit wireline conveyance.
EPA enforcement of methane emissions standards under the Clean Air Act intensifies well integrity verification requirements. Operators must document cement bond quality and casing corrosion status across aging well inventories. Cased hole logging services capture expanded scope as leak detection and repair programs mandate production logging across Texas and New Mexico.
Service bundling now dominates procurement decisions as exploration companies consolidate vendor relationships. Integrated logging packages that combine conveyance with real-time data delivery displace discrete tool rentals. This consolidation concentrates most visible in the Permian Basin where supermajors and large independents negotiate multi-well master service agreements.
North America Wireline Logging Services Market Segmentation
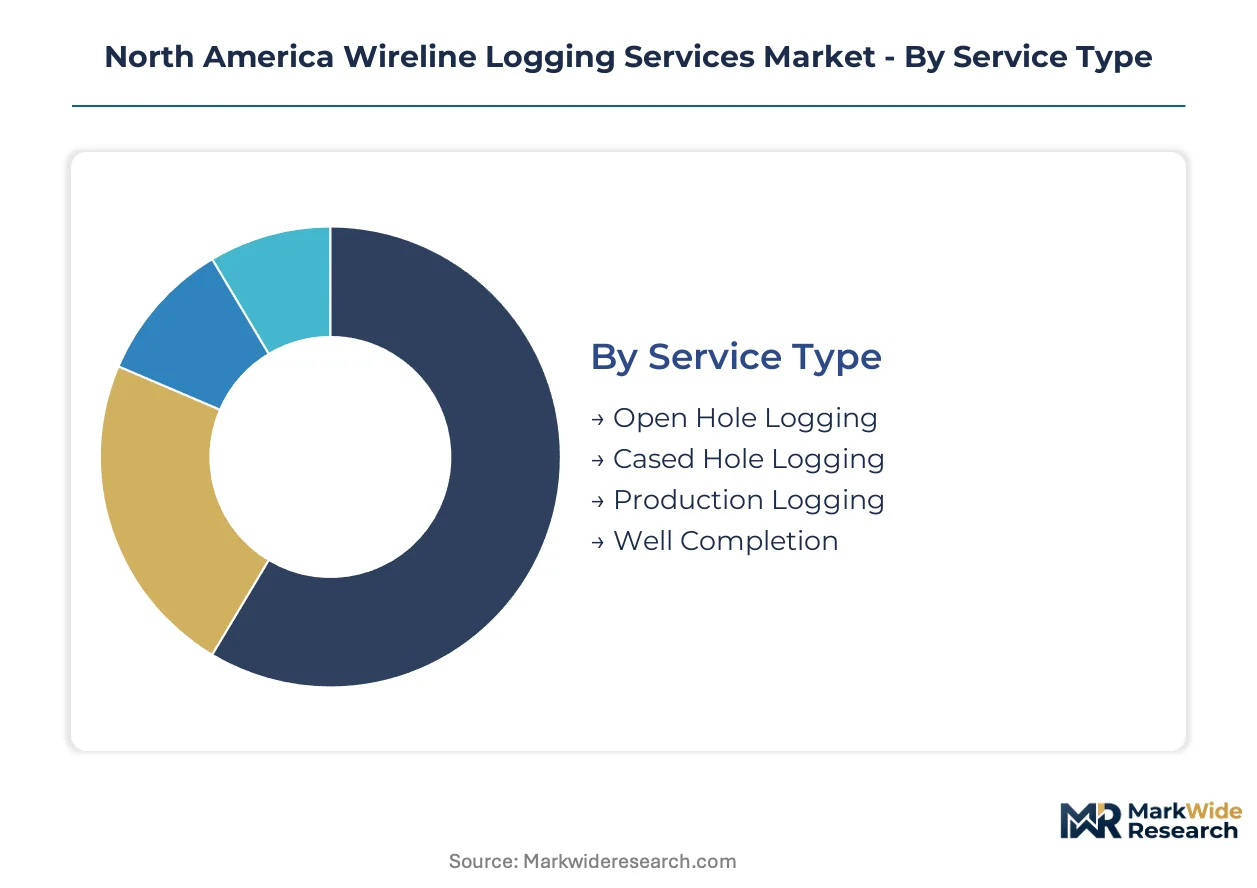
Wireline logging services fragment across technical specifications, operational phases, and regulatory requirements that shape procurement decisions. Each segment carries distinct margin profiles and technology barriers that influence vendor positioning across North American basins.
Service Type:
Service selection tracks the well lifecycle from initial drilling through abandonment, with operators calibrating logging intensity against formation complexity and regulatory obligations.
- Open Hole Logging:Deployed prior to casing installation to capture resistivity, porosity, and lithology data across virgin formations. Permian Basin operators require these services for Wolfcamp and Bone Spring pre-completion evaluation in horizontal wells exceeding two-mile laterals.
- Cased Hole Logging:Performed through installed casing to assess cement bond integrity, casing corrosion, and perforation effectiveness. EPA methane regulations under the Clean Air Act are accelerating procurement cycles for cement evaluation and leak detection across aging well inventories in Texas and New Mexico.
- Production Logging:Monitors inflow profiles and identifies water or gas breakthrough zones in producing wells.
- Well Completion:Supports perforation placement, fracture staging, and post-stimulation evaluation in unconventional developments.
Established volume favors Open Hole Logging; emerging adoption favors Cased Hole Logging.
Technology:
Technology mix reflects the trade-off between measurement precision and operational constraints imposed by downhole conditions and regulatory oversight.
- Electromagnetic:Measures formation conductivity to distinguish hydrocarbon-bearing zones from water-saturated intervals. Azimuthal resistivity arrays now guide geosteering decisions in Delaware Basin laterals where target windows narrow below 10 feet.
- Resistivity:Provides depth-resolved formation evaluation through multiple spacing configurations. Deep-reading laterolog tools penetrate beyond invaded zones in Gulf of Mexico high-pressure formations where mud filtrate obscures near-borehole measurements.
- Acoustic:Captures compressional and shear wave velocities for mechanical property estimation and cement bond verification.
- Nuclear:Employs radioactive sources for neutron porosity and density measurements, commanding premium pricing despite OSHA and NRC licensing friction.
Electromagnetic and Resistivity tools dominate current revenue; Nuclear logging faces regulatory headwinds that constrain crew availability.
Application:
Application demand concentrates in hydrocarbon extraction while regulatory enforcement expands integrity verification scope.
- Oil Extraction:Formation evaluation guides completion design in unconventional oil plays where landing zone selection determines EUR. Midland Basin operators deploy full logging suites across stacked pay intervals in the Spraberry and Wolfcamp formations.
- Gas Extraction:Porosity and saturation measurements target dry gas and liquids-rich windows in Appalachian and Haynesville shales. Cased hole services monitor casing corrosion in high-H2S environments where sulfide stress cracking threatens wellbore barriers.
- Mineral Exploration:Supports lithium brine and critical mineral assessment in Nevada and Utah geothermal systems.
- Well Integrity:Cement bond logs and corrosion evaluation satisfy EPA leak detection mandates across Texas, New Mexico, and Colorado.
Oil Extraction retains the largest service volume; Well Integrity is climbing the fastest on regulatory enforcement.
End User:
End user structure reflects asset ownership patterns and the outsourcing of technical evaluation to specialized service providers.
- Oil & Gas Companies:Integrated majors and large independents negotiate multi-well master service agreements that bundle conveyance with real-time data delivery. Supermajors operating in the Permian Basin specify high-temperature tool ratings for deep Delaware Basin targets below 12,000 feet.
- Mining Companies:Require formation evaluation for potash, uranium, and critical mineral deposits where borehole geophysics reduces core recovery costs.
- Environmental Agencies:Procure logging services for groundwater monitoring, carbon sequestration site characterization, and abandoned well assessment.
- Research Institutions:Deploy advanced logging suites for geothermal reservoir characterization and academic formation evaluation studies.
Oil & Gas Companies command procurement scale; Environmental Agencies represent the fastest-expanding customer category on methane rule enforcement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Texas and New Mexico exceeds Canadian basins by substantial margins, reflecting deeper formation complexity and stricter state-level methane enforcement. Delaware Basin operators command premium rates for high-temperature tool deployments below 12,000 feet.
United States
Permian Basin supermajors drive demand for integrated logging packages bundling conveyance with real-time telemetry. EPA methane regulations under the Clean Air Act compress procurement cycles for cement evaluation services. Midland and Delaware sub-basins concentrate Wolfcamp and Bone Spring drilling where azimuthal resistivity tools guide geosteering in 15,000-foot laterals.
Canada
Alberta oil sands and British Columbia shale plays sustain steady cased hole logging demand for well integrity verification. Health Canada and PMRA enforce parallel radiation handling standards that extend crew certification timelines. Calgary-based service hubs navigate provincial regulatory fragmentation between Alberta and British Columbia compliance requirements.
Mexico
Deepwater Gulf of Mexico developments require specialized open hole logging for high-pressure carbonate formations. Comisión Nacional de Hidrocarburos oversees upstream contracting terms that influence service procurement structures. Ciudad del Carmen and Tampico clusters host offshore logistics bases supporting Pemex and international operator campaigns.
North America Wireline Logging Services Market Competitive Landscape
Technology-integrated majors and independent conveyance specialists split the market along capability depth and geographic coverage vectors. Three players control proprietary high-temperature tool manufacturing, creating tiered access to premium-rated services. Competitive moves concentrate on backward integration into downhole sensor production and multi-well master service agreement consolidation across Permian operators.
Among North American integrated service providers, Schlumberger Limited, Baker Hughes Company, and Halliburton Company occupy positions defined by manufacturing scale and basin-specific expertise. Schlumberger exemplifies technology leadership in resistivity and nuclear logging applications. Baker Hughes anchors its presence through captive supply of downhole sensors. Halliburton represents specialized open hole capabilities in complex offshore architectures.
| Leading Market Players |
|---|
| Weatherford International PLC |
| Superior Energy Services Inc |
| Schlumberger Limited |
| Pioneer Energy Services Corp |
| Nabors Industries Ltd |
| Baker Hughes Company |
| Expro Group |
| NexTier Oilfield Solution Inc |
| Halliburton Company |
| Others |
Value Network & Pricing Analysis
Radioactive source licensing friction under OSHA and NRC regulations determines both the premium spread for nuclear logging crews and the geographic clustering of certified service hubs. This regulatory chokepoint compresses supply availability for neutron porosity tools while elevating pricing power for providers holding captive certification capacity.
Pricing Analysis
Configured-to-order pricing for high-temperature tool suites rated above 200°C commands substantial premiums over standard resistivity arrays in Delaware Basin deployments. Project-based contracting dominates, with price differentiation driven by tool certification tier and volume scale across multi-well master service agreements. Cost compression in standard electromagnetic logging is intensifying because independent conveyance specialists lack backward integration into sensor manufacturing. Small independents exhibit highest price sensitivity, while Permian supermajors prioritize performance guarantees over unit economics.
Supply Chain Analysis
Contract manufacturing of downhole pressure sensors and gamma ray detectors concentrates in the United States, Germany, and Japan. Raw material dependencies include high-grade tungsten for radiation shielding, specialized ceramics for high-temperature electronics, and synthetic monocrystalline sapphire for optical sensors. Single-source vulnerability runs through domestic suppliers of He-3 neutron detection tubes. Distribution runs through basin-anchored service hubs in Midland, Odessa, and Hobbs that maintain tool inventory within four-hour mobilization radius of active rigs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wireline logging procurement is consolidating around integrated data platforms that bundle conveyance with cloud-based interpretation, creating platform-economics dynamics where interoperability between operator SCADA systems and vendor telemetry architectures determines competitive survival.
For Market Incumbents: Entrench technology leadership through captive manufacturing of high-temperature sensor arrays and exclusive certification capacity for nuclear logging sources. Defensive consolidation should prioritize multi-well master service agreements with Permian operators that lock in conveyance-plus-telemetry bundles, while countering the threat from logging-while-tripping technologies displacing conventional open hole services in extended-reach laterals. For New Entrants and Emerging Players: Pursue geothermal logging applications in Nevada and Utah where temperature-rated tool suites developed for oil and gas transfer to enhanced geothermal systems with minimal adaptation. The most penetrable white space sits in environmental agency contracts for abandoned well assessment and carbon sequestration site characterization, with go-to-market execution through direct engagement with state environmental regulators rather than oilfield procurement channels. For Investors and Strategic Acquirers: The market sits at a regulatory-intensification phase that favors vertically integrated service providers holding proprietary tool manufacturing and radiation handling licenses. Long-term viability over the next decade rests on backward integration depth rather than geographic coverage alone. Watch EPA enforcement cadence on methane leak detection mandates as the primary inflection signal for cased hole logging demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| High-Temperature Tool Certification | Delaware Basin operators below 12,000 feet require 200°C+ ratings that exclude uncertified competitors. |
| Real-Time Telemetry Integration | Cloud-based formation evaluation platforms enable remote geosteering decisions that reduce rig time. |
| Radiation Handling License Acquisition | NRC and OSHA certifications for neutron porosity tools create defensible supply constraints. |
| Geothermal Application Expansion | Temperature-rated logging suites transfer to Nevada and Utah enhanced geothermal developments. |
| Master Service Agreement Consolidation | Multi-well bundles with Permian supermajors lock in conveyance-plus-data-delivery revenue streams. |
Research Methodology
Initial hypotheses were tested against primary input from wireline operations managers, petrophysicist team leads, E&P procurement executives, and regulatory compliance officers at service providers, then refined through secondary validation against EPA enforcement records, state oil and gas commission permitting databases, SEC 10-K filings from integrated service companies, and rig count data from Baker Hughes. Bottom-up well-level logging intensity estimates were triangulated against top-down service revenue allocations across North American basins.
Demand-supply balance framing anchored the forecast framework, with segmentation dimensions spanning service type, technology category, application, and end-user archetype across the projection horizon. CAGRs were derived from basin-specific drilling program trajectories, regulatory compliance cost imposition models, and technology substitution curves for logging-while-tripping versus conventional wireline conveyance. Forecast inputs incorporated EPA methane rule implementation timelines and high-temperature tool adoption rates in deep Delaware Basin targets.
Macroeconomic conditions sit as an overlay; deviation in WTI crude price bands, federal lease issuance velocity, or geothermal investment tax credit extensions would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement continuity and technology substitution elasticity. Quarterly review of EPA enforcement actions, state methane rule adoptions, and rig mobilization patterns toward deep Wolfcamp targets is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Sucker Rod Market
Oil & Gas
Oil Tank Rotating Stacker Market
Oil & Gas
3D Printing in Oil and Gas Market
Oil & Gas
Thailand Oil and Gas Market
Oil & Gas
GCC and North Africa Coiled Tubing Market
Oil & Gas
Subsea Flowlines Market
Oil & Gas
Middle East and Africa Coiled Tubing Market
Oil & Gas
Delayed Coker Unit Market
Oil & Gas
Copper Mining Market
Oil & Gas
Europe Oilfield Chemicals Market
Oil & Gas
Global Upstream Petrotechnical Training Services Market
Oil & Gas
United States Liner Hanger System Market
Oil & Gas
Nigeria Oil and Gas Midstream Market
Oil & Gas
Canada LNG Bunkering Market
Oil & Gas
Europe Oilfield Equipment Rental Services Market
Oil & Gas
Europe Well Intervention Market