
 Middle-East Oil and Gas Line Pipe Market | 2026-2036
Middle-East Oil and Gas Line Pipe Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East Oil and Gas Line Pipe Market Foresight
Procurement channels for long-lead line pipe are reconfiguring as national oil companies consolidate vendor lists and shift toward framework agreements. Tenaris SA leverages its Dammam threading facility to sustain proximity supply to Saudi Aramco's onshore programs. Arabian Pipes Company anchors domestic fabrication capacity through its Riyadh and Jubail plants, while Jindal SAW Ltd competes on spiral-weld cost structures for water and gas transmission lines.
Middle-East oil and gas line pipe denotes cylindrical steel conduit manufactured to API 5L, ISO 3183, or equivalent sour-service specifications, with wall thicknesses engineered to withstand internal pressures from sweet and corrosive hydrocarbon streams. Seamless pipe commands premium placement in high-pressure offshore risers and downhole applications where defect tolerance approaches zero. Welded pipe, particularly longitudinal submerged arc weld variants, occupies volume leadership in onshore trunk lines where diameter exceeds twenty inches and cost efficiency governs selection.
API standards, Saudi Aramco engineering procedures, and ADNOC technical specifications collectively define material grades, testing protocols, and supplier qualification thresholds across the Gulf. The Saudi Standards, Metrology and Quality Organization enforces local content mandates that redirect procurement toward in-country value-add operations. Stakeholders must monitor qualification timeline compression and sour-service alloy premium volatility as project cycles accelerate and reservoir chemistry grows more aggressive.
Market Dynamics
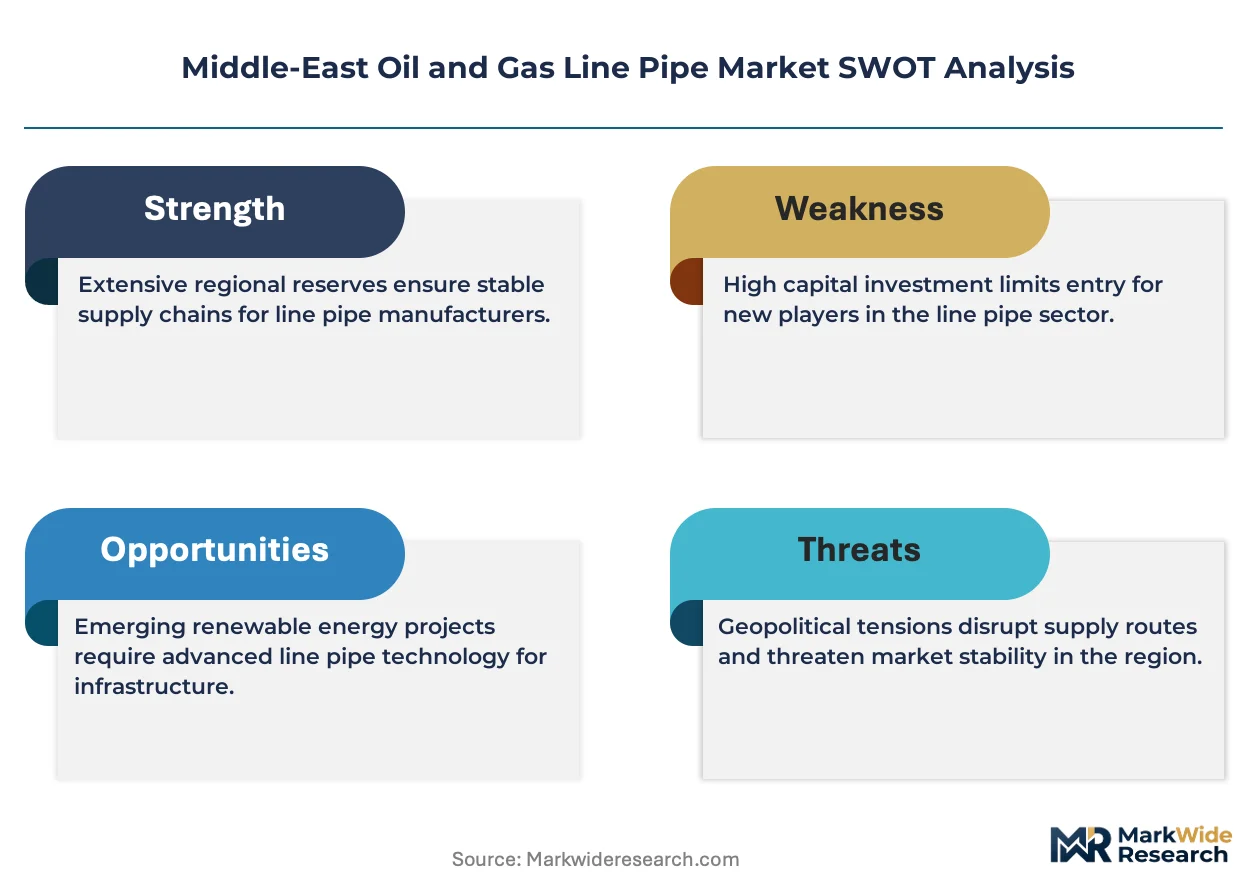
Saudi Aramco's vendor consolidation into framework agreements is compressing qualification timelines and privileging in-country threading and coating capabilities over pure import supply.
Growth Catalysts
- Gas trunk line expansion:Qatari and Emirati LNG export capacity additions require high-pressure transmission infrastructure connecting liquefaction trains to marine terminals.
- Saudi Standards, Metrology and Quality Organization local content mandates:Procurement rules redirect value-add operations toward domestic threading, inspection, and coating facilities.
- API 5L specification upgrades:Tighter sour-service material requirements are accelerating alloy premium demand for corrosive reservoir chemistry.
Market Restraints
- Alloy input cost volatility:Nickel and molybdenum price swings compress margin predictability for sour-service pipe grades.
- Vendor base concentration:Saudi Aramco's approved manufacturer list has narrowed to fewer than twelve qualified seamless suppliers.
- Seamless capacity scarcity:Limited Gulf-region hot-rolling mill availability constrains rapid order fulfillment for large-diameter high-pressure applications.
Strategic Opportunities
- Iraq underinvestment recovery:Basra field rehabilitation and water injection programs will require extensive gathering line replacement.
- Digital twin integration:Pipeline integrity monitoring systems are converging with smart pigging data to enable predictive maintenance contracts.
- UAE hydrogen backbone:ADNOC's blue ammonia and hydrogen export plans specify new dedicated hydrogen-ready line pipe specifications.
Industry Challenges
- Welding technician scarcity:Qualified sour-service welders and NDT inspectors face acute shortage across Eastern Province fabrication yards.
- Qualification timeline compression:Aramco's accelerated project cycles compress factory acceptance testing and third-party inspection windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East Oil and Gas Line Pipe Market |
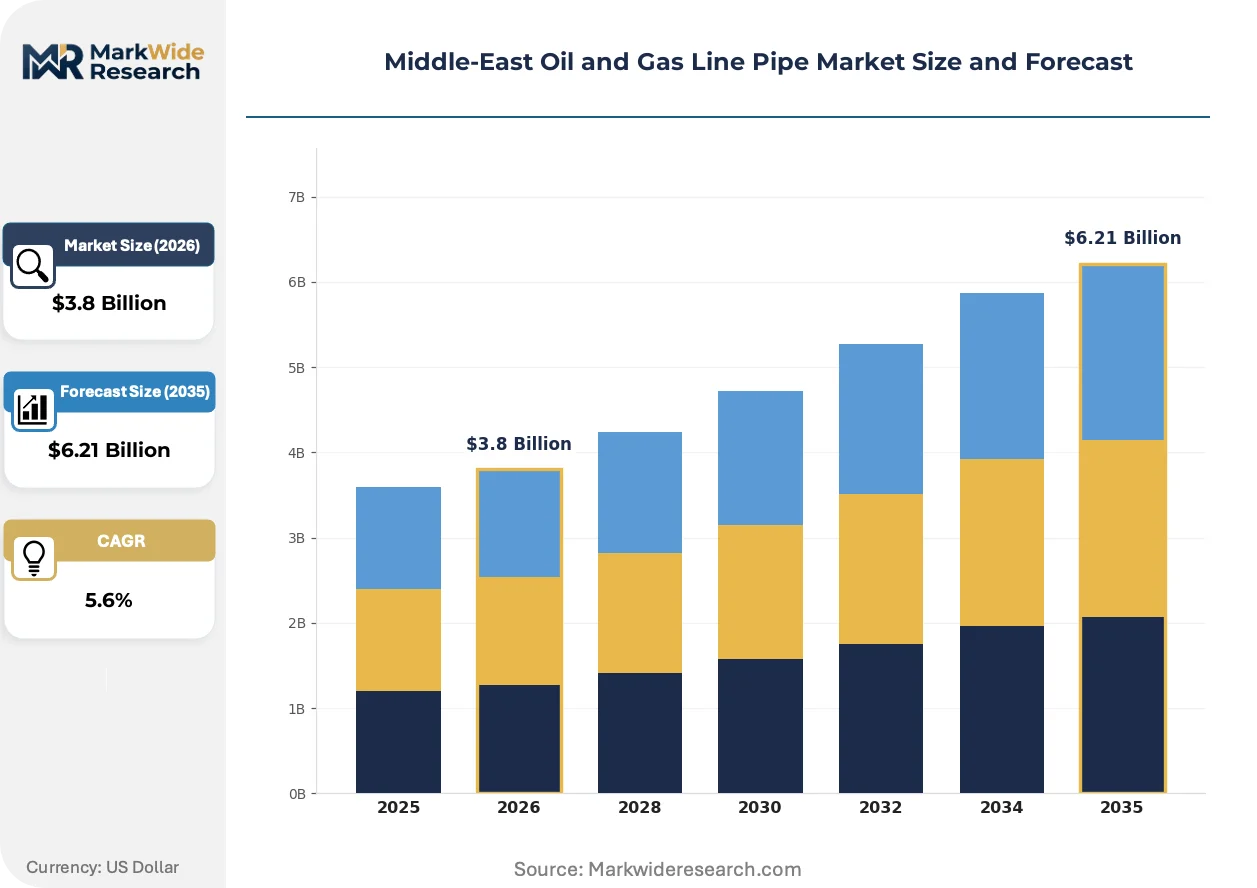
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seamless Pipe, Welded Pipe, Spiral Pipe, Coiled Pipe End User: Oil Producers, Gas Distributors, Pipeline Contractors, Energy Utilities Material: Carbon Steel, Alloy Steel, Stainless Steel, Polymer Application: Onshore Pipelines, Offshore Pipelines, Transportation, Distribution |
| Companies Covered | Tenaris SA, EEW Group, Arabian Pipes Company, Sumitomo Corporation, Abu Dhabi Metal Pipes & Profiles, Rezayat Group, Jindal SAW Ltd, ArcelorMittal SA, Vallourec SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East Oil and Gas Line Pipe Market Shifts & Advancements
Digital thread technologies and material science advances are reconfiguring how line pipe is specified, monitored, and maintained across Gulf upstream and midstream programs.
Composite reinforcement layers bonded to steel substrates are virtualizing traditional corrosion protection approaches. Offshore operators in Qatar's North Field expansion are specifying thermoplastic composite pipe for riser applications where weight reduction governs installation economics. This hybrid architecture is virtualizing cathodic protection system requirements and compressing lifecycle maintenance schedules.
Saudi Standards, Metrology and Quality Organization enforcement of in-country value-add thresholds is tightening import substitution rules. Foreign manufacturers must now thread, inspect, and coat within Kingdom borders to qualify for Aramco framework awards. Seamless pipe importers are responding by licensing technology to Dammam-based joint ventures rather than shipping finished goods.
Buyer consolidation into multi-year framework agreements is compressing spot market liquidity. National oil companies now bundle line pipe with valves, fittings, and inspection services into single-source procurement vehicles. This bundling is most visible in Saudi Arabia's Eastern Province, where master service agreements cover three-year drilling and trunk line programs.
Middle-East Oil and Gas Line Pipe Market Segmentation
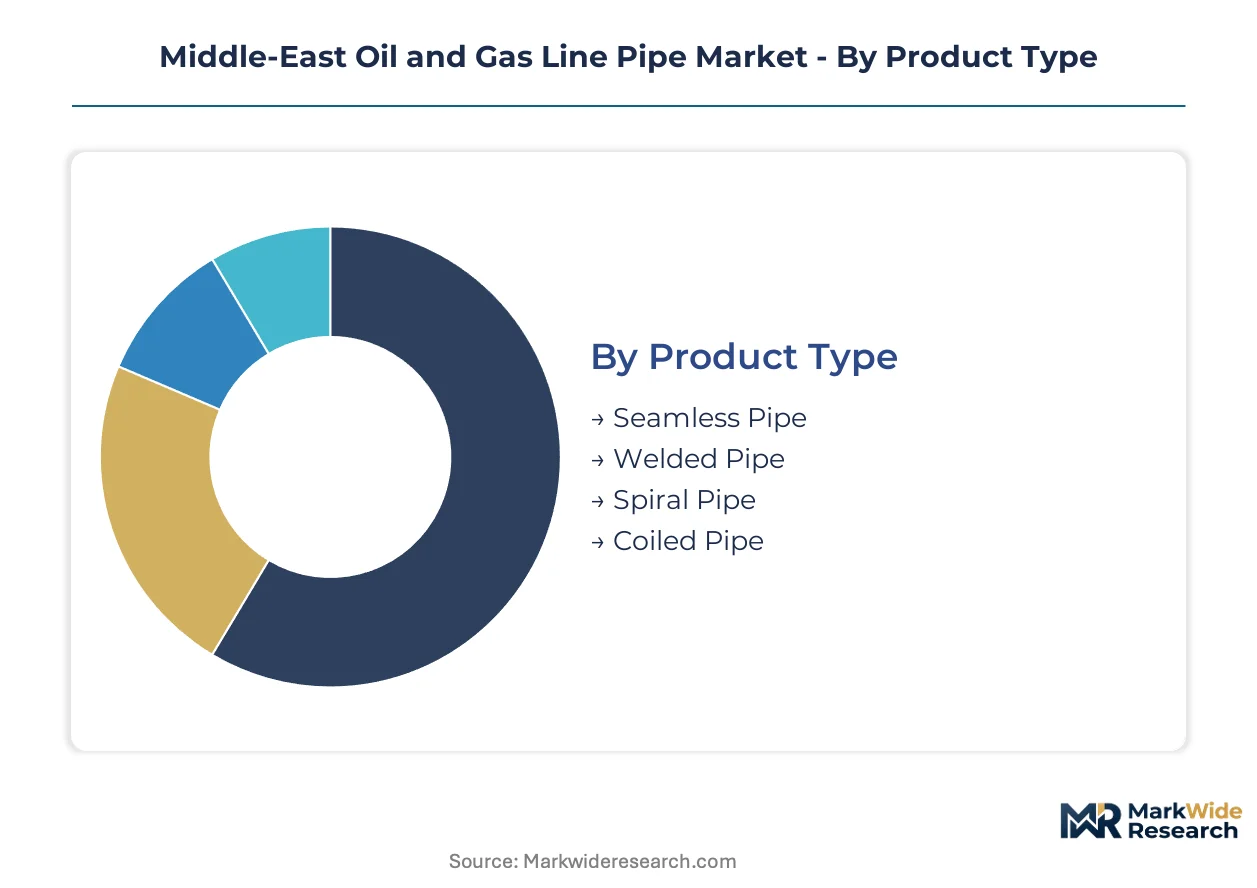
Line pipe procurement in the Middle East fragments across technical specifications, end-use requirements, and material chemistry demands. Each segmentation dimension governs supplier qualification pathways and framework agreement eligibility differently.
Product Type:
After-sales service intensity varies sharply across manufacturing processes, with seamless pipe demanding metallurgical support and welded variants requiring field welding supervision.
- Seamless Pipe:Hot-rolled cylindrical steel manufactured without longitudinal welds, meeting API 5L X80 and sour-service grades for high-pressure applications. Aramco's offshore riser programs in Saudi Arabia's Eastern Province specify seamless exclusively, though limited Gulf-region hot-rolling mill capacity constrains rapid order fulfillment.
- Welded Pipe:Longitudinal submerged arc weld (LSAW) and electric resistance weld (ERW) variants dominate onshore trunk lines where diameter exceeds twenty inches. Qatar's North Field expansion drives volume demand for LSAW in gas transmission corridors, with cost efficiency governing selection over defect tolerance.
- Spiral Pipe:Helical seam construction from coiled strip enables large-diameter production at lower capital intensity. Water injection and gathering line applications in Iraq's Basra fields utilize spiral weld for non-critical pressure ratings.
- Coiled Pipe:Continuous length tubing deployed for downhole and gathering line applications requiring minimal joint count. Coiled tubing units service well intervention programs across UAE onshore concessions.
By volume, welded pipe leads. By growth pace, seamless is gaining share fastest as sour-service specifications tighten.
End User:
Procurement authority concentrates with national oil companies, though contractor intermediaries shape technical specifications and logistics execution.
- Oil Producers:Saudi Aramco, ADNOC, and QatarEnergy anchor demand through multi-year framework agreements bundling pipe with valves and inspection services. These operators dictate material grades, testing protocols, and in-country value-add thresholds through technical specifications.
- Gas Distributors:Qatari and Emirati LNG export capacity expansions require high-pressure transmission infrastructure connecting liquefaction trains to marine terminals. Gas trunk line procurement emphasizes large-diameter welded pipe with sour-service alloy content.
- Pipeline Contractors:Construction firms execute installation programs under engineering-procurement-construction contracts, managing welding crew deployment and field joint coating. Saudi Arabia's Eastern Province fabrication yards face acute shortage of qualified sour-service welders.
- Energy Utilities:Power generation and water desalination facilities require distribution networks for fuel gas and feedwater. UAE hydrogen backbone initiatives specify hydrogen-ready line pipe for blue ammonia export infrastructure.
By contract value, oil producers dominate. By project velocity, gas distributors are expanding most quickly.
Material:
Material selection governs corrosion resistance, pressure rating, and total installed cost across sweet and sour hydrocarbon environments.
- Carbon Steel:API 5L B through X70 grades serve sweet gas and crude transmission where CO2 and H2S content remains minimal. Standard carbon grades occupy volume leadership in Saudi onshore gathering systems.
- Alloy Steel:Chromium-molybdenum additions enhance sour-service performance for corrosive reservoir chemistry. Nickel and molybdenum input cost volatility compresses margin predictability for these premium grades.
- Stainless Steel:Duplex and super-duplex alloys specified for offshore risers and subsea manifolds where chloride exposure is severe. North Field expansion projects in Qatar utilize super-duplex for critical flowlines.
- Polymer:Thermoplastic composite pipe and flexible riser systems reduce topside weight in offshore installations. Composite reinforcement layers bonded to steel substrates are displacing traditional cathodic protection approaches.
By tonnage shipped, carbon steel leads. By specification upgrades, alloy steel shows the steepest expansion trajectory.
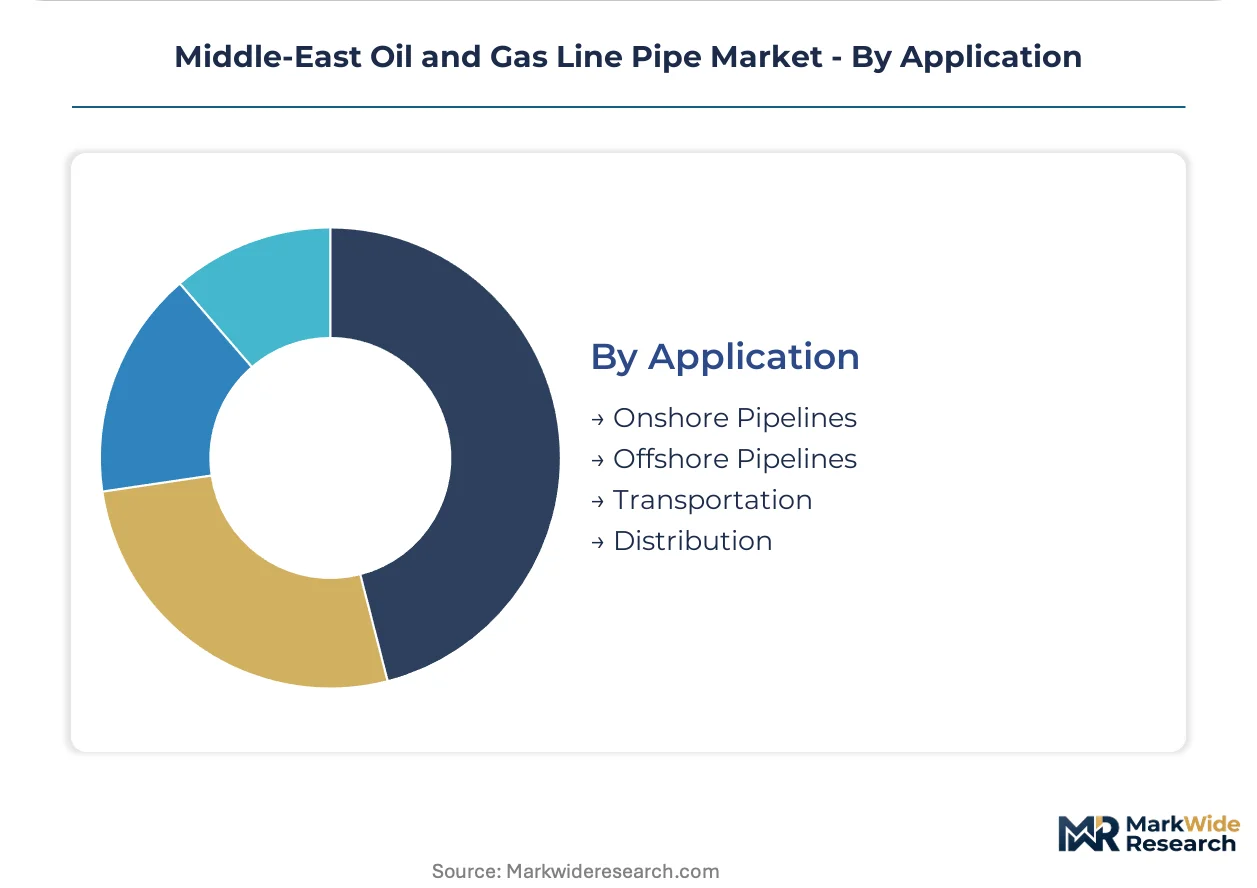
Application:
Installation environment dictates diameter range, pressure class, and coating requirements more than any other segmentation dimension.
- Onshore Pipelines:Trunk lines and gathering systems across Saudi Arabia's Eastern Province sustain large-diameter orders. Aramco's field development programs specify longitudinal submerged arc weld pipe for transmission corridors exceeding 500 kilometers.
- Offshore Pipelines:Subsea flowlines and export lines require seamless or clad pipe with enhanced collapse resistance. Qatar's North Field expansion drives demand for heavy-wall seamless in deepwater applications.
- Transportation:Inter-regional trunk lines and cross-border export infrastructure. Iraq underinvestment recovery will require extensive gathering line replacement for Basra field rehabilitation.
- Distribution:Last-mile networks connecting processing facilities to end-use points. Urban distribution in UAE industrial zones specifies smaller-diameter pipe with polyethylene coating.
By installed length, onshore pipelines lead. By capital intensity per kilometer, offshore pipelines command premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Standards, Metrology and Quality Organization local content mandates are redirecting procurement toward domestic fabrication across the Gulf. Pipeline networks in Saudi Arabia, Qatar, and the UAE anchor regional demand as LNG export capacity expands.
Saudi Arabia
Aramco's field development programs in the Eastern Province sustain large-diameter seamless and welded pipe orders. The Saudi Standards, Metrology and Quality Organization enforces in-country value-add thresholds that require foreign manufacturers to thread, inspect, and coat within Kingdom borders. Dammam-based joint ventures and Riyadh fabrication yards are expanding capacity to meet framework agreement qualification requirements.
Qatar
QatarEnergy's North Field expansion drives demand for heavy-wall seamless pipe in deepwater offshore applications. The country's national hydrocarbon regulator mandates sour-service material specifications for corrosive reservoir chemistry. Industrial clusters around Ras Laffan concentrate liquefaction train infrastructure and marine terminal connectivity projects.
United Arab Emirates
ADNOC's blue ammonia and hydrogen export plans specify new dedicated hydrogen-ready line pipe specifications for transmission infrastructure. The national oil company's technical procurement standards privilege suppliers with in-country coating and inspection capabilities. Abu Dhabi and Dubai fabrication facilities are upgrading to meet accelerated project cycle timelines.
Iraq
Basra field rehabilitation and water injection programs will require extensive gathering line replacement as underinvestment recovery accelerates. The country's national oil ministry is revising procurement regulations to attract international fabricators for trunk line reconstruction. Southern oilfields around Basra represent the primary concentration of pipeline replacement demand.
Kuwait
Kuwait Oil Company heavy oil development programs are specifying sour-service alloy grades for high-pressure steam injection lines. The national petroleum regulator maintains approved manufacturer lists that prioritize API 5L qualified suppliers with regional threading facilities. Ahmadi and Mina Al-Ahmadi industrial zones concentrate fabrication and coating operations for upstream gathering systems.
Middle-East Oil and Gas Line Pipe Market Competitive Landscape
Integrated seamless producers and regional welded specialists split the market between premium high-pressure applications and volume onshore trunk lines. Saudi Aramco's vendor consolidation into framework agreements has compressed the qualified supplier base to fewer than twelve seamless manufacturers. Two strategic archetypes dominate: global mill operators with Gulf-region threading facilities, and domestic fabricators leveraging local content mandates. Capacity expansion through joint venture licensing and backward integration into hot-rolling represents the primary competitive moves.
Within the integrated mill tier, Tenaris SA and Vallourec SA exemplify global operators positioning through proximity supply strategies. Arabian Pipes Company anchors domestic fabrication capacity through Riyadh and Jubail plants, representing the regional specialist archetype that Saudi Standards, Metrology and Quality Organization regulations privilege. Jindal SAW Ltd occupies a position on spiral-weld cost structures for water and gas transmission lines where diameter and efficiency govern selection.
| Leading Market Players |
|---|
| Tenaris SA |
| EEW Group |
| Arabian Pipes Company |
| Sumitomo Corporation |
| Abu Dhabi Metal Pipes & Profiles |
| Rezayat Group |
| Jindal SAW Ltd |
| ArcelorMittal SA |
| Vallourec SA |
| Others |
Supply & Pricing Matrix
Nickel and molybdenum price volatility determines both the alloy premium spread across sour-service grades and the geographic configuration of threading and coating capacity. Saudi Standards, Metrology and Quality Organization local content mandates compress standard-carbon pricing tiers while amplifying configured-to-order premiums for in-country value-add operations.
Pricing Analysis
Configured-to-order pricing for sour-service seamless pipe commands a substantial premium over standard carbon grades in spot procurement. Price differentiation rests on API 5L certification tier and in-country threading completion, with alloy steel grades exhibiting the widest spreads due to nickel-molybdenum input cost exposure. Cost compression in welded trunk-line segments is intensifying because Qatari and Emirati LNG contractors consolidate volume into multi-year frameworks. Pipeline contractors represent the most price-sensitive buyer archetype, while Saudi Aramco's engineering-procurement-construction bundles show lowest sensitivity due to lifecycle cost framing.
Supply Chain Analysis
Tariff exposure between seamless pipe source mills in Japan, South Korea, and Italy and Saudi Arabia's Eastern Province fabrication yards dominates supply chain risk assessment. Raw material dependencies center on hot-rolled coil from China, nickel from Indonesia, and molybdenum from Chile. Single-source vulnerability concentrates in Gulf-region hot-rolling mill capacity for large-diameter seamless. Distribution runs through Dammam-based joint ventures and Riyadh coating facilities qualified under Saudi Aramco framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to Iraq's Basra field rehabilitation and Qatar's North Field expansion capex cycles. Capital deployment should front-load qualification investments before framework agreement windows compress.
For Market Incumbents: Harden framework agreement positioning by securing Saudi Standards, Metrology and Quality Organization certification for expanded Dammam threading capacity. Defensive consolidation should prioritize backward integration into hot-rolling through joint venture licensing to offset seamless capacity scarcity. Threat substitution from thermoplastic composite pipe in Qatar's offshore riser applications demands metallurgical R&D investment in clad steel alternatives.
For New Entrants and Emerging Players: Pursue Iraq's gathering line replacement segment where procurement regulations are revising to attract international fabricators. Basra field water injection programs represent the most penetrable white-space target due to underinvestment recovery acceleration. A go-to-market angle through EPC contractor partnerships for field welding supervision bypasses Aramco's consolidated vendor list chokepoint.
For Investors and Strategic Acquirers: ADNOC's hydrogen-ready line pipe specification issuance reshapes the acquisition landscape toward coating specialists with UAE in-country capabilities. Long-term viability favors regional specialists with qualified threading facilities over pure import traders. The signal to watch is qualification timeline compression for sour-service welders and NDT inspectors across Eastern Province fabrication yards.
| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Licensing | Enables foreign seamless mills to meet Saudi Standards, Metrology and Quality Organization threading mandates without greenfield capex. |
| Capacity Expansion | Arabian Pipes Company's Riyadh and Jubail plants anchor domestic fabrication for Aramco framework eligibility. |
| Long-term Supply Agreement | Tenaris SA's Dammam proximity supply sustains Saudi Aramco onshore program continuity through multi-year bundles. |
| Technology Licensing | Thermoplastic composite pipe technology transfer addresses Qatar's North Field weight-reduction specifications for deepwater risers. |
| Backward Integration | Hot-rolling mill investment in the Gulf region alleviates seamless capacity scarcity for large-diameter high-pressure applications. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with procurement directors at Saudi Aramco, ADNOC, and QatarEnergy, welding supervisors at Eastern Province fabrication yards, and EPC contract managers; and secondary validation through API specification revision logs, Saudi Standards, Metrology and Quality Organization local content enforcement notices, and customs records for alloy steel imports. Bottom-up triangulation across project-level line pipe orders and top-down reconciliation against national oil company capex disclosures anchored volume estimates.
Forecast inputs considered manufacturing process, material chemistry grade, end-use pressure class, and in-country value-add completion across the projection horizon. CAGRs were derived from regression against historical framework agreement award patterns and project cycle acceleration trends. Specific inputs included sour-service specification upgrade trajectories and hydrogen-ready pipe qualification timelines under ADNOC technical standards.
Sensitivities concentrate around nickel-molybdenum price volatility, qualification timeline compression, and thermoplastic composite pipe substitution rates in offshore applications. Forecasts embed assumptions regarding Saudi Aramco vendor list stability and Iraq procurement regulatory revision pace. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
US Oil and Gas Analytics Market
Oil & Gas
Oil and Gas Well Conductor Installation Services Market
Oil & Gas
India Artificial Lift Systems Market
Oil & Gas
North America Oil and Gas Electric Submersible Pump Market
Oil & Gas
Russia Drill Pipe Market
Oil & Gas
Expandable Liner Hanger System Market
Oil & Gas
Netherlands LNG Bunkering Market
Oil & Gas
Geothermal Drill Bits Market
Oil & Gas
Asia-Pacific Intelligent Pigging Market
Oil & Gas
Indonesia Oilfield Equipment Rental Services Market
Oil & Gas
Subsea Well Access System Market
Oil & Gas
Drilling Services Market
Oil & Gas
Crude Oil Assay Testing Services Market
Oil & Gas
Oman Oil and Gas Pipeline Market
Oil & Gas
Oilwell Spacer Fluids Market
Oil & Gas
Seismic Survey Equipment Market