
 Workover Rigs Market | 2026-2036
Workover Rigs Market Size, Share, and Industry Trends Forecast 2026-2036
Workover Rigs Market Analysis
The EPA's updated methane emissions standards for oil and gas infrastructure is broadening the addressable market for low-emission workover systems. Precision Drilling Corporation leverages its fleet modernization program to capture contracts under stricter environmental compliance timelines. Nabors Industries Ltd. sustains manufacturing scale through its rig-upgrading facilities in Houston. Schlumberger Ltd. differentiates via integrated well intervention packages that bundle workover rigs with diagnostics.
Workover rigs are mobile or skid-mounted drilling and servicing units designed to perform well intervention, recompletion, and repair operations on existing oil and gas wells, typically rated between 150 and 1,000 horsepower depending on well depth and complexity. These units restore or enhance production from mature wells by replacing downhole equipment, stimulating formations, or sealing unwanted fluid entry. Mobile rigs lead the type category due to their rapid deployment across dispersed well pads in unconventional fields. Electric technology represents the fastest-expanding segment as operators seek to replace diesel-powered units and reduce fuel logistics costs. Onshore operations anchor application demand, though offshore workover activity generates premium pricing for specialized mast and substructure configurations.
The US EPA methane rules, alongside OSHA drilling safety standards and Texas Railroad Commission well integrity requirements, shape equipment specifications and operational protocols for domestic workover contractors. API certification standards for mast and substructure design govern market access for rig manufacturers serving North American operators. Stakeholders must monitor the pace of electric rig adoption against diesel retrofit economics and track how state-level flaring restrictions redirect workover investment toward gas-capture-ready equipment configurations.
Market Dynamics
The EPA's methane emissions standards are compressing the operational window for conventional diesel-powered workover rigs across North American shale basins. Electric rig retrofit economics now dominate capital allocation discussions among Permian Basin operators.
Growth Catalysts
- EPA Methane Rules:The US EPA's updated emissions standards for oil and gas infrastructure are mandating equipment upgrades at wellheads, expanding demand for low-emission workover systems in Texas and New Mexico.
- Permian Basin Concentration:Thousands of aging horizontal wells in the Permian require annual intervention to restore production, creating sustained demand for mobile workover units.
- Electric Powertrain Adoption:Grid-tied and battery-electric rig packages are eliminating diesel fuel logistics costs while meeting stricter flaring restrictions in the Delaware Basin.
Market Restraints
- Steel Input Volatility:Mast and substructure fabrication depends on specialized high-strength steel grades subject to price swings from domestic mill capacity constraints.
- Skilled Labor Scarcity:The dwindling pool of certified rig technicians and well intervention specialists limits fleet expansion regardless of equipment availability.
- Diesel Retrofit Economics:Existing diesel rig fleets face stranded asset risk as electric conversion costs often exceed replacement thresholds for mid-life units.
Strategic Opportunities
- Osage Mineral Rights:Oklahoma's stacked pay formations and underpenetrated well density present untapped demand for shallow-depth workover services.
- Carbon Capture Integration:Workover rigs configured for CO2 injection well maintenance are capturing contracts tied to 45Q tax credit eligibility.
- Remote Monitoring Convergence:IoT sensor networks combined with predictive maintenance software are enabling condition-based service contracts that bundle rig deployment with diagnostics.
Industry Challenges
- API Certification Timelines:Mast and substructure design approvals under API 4F standards create 12-18 month delays for new rig models entering North American service.
- Legacy Control System Integration:Electric rig retrofits must interface with existing SCADA infrastructure, complicating fleet standardization for multi-basin operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Workover Rigs Market |
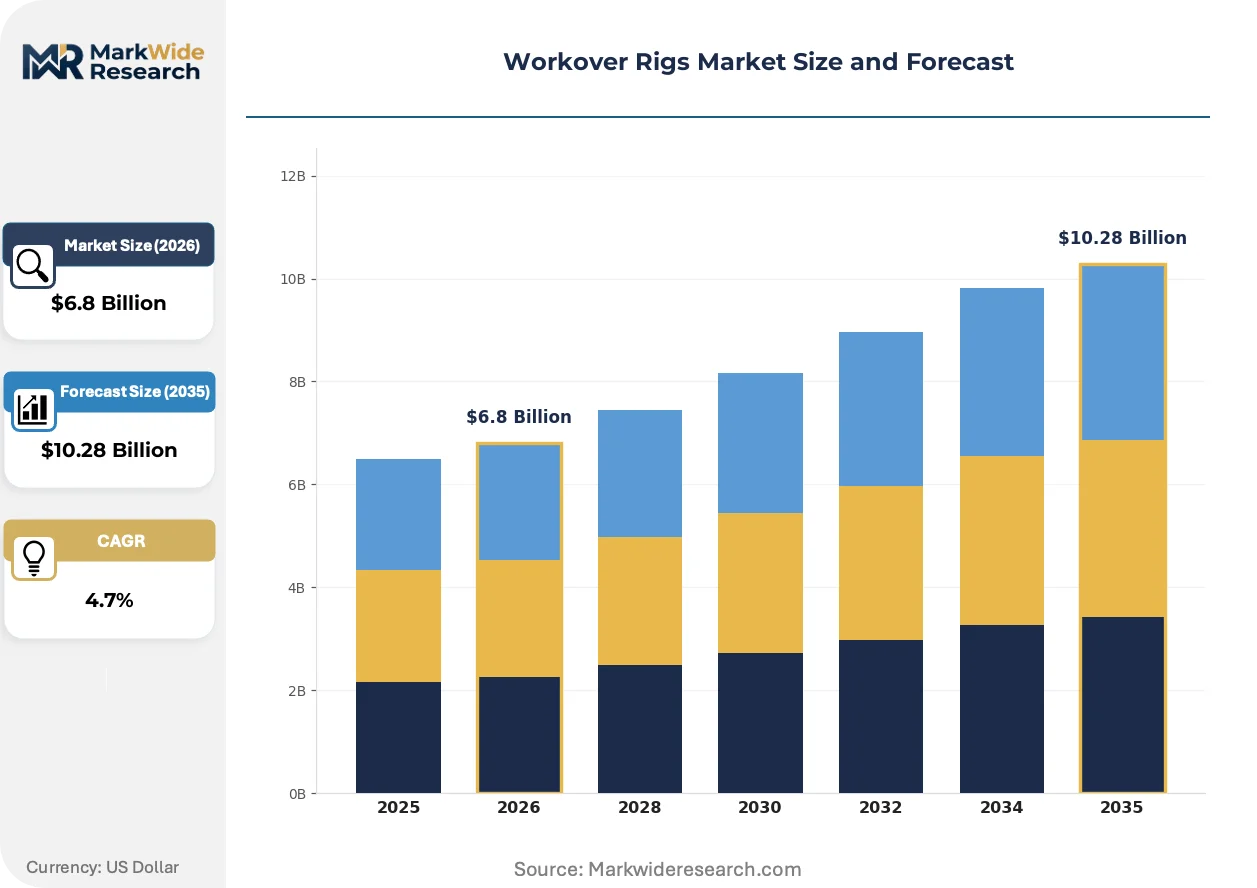
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Mobile Rigs, Modular Rigs, Conventional Rigs, Land Rigs Technology: Hydraulic, Electric, Mechanical, Hybrid Application: Onshore Operations, Offshore Operations, Oil Recovery, Gas Recovery End User: Oil Producers, Gas Producers, Energy Companies, Service Providers |
| Companies Covered | Precision Drilling Corporation, Superior Energy Services, Schlumberger Ltd., KLX Energy Services Holdings Inc., National Energy Services Reunited Corp., Nabors Industries Ltd., National Oilwell Varco Inc., San Antonio Internacional, Helmerich & Payne Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Workover Rigs Market Emerging Trajectories
Workover rig technology is pivoting toward electrification and automation as environmental compliance costs reshape operator procurement criteria. The convergence of grid infrastructure and digital controls is redefining service delivery models.
Automated pipe handling systems are automating tripping operations that previously required manual floor crews. Permian Basin operators are deploying these systems on new-build electric rigs to reduce headcount and accelerate cycle times. The technology is automating the most labor-intensive phase of workover operations while improving safety metrics under OSHA drilling standards.
The EPA's methane emissions standards are forcing equipment specifications that favor sealed wellbore interventions and closed-loop circulation systems. Manufacturers must now engineer mast structures that accommodate gas-capture shrouds and vapor recovery units. Onshore contractors in the Permian and Eagle Ford are responding by specifying electric prime movers that eliminate engine exhaust sources near the wellhead.
Service contract structures are unbundling rig dayrates from integrated diagnostics that were previously bundled. Large independents in the Delaware Basin now source workover rigs separately from wireline and logging services, compressing vendor relationships and favoring specialized rig operators over integrated service companies. This disaggregation is most visible among Permian-focused E&Ps with centralized procurement functions.
Workover Rigs Market Segmentation
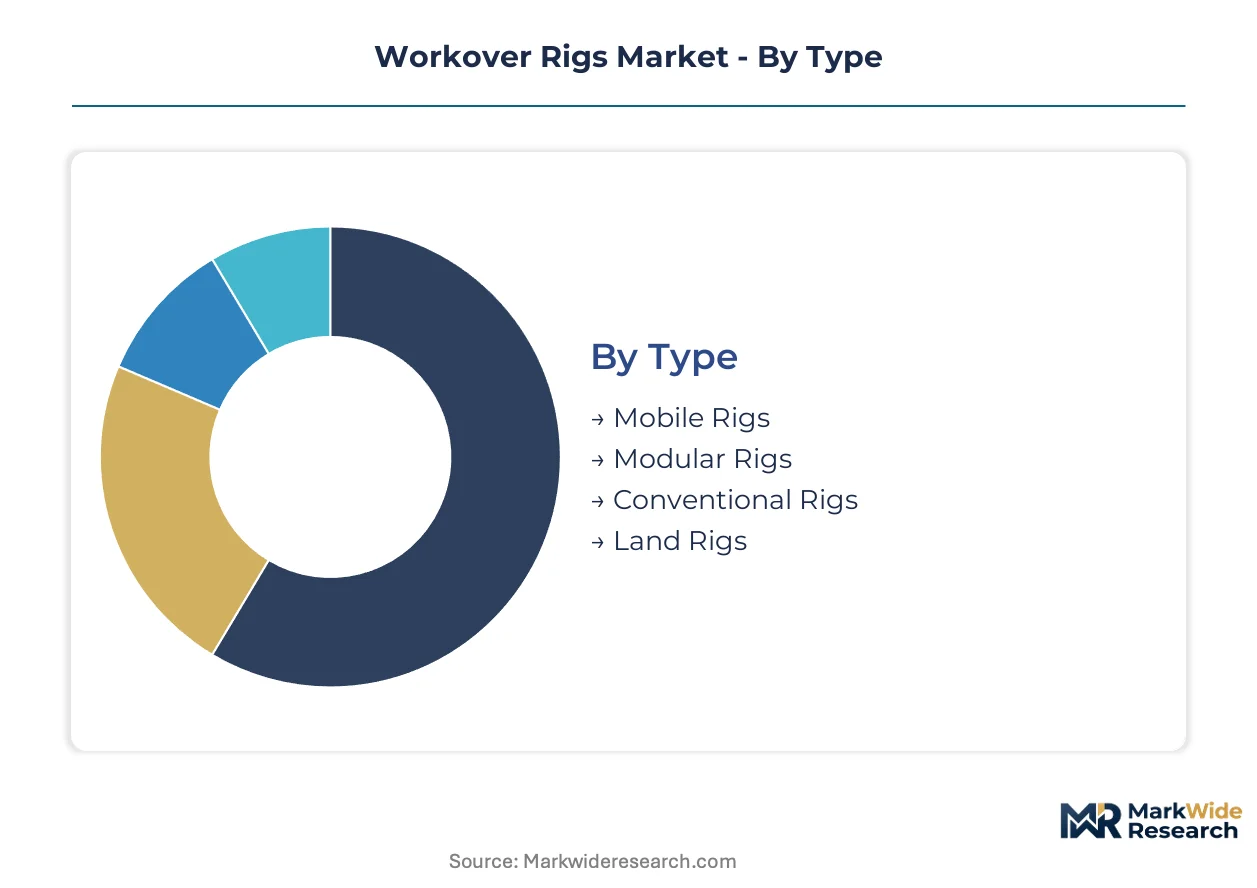
Workover rig procurement varies sharply by operational context, with mobility requirements and emissions compliance driving category selection. Operators in mature basins prioritize rapid deployment and environmental specifications over raw lifting capacity.
Type:
The customization-to-standardization spectrum spans purpose-built mobile units for pad drilling against fixed conventional configurations for permanent yard operations.
- Mobile Rigs:Self-propelled or truck-mounted units rated 150-600 horsepower enable same-day relocation between dispersed well pads. Demand concentrates in the Permian Basin of Texas and New Mexico where operators must service thousands of horizontal wells across multi-county leaseholds. EPA methane rules favor these units for their compatibility with closed-loop circulation systems and vapor recovery integration.
- Modular Rigs:Mast and substructure components ship separately for rapid field assembly, suiting remote locations with limited road infrastructure. The Delaware Basin's gas-capture mandates accelerate procurement of modular electric packages that split across standard flatbed trucks.
- Conventional Rigs:Skid-mounted permanent installations serve centralized workover yards with dedicated power infrastructure.
- Land Rigs:Heavy-duty fixed structures rated above 750 horsepower address deep recompletions in Oklahoma's Anadarko Basin.
Leading the category by volume: Mobile Rigs. Growing fastest: Modular Rigs.
Technology:
Cost tier stratification separates premium electric systems from baseline mechanical drive trains, with hybrid configurations occupying the mid-market retrofit niche.
- Electric:Grid-tied or battery-electric prime movers eliminate diesel exhaust at the wellhead while cutting fuel logistics costs. The Texas Railroad Commission's flaring restrictions and EPA methane standards accelerate Permian Basin adoption. These systems command premium pricing but reduce operational expenditures through eliminated fuel transport and simplified maintenance intervals.
- Hydraulic:Hydrostatic drive systems deliver precise torque control for extended-reach lateral interventions. Demand clusters in the Eagle Ford Shale where high-pressure formations require controlled weight-on-bit management during plug drillouts.
- Mechanical:Diesel-mechanical drive trains dominate legacy fleets facing stranded asset risk under tightening emissions standards.
- Hybrid:Dual-power configurations blend diesel generation with battery buffering for peak shaving during tripping operations.
Electric technology claims the steepest expansion trajectory as compliance costs reshape capital allocation. Hydraulic systems retain share in high-torque applications.
Application:
Volume concentration favors onshore shale operations, while offshore configurations generate margin premiums through specialized mast engineering and marine certification requirements.
- Onshore Operations:Land-based workover activity spans well intervention, recompletion, and artificial lift installation across mature basins. The Permian and Delaware Basins generate sustained demand for mobile units handling annual interventions on horizontal wells. OSHA drilling safety standards and Texas Railroad Commission well integrity requirements govern equipment specifications.
- Offshore Operations:Platform-based and modular offshore rigs require API 4F-certified mast structures with enhanced fatigue resistance. Premium pricing reflects marine environment engineering and specialized subsea intervention packages.
- Oil Recovery:Artificial lift replacement and formation stimulation target declining oil wells.
- Gas Recovery:Wellhead compression and dehydration system maintenance address gas well productivity restoration.
Onshore Operations anchor absolute demand. Offshore Operations extract highest dayrate premiums per rig.
End User:
Customer type determines procurement sophistication, with integrated energy companies driving standardization against service provider flexibility requirements.
- Oil Producers:Exploration and production companies with concentrated Permian leaseholds favor long-term rig contracts with embedded maintenance provisions. These operators specify electric technology to meet EPA compliance timelines and secure 45Q tax credit eligibility for carbon capture integration.
- Service Providers:Independent workover contractors prioritize fleet interchangeability across multiple operator clients. These stakeholders resist technology lock-in, favoring mechanical and hydraulic systems with broad maintenance technician availability.
- Gas Producers:Dry gas operators in the Marcellus and Haynesville prioritize gas-capture-ready configurations.
- Energy Companies:Integrated majors with diversified portfolios standardize on modular electric platforms.
Oil Producers dominate capital deployment. Service Providers expand fastest as operators outsource workover activity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States produces the majority of workover rig demand while fabrication capacity concentrates in Texas and Oklahoma. Consumption patterns track shale basin maturity curves rather than population centers.
United States
Permian Basin operators deploy thousands of mobile workover units annually to restore production from aging horizontal wells. The EPA's updated methane emissions standards mandate equipment upgrades at wellheads, accelerating electric rig procurement timelines. Midland-Odessa anchors the densest rig concentration, with service yards clustering along Interstate 20 to minimize mobilization distances.
Canada
Alberta's oil sands and conventional heavy oil fields sustain steady demand for high-horsepower workover systems. The country's national energy regulator enforces stringent well integrity requirements that favor API-certified mast structures. Calgary serves as the procurement hub, with fabrication partnerships extending into Saskatchewan's Bakken extension plays.
Saudi Arabia
Aramco's mature onshore fields require continuous intervention to maintain plateau production rates. The national oil company imposes localization mandates that steer contract awards toward joint ventures with domestic fabrication partners. Dammam's industrial zone hosts the primary rig assembly and maintenance facilities serving Eastern Province operations.
China
Sinopec and PetroChina accelerate workover activity in aging Daqing and Shengli oilfields to offset natural decline rates. The Ministry of Ecology and Environment enforces dual carbon goals that favor electric and natural gas-powered rig configurations over diesel units. Shandong Province's manufacturing corridor supplies the domestic market while exporting skid-mounted units to Central Asian operators.
Brazil
Pre-salt field maturation drives offshore workover demand for platform-compatible mast configurations. ANP regulatory frameworks mandate Brazilian content requirements that shape supplier selection for Petrobras contracts. Macaé's port complex anchors the service vessel and modular rig supply chain for Campos Basin operations.
Workover Rigs Market Vendor Landscape
The competitive structure tilts toward integrated service conglomerates with manufacturing depth. Tier-one participants combine rig fabrication capabilities with bundled well intervention services, while mid-scale contractors compete on fleet mobility and basin-specific expertise. Two archetypes dominate: vertically integrated energy service companies controlling upstream equipment supply chains, and specialized rig operators focusing on rapid-deployment mobile units. Competitive moves center on electric powertrain retrofit partnerships and carbon-capture-ready equipment certifications.
Among North American energy service providers, Precision Drilling Corporation and Nabors Industries Ltd. exemplify the integrated manufacturing archetype, while Schlumberger Ltd. occupies a position emphasizing technology bundling over captive rig production. These three anchors represent divergent strategic postures within a market where environmental compliance timelines increasingly determine contract awards.
| Leading Market Players |
|---|
| Precision Drilling Corporation |
| Superior Energy Services |
| Schlumberger Ltd. |
| KLX Energy Services Holdings Inc. |
| National Energy Services Reunited Corp. |
| Nabors Industries Ltd. |
| National Oilwell Varco Inc. |
| San Antonio Internacional |
| Helmerich & Payne Inc. |
| Others |
Supply Flow & Price Mechanics
Permian Basin operators with concentrated horizontal well portfolios negotiate electric rig contracts on a project-basis with embedded maintenance provisions, compressing dayrate premiums for diesel-mechanical units while elevating grid-tied powertrain pricing.
Pricing Analysis
Margin tightening in legacy diesel-mechanical tiers reflects stranded asset risk as EPA methane compliance timelines accelerate fleet obsolescence. Three-tier pricing structure across premium electric, standard hydraulic, and economy mechanical levels segments buyers by environmental mandate exposure and capital availability. Oil Producers with 45Q tax credit eligibility absorb premium electric pricing; Service Providers with multi-basin fleets exhibit acute price sensitivity to avoid technology lock-in.
Supply Chain Analysis
Regional distribution centers in Houston, Calgary, and Dammam anchor hub-and-spoke patterns for mast and substructure components. Fabrication draws from high-strength steel mills in the United States, China, and South Korea. Single-source vulnerability concentrates in specialized API 4F-certified casting foundries. Distribution runs through basin-proximate service yards along Interstate 20 and Alberta Highway 2.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The workover rigs sector is consolidating around captive manufacturing of electric powertrains and proprietary control systems as environmental compliance becomes the primary procurement filter.
For Market Incumbents: Anchor fleet modernization programs in Permian Basin service yards to capture EPA-driven contract migration away from diesel units. Secure backward integration into battery-electric powertrain assembly to defend margin position against integrated energy service conglomerates. Prioritize API 4F certification pipelines for next-generation mast structures. For New Entrants and Emerging Players: Launch via modular electric rig platforms targeting Oklahoma's Osage Mineral Rights where shallow-depth specifications lower capital barriers. Exploit Service Provider resistance to technology lock-in by offering interchangeable hydraulic-electric hybrid configurations. Penetrate through condition-based service contracts bundling predictive maintenance software with rig deployment. For Investors and Strategic Acquirers: The window for entry favors mid-scale contractors with basin-specific expertise and established maintenance technician networks. Long-term viability hinges on carbon-capture-ready equipment certifications and 45Q tax credit eligibility. Monitor Texas Railroad Commission flaring restriction enforcement as the inflection signal for electric rig procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Powertrain Retrofit Program | EPA methane rules in Texas and New Mexico mandate diesel elimination at wellheads. |
| API 4F Certification Fast-Track | 12-18 month approval timelines create first-mover advantage for compliant mast structures. |
| Carbon Capture Integration Partnership | 45Q tax credit eligibility redirects workover investment toward CO2 injection maintenance. |
| Remote Monitoring Platform Launch | IoT sensor networks enable condition-based contracts bundling diagnostics with rig deployment. |
| Basin-Proximate Service Yard Expansion | Midland-Odessa clustering minimizes mobilization distances across multi-county Permian leaseholds. |
Methodological Framework
Document review covered SEC 10-K filings from energy service providers, EIA drilling activity databases, and EPA regulatory dockets, complemented by interviews with rig fleet managers, well intervention specialists, and procurement officers at Permian Basin E&Ps. Secondary validation drew from API certification records, Texas Railroad Commission well integrity reports, and OSHA drilling safety incident data. Bottom-up rig deployment counts triangulated against top-down basin-level capital expenditure estimates.
Unit-level pricing and fleet composition outputs across the projection horizon reflect modeled segmentation by powertrain technology, mobility configuration, and basin-specific regulatory framework. The analytical framework incorporated well intervention frequency curves for mature horizontal wells, electric grid infrastructure expansion timelines, and diesel retrofit economics thresholds. CAGRs derived from regression against historical rig utilization rates and capital deployment patterns in the Permian and Delaware Basins.
EPA enforcement variance, steel input cost volatility, and skilled technician availability constraints are the dominant revision risks to modeled outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Malaysia Oilfield Services Market
Oil & Gas
Large Scale LNG Terminal Market
Oil & Gas
Well Test Market
Oil & Gas
Digital Twin in Oil and Gas Market
Oil & Gas
Small Scale LNG (SSLNG) Market
Oil & Gas
Oil and Gas Hose Assemblies Market
Oil & Gas
Sand Screen Sales Market
Oil & Gas
South America Oil and Gas Hoses and Coupling Market
Oil & Gas
Oil Hose Market
Oil & Gas
Asia Pacific Oil Storage Tank Service Market
Oil & Gas
Oil Storage Terminal Market
Oil & Gas
Drones for Oil & Gas Market
Oil & Gas
Whipstocks Market
Oil & Gas
Modular Gas Processing Plants Market
Oil & Gas
Saudi Arabia Liner Hanger System Market
Oil & Gas
LAMEA Oilfield Auxiliary Rental Equipment Market