
 Gaucher and Pompe Diseases Enzyme Replacement Therapy (ERT) Market | 2026-2036
Gaucher and Pompe Diseases Enzyme Replacement Therapy (ERT) Market Size, Share, and Industry Trends Forecast 2026-2036
Gaucher and Pompe Diseases Enzyme Replacement Therapy (ERT) Market Foresight
Subcutaneous enzyme delivery platforms is fragmenting the traditional intravenous infusion paradigm that has dominated lysosomal storage disease management for decades. Sanofi sustains manufacturing scale through its established recombinant enzyme production infrastructure in Europe and North America. Takeda Pharmaceutical Company Limited anchors its position through deep clinical experience with alglucosidase alfa across both infantile and late-onset Pompe indications. BioMarin Pharmaceutical specializes in ultra-rare genetic disease modalities, leveraging its gene therapy adjacent capabilities to inform next-generation ERT engineering.
Gaucher and Pompe Diseases Enzyme Replacement Therapy comprises parenterally administered recombinant hydrolases that supplement or replace deficient glucocerebrosidase or acid alpha-glucosidase activity in lysosomal compartments, typically requiring stabilization in citrate-buffered formulations at controlled temperatures during distribution. These biologics functionally prevent glycosphingolipid or glycogen accumulation in macrophages and cardiac or skeletal muscle tissue, thereby preserving organ function in progressive storage disorders. Among therapy areas, Gaucher Disease Type 1 maintains the largest treated population given its non-neuronopathic course and longer life expectancy, while Pompe Disease Infantile commands premium positioning due to catastrophic disease progression without intervention. Velaglucerase Alfa and Taliglucerase Alfa within product types compete on immunogenicity profiles and plant-cell versus mammalian expression system manufacturing economics.
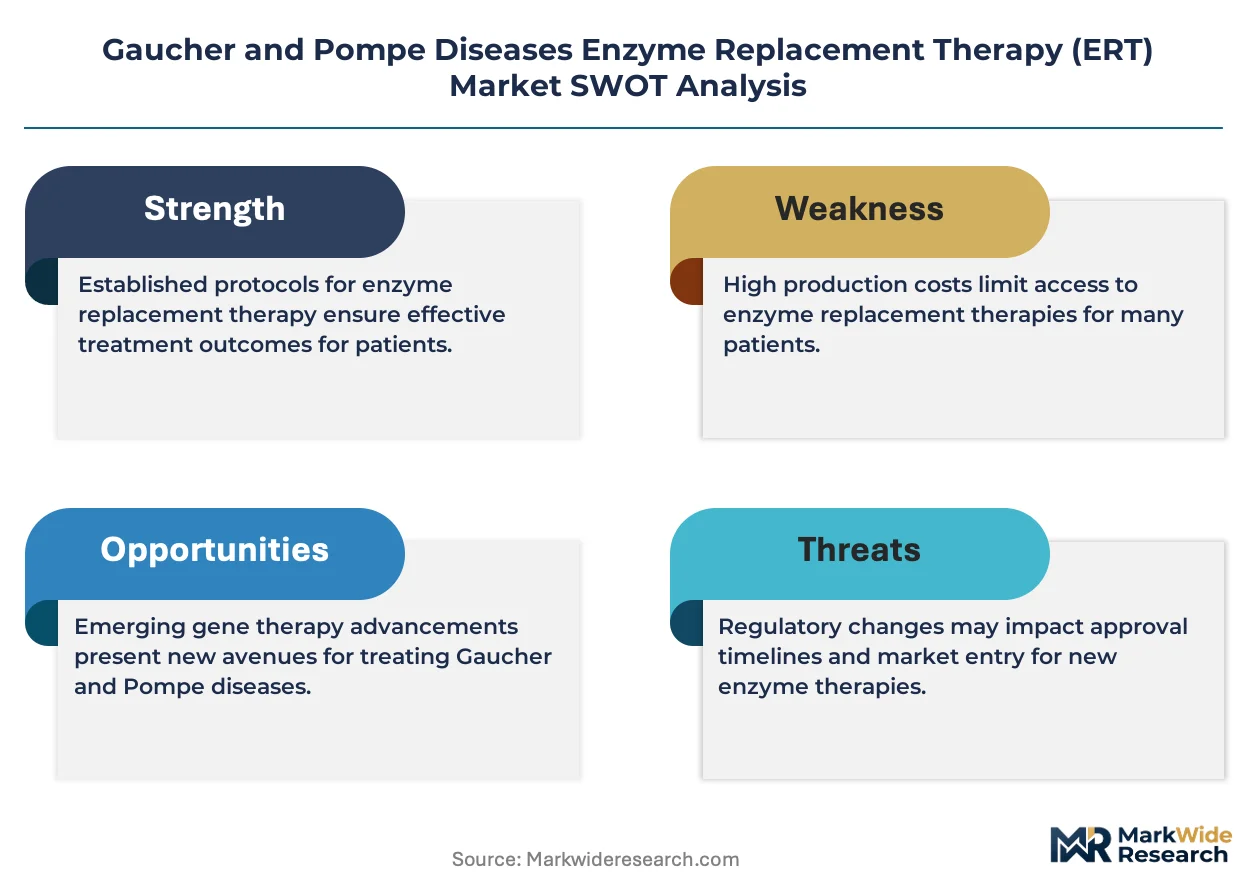
The FDA's Rare Pediatric Disease program and EMA's orphan drug framework jointly shape clinical trial design and post-market surveillance obligations for enzyme replacement developers seeking expedited pathways. Reimbursement authorities including Germany's G-BA and France's HAS apply incremental cost-effectiveness thresholds that constrain pricing flexibility for therapies addressing ultra-small prevalence populations. Stakeholders must monitor competitive entry of oral substrate reduction therapies and gene replacement approaches that could displace chronic ERT administration paradigms.
Market Dynamics
Subcutaneous enzyme delivery platforms are compressing the chronic infusion burden that has defined lysosomal storage disease management for two decades. This modality shift is redistributing prescriber influence from hospital-based infusion centers toward specialty pharmacy networks and home health services.
Growth Catalysts
- FDA Rare Pediatric Disease Priority Review Voucher program:The voucher incentive accelerates regulatory timelines for novel enzyme formulations targeting infantile-onset indications. Developers capture secondary revenue through voucher monetization.
- Neonatal screening expansion:State-level newborn screening programs for Pompe disease in the United States identify presymptomatic infants before irreversible cardiac damage. Early detection expands the addressable patient pool for chronic ERT initiation.
- Plant-cell expression systems:Taliglucerase Alfa's tobacco-cell manufacturing platform reduces production costs versus mammalian-cell alternatives. This technology is broadening payer acceptance of ERT in cost-constrained reimbursement environments.
Market Restraints
- Plasma-derived enzyme supply concentration:Alglucerase production historically depended on human placental tissue sourcing. Recombinant alternatives now dominate, but manufacturing scale remains concentrated among three European and North American production facilities.
- Incremental cost-effectiveness thresholds:Germany's G-BA applies strict quality-adjusted life year limits to ultra-rare disease therapies. ERT pricing faces downward pressure when incremental clinical benefit is marginal versus standard of care.
- Oral substrate reduction therapy substitution:Eliglustat for Gaucher Disease Type 1 eliminates biweekly infusion requirements. Patient switching to oral alternatives constrains ERT volume growth in the largest treated population segment.
Strategic Opportunities
- Gene therapy convergence:AAV vector delivery of functional GAA or GBA genes promises single-dose disease modification. ERT developers with gene therapy adjacent capabilities can leverage clinical infrastructure and prescriber relationships for pipeline transition.
- Home infusion channel expansion:Specialty pharmacy networks are capturing ERT administration from hospital outpatient departments. This channel shift reduces facility fees and improves patient compliance through reduced travel burden.
- EMA orphan drug market exclusivity:The ten-year exclusivity period protects novel enzyme formulations from biosimilar competition. Developers can secure premium positioning for next-generation products with improved immunogenicity profiles.
Industry Challenges
- Immunogenicity management expertise:Anti-drug antibody development requires specialized monitoring protocols. Clinical teams must maintain competence in infusion reaction management and immune tolerance induction procedures.
- Cold chain integrity maintenance:Citrate-buffered enzyme formulations require controlled temperature distribution from manufacturing through patient administration. Logistics failures degrade product potency and trigger safety reporting obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gaucher and Pompe Diseases Enzyme Replacement Therapy (ERT) Market |
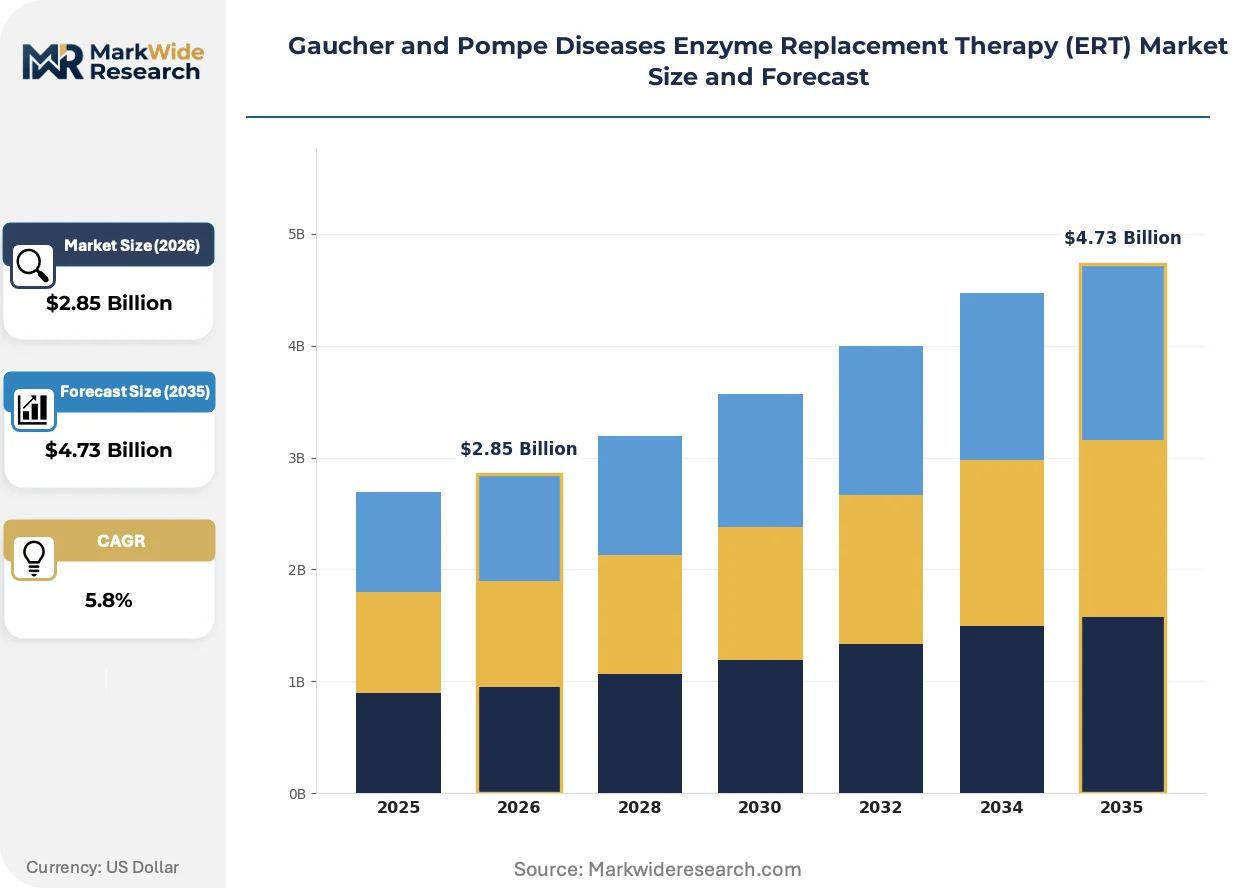
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.73 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alglucerase, Imiglucerase, Velaglucerase Alfa, Taliglucerase Alfa, Alglucosidase Alfa Therapy Area: Gaucher Disease Type 1, Gaucher Disease Type 2, Pompe Disease Infantile, Pompe Disease Late-Onset Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Oral, Inhalation End User: Specialty Clinics, Research Institutes, Home Care Providers, Rare Disease Centers |
| Companies Covered | Amicus Therapeutics, Ultragenyx Pharmaceutical Inc., Sanofi, AbbVie Inc., Pfizer Inc., Takeda Pharmaceutical Company Limited, Alexion Pharmaceuticals, Protalix Biotherapeutics Inc., BioMarin Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gaucher and Pompe Diseases Enzyme Replacement Therapy (ERT) Market Shifts & Advancements
Enzyme engineering and delivery modality innovation are converging to reshape chronic dosing paradigms. These developments are compressing treatment burden while expanding the prescriber base beyond traditional academic medical centers.
Subcutaneous enzyme formulations are hybridizing the administration landscape for lysosomal storage diseases. These platforms reduce infusion duration from hours to minutes and eliminate vascular access requirements. Pediatric patients and their caregivers are adopting home-based subcutaneous delivery at accelerating rates. This technology is hybridizing site-of-care economics and redistributing revenue from hospital infusion suites toward specialty pharmacy providers.
The EMA's orphan drug framework is tightening post-authorization evidence requirements for enzyme replacement therapies. Regulators now mandate long-term registry data on clinical outcomes and immunogenicity profiles. This policy shift is extending development timelines and increasing post-market surveillance costs. Developers are responding by embedding patient registries into clinical trial design rather than retrofitting data collection after approval.
Patient advocacy organizations are consolidating purchasing influence through centralized referral networks. These groups are directing newly diagnosed patients toward centers with demonstrated ERT expertise and favorable payer contracts. Academic medical centers with established lysosomal storage disease programs are capturing disproportionate patient flow. This behavioral shift concentrates volume among high-experience prescribers and marginalizes community hospital infusion capabilities.
Gaucher and Pompe Diseases Enzyme Replacement Therapy (ERT) Market Segmentation
Enzyme replacement therapy segmentation reflects divergent clinical trajectories across Gaucher and Pompe phenotypes. Product type stratification separates legacy mammalian-cell formulations from emerging plant-cell platforms, while delivery mode innovation is redistributing site-of-care economics.
Product Type:
Mature mammalian-cell products anchor current revenue, while plant-cell expression systems are emerging as cost-competitive alternatives with distinct immunogenicity profiles.
- Imiglucerase:Recombinant glucocerebrosidase produced in Chinese hamster ovary cells remains the reference standard for Gaucher Disease Type 1. Demand concentrates in the United States and Germany where long-term safety databases support payer confidence.
- Velaglucerase Alfa:Gene-activated human fibroblast-derived enzyme offers an immunogenicity profile with reduced neutralizing antibody formation versus earlier alternatives. Pediatric hematology-oncology units in academic medical centers are driving adoption for treatment-naïve patients.
- Taliglucerase Alfa:Plant-cell manufactured glucocerebrosidase from Protalix Biotherapeutics' carrot-cell platform reduces production costs and cold-chain burden.
- Alglucosidase Alfa:Recombinant acid alpha-glucosidase for Pompe disease manufactured at large-scale bioreactor facilities.
- Alglucerase:Placental-derived enzyme largely supplanted by recombinant alternatives but retains historical registry significance.
Imiglucerase handles the majority of throughput; Taliglucerase Alfa is the fastest mover on share.
Therapy Area:
Clinical heterogeneity across Gaucher and Pompe phenotypes creates divergent pricing power and treatment duration economics.
- Gaucher Disease Type 1:Non-neuronopathic variant with longest treatment duration and largest addressable population. Sustained enzyme replacement prevents skeletal complications and hypersplenism.
- Pompe Disease Infantile:Catastrophic cardiac and skeletal muscle glycogen accumulation without intervention commands premium pricing and urgent treatment initiation upon newborn screening detection.
- Pompe Disease Late-Onset:Progressive respiratory and proximal muscle weakness in adults requires chronic ventilation support correlation with enzyme dosing.
- Gaucher Disease Type 2:Acute neuronopathic variant with limited ERT efficacy due to blood-brain barrier penetration constraints.
Gaucher Disease Type 1 generates the dominant prescription volume; Pompe Disease Infantile commands the steepest expansion trajectory.
Delivery Mode:
Route of administration stratification is compressing treatment burden and redistributing prescriber influence from hospital suites toward community settings.
- Intravenous:Biweekly infusion over several hours remains standard for current enzyme formulations requiring high-volume distribution.
- Subcutaneous:Next-generation enzyme engineering enables rapid administration without vascular access, accelerating home health adoption.
- Intramuscular:Limited applicability for enzyme replacement given tissue distribution requirements and immunogenicity concerns.
- Oral:Not applicable for enzyme replacement; substrate reduction therapy substitutes in select Gaucher populations.
- Inhalation:Investigational route for respiratory-targeted enzyme delivery in Pompe disease with pulmonary involvement.
Intravenous delivery handles the majority of throughput; subcutaneous platforms are expanding most quickly.
End User:
Site-of-care consolidation is concentrating volume among high-experience providers with established rare disease infrastructure.
- Rare Disease Centers:Academic medical centers with multidisciplinary lysosomal storage disease programs capture complex case referrals and clinical trial enrollment.
- Specialty Clinics:Hospital-affiliated infusion centers with dedicated nursing staff for immunogenicity monitoring and reaction management.
- Home Care Providers:Nursing services for subcutaneous administration are expanding as patient eligibility broadens.
- Research Institutes:Early-phase clinical trial sites for next-generation enzyme and gene therapy candidates.
Rare Disease Centers handle the majority of throughput; Home Care Providers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pediatric hematology-oncology units in academic medical centers concentrate purchasing power across major markets. Commercial payer coverage for biweekly IV infusions and newborn screening penetration for Pompe disease shape demand geography.
United States
FDA's Breakthrough Therapy designation and Rare Pediatric Disease Priority Review Voucher programs compress development timelines for novel enzyme formulations. State-level newborn screening programs for Pompe disease identify presymptomatic infants before irreversible cardiac damage. Boston and San Francisco biotech clusters host clinical trial infrastructure for next-generation ERT candidates.
Germany
G-BA applies strict quality-adjusted life year limits to ultra-rare disease therapies, constraining ERT pricing flexibility. The country's orphan drug framework supports reimbursement for enzyme replacement in Gaucher Disease Type 1. Heidelberg and Munich rare disease centers capture complex case referrals from across Central Europe.
France
HAS incremental cost-effectiveness thresholds pressure pricing for therapies addressing ultra-small prevalence populations. The national newborn screening program expands detection of infantile-onset Pompe disease. Paris academic medical centers maintain deep clinical experience with alglucosidase alfa across both infantile and late-onset indications.
Japan
PMDA's orphan drug designation accelerates regulatory review for enzyme replacement therapies targeting lysosomal storage diseases. The country's aging population drives late-onset Pompe disease diagnosis rates. Tokyo and Osaka rare disease centers concentrate prescriber expertise and patient registry participation.
United Kingdom
NICE technology appraisals apply cost-effectiveness criteria that limit NHS funding for high-cost biologics in ultra-rare conditions. The UK screens for Pompe disease through the newborn blood spot program. London teaching hospitals anchor multidisciplinary lysosomal storage disease programs with established ERT infusion protocols.
Gaucher and Pompe Diseases Enzyme Replacement Therapy (ERT) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across the enzyme replacement therapy landscape. Manufacturing scale concentrates among three European and North American production facilities. Strategic archetypes include diversified biopharmaceutical conglomerates, rare disease pure-plays, and plant-cell manufacturing innovators. Dominant competitive moves encompass gene therapy pipeline convergence and home infusion channel expansion.
Within the rare disease pure-play tier, Amicus Therapeutics and Ultragenyx Pharmaceutical Inc. exemplify development-stage positioning adjacent to ERT markets. Sanofi and Takeda Pharmaceutical Company Limited anchor the diversified biopharmaceutical conglomerate archetype through established recombinant enzyme production infrastructure. Protalix Biotherapeutics Inc. occupies a distinct position as the plant-cell manufacturing specialist with tobacco-cell platform economics.
| Leading Market Players |
|---|
| Amicus Therapeutics |
| Ultragenyx Pharmaceutical Inc. |
| Sanofi |
| AbbVie Inc. |
| Pfizer Inc. |
| Takeda Pharmaceutical Company Limited |
| Alexion Pharmaceuticals |
| Protalix Biotherapeutics Inc. |
| BioMarin Pharmaceutical |
| Others |
Supply & Pricing Matrix
Belgium's recombinant enzyme manufacturing cluster in the Brussels-Capital region anchors global supply capacity for Gaucher and Pompe therapies, with facility utilization rates directly transmitting to downstream pricing power for biweekly IV infusion contracts. Cold-chain logistics costs from this hub to United States rare disease centers represent a significant pass-through component in payer negotiations.
Pricing Analysis
Cost-plus contracts with producer price indexation dominate enzyme replacement therapy procurement between manufacturers and specialty pharmacy networks. Three-tier pricing structure across premium mammalian-cell formulations, standard plant-cell alternatives, and economy-tier biosimilar-ready products segments the market by immunogenicity profile and manufacturing platform. Cost compression in the standard tier is intensifying because Germany's G-BA applies strict quality-adjusted life year ceilings to ultra-rare disease therapies. Pediatric hematology-oncology units exhibit the lowest price sensitivity due to urgent clinical need, while adult late-onset Pompe patients in home care settings demonstrate higher elasticity.
Supply Chain Analysis
Tariff exposure between Belgium and the United States dominates supply chain risk planning for citrate-buffered enzyme formulations. Manufacturing concentrates in Belgium, Ireland, and Massachusetts, with each site drawing from Chinese hamster ovary cell banks or Protalix carrot-cell platforms as foundational inputs. Single-source vulnerability persists for acid alpha-glucosidase production given Takeda's concentration of large-scale bioreactor capacity. Distribution runs through controlled-temperature specialty pharmacy networks with validated cold-chain monitoring from manufacturing through patient administration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subcutaneous enzyme delivery platforms are triggering a platform-economics inflection in lysosomal storage disease management, with interoperability between home health nursing services and specialty pharmacy networks redefining site-of-care capture.
For Market Incumbents: Harden manufacturing scale advantages through backward integration into plasmid vector production for gene therapy pipeline convergence. Secure capacity expansion in the United States to offset European regulatory concentration risk. Immunogenicity monitoring infrastructure represents a defensible moat against oral substrate reduction therapy substitution in Gaucher Disease Type 1. For New Entrants and Emerging Players: Establish a beachhead in home infusion channel partnerships before hospital outpatient departments consolidate further. Target presymptomatic Pompe patients identified through state-level newborn screening programs as the most penetrable population segment. A go-to-market angle anchored in plant-cell manufacturing economics offers payer differentiation against legacy mammalian-cell incumbents. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors rare disease pure-plays with gene therapy adjacent capabilities over diversified biopharmaceutical conglomerates. Long-term viability across the analysis window hinges on successful pipeline transition from chronic ERT administration to single-dose disease modification. The signal to watch is FDA Breakthrough Therapy designation velocity for AAV vector candidates targeting infantile-onset indications.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Reduces infusion burden and shifts site-of-care economics toward specialty pharmacy networks. |
| Gene Therapy Pipeline Convergence | Leverages existing clinical infrastructure for transition from chronic ERT to single-dose modification. |
| Newborn Screening Partnership Expansion | Captures presymptomatic Pompe patients before irreversible cardiac damage limits treatment efficacy. |
| Plant-Cell Manufacturing Scale-Up | Reduces production costs and cold-chain burden versus mammalian-cell alternatives. |
| Patient Registry Integration | Meets EMA post-authorization evidence requirements and supports long-term immunogenicity surveillance. |
Research Methodology
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and refined through secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient pool estimates by phenotype and top-down revenue triangulation across manufacturer disclosures were reconciled to produce segmentation outputs.
Demand-supply-balance framing anchored the analytical framework across the modeling period, with patient diagnosis rates by newborn screening penetration and treatment initiation assumptions by therapy area serving as core demand drivers. Segmentation dimensions modeled encompassed product type, therapy area, delivery mode, and end user. CAGRs were derived from slope analysis of historical revenue trajectories and forward projection of enrollment curves.
Stress conditions across regulatory approval timelines, reimbursement negotiation outcomes, and gene therapy clinical trial results were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about screening expansion and competitive entry. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Fatty Liver Treatment Market
Specialty Medicine
Hyperuricemia Market
Specialty Medicine
Nocturnal Polyuria Treatment Market
Specialty Medicine
Epistaxis Market
Specialty Medicine
Castrate Resistant Prostate Cancer Therapeutics Market
Specialty Medicine
Chronic Lymphocytic Leukemia Market
Specialty Medicine
Angioimmunoblastic T-Cell Lymphoma (AILT) Market
Specialty Medicine
Alport Syndrome Treatment Market
Specialty Medicine
Immunoglobulin (Igg) Replacement Therapy Market
Specialty Medicine
Open Angle Glaucoma Market
Specialty Medicine
Global Fuchs Endothelial Corneal Dystrophy (FECD) Market
Specialty Medicine
Congenital Neutropenia Treatment Market
Specialty Medicine
Global Polycystic Ovarian Syndrome Treatment Market
Specialty Medicine
Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Botulism Treatment Market
Specialty Medicine
Endometriosis Market