
 Endometriosis Market | 2026-2036
Endometriosis Market Size, Share, and Industry Trends Forecast 2026-2036
Endometriosis Market Intelligence
Project finance for late-stage clinical trials is fragmenting competitive access in endometriosis therapeutics, allowing mid-cap developers to retain program control without dilutive equity rounds. AbbVie leverages its established gynecology franchise to sustain commercial infrastructure across major markets. Bayer AG anchors its position through in-house production of hormonal platforms. Pfizer competes via broad primary-care reach that extends into women's health prescribing networks.
Endometriosis constitutes a chronic inflammatory disorder characterized by ectopic endometrial tissue growth outside the uterine cavity, triggering cyclical bleeding, fibrosis, and pelvic adhesions; its primary clinical purpose centers on restoring quality of life and preserving fertility through pharmacological suppression or surgical excision. Hormonal therapies dominate current prescription volume as first-line maintenance protocols, while surgical instruments command premium margin pools in recurrent or refractory cases. Diagnostic procedures represent the fastest-growing therapy area segment, propelled by non-invasive biomarker development and imaging protocol refinements that shorten time-to-diagnosis.
The FDA's orphan drug designation and EMA's priority medicines scheme jointly accelerate novel endometriosis therapy development timelines, compressing regulatory review periods for mechanisms addressing unmet pain management needs. ISO 14155 clinical investigation standards and WHO prequalification pathways further shape trial conduct and eventual market access across jurisdictions. Stakeholders must monitor evolving payer evidence requirements for non-opioid pain endpoints as reimbursement authorities recalibrate value thresholds for chronic gynecological conditions.
Market Dynamics
Non-invasive diagnostic biomarker development is compressing time-to-diagnosis from years to months, fundamentally restructuring patient flow through specialty gynecology clinics and redirecting pharmaceutical prescribing patterns toward earlier-stage intervention.
Growth Catalysts
- FDA Orphan Drug Designation:The pathway accelerates novel therapeutic review timelines for mechanisms targeting unmet pain management needs, incentivizing mid-cap developers to retain program control.
- Specialty Clinic Expansion:Dedicated endometriosis centers in the United States concentrate diagnostic expertise and pharmaceutical adoption, creating concentrated demand pools for hormonal maintenance protocols.
- Non-Invasive Biomarker Validation:Blood-based and imaging refinements are shortening diagnostic delays, expanding addressable patient populations previously lost to misdiagnosis cycles.
Market Restraints
- Hormonal Therapy Side-Effect Burden:Bone density loss and mood disturbance profiles limit long-term adherence, constraining maintenance protocol effectiveness and driving surgical recurrence.
- Diagnostic Cost Concentration:Advanced MRI and laparoscopic confirmation requirements concentrate spending in tertiary medical centers, excluding rural and underinsured patient segments from timely access.
- Opioid Prescribing Restrictions:DEA scheduling and state-level monitoring programs have eliminated prior pain management pathways, forcing rapid non-opioid therapeutic substitution without mature alternatives.
Strategic Opportunities
- Fertility Preservation Protocols:Surgical excision techniques that prioritize ovarian reserve are creating premium service tiers within academic medical centers, commanding out-of-pocket payment from delayed-childbearing demographics.
- EMA Priority Medicines Scheme:Accelerated assessment pathways for novel mechanisms are compressing European market entry timelines, rewarding first-mover developers with orphan exclusivity extensions.
- Telemedicine Triage Networks:Virtual first-contact platforms are capturing preliminary symptom assessment, redirecting confirmed cases to specialized centers while reducing primary care misdiagnosis rates.
Industry Challenges
- Gynecologic Surgeon Training Pipeline:Declining fellowship enrollment in advanced laparoscopy is constraining excision capacity, extending wait times for definitive surgical intervention at major referral centers.
- Biomarker Reimbursement Coding:Novel blood-based diagnostics lack established CPT classifications, forcing cash-pay adoption and limiting penetration among commercially insured populations.
- Patient Registry Interoperability:Fragmented electronic health record systems prevent longitudinal outcome tracking, complicating real-world evidence generation for payer negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endometriosis Market |
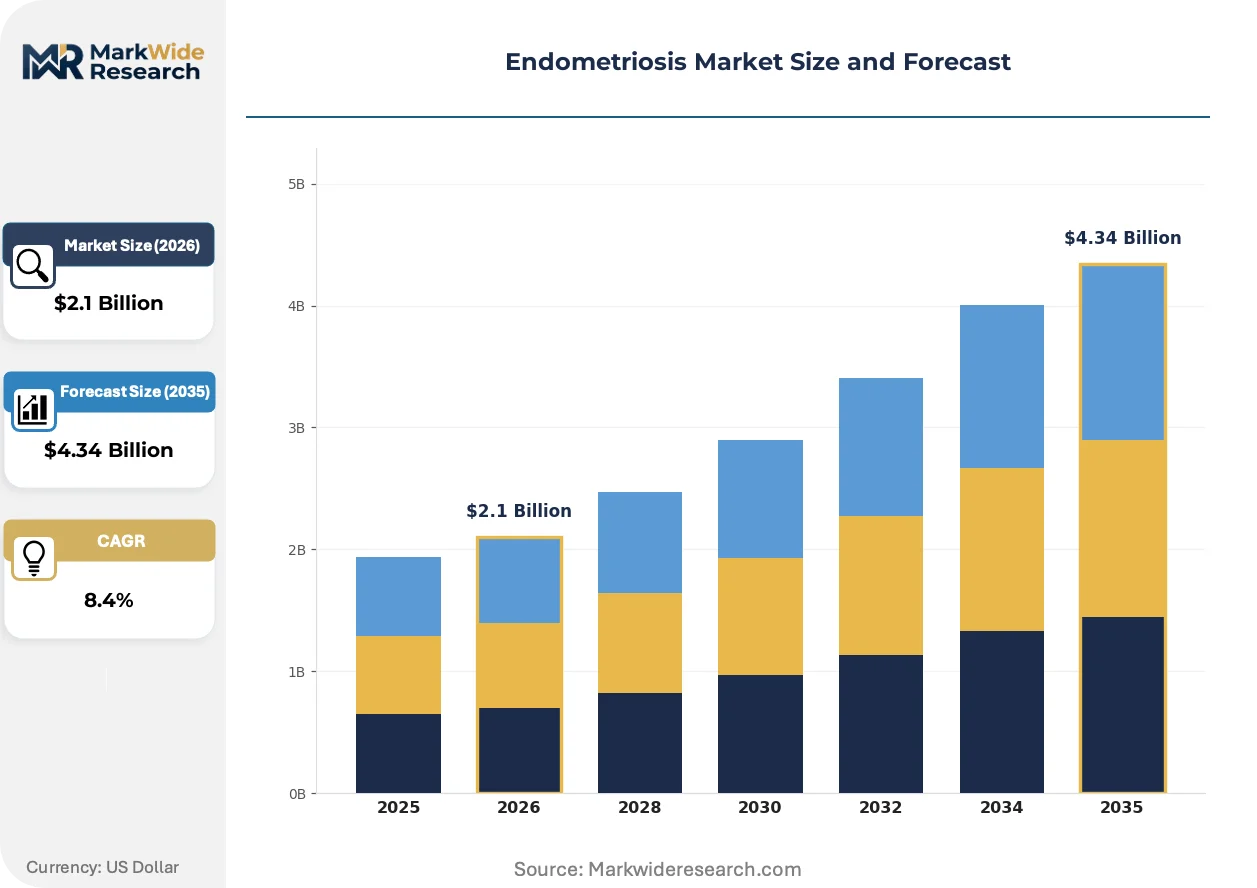
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Drugs, Over-the-Counter Medications, Hormonal Therapies, Surgical Instruments Therapy Area: Pain Management, Fertility Preservation, Surgical Intervention, Diagnostic Procedures End User: Hospitals, Specialty Clinics, Home Care, Research Institutes Delivery Mode: Injectables, Oral Tablets, Topical Applications, Surgical Procedures |
| Companies Covered | AbbVie, Bayer AG, Pfizer, AstraZeneca, Gedeon Richter, Teva Pharmaceutical Industries, Kissei Pharmaceutical, Astellas Pharma, Zydus Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endometriosis Market Strategic Shifts & Innovations
Artificial intelligence applications are penetrating diagnostic imaging and patient stratification, while regulatory frameworks on both sides of the Atlantic accelerate novel mechanism review. These forces are compressing development timelines and redistributing competitive advantage toward data-rich developers.
Machine learning algorithms trained on transvaginal ultrasound datasets are digitizing endometrioma detection and deep-infiltrating lesion classification, reducing radiologist interpretation variability. Academic medical centers in Germany and the United States are deploying these tools for pre-surgical mapping, compressing diagnostic workup duration and improving surgical planning precision.
EMA's priority medicines scheme and FDA's breakthrough therapy designation are jointly compressing regulatory review periods for non-hormonal pain mechanisms, creating parallel track opportunities for developers with robust Phase II biomarker data. European reimbursement authorities are responding with early access frameworks, while US commercial payers are pre-negotiating outcomes-based contracts for anticipated launches.
Direct-to-patient education platforms are shortening the diagnostic odyssey by bypassing primary care gatekeepers, with concentrated adoption among commercially insured women aged 25-35 in metropolitan US markets. These channels are displacing traditional physician-referral pathways, forcing specialty clinics to invest in digital patient acquisition infrastructure and redesign intake workflows around self-referred cases.
Endometriosis Market Segmentation
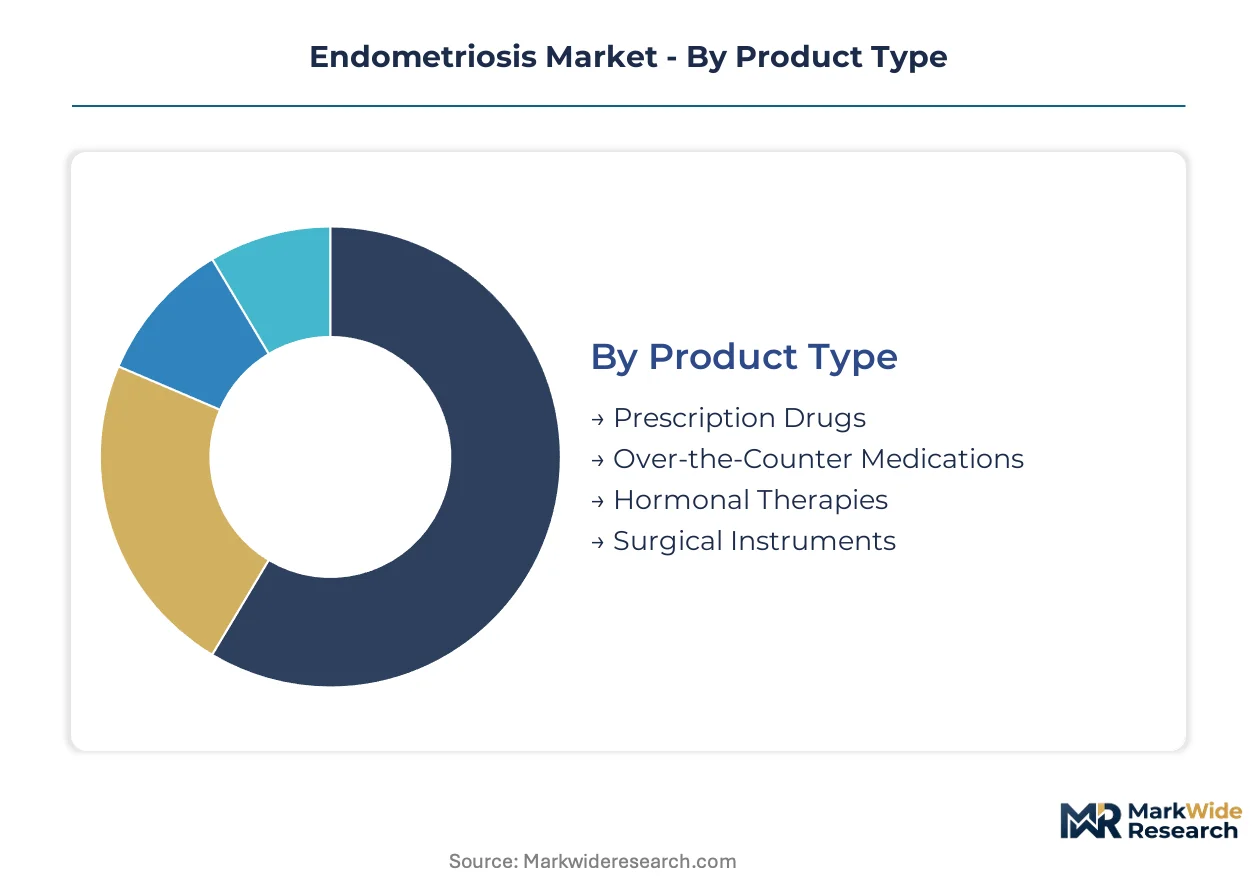
Endometriosis therapeutics fragment across hormonal suppression, surgical excision, and diagnostic modalities. Each segment carries distinct margin profiles and reimbursement pathways that shape developer investment priorities.
Product Type:
Cost tier stratification separates chronic maintenance therapies from acute surgical interventions and self-managed symptom relief.
- Hormonal Therapies:GnRH agonists, progestins, and combined oral contraceptives suppress estrogen-driven lesion proliferation. Demand concentrates in United States specialty clinics where prior authorization requirements favor established formularies over novel mechanisms.
- Surgical Instruments:Advanced laparoscopic excision tools and robotic platforms command premium pricing in tertiary medical centers. German academic hospitals and US academic medical centers drive adoption of precision energy devices that preserve ovarian reserve.
- Prescription Drugs:Non-hormonal analgesics and emerging small-molecule therapies target pain endpoints.
- Over-the-Counter Medications:NSAIDs and adjunctive supplements address breakthrough symptoms between clinical visits.
Hormonal Therapies holds installed capacity. Surgical Instruments is rotating up the share rankings.
Therapy Area:
Application focus distinguishes symptomatic management from definitive intervention and reproductive planning objectives.
- Diagnostic Procedures:Transvaginal ultrasound refinements and blood-based biomarker panels compress time-to-diagnosis from years to months. United States metropolitan markets show concentrated adoption of AI-augmented imaging that reduces radiologist interpretation variability.
- Pain Management:Non-opioid pharmacological protocols and neuromodulation techniques address chronic pelvic pain. DEA scheduling restrictions have eliminated prior opioid pathways, forcing rapid substitution toward EMA-prioritized novel mechanisms.
- Fertility Preservation:Ovarian reserve-sparing excision techniques serve delayed-childbearing demographics.
- Surgical Intervention:Definitive excision addresses deep-infiltrating disease and adhesiolysis needs.
Diagnostic Procedures holds installed capacity. Pain Management is rotating up the share rankings.
End User:
Customer type determines reimbursement complexity and patient volume throughput for therapeutic delivery.
- Specialty Clinics:Dedicated endometriosis centers concentrate diagnostic expertise and pharmaceutical prescribing authority. United States urban markets host the densest networks, with Medicare Advantage contracts increasingly requiring center-of-excellence designation.
- Hospitals:Tertiary academic medical centers handle complex excision cases and fertility-sparing surgeries. German university hospitals and US academic medical centers maintain the deepest laparoscopic fellowship pipelines.
- Home Care:Self-administered hormonal injections and telemedicine monitoring extend chronic management.
- Research Institutes:Longitudinal registries and biomarker validation studies generate real-world evidence.
Specialty Clinics holds installed capacity. Hospitals is rotating up the share rankings.
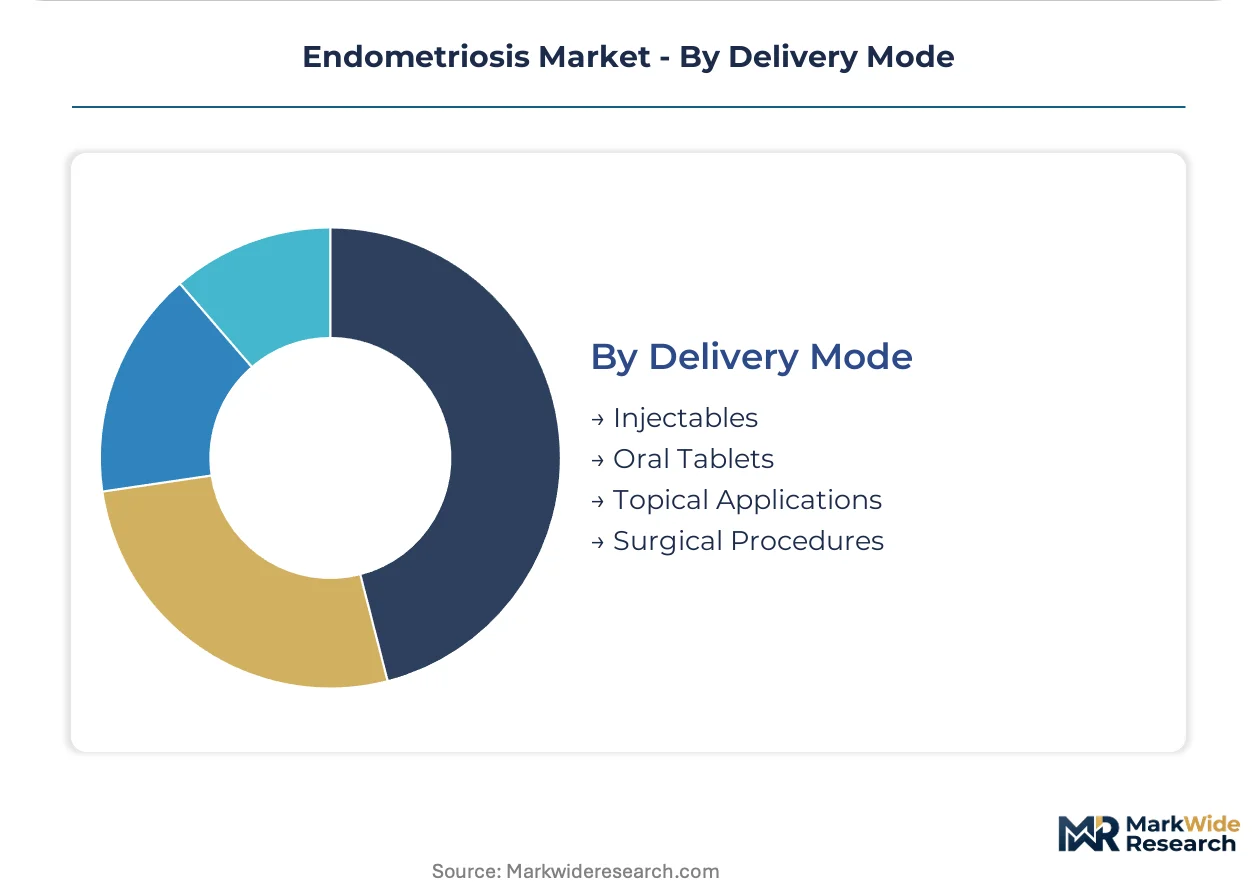
Delivery Mode:
Volume concentration varies by administration complexity and patient adherence requirements.
- Injectables:Depot formulations of GnRH analogs and long-acting progestins improve adherence over daily oral regimens. United States commercial payers favor 3-month depot injections for maintenance protocol compliance.
- Surgical Procedures:Laparoscopic and robotic-assisted excision delivers definitive intervention for refractory cases. German surgical volume concentrates in certified endometriosis centers meeting EMA quality benchmarks.
- Oral Tablets:Daily hormonal and analgesic regimens dominate first-line maintenance.
- Topical Applications:Transdermal estrogen-progestin combinations and localized pain therapies serve adherence-challenged patients.
Injectables holds installed capacity. Surgical Procedures is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA orphan drug designation and EMA priority medicines schemes are redirecting pharmaceutical investment toward concentrated clinical trial networks in the United States, Germany, and Japan. Reimbursement infrastructure maturity varies sharply across these markets, fragmenting patient access timelines.
United States
Commercial payers in metropolitan markets pre-negotiate outcomes-based contracts for novel non-hormonal therapies. FDA breakthrough therapy designation compresses review timelines for mechanisms addressing unmet pain endpoints. Specialty clinic density concentrates in Boston, New York, and San Francisco, where Medicare Advantage contracts increasingly require center-of-excellence designation.
Germany
EMA accelerated assessment pathways reward first-mover developers with orphan exclusivity extensions. Statutory health insurance funds negotiate reference pricing for hormonal maintenance protocols. Academic medical centers in Munich and Heidelberg deploy AI-augmented transvaginal ultrasound for pre-surgical mapping of deep-infiltrating lesions.
Japan
PMDA sakigake designation fast-tracks novel endometriosis therapies with robust Phase II biomarker data. Aging demographics expand the delayed-childbearing population seeking fertility-preserving excision techniques. Tokyo and Osaka maintain the deepest laparoscopic fellowship pipelines in the Asia-Pacific region.
United Kingdom
NICE technology appraisals recalibrate value thresholds for chronic gynecological conditions based on quality-adjusted life year metrics. NHS England specialist commissioning concentrates excision capacity in London and Manchester tertiary centers. Blood-based diagnostic biomarker panels face delayed adoption pending NICE diagnostic guidance.
Canada
Health Canada priority review pathways align with FDA orphan drug timelines for overlapping development programs. Provincial formularies fragment reimbursement for hormonal depot injections across Ontario, Quebec, and British Columbia. Toronto academic hospitals lead North American validation of machine learning algorithms for endometrioma detection.
Endometriosis Market Key Industry Players
Channel-controlling players compete with product-specialist players across hormonal maintenance, surgical intervention, and diagnostic modality segments. Market structure tilts toward consolidated pharmaceutical developers with established gynecology franchises, while surgical instrument supply fragments across device manufacturers. Three archetypes dominate: integrated pharma majors with women's health divisions, mid-cap biotechs retaining program control through non-dilutive financing, and precision surgical device specialists. Competitive moves concentrate on M&A for biomarker platforms and strategic partnerships for telemedicine triage networks.
Among integrated pharmaceutical developers, AbbVie, Bayer AG, and Pfizer occupy positions that exemplify contrasting channel strategies. AbbVie anchors the specialty clinic vector through its established gynecology franchise. Bayer AG represents the in-house manufacturing archetype with captive hormonal platform production. Pfizer sits within the primary-care extension model, leveraging broad prescribing networks into women's health.
| Leading Market Players |
|---|
| AbbVie |
| Bayer AG |
| Pfizer |
| AstraZeneca |
| Gedeon Richter |
| Teva Pharmaceutical Industries |
| Kissei Pharmaceutical |
| Astellas Pharma |
| Zydus Healthcare |
| Others |
Cost & Logistics Intelligence
Undercapacity in advanced laparoscopic excision capacity across United States academic medical centers is tightening surgical procedure pricing while simultaneously forcing pharmaceutical developers to absorb higher patient acquisition costs through specialty clinic partnerships. This utilization squeeze concentrates pricing power with certified endometriosis centers meeting ISO 14155 clinical investigation standards, compressing margins for mid-cap developers competing on non-hormonal mechanisms.
Pricing Analysis
Certification level (FDA-breakthrough versus standard-of-care) creates the primary spread between premium non-hormonal therapies and commoditized hormonal maintenance protocols. Three-tier pricing structure across premium, standard, and economy levels separates orphan-designated novel mechanisms from established GnRH agonists and generic progestins. Pricing pressure stems from Medicare Advantage center-of-excellence requirements concentrating volume in designated networks. Commercially insured patients in metropolitan markets show lowest price sensitivity for fertility-preserving surgical tiers, while rural segments facing diagnostic cost concentration exhibit highest sensitivity to out-of-pocket biomarker panel expenses.
Supply Chain Analysis
Export-control restrictions on AI-augmented diagnostic algorithms and precision energy surgical devices limit technology transfer from German and United States academic centers to developing markets. Active pharmaceutical ingredient production for hormonal platforms concentrates in Germany, Switzerland, and Japan, with sterile injectable formulation capacity anchored in United States and Irish facilities. Supply chain risk centers on single-source vulnerability for long-acting progestin depot formulations following consolidation among contract manufacturing organizations. Distribution runs through specialty pharmacy networks for maintenance protocols and direct-to-hospital consignment for surgical instrument suites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent hormonal therapy developers face substitution pressure from EMA-prioritized non-opioid pain mechanisms that threaten to displace maintenance protocol prescribing authority. Defensive positioning requires preemptive moves before regulatory exclusivity erosion accelerates.
For Market Incumbents: Pre-empt biosimilar erosion by securing backward integration into long-acting injectable formulation capacity in Ireland or Switzerland. Anchor formulary position through outcomes-based contracts with Medicare Advantage plans requiring center-of-excellence designation, while accelerating FDA-breakthrough submissions for pain mechanisms before EMA orphan exclusivity extensions reward European first-movers. For New Entrants and Emerging Players: Mid-market specialty clinics in Texas, Florida, and Arizona represent the most penetrable entry point for AI-augmented diagnostic platforms lacking established CPT reimbursement codes. Telemedicine triage networks capturing self-referred patients aged 25-35 offer direct channel access bypassing primary care gatekeepers. Go-to-market execution should prioritize cash-pay biomarker adoption with subsequent payer evidence generation for coding establishment. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across surgical instrument manufacturing as robotic platform development demands escalate. Long-term viability favors developers with captive supply of precision energy devices and validated biomarker panels generating real-world evidence. Acquisition target archetype: mid-cap biotechs retaining program control through FDA orphan designation with Phase II biomarker data. Signal to watch: NICE technology appraisal decisions on blood-based diagnostics as inflection indicator for European reimbursement trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA breakthrough pathway compresses review timelines for novel pain mechanisms addressing DEA-restricted opioid substitution. |
| Specialty Clinic Network Partnership | Center-of-excellence designation locks in Medicare Advantage volume concentration and pharmaceutical prescribing authority. |
| AI Diagnostic Platform Integration | Machine learning algorithms for transvaginal ultrasound reduce radiologist variability and shorten diagnostic workup duration. |
| Biomarker Reimbursement Strategy | CPT code establishment unlocks commercial payer adoption beyond cash-pay metropolitan demographics. |
| Fertility Preservation Protocol Development | Ovarian reserve-sparing excision techniques command premium out-of-pocket payment from delayed-childbearing segments. |
Research Approach
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and refined through secondary validation across FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient flow modeling through specialty clinics triangulated with top-down pharmaceutical revenue analysis across hormonal and surgical segments.
Demand-supply balance across the analysis window incorporated therapy area segmentation by diagnostic procedure, pain management, fertility preservation, and surgical intervention alongside delivery mode stratification. CAGRs were derived from epidemiological prevalence projections, diagnosis rate improvements, and pricing elasticity assumptions for non-hormonal mechanisms. Forecast inputs included EMA priority medicines scheme approval timelines and Medicare Advantage center-of-excellence network expansion trajectories.
Macroeconomic conditions sit as an overlay; deviation in reimbursement policy shifts, interest rate environments affecting project finance for clinical trials, or regulatory review timeline extensions would shift the trajectory. Forecasts reflect documented assumptions regarding biomarker validation progress and surgical fellowship pipeline recovery. Material shifts in FDA orphan drug designation criteria or NICE diagnostic guidance timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Autism Spectrum Disorder Management Market
Specialty Medicine
Global Non-Oncology Precision Medicine Market
Specialty Medicine
Psychedelic Medicine Market
Specialty Medicine
Dural Arteriovenous Fistulas Treatment Market
Specialty Medicine
Carcinoid Syndrome Management Market
Specialty Medicine
Listeriosis Treatment Market
Specialty Medicine
Polycystic Kidney Disease Treatment Market
Specialty Medicine
Pleural Diseases Therapeutics Market
Specialty Medicine
Castrate Resistant Prostate Cancer Therapeutics Market
Specialty Medicine
Chromoblastomycosis Treatment Market
Specialty Medicine
Cryptococcosis Market
Specialty Medicine
Epileptic Seizures Treatment Market
Specialty Medicine
Generalized Anxiety Disorder (GAD) Market
Specialty Medicine
Generalized Anxiety Disorder Treatment Market
Specialty Medicine
Parathyroid Disorders Market
Specialty Medicine
Schizophrenia Treatment Market