
 Global Fuchs Endothelial Corneal Dystrophy (FECD) Market | 2026-2036
Global Fuchs Endothelial Corneal Dystrophy (FECD) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fuchs Endothelial Corneal Dystrophy (FECD) Market Foresight
Ambulatory surgery centers is recalibrating the patient access model for FECD interventions, shifting volume away from traditional hospital settings toward outpatient environments. Novartis leverages its ophthalmology franchise depth to sustain clinical trial momentum across regenerative therapies. Johnson & Johnson anchors its position through surgical device portfolios tied to Descemet's membrane endothelial keratoplasty workflows. Trefoil Therapeutics differentiates via cell therapy platforms targeting endothelial cell loss reversal rather than replacement.
Fuchs endothelial corneal dystrophy denotes a progressive, bilateral disorder of the corneal endothelium characterized by extracellular matrix deposition in Descemet's membrane, leading to stromal edema and vision impairment; its primary commercial purpose centers on restoring optical clarity through medical management or surgical intervention. Corneal transplants occupy the dominant revenue position within product type segmentation, reflecting established surgical reimbursement and graft availability through eye bank networks. Disease management applications within the application dimension are gaining fastest traction as pharmaceutical developers pursue topical rho-kinase inhibitors and cell-based therapies that delay or obviate surgical progression.
The FDA orphan drug program accelerates development timelines for novel FECD therapeutics, while the EMA's centralized marketing authorization shapes commercialization pathways across European member states and the EU Medical Device Regulation imposes clinical evidence requirements on corneal implantable devices. Japan's PMDA sakigake designation system offers priority review for regenerative medicine products targeting endothelial dysfunction. Stakeholders must monitor regulatory divergence between accelerated approval pathways and post-market evidence obligations as gene and cell therapies advance toward commercialization.
Market Dynamics
The transition from penetrating keratoplasty to endothelial keratoplasty techniques is compressing surgical recovery timelines and redirecting reimbursement flows toward outpatient facility fees rather than inpatient hospital stays.
Growth Catalysts
- EMA Centralized Marketing Authorization:The streamlined pathway accelerates commercialization across European member states, reducing regulatory fragmentation for corneal implantable devices and cell therapy platforms.
- Ambulatory Surgery Centers:These facilities capture shifting case volumes as payers favor same-day discharge protocols and reduced facility fees for Descemet's membrane endothelial keratoplasty procedures.
- Gene Therapy Platforms:CRISPR-based approaches targeting TCF4 repeat expansions are advancing through preclinical stages, offering potential disease-modifying interventions before endothelial cell loss progresses.
Market Restraints
- Corneal Tissue Availability:Eye bank networks face chronic supply constraints, with donor tissue procurement rates failing to match surgical demand growth in aging populations.
- EU Medical Device Regulation:Enhanced clinical evidence requirements for corneal implants extend approval timelines and elevate documentation burdens for manufacturers seeking CE marking.
- Technical Limitation in Cell Culture:Human corneal endothelial cells exhibit limited proliferative capacity ex vivo, constraining scale-up of autologous cell therapy manufacturing.
Strategic Opportunities
- Japan's PMDA Sakigake Designation:Priority review pathways for regenerative medicine products offer accelerated timelines for developers targeting endothelial dysfunction with cell-based interventions.
- Topical Rho-Kinase Inhibitors:Pharmaceutical formulations that delay surgical progression represent an emerging application segment with reimbursement potential in managed care settings.
- Teleophthalmology Integration:Remote monitoring platforms enable pre-surgical screening and post-operative surveillance, extending specialist reach into underserved regions.
Industry Challenges
- GMP Manufacturing Scale-Up:Cell therapy production requires specialized cleanroom infrastructure and analytical validation that strains capital deployment timelines for emerging developers.
- Surgical Training Pipeline:Descemet's membrane endothelial keratoplasty demands specialized microsurgical skills; fellowship programs produce insufficient trained surgeons to match procedural demand growth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fuchs Endothelial Corneal Dystrophy (FECD) Market |
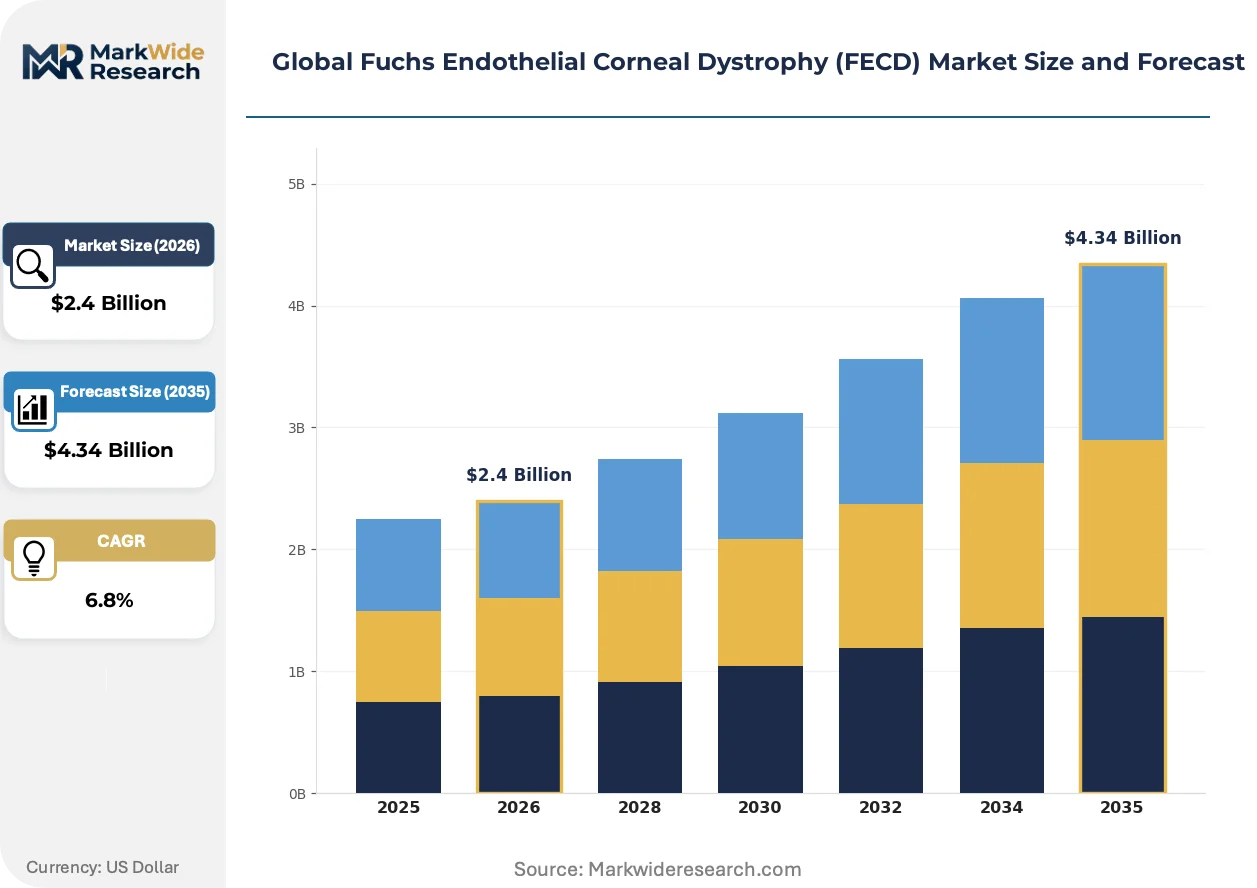
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corneal Transplants, Artificial Corneas, Medication, Diagnostic Tools End User: Hospitals, Clinics, Ambulatory Surgery Centers, Eye Banks Delivery Mode: Topical, Parenteral, Intravitreal, Oral Application: Vision Restoration, Disease Management, Research, Treatment Protocols |
| Companies Covered | ActualEyes, Novartis, Kowa Pharmaceuticals, AbbVie, Johnson & Johnson, Trefoil Therapeutics, GlaxoSmithKline, AstraZeneca, Santen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fuchs Endothelial Corneal Dystrophy (FECD) Market Shifts & Advancements
Endothelial keratoplasty techniques are displacing full-thickness transplantation as the standard of care, while pharmaceutical developers pursue topical interventions that interrupt disease progression before surgical thresholds.
Femtosecond laser technology is integrating with donor tissue preparation workflows, enabling precise Descemet's membrane scoring and standardized graft dimensions. High-volume ophthalmology clinics in Germany and Japan are adopting these platforms to reduce operative variability and compress tissue manipulation time. The technology is integrating surgical training protocols, flattening learning curves for fellowship-trained corneal specialists transitioning from manual techniques.
The FDA's orphan drug designation pathway is compressing development timelines for novel FECD therapeutics by offering tax incentives and waived user fees. Gene therapy sponsors targeting TCF4-associated endothelial degeneration are leveraging this framework to advance toward first-in-human studies. Developers are responding by structuring clinical programs to meet post-market evidence obligations under accelerated approval mechanisms.
Patient selection criteria are tightening as optical coherence tomography imaging enables quantitative endothelial cell density monitoring. Private practice ophthalmologists in the United States are deferring surgical referrals until visual acuity thresholds trigger insurance pre-authorization, compressing the window between diagnosis and intervention. This behavioral shift concentrates surgical volume in tertiary referral centers with dedicated corneal subspecialists.
Global Fuchs Endothelial Corneal Dystrophy (FECD) Market Segmentation
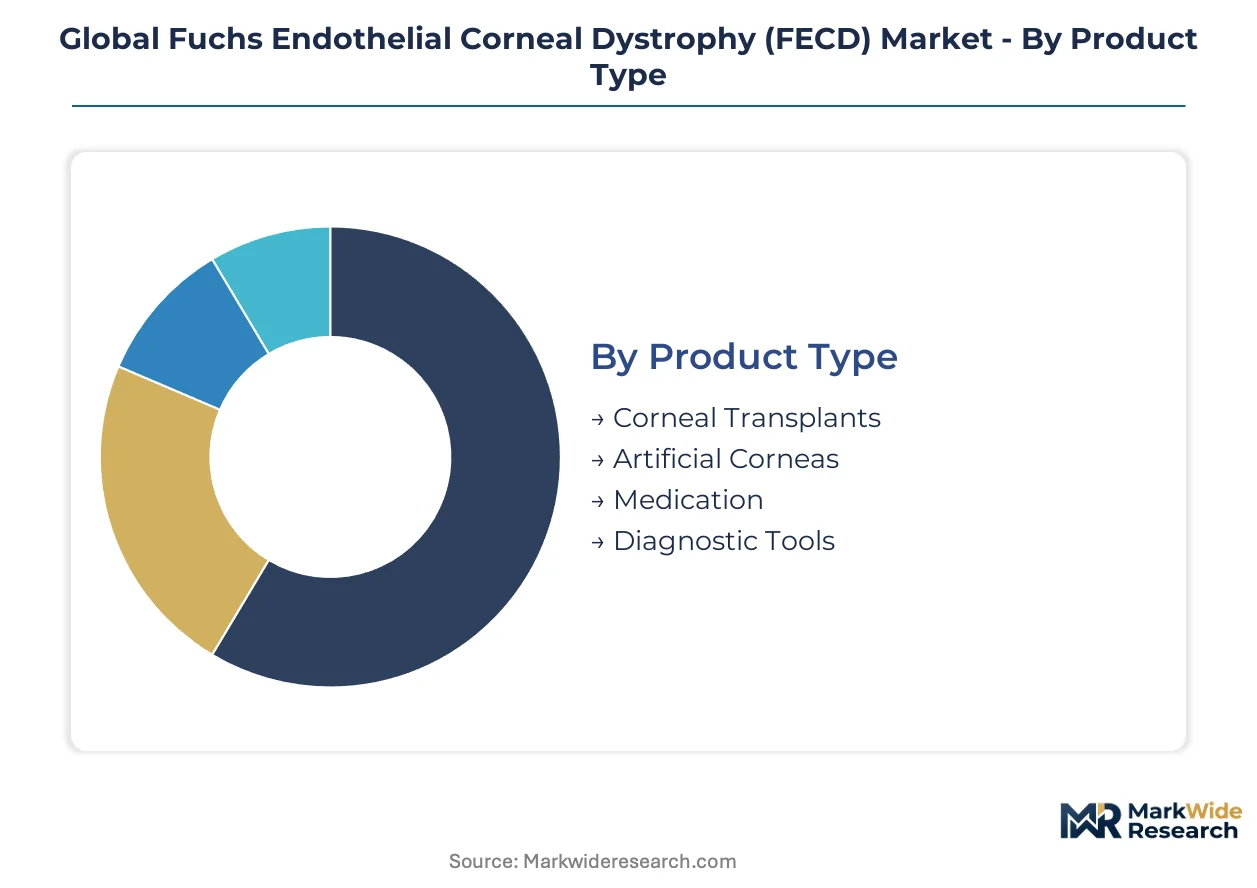
Segmentation in FECD therapeutics reveals divergent commercial logics between acute surgical intervention and chronic disease modification. Product architecture, delivery science, and care setting economics each create distinct margin profiles and regulatory pathways that reshape competitive positioning across the value chain.
Product Type:
Standardization dominates implantable categories while pharmaceutical and diagnostic segments permit greater customization to patient endothelial cell density profiles.
- Corneal Transplants:Allograft tissue from eye bank networks remains the clinical standard for advanced FECD with stromal edema. Demand concentrates in the United States and Germany where Descemet's membrane endothelial keratoplasty reimbursement codes sustain high procedural volumes despite chronic donor tissue shortages.
- Artificial Corneas:Keratoprosthesis devices address graft failure or tissue-incompatible cases through synthetic optical cylinders. Japan's PMDA has accelerated review timelines for collagen-mimetic implants, though adoption remains constrained by endothelialization failure risks and specialized postoperative management requirements.
- Medication:Topical hypertonic saline and rho-kinase inhibitors target early-stage edema control.
- Diagnostic Tools:Specular microscopy and anterior segment optical coherence tomography enable quantitative endothelial cell monitoring.
Most installed capacity flows through Corneal Transplants. Expansion is steepest in Medication as disease-modifying platforms advance through clinical pipelines.
End User:
Site-of-care economics drive divergence between capital-intensive hospital infrastructure and lean ambulatory models optimized for same-day keratoplasty discharge.
- Ambulatory Surgery Centers:Freestanding facilities capture shifting payer preferences for reduced facility fees and lower infection risk in endothelial keratoplasty workflows. United States Medicare reimbursement policies now favor ASC site-of-service differentials, redirecting volume from hospital outpatient departments in metropolitan markets with established corneal subspecialty density.
- Hospitals: Academic medical centers retain complex regraft cases and combined procedures requiring general anesthesia. Germany's university hospital networks maintain dominance for triple Descemet's stripping procedures with concurrent cataract extraction, leveraging integrated eye bank partnerships and fellowship training pipelines.
- Clinics:Private practice ophthalmology groups concentrate preoperative screening and postoperative surveillance.
- Eye Banks:Tissue procurement and distribution organizations anchor supply chain integrity.
Procedure volume concentrates in Ambulatory Surgery Centers. Investment intensity runs highest in Eye Banks facing donor recruitment scalability constraints.
Delivery Mode:
Route selection reflects the anatomical barrier properties of corneal tissue and the pharmacokinetic requirements of endothelial cell-targeted therapeutics.
- Topical:Eye drop formulations penetrate through epithelial and stromal layers to reach dysfunctional endothelium. Formulation science advances in the United States focus on enhanced corneal residence time through viscosity-modifying agents, addressing the challenge of achieving therapeutic concentrations at Descemet's membrane without systemic exposure.
- Intravitreal:Posterior segment injection enables sustained release depot formulations for combined posterior segment pathology. Japanese developers are exploring intravitreal cell therapy delivery to bypass anterior segment barriers, though regulatory pathways require demonstration of endothelial cell migration to target tissue.
- Parenteral:Systemic administration supports perioperative immunosuppression in high-risk keratoplasty.
- Oral:Enteric routes remain investigational for FECD-specific indications.
Clinical utilization clusters in Topical delivery. Development activity is accelerating fastest in Intravitreal approaches for regenerative medicine products.
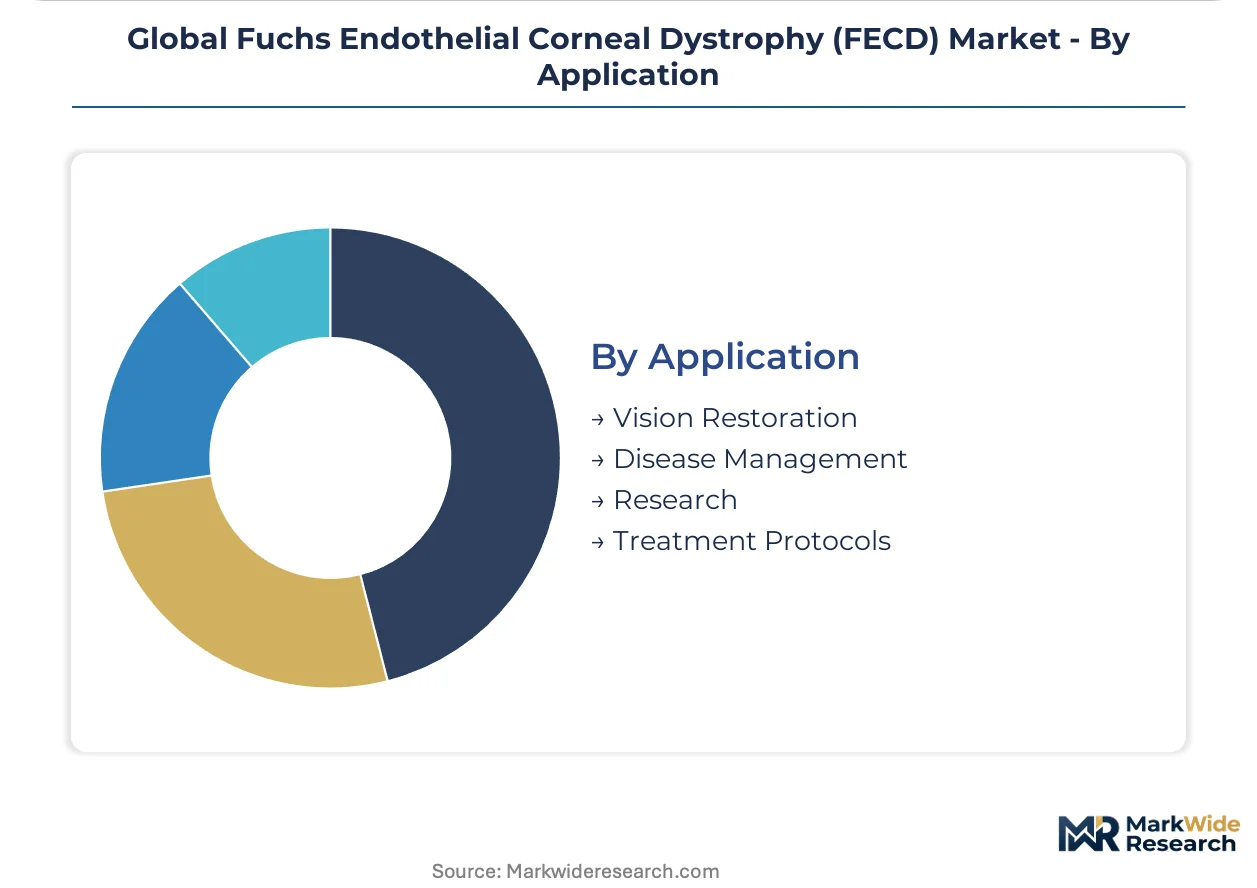
Application:
Commercial maturity separates established vision restoration procedures from emerging disease management platforms seeking to delay or obviate surgical thresholds.
- Disease Management:Pharmaceutical and cell-based interventions target TCF4-associated endothelial degeneration before irreversible cell loss. Gene therapy sponsors in the United States are structuring clinical programs around FDA orphan drug designation pathways, pursuing disease modification endpoints rather than visual acuity rescue.
- Vision Restoration:Surgical replacement of dysfunctional endothelium through keratoplasty techniques remains the revenue foundation. Germany's statutory health insurance system maintains comprehensive reimbursement for Descemet's membrane endothelial keratoplasty, supporting procedural volume growth despite workforce training bottlenecks.
- Research:Academic and industry investigations advance mechanistic understanding and therapeutic discovery.
- Treatment Protocols:Standardized care pathways optimize outcomes and resource utilization.
Revenue concentration sits with Vision Restoration. Pipeline investment is expanding most aggressively in Disease Management as developers pursue pre-surgical intervention windows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage in accelerated approval pathways is reshaping clinical trial placement, with sponsors migrating studies toward jurisdictions offering orphan drug incentives and regenerative medicine fast tracks. Cost-of-compliance gaps between the FDA's tax credit framework and EMA's centralized procedures are concentrating early-phase investment in the United States.
United States
Medicare reimbursement differentials for ambulatory surgery centers are redirecting Descemet's membrane endothelial keratoplasty volume from hospital outpatient departments. The FDA's orphan drug designation pathway compresses development timelines through waived user fees and tax incentives for gene therapy sponsors. High-volume corneal subspecialty clusters in Boston and Baltimore anchor surgical training pipelines and eye bank distribution networks.
Germany
Statutory health insurance maintains comprehensive reimbursement for endothelial keratoplasty procedures despite chronic donor tissue shortages. The EU Medical Device Regulation imposes enhanced clinical evidence requirements on corneal implantable devices seeking CE marking. University hospital networks in Heidelberg and Tübingen concentrate complex regraft cases and triple Descemet's stripping procedures with concurrent cataract extraction.
Japan
Aging demographics and established corneal surgery infrastructure align to sustain procedural demand growth in metropolitan markets. The PMDA's sakigake designation system offers priority review timelines for regenerative medicine products targeting endothelial dysfunction. Tokyo-based ophthalmology clinics are adopting femtosecond laser platforms for standardized donor tissue preparation workflows.
United Kingdom
NHS England's commissioning frameworks are tightening patient selection criteria for elective keratoplasty based on visual acuity thresholds. The MHRA's post-Brexit regulatory autonomy enables divergence from EU MDR timelines for novel corneal therapeutics. Moorfields Eye Hospital in London anchors national referral patterns for complex endothelial failure cases and fellowship training programs.
Switzerland
Swissmedic's streamlined marketing authorization procedures attract sponsors seeking parallel-track submissions alongside EMA centralized procedures. Private health insurance models sustain premium reimbursement for advanced surgical techniques and experimental cell therapies. The Basel-Zurich corridor concentrates pharmaceutical development infrastructure for ophthalmology-focused regenerative medicine platforms.
Global Fuchs Endothelial Corneal Dystrophy (FECD) Market Competitive Landscape
Strategic partnerships dominate the current landscape as developers seek access to specialized manufacturing infrastructure and surgical distribution channels. The competitive structure fragments across three tiers: multinational pharmaceutical conglomerates with ophthalmology franchises, mid-cap cell therapy specialists, and surgical device manufacturers with keratoplasty workflow portfolios. Two strategic archetypes anchor positioning: disease-modification platforms pursuing pre-surgical intervention windows, and surgical replacement technologies optimizing endothelial keratoplasty outcomes. Portfolio diversification and technology licensing represent the dominant competitive moves, with sponsors securing access to gene editing platforms and cell culture scale-up capabilities.
Within the multinational pharmaceutical tier, Novartis and Johnson & Johnson occupy positions reflecting deep ophthalmology franchise integration. Novartis leverages clinical trial infrastructure across regenerative therapy pipelines, while Johnson & Johnson anchors surgical device portfolios tied to Descemet's membrane endothelial keratoplasty workflows. Trefoil Therapeutics exemplifies the cell therapy specialist archetype, differentiating via platforms targeting endothelial cell loss reversal rather than replacement. ActualEyes represents the emerging diagnostic and therapeutic convergence segment, sitting within the precision ophthalmology tier focused on quantitative endothelial monitoring.
| Leading Market Players |
|---|
| ActualEyes |
| Novartis |
| Kowa Pharmaceuticals |
| AbbVie |
| Johnson & Johnson |
| Trefoil Therapeutics |
| GlaxoSmithKline |
| AstraZeneca |
| Santen |
| Others |
Supply & Pricing Matrix
The EU Medical Device Regulation's enhanced clinical evidence requirements for corneal implantable devices gates qualified supply for premium-tier pricing access, compressing margins for manufacturers unable to document post-market surveillance while concentrating pricing power among sponsors with established CE marking pathways.
Pricing Analysis
Distributor margins for Descemet's membrane endothelial keratoplasty devices compress at the hospital procurement tier while direct-to-ASC contracts command volume discounts. Three-tier pricing structure across premium femtosecond laser platforms, standard manual keratoplasty systems, and economy-grade tissue preparation kits reflects ISO certification tiers and after-sales service bundling. Pricing pressure stems from Medicare's site-of-service differentials favoring ambulatory settings over hospital outpatient departments. Academic medical centers exhibit lowest price sensitivity due to bundled reimbursement for complex regraft cases; private ASCs negotiate aggressively on per-procedure device costs.
Supply Chain Analysis
Japan's PMDA domestic-content preferences for regenerative medicine products are reshaping sourcing patterns for cell therapy platforms, pushing sponsors toward local manufacturing partnerships. Geographic supply concentration centers on the United States, Germany, and Japan for corneal tissue processing equipment and femtosecond laser platforms. Raw material dependencies include donor corneal tissue from eye bank networks, specialized optical components from German precision manufacturers, and cell culture media from Japanese suppliers. Single-source vulnerability runs through concentrated femtosecond laser component suppliers. Distribution runs through ophthalmology device distributors with dedicated corneal subspecialty sales forces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's orphan drug designation pathway functions as a regulatory compounder, accelerating development timelines through tax incentives and waived user fees that compound returns for gene therapy sponsors targeting TCF4-associated endothelial degeneration.
For Market Incumbents: Deploy GMP manufacturing scale-up as the priority lever to defend against cell therapy specialists capturing regenerative medicine market share. Incumbents should secure captive supply of corneal endothelial cell culture capacity through backward integration into specialized cleanroom infrastructure, while investing in FDA breakthrough device designation for next-generation femtosecond laser platforms to preempt competitive entry. For New Entrants and Emerging Players: Ambulatory surgery centers in secondary US metropolitan markets represent the most penetrable buyer archetype, with underserved procedural volume shifting from hospital outpatient departments under Medicare reimbursement differentials. New entrants should pursue white-space targets in topical rho-kinase inhibitor formulations for early-stage disease management and teleophthalmology-enabled remote monitoring platforms for pre-surgical screening, leveraging direct-to-ASC distribution partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for cell therapy platform specialists because chronic donor tissue shortages and limited human corneal endothelial cell proliferative capacity create durable scarcity value for scalable manufacturing solutions. Long-term viability centers on acquisition targets with validated GMP processes and PMDA sakigake designation progress. The signal to watch is FDA acceptance of disease-modification endpoints in Phase II gene therapy trials, indicating inflection toward reimbursable pre-surgical intervention windows.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Orphan Drug Designation Pursuit | Compresses development timelines through tax incentives and waived user fees for gene therapy sponsors. |
| CE Marking Pathway Investment | EMA centralized procedures reduce regulatory fragmentation for corneal implantable devices across European markets. |
| Ambulatory Surgery Center Partnership | Medicare site-of-service differentials redirect procedural volume toward freestanding facilities with lower infection risk. |
| Cell Culture Scale-Up Infrastructure | Specialized cleanroom capacity addresses GMP manufacturing bottlenecks constraining autologous therapy commercialization. |
| Teleophthalmology Platform Integration | Remote monitoring extends specialist reach into underserved regions for pre-surgical screening and post-operative surveillance. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with corneal surgeons, eye bank procurement directors, regulatory affairs leads at ophthalmology device manufacturers, and payer access specialists with secondary validation against FDA 510(k) filings, EMA centralized procedure documentation, ClinicalTrials.gov records, and Medicare reimbursement code updates. Bottom-up demand modeling triangulated against top-down market sizing.
Segment-weighting across product type, end user, delivery mode, and application dimensions anchored the analytical framework over the projection horizon. CAGRs derived from procedure volume trajectories, reimbursement code utilization trends, and pipeline advancement milestones. Forecast inputs incorporated endothelial keratoplasty adoption curves and gene therapy clinical trial progression timelines.
Underlying measurement precision varies by segment; corneal transplant volume data carries tighter precision than emerging cell therapy market estimates due to established eye bank reporting infrastructure. Forecasts reflect documented assumptions regarding regulatory approval timelines and reimbursement policy stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Pyoderma Gangrenosum Therapeutics Market
Specialty Medicine
Europe Precision Medicine Market
Specialty Medicine
US Mobile Physician Practice Market
Specialty Medicine
Severe Combined Immunodeficiency Market
Specialty Medicine
Grand Mal Seizure Market
Specialty Medicine
Global Tourette Syndrome Treatment Market
Specialty Medicine
Tropical Spastic Paraparesis Market
Specialty Medicine
Piriformis Syndrome Market
Specialty Medicine
Coagulation Disorders Market
Specialty Medicine
Transient Ischemic Attack Market
Specialty Medicine
Americas Gerd and Nerd Treatment Market
Specialty Medicine
Rhabdomyosarcoma Market
Specialty Medicine
Listeriosis Treatment Market
Specialty Medicine
Global Restless Legs Syndrome Market
Specialty Medicine
Granulomatosis with Polyangiitis Treatment Market
Specialty Medicine
Global Lupus Market