
 Angioimmunoblastic T-Cell Lymphoma (AILT) Market | 2026-2036
Angioimmunoblastic T-Cell Lymphoma (AILT) Market Size, Share, and Industry Trends Forecast 2026-2036
Angioimmunoblastic T-Cell Lymphoma (AILT) Market Outlook
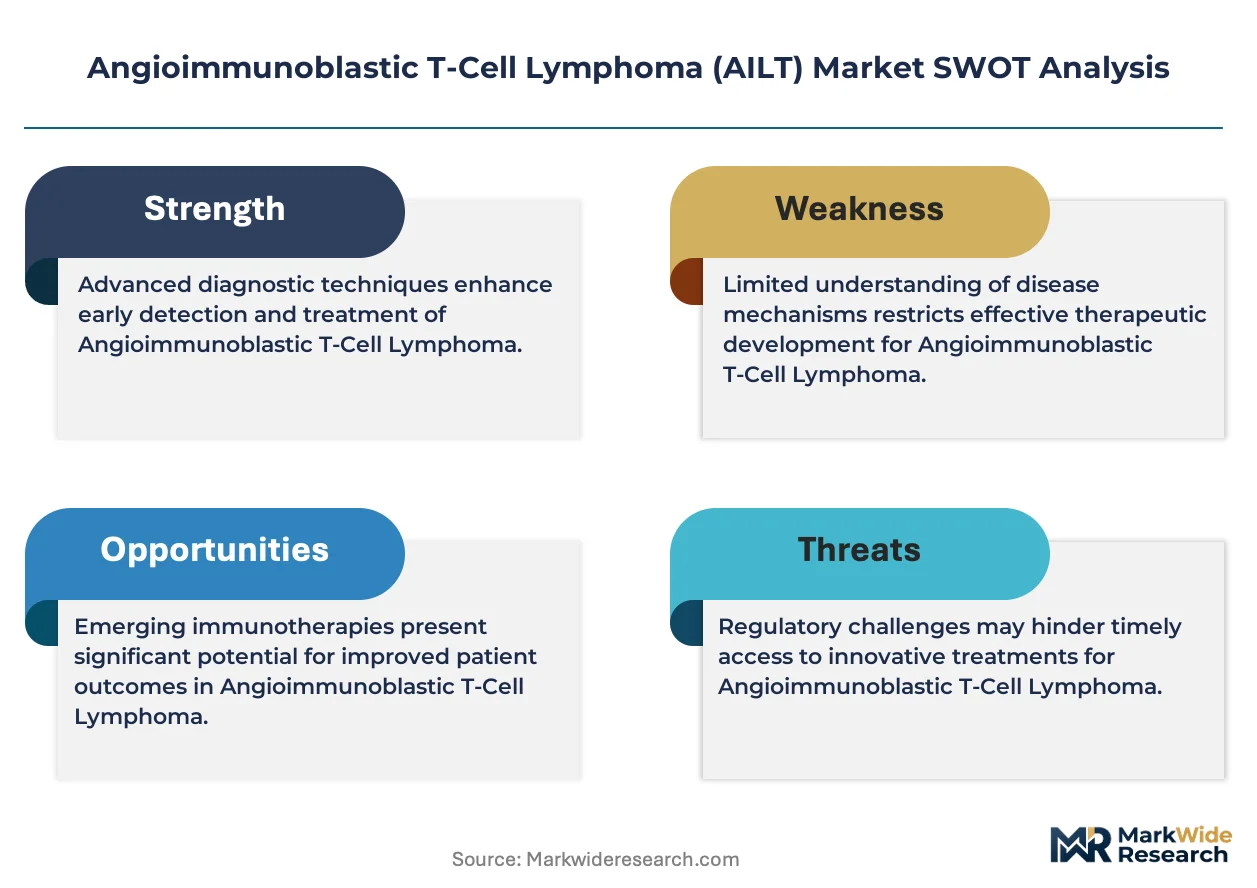
The EU Green Deal's pharmaceutical sustainability requirements is broadening scrutiny across oncology supply chains, with manufacturers facing new carbon-footprint disclosure mandates for active pharmaceutical ingredients. Bristol-Myers Squibb leverages its integrated biologics manufacturing network to sustain cost-competitive checkpoint inhibitor production. Novartis anchors its position through deep R&D investment in targeted hematology agents. Autolus Limited differentiates via specialized cell-therapy engineering capabilities for T-cell malignancies.
Angioimmunoblastic T-cell lymphoma constitutes a peripheral T-cell lymphoma subtype characterized by systemic immune dysregulation, proliferating follicular helper T cells, and Epstein-Barr virus-positive B-cell expansions, typically presenting with lymphadenopathy, hepatosplenomegaly, polyclonal hypergammaglobulinemia, and autoimmune phenomena. Its primary clinical purpose centers on guiding therapeutic intervention to control malignant T-cell proliferation while managing inflammatory complications. Immunotherapy approaches including monoclonal antibodies represent the fastest-expanding segment as investigators pursue durable responses beyond conventional chemotherapy failure. Targeted therapy categories anchored by tyrosine kinase inhibitors command concentrated margin pools due to premium pricing and specialized manufacturing requirements. Stem cell transplant maintains structural importance as curative-intent salvage despite restricted eligibility.
The FDA's accelerated approval framework for hematologic malignancies shapes trial design and commercial access timelines, while the EMA's orphan drug incentives influence European development priorities for rare lymphoma subtypes. ISO 14155 clinical investigation standards govern multinational trial conduct, directly impacting data acceptability across regulatory jurisdictions. Stakeholders must monitor evolving biomarker-driven eligibility criteria that will determine which patient subsets access novel mechanism classes versus standard-of-care protocols.
Market Dynamics
FDA's accelerated approval framework for hematologic malignancies is compressing clinical trial timelines and reshaping how novel AILT therapies reach tertiary care centers. This regulatory velocity is creating asymmetric access patterns between academic medical centers and community oncology practices.
Growth Catalysts
- Orphan drug incentives:EMA's regulatory framework for rare lymphoma subtypes reduces development costs and expedites European market entry for targeted hematology agents.
- Academic medical center expansion:Tertiary care institutions in the United States are building dedicated T-cell lymphoma programs that drive protocol development for relapsed or refractory cases.
- Checkpoint inhibitor engineering:Advances in biologics manufacturing are enabling cost-competitive production of monoclonal antibodies for systemic immune dysregulation management.
Market Restraints
- Stem cell transplant eligibility constraints:Curative-intent salvage therapy remains restricted to patients meeting stringent organ function criteria, capping addressable population.
- Carbon-footprint disclosure mandates:EU Green Deal pharmaceutical sustainability requirements impose new compliance burdens on active pharmaceutical ingredient supply chains.
- Tyrosine kinase inhibitor manufacturing concentration:Premium-priced targeted therapies depend on specialized production capabilities concentrated among limited contract manufacturers.
Strategic Opportunities
- Biomarker-driven eligibility expansion:Evolving patient stratification criteria will unlock novel mechanism classes for follicular helper T-cell proliferation subsets currently excluded from trials.
- Cell-therapy engineering specialization:Convergence of autologous cell processing and CRISPR-based editing creates white space for engineered T-cell products in relapsed disease.
- ISO 14155 harmonization:Standardized multinational trial conduct protocols reduce data acceptability friction across FDA and EMA jurisdictions, accelerating concurrent regulatory submissions.
Industry Challenges
- Multinational trial coordination complexity:Divergent national ethics review timelines and site activation requirements delay patient enrollment across European investigational sites.
- Immunotherapy manufacturing scale-up:Viral vector production bottlenecks and cell expansion capacity constraints limit supply of personalized T-cell products to qualified treatment centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Angioimmunoblastic T-Cell Lymphoma (AILT) Market |
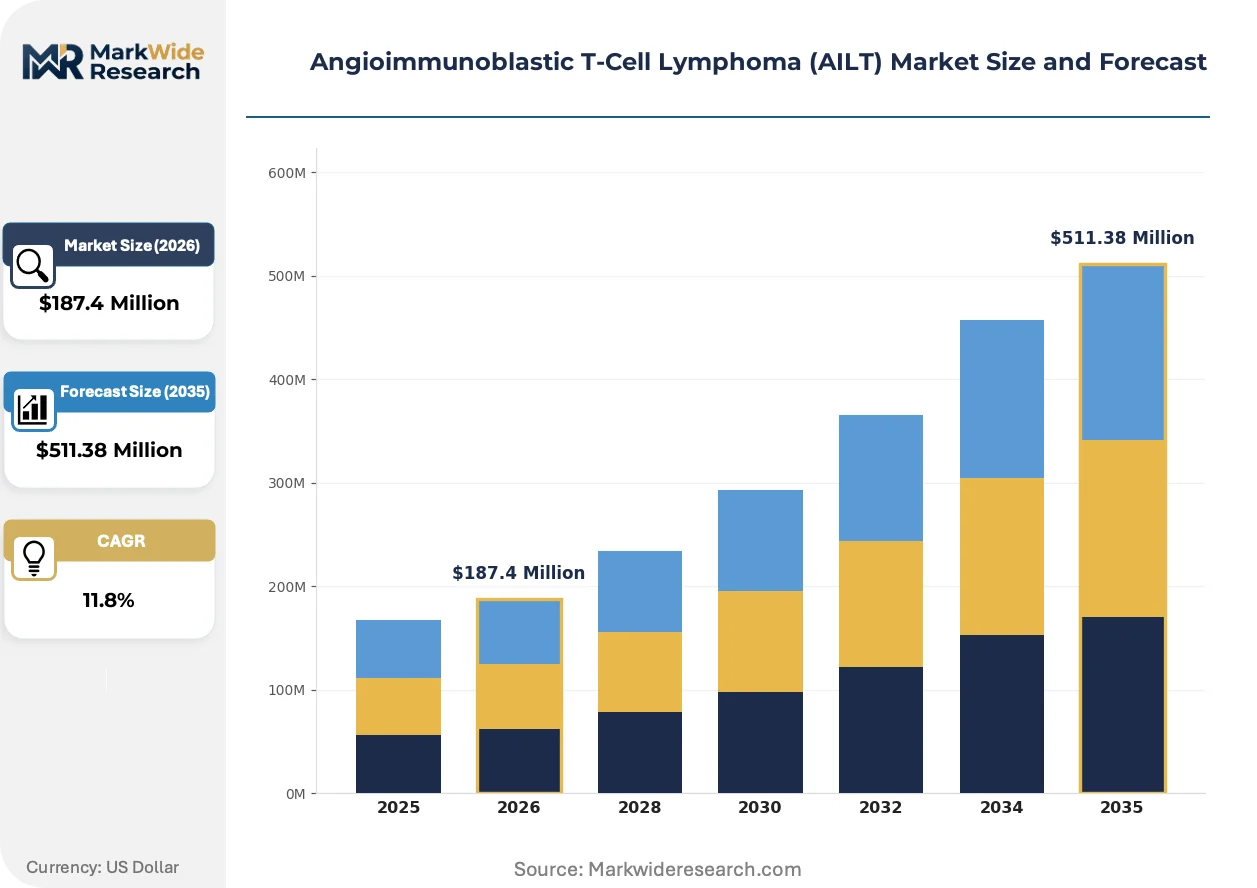
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $511.38 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Chemotherapy, Immunotherapy, Targeted Therapy, Stem Cell Transplant Drug Type: Corticosteroids, Monoclonal Antibodies, Cytotoxic Agents, Tyrosine Kinase Inhibitors End User: Hospitals, Specialty Clinics, Outpatient Centers, Home Care Treatment Strategy: Combined Modality, Maintenance Therapy, Palliative Care, Watchful Waiting |
| Companies Covered | Bristol-Myers Squibb, Millennium Pharmaceuticals, Inc., Autolus Limited, Eisai Inc., Novartis, Kura Oncology, PersonGen BioTherapeutics (Suzhou) Co., Ltd., Verastem Oncology, ADC Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Angioimmunoblastic T-Cell Lymphoma (AILT) Market Strategic Shifts
Novel combination regimens are displacing single-agent chemotherapy as first-line investigation priorities, while biomarker integration into trial design is compressing traditional response assessment timelines. These shifts are reconfiguring how therapeutic value is demonstrated to payers and regulators.
Chimeric antigen receptor T-cell therapy is overtaking conventional salvage chemotherapy as the investigational backbone for relapsed AILT. Academic medical centers in the United States are adopting these protocols at accelerating pace, compressing the window between chemotherapy failure and cellular intervention. This displacement is restructuring referral patterns toward centers with captive apheresis and cell processing capabilities.
EMA's orphan drug designation pathway is streamlining development priorities for peripheral T-cell lymphoma subtypes across European member states. The framework reduces regulatory friction for sponsors pursuing conditional marketing authorization based on single-arm efficacy data. Hematology-focused biotechnology firms are responding by anchoring European trial footprints earlier in development cycles.
Academic medical centers are consolidating investigator-initiated trial sponsorship away from community oncology networks. Centralized protocol development at tertiary care institutions is displacing distributed site participation, concentrating patient access to investigational therapies. This geographic concentration is most visible across the United States, where NCI-designated cancer centers capture disproportionate shares of novel mechanism enrollment.
Angioimmunoblastic T-Cell Lymphoma (AILT) Market Segmentation
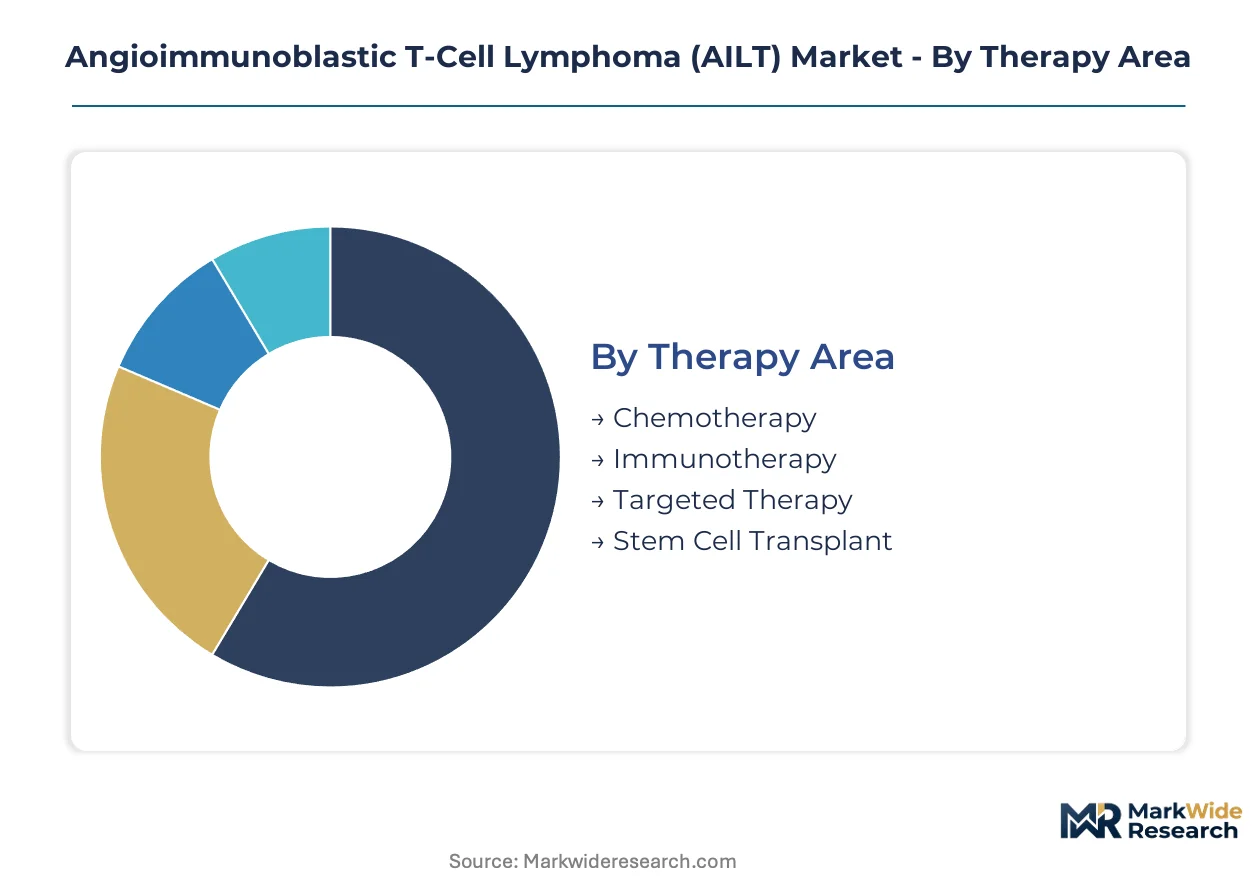
Segmentation in the AILT market reflects divergent clinical objectives across therapy modalities and care settings. Treatment decisions hinge on disease stage, prior therapy failure, and eligibility for intensive interventions. Understanding these partitions reveals where commercial investment concentrates versus where unmet need persists.
Therapy Area:
Payer reimbursement thresholds and clinical trial access patterns determine how physicians allocate patients across mechanism classes.
- Immunotherapy:Monoclonal antibodies and checkpoint inhibitors target systemic immune dysregulation characteristic of AILT pathophysiology. Academic medical centers in the United States are prioritizing these agents for relapsed cases following chemotherapy failure, driven by FDA accelerated approval pathways that compress commercialization timelines.
- Targeted Therapy:Tyrosine kinase inhibitors and other molecularly directed agents interrupt follicular helper T-cell proliferation signaling. Premium pricing reflects specialized manufacturing requirements and concentrated production capabilities among limited contract manufacturers.
- Chemotherapy:Anthracycline-based regimens remain foundational for frontline disease control despite limited durability. Community oncology practices continue administering these protocols where access to novel agents is restricted.
- Stem Cell Transplant:Autologous and allogeneic transplantation offers curative-intent salvage for eligible patients. Stringent organ function criteria cap addressable population, with eligibility assessments concentrated at tertiary care institutions.
Chemotherapy leads on scale; immunotherapy leads on momentum.
Drug Type:
Manufacturing complexity and regulatory exclusivity create tiered margin structures across molecular categories.
- Monoclonal Antibodies:Engineered biologics targeting CD30, PD-1, and other lymphoma-associated antigens require sophisticated cell culture production. Bristol-Myers Squibb leverages integrated manufacturing networks to sustain cost-competitive supply.
- Tyrosine Kinase Inhibitors:Small-molecule agents with specialized synthesis pathways command concentrated margin pools. EMA orphan drug incentives are accelerating European development priorities for these targeted hematology agents.
- Corticosteroids:Systemic glucocorticoids manage inflammatory complications and serve as bridge therapy. Generic availability limits commercial opportunity despite high utilization.
- Cytotoxic Agents:Conventional chemotherapeutics including anthracyclines and alkylating agents constitute historical backbone regimens. Pricing pressure from biosimilar and generic competition constrains revenue expansion.
Tyrosine kinase inhibitors capture premium economics; monoclonal antibodies are expanding most quickly.
End User:
Site-of-care capabilities determine which patient populations access standard versus investigational therapies.
- Hospitals:Tertiary care institutions with specialized lymphoma programs manage complex AILT cases requiring multidisciplinary coordination. NCI-designated cancer centers capture disproportionate shares of novel mechanism enrollment through centralized protocol development.
- Specialty Clinics:Hematology-focused outpatient facilities deliver concentrated expertise for disease monitoring and therapy administration. These settings bridge community access and academic center capabilities.
- Outpatient Centers:Ambulatory infusion sites administer conventional chemotherapy and supportive care. Cost pressures are shifting stable patients away from hospital-based delivery.
- Home Care:Oral agent administration and remote monitoring enable selected patients to receive therapy outside clinical facilities. Expansion depends on caregiver support infrastructure and telemedicine integration.
Hospitals lead on scale; specialty clinics lead on momentum.
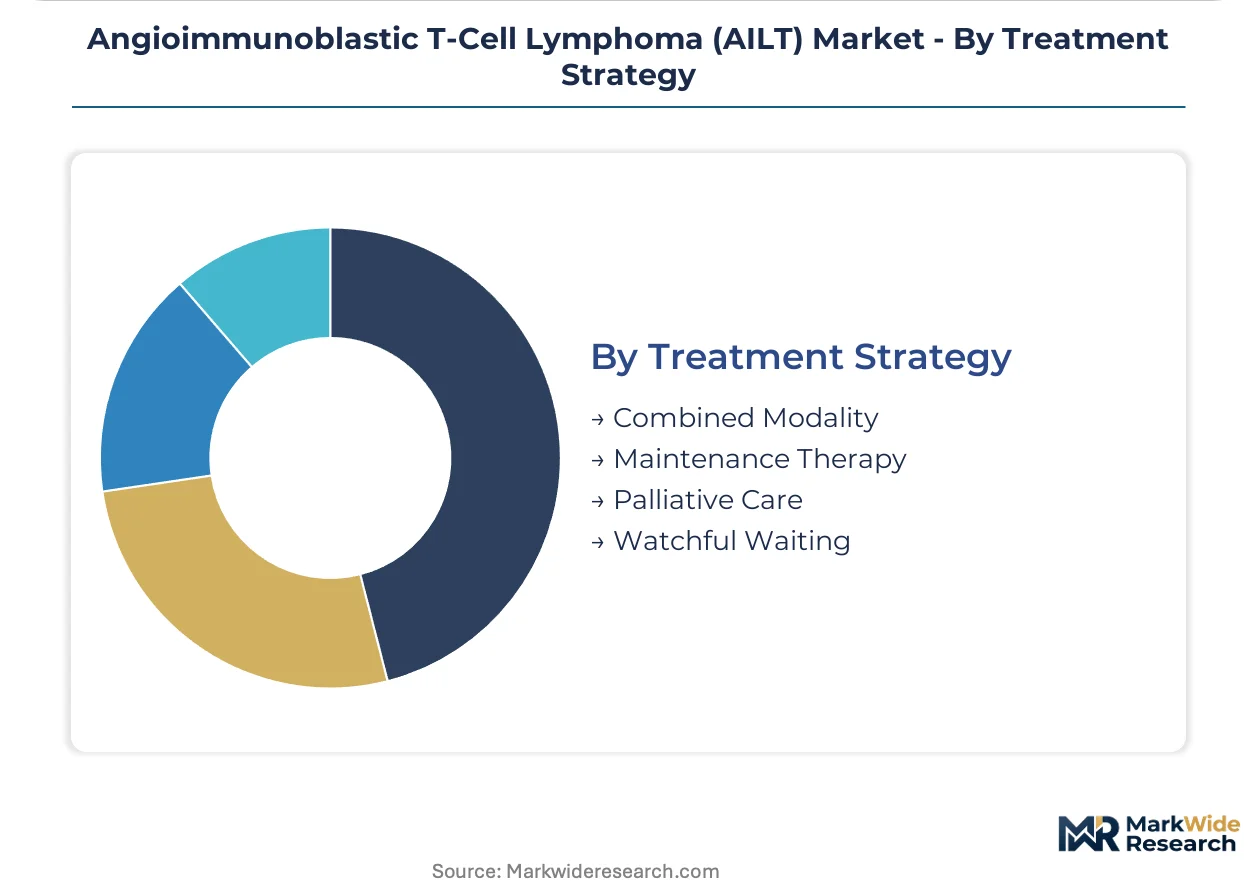
Treatment Strategy:
Clinical risk tolerance and patient functional status shape modality selection across disease trajectories.
- Combined Modality:Sequential or concurrent integration of chemotherapy, immunotherapy, and targeted agents represents the dominant investigative paradigm. Novel combination regimens are displacing single-agent approaches in frontline and relapsed settings.
- Maintenance Therapy:Extended treatment phases following initial response aim to prolong remission duration. Efficacy data from randomized trials are reshaping payer coverage determinations for prolonged therapy.
- Palliative Care:Symptom-focused interventions for refractory disease emphasize quality-of-life preservation. Hospice integration remains underutilized relative to disease burden.
- Watchful Waiting:Observation without immediate intervention applies to select asymptomatic presentations. Clinical vigilance for transformation to aggressive disease is mandatory.
Combined modality leads on scale; maintenance therapy leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Angioimmunoblastic T-cell lymphoma therapeutics originated in academic medical centers across the United States and Western Europe, where specialized lymphoma programs first characterized the disease and pioneered combination regimens. These institutional foundations established the clinical protocols now driving market expansion.
United States
NCI-designated cancer centers and tertiary care institutions anchor demand for novel AILT therapies, with academic medical centers capturing disproportionate shares of investigational drug enrollment. FDA accelerated approval pathways for hematologic malignancies compress commercialization timelines and reshape referral patterns toward centers with captive cell processing capabilities. The Greater Boston and San Francisco Bay Area clusters concentrate biotechnology R&D for T-cell malignancies.
Germany
Specialized hematology centers in Munich and Heidelberg drive adoption of targeted hematology agents for relapsed peripheral T-cell lymphoma subtypes. EMA orphan drug incentives reduce regulatory friction for sponsors pursuing conditional marketing authorization based on single-arm efficacy data. The country's pharmaceutical manufacturing base supports cost-competitive production of monoclonal antibodies through integrated biologics networks.
United Kingdom
London and Manchester academic hospital networks concentrate protocol development for follicular helper T-cell malignancies, with centralized trial sponsorship displacing distributed site participation. MHRA alignment with FDA accelerated approval frameworks enables concurrent regulatory submissions for novel mechanism classes. The NHS specialized commissioning framework determines patient access to premium-priced targeted therapies outside trial settings.
Japan
PMDA's sakigake designation system accelerates review timelines for innovative hematology agents addressing unmet need in aggressive lymphomas. Tokyo and Osaka university hospitals lead investigator-initiated trials for combination regimens in relapsed AILT, leveraging the country's aging population demographics to justify priority review. Domestic pharmaceutical firms anchor development partnerships with Western sponsors seeking Asian trial footprints.
Switzerland
Basel and Zurich pharmaceutical clusters concentrate headquarters operations for global hematology franchises, with proximity to EMA influencing European development prioritization. Swissmedic's streamlined orphan drug procedures attract sponsors seeking efficient market access for rare lymphoma indications. The country's contract manufacturing ecosystem supports specialized production of tyrosine kinase inhibitors and biologics for global supply.
Angioimmunoblastic T-Cell Lymphoma (AILT) Market Competitive Environment
Premium-margin players sit above commodity-margin players across the therapy modality spectrum, with targeted agents and cell therapies commanding concentrated economics versus generic chemotherapy backbones. The market structures around three tiers: integrated pharmaceutical conglomerates with hematology franchises, specialized biotechnology firms with engineered cell platforms, and regional generic manufacturers supplying cytotoxic agents. Consolidation pressures favor acquisition of cell-therapy engineering capabilities by established oncology players, while strategic partnerships bridge viral vector production bottlenecks.
Within the integrated pharmaceutical tier, Bristol-Myers Squibb and Novartis occupy positions representing scale-driven manufacturing and deep R&D investment archetypes respectively. Autolus Limited exemplifies the specialized cell-therapy engineering segment, anchoring the biotechnology tier focused on T-cell malignancy applications. These three entities collectively illustrate the competitive spectrum from mass-market biologics production through precision cellular engineering.
| Leading Market Players |
|---|
| Bristol-Myers Squibb |
| Millennium Pharmaceuticals, Inc. |
| Autolus Limited |
| Eisai Inc. |
| Novartis |
| Kura Oncology |
| PersonGen BioTherapeutics (Suzhou) Co., Ltd. |
| Verastem Oncology |
| ADC Therapeutics |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal pharmaceutical sustainability requirements now gate qualified supply access and premium-tier pricing power across AILT therapeutics. Manufacturers disclosing carbon footprints for active pharmaceutical ingredients secure preferential formulary positioning at tertiary care institutions, while non-compliant suppliers face exclusion from high-margin procurement channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates targeted biologics from conventional chemotherapeutics and generic supportive care agents. Premium-tier checkpoint inhibitors command price differentiation through FDA breakthrough therapy designation and specialized cold-chain logistics, while cost compression in the chemotherapy tier intensifies from biosimilar erosion. Academic medical centers exhibit lowest price sensitivity due to research funding offsets; community oncology practices face acute budget constraints driving formulary restriction.
Supply Chain Analysis
Single-source vulnerability sits with Chinese and Indian contract manufacturers for small-molecule tyrosine kinase inhibitor intermediates. Viral vector production for cell therapies draws from limited US and European biologics facilities, with plasmid DNA supply resting on a concentrated base of specialized producers. Tariff exposure on imported starting materials creates margin volatility for sponsors without captive synthesis capabilities. Distribution runs through hospital-based specialty pharmacies and centralized compounding facilities with temperature-controlled logistics mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AILT market functions as a stable compounder anchored by durable orphan drug exclusivity periods that protect revenue streams across therapy classes. FDA accelerated approval pathways for hematologic malignancies compress development timelines and sustain investor confidence in long-term cash flow visibility.
For Market Incumbents: Hedge against biosimilar erosion in the chemotherapy backbone by deepening investment in combination regimen intellectual property and securing exclusive cell-therapy engineering partnerships. Bristol-Myers Squibb's integrated biologics manufacturing network demonstrates how backward integration into viral vector production insulates supply continuity. Prioritize acquisition of CRISPR-editing platforms to defend against emerging allogeneic cell therapy entrants. For New Entrants and Emerging Players: Begin with biomarker-driven patient stratification services that academic medical centers lack internal capacity to operationalize, creating sticky relationships before therapeutic asset commercialization. The most penetrable white space sits with community oncology practices excluded from NCI-designated cancer center trial networks. A go-to-market angle anchored in decentralized apheresis coordination addresses geographic access barriers that concentrate patient flow at tertiary institutions. For Investors and Strategic Acquirers: Valuations sit cheapest among cell-therapy engineering platforms with T-cell malignancy specialization but limited manufacturing scale. Long-term viability over a five-to-ten year window hinges on successful navigation of viral vector production bottlenecks and demonstration of durable complete response rates in relapsed disease. The signal to watch is EMA conditional marketing authorization conversion rates for single-arm hematologic malignancy trials.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Expanded viral vector capacity at Bristol-Myers Squibb's integrated network reduces supply constraints for checkpoint inhibitor combinations. |
| Regulatory Approval Pathway | FDA accelerated approval for hematologic malignancies compresses commercialization timelines for novel mechanism classes in relapsed AILT. |
| Clinical Trial Advancement | Biomarker-driven eligibility expansion at academic medical centers unlocks patient subsets for follicular helper T-cell targeted agents. |
| Licensing Agreement | EMA orphan drug incentives reduce development costs for European market entry of targeted hematology agents. |
| Pipeline Diversification | CRISPR-based allogeneic cell therapy programs address manufacturing bottlenecks constraining autologous product supply. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient-flow modeling and top-down revenue reconciliation anchored market size estimation across therapy segments.
Segment-weighting approaches distributed value across immunotherapy, targeted therapy, chemotherapy, and stem cell transplant modalities, with additional stratification by treatment line and regional regulatory cluster. CAGRs derived from patient incidence projections, therapy penetration curves, and pricing trajectory assumptions across the analysis window. Forecast inputs incorporated investigator-initiated trial enrollment rates at NCI-designated cancer centers and EMA conditional marketing authorization conversion patterns.
Several conditions sit outside the modeled scope, including pipeline attrition from phase II efficacy failures, reimbursement restriction by national health technology assessment bodies, and manufacturing disruptions from viral vector contamination events. Forecasts reflect documented assumptions about regulatory pathway efficiency and physician adoption velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Appendiceal Cancer Treatment Market
Specialty Medicine
Gaucher and Pompe Diseases Enzyme Replacement Therapy (ERT) Market
Specialty Medicine
Herpangina Treatment Market
Specialty Medicine
CARD9 Deficiency Treatment Market
Specialty Medicine
Interstitial Lung Disease Treatment Market
Specialty Medicine
Rheumatoid Arthritis Treatment Market
Specialty Medicine
Global Primary Angle-Closure Glaucoma Market
Specialty Medicine
Secondary Progressive Multiple Sclerosis (SPMS) Treatment Market
Specialty Medicine
Chronic Urticaria Market
Specialty Medicine
Mantle Cell Lymphoma Market
Specialty Medicine
Global Amyotrophic Lateral Sclerosis (ALS) Treatment Market
Specialty Medicine
Dry Eye Syndrome Market
Specialty Medicine
Global Anal Fistula Treatment Market
Specialty Medicine
US Opioid Use Disorder (OUD) Market
Specialty Medicine
Kaposi Sarcoma Market
Specialty Medicine
Global Photodynamic Therapy Market