
 Immunoglobulin (Igg) Replacement Therapy Market | 2026-2036
Immunoglobulin (Igg) Replacement Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Immunoglobulin (Igg) Replacement Therapy Market Foresight
Market Context
Modular dosing formats and home-infusion kit bundling is restructuring how physicians and patients select between intravenous and subcutaneous regimens. CSL Behring leverages its vertically integrated plasma collection network to sustain supply security across multiple continents. Grifols anchors European manufacturing capacity with one of the largest fractionation footprints outside the United States. Takeda Pharmaceutical Company differentiates through specialty immunoglobulin portfolios targeting neurological indications.
Technical Definition and Segment Structure
Immunoglobulin (IgG) Replacement Therapy comprises purified human immunoglobulin G preparations, typically containing 90-98% IgG with trace IgA and IgM, manufactured through cold ethanol fractionation followed by viral reduction steps including nanofiltration and solvent-detergent treatment. These therapies restore functional antibody levels in patients with primary immunodeficiency disorders, secondary immunodeficiency from hematologic malignancies, and select autoimmune conditions. Intravenous immunoglobulin retains the largest revenue pool due to established reimbursement and hospital infrastructure, while subcutaneous immunoglobulin captures the fastest expansion as homecare settings reduce infusion center burden. Specialty immunoglobulin commands premium positioning in neurological diseases such as chronic inflammatory demyelinating polyneuropathy where higher dosing protocols apply.
Regulatory Framework and Outlook
FDA plasma donor deferral policies, EMA Guideline on Plasma-Derived Medicinal Products, and WHO International Standards for Immunoglobulins collectively govern viral safety, potency labeling, and batch consistency requirements that determine market access. Health technology assessment bodies in Germany, France, and England apply distinct cost-effectiveness thresholds that fragment pricing and indication approval across European markets. Stakeholders must monitor evolving subcutaneous bioequivalence standards and plasma collection economics as supply constraints interact with expanding prophylactic use in secondary immunodeficiency.
Market Dynamics
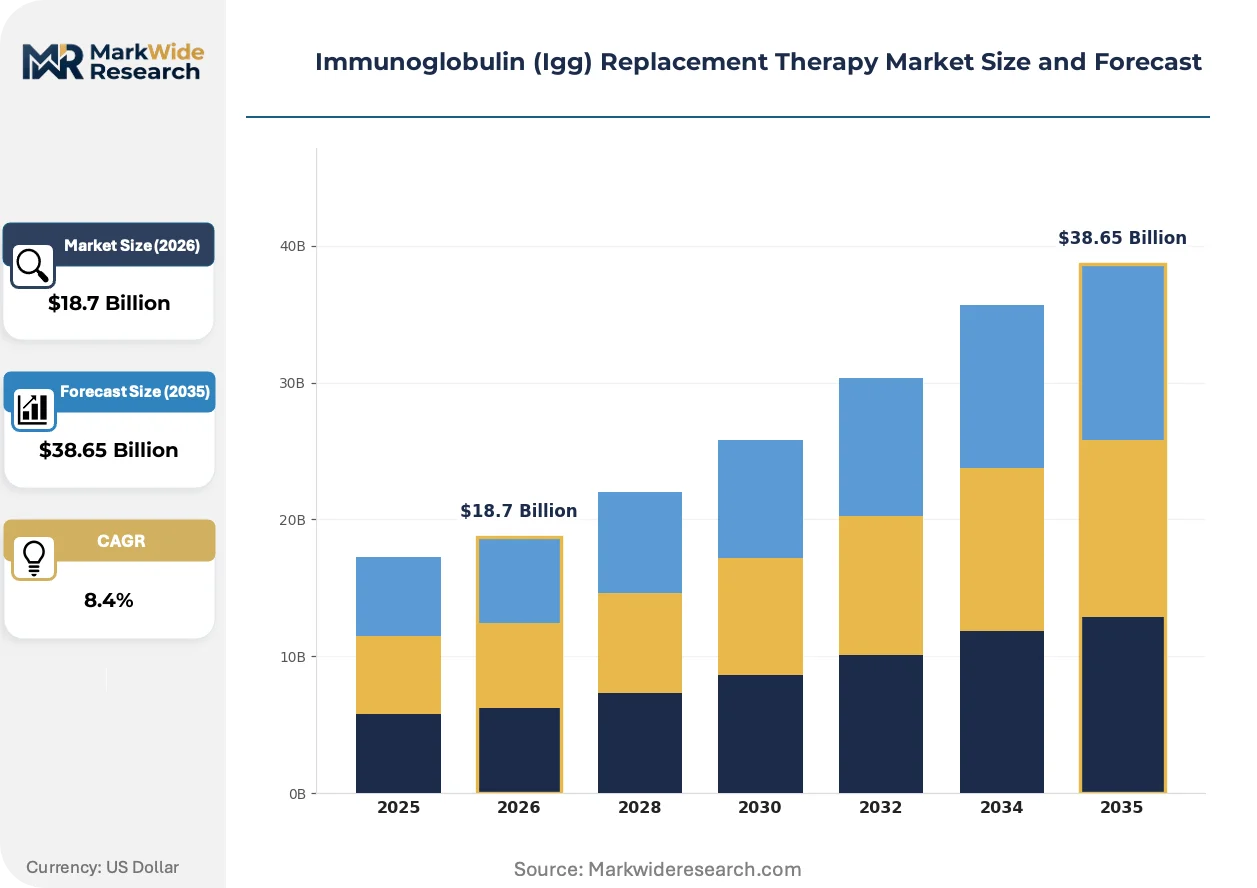
Plasma collection economics and fractionation capacity constraints are compressing supply availability while demand for prophylactic immunoglobulin expands across neurological and secondary immunodeficiency indications.
Growth Catalysts
- FDA plasma-sourcing guidelines:Stricter donor deferral policies and viral safety standards are elevating product qualification thresholds, favoring manufacturers with captive collection networks and certified fractionation infrastructure.
- Home-infusion kit bundling:Subcutaneous administration systems paired with remote patient monitoring are reducing hospital infusion center dependency and extending therapy access to rural patient populations.
- Germany's neurological indication expansion:Health technology assessment bodies in Germany have broadened reimbursed access for chronic inflammatory demyelinating polyneuropathy, creating demand pull for higher-dose specialty immunoglobulin protocols.
Market Restraints
- Plasma collection concentration:United States-based collection centers supply over sixty percent of global source plasma, creating geographic supply vulnerability to donor pool fluctuations and transport logistics disruptions.
- EMA viral-inactivation compliance costs:European manufacturers face elevated capital requirements for nanofiltration and solvent-detergent validation, compressing margins for mid-scale fractionators without integrated collection networks.
- Recombinant monoclonal antibody substitution:Engineered antibody therapies for select autoimmune indications are displacing immunoglobulin in prophylactic protocols where targeted mechanisms demonstrate comparable efficacy.
Strategic Opportunities
- Japan's aging immunodeficient population:Underpenetrated secondary immunodeficiency diagnosis among hematologic malignancy patients in Japan creates expansion potential for hospital-based infusion partnerships and specialty distributor alliances.
- CSRD supply-chain disclosure mandates:European sustainability reporting requirements are creating competitive differentiation for manufacturers with verified plasma provenance tracking and carbon-accounted cold-chain logistics.
- Subcutaneous bioequivalence pathway convergence:Harmonization of FDA and EMA standards for immunoglobulin pharmacokinetic equivalence is enabling single-development programs to serve multiple regulatory jurisdictions simultaneously.
Industry Challenges
- Fractionation specialist scarcity:Plasma protein purification expertise concentrated among retiring cohorts in European and North American facilities is constraining operational scale-up without structured knowledge-transfer programs.
- Legacy hospital inventory system integration:Subcutaneous home-infusion platforms require real-time adherence tracking and adverse event reporting interfaces that conflict with established electronic health record architectures in United States health systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immunoglobulin (Igg) Replacement Therapy Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intravenous Immunoglobulin, Subcutaneous Immunoglobulin, Specialty Immunoglobulin, Others End User: Hospitals, Clinics, Homecare Settings, Rehabilitation Centers Delivery Mode: IV Infusion, Subcutaneous Injection, Intramuscular Injection, Oral Administration Indication: Primary Immunodeficiency, Secondary Immunodeficiency, Autoimmune Disorders, Neurological Diseases |
| Companies Covered | CSL Behring, Grifols, Takeda Pharmaceutical Company, Octapharma AG, Kedrion Biopharma, Baxter International, LFB Group, Biotest AG, China Biologic Products Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immunoglobulin (Igg) Replacement Therapy Market Shifts & Advancements
Digital adherence monitoring and modular dosing platforms are compressing the traditional boundary between clinical and home-based immunoglobulin administration, reshaping how therapy protocols are prescribed and reimbursed.
Subcutaneous infusion pump technology with embedded dose-tracking sensors is decentralizing immunoglobulin delivery from hospital infusion centers to patient-managed home environments. Neurology and immunology practices in the United States and Germany are adopting these systems at accelerating rates for chronic inflammatory demyelinating polyneuropathy patients. This shift is decentralizing site-of-care revenue pools and forcing hospital outpatient departments to renegotiate service contracts around monitoring rather than administration.
EMA's Guideline on Plasma-Derived Medicinal Products is tightening viral safety documentation requirements for fractionation batch release across European markets. Manufacturers must now submit extended nucleic acid testing data and enhanced donor pool epidemiological surveillance. Specialty immunoglobulin portfolios targeting neurological indications face the steepest compliance burden due to higher dosing volumes and extended treatment durations.
Patient-directed therapy scheduling through pharmacy-integrated digital platforms is replacing physician-office-based infusion booking in United States commercial and Medicare Advantage plans. Third-party logistics providers with temperature-validated networks are displacing traditional wholesale distribution for subcutaneous product fulfillment. This pattern is most visible in California, Texas, and Florida where home-infusion nursing density supports same-day kit delivery protocols.
Immunoglobulin (Igg) Replacement Therapy Market Segmentation
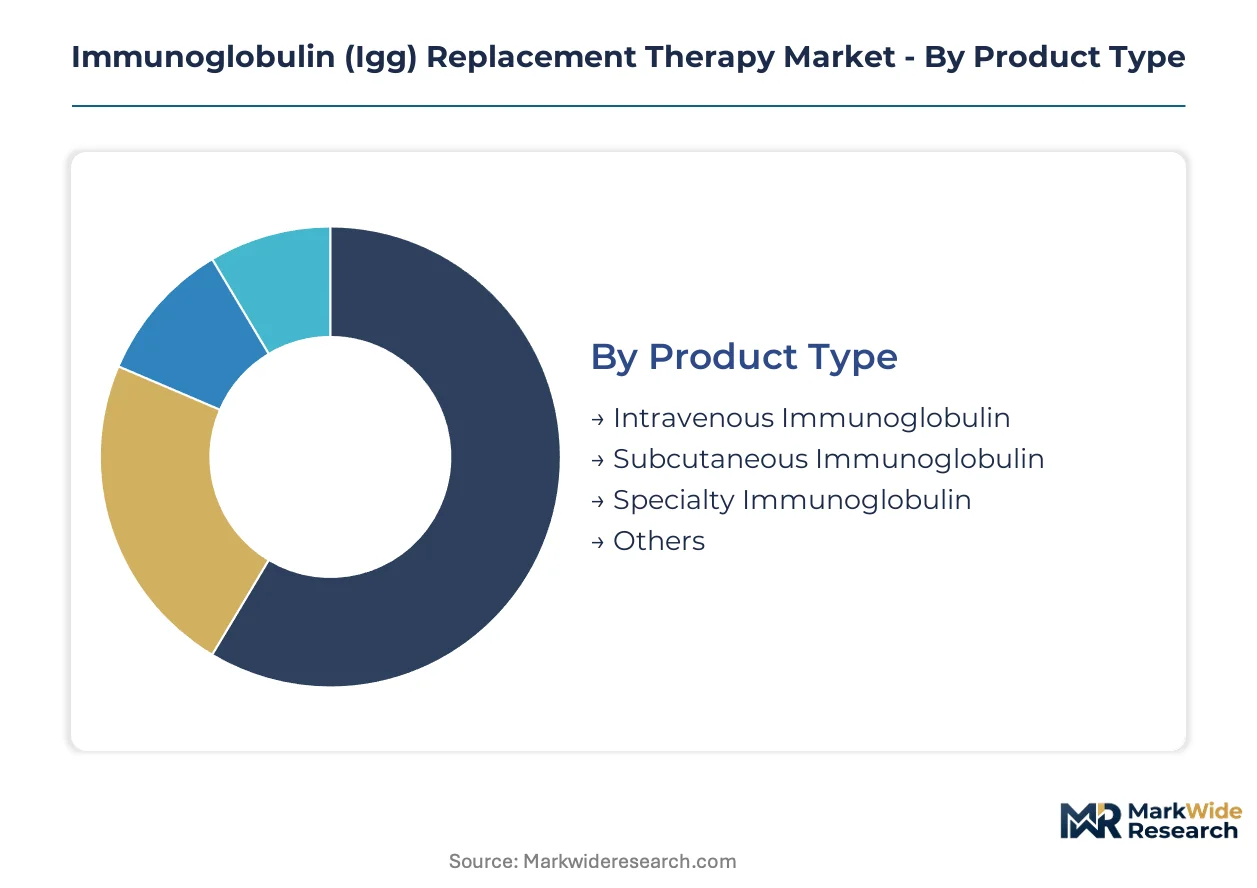
IgG replacement therapy segments diverge sharply between hospital-centric volume plays and premium specialty niches. Understanding these fault lines reveals where pricing power concentrates and where reimbursement pressure bites hardest.
Product Type:
Volume concentration in mature intravenous formats contrasts with premium capture in neurological specialty products, creating a bifurcated margin structure across the category.
- Intravenous Immunoglobulin:Standard 5-10% protein solutions administered via hospital infusion centers dominate therapeutic antibody replacement for primary immunodeficiency. United States hospital outpatient departments absorb the largest share of these infusions due to established Medicare reimbursement codes and nursing infrastructure.
- Subcutaneous Immunoglobulin:Concentrated 20% formulations enable patient-managed weekly dosing through portable pump systems. Germany and Japan are expanding home-infusion coverage fastest as health technology assessments recognize reduced hospitalization costs.
- Specialty Immunoglobulin:Higher-dose protocols for chronic inflammatory demyelinating polyneuropathy command premium positioning.
- Others:Lyophilized and liquid preparations for rare indication extensions.
Today's leader: Intravenous Immunoglobulin. Tomorrow's challenger: Subcutaneous Immunoglobulin.
End User:
Site-of-care economics determine profitability more than clinical indication, with homecare settings capturing margin expansion while hospitals defend volume.
- Hospitals:Academic medical centers and community hospital infusion suites retain the bulk of neurological and hematologic malignancy cases requiring monitoring-intensive administration. EMA viral-inactivation compliance costs weigh heavier on European hospital pharmacy procurement than United States counterparts.
- Homecare Settings:Subcutaneous pump therapy with remote nursing oversight is displacing hospital day-ward admissions for stable primary immunodeficiency patients. California and Texas lead United States adoption due to dense home-infusion nursing networks and favorable Medicare Advantage contracting.
- Clinics:Physician office-based infusion centers serve as a transitional site for patients converting from IV to subcutaneous regimens.
- Rehabilitation Centers:Post-acute facilities manage immunoglobulin for secondary immunodeficiency following hematopoietic stem cell transplantation.
Hospitals still capture the revenue base. Homecare Settings are climbing the fastest.
Delivery Mode:
Route selection locks in supply chain requirements, with infusion-dependent formats demanding cold-chain integrity that injections bypass.
- IV Infusion:Gravity or pump-controlled administration of diluted immunoglobulin over 2-4 hours requires temperature-controlled storage and compounding pharmacy support. United States hospital networks favor this route for high-dose neurological indications where adverse event monitoring is mandatory.
- Subcutaneous Injection:Patient or caregiver-administered bolus or continuous pump delivery eliminates infusion center dependency. Germany's outpatient reimbursement reforms have accelerated patient training program investments by specialty pharmacy distributors.
- Intramuscular Injection:Limited to specific prophylactic applications with lower volume requirements.
- Oral Administration:Not clinically viable for IgG replacement due to gastrointestinal degradation.
IV Infusion holds the installed base. Subcutaneous Injection shows the steepest expansion trajectory.
Indication:
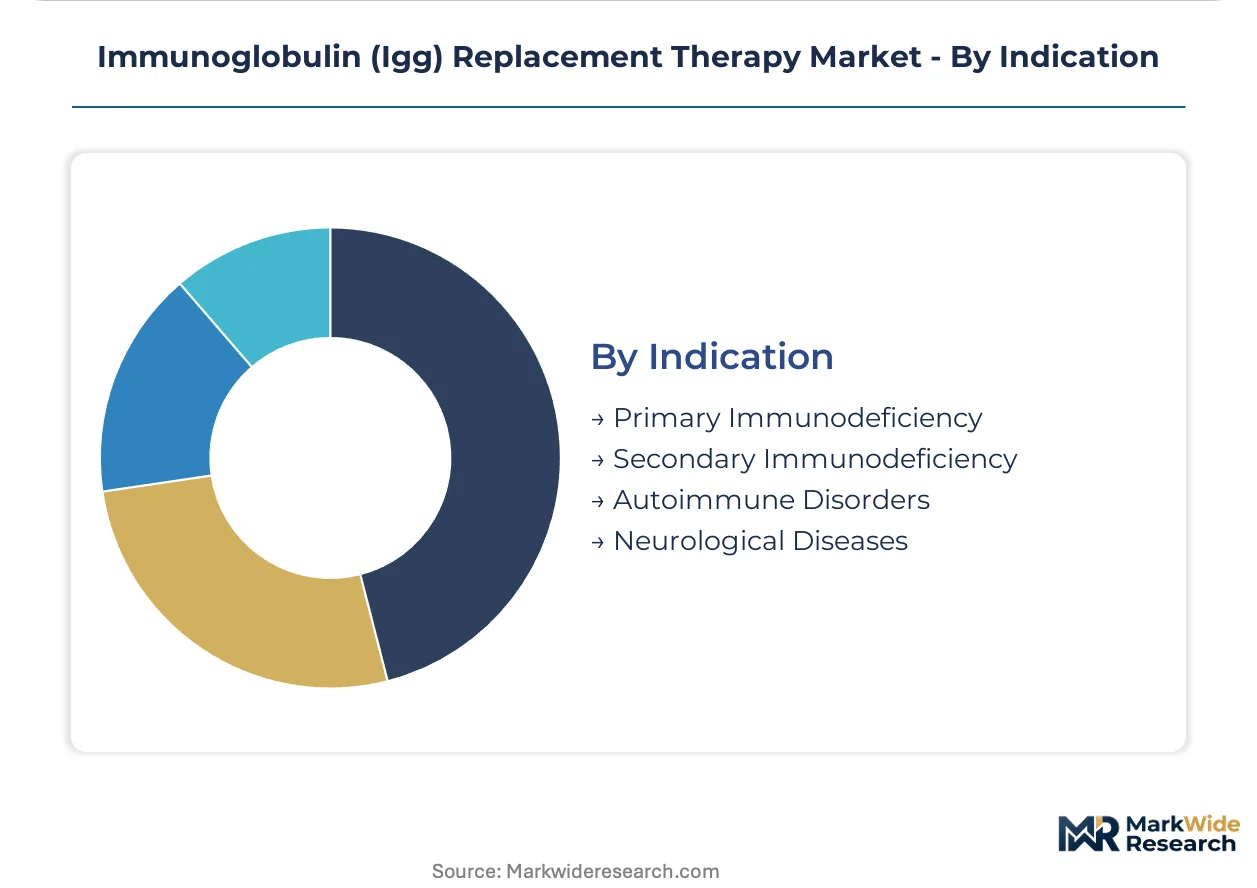
Prescription volume concentrates in prophylactic immunodeficiency management, while pricing power clusters in neurological applications with higher dosing intensity.
- Primary Immunodeficiency:Lifelong antibody replacement for congenital disorders such as common variable immunodeficiency and X-linked agammaglobulinemia constitutes the foundational demand pool. Japan's underpenetrated diagnosis rates among pediatric and adult populations present expansion opportunity for hospital-based specialty referral networks.
- Neurological Diseases:Chronic inflammatory demyelinating polyneuropathy and multifocal motor neuropathy require higher immunoglobulin doses over extended treatment durations. FDA maintenance-of-benefit studies and Germany's G-BA assessments have solidified reimbursed access, concentrating demand pull among specialty neurologists.
- Secondary Immunodeficiency:Post-chemotherapy and post-transplant antibody replacement grows with hematologic malignancy incidence.
- Autoimmune Disorders:Immunomodulatory applications face competitive pressure from recombinant monoclonal alternatives.
Primary Immunodeficiency anchors volume. Neurological Diseases drive premium realization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plasma fractionation originated in university medical centers across the United States and Switzerland during the 1940s, establishing the foundational processing techniques that now govern immunoglobulin manufacturing worldwide. These early research programs created the technical standards and regulatory precedents that shaped subsequent market development across North America, Europe, and Asia-Pacific.
United States
Hospital outpatient departments absorb the largest infusion volume for chronic inflammatory demyelinating polyneuropathy and primary immunodeficiency. FDA plasma donor deferral policies and viral safety standards elevate qualification thresholds for imported products. The Southeast and Texas corridor concentrates home-infusion nursing networks that enable subcutaneous pump therapy expansion.
Germany
G-BA health technology assessments have broadened reimbursed access for neurological indications, pulling demand toward higher-dose specialty protocols. EMA Guideline on Plasma-Derived Medicinal Products imposes extended nucleic acid testing documentation for batch release. Bavaria and North Rhine-Westphalia anchor European fractionation capacity with certified manufacturing infrastructure.
Japan
Underpenetrated secondary immunodeficiency diagnosis among hematologic malignancy patients creates expansion potential for hospital-based specialty referral networks. PMDA oversight of plasma-derived products aligns with WHO International Standards for viral safety validation. The Kanto region around Tokyo concentrates academic medical centers driving neurology protocol adoption.
China
Domestic plasma collection networks are scaling to reduce dependency on imported source material for fractionation. NMPA regulations governing plasma-derived biologics are converging toward international viral-inactivation standards. Yangtze River Delta bioclusters are incubating regional manufacturers with captive collection infrastructure.
Switzerland
Swissmedic certification serves as a regulatory gateway for European market access among non-EU manufacturers. Precision medicine research programs in Basel and Zurich accelerate specialty immunoglobulin development for rare neurological conditions. The country's fractionation heritage supports technical consultancy and process validation services for emerging market entrants.
Immunoglobulin (Igg) Replacement Therapy Market Competitive Landscape
Premium-margin players sit above commodity-margin players across plasma collection security and fractionation scale, creating a tiered competitive structure. The vendor base concentrates among vertically integrated specialists with captive donor networks and multi-continent manufacturing footprints. Three archetypes dominate: plasma collectors with backward integration into fractionation, pure-play fractionators dependent on contracted plasma supply, and diversified pharmaceutical companies with specialty immunoglobulin portfolios. Competitive moves center on collection network expansion and subcutaneous delivery platform partnerships.
Among the integrated plasma specialists, CSL Behring and Grifols occupy positions defined by collection network breadth and fractionation capacity scale. Takeda Pharmaceutical Company exemplifies the diversified pharmaceutical archetype with concentration in neurological specialty segments. These three entities represent distinct strategic postures: captive supply security, European manufacturing anchoring, and indication-specific premium positioning respectively.
| Leading Market Players |
|---|
| CSL Behring |
| Grifols |
| Takeda Pharmaceutical Company |
| Octapharma AG |
| Kedrion Biopharma |
| Baxter International |
| LFB Group |
| Biotest AG |
| China Biologic Products Holdings |
| Others |
Supply & Pricing Matrix
Plasma collection labor costs in the United States feed through fractionation economics to stratify immunoglobulin pricing across premium specialty, standard hospital-grade, and economy contract tiers. This cost cascade from donor recruitment through cold-chain logistics determines margin capture at each downstream node.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates neurological specialty protocols from primary immunodeficiency maintenance doses and bulk contract hospital supply. FDA certification tier and fractionation scale drive price differentiation, with EMA viral-inactivation compliance adding cost compression in European markets. Margins are tightening due to plasma collection economics favoring manufacturers with captive donor networks. Hospital procurement committees exhibit highest price sensitivity, while neurology practices demonstrate lowest sensitivity due to limited therapeutic alternatives.
Supply Chain Analysis
Fractionation specialist workforce availability constrains operational scale-up in Bavaria and North Rhine-Westphalia manufacturing clusters, where retiring cohorts exceed knowledge-transfer program capacity. Supply concentrates in the United States, Germany, and Switzerland, with raw material dependencies on source plasma, cold-chain packaging, and viral-inactivation reagents. Single-source vulnerability runs through United States-based collection centers supplying over sixty percent of global plasma. Distribution runs through temperature-validated third-party logistics networks displacing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The immunoglobulin replacement therapy market represents a late-cycle quality story as demand shifts toward higher-dose neurological specialty protocols with superior reimbursement durability.
For Market Incumbents: Deepen captive plasma collection network coverage across multiple continents to defend against supply security threats from geographic donor pool fluctuations. Invest in subcutaneous pump technology partnerships to control channel migration from hospital infusion centers. EMA viral-inactivation compliance costs favor integrated fractionators with certified infrastructure over mid-scale competitors. For New Entrants and Emerging Players: Launch via specialty pharmacy distributor alliances targeting Japan's underpenetrated secondary immunodeficiency diagnosis among hematologic malignancy patients. Home-infusion nursing networks in California and Texas present the most penetrable site-of-care entry points. Focus go-to-market efforts on remote patient monitoring platform integration to differentiate from established hospital-centric competitors. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale fractionators lack integrated collection networks and face EMA compliance cost burdens. Long-term viability favors vertically integrated specialists with multi-continent manufacturing footprints and specialty immunoglobulin portfolios. Monitor subcutaneous bioequivalence pathway harmonization between FDA and EMA as the signal indicating regulatory efficiency inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Collection Network Expansion | Captive donor pools in the United States and Germany secure supply against collection economics volatility. |
| Subcutaneous Pump Technology Partnership | Home-infusion platforms in California and Texas reduce hospital dependency and extend rural access. |
| EMA Viral-Inactivation Compliance Investment | Extended nucleic acid testing documentation satisfies batch release requirements across European markets. |
| Neurological Indication Portfolio Development | Higher-dose protocols for chronic inflammatory demyelinating polyneuropathy command premium positioning. |
| Remote Patient Monitoring Platform Integration | Digital adherence tracking interfaces with Medicare Advantage contracting requirements in United States commercial plans. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists provided qualitative inputs. Secondary sources include FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient population modeling and top-down fractionation capacity analysis enable triangulation across data streams.
Rate-of-change decomposition separates volume growth from price evolution across the analysis window. Segmentation dimensions include product type, administration route, indication category, and regional regulatory cluster. CAGRs derive from plasma collection economics modeling and demand expansion in neurological applications. Forecast inputs incorporate health technology assessment decisions and subcutaneous bioequivalence standard harmonization.
Several conditions sit outside the modeled scope, including unforeseen regulatory revocation of approved indications and abrupt plasma donor pool disruptions from public health events. Forecasts reflect assumptions about reimbursement stability and fractionation capacity expansion timelines. Material deviation in FDA donor deferral policies or EMA viral-safety standard revisions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Gingivostomatitis Market
Specialty Medicine
Advanced Basal Cell Carcinoma Market
Specialty Medicine
HPV Associated Disorders Market
Specialty Medicine
Vertigo Market
Specialty Medicine
Ragweed Pollen Allergy Treatment Market
Specialty Medicine
Latin America Bladder Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Global Acute Agitation and Aggression Treatment Market
Specialty Medicine
Serotonin Syndrome Market
Specialty Medicine
Japan Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
Bulimia Nervosa Market
Specialty Medicine
Global Breast Cancer Therapeutics Market
Specialty Medicine
Iron Deficiency Anemia Therapy Market
Specialty Medicine
Selectin Blocker Market
Specialty Medicine
Epileptic Seizures Treatment Market
Specialty Medicine
Balantidiasis Treatment Market
Specialty Medicine
Malabsorption Syndrome Market