
 Uterine Cancer Therapeutics and Diagnostics Market | 2026-2036
Uterine Cancer Therapeutics and Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Uterine Cancer Therapeutics and Diagnostics Market Analytics
Multi-source biologics sourcing is restructuring supply security for platinum-resistant endometrial cancer therapies. Merck & Co. leverages its pembrolizumab franchise to anchor immuno-oncology positioning in uterine malignancies. Roche sustains dominance in companion diagnostics through its tissue-agnostic testing platforms. Abbott Laboratories competes on point-of-care molecular assay portability for decentralized oncology workflows.
Uterine cancer therapeutics and diagnostics encompasses systemic treatments and detection modalities for malignancies of the endometrium and uterine sarcomas, including carboplatin-paclitaxel combination regimens, immune checkpoint inhibitors targeting PD-1/PD-L1 pathways, and next-generation sequencing panels assessing microsatellite instability or tumor mutational burden to guide therapy selection. The primary purpose is reducing mortality from the most common gynecologic malignancy in high-income countries through stage-appropriate intervention. Immunotherapy now leads growth velocity among product types as checkpoint inhibitors expand into frontline endometrial cancer settings alongside chemotherapy. Genetic testing captures disproportionate investment focus within diagnosis methods as Foundation Medicine-style comprehensive genomic profiling becomes standard before systemic therapy initiation.
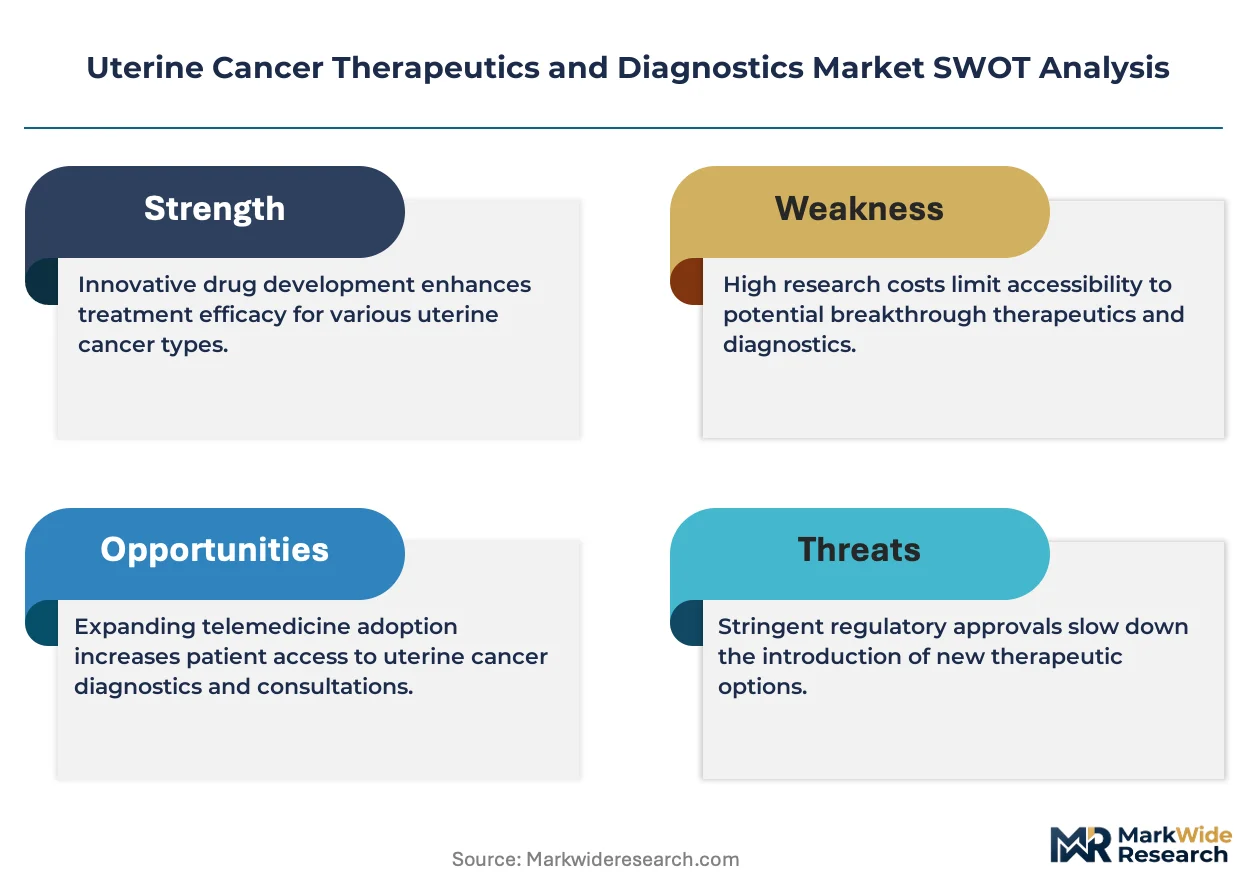
FDA breakthrough therapy designation and EMA conditional marketing authorization frameworks compress development timelines for uterine cancer drugs with compelling early efficacy signals. NMPA oncology center reforms in China accelerate domestic PD-1 inhibitor approvals for endometrial carcinoma indications. Stakeholders must monitor evolving reimbursement for circulating tumor DNA assays versus tissue-based testing as health technology assessment bodies scrutinize diagnostic cost-effectiveness across treatment pathways.
Market Dynamics
Biomarker-directed therapy selection is compressing treatment pathways for endometrial carcinoma patients, forcing hospital networks to consolidate molecular testing infrastructure ahead of systemic therapy initiation.
Growth Catalysts
- FDA Breakthrough Therapy Designation:Accelerated approval pathways compress development timelines for PD-1 inhibitors in mismatch repair-deficient endometrial cancer, rewarding early efficacy signals with expedited market access.
- Comprehensive Genomic Profiling:Next-generation sequencing panels assessing microsatellite instability and tumor mutational burden are becoming mandatory prerequisites for therapy selection in gynecologic oncology departments.
- Japan:Centralized gynecologic oncology networks in Tokyo and Osaka are standardizing biomarker testing protocols, creating template adoption pathways for other high-income healthcare systems.
Market Restraints
- Platinum Supply Concentration:Carboplatin and cisplatin active pharmaceutical ingredient production clusters in India and China create vulnerability for combination chemotherapy backbones in endometrial cancer regimens.
- Reimbursement Scrutiny:Health technology assessment bodies in Germany and England are tightening evidentiary standards for circulating tumor DNA assays versus tissue-based companion diagnostics.
- Technical Limitation:Tumor heterogeneity in uterine serous carcinoma reduces predictive accuracy of single-site biopsies for guiding targeted therapy decisions.
Strategic Opportunities
- Decentralized Molecular Assays:Point-of-care testing platforms for Lynch syndrome screening in community gynecology practices capture patients before referral to academic medical centers.
- EMA Conditional Marketing Authorization:Early access schemes for antibody-drug conjugates in platinum-resistant disease create revenue windows ahead of full label expansion.
- Artificial Intelligence:Digital pathology algorithms integrating with whole-slide imaging are converging with radiomics for preoperative risk stratification in endometrial cancer staging.
Industry Challenges
- Bioinformatics Talent Gap:Clinical interpretation of complex genomic signatures requires specialized computational pathology expertise that academic medical centers struggle to recruit.
- Multi-Site Trial Complexity:International protocols for biomarker-enriched uterine cancer studies face harmonization friction across FDA, EMA, and PMDA evidentiary requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uterine Cancer Therapeutics and Diagnostics Market |
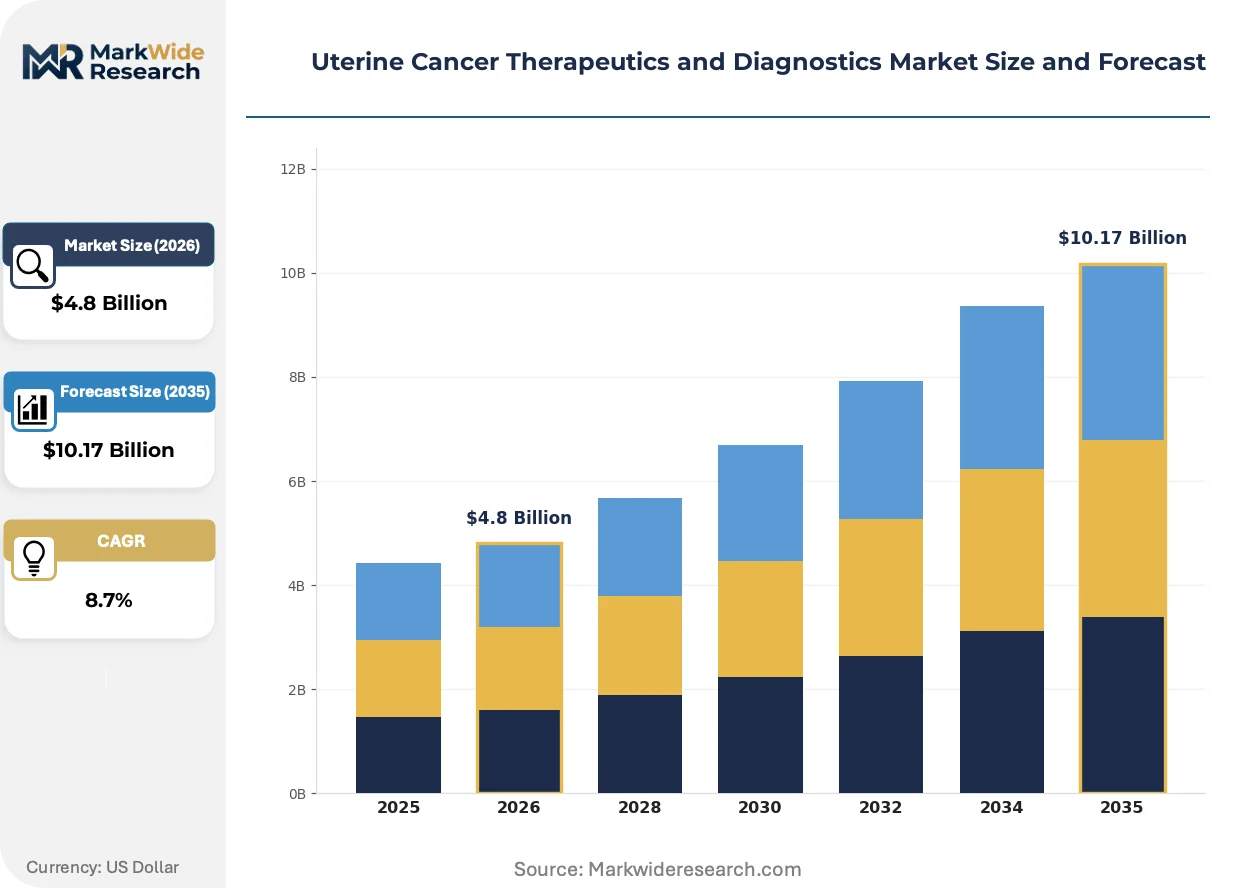
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Immunotherapy, Radiotherapy, Targeted Therapy Delivery Mode: Intravenous, Oral, Subcutaneous, Topical End User: Hospitals, Clinics, Diagnostic Laboratories, Home Care Diagnosis Method: Biopsy, Imaging, Blood Tests, Genetic Testing |
| Companies Covered | Abbott Laboratories, Merck & Co., Inc., Roche, GlaxoSmithKline, Novartis AG, AstraZeneca, Pfizer, Becton, Dickinson and Company, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uterine Cancer Therapeutics and Diagnostics Market Evolving Landscape
Liquid biopsy platforms and artificial intelligence-enabled pathology are restructuring how endometrial malignancies are detected, characterized, and monitored across the care continuum.
Next-generation sequencing of circulating tumor DNA is decentralizing molecular profiling for endometrial cancer recurrence monitoring. Community oncology practices in the United States are adopting blood-based assays to reduce dependency on tissue re-biopsy. This shift is compressing turnaround times for treatment modification decisions and redistributing testing volume from centralized academic pathology laboratories.
EMA's In Vitro Diagnostic Regulation is tightening performance validation requirements for companion diagnostics co-developed with targeted therapies. Manufacturers must now demonstrate clinical utility through prospective trials rather than retrospective analytical validation. High-complexity molecular assays for PD-L1 expression and mismatch repair status face extended conformity assessment timelines in European markets.
Gynecologic oncology departments are unbundling comprehensive genomic profiling from drug procurement decisions. Hospital pharmacy and therapeutics committees in Germany and Japan now require pre-authorization documentation of biomarker results before immune checkpoint inhibitor dispensing. This behavioral shift is elevating pathologist influence in treatment selection and compressing physician autonomy in empirical therapy initiation.
Uterine Cancer Therapeutics and Diagnostics Market Segmentation
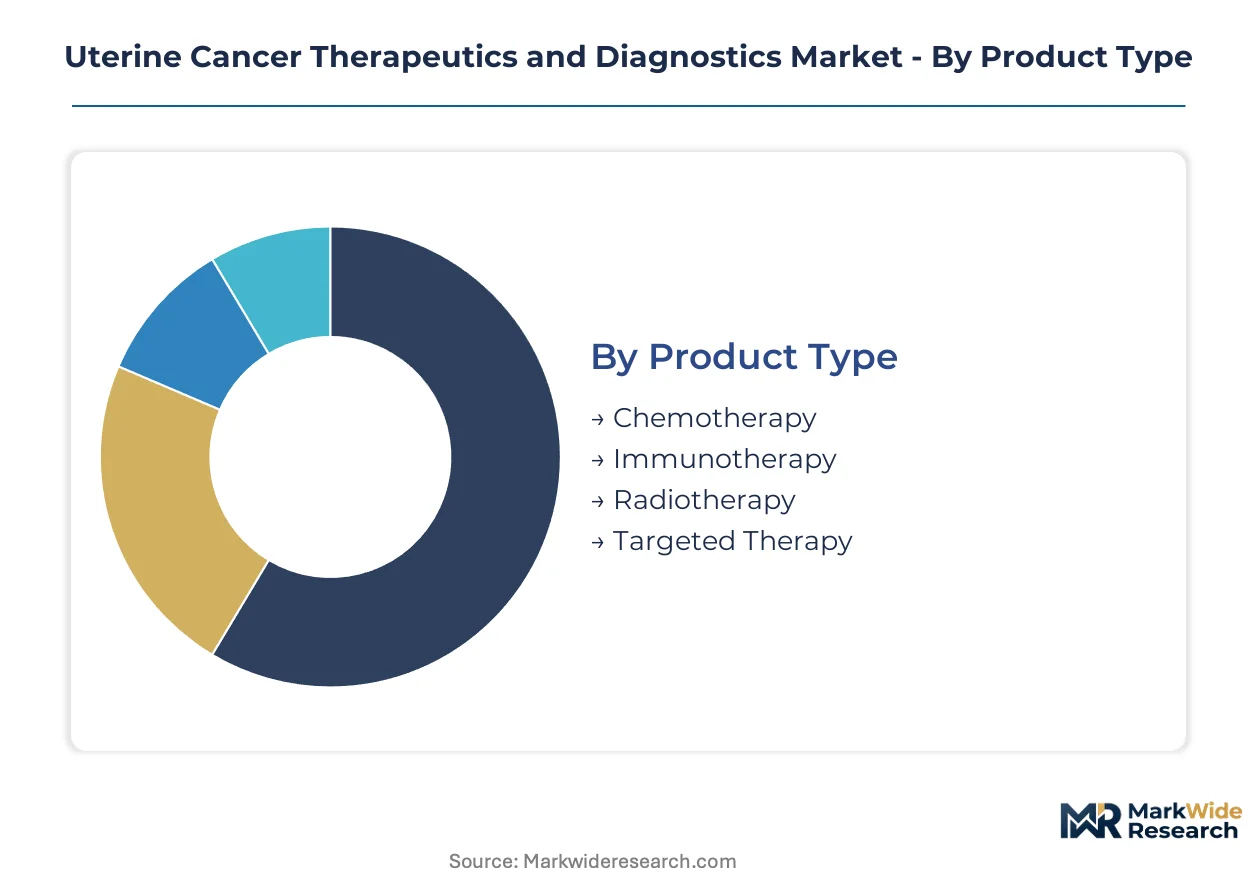
Therapy selection in uterine malignancies hinges on precise patient stratification across molecular, anatomical, and care-setting dimensions. Segmentation clarity enables manufacturers to align development pipelines with where clinical decisions actually occur.
Product Type:
Upgrade cycles in endometrial carcinoma treatment are shortening as biomarker discovery redefines standard-of-care boundaries every 3-4 years.
- Immunotherapy:PD-1 and PD-L1 checkpoint inhibitors demonstrate durable responses in mismatch repair-deficient subpopulations. United States academic medical centers now frontline these agents alongside carboplatin-paclitaxel, compressing the effective patent window for conventional cytotoxics.
- Targeted Therapy:Antibody-drug conjugates and PI3K pathway inhibitors address hormone receptor-positive and HER2-amplified disease segments. Japan's PMDA accelerated approval framework prioritizes these modalities for platinum-resistant populations, creating early revenue capture opportunities.
- Chemotherapy:Platinum-taxane combinations retain utility in frontline advanced disease despite immunotherapy encroachment. Supply security concerns around carboplatin API sourcing from India and China constrain hospital formulary flexibility.
- Radiotherapy:External beam and brachytherapy approaches dominate locoregional disease management. Germany's hospital reimbursement structures favor fractionation protocols that minimize inpatient bed utilization.
Immunotherapy sits at the top of the volume ranking, with targeted therapy climbing the fastest.
Delivery Mode:
Patient preference and healthcare resource constraints are redistributing administration site decisions across the care continuum.
- Intravenous:Checkpoint inhibitors and cytotoxic regimens require infusion center infrastructure with oncology nursing specialization. United States hospital networks are consolidating these services into dedicated cancer centers to capture bundled reimbursement.
- Oral:Poly ADP ribose polymerase inhibitors and hormonal agents enable outpatient maintenance therapy. Home care adoption in Japan reduces transportation burden for elderly endometrial cancer patients in rural prefectures.
- Subcutaneous:Fixed-dose combination formulations reduce pharmacy preparation time and infusion chair occupancy. Germany's outpatient oncology clinics favor these for capacity-constrained environments.
- Topical:Limited to palliative symptom management and localized vaginal applications. Clinical trial activity in this modality remains minimal for invasive disease.
Intravenous administration commands current procedure volume, though oral delivery is gaining share fastest among new patient starts.
End User:
Site-of-care economics and molecular testing capabilities are concentrating complex uterine cancer management into specific institutional tiers.
- Hospitals:Academic medical centers with embedded molecular tumor boards dominate biomarker-directed therapy initiation. Foundation Medicine-style comprehensive genomic profiling requires pathology informatics infrastructure concentrated in United States NCI-designated cancer centers.
- Diagnostic Laboratories:Centralized reference labs process immunohistochemistry and next-generation sequencing for community oncology practices. EMA's In Vitro Diagnostic Regulation is extending conformity assessment timelines for PD-L1 and mismatch repair assays in European markets.
- Clinics:Community gynecologic oncology practices in the United States are adopting liquid biopsy platforms to reduce tissue re-biopsy dependency. Turnaround time compression enables faster treatment modification decisions.
- Home Care:Oral therapy administration and remote patient monitoring expand following COVID-19 infrastructure investments. Japan's aging population demographics accelerate demand for in-home supportive care.
Hospitals anchor the patient volume base, while diagnostic laboratories are expanding capacity most aggressively.
Diagnosis Method:
Detection modality selection follows disease presentation stage and suspected histologic subtype, with technology substitution accelerating in recurrence monitoring.
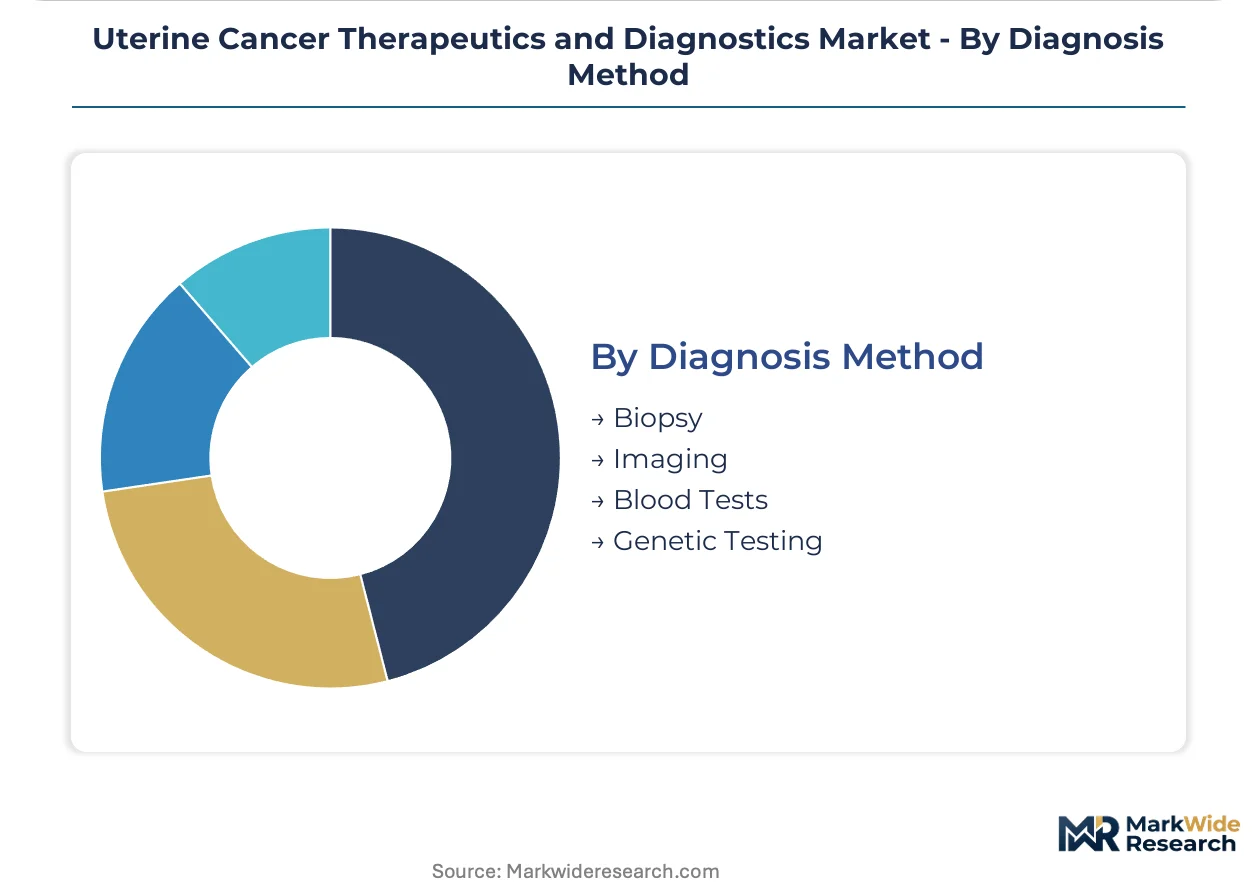
- Genetic Testing:Lynch syndrome screening and somatic profiling guide prevention strategies and therapy selection. United States gynecologic oncology guidelines now mandate universal mismatch repair testing for all endometrial cancer diagnoses.
- Imaging:MRI and CT staging determines surgical approach and radiation field design. Germany's statutory health insurance funds require preoperative imaging documentation prior to radical hysterectomy authorization.
- Biopsy:Endometrial sampling remains definitive for histologic diagnosis and molecular subtyping. Tumor heterogeneity in uterine serous carcinoma reduces single-site biopsy predictive accuracy for targeted therapy decisions.
- Blood Tests:Circulating tumor DNA assays are decentralizing recurrence monitoring to community practices. Health technology assessment bodies in England scrutinize cost-effectiveness versus tissue-based alternatives.
Genetic testing leads current procedure volume, with blood-based assays demonstrating the steepest expansion trajectory in monitoring applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is concentrating biomarker testing infrastructure in jurisdictions with harmonized approval frameworks, as manufacturers prioritize markets where FDA breakthrough designations and EMA conditional authorizations accelerate commercialization timelines for uterine cancer therapies.
United States
NCI-designated cancer centers in Boston and Houston anchor demand for comprehensive genomic profiling, with Foundation Medicine-style panels now mandatory before systemic therapy initiation. FDA breakthrough therapy designations for PD-1 inhibitors in mismatch repair-deficient disease compress development timelines, rewarding early efficacy signals with expedited market access. Academic medical centers in the Mid-Atlantic and Pacific Coast regions are consolidating molecular tumor board infrastructure to capture bundled reimbursement for biomarker-directed care.
Germany
Statutory health insurance funds require preoperative imaging documentation prior to radical hysterectomy authorization, embedding diagnostics deeply in surgical pathways. EMA's In Vitro Diagnostic Regulation extends conformity assessment timelines for PD-L1 and mismatch repair assays, creating compliance cost gaps that favor established reference laboratories. The Rhine-Ruhr and Bavarian hospital networks are standardizing biomarker testing protocols across centralized gynecologic oncology departments.
Japan
PMDA accelerated approval frameworks prioritize antibody-drug conjugates for platinum-resistant populations, creating early revenue capture opportunities before full label expansion. METI oncology center reforms align domestic PD-1 inhibitor approvals with international evidentiary standards. Tokyo and Osaka metropolitan clusters are template adoption pathways for standardized biomarker testing that other high-income healthcare systems replicate.
China
NMPA oncology center reforms accelerate domestic PD-1 inhibitor approvals for endometrial carcinoma indications, compressing development timelines for local manufacturers. The country's national pharmaceutical regulator is tightening clinical trial harmonization requirements with FDA and EMA standards. Shanghai and Beijing hospital networks are building molecular profiling capabilities to match academic medical center throughput in Western markets.
United Kingdom
NICE health technology assessment bodies scrutinize cost-effectiveness of circulating tumor DNA assays versus tissue-based companion diagnostics, tightening evidentiary standards for reimbursement. The NHS Long Term Plan embeds Lynch syndrome screening in community gynecology pathways. London and Manchester cancer centers are piloting digital pathology algorithms for preoperative risk stratification in endometrial cancer staging.
Uterine Cancer Therapeutics and Diagnostics Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue decentralized molecular assay portability and point-of-care testing platforms. The market structures around three tiers: multinational pharmaceutical conglomerates anchoring immuno-oncology franchises, diagnostic specialists commanding companion diagnostics platforms, and emerging biotechs targeting biomarker-enriched subpopulations. Strategic moves concentrate on M&A for molecular testing capabilities and strategic partnerships to secure platinum API supply chains.
Within the pharmaceutical tier, Merck & Co., Inc. and AstraZeneca exemplify checkpoint inhibitor anchoring strategies, while Roche occupies a position in companion diagnostics through tissue-agnostic testing platforms. Abbott Laboratories represents the decentralized diagnostics archetype, competing on assay portability for community oncology workflows. These three companies illustrate how competitive positioning splits between therapy development infrastructure and diagnostic enablement capabilities.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Merck & Co., Inc. |
| Roche |
| GlaxoSmithKline |
| Novartis AG |
| AstraZeneca |
| Pfizer |
| Becton, Dickinson and Company |
| Siemens Healthineers |
| Others |
Value Network & Pricing Analysis
Platinum group metal price indices cascade through carboplatin and cisplatin active pharmaceutical ingredient procurement, compressing margins on combination chemotherapy backbones while amplifying pricing power for immunotherapy franchises that reduce platinum dependency in frontline endometrial carcinoma protocols.
Pricing Analysis
Input-cost pass-through from Indian and Chinese API manufacturing clusters shapes contract-based long-term offtake structures for platinum-taxane regimens, with pricing stratifying across branded originator, authorized generic, and commodity API tiers. Certification level under FDA Current Good Manufacturing Practice and EMA GMP standards commands substantial premia over non-validated sourcing. Pricing pressure stems from health technology assessment scrutiny in Germany and England, where NICE and IQWiG evidentiary standards tighten reimbursement for circulating tumor DNA assays. Community oncology practices exhibit highest price sensitivity due to bundled reimbursement constraints, while academic medical centers prioritize biomarker turnaround time over per-test cost.
Supply Chain Analysis
Specialized oncology nursing workforce availability in United States Mid-Atlantic and Pacific Coast regions anchors infusion center capacity expansion for checkpoint inhibitor administration. API production concentrates in India and China for platinum agents, with antibody-drug conjugate biologics sourcing from South Korean and Singaporean contract manufacturing organizations. Supply chain risk centers on single-source vulnerability for carboplatin precursors following manufacturing consolidation. Distribution runs through specialty pharmacy networks and hospital-based oncology pharmacies, with cold-chain logistics for biologics requiring validated temperature monitoring.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The uterine cancer therapeutics and diagnostics market functions as a regulatory compounder, with FDA breakthrough therapy designation and EMA conditional marketing authorization frameworks compressing development timelines and concentrating investment in biomarker-directed modalities.
For Market Incumbents: Lock in molecular testing infrastructure partnerships with NCI-designated cancer centers to secure formulary placement ahead of pipeline competitors. Backward integration into companion diagnostics manufacturing reduces dependency on Roche and Abbott reference platforms. Consolidate supply agreements for platinum API to mitigate Indian and Chinese sourcing concentration risk. For New Entrants and Emerging Players: Point-of-care Lynch syndrome screening platforms represent the most penetrable white-space target, capturing patients in community gynecology practices before academic medical center referral. Decentralized liquid biopsy assays for recurrence monitoring offer second entry vector with lower regulatory burden than frontline therapy development. Pursue hospital system partnerships emphasizing turnaround time compression over comprehensive genomic profiling breadth. For Investors and Strategic Acquirers: Asymmetric upside sits with diagnostic platform specialists possessing tissue-agnostic testing capabilities and FDA premarket approval pathways. Long-term viability over the extended analysis window favors companies with reimbursement strategy integration across Medicare, Medicaid, and commercial payer contracts. Watch PMDA accelerated approval decisions for antibody-drug conjugates in platinum-resistant disease as inflection signal for Japanese market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Biomarker-enriched protocols accelerate FDA breakthrough therapy designation for mismatch repair-deficient populations. |
| Regulatory Approval Pathway | EMA conditional marketing authorization creates revenue windows before full label expansion in European markets. |
| Manufacturing Scale-Up | Carboplatin API capacity expansion in India reduces supply vulnerability for combination chemotherapy backbones. |
| Hospital System Partnership | Molecular tumor board integration with Foundation Medicine-style profiling secures bundled reimbursement capture. |
| Reimbursement Strategy | NICE health technology assessment navigation determines circulating tumor DNA assay adoption in England. |
Research Methodology
Multiple input streams — primary interviews with gynecologic oncologists, formulary directors, and pathology informatics specialists; secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov, and hospital procurement databases; and bottom-up and top-down triangulation — were reconciled to construct market estimates. Conversations with biomarker testing laboratory directors and payer access specialists informed reimbursement pathway dynamics. SEC 10-K disclosures from Merck, Roche, and Abbott provided revenue segmentation benchmarks.
Data-stream reconciliation across therapy line, administration route, diagnosis method, and regional regulatory cluster dimensions generated volume and value outputs across the projection horizon. CAGRs were derived from segmented growth rate modeling incorporating biomarker testing adoption curves, checkpoint inhibitor frontline penetration assumptions, and platinum-resistant population epidemiology. Forecast inputs included PMDA approval timelines, NICE technology appraisal schedules, and CMS coverage determination patterns for companion diagnostics.
The model holds under stable FDA and EMA regulatory frameworks; deviation in accelerated approval evidentiary standards or biomarker testing reimbursement policy would shift therapy selection patterns and diagnostic volume forecasts. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Neurometabolic Disorder Market
Specialty Medicine
Checkpoint Inhibitor Refractory Cancer Market
Specialty Medicine
SPINA Bifida and Hydrocephalus Market
Specialty Medicine
Global Lupus Market
Specialty Medicine
Global Endometriosis Treatment Market
Specialty Medicine
Pseudomonas Aeruginosa Treatment Market
Specialty Medicine
Wilms Tumor Treatment Market
Specialty Medicine
Sjogrens Syndrome Market
Specialty Medicine
Dementia Management Market
Specialty Medicine
Middle East and Africa Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Global Female Sexual Dysfunction Treatment Market
Specialty Medicine
Leukocytoclastic Vasculitis Market
Specialty Medicine
Zygomycosis Treatments Market
Specialty Medicine
Atrial Septal Defect Market
Specialty Medicine
Global Lung Transplant Therapeutics Market
Specialty Medicine
Global Breast Cancer Therapeutics Market