
 Middle-East and Africa Alpha-Glucosidase Inhibitors Market | 2026-2036
Middle-East and Africa Alpha-Glucosidase Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Alpha-Glucosidase Inhibitors Market Foresight
Aftermarket patient support programs is tilting from pure drug dispensing toward glycemic monitoring integration and adherence coaching. Sun Pharma leverages its established generic manufacturing base to supply cost-competitive acarbose across North African markets. Pfizer sustains brand loyalty through specialist physician education initiatives in Gulf state medical centers. Takeda differentiates via its legacy voglibose franchise and endocrinology-focused medical affairs teams.
Alpha-glucosidase inhibitors are oral antidiabetic agents that delay carbohydrate digestion in the intestinal brush border through reversible inhibition of membrane-bound alpha-glucosidase enzymes, thereby flattening postprandial glucose excursions. These compounds serve primarily as second-line or combination therapy in type 2 diabetes management where post-meal hyperglycemia remains poorly controlled. Acarbose dominates prescription volumes across public hospital formularies due to its extensive safety record and favorable reimbursement positioning. The homecare delivery mode is expanding fastest among Gulf state expatriate populations seeking chronic disease management outside institutional settings. Diabetes management anchors therapy area demand, though metabolic disorders applications are gaining specialist attention for prediabetes intervention protocols.
Saudi Arabia's SFDA and South Africa's SAHPRA enforce bioequivalence standards that shape generic substitution patterns and local manufacturing investment decisions. Egypt's drug authority applies pricing controls that compress margin pools for imported finished formulations while stimulating local tableting operations. The UAE's MOHAP registration pathway influences Gulf-wide product launch sequencing for multinational sponsors. Stakeholders must monitor evolving Gulf Cooperation Council regulatory harmonization timelines and their impact on centralized versus national approval strategies.
Market Dynamics
Hospital-based diabetes management programs across South Africa are expanding adoption of alpha-glucosidase inhibitors through integrated glycemic monitoring protocols. CDSCO-aligned quality benchmarks and Gulf Cooperation Council harmonization initiatives are simultaneously tightening manufacturing standards and reshaping competitive entry requirements across the region.
Growth Catalysts
- SFDA bioequivalence enforcement:Saudi Arabia's regulator mandates rigorous generic substitution standards that elevate quality-tier products into formulary preference positions.
- Expatriate homecare demand:Gulf state foreign worker populations drive rapid expansion of chronic disease management outside institutional settings.
- Public hospital procurement centralization:Egypt's drug authority consolidates purchasing volumes that favor established acarbose suppliers with local tableting capabilities.
Market Restraints
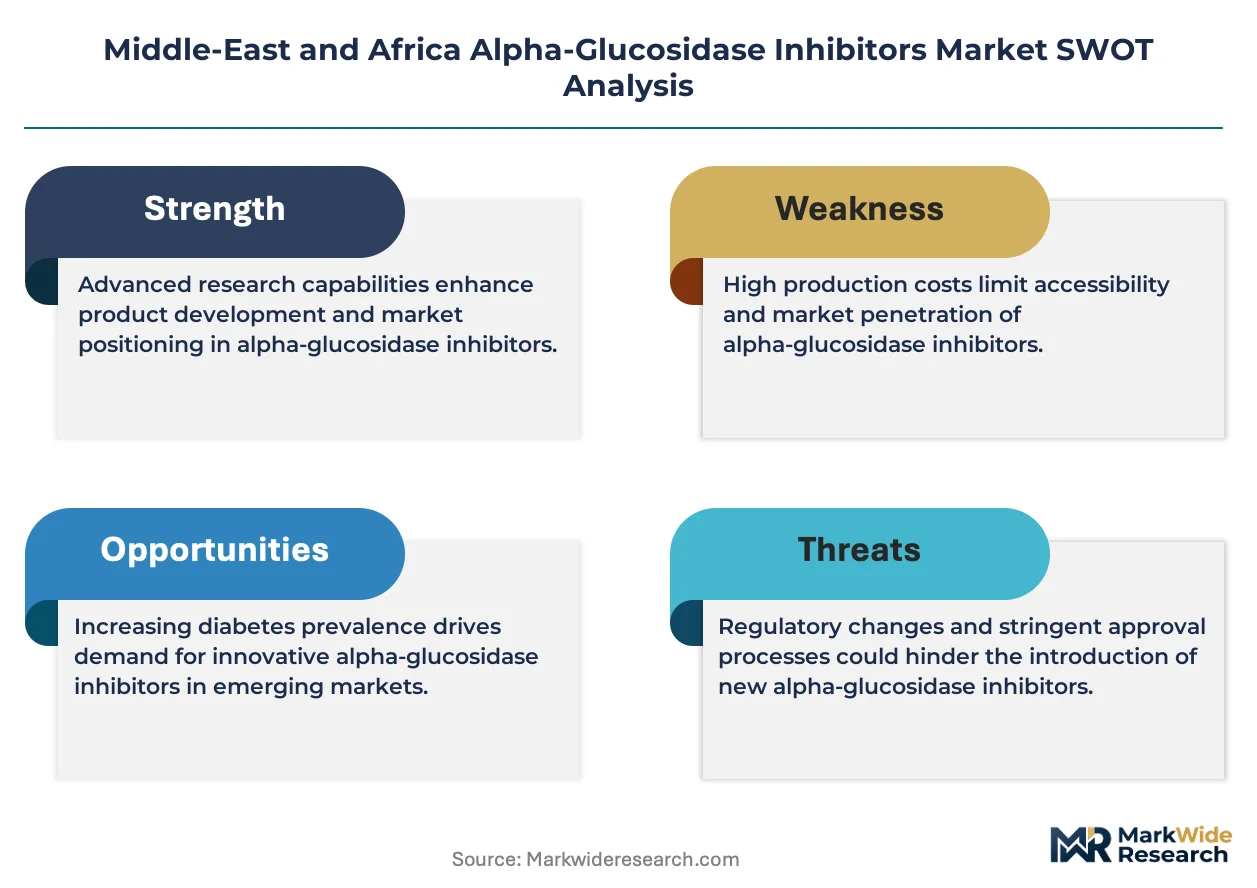
- Active pharmaceutical ingredient concentration:China and India supply over 80 percent of acarbose API, creating exposure to cross-border logistics disruptions.
- Pricing compression mechanics:Egypt's pricing controls compress margin pools for imported finished formulations below sustainable thresholds for some multinational sponsors.
- Second-line therapy positioning:Clinical guidelines consistently position alpha-glucosidase inhibitors behind metformin and SGLT2 inhibitors, limiting first-prescription access.
Strategic Opportunities
- Prediabetes protocol expansion:Metabolic disorder applications for acarbose in glucose intolerance populations remain underpenetrated across North African specialist networks.
- GCC regulatory harmonization:Gulf Cooperation Council centralized approval pathways reduce duplicate registration costs for sponsors with regional manufacturing footprints.
- Adherence coaching integration:Patient support programs that bundle glycemic monitoring with medication dispensing create stickier prescriber relationships.
Industry Challenges
- Endocrinology specialist scarcity:Gulf states and North Africa face acute shortages of diabetes specialists capable of managing complex combination therapy protocols.
- MOHAP registration sequencing complexity:UAE's regulator influences Gulf-wide launch timing, requiring sponsors to navigate interdependent national approval timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Alpha-Glucosidase Inhibitors Market |
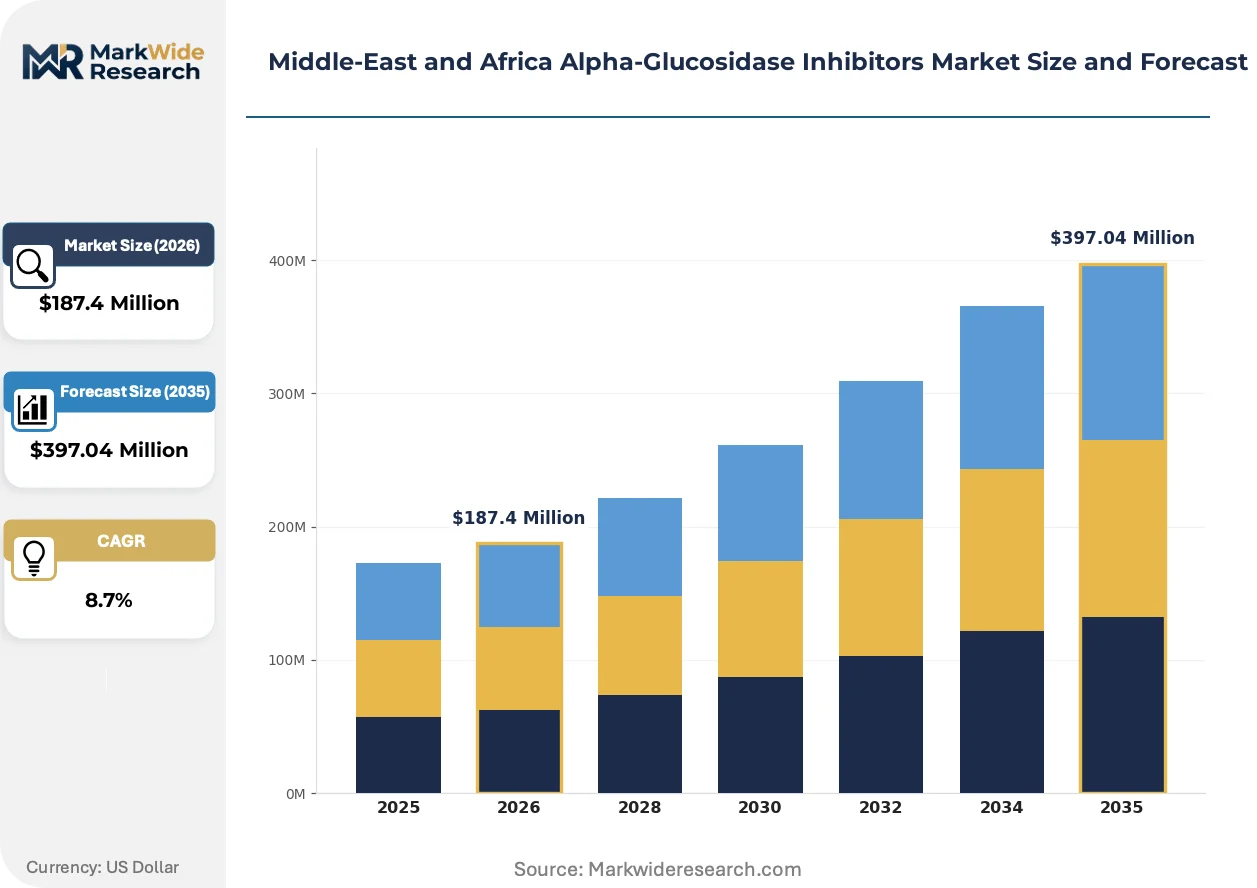
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acarbose, Miglitol, Voglibose, Others Delivery Mode: Oral, Injectable, Topical, Transdermal End User: Hospitals, Clinics, Homecare, Research Institutions Therapy Area: Diabetes Management, Metabolic Disorders, Glycemic Control, Others |
| Companies Covered | Sun Pharma, Unichem, Pfizer, Cipla, Torrent, Takeda, Glenmark Pharma, Lupin, Bayer, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Alpha-Glucosidase Inhibitors Market Shifts & Advancements
Digital therapeutics and connected monitoring devices are restructuring how alpha-glucosidase inhibitors integrate into longitudinal diabetes care. Three distinct vectors are reshaping competitive positioning and stakeholder value capture across the Middle-East and Africa.
Continuous glucose monitoring systems paired with mobile adherence applications are collapsing the traditional boundary between pharmaceutical dispensing and disease management services. Private hospital networks in the UAE and Saudi Arabia deploy these integrated platforms to reduce HbA1c variability in type 2 diabetes populations. The technology compresses reimbursement frameworks toward outcomes-based models that reward sustained glycemic control rather than prescription volume.
Gulf Cooperation Council regulatory harmonization timelines are accelerating centralized versus national approval strategies for multinational sponsors. SFDA and MOHAP alignment initiatives reduce redundant dossier submissions across Saudi Arabia, UAE, Kuwait, and Qatar. Generic manufacturers with regional tableting facilities capture first-mover advantage in streamlined registration pathways.
Homecare delivery channels are displacing hospital-based dispensing for chronic diabetes populations with stable glycemic profiles. Expatriate communities in Dubai, Riyadh, and Jeddah drive demand for medication delivery services that bypass traditional pharmacy retail. Egyptian and South African public systems lag this shift due to reimbursement infrastructure constraints.
Middle-East and Africa Alpha-Glucosidase Inhibitors Market Segmentation
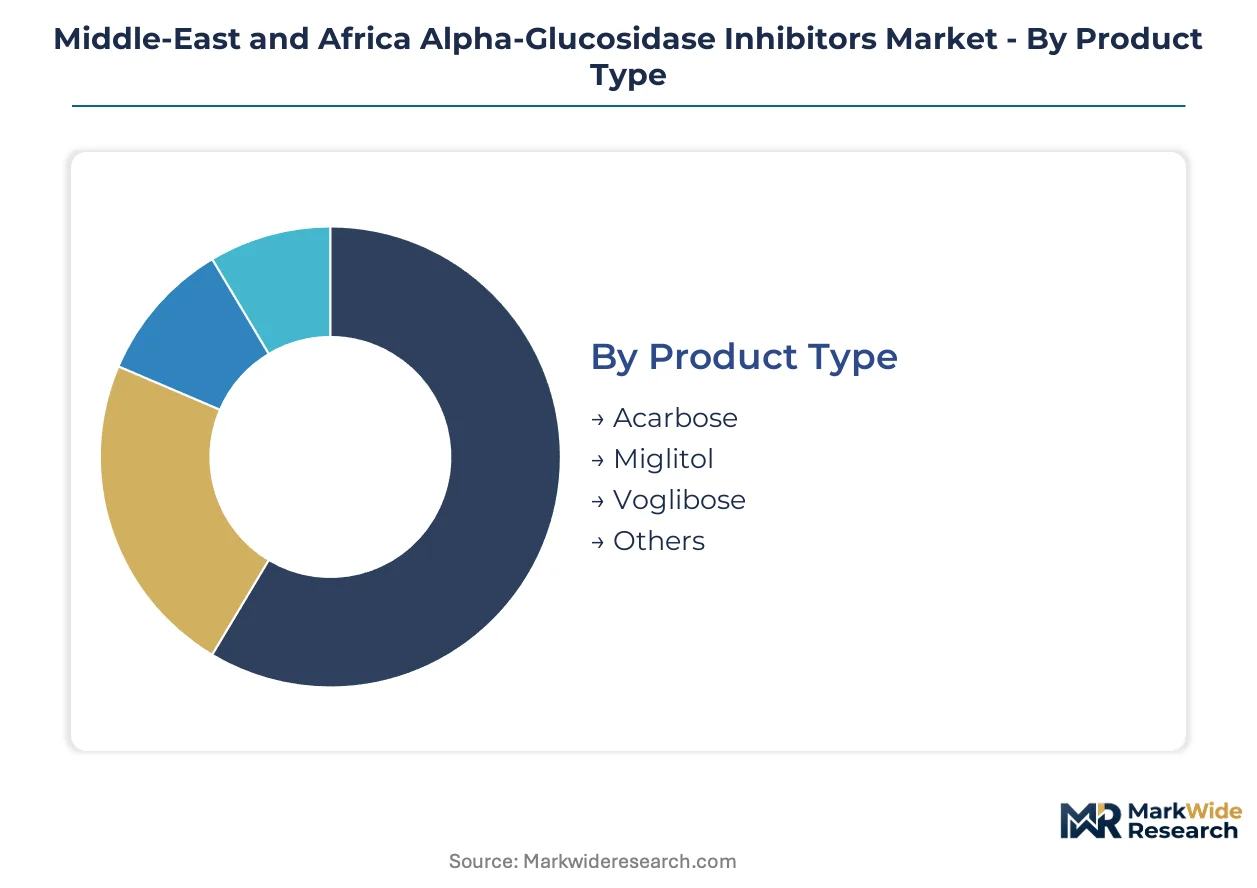
Alpha-glucosidase inhibitor markets fragment across four distinct dimensions that shape procurement patterns and margin structures. Product type concentration determines API sourcing strategies, while delivery mode evolution reflects shifting care settings across Gulf and North African healthcare systems.
Product Type:
Mature molecules dominate prescription volumes while newer alternatives carve specialist niches through differentiated safety profiles.
- Acarbose:The original alpha-glucosidase inhibitor with extensive post-marketing surveillance data and established reimbursement codes across Egyptian and South African public formularies. Hospital procurement centralization in Cairo and Johannesburg favors suppliers with demonstrated bioequivalence documentation.
- Voglibose:A newer-generation agent with reduced gastrointestinal adverse event rates that commands preference in UAE private hospital networks. Takeda's medical affairs investment sustains specialist prescriber loyalty despite higher per-unit acquisition costs.
- Miglitol:Absorbed systemically unlike other agents in this class, creating distinct pharmacokinetic considerations for endocrinologists managing complex polypharmacy.
- Others:Emerging biosimilar candidates and fixed-dose combinations under evaluation in Saudi SFDA pilot programs.
Acarbose retains volume leadership; Voglibose holds the steepest expansion curve.
Delivery Mode:
Cost tier differentiation separates institutional procurement from premium homecare channels.
- Oral:Tablet and capsule formulations constitute the overwhelming majority of dispensed volumes across Middle-East and Africa diabetes programs. Manufacturing standardization keeps unit economics favorable for public tender participation.
- Homecare:Medication delivery services bypass traditional pharmacy retail for stable chronic patients in Dubai, Riyadh, and Jeddah expatriate communities. This channel climbs the fastest as Gulf state healthcare privatization accelerates.
- Injectable:Limited relevance for alpha-glucosidase inhibitors specifically, though combination device development continues in European R&D centers.
- Topical:No commercialized formulations currently; research-stage transdermal absorption studies ongoing at select Saudi academic medical centers.
Oral administration commands institutional preference; Homecare delivery gains share fastest among Gulf expatriate populations.
End User:
Customer type segmentation reflects divergent reimbursement infrastructure maturity across the region's healthcare systems.
- Hospitals:Tertiary care centers in Saudi Arabia and Egypt's public hospital system anchor formulary placement decisions. Integrated glycemic monitoring protocols drive combination therapy adoption in Johannesburg academic medical centers.
- Homecare:Chronic disease management outside institutional settings expands rapidly where private insurance penetration supports subscription-based delivery models.
- Clinics:Primary care gatekeepers in North African markets initiate most acarbose prescriptions prior to specialist referral.
- Research Institutions:Academic medical centers in UAE and South Africa conduct prediabetes intervention protocol studies that may expand labeled indications.
Hospitals retain formulary control; Homecare demonstrates the steepest adoption trajectory.
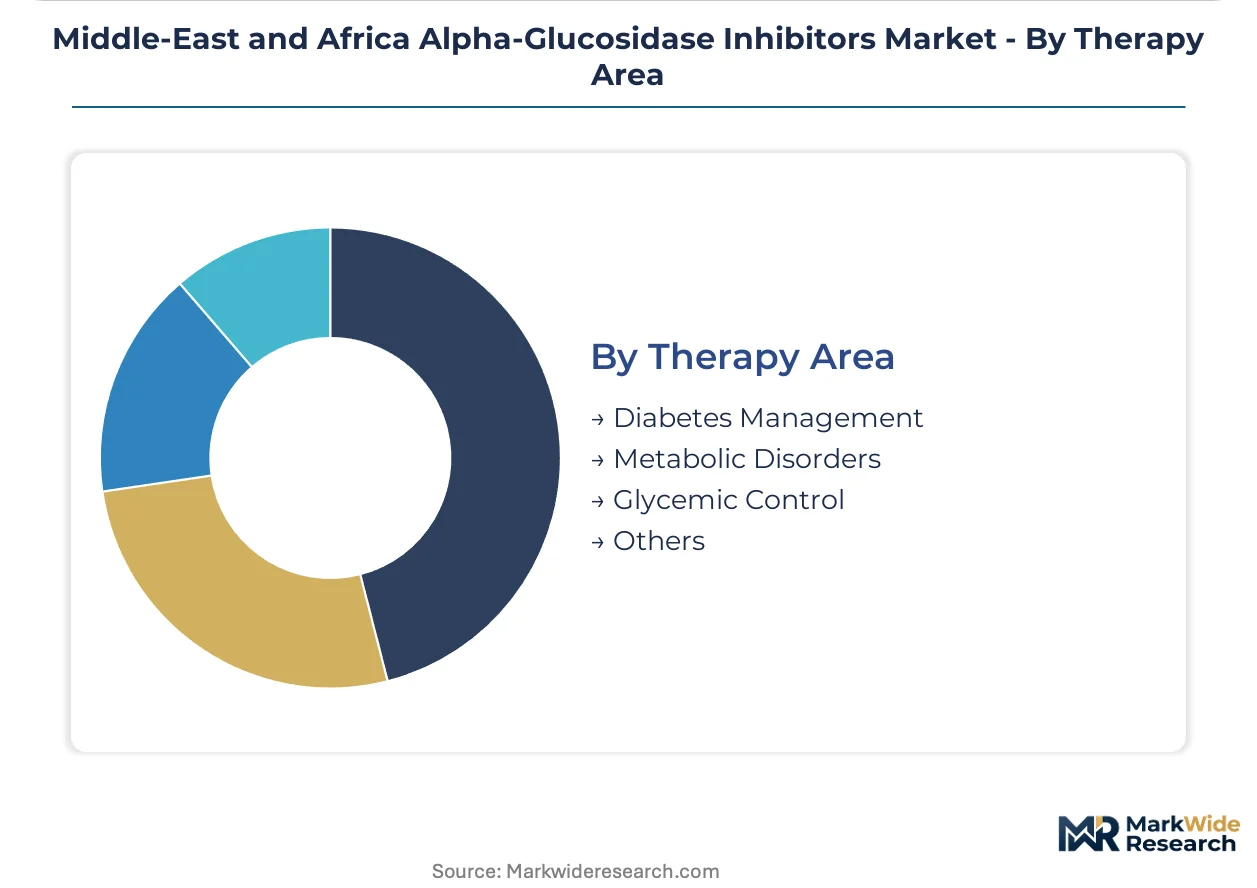
Therapy Area:
Application focus concentrates in diabetes while metabolic disorder protocols represent underpenetrated expansion territory.
- Diabetes Management:Type 2 diabetes combination therapy where postprandial glucose excursions persist despite metformin monotherapy. South African hospital-based programs standardize these agents in step-care algorithms.
- Metabolic Disorders:Prediabetes intervention protocols remain underdeveloped across North African specialist networks despite emerging evidence for acarbose in glucose intolerance populations.
- Glycemic Control:Post-meal hyperglycemia targeting in patients with contraindications to first-line agents.
- Others:Investigational applications in polycystic ovary syndrome and reactive hypoglycemia management.
Diabetes Management anchors revenue concentration; Metabolic Disorders present the most rapid expansion opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across the Middle-East and Africa diverge sharply: Gulf states favor premium voglibose in private hospital networks while North African public systems standardize cost-optimized acarbose through centralized procurement.
Saudi Arabia
Tertiary care centers in Riyadh and Jeddah drive demand for combination diabetes therapies with integrated glycemic monitoring. The Saudi Food and Drug Authority enforces stringent bioequivalence standards that elevate quality-tier generics into formulary preference positions. The Eastern Province's industrial corridor hosts tableting operations serving Gulf-wide distribution networks.
United Arab Emirates
Expatriate populations in Dubai and Abu Dhabi fuel rapid expansion of homecare delivery channels bypassing traditional pharmacy retail. The Ministry of Health and Prevention registration pathway influences Gulf-wide product launch sequencing for multinational sponsors. Private hospital networks deploy continuous glucose monitoring paired with mobile adherence applications.
Egypt
Public hospital procurement centralization in Cairo favors established acarbose suppliers with demonstrated local manufacturing capabilities. The Egyptian Drug Authority applies pricing controls that compress margin pools for imported finished formulations while stimulating domestic tableting operations. Alexandria's pharmaceutical industrial zone anchors regional supply for North African markets.
South Africa
Hospital-based diabetes management programs in Johannesburg academic medical centers expand adoption through integrated glycemic monitoring protocols. The South African Health Products Regulatory Authority shapes generic substitution patterns through bioequivalence enforcement. Cape Town's specialist endocrinology networks pilot prediabetes intervention protocols.
Nigeria
Urban centers Lagos and Abuja concentrate demand for oral antidiabetic agents amid rising type 2 diabetes prevalence. The national pharmaceutical regulator applies import licensing requirements that favor suppliers with established West African distribution infrastructure. Local pharmaceutical clusters in Ogun State expand generic formulation capabilities.
Middle-East and Africa Alpha-Glucosidase Inhibitors Market Competitive Landscape
Capability concentration sits with multinational specialists possessing legacy endocrinology franchises; scale advantage sits with Indian generic manufacturers leveraging cost-competitive API sourcing. The market structures around three tiers: originator brands with specialist prescriber relationships, quality-tier generics with bioequivalence documentation, and economy-tier suppliers competing on tender price. Two competitive moves dominate: backward integration into API production to secure supply continuity, and patient support program expansion bundling adherence coaching with medication dispensing.
Among Indian pharmaceutical conglomerates, Sun Pharma, Cipla, and Lupin occupy positions exemplifying the scale-driven generic archetype. These Mumbai- and Pune-based entities leverage established manufacturing bases to supply cost-competitive acarbose across North African tender markets. Takeda represents the originator-specialist archetype, sustaining prescriber loyalty through medical affairs investment in Gulf state endocrinology networks. Pfizer occupies an intermediate position, combining brand recognition with broad distribution infrastructure.
| Leading Market Players |
|---|
| Sun Pharma |
| Unichem |
| Pfizer |
| Cipla |
| Torrent |
| Takeda |
| Glenmark Pharma |
| Lupin |
| Bayer |
| Others |
Supply & Pricing Matrix
The Jebel Ali-Djibouti maritime corridor's freight cost volatility transmits directly into Egyptian public tender pricing, compressing margin pools for Indian API-dependent suppliers while amplifying price differentiation between Gulf private hospital premiums and North African economy-tier procurement.
Pricing Analysis
Long-term offtake contracts dominate Egyptian and South African public hospital procurement, locking in volume commitments that insulate established suppliers from spot API price swings. Pricing stratifies across premium voglibose in UAE private networks, standard acarbose with bioequivalence documentation in Saudi tertiary centers, and economy-tier unbranded generics in Nigerian urban clinics. Cost compression in North African tenders intensifies as Egypt's drug authority tightens pricing controls. Public procurement managers exhibit extreme price sensitivity; Gulf expatriate homecare subscribers prioritize adherence coaching bundles over unit cost.
Supply Chain Analysis
Extended payment terms from Egyptian and Nigerian public buyers strain working capital for regional distributors, forcing upstream financing burdens onto Indian API suppliers. Active pharmaceutical ingredient production draws from China, India, and limited European fermentation facilities. Acarbose API, starch excipients, and tablet coating materials constitute the critical input trinity. Single-source vulnerability concentrates in Chinese fermentation capacity for acarbose precursors. Distribution runs through Dubai's pharmaceutical free zone for Gulf-wide reach, with Lagos and Cairo serving as West and North African distribution hubs respectively.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Patient support programs bundling glycemic monitoring with medication dispensing expand faster than pure pharmaceutical sales, converting alpha-glucosidase inhibitors into service-attach platforms for chronic disease management.
For Market Incumbents: Pre-empt generic erosion in Saudi and UAE markets by embedding continuous glucose monitoring partnerships into formulary contracts before SFDA harmonization streamlines competitor entry. Backward integration into API fermentation capacity secures supply continuity against Chinese logistics disruptions. Capture specialist prescriber loyalty through endocrinology fellowship sponsorships that outlast patent cliffs. For New Entrants and Emerging Players: Pursue prediabetes intervention protocols across North African specialist networks where metabolic disorder applications remain underpenetrated. Target Egyptian local tableting partnerships to bypass import licensing barriers and access centralized public procurement volumes. Lead with bioequivalence documentation as the primary gating credential for Saudi formulary inclusion. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational pharmaceutical parents divesting legacy diabetes franchises amid portfolio prioritization toward GLP-1 agonists and SGLT2 inhibitors. Mid-tier Indian generics with captive API supply and established North African tender relationships offer the strongest 5-10 year viability profile. Monitor Gulf Cooperation Council regulatory harmonization implementation timelines as the critical inflection signal for regional manufacturing asset valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Fermentation | Captive acarbose precursor production insulates against Chinese supply chain disruptions affecting 80 percent of regional API. |
| Continuous Glucose Monitoring Partnership | UAE private hospital networks deploy integrated platforms that collapse reimbursement toward outcomes-based glycemic control metrics. |
| SFDA Bioequivalence Certification Investment | Rigorous Saudi standards elevate quality-tier generics into formulary preference positions ahead of GCC harmonization. |
| Homecare Delivery Channel Buildout | Dubai and Riyadh expatriate populations drive fastest-expanding chronic disease management outside institutional pharmacy retail. |
| Prediabetes Protocol Clinical Development | North African specialist networks remain underpenetrated for metabolic disorder applications despite emerging glucose intolerance evidence. |
Research Methodology
Initial hypotheses were tested against primary input from formulary directors at Saudi tertiary centers, Egyptian public hospital procurement managers, UAE endocrinology specialists, and Indian generic manufacturing executives, then refined through secondary validation against SFDA registration databases, EMA bioequivalence assessment reports, Egyptian Drug Authority pricing circulars, and Gulf Cooperation Council harmonization documentation. Bottom-up prescription volume modeling and top-down pharmaceutical expenditure triangulation anchored market sizing.
Demand-supply-balance framing structured the analytical approach across the analysis window, with segmentation dimensions spanning product type, delivery mode, end user category, and therapy area. CAGRs derived from fitted growth curves applied to hospital procurement volumes, homecare subscription trajectories, and metabolic disorder protocol expansion rates. Modeled inputs included SFDA approval timelines, Egyptian pricing control stringency indices, and Gulf expatriate population health insurance penetration.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese API suppliers vertically integrating into finished formulation exports would shift outcomes. Macroeconomic volatility in Egyptian pound valuation, regulatory acceleration of GCC centralized approval pathways, or breakthrough SGLT2 inhibitor cardiovascular outcomes data would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Equine Pharmaceuticals and Supplements Market
Pharmaceuticals
Global HER2 Antibodies Market
Pharmaceuticals
Global Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Anticonvulsants Market
Pharmaceuticals
Global Interstitial Cystitis Drugs Market
Pharmaceuticals
Acetylcholine Market
Pharmaceuticals
Mucosolvan (Ambroxol) Market
Pharmaceuticals
Canine Dilated Cardiomyopathy Drugs Market
Pharmaceuticals
Water for Injection Market
Pharmaceuticals
Contraceptive Drugs Market
Pharmaceuticals
Plasma-Derived Drugs Market
Pharmaceuticals
Thrombosis Drugs Market
Pharmaceuticals
Dual Antiplatelet Therapy Market
Pharmaceuticals
Mexico Dimenhydrinate Market
Pharmaceuticals
US Pharmacy Market
Pharmaceuticals
Global Doxorubicin Market