
 Wind Turbine Pitch System Sales Market | 2026-2036
Wind Turbine Pitch System Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Turbine Pitch System Sales Market Insights
Lifecycle service contracts for blade pitch maintenance and software-defined torque calibration is consolidating revenue streams around uptime guarantees rather than hardware shipments alone. Vestas Wind Systems leverages its global installed base to anchor long-term service agreements across Europe and North America. Siemens Gamesa Renewable Energy competes through integrated drivetrain-pitch offerings that reduce interface complexity for offshore developers. Bosch Rexroth AG specializes in precision hydraulic power units that still dominate retrofits of earlier turbine generations.
A wind turbine pitch system modulates blade angle to optimize aerodynamic torque and protect rotor assemblies from overspeed damage, typically employing electromechanical actuators rated for continuous duty cycles exceeding twenty years in salt-laden environments. Electric pitch systems now lead new installations as their superior response bandwidth and reduced environmental liability displace legacy hydraulic architectures. Offshore application segments command the fastest expansion trajectory given the disproportionate pitch load variability imposed by marine atmospheric boundary layers. Control systems within the technology dimension concentrate margin pools, since real-time pitch algorithms determine energy capture efficiency and structural fatigue accumulation.
The EU F-Gas Regulation and REACH chemical restrictions are compelling European manufacturers to eliminate hydraulic fluids with high global warming potential, while China's GB standards for wind turbine safety enforce redundant pitch battery backup requirements. The US FAA coordinates with offshore wind developers on radar interference mitigation, indirectly shaping turbine height and pitch control specifications near coastal military installations. Stakeholders must monitor evolving certification requirements for floating offshore platforms, where pitch system dynamics respond to six-degree-of-freedom platform motion rather than fixed-bottom stability assumptions.
Market Dynamics
The hydraulic-to-electric conversion mandate across European jurisdictions is compressing supplier margins while accelerating R&D cycles for electromechanical architectures. This structural shift forces incumbent hydraulic specialists to requalify entire product portfolios under REACH and F-Gas compliance timelines.
Growth Catalysts
- EU F-Gas Regulation:The refrigerant-phaseout mandate eliminates high-GWP hydraulic fluids, compelling turbine OEMs to specify electric pitch systems for new offshore installations.
- Offshore wind developers:Gigawatt-scale auctions in Germany, China, and the United States are concentrating demand for high-reliability pitch systems rated for marine atmospheric boundary layers.
- GB standards:China's mandatory redundant pitch battery backup requirements for wind turbine safety are expanding the addressable market for integrated power electronics.
Market Restraints
- Rare earth magnet supply concentration:Permanent magnet motors in electric pitch actuators depend on Chinese-processed neodymium, creating single-source vulnerability for European and North American manufacturers.
- Subsea cable installation bottlenecks:Offshore grid connection delays in the North Sea and US Atlantic coast are deferring turbine commissioning dates and pitch system revenue recognition.
- Hydraulic fluid compatibility:Bio-based hydraulic alternatives under development face viscosity instability across the -40°C to +60°C operating envelope required for Arctic offshore sites.
Strategic Opportunities
- Floating offshore platforms:Six-degree-of-freedom platform motion creates demand for predictive pitch algorithms that compensate for yaw-pitch-heave coupling unavailable in fixed-bottom designs.
- Lifecycle service contracts:Software-defined torque calibration and blade pitch maintenance agreements are consolidating revenue streams around uptime guarantees rather than hardware shipments.
- US Inflation Reduction Act:Domestic content bonuses for offshore wind components are incentivizing pitch system assembly localization in Maryland and Virginia port corridors.
Industry Challenges
- Electromechanical technician scarcity:Hydraulic-era service networks lack expertise in servo motor encoder calibration and power electronics troubleshooting for next-generation electric systems.
- Floating platform certification timelines:DNV and Bureau Veritas have yet to harmonize standards for pitch system fault response under combined wind-wave loading, delaying project financing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Turbine Pitch System Sales Market |
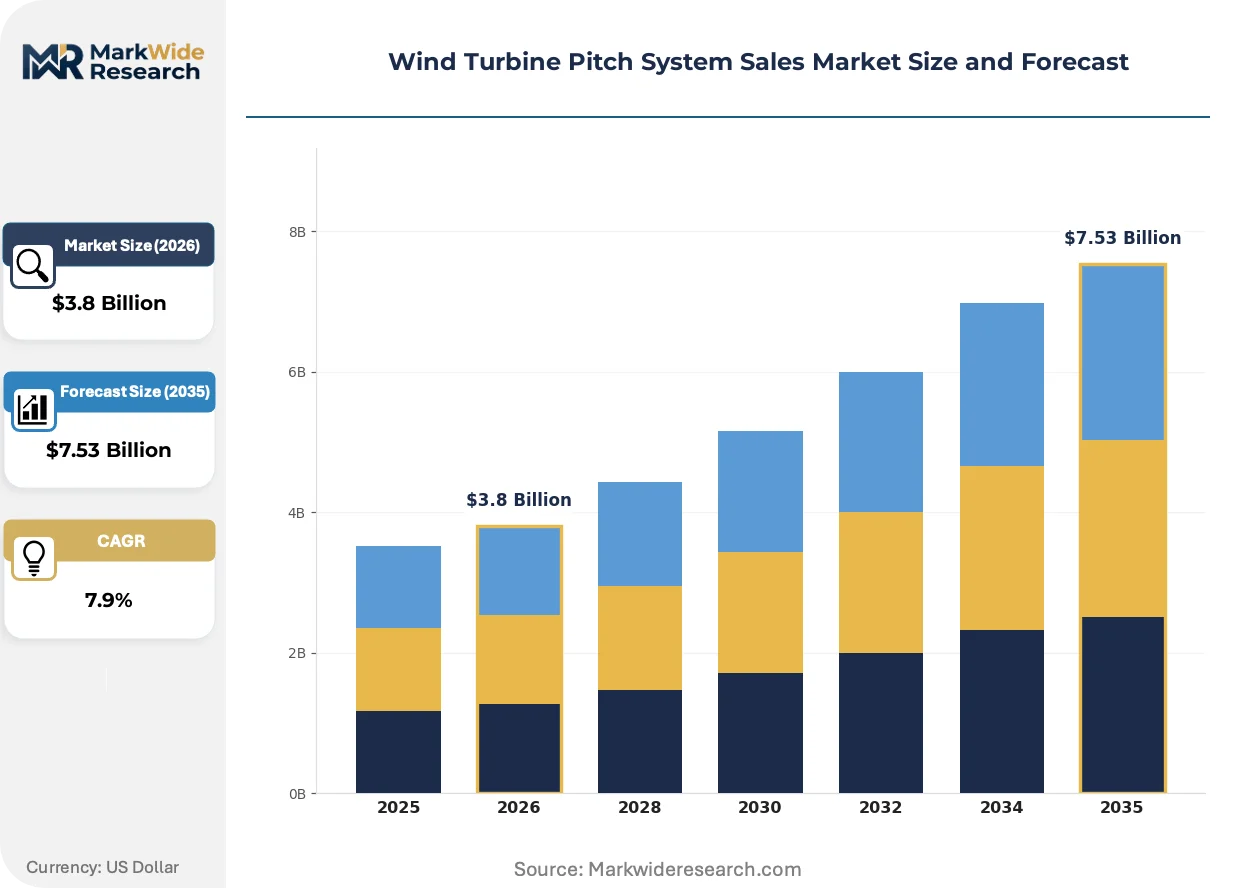
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.53 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Pitch Systems, Electric Pitch Systems, Mechanical Pitch Systems, Variable Pitch Systems End User: OEMs, Independent Power Producers, Utilities, Project Developers Technology: Electromechanical Systems, Control Systems, Sensor Technologies, Safety Mechanisms Application: Onshore, Offshore, Utility Scale, Distributed Generation |
| Companies Covered | Siemens Gamesa Renewable Energy, Vestas Wind Systems, General Electric, Bosch Rexroth AG, Moog Inc., ABB Ltd., KEB Automation, Eaton, Ingeteam S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Turbine Pitch System Sales Market Trends and Innovations
Digital twin integration is reshaping how pitch system performance gets validated before physical deployment. Real-time simulation environments now compress commissioning cycles while exposing failure modes invisible in component-level testing.
Predictive pitch control algorithms that modulate blade angle based on upstream LiDAR wind measurements are converging with turbine supervisory control architectures. Offshore developers in the North Sea are adopting these systems to reduce fatigue loading on blade root bearings. The convergence is compressing the competitive window for hydraulic retrofit specialists who lack embedded software capabilities.
The EU F-Gas Regulation's 2027 phaseout deadline for high-global-warming-potential fluids is forcing hydraulic power unit manufacturers to reformulate product lines. Industrial consequence includes accelerated qualification costs for bio-based alternatives. German and Danish turbine OEMs are responding by dual-sourcing electric and next-generation hydraulic systems to maintain supply continuity.
Service contract unbundling is separating hardware procurement from long-term maintenance obligations. Independent service providers in the United States are capturing blade pitch calibration work previously captive to OEM networks. This shift is most visible in Texas and Iowa, where post-warranty onshore fleets exceed ten thousand units and third-party technicians now hold specialized certifications for pitch battery replacement protocols.
Wind Turbine Pitch System Sales Market Segmentation
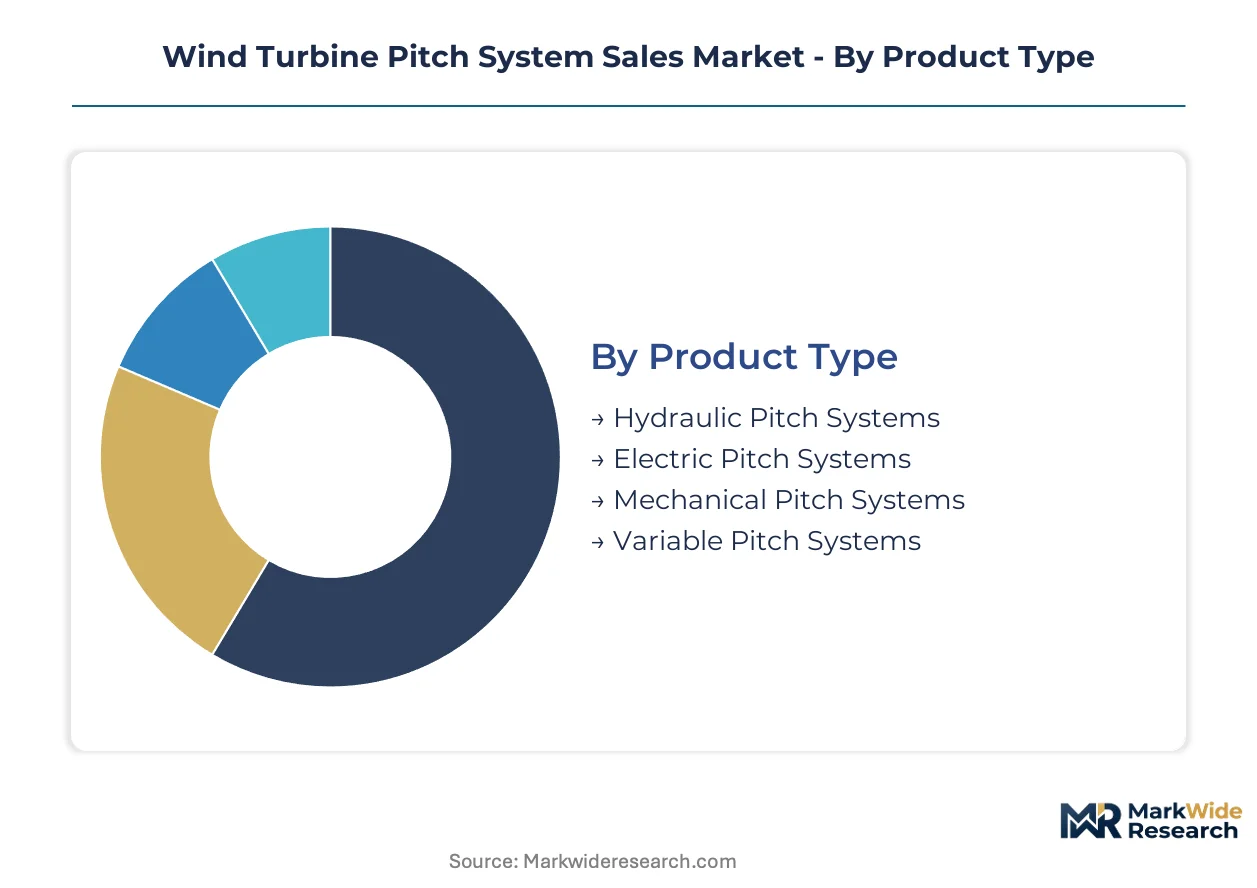
Pitch system architectures diverge sharply across turbine vintages and deployment environments. Procurement patterns in this market track the hydraulic-to-electric transition while accommodating divergent maintenance capabilities across customer types.
Product Type:
Customization intensity varies from fully proprietary hydraulic units to commoditized electromechanical modules.
- Electric Pitch Systems:Servo motors with integrated power electronics deliver sub-second blade angle response for variable wind conditions. Demand concentrates in Germany and Denmark where Vestas and Siemens Gamesa specify all-electric architectures for offshore installations rated above 8 MW. The EU F-Gas Regulation accelerates displacement of legacy alternatives.
- Hydraulic Pitch Systems:Proportional valve-controlled actuators with accumulators provide high force density for retrofits of turbines commissioned before 2015. Remaining demand clusters in Texas and Iowa where independent service providers maintain bio-based fluid inventories for post-warranty fleets.
- Mechanical Pitch Systems:Centrifugal governors and spring-return mechanisms persist in small-scale turbines below 100 kW.
- Variable Pitch Systems:Hybrid architectures combining hydraulic force generation with electric valve control serve floating platform prototypes.
Most installed capacity flows through Electric Pitch Systems. Expansion is steepest in Variable Pitch Systems.
End User:
Contract structure and technical specification authority shift dramatically across the procurement chain.
- OEMs:Turbine manufacturers integrate pitch systems into nacelle assemblies during original fabrication, specifying encoder resolution and battery backup protocols. Siemens Gamesa and Vestas source electromechanical actuators through multi-year frame agreements with Bosch Rexroth and in-house divisions.
- Utilities:Vertically integrated power companies in Germany and China negotiate lifecycle service contracts covering blade pitch calibration, battery replacement, and control software updates across multi-gigawatt portfolios.
- Independent Power Producers:Non-utility developers in Texas and Oklahoma purchase pitch maintenance separately from hardware procurement, unbundling service obligations previously captive to OEM networks.
- Project Developers:Offshore consortia in Maryland and Virginia specify pitch system uptime guarantees as condition precedent to project financing, transferring operational risk to subsystem suppliers.
Volume concentrates with OEMs. Margin expansion is fastest among Project Developers.
Technology:
Value capture migrates from mechanical components toward embedded intelligence and predictive algorithms.
- Control Systems:Real-time pitch algorithms determine energy capture efficiency and structural fatigue accumulation. Offshore developers in the North Sea deploy LiDAR-integrated predictive control to reduce blade root bearing loads. Software-defined torque calibration commands premium pricing over hardware-only procurement.
- Electromechanical Systems:Permanent magnet servo motors with resolver feedback achieve positioning accuracy within 0.1 degrees. Chinese manufacturers face neodymium supply concentration risk as domestic processing dominates rare earth magnet supply.
- Sensor Technologies:Blade-mounted strain gauges and accelerometers feed vibration data to supervisory control architectures.
- Safety Mechanisms:Redundant battery backup systems satisfy GB standards for emergency feathering during grid loss events.
Revenue pools deepest in Control Systems. Sensor Technologies are climbing the fastest.
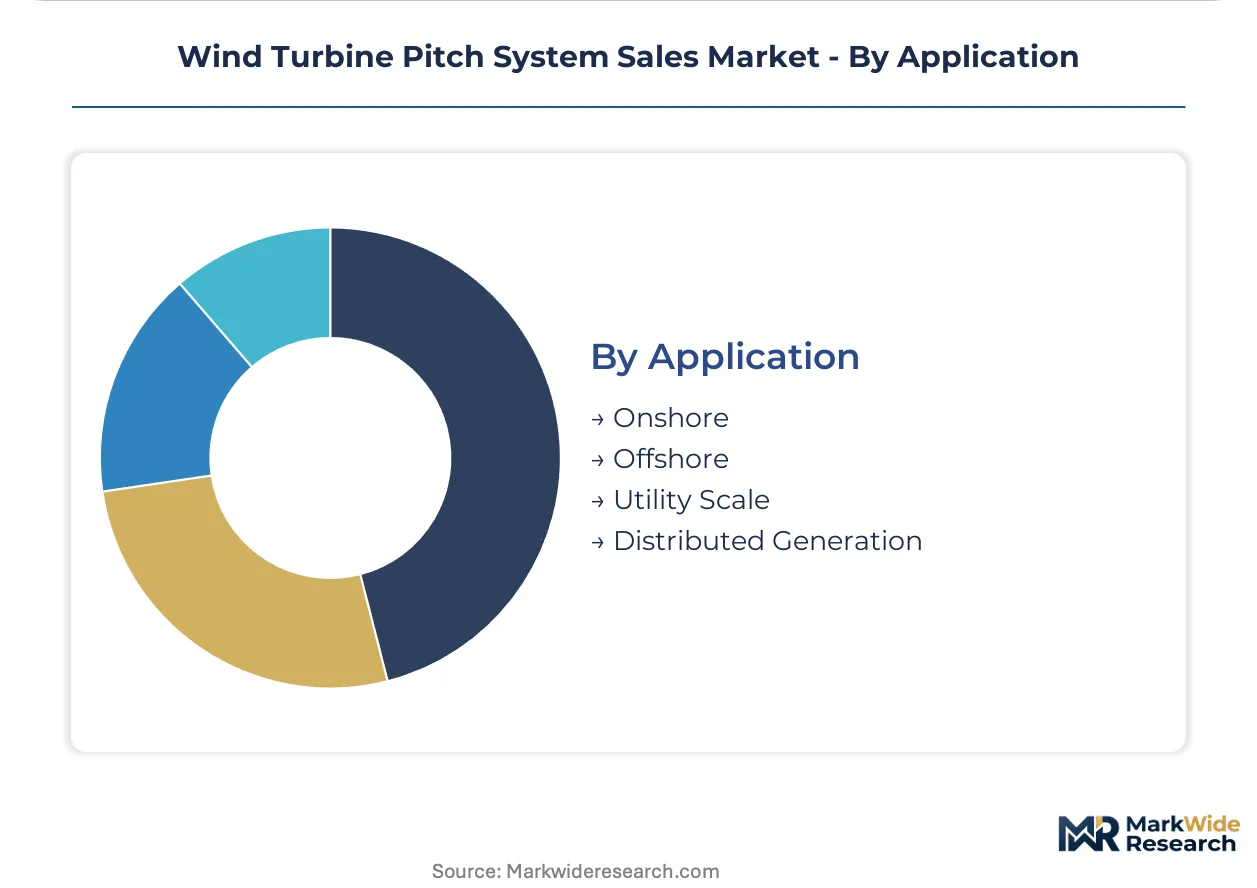
Application:
Environmental exposure severity and accessibility constraints reshape reliability specifications.
- Offshore:Marine atmospheric boundary layers impose disproportionate pitch load variability. Salt-laden environments demand sealed enclosures rated for twenty-year continuous duty. Floating platforms require six-degree-of-freedom motion compensation unavailable in fixed-bottom designs.
- Utility Scale:Turbines exceeding 5 MW rating specify electric pitch systems exclusively. Gigawatt-scale auctions in Germany, China, and the United States concentrate procurement volume for high-reliability architectures.
- Onshore:Established fleets in Texas and Iowa drive aftermarket demand for battery replacement and encoder recalibration services.
- Distributed Generation:Small-scale turbines below 1 MW retain mechanical or simplified hydraulic pitch for cost containment.
Most new capacity investment flows through Offshore. Steepest expansion trajectory belongs to Utility Scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands a larger share of offshore pitch system procurement than China, yet Chinese domestic suppliers are capturing an expanding portion of onshore utility-scale installations through cost-optimized electromechanical architectures.
Germany
Offshore auctions in the North Sea and Baltic Sea are driving demand for 15 MW+ turbines requiring sub-second pitch response. The EU F-Gas Regulation's 2027 phaseout deadline accelerates hydraulic-to-electric conversions across existing fleets. Industrial concentration centers on Hamburg and Bremen port corridors, where Vestas and Siemens Gamesa operate blade assembly facilities integrated with pitch system testing laboratories.
China
GB standards mandating redundant pitch battery backup systems are expanding the addressable market for integrated power electronics manufacturers. The dual carbon goals framework prioritizes domestic turbine component sourcing through preferential procurement policies. Yangtze River Delta clusters around Shanghai and Jiangsu province host the majority of pitch motor and encoder production capacity serving both domestic OEMs and export markets.
United States
The US Inflation Reduction Act's domestic content bonuses are incentivizing pitch system assembly localization in Maryland and Virginia port corridors. FAA coordination requirements on radar interference indirectly shape turbine height specifications affecting pitch control dynamics near coastal military installations. Atlantic coast offshore lease areas from Massachusetts to North Carolina are concentrating project developer procurement for floating platform-compatible architectures.
Denmark
Vestas Wind Systems anchors long-term service agreements across its global installed base from Copenhagen headquarters, consolidating lifecycle revenue streams. REACH chemical restrictions complement F-Gas mandates in eliminating high-GWP hydraulic fluids from North Sea installations. Esbjerg port infrastructure supports the largest European offshore wind marshaling yard, with dedicated quayside facilities for pitch system pre-commissioning and blade integration.
United Kingdom
Round 4 and Round 5 offshore leasing rounds are procuring pitch systems rated for 60-year design lives including major component replacement cycles. Health and Safety Executive regulations on machinery safety enforce redundant pitch brake architectures for turbines exceeding 10 MW rating. Humber region industrial clusters around Hull and Grimsby host blade manufacturing and pitch system maintenance facilities serving Dogger Bank and Hornsea developments.
Wind Turbine Pitch System Sales Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with turbine OEMs integrating proprietary pitch architectures while independent suppliers capture aftermarket service volumes. The market structure tilts toward consolidation at the premium tier, where integrated drivetrain-pitch offerings reduce interface complexity for offshore developers. Three archetypes dominate: full-system OEMs with captive production, precision motion control specialists supplying electromechanical actuators, and hydraulic power unit manufacturers defending retrofit positions. Competitive moves concentrate on strategic partnerships for floating platform qualification and geographic expansion through port corridor assembly localization.
Within the full-system OEM tier, Siemens Gamesa Renewable Energy and Vestas Wind Systems occupy positions defined by global installed base scale and long-term service agreement penetration. Among precision motion control suppliers, Moog Inc. exemplifies the electromechanical actuator specialist archetype, while Bosch Rexroth AG represents hydraulic-era incumbents navigating F-Gas compliance transitions. These three companies anchor the competitive structure through divergent technology legacies and customer relationship models spanning original equipment procurement and lifecycle maintenance.
| Leading Market Players |
|---|
| Siemens Gamesa Renewable Energy |
| Vestas Wind Systems |
| General Electric |
| Bosch Rexroth AG |
| Moog Inc. |
| ABB Ltd. |
| KEB Automation |
| Eaton |
| Ingeteam S.A. |
| Others |
Pricing and Supply Chain Analysis
EU F-Gas Regulation compliance deadlines are compressing procurement timelines for electric pitch systems, forcing turbine OEMs to absorb qualification costs while suppliers reprice legacy hydraulic inventories for accelerated phaseout. This demand-side regulatory pressure concentrates buyer power among Vestas and Siemens Gamesa, who leverage frame agreement volumes to extract cost concessions from electromechanical actuator specialists.
Pricing Analysis
Capacity additions in China are reshaping price floors for permanent magnet servo motors, eroding the premium that European suppliers commanded for resolver-feedback positioning systems. Three-tier pricing structure across marine-certified, standard industrial, and retrofit economy levels differentiates offerings, with certification grade and after-sales service bundling as primary price drivers. Cost compression in economy-tier hydraulic retrofits is intensifying because bio-based fluid R&D costs remain unrecovered. Independent service providers in Texas exhibit highest price sensitivity, while offshore project developers in Germany prioritize uptime guarantees over unit cost.
Supply Chain Analysis
DNV and Bureau Veritas certification requirements for floating platform fault response are gating supplier qualification timelines and concentrating procurement among pre-approved electromechanical specialists. Manufacturing gravity centers on China, Germany, and Denmark, with Chinese Yangtze River Delta clusters feeding domestic OEMs and export markets. Neodymium permanent magnets, lithium-ion backup batteries, and precision-machined gearboxes constitute critical input dependencies. Single-source vulnerability in Chinese-processed rare earth magnet supply anchors the dominant structural risk. Distribution runs through port corridor assembly facilities in Maryland, Virginia, and Esbjerg for offshore project integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder, with offshore wind auction pipelines across Germany, China, and the United States providing visible demand visibility that supports long-term service contract economics.
For Market Incumbents: Extend lifecycle service agreement penetration across post-warranty fleets in Texas and Iowa before independent providers capture blade pitch calibration work. Deepen backward integration into permanent magnet motor production to offset neodymium supply concentration risk from Chinese processors. Prioritize DNV floating platform certification investment ahead of Bureau Veritas harmonization to secure project developer procurement for six-degree-of-freedom motion compensation architectures. For New Entrants and Emerging Players: Direct-to-turbine-OEM software licensing offers the lowest barrier entry path, bypassing the capital intensity of electromechanical actuator manufacturing. Target predictive pitch algorithm development for LiDAR-integrated control systems, where embedded software capabilities remain scarce among hydraulic-era incumbents. Pursue white-space in third-party battery replacement protocols for GB-standard redundant backup systems, where certification gaps limit incumbent responsiveness. For Investors and Strategic Acquirers: Asymmetric upside sits with precision motion control specialists possessing embedded software capabilities and floating platform qualification progress. Five-to-ten year viability hinges on electromechanical architecture dominance displacing residual hydraulic retrofit demand. Monitor DNV-Bureau Veritas standard harmonization timelines as the critical inflection signal for project financing unlock and pitch system supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Electromechanical Architecture Transition | EU F-Gas Regulation mandates accelerate displacement of hydraulic systems in North Sea installations. |
| Floating Platform Certification Investment | DNV qualification for six-degree-of-freedom motion compensation unlocks Dogger Bank and Atlantic coast procurement. |
| Lifecycle Service Contract Expansion | Vestas and Siemens Gamesa anchor revenue streams around uptime guarantees rather than hardware shipments alone. |
| Domestic Content Assembly Localization | US Inflation Reduction Act bonuses incentivize Maryland and Virginia port corridor manufacturing footprint. |
| Predictive Control Algorithm Development | LiDAR-integrated pitch modulation reduces blade root bearing fatigue for North Sea offshore developers. |
Research Methodology
Coverage spans Germany, China, the United States, Denmark, and the United Kingdom, with primary inputs from each market. Primary interviews with turbine OEM procurement directors, offshore project developer engineering leads, independent service provider technicians, and electromechanical actuator R&D heads combined with secondary validation from SEC filings, EIA project databases, FERC interconnection queues, and EU auction award announcements. Bottom-up installation forecasts and top-down supplier revenue triangulation anchored market sizing across the analysis window.
Rate-of-change decomposition structured the analytical framework, disaggregating growth into offshore capacity additions, hydraulic-to-electric replacement cycles, and floating platform penetration. Segmentation dimensions spanned product architecture, end-user contract structure, control system technology, and application environment severity. CAGRs derived from regression against turbine commissioning schedules and pitch system replacement curves, with neodymium price volatility and subsea cable installation bottlenecks as industry-specific forecast sensitivity inputs.
Regulatory timeline acceleration, rare earth supply disruption, and floating platform certification delay are the dominant revision risks to modeled outcomes. Forecasts embed assumptions regarding F-Gas phaseout adherence and GB standard enforcement continuity. A model refresh is warranted upon material change in DNV-Bureau Veritas harmonization progress or US offshore lease auction award velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Power Forgings Market
Wind Energy Systems
North America Wind Power Equipment Market
Wind Energy Systems
Wind Turbine Scrap Market
Wind Energy Systems
Wind Energy Rescue System Market
Wind Energy Systems
Global Wind Power Equipment Market
Wind Energy Systems
North America Large Wind Turbine Market
Wind Energy Systems
Wind Blades NDT Market
Wind Energy Systems
Wind Turbine Market
Wind Energy Systems
Thailand Wind Energy Market
Wind Energy Systems
Wind Turbine Shaft Market
Wind Energy Systems
Wind Power Converter Systems Market
Wind Energy Systems
Wind Turbine Operation and Maintenance Market
Wind Energy Systems
Quiet Wind Turbine Market
Wind Energy Systems
United States Wind Energy Market
Wind Energy Systems
United Kingdom Wind Energy Market
Wind Energy Systems
Wind Energy Equipment Logistics Market