
 United States Dry-Type Transformer Market | 2026-2036
United States Dry-Type Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
United States Dry-Type Transformer Market Analytics
Domestic transformer fabrication is restructuring around resin-casting and vacuum impregnation capacity additions in the Midwest and Southeast. GE Vernova leverages its integrated power systems portfolio to anchor large industrial and utility contracts across Texas and the Southeast. ABB sustains technology leadership in cast resin designs through continuous R&D investment in coil geometry optimization. Siemens Energy competes aggressively in the medium-voltage segment, where data center electrification drives order backlogs.
A dry-type transformer relies on air or solid insulation rather than liquid dielectrics, typically employing epoxy resin or vacuum pressure impregnated windings rated from low voltage through medium voltage classes up to 72.5 kV, with core assemblies built from grain-oriented electrical steel to minimize no-load losses. Cast resin transformers dominate commercial and indoor installations where fire safety codes prohibit oil-filled alternatives, while vacuum pressure impregnated units occupy cost-sensitive industrial applications. The utility end-user segment generates the deepest margin pools as grid modernization and renewable interconnection projects specify high-reliability designs with extended thermal ratings.
The Department of Energy enforces minimum efficiency standards under 10 CFR 431, while NEMA and IEEE publish design and testing protocols that determine product eligibility for federal procurement and utility rebate programs. State-level building codes in California and New York incorporate these standards into mandatory efficiency requirements for new commercial construction. Stakeholders must monitor pending DOE rulemakings on distribution transformer efficiency, as revised loss limits would force core material and design changes across the supplier base.
Market Dynamics
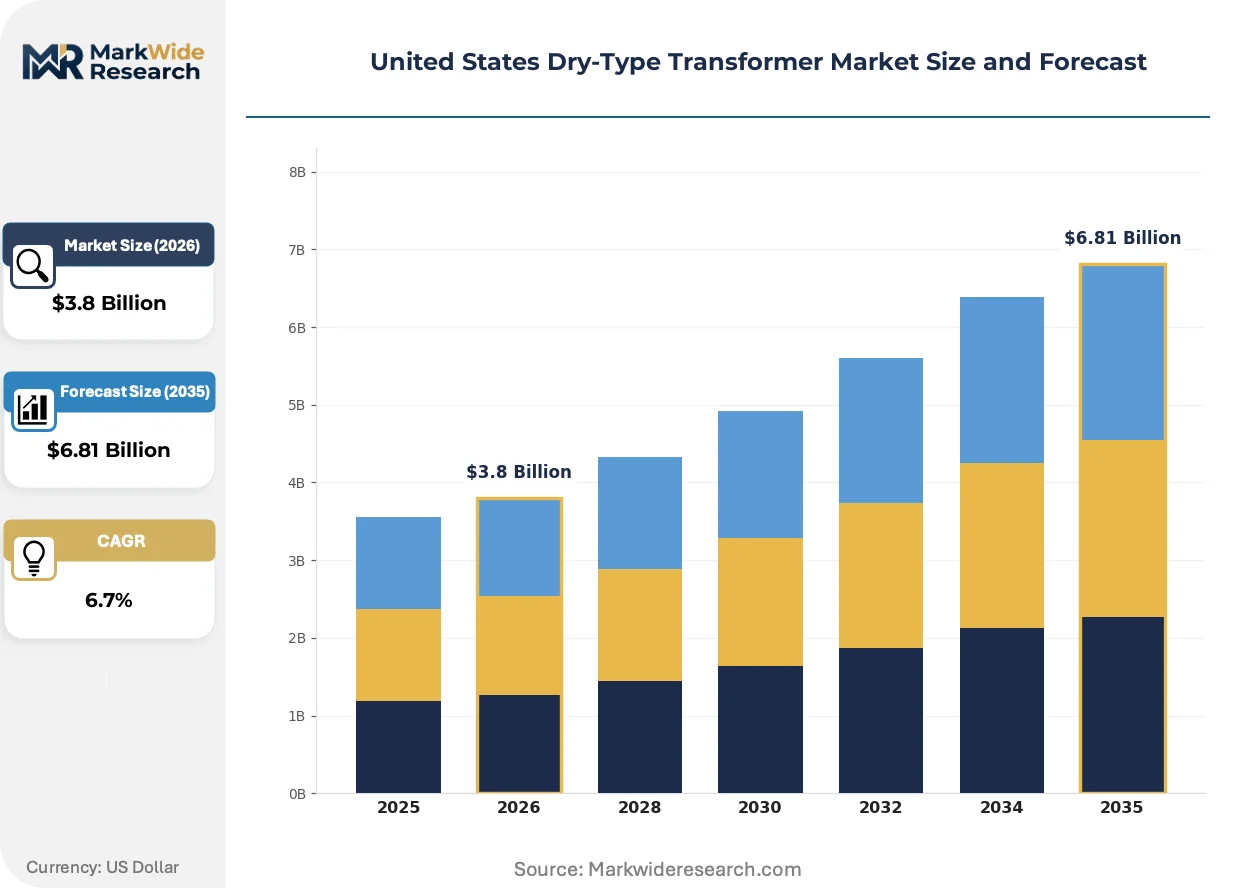
The United States dry-type transformer market is restructuring around efficiency mandates and data center electrification, with the Department of Energy's pending distribution transformer rulemaking forcing core material transitions and manufacturing line reconfigurations across domestic fabricators.
Growth Catalysts
- Data Center Electrification:Hyperscale operators in Virginia and Texas are procuring medium-voltage dry-type units at volumes that absorb excess casting capacity and justify resin plant expansions in the Southeast.
- 10 CFR 431 Efficiency Mandates:The DOE's minimum efficiency standards are phasing out conventional core designs and redirecting R&D budgets toward amorphous metal and advanced grain-oriented electrical steel formulations.
- Utility-Scale Solar Interconnection:Pad-mounted dry-type installations for solar farm grid connections in the Southeast are consuming production slots and extending order backlogs through 2026.
Market Restraints
- Electrical Steel Supply Concentration:Domestic grain-oriented electrical steel production is concentrated among a limited supplier base, exposing fabricators to allocation risk and volatile input pricing.
- Cast Resin Material Costs:Epoxy resin and hardener formulations depend on petrochemical feedstocks whose pricing tracks crude oil volatility, compressing margin predictability for cast coil manufacturers.
- Technical Performance Ceilings:Air-insulated designs face thermal dissipation limits above 72.5 kV that constrain applications in high-voltage transmission substations where oil-filled units retain dominance.
Strategic Opportunities
- Texas Industrial Corridor Expansion:Petrochemical and semiconductor fabrication projects along the Gulf Coast are specifying explosion-proof dry-type units for hazardous location installations, creating a premium product tier.
- Smart Grid Integration:Convergence of dry-type transformers with power electronics and embedded sensors is enabling predictive maintenance contracts and recurring revenue streams for OEM service divisions.
- California Building Electrification Codes:The state's mandate for zero-emission new construction is prohibiting oil-filled transformers in commercial buildings and accelerating specification of cast resin alternatives in urban cores.
Industry Challenges
- Vacuum Impregnation Technician Shortage:The specialized craft skills required for VPI coil processing are aging out of the workforce faster than apprenticeship programs in the Midwest and Southeast can replenish them.
- NEMA/IEEE Certification Timelines:Extended testing protocols for thermal class upgrades and short-circuit withstand certifications are delaying new product introductions and locking in incumbent design advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Dry-Type Transformer Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cast Resin, Vacuum Pressure Impregnated, Encapsulated, Non-Encapsulated End User: Commercial, Industrial, Residential, Utility Installation Type: Indoor, Outdoor, Wall-Mounted, Floor-Mounted Power Rating: Low Voltage, Medium Voltage, High Voltage, Others |
| Companies Covered | GE Vernova, ABB, Siemens Energy, Eaton, Schneider Electric, Hitachi Energy, Hammond Power Solutions, TMC Transformers, ELSCO Transformers, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Dry-Type Transformer Market Evolving Landscape
Transformer design is converging around digital monitoring capabilities and advanced insulation systems that extend thermal ratings while satisfying stricter loss limits. Three developments are compressing competitive timelines and reshaping procurement criteria.
Amorphous metal core technology is consolidating its position in low-loss distribution applications by reducing no-load losses by 60-70% versus conventional silicon steel. Data center operators and utility renewable interconnection projects are specifying amorphous designs despite 15-20% cost premiums to meet corporate sustainability targets and loss-capitalization formulas. This consolidation is compressing market share for legacy core suppliers unable to source amorphous ribbon or license relevant winding techniques.
The EPA's updated ENERGY STAR specifications for distribution transformers are tightening loss limits and disqualifying conventional designs from federal procurement eligibility. Manufacturers are responding by redesigning core geometries and increasing conductor cross-sections to reduce winding losses, with the most aggressive design changes concentrated in the 25-500 kVA range that dominates commercial building applications. State energy offices in California and New York are incorporating these federal standards into mandatory rebate program requirements, accelerating design turnover.
Buyer consolidation among hyperscale data center operators is compressing supplier qualification cycles and unbundling after-sales service from equipment procurement. Amazon Web Services, Microsoft, and Google are negotiating multi-year framework agreements that specify thermal monitoring, predictive analytics, and guaranteed replacement timelines as standard terms. This behavioral shift is visible most acutely in Northern Virginia's Loudoun County, where transformer procurement now flows through consolidated engineering-procurement-construction contractors rather than direct OEM relationships.
United States Dry-Type Transformer Market Segmentation
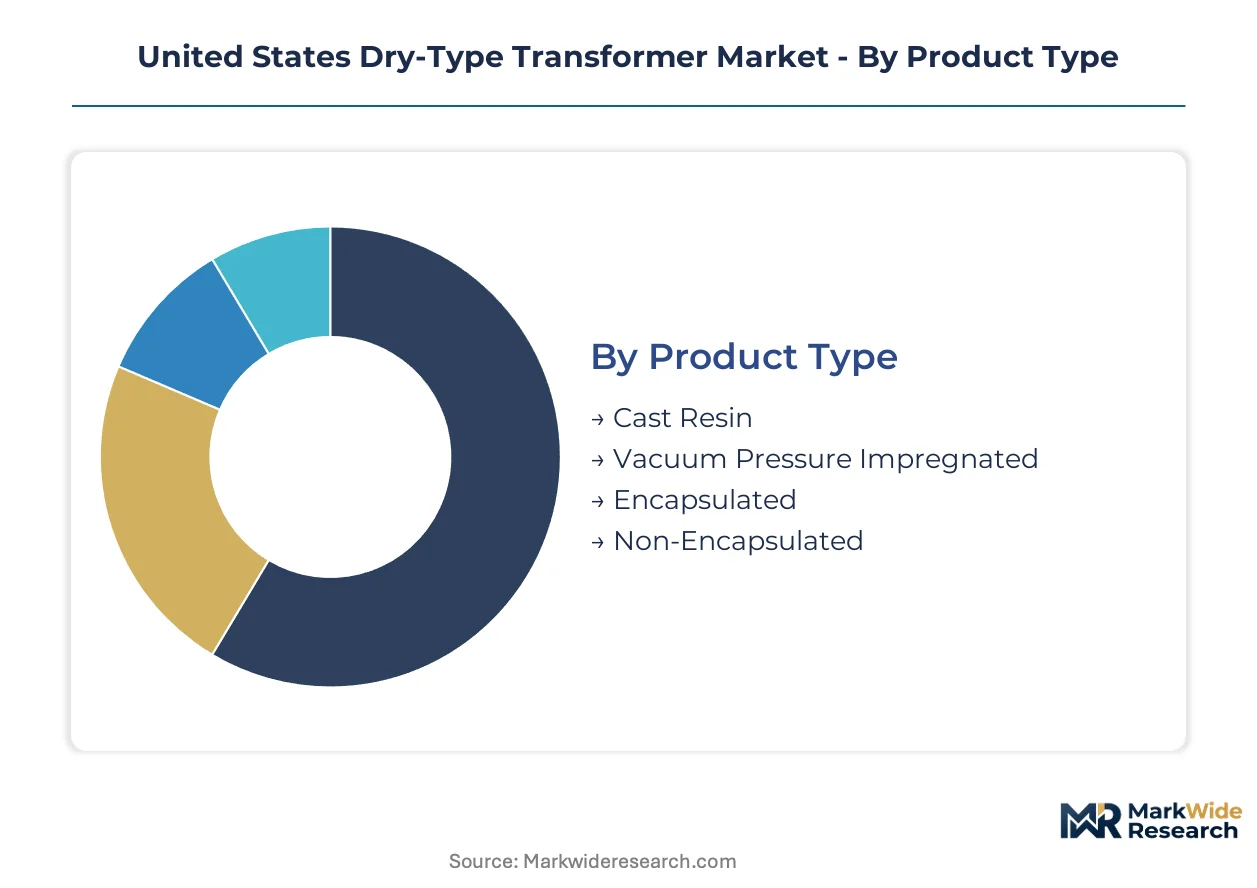
Product architecture, installation environment, and buyer power concentration create distinct margin pools across the United States dry-type transformer landscape. Specification engineers weigh thermal ratings against fire codes and lifecycle loss economics when selecting between cast resin and vacuum-impregnated alternatives.
Product Type:
Procurement teams segment supplier bids first by insulation system maturity and total cost of ownership over 20-year depreciation schedules.
- Cast Resin:Epoxy resin vacuum-cast around windings creates a monolithic insulation block rated for Class F or H thermal limits with zero fire propagation risk. Data center operators in Loudoun County and utility-scale solar developers in the Southeast specify cast resin designs to satisfy indoor fire codes and minimize insurance premiums.
- Vacuum Pressure Impregnated:Windings receive multiple varnish cycles under vacuum and pressure cycles, delivering Class B or F ratings at 15-25% lower first cost than cast equivalents. Industrial facilities in the Midwest favor VPI units for cost-sensitive motor drive applications where outdoor installation avoids stringent indoor fire ratings.
- Encapsulated:Silica sand or epoxy compounds fill the casing around conventional windings, bridging performance between cast resin and VPI for harsh-environment outdoor installations.
- Non-Encapsulated:Open-ventilated designs with air gaps between windings serve temporary construction power and low-cost commercial tenant improvements where initial capital outlay dominates specification criteria.
Volume sits with Cast Resin; growth tilts toward Vacuum Pressure Impregnated.
End User:
Contracting authority and loss-capitalization methodology separate buyers into four distinct specification regimes with divergent technical priorities.
- Commercial:Building owners and electrical contractors specify dry-type units for office towers, retail centers, and institutional facilities where indoor fire codes prohibit oil-filled alternatives. California Title 24 building electrification mandates are accelerating cast resin specifications in urban cores.
- Industrial:Manufacturing plants and process facilities prioritize reliability and short-circuit withstand capability over first cost, with petrochemical clusters along the Texas Gulf Coast demanding explosion-proof variants.
- Residential:Multi-family housing developers and utility distribution departments specify compact pad-mounted or indoor units for apartment complexes and suburban subdivisions where load density supports centralized transformation.
- Utility:Investor-owned utilities and independent power producers generate the deepest margin pools through renewable interconnection projects and grid modernization programs specifying extended thermal ratings and 30-year service life guarantees.
Revenue concentrates with Utility; specification activity is climbing fastest in Commercial.
Installation Type:
Physical mounting constraints and environmental exposure determine enclosure ratings, cooling method, and maintenance access requirements.
- Indoor:Ventilated or sealed designs for electrical rooms and building basements where fire separation and noise attenuation matter. Data center white spaces in Northern Virginia and Dallas-Fort Worth absorb the highest indoor unit volumes.
- Outdoor:Weatherproof enclosures with filtered ventilation or sealed tanks for solar farm substations and industrial yard distribution where ambient temperature swings demand derating calculations.
- Wall-Mounted:Compact kVA-rated units for commercial tenant spaces and light industrial workshops where floor space constraints favor vertical installation.
- Floor-Mounted:Heavy-duty frames for medium-voltage substations and large industrial loads requiring vibration isolation and rolling-element bearings for seismic compliance.
Order backlog depth favors Indoor; expansion is sharpest in Outdoor.
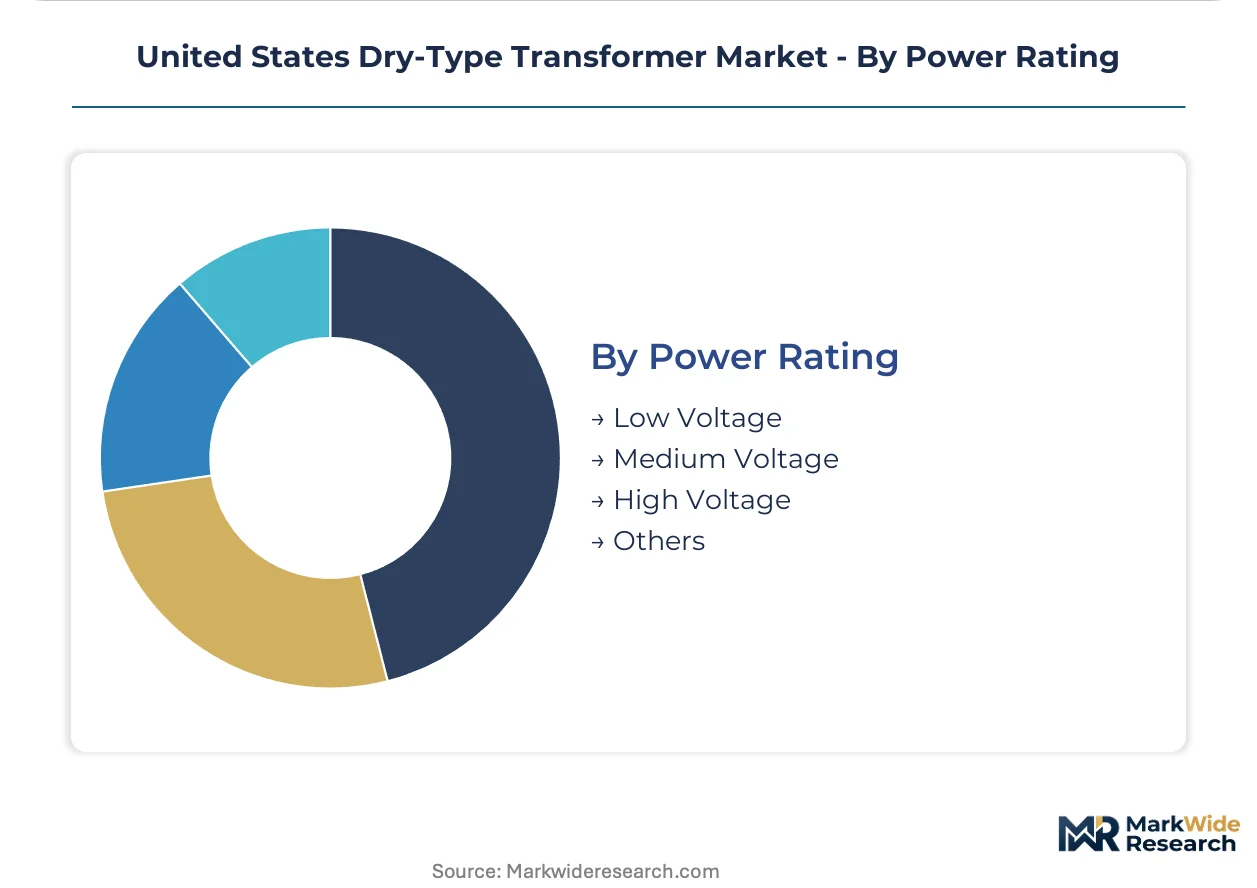
Power Rating:
Voltage class boundaries align with insulation coordination standards and switchgear compatibility requirements across the procurement landscape.
- Low Voltage:Units rated below 1 kV serve commercial building distribution panels and industrial motor control centers where standardization with switchgear bus configurations simplifies engineering.
- Medium Voltage:Designs from 1 kV through 72.5 kV support utility distribution feeders, data center substations, and renewable interconnection points where cast resin technology dominates indoor specifications.
- High Voltage:Applications above 72.5 kV remain oil-filled territory due to air insulation thermal limits, with dry-type designs confined to specialized research and testing facilities.
- Others:Custom specialty ratings for naval vessels, mining equipment, and traction power systems fall outside standard NEMA kVA tables.
Shipment value clusters in Medium Voltage; Low Voltage commands absolute unit volume leadership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grain-oriented electrical steel production in the Midwest and Southeast anchors domestic fabrication capacity for dry-type transformer manufacturing.
Southeast
Utility-scale solar interconnection projects in Georgia and the Carolinas consume pad-mounted dry-type units at accelerating rates. State renewable portfolio standards mandate solar capacity additions that strain transformer lead times through 2026. Charlotte and Atlanta electrical contractors report order backlogs extending eighteen months for medium-voltage cast resin designs.
Texas
Hyperscale data center construction in Dallas-Fort Worth and Austin drives procurement of explosion-proof dry-type units for hazardous location specifications. ERCOT grid interconnection rules require extended thermal ratings for renewable and load projects. Houston petrochemical clusters specify custom VPI designs for motor drive applications in refinery expansions.
Virginia
Loudoun County data center operators negotiate multi-year framework agreements for medium-voltage substation equipment. Dominion Energy interconnection standards favor cast resin designs for indoor installations in white space facilities. Northern Virginia electrical rooms absorb the highest per-capita dry-type transformer density nationally.
California
Title 24 building electrification codes prohibit oil-filled transformers in new commercial construction statewide. Silicon Valley hyperscale campuses specify amorphous metal core designs to meet corporate carbon neutrality commitments. Los Angeles and San Francisco electrical contractors face compressed installation schedules for urban high-rise projects.
Midwest
Industrial motor drive applications in Ohio and Michigan manufacturing corridors sustain demand for cost-sensitive VPI units. NEMA certification requirements from regional testing laboratories influence design standardization across the supplier base. Chicago electrical distributors maintain inventory positions for commercial building retrofits and institutional projects.
United States Dry-Type Transformer Market Competitive Landscape
Global majors compete with regional champions across technology licensing and local fabrication capacity. The supplier base organizes into three tiers: integrated power systems conglomerates with full energy portfolios, specialized transformer fabricators with resin-casting expertise, and regional electrical equipment distributors with assembly capabilities. Capacity expansion and strategic partnerships represent the dominant competitive vectors as firms position for data center and utility-scale solar procurement cycles.
Among diversified industrial conglomerates, GE Vernova and ABB exemplify the integrated power systems archetype, anchoring large utility and industrial contracts through comprehensive energy infrastructure portfolios. Siemens Energy occupies a position within the medium-voltage technology tier, where data center electrification requirements concentrate order activity. These three firms represent the scale-driven segment where consolidated engineering-procurement-construction relationships determine procurement flows.
| Leading Market Players |
|---|
| GE Vernova |
| ABB |
| Siemens Energy |
| Eaton |
| Schneider Electric |
| Hitachi Energy |
| Hammond Power Solutions |
| TMC Transformers |
| ELSCO Transformers |
| Others |
Value Network & Pricing Analysis
Grain-oriented electrical steel spot indices cascade through fabrication tiers, compressing margin pools for cast resin manufacturers while amplifying pricing power for amorphous metal core suppliers serving data center operators with loss-capitalization formulas.
Pricing Analysis
Warranty bundling separates premium from standard tiers, with multi-year thermal performance guarantees commanding 12-18% uplifts over bare-equipment transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service inclusion. Cost compression in the VPI segment is intensifying because epoxy resin feedstock volatility feeds through petrochemical supply chains. Industrial motor drive buyers in the Midwest exhibit highest price sensitivity, while utility-scale solar developers prioritize loss economics over first cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand in Northern Virginia and Dallas-Fort Worth, bypassing traditional electrical distributor networks. Domestic fabrication draws from grain-oriented electrical steel production concentrated in the Midwest and Southeast, with amorphous metal ribbon sourcing anchored in Japan and Germany. Epoxy resin formulations and copper conductor stock represent critical input dependencies. Single-source vulnerability for electrical steel exposes fabricators to allocation risk during demand surges. Distribution runs through EPC contractors for data center projects and electrical wholesalers for commercial building retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
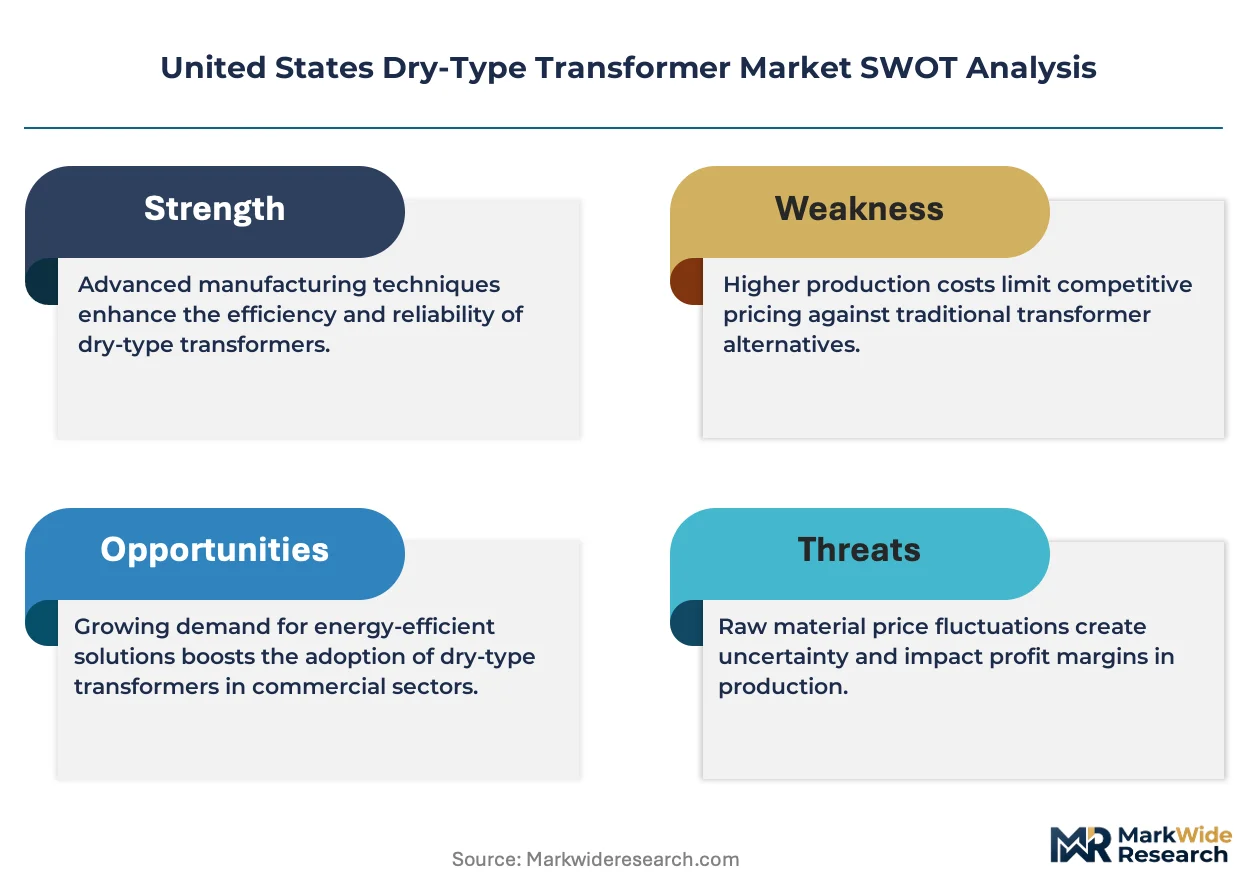
Cast resin casting capacity constraints in the Southeast prop pricing premiums, creating a supply-constrained market where order backlogs extend through the analysis window.
For Market Incumbents: Anticipate margin compression from amorphous metal core substitution by securing long-term electrical steel offtake agreements and accelerating in-house resin-casting capacity additions in Georgia and South Carolina. Dominant OEMs must defend against emerging Asian fabricators by embedding predictive maintenance software into standard equipment offerings. For New Entrants and Emerging Players: Launch via specialized hazardous location certification to penetrate the Texas Gulf Coast petrochemical corridor, where explosion-proof dry-type specifications remain underserved by incumbent portfolios. Target vacuum impregnation technician training partnerships with Midwest community colleges to address workforce gaps constraining regional supply. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional VPI specialists with established utility relationships in the Southeast, where solar interconnection backlogs ensure revenue visibility. Monitor DOE efficiency rulemaking timelines as the inflection signal for core material transition capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Amorphous Metal Core Manufacturing Scale-Up | Captures data center sustainability procurement mandates requiring 60-70% loss reduction. |
| Resin-Casting Capacity Expansion | Absorbs utility-scale solar interconnection demand concentrated in Georgia and the Carolinas. |
| Predictive Maintenance Platform Integration | Enables recurring revenue streams from hyperscale operator framework agreements. |
| Hazardous Location Certification Investment | Unlocks premium pricing in Texas petrochemical and semiconductor fabrication corridors. |
| Backward Integration into Electrical Steel Sourcing | Mitigates allocation risk from concentrated domestic supplier base. |
Research Methodology
SEC 10-K filings, EIA generation interconnection queues, and NEMA shipment statistics formed the secondary backbone, cross-referenced against primary interviews with utility procurement managers, data center engineering directors, cast resin plant operations heads, and electrical distributor category buyers. Bottom-up and top-down triangulation validated volume estimates across product tiers.
Bottom-up modeling anchored forecasts, with top-down macro checks against utility capex and data center construction permitting data. Segmentation dimensions included insulation system type, end-user vertical, installation environment, and power rating class across the projection horizon. CAGRs derived from installer order backlog analysis and OEM capacity expansion announcements, with loss-capitalization formulas and efficiency standard compliance timelines as industry-specific inputs.
DOE rulemaking delays, electrical steel supply disruptions, and data center construction cycle pauses are the dominant revision risks to base-case assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Europe Distribution Transformer Market
Transformers
Air Cooled Transformer Market
Transformers
Distribution Transformer Market
Transformers
United States Power Transformer Market
Transformers
India Distribution Transformer Market
Transformers
Current Transformer Market
Transformers
Smart Transformer Market
Transformers
Transformer Bobbin Market
Transformers
HVDC Converter Transformers Market
Transformers
Canada Transformer Market
Transformers
Gas Insulated Transformer Market
Transformers
Middle-East Smart Transformer Market
Transformers
Transformer Oil Market
Transformers
Green Transformer Market
Transformers
United Arab Emirates Transformer Market
Transformers
North America Power Transformer Market